
 Europe Postal Services Market | 2026-2036
Europe Postal Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Postal Services Market Foresight
Benelux distribution capacity is fragmenting as legacy mail volumes decline and parcel infrastructure expands. Deutsche Post DHL leverages its integrated European ground network to sustain density across Germany and neighboring corridors. Royal Mail anchors its position through UK-specific regulatory adaptations while competing with pan-European parcel specialists. La Poste differentiates via rural coverage obligations that occupy a protected service tier.
Europe postal services encompass physical mail processing, parcel logistics, and last-mile delivery operating through automated sorting hubs, standardized addressing protocols, and intermodal transport networks designed to move documents and goods between senders and recipients under universal service obligations. Express Delivery commands premium pricing for time-definite shipments while Standard Mail contracts as digital substitution advances. Parcels represents the fastest-growing service type as E-commerce customer demand reshapes network design and capacity allocation across the region.
EU Green Deal emissions frameworks and national postal regulators in France, Germany, and the Netherlands enforce fleet decarbonization timelines and universal service requirements that shape operator investment priorities. CE marking for automated sorting equipment and GDPR-compliant tracking data handling create compliance thresholds for technology deployment. Stakeholders must monitor how EU AI Act classification of automated routing systems affects algorithmic transparency mandates and procurement specifications.
Market Dynamics
E-commerce parcel throughput is forcing network reconfiguration across European postal operators, compressing legacy mail infrastructure while expanding automated sorting capacity for B2C fulfillment.
Growth Catalysts
- EU Green Deal fleet mandates:Electrification timelines for last-mile delivery vehicles in France, Germany, and the Netherlands are accelerating capital deployment into zero-emission vans and charging infrastructure.
- Cross-border corridor density:Parcel flows linking the Benelux cluster to Southern European distribution hubs are deepening intermodal connectivity and hub automation investment.
- GDPR-compliant tracking systems:Standardized data handling protocols for shipment visibility are enabling pan-European interoperability and customer transparency requirements.
Market Restraints
- Labor cost rigidity:Universal service obligations and collective bargaining frameworks in France and Germany constrain workforce flexibility during volume volatility.
- Sorting equipment concentration:Automated parcel handling systems rely on a narrow supplier base concentrated in German and Dutch manufacturing clusters.
- Digital substitution acceleration:Electronic invoicing and document digitization are structurally displacing transactional mail volumes in corporate and government segments.
Strategic Opportunities
- Rural coverage monetization:Obligated delivery networks in France, Spain, and Italy offer fixed-cost infrastructure that can support premium rural B2C services and pharmaceutical cold-chain expansion.
- CE marking harmonization:Standardized equipment certification across EU member states reduces procurement complexity for automated sorting technology deployment.
- Reverse logistics integration:E-commerce return flows are converging with forward parcel networks, enabling density-sharing models that improve per-stop economics.
Industry Challenges
- Algorithmic transparency compliance:EU AI Act classification of automated routing systems requires documentation and audit trails that extend procurement and deployment timelines.
- Intermodal handoff coordination:Parcel transfers between rail, road, and urban micro-depots demand synchronized scheduling systems that legacy IT architectures struggle to support.
- Workforce reskilling velocity:Transition from mail-centric operations to parcel handling requires retraining programs that outpace current HR capacity in several national operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Postal Services Market |
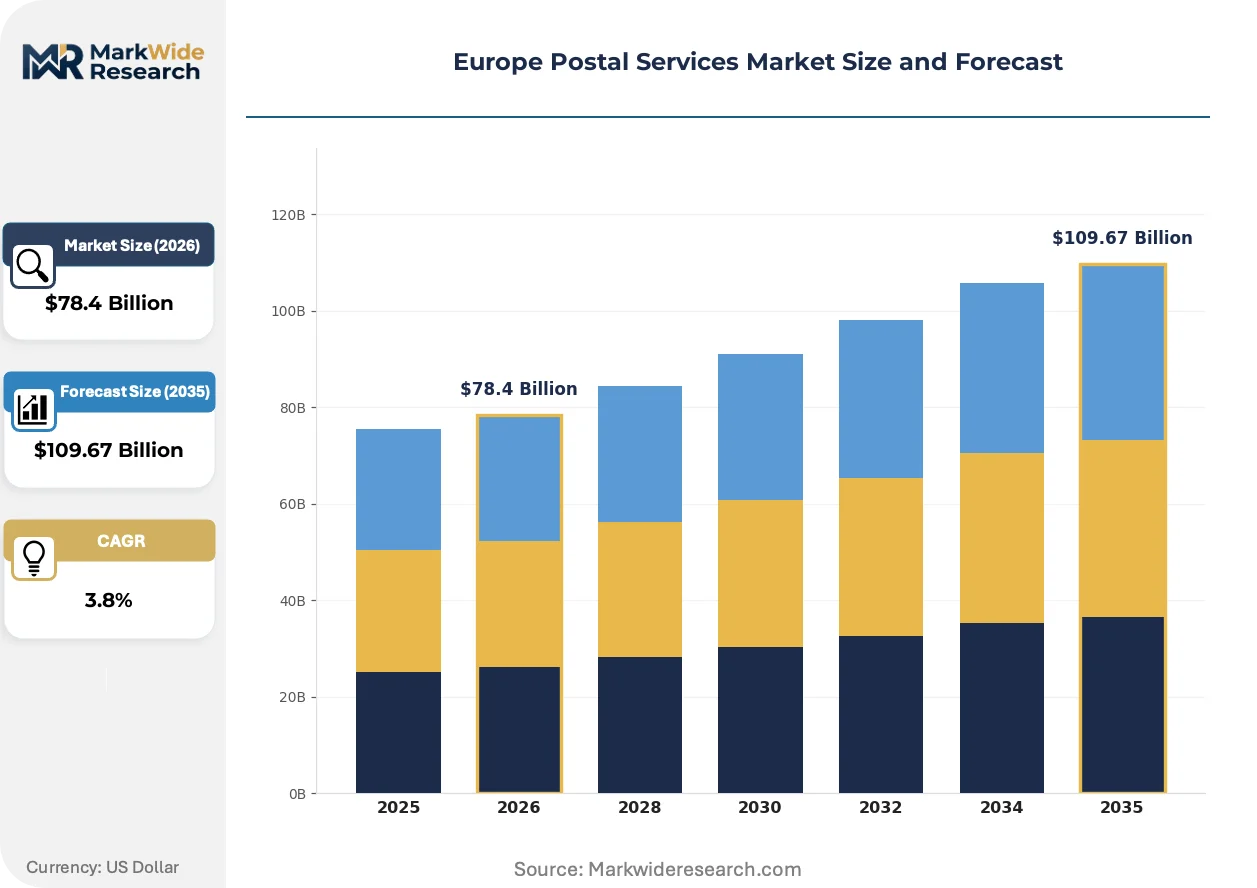
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $109.67 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Delivery, Standard Mail, Parcels, Registered Mail Delivery Model: Door-to-Door, Drop-off, Return Services, Tracking Services Customer Type: Businesses, Government, Individuals, E-commerce Technology: Automated Sorting, Mobile Apps, GPS Tracking, Barcode Scanning |
| Companies Covered | PostNL, UPS, Deutsche Post DHL, Bpost, Swiss Post, La Poste, DPD/Geopost, PostNord AB, Royal Mail, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Postal Services Market Shifts & Advancements
Digital twin technology is virtualizing European postal infrastructure planning, compressing capital deployment cycles while regulatory frameworks harden emissions accountability across member states.
Automated sorting robotics is virtualizing parcel handling workflows in high-throughput hubs. Deutsche Post DHL and La Poste are deploying vision-guided robotic arms for irregular package manipulation. This technology is virtualizing manual sort positions while compressing hub footprint requirements and enabling 24-hour processing windows.
EU AI Act algorithmic accountability mandates are reshaping procurement specifications for routing optimization software. Automated decision systems for delivery sequencing now require explainability documentation and bias testing. Parcel operators in France and Germany are responding by embedding compliance checkpoints into vendor selection criteria and extending pilot-to-production timelines.
Subscription-based delivery preferences are consolidating B2C parcel volumes around predictable scheduling windows. Retailers in the Benelux region and Northern Italy are displacing ad-hoc shipping with membership models that bundle delivery into annual contracts. This pattern is most visible in fashion and consumer electronics verticals where return rates justify fixed-fee logistics arrangements.
Europe Postal Services Market Segmentation
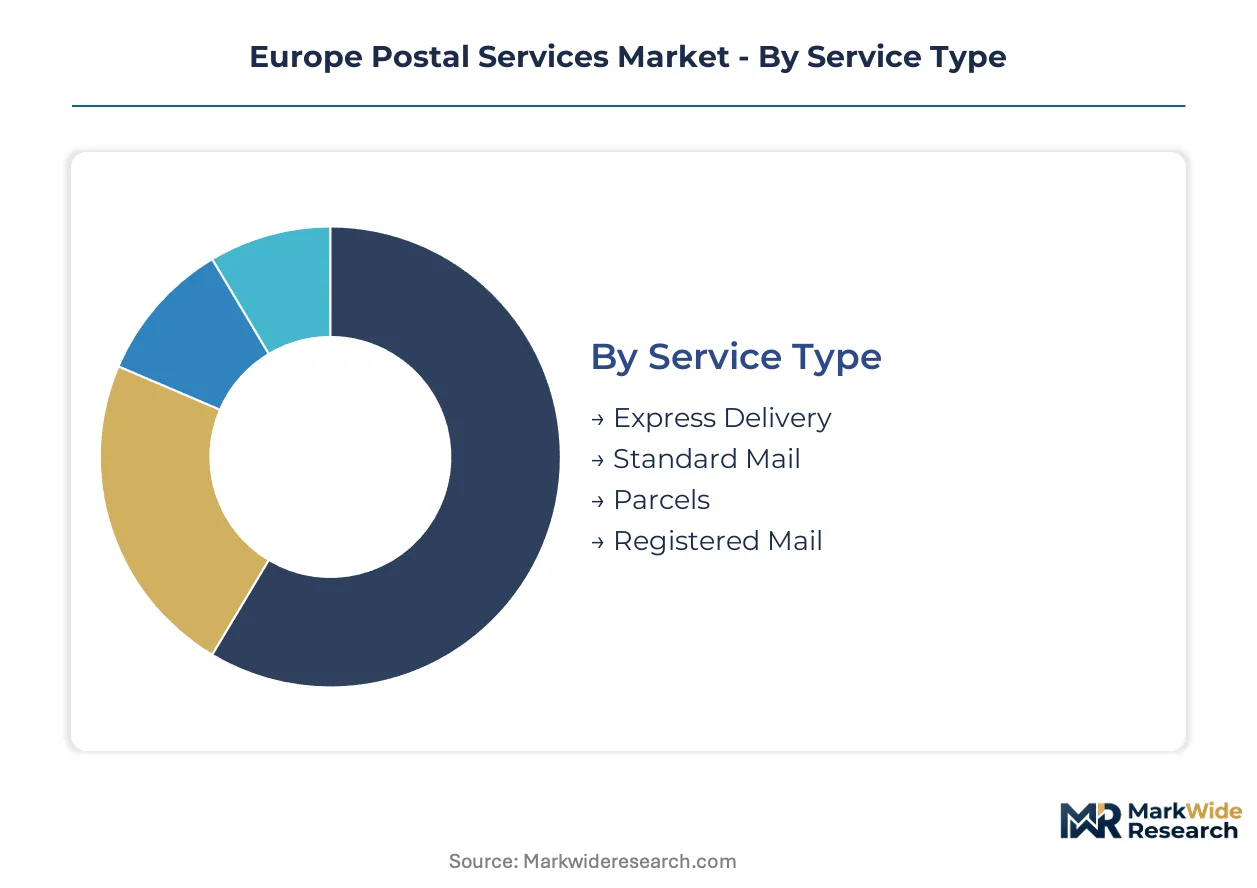
European postal operators configure service portfolios around diverging volume trajectories: collapsing transactional mail against surging e-commerce parcel flows. Segmentation reveals where capital allocation, regulatory obligations, and technology deployment concentrate across distinct service tiers and customer interfaces.
Service Type:
Express Delivery through Registered Mail span a use-case spectrum from time-critical logistics to legally verifiable document transmission, each commanding distinct network infrastructure and margin profiles.
- Parcels:B2C e-commerce fulfillment dominates throughput expansion, with automated sorting hubs across Germany and France scaling capacity for irregular package dimensions. Last-mile density in Benelux-to-Southern European corridors is the primary network investment driver.
- Express Delivery:Time-definite shipments leverage dedicated air and road networks for next-day delivery commitments. Premium pricing applies to cross-border medical supplies and high-value electronics moving through temperature-controlled lanes.
- Standard Mail:Transactional documents and marketing materials face structural displacement from electronic invoicing mandates under EU digitalization directives. Volume concentration persists in rural France and Italy where digital infrastructure gaps sustain physical delivery requirements.
- Registered Mail:Legally recognized proof-of-delivery services anchor government and judicial workflows. National postal operators in Germany and Spain maintain protected service tiers under universal service obligation frameworks.
The dominant share belongs to Standard Mail, while Parcels is closing the gap fastest.
Delivery Model:
Customer interface choices stratify by convenience premium versus cost minimization, shaping last-mile economics and infrastructure requirements across urban and rural deployment.
- Door-to-Door:Residential delivery to individual addresses commands the highest per-stop cost but captures e-commerce subscription models. Fleet electrification timelines under EU Green Deal mandates concentrate investment here.
- Return Services:Reverse logistics integration with forward parcel networks enables density-sharing in fashion and consumer electronics verticals. Automated return label generation through mobile interfaces reduces customer friction.
- Drop-off:Parcel lockers and retail partner locations extend reach without dedicated fleet expansion. France and the Netherlands lead locker network density through La Poste and PostNL infrastructure.
- Tracking Services:GDPR-compliant shipment visibility systems require standardized data protocols across member states. Real-time GPS integration supports delivery window prediction and exception management.
Door-to-Door retains volume leadership, though Return Services is expanding most quickly as e-commerce return rates climb.
Customer Type:
Revenue concentration shifts from institutional senders toward digital commerce platforms, reconfiguring sales channels and contract structures.
- E-commerce:Online retail platforms drive parcel volume growth through subscription delivery models. Benelux and Northern Italy retailers are consolidating shipping volumes under annual logistics contracts.
- Businesses:Corporate mailrooms and B2B supply chains sustain bulk contracting for document and parts logistics. Sourcing departments negotiate multi-year agreements with service level guarantees.
- Government:Public administration remains a protected client segment under universal service obligations. Judicial and tax authorities require registered mail for legally binding communications.
- Individuals:Ad-hoc shipping represents declining share as platform economics concentrate volume through e-commerce intermediaries. Occasional use persists for personal correspondence and gift shipments.
E-commerce has overtaken Businesses for parcel revenue leadership, while Government contracts provide stable, regulated returns.
Technology:
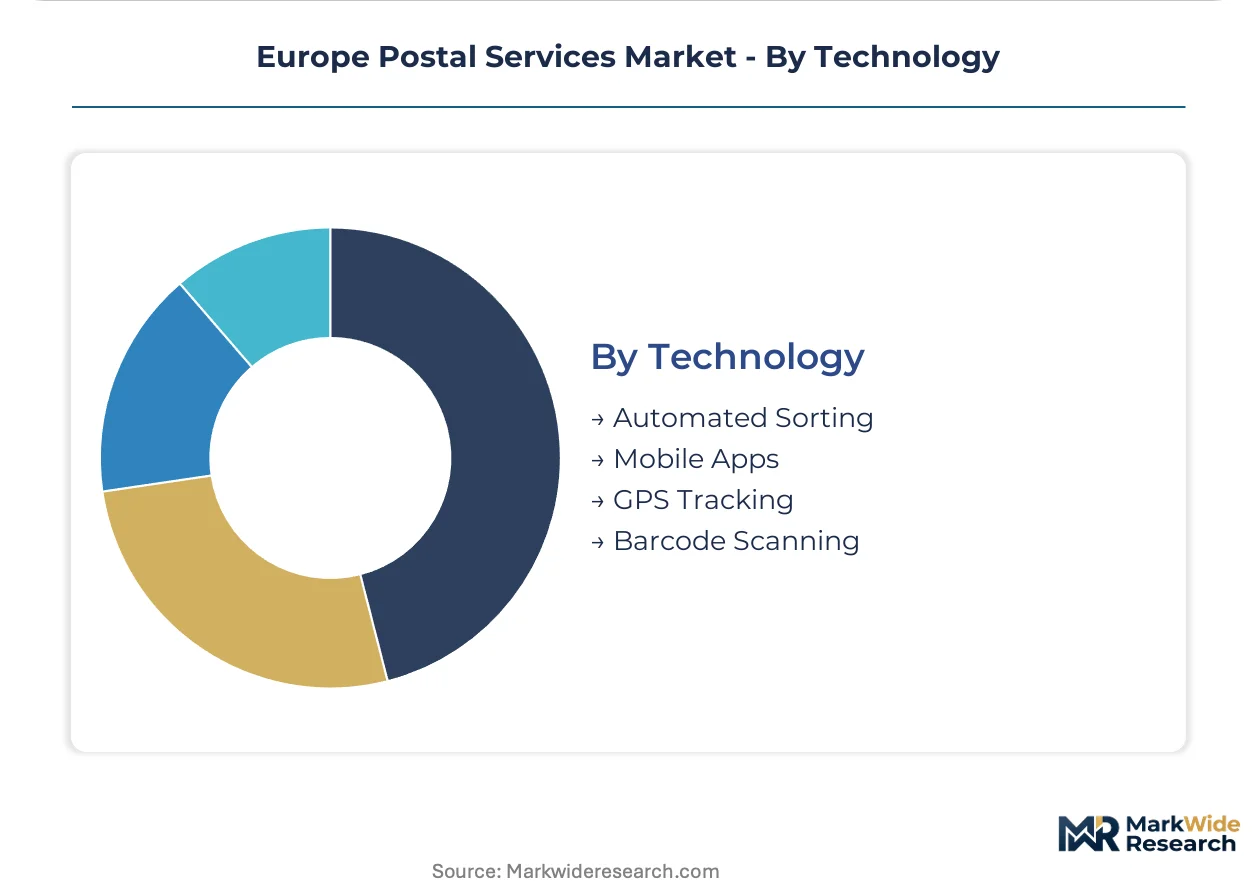
Operational technology deployment separates throughput capacity leaders from legacy-constrained competitors, with regulatory compliance adding implementation complexity.
- Automated Sorting:Vision-guided robotic arms and high-speed conveyor systems process irregular parcels in Deutsche Post DHL and La Poste hubs. CE marking harmonization reduces procurement friction across EU member states.
- Barcode Scanning:Standardized package identification enables handoff tracking across multimodal networks. Integration with retailer inventory systems supports pre-shipment label generation.
- GPS Tracking:Real-time vehicle and parcel location data feeds routing optimization and customer notification systems. GDPR compliance requires anonymization protocols for driver location histories.
- Mobile Apps:Customer-facing interfaces support delivery rescheduling, locker access, and return initiation. PostNL and Royal Mail lead feature integration for subscription management.
Automated Sorting commands the largest capital allocation, while Mobile Apps are climbing the fastest as customer experience differentiation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bundesnetzagentur postal regulations anchor German market structure, with universal service obligations and fleet electrification mandates under EU Green Deal frameworks shaping investment patterns across member states.
Germany
E-commerce parcel volumes through Cologne-Bonn and Leipzig air cargo hubs drive Deutsche Post DHL network densification. KBA enforces zero-emission van procurement timelines for urban last-mile fleets. The Rhine-Ruhr corridor concentrates automated sorting infrastructure investment.
France
Rural coverage obligations sustain La Poste delivery density where digital infrastructure gaps persist. ANSM and CNIL oversight extends to pharmaceutical cold-chain logistics and customer data handling. The Île-de-France region anchors cross-border parcel flows toward Southern European distribution hubs.
Netherlands
Rotterdam port integration and Schiphol air freight capacity position Dutch operators as Benelux distribution gatekeepers. PostNL locker network density leads European parcel access point deployment. Randstad urban logistics clusters concentrate electric fleet charging infrastructure.
United Kingdom
Regulatory adaptations following EU exit reshape Royal Mail universal service cost structures. Ofcom pricing controls intersect with declining letter volumes and surging B2C parcel demand. Midlands distribution hubs handle cross-channel freight diversion from traditional Calais-Dover corridors.
Belgium
Bpost leverages Brussels air hub connectivity for time-definite European express corridors. Federal postal regulator BIPT monitors service quality benchmarks across declining mail and expanding parcel segments. The Antwerp-Brussels logistics axis supports pharmaceutical and diamond trade verticals.
Europe Postal Services Market Competitive Landscape
Capability concentration sits with integrated pan-European networks; scale advantage sits with national incumbents bound by universal service obligations. The market structures around three tiers: state-affiliated postal operators with protected service mandates, parcel specialists competing on cross-border density, and global integrators leveraging air freight assets. Competitive moves center on automated sorting capacity expansion and strategic partnerships with e-commerce platforms for volume commitment.
Within the national incumbent tier, Deutsche Post DHL and La Poste exemplify divergent strategic postures—one integrating parcel growth with international express networks, the other protecting rural coverage economics. Royal Mail occupies a position shaped by regulatory adaptation rather than network expansion. Among Benelux specialists, PostNL and Bpost represent contrasting density models: locker-heavy urban optimization versus hub-and-spoke international connectivity.
| Leading Market Players |
|---|
| PostNL |
| UPS |
| Deutsche Post DHL |
| Bpost |
| Swiss Post |
| La Poste |
| DPD/Geopost |
| PostNord AB |
| Royal Mail |
| Others |
Supply & Pricing Matrix
Single-source dependency on German and Dutch automated sorting equipment manufacturers compresses pricing tier spreads while tethering supply chain resilience to CE marking harmonization timelines and cross-border component logistics. This concentration dynamic forces operators to absorb equipment premiums or accept extended procurement cycles that cascade into service-level pricing adjustments.
Pricing Analysis
Cross-border parcel corridors between Benelux and Southern Europe exhibit wider price spreads than intra-national lanes due to intermodal handoff complexity and customs processing overhead. Three-tier pricing structure across express, standard parcel, and economy mail levels reflects delivery speed guarantees and tracking depth. Cost compression in standard mail is intensifying because digital substitution erodes volume density needed for per-unit cost coverage. E-commerce platforms negotiating annual logistics contracts demonstrate lowest price sensitivity, while individual ad-hoc shippers face steep per-shipment premiums.
Supply Chain Analysis
Tariff exposure between EU member states and third-country equipment suppliers dominates supply chain risk profiles for automated handling systems. Manufacturing concentrates in Germany, the Netherlands, and Italy for sorting machinery, conveyor systems, and electric van components. Raw material dependencies span lithium-ion battery cells, high-grade steel for hub infrastructure, and semiconductor chips for routing optimization. Distribution runs through Rotterdam port integration and Rhine-Ruhr rail corridors into last-mile depots across member states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across rural coverage obligations and e-commerce fulfillment specialization creates niche expansion opportunities as subscription delivery models displace ad-hoc shipping volumes.
For Market Incumbents: Harden rural infrastructure monetization by deploying pharmaceutical cold-chain capabilities through obligated delivery networks in France, Spain, and Italy. Deepen vertical integration into automated sorting technology through captive maintenance capabilities that reduce supplier dependency. Defend against parcel specialists by locking e-commerce platforms into multi-year volume commitments with guaranteed capacity tiers. For New Entrants and Emerging Players: Build out locker network density in secondary cities where PostNL and La Poste coverage remains thin, particularly in Eastern European markets. Target reverse logistics integration as the most penetrable segment, converging return flows with forward parcel networks to achieve density-sharing economics. Pursue white-label fulfillment partnerships with fashion and consumer electronics retailers seeking fixed-fee logistics arrangements. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors automated technology specialists with CE marking expertise and proven EU AI Act compliance documentation. Long-term viability hinges on operators achieving parcel volume density sufficient to offset collapsing mail revenues. Watch fleet electrification capex deployment rates as the signal indicating which operators can absorb EU Green Deal mandates without margin erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Sorting Capacity Expansion | Deutsche Post DHL and La Poste deployments compress hub footprints while enabling 24-hour processing windows. |
| Fleet Electrification Partnership | KBA and ANSM mandates accelerate zero-emission van procurement timelines across German and French urban corridors. |
| Reverse Logistics Integration | Fashion and electronics return flows converge with forward networks, improving per-stop economics for B2C operators. |
| Rural Coverage Monetization | La Poste's protected service tier anchors pharmaceutical cold-chain expansion into underserved French territories. |
| GDPR-Compliant Tracking Deployment | PostNL and Royal Mail lead real-time GPS integration supporting delivery window prediction and exception management. |
Research Methodology
Cross-validation between regulatory filing analysis and operator capex disclosures anchors the qualitative findings on fleet electrification timelines and automated sorting deployment. Primary interviews with postal network planners, last-mile logistics directors, e-commerce procurement leads, and EU regulatory affairs specialists were combined with secondary validation through Bundesnetzagentur and BIPT service quality reports, EU Green Deal implementation tracking, and CE marking certification databases. Bottom-up volume modeling across parcel, express, and mail segments triangulates against top-down market sizing from national postal operator financial disclosures.
Calibration against historical volume shifts during prior digital substitution waves and e-commerce acceleration periods informs the projection framework. Segmentation dimensions modeled include service type, delivery model, customer archetype, and technology deployment tier across the analysis window. CAGRs were derived from trend extrapolation adjusted for regulatory mandate impacts and infrastructure investment cycles. Forecast inputs incorporate EU AI Act compliance timelines and intermodal rail capacity expansion schedules.
Stress conditions across diesel price volatility, lithium-ion cell supply constraints, and labor cost inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on e-commerce penetration rates and universal service obligation cost recovery mechanisms. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Advanced Fiber-Based Gasket Market
Others
Smart Home Gateways Market
Others
Japan Indoor LBS Market
Others
Surgical Simulation Market
Others
Vegan Confectionery Market
Others
Connected Homes Market
Others
Coriolis Meters Market
Others
Infant Positioning Aids Market
Others
Italy Automotive Adaptive Lighting System Market
Others
Dental Ceramics Market
Others
Cloud-Based Streaming Services Market
Others
Coloring Apps Market
Others
Smart Home Controller Market
Others
Telecom Transformers Market
Others
One-Way Degassing Valve Market
Others
Smart Home Water Softener Market