
 HPHT Diamond Cubic Press Market | 2026-2036
HPHT Diamond Cubic Press Market Size, Share, and Industry Trends Forecast 2026-2036
HPHT Diamond Cubic Press Market Insights
Asset-light leasing arrangements for cubic press machinery is fragmenting competitive dynamics across the HPHT diamond production landscape. Sinomach Precision Industry leverages captive forging capabilities to sustain vertical integration from press frames to finished synthetic stones. Labrilliante anchors its position through specialized service contracts that bundle equipment with process engineering support.
HPHT diamond cubic press denotes a high-pressure, high-temperature synthesis apparatus employing six anvils arranged in cubic symmetry to generate pressures exceeding 5 GPa at temperatures above 1,400°C for carbon phase transformation into diamond. The system relies on tungsten carbide anvils with pyrophyllite gaskets to maintain pressure containment during extended growth cycles for gem-quality and industrial crystals. Multi-stage press configurations command premium positioning due to their throughput advantage in large crystal production runs exceeding 50 carats per cycle. Static pressure technology dominates installed capacity, though hybrid systems integrating continuous feed mechanisms represent the fastest-expanding segment as manufacturers seek reduced downtime between synthesis batches.
China's MIIT enforces GB standards for superhard material equipment safety and electromagnetic compatibility, while the EPA regulates coolant discharge from press cooling circuits in United States manufacturing facilities. India's BIS mandates certification for synthetic diamond disclosure, directly shaping import demand for traceable HPHT production systems. Stakeholders must monitor evolving carbon accounting rules for synthetic diamond energy intensity as jurisdictions differentially classify lab-grown versus mined stone environmental profiles.
Market Dynamics
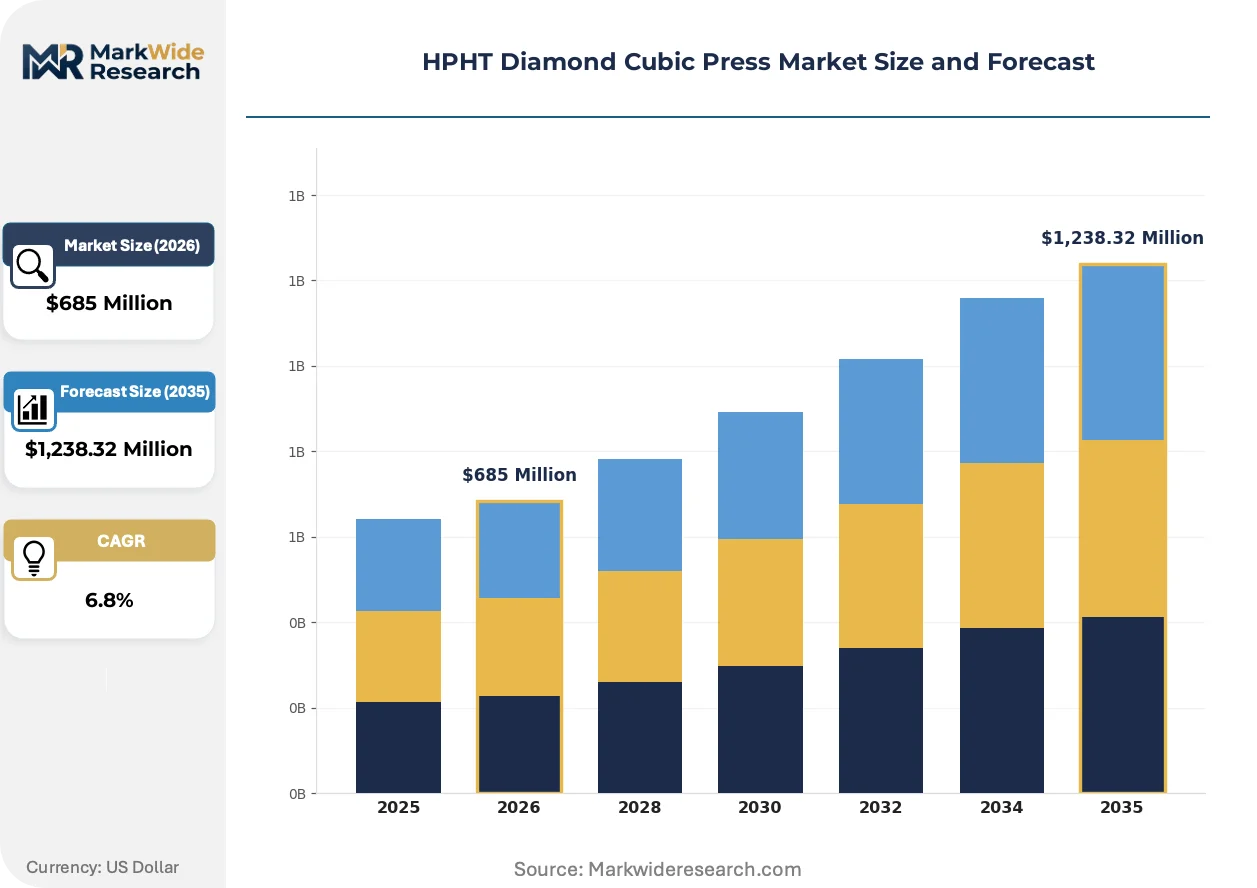
Leasing-based equipment access is fragmenting competitive positioning across HPHT diamond cubic press manufacturing, as asset-light operators erode the dominance of vertically integrated frame producers in Henan Province.
Growth Catalysts
- BIS Certification Framework:India's Bureau of Indian Standards mandates synthetic gemstone disclosure, creating traceable demand for certified HPHT production systems among jewelry fabricators in Surat and Mumbai.
- Industrial Abrasive Demand:Precision machining applications in automotive and aerospace sectors pull large-crystal synthetic diamond output exceeding 50 carats per synthesis cycle.
- Dual Carbon Goals:China's national decarbonization targets classify lab-grown diamond energy profiles favorably versus mined extraction, channeling policy support toward domestic cubic press deployment.
Market Restraints
- Tungsten Carbide Supply Concentration:Anvil raw material sourcing clusters in select metallurgical zones, exposing press manufacturers to input cost volatility and geopolitical supply friction.
- GB Standards Compliance Burden:China's MIIT safety and electromagnetic compatibility certifications impose extended validation timelines for new press configurations entering commercial deployment.
- Chemical Vapor Deposition Substitution:CVD diamond synthesis achieves finer control over crystal purity for electronics substrates, displacing HPHT in semiconductor heat-spreader applications.
Strategic Opportunities
- Continuous Feed Hybrid Systems:Technology convergence between static pressure apparatus and automated material handling reduces batch-to-batch downtime, unlocking throughput premiums for early adopters.
- US IRA Clean Energy Credits:Inflation Reduction Act provisions for domestic manufacturing equipment investment create fiscal incentives for cubic press installation in American synthetic diamond facilities.
- Service Contract Unbundling:Process engineering support sold separately from hardware procurement opens recurring revenue streams for specialized technical consultancies serving mid-scale producers.
Industry Challenges
- Pyrophyllite Gasket Sourcing:High-purity ceramic sealant procurement requires qualification relationships with limited specialty mineral processors, constraining rapid capacity scaling.
- Multi-Anvil Alignment Expertise:Six-anvil cubic symmetry calibration demands rare metrology skill sets, creating talent bottlenecks for press commissioning and maintenance operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HPHT Diamond Cubic Press Market |
| Market Size in 2026 | $685 Million |
| Market Size in 2035 | $1,238.32 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Stage Press, Multi-Stage Press, Modular Press, Specialized Press Technology: Static Pressure Technology, Dynamic Pressure Technology, Continuous Feed Technology, Hybrid Technology Application: Gemstone Production, Industrial Tool Manufacturing, Aerospace Components, Synthetic Diamonds End User: Jewelry Manufacturers, Industrial Suppliers, Research Institutions, Electronics Producers |
| Companies Covered | Max Voggenreiter, Labrilliante, Sinomach Precision Industry, Guilin Guiye Machinery, Luoyang Qiming Superhard Material, Huanghe Whirlwind, Henan Deshen Machinery, Tianbao Huanxiang Machinery Technology, Henan BoTai Samsara, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HPHT Diamond Cubic Press Market Trends and Innovations
Active transformation in HPHT diamond cubic press markets centers on equipment architecture evolution, tightening environmental compliance, and buyer-side restructuring of procurement relationships.
Continuous feed mechanism integration is migrating from experimental installations to mainstream production configurations. Jewelry manufacturers seeking gem-quality output above two carats adopt hybrid systems that automate carbon source replenishment between growth cycles. This architecture compresses unit economics for large-crystal runs while reducing manual intervention requirements in 24-hour synthesis operations.
REACH chemical registration requirements in Europe now govern coolant formulations circulating through press thermal management circuits. Manufacturers serving EU export markets reformulate hydraulic fluids to eliminate Substance of Very High Concern classifications, adding compliance cost layers that smaller frame builders struggle to absorb. German and French import channels increasingly demand full material safety documentation upstream of equipment purchase decisions.
Buyer concentration among Indian jewelry exporters is consolidating procurement leverage around bundled service offerings. Surat-based cutting houses now specify multi-year technical support contracts as mandatory bid components, displacing pure equipment transactions. This behavioral shift rewards cubic press suppliers with captive process engineering capabilities rather than standalone hardware vendors.
HPHT Diamond Cubic Press Market Segmentation
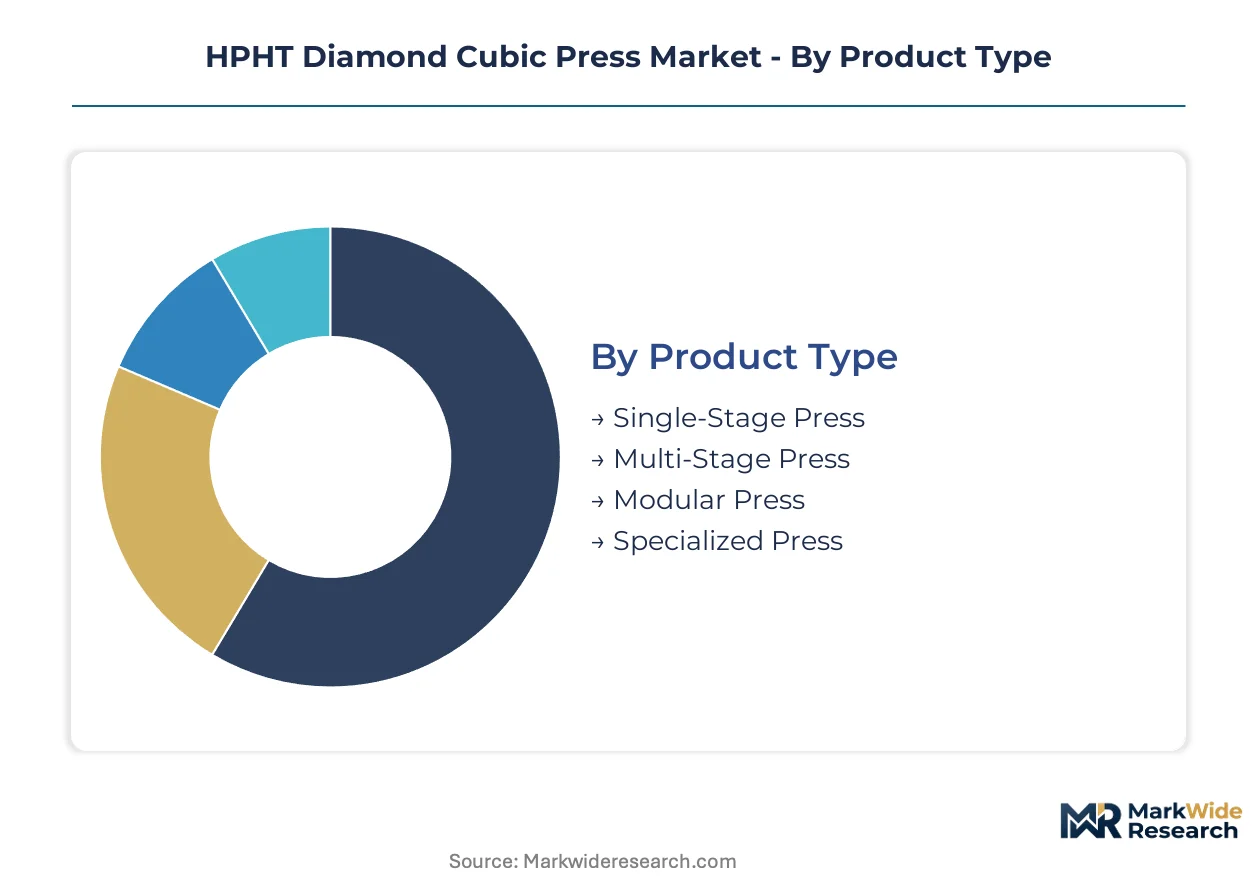
HPHT diamond cubic press segmentation reveals how equipment architecture, synthesis methodology, and buyer sophistication stratify commercial opportunity. Technology choices lock in operational economics for decades, while application mix determines exposure to gem versus industrial pricing cycles.
Product Type:
Cost tier differentiation across press architectures separates mass-market frame producers from premium system integrators serving specialized crystal growth requirements.
- Multi-Stage Press:Stacked anvil configurations sustain pressure gradients across sequential compression chambers, enabling single-cycle yields exceeding 50 carats. Indian jewelry exporters in Surat specify these systems for two-carat-plus rough production, absorbing capital premiums to reduce per-carat labor intensity.
- Single-Stage Press:Compact six-anvil designs dominate entry-level installations among first-time synthetic diamond entrants in Henan Province. These units trade throughput for accessibility, serving industrial abrasive producers with tolerance for smaller crystal dimensions.
- Modular Press:Field-upgradable frame architectures allow capacity expansion without full replacement. Electronics substrate manufacturers favor this flexibility given uncertain demand scaling for heat-spreader applications.
- Specialized Press:Custom-configured systems address exotic carbon allotrope research and ultra-high-purity semiconductor material synthesis. Research institutions in Japan and Germany anchor demand through national laboratory procurement channels.
Multi-stage press holds installed capacity. Modular press is rotating up the share rankings.
Technology:
Application requirements for crystal size, purity, and batch frequency dictate technology selection across buyer segments with divergent technical capabilities.
- Static Pressure Technology:Conventional hydraulic systems maintain fixed pressure-temperature envelopes throughout growth cycles. This mature approach commands the largest installed base among Chinese producers serving industrial diamond markets with standardized quality tolerances.
- Hybrid Technology:Convergence of static pressure apparatus with automated material handling enables carbon source replenishment without full cycle interruption. Jewelry manufacturers seeking 24-hour operations adopt these configurations to compress labor costs and improve capital turnover.
- Dynamic Pressure Technology:Pulsed pressure modulation accelerates nucleation kinetics for specific crystal morphologies. Niche adoption concentrates in research settings exploring novel diamond properties for quantum sensing applications.
- Continuous Feed Technology:Conveyor-based material transport systems remain experimental outside pilot installations. Early deployments focus on industrial abrasive production where purity requirements permit higher throughput processing.
Static pressure technology anchors current revenue. Hybrid configurations are climbing the fastest as operational labor costs rise across manufacturing bases.
Application:
Volume concentration across end-use segments determines exposure to consumer discretionary cycles versus industrial capital expenditure patterns.
- Gemstone Production:Rough synthesis for jewelry cutting commands premium pricing contingent on color and clarity certification. Indian BIS disclosure mandates create traceability requirements that favor HPHT over competing synthesis methods for export-oriented producers.
- Industrial Tool Manufacturing:Polycrystalline diamond compact substrates for oilfield drilling and precision machining absorb the majority of large-crystal output. Automotive and aerospace sector demand for hardened cutting tools sustains consistent procurement regardless of gem market volatility.
- Synthetic Diamonds:General-purpose material supply serves abrasive manufacturers and composite reinforcement applications. This commoditized segment competes directly with natural diamond grit on price per carat.
- Aerospace Components:Thermal management and wear-resistant coatings for turbine applications represent emerging demand with stringent qualification timelines. Defense procurement channels in the US and France drive specification development.
Gemstone production captures margin concentration. Industrial tool manufacturing is expanding most quickly as precision machining requirements tighten across automotive supply chains.
End User:
Customer type stratification separates specification-heavy institutional buyers from price-sensitive commercial operators with diverging service requirements.
- Jewelry Manufacturers:Cutting houses in Surat and Mumbai bundle multi-year technical support contracts with equipment procurement, displacing pure hardware transactions. These buyers prioritize process engineering partnerships over capital cost minimization.
- Industrial Suppliers:Abrasive and cutting tool producers emphasize throughput metrics and equipment uptime guarantees. Leasing arrangements fragment competitive positioning as asset-light operators erode vertically integrated frame builders.
- Electronics Producers:Semiconductor heat-spreader and substrate manufacturers impose purity specifications that favor CVD alternatives for certain applications. HPHT retains position in larger-dimension thermal management components.
- Research Institutions:National laboratories and university facilities drive specification innovation through custom equipment orders. METI-funded programs in Japan and EU Horizon initiatives sustain demand for experimental press configurations.
Jewelry manufacturers concentrate procurement leverage. Electronics producers are gaining share fastest as thermal management applications multiply across power semiconductor architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in synthetic diamond equipment tilt toward net shipments from Chinese manufacturing bases, while import demand concentrates in Indian jewelry processing centers and European research institutions. Currency volatility and carbon-border adjustment mechanisms are reshaping cross-border procurement patterns for cubic press systems.
China
Henan Province hosts the densest concentration of cubic press fabricators globally, with Zhengzhou and Luoyang anchoring frame production and synthetic diamond crystal growth. MIIT enforces GB standards for electromagnetic compatibility and equipment safety, extending validation timelines for new press configurations. The dual carbon goals framework classifies lab-grown diamond energy profiles favorably versus mined extraction, channeling policy support toward domestic capacity expansion.
India
Surat and Mumbai drive equipment demand through Bureau of Indian Standards certification mandates for synthetic gemstone disclosure. BIS traceability requirements favor HPHT production systems over competing synthesis methods for export-oriented jewelry fabricators. Cutting houses now bundle multi-year technical support contracts with equipment procurement, displacing pure hardware transactions.
United States
Domestic synthetic diamond facilities concentrate in Ohio and Pennsylvania, serving precision machining and aerospace thermal management applications. EPA regulates coolant discharge from press cooling circuits, adding compliance layers for hydraulic fluid formulations. Inflation Reduction Act provisions for domestic manufacturing equipment investment create fiscal incentives for cubic press installation.
Germany
Research institutions in Bavaria and Baden-Württemberg anchor demand for experimental press configurations through national laboratory procurement channels. REACH chemical registration requirements govern coolant formulations circulating through thermal management circuits, forcing reformulation of hydraulic fluids to eliminate Substance of Very High Concern classifications. German import channels increasingly demand full material safety documentation upstream of equipment purchase decisions.
Japan
METI-funded programs sustain demand for specialized press systems addressing quantum sensing and exotic carbon allotrope research. National laboratories in the Kanto region drive specification innovation through custom equipment orders. Japanese electronics producers impose purity specifications that favor CVD alternatives for certain semiconductor substrate applications, though HPHT retains position in larger-dimension thermal management components.
HPHT Diamond Cubic Press Market Competitive Landscape
On the supply side, the industry is consolidating around vertically integrated frame builders in Henan Province while asset-light leasing operators fragment positioning among mid-scale entrants. Strategic archetypes separate captive forging specialists, bundled service providers, and pure equipment lessors. Dominant competitive moves include backward integration into tungsten carbide anvil supply and geographic expansion through localized technical support partnerships.
Among Chinese fabricators, Sinomach Precision Industry and Huanghe Whirlwind exemplify the vertically integrated archetype, while Labrilliante occupies a position within the bundled service tier. Max Voggenreiter represents European precision engineering specialization in high-pressure apparatus. These three anchors illustrate how geographic origin and organizational structure stratify competitive positioning across equipment procurement channels.
| Leading Market Players |
|---|
| Max Voggenreiter |
| Labrilliante |
| Sinomach Precision Industry |
| Guilin Guiye Machinery |
| Luoyang Qiming Superhard Material |
| Huanghe Whirlwind |
| Henan Deshen Machinery |
| Tianbao Huanxiang Machinery Technology |
| Henan BoTai Samsara |
| Others |
Pricing and Supply Chain Analysis
Zhengzhou-Luoyang rail freight corridors carry tungsten carbide anvils and pyrophyllite gaskets from Henan Province forging centers to coastal export terminals, with logistics cost volatility feeding directly into multi-stage press premiums and compressing margins on single-stage configurations for price-sensitive abrasive producers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in HPHT cubic press procurement. Multi-stage systems with 50-carat-plus yields command premiums based on BIS certification bundling and Surat jewelry exporter specifications, while single-stage units face cost compression from leasing-based entrants in Henan. Electronics substrate manufacturers show least price sensitivity given purity-driven specification requirements, whereas first-time industrial abrasive entrants in Central China exhibit highest elasticity to capital outlay.
Supply Chain Analysis
Tungsten carbide feedstock concentrates in Chinese metallurgical zones, Brazilian hardmetal processing facilities, and select Russian mining operations, with pyrophyllite gasket supply tethered to South African and Indian specialty mineral processors. Anvil raw material sourcing exposes press fabricators to commodity price volatility and geopolitical friction, particularly around tungsten concentrate export licensing. Distribution runs through direct OEM relationships for large-frame systems and equipment lessor networks for mid-scale entrants, with aftermarket service contracts increasingly bundled into initial procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Surat-based jewelry exporters who now mandate multi-year technical support contracts as mandatory bid components, fragmenting competitive positioning for pure hardware vendors while rewarding bundled service providers.
For Market Incumbents: Entrench through captive forging capabilities extending from press frames to finished synthetic stones, mirroring Sinomach Precision Industry's upstream control over tungsten carbide anvil production. Secure BIS certification pathways for Indian export channels before CVD substitution accelerates in semiconductor heat-spreader applications. Prioritize continuous feed hybrid system R&D to defend against asset-light leasing operators eroding Henan Province's vertically integrated frame builders. For New Entrants and Emerging Players: Build out modular press architectures targeting electronics producers in Japan and Germany where thermal management applications favor field-upgradable capacity expansion. Focus initial penetration on research institution procurement channels through METI-funded programs and EU Horizon initiatives, where custom experimental configurations command pricing premiums absent in commoditized industrial abrasive segments. Position through specialized service contracts unbundling process engineering from hardware. For Investors and Strategic Acquirers: Asset-light technical consultancies with captive process engineering capabilities present attractive acquisition profiles given Surat jewelry manufacturer procurement shifts toward bundled support. Long-term viability hinges on carbon accounting rule evolution differentially classifying lab-grown versus mined stone environmental profiles. Watch for MIIT GB standards compliance timeline extensions as inflection indicators for new press configuration commercial deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Anvil Supply | Captive tungsten carbide forging insulates Henan fabricators from raw material cost volatility. |
| Hybrid System Technology Licensing | Continuous feed mechanism patents unlock recurring royalty streams from mid-scale jewelry producers. |
| BIS Certification Partnership Program | Pre-certified press configurations accelerate Indian jewelry exporter market access timelines. |
| Modular Press Field Upgrade Services | Electronics substrate manufacturers pay premiums for capacity expansion without full replacement. |
| REACH-Compliant Coolant Formulation | Elimination of SVHC classifications preserves German and French export channel access. |
Research Methodology
A spread of perspectives from cubic press plant engineers, synthetic diamond procurement leads at Surat cutting houses, tungsten carbide metallurgical specialists, and MIIT standards compliance officers converged on the working assumptions shaping this analysis. Primary fieldwork combined with secondary validation from GB standards documentation, BIS certification registries, EPA coolant discharge filings, and REACH chemical registration databases. Bottom-up equipment shipment tallies from Henan Province fabricators triangulated against top-down synthetic diamond output estimates across gem and industrial segments.
Demand-supply balance modeling across the projection horizon segmented by press architecture, synthesis technology, application mix, and end-user sophistication. The analytical framework incorporated static pressure versus hybrid technology adoption curves, jewelry manufacturer bundled service contract penetration rates, and CVD substitution thresholds in semiconductor applications. CAGRs derived from equipment installation run-rates, crystal yield improvements per cycle, and regional policy support intensity under China's dual carbon goals framework.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by asset-light leasing operators or accelerated CVD technology maturation would shift outcomes beyond modeled ranges. Cross-checking against MIIT equipment safety certification issuance rates and BIS synthetic diamond disclosure enforcement intensity is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Aircraft Sensors Market
Others
Asia-Pacific Adtech Market
Others
Middle East and Africa Medium Voltage Switchgear Market
Others
PCB Laminate Market
Others
Green Technologies Market
Others
Allogeneic T Cell Therapies Market
Others
Asia-Pacific Air Separation Unit Market
Others
Hydrostatic Testing Market
Others
ASEAN Smart Homes Market
Others
Drum Motor Market
Others
Process Spectroscopy Market
Others
Stand-Up Pouch Valves Market
Others
Global Smart Home Installation Service Market
Others
Europe Indoor Air Purification Market
Others
Vortexers Market
Others
Video-As-A-Service (Vaas) Market