
 Asia-Pacific Professional Scalp Treatment Products Market | 2026-2036
Asia-Pacific Professional Scalp Treatment Products Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Professional Scalp Treatment Products Market Insights
Peptide complexes and fermented botanical extracts are broadening formulation possibilities across the professional scalp treatment category. Amorepacific Corporation leverages decades of fermentation science to anchor its salon-exclusive scalp therapy lines. L'Oréal Professionnel sustains competitive intensity through dedicated R&D centers in Shanghai and Tokyo that specialize in Asian hair biology. Kao Corporation controls distribution depth across Japanese professional channels, where stylist certification programs lock in brand loyalty.
Professional scalp treatment products comprise clinically formulated topical preparations designed for application by licensed cosmetologists or trichologists, typically containing active concentrations of antifungal agents, exfoliating acids, or bioactive peptides at pH ranges calibrated to scalp skin rather than hair fiber. Their primary commercial purpose is to address pathological or subclinical scalp conditions through protocol-driven salon services that command premium pricing over retail equivalents. Serum formats targeting hair loss concerns carry the highest margin pools due to concentrated actives and repeat treatment cycles, while scalp mask applications are expanding fastest as add-on services in premium salons. Salon distribution channels retain the dominant value share, though e-commerce is fragmenting repurchase behavior for maintenance products between professional appointments.
China's NMPA and SAMR enforce escalating GB standards for cosmetic ingredient safety and advertising claims, compelling foreign entrants to complete extended domestic testing protocols before salon channel entry. Japan's MHLW and quasi-drug regulations create additional compliance layers for products making hair growth or anti-dandruff assertions, effectively segmenting the market between cosmetic and therapeutic positioning. South Korea's MFDS maintains rigorous manufacturing facility audits that professional brands must pass to supply the dense network of scalp care specialty salons concentrated in Seoul's Gangnam district. Stakeholders must monitor regulatory divergence across these three jurisdictions, as harmonization failure would multiply compliance costs for regional portfolio strategies.
Market Dynamics
Salon channel consolidation across Southeast Asia is compressing distributor margins and forcing professional brands to build direct education infrastructure for stylist certification. China's GB standards for cosmetic ingredient disclosure are simultaneously raising compliance costs and creating competitive moats for manufacturers with established domestic testing capabilities.
Growth Catalysts
- K-beauty protocol licensing:South Korean scalp care methodologies developed for professional channels are being exported to salons throughout Thailand, Vietnam, and Indonesia, creating standardized service frameworks that lock in product adoption.
- MFDS facility certification:South Korea's rigorous manufacturing audits create quality signaling that premium salons use to differentiate their scalp therapy menus from retail alternatives.
- Fermentation biotechnology:Advances in controlled fermentation processes are expanding the library of bioactive peptides available for scalp-specific formulations at concentration levels previously restricted to pharmaceutical applications.
Market Restraints
- Extended NMPA testing timelines:China's domestic cosmetic safety protocols add 18-24 months to foreign brand entry, freezing market share for early entrants with established compliance infrastructure.
- Active ingredient supply concentration:Pharmaceutical-grade minoxidil and peptide precursors source predominantly from Zhejiang and Jiangsu provinces, creating single-geography vulnerability for regional formulators.
- Quasi-drug classification friction:Japan's MHLW segments products making hair growth claims into separate regulatory tracks, forcing brands to maintain dual formulation portfolios or abandon therapeutic positioning.
Strategic Opportunities
- Vietnam salon network expansion:Ho Chi Minh City's emerging premium salon clusters remain undersupplied with professional scalp protocols, offering first-mover positioning before distributor relationships solidify.
- Maintenance product e-commerce:Direct-to-consumer repurchase channels for between-appointment scalp serums bypass salon markups while capturing lifetime value from protocol graduates.
- Dual carbon alignment:China's MEE environmental compliance frameworks reward manufacturers with carbon-efficient fermentation processes, creating procurement preference at state-affiliated salon chains.
Industry Challenges
- Trichologist certification scarcity:Qualified scalp diagnostics practitioners remain concentrated in Seoul and Tokyo, limiting protocol rollout speed in secondary cities.
- Legacy salon software integration:Appointment and inventory management systems at established Japanese salon chains require custom API development for professional product ordering portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Professional Scalp Treatment Products Market |
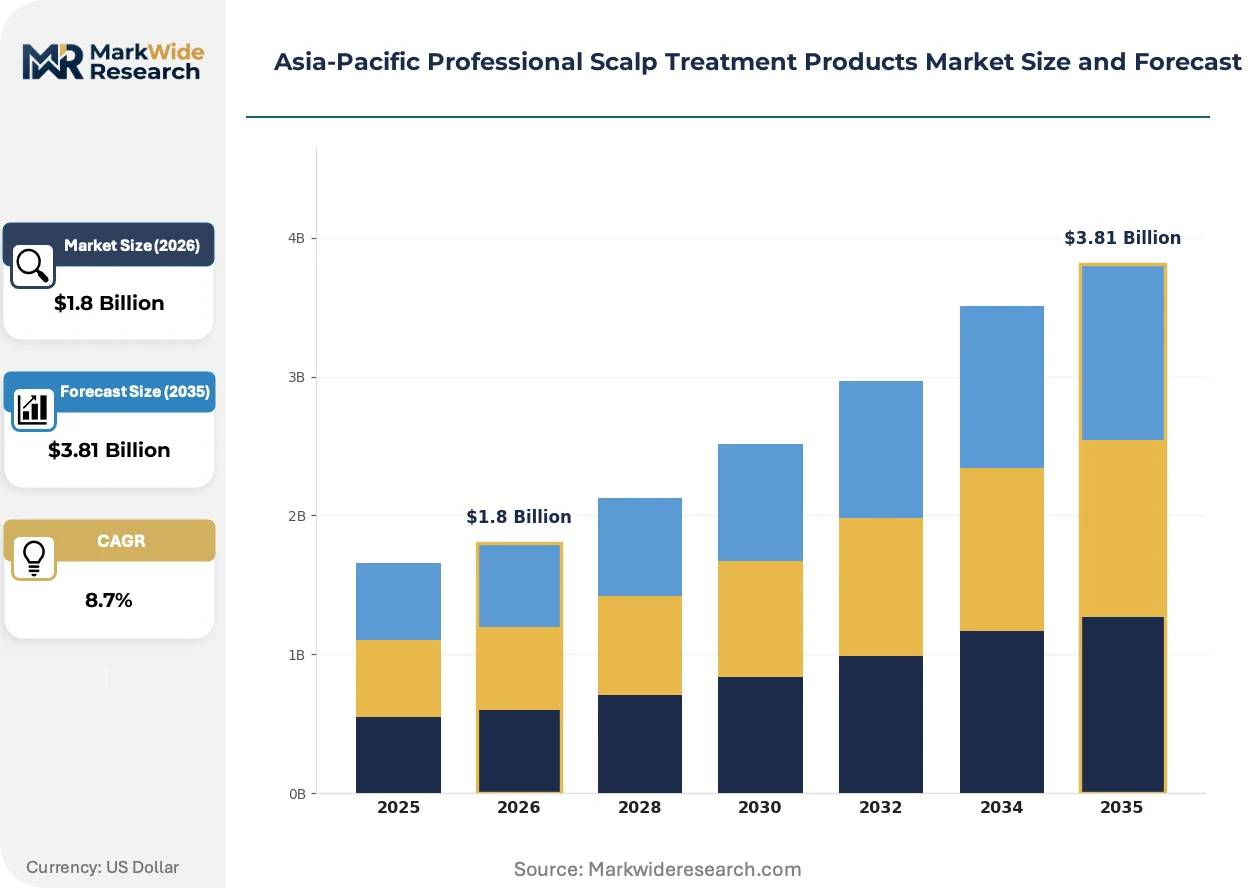
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoo, Serum, Conditioner, Scalp Mask Active Ingredient: Ketoconazole, Tea Tree Oil, Salicylic Acid, Aloe Vera Target Concern: Dandruff, Hair Loss, Itchiness, Scalp Sensitivity Distribution Channel: Salons, E-commerce, Retail Stores, Clinics |
| Companies Covered | Amorepacific Corporation, Milbon Co. Ltd, Shiseido Professional, Estée Lauder, Henkel Schwarzkopf Professional, L'Oréal Professionnel, KOSÉ Corporation, Davines Group, Kao Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Professional Scalp Treatment Products Market Trends and Innovations
Biotechnology advances and regulatory precision are converging to reshape how professional scalp treatments are formulated, positioned, and delivered through licensed channels. Three developments dominate the current transformation cycle.
Fermentation-derived peptide complexes are automating the scale-up of bioactive ingredient production that previously required synthetic chemistry at pharmaceutical cost structures. Premium salon chains in Seoul and Shanghai are adopting these actives for hair loss protocols within six-month certification cycles. The technology is automating margin expansion for manufacturers who previously faced raw material bottlenecks at clinical-grade purity thresholds.
China's SAMR has tightened enforcement of GB standards for cosmetic ingredient disclosure and advertising substantiation, requiring clinical documentation for any scalp health claims beyond basic cleansing. Foreign entrants must complete extended domestic testing protocols before salon channel authorization, effectively segmenting the market between compliant and non-compliant brand portfolios. Professional lines positioned as scalp wellness rather than therapeutic intervention face lower documentation burdens but sacrifice pricing power in medical-adjacent salon segments.
Salon clients are purchasing maintenance serums through brand-operated e-commerce platforms between scheduled appointments, fragmenting repurchase behavior away from stylist-mediated sales. This channel disintermediation is most visible in South Korea's Gangnam district scalp specialty salons, where digital-native consumers prefer subscription models over in-salon restocking. Professional brands are responding with QR-code activated repurchase flows that preserve stylist attribution while capturing direct consumer relationships.
Asia-Pacific Professional Scalp Treatment Products Market Segmentation
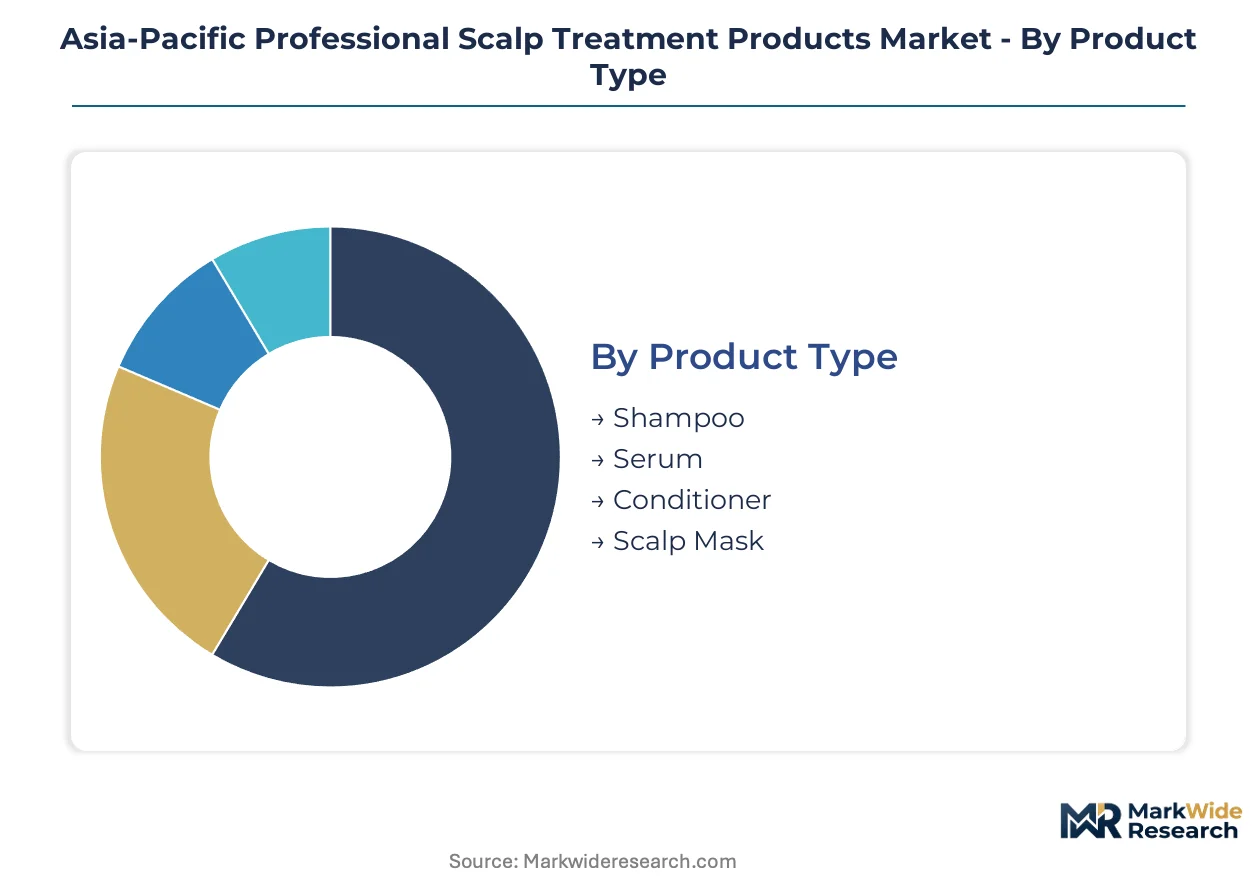
Professional scalp treatment products demand precise segmentation because regulatory pathways and pricing power diverge sharply across formulation types and channel positioning. Certification requirements from NMPA, MFDS, and MHLW create tiered compliance burdens that reshape competitive dynamics within each segment cluster.
Product Type:
Certification intensity escalates from rinse-off formats to leave-in treatments, with NMPA and MFDS imposing stricter stability testing on serums and masks designed for extended scalp contact.
- Serum:Concentrated peptide and minoxidil formulations requiring pharmaceutical-grade purity documentation. Demand concentrates in Seoul's Gangnam scalp specialty salons where MFDS-certified protocols command premium service pricing and repeat treatment cycles lock in client retention.
- Scalp Mask:Clay-based and bio-cellulose delivery systems for intensive exfoliation and hydration. Adoption accelerates across Bangkok and Ho Chi Minh City premium salons as add-on services that extend appointment duration without requiring trichologist certification.
- Shampoo:Lower-concentration active formulations with faster NMPA registration timelines.
- Conditioner:Rinse-off formats facing compressed margins due to retail channel competition.
Leading the category by volume: Shampoo. Growing fastest: Scalp Mask.
Active Ingredient:
Ingredient sourcing geography dictates supply security, with Zhejiang and Jiangsu provinces dominating pharmaceutical-grade precursor production for synthetic actives.
- Salicylic Acid:Beta-hydroxy acid exfoliant at concentrations requiring pH calibration for scalp skin tolerance. Procurement concentrates among Japanese formulators seeking METI-compliant manufacturing documentation for professional channel distribution.
- Ketoconazole:Antifungal agent subject to quasi-drug classification in Japan and pharmaceutical oversight in China. Clinical substantiation burdens limit brand participation to manufacturers with established NMPA testing infrastructure.
- Tea Tree Oil:Botanical extract with simpler cosmetic registration pathways across Asia-Pacific jurisdictions.
- Aloe Vera:Fermentation-derived variants gaining traction in K-beauty protocol licensing.
Dominant by formulation volume: Tea Tree Oil. Steepest expansion trajectory: Fermentation-enhanced Aloe Vera complexes.
Target Concern:
Regulatory claim substantiation thresholds separate cosmetic positioning from therapeutic assertions, with hair loss and dandruff categories facing heightened documentation requirements.
- Hair Loss:Peptide and growth factor formulations requiring clinical trial data for NMPA registration. Demand clusters in Tokyo and Osaka where MHLW quasi-drug classification restricts competitive entry to brands with dedicated regulatory affairs teams.
- Dandruff:Antifungal and keratolytic protocols with established efficacy documentation enabling faster salon channel penetration. Adoption spreads through Southeast Asian salon chains seeking standardized service menus with proven client retention metrics.
- Itchiness:Soothing formulations occupying mid-tier pricing with lower compliance barriers.
- Scalp Sensitivity:Barrier-repair positioning aligned with K-beauty wellness protocols.
Highest revenue concentration: Hair Loss. Expanding most quickly: Scalp Sensitivity.
Distribution Channel:
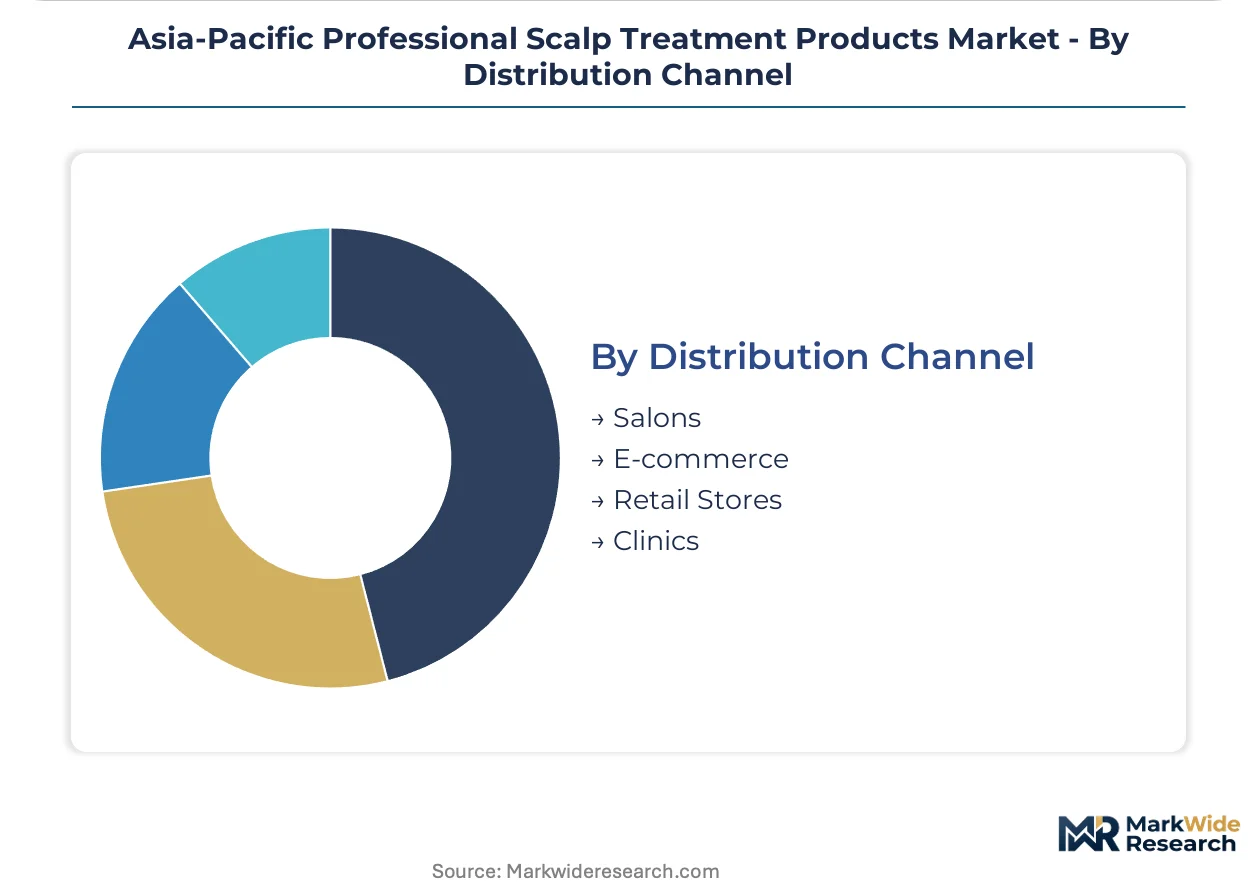
Channel selection determines margin structure and client relationship control, with salon-exclusive lines requiring stylist certification investments that e-commerce bypasses.
- Salons:Protocol-driven service delivery with locked-in product adoption through stylist training programs. Kao Corporation's certification infrastructure across Japanese professional channels exemplifies distribution depth that competitors struggle to replicate.
- E-commerce:Direct-to-consumer repurchase platforms capturing between-appointment maintenance serum sales. QR-code activation in South Korean salons preserves stylist attribution while fragmenting traditional channel economics.
- Clinics:Medical-adjacent positioning requiring elevated clinical substantiation.
- Retail Stores:Mass-market competition compressing professional brand pricing power.
Dominant value share: Salons. Gaining share fastest: E-commerce.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's Gangnam district operates as a specialized economic zone for scalp care innovation, concentrating K-beauty protocol development and MFDS-certified manufacturing facilities that supply premium salon chains across the Asia-Pacific region.
China
NMPA registration requirements for scalp serums with peptide actives extend foreign brand entry timelines to 18-24 months, compressing competitive pressure on early entrants. Shanghai's Yangtze River Delta hosts the densest cluster of professional product distributors serving salon chains expanding into Hangzhou and Suzhou secondary markets.
South Korea
MFDS facility audits create quality signaling that Gangnam scalp specialty salons leverage for premium positioning against retail alternatives. Seoul Capital Area manufacturers license K-beauty scalp protocols to Thai and Vietnamese salon operators, standardizing service frameworks that lock in product adoption.
Japan
MHLW quasi-drug classification segments hair growth formulations into separate regulatory tracks, forcing brands to maintain dual portfolios or abandon therapeutic claims. Osaka-Kansai salon chains retain deeper stylist certification infrastructure than Tokyo equivalents, locking in brand loyalty through Kao Corporation's professional education programs.
Vietnam
Ho Chi Minh City's emerging premium salon clusters remain undersupplied with professional scalp protocols, offering first-mover positioning before distributor relationships solidify. Local salon entrepreneurs import Korean-certified products through Da Nang logistics hubs to bypass extended NMPA timelines for China-sourced alternatives.
Thailand
Bangkok's Sukhumvit salon corridor adopts scalp mask add-on services to extend appointment duration without requiring trichologist certification. Thai distributors partner with Seoul-based manufacturers to localize K-beauty protocols for Southeast Asian hair biology, creating regional adaptation hubs.
Asia-Pacific Professional Scalp Treatment Products Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with salon-exclusive lines commanding premium positioning through stylist certification investments while private-label suppliers capture volume in emerging markets. The vendor base concentrates among fermentation-science heritage houses and dedicated professional divisions of beauty conglomerates. Three archetypes dominate: K-beauty protocol licensors, Japanese distribution-depth specialists, and European professional brands with Asian R&D localization. Competitive moves center on direct education infrastructure buildout and e-commerce channel disintermediation for maintenance product repurchase.
Within the fermentation-science tier, Amorepacific Corporation anchors Korean-origin protocol development, while Kao Corporation exemplifies Japanese distribution-depth strategies through stylist certification lock-in. L'Oréal Professionnel occupies a position bridging European brand heritage with Shanghai and Tokyo R&D localization for Asian hair biology specialization.
| Leading Market Players |
|---|
| Amorepacific Corporation |
| Milbon Co. Ltd |
| Shiseido Professional |
| Estée Lauder |
| Henkel Schwarzkopf Professional |
| L'Oréal Professionnel |
| KOSÉ Corporation |
| Davines Group |
| Kao Corporation |
| Others |
Pricing and Supply Chain Analysis
Pharmaceutical-grade peptide precursor costs originating from Zhejiang and Jiangsu provinces cascade through three distinct pricing tiers before reaching Seoul's Gangnam scalp specialty salons, with MFDS certification status determining margin capture at each downstream node.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations, with salons paying elevated rates for NMPA-registered serums held in Shanghai bonded warehouses versus spot inventory sourced through Da Nang logistics hubs. Three-tier pricing structure across MFDS-certified, NMPA-registered, and unregistered cosmetic tiers reflects documentation burden differentials. Pricing pressure stems from salon channel consolidation across Southeast Asia compressing distributor markups. Independent Ho Chi Minh City salon operators exhibit highest price sensitivity, while Tokyo's Osaka-Kansai chain affiliates absorb premiums for Kao Corporation certification lock-in.
Supply Chain Analysis
MFDS facility certification gates upstream supplier qualification, with Seoul Capital Area manufacturers, Shanghai Yangtze River Delta formulators, and Osaka-Kansai production sites constituting the tripartite supply base. Active ingredient sourcing draws from Zhejiang province peptide precursors, Jiangsu province minoxidil intermediates, and Korean fermentation biotechnology outputs. Single-geography concentration in east-central China creates vulnerability to NMPA inspection backlogs. Distribution runs through salon-exclusive authorized distributors in Japan, direct brand-to-salon relationships in South Korea, and fragmented import agents in Vietnam and Thailand.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation-derived peptide automation is displacing synthetic chemistry cost structures, compressing legacy formulators while rewarding biotechnology heritage houses with margin expansion headroom.
For Market Incumbents: Cement stylist certification infrastructure as a defensive moat against K-beauty protocol licensors expanding through Southeast Asia. Invest in backward integration into captive peptide fermentation capacity to offset Zhejiang precursor supply concentration. Prioritize NMPA testing pipeline expansion to exploit 18-24 month foreign entrant delays.
For New Entrants and Emerging Players: Capture Ho Chi Minh City premium salon clusters before distributor relationships solidify around Korean-imported protocols. Target scalp mask add-on services in Bangkok's Sukhumvit corridor where trichologist certification requirements are absent. Deploy QR-code activated e-commerce repurchase flows to fragment traditional salon channel economics.
For Investors and Strategic Acquirers: MFDS facility audit completion announcements are the leading indicator that Korean manufacturers are scaling export licensing operations. Position for 5-10 year horizon consolidation around fermentation-science specialists with established professional channel education infrastructure. Monitor NMPA registration timeline compression as signal for foreign brand entry acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| K-beauty Protocol Licensing | Standardized service frameworks lock in product adoption across Thai and Vietnamese salon networks. |
| MFDS Facility Certification | Quality signaling enables premium positioning against retail alternatives in Seoul's Gangnam district. |
| E-commerce Repurchase Channel | QR-code activation preserves stylist attribution while capturing direct consumer lifetime value. |
| NMPA Testing Infrastructure | Domestic compliance capability creates competitive moat against delayed foreign brand entry. |
| Fermentation Scale-Up Investment | Automated bioactive production expands margin pools previously restricted to pharmaceutical cost structures. |
Research Methodology
Trade databases, regulatory filing repositories, and salon industry association publications formed the secondary backbone, supplemented by primary interviews with Seoul scalp specialty salon owners, Shanghai professional product distributors, Tokyo stylist certification program directors, and Ho Chi Minh City salon entrepreneurs. Bottom-up volume estimates from salon service menu pricing and product procurement patterns were triangulated against top-down market sizing from manufacturer shipment disclosures and import customs records.
Historical trendline analysis of salon service adoption rates and professional product shipment volumes established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product type, active ingredient class, target concern category, and distribution channel dimensions. CAGRs were derived from regression analysis of documented adoption curves and regulatory timeline impacts, with NMPA registration delays and MFDS audit cycles serving as industry-specific forecast modifiers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA timeline compression, fermentation technology cost curves, and salon channel consolidation velocity. Forecasts reflect documented assumptions regarding regulatory pathway stability and peptide precursor supply geography. A model refresh is warranted upon material change in China's cosmetic ingredient disclosure enforcement posture or Korean manufacturing facility audit throughput.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Signal Transformer Market
Others
United States Printed Signage Market
Others
Europe Intercom Devices Market
Others
Latin America Smart Home Market
Others
Global Electronic Filters Market
Others
Coalescing Filter Market
Others
Canada Feed Additives Market
Others
Global Hair Loss Treatment Products Market
Others
Smart TV Platforms Market
Others
India Foundry Market
Others
Latin America Domestic CEP Market
Others
North America Medical Simulation Market
Others
Aluminium Clad Printed Circuit Board Market
Others
Folding Mobile Phone Market
Others
Solar Panel Testers Market
Others
Agitation System Market