
 Smart TV Platforms Market | 2026-2036
Smart TV Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Smart TV Platforms Market Insights
South Korea is reconfiguring its display panel and semiconductor supply chains to support integrated smart TV platform ecosystems. Samsung Electronics leverages vertical control over OLED and QD-OLED manufacturing to sustain proprietary Tizen OS distribution across its global installed base. LG Electronics anchors its webOS platform through premium display specialization and differentiated content partnerships with major streaming aggregators.
Smart TV platforms are software operating environments embedded within connected television hardware, enabling content aggregation, application execution, and interactive services through internet protocol delivery with processing capabilities typically exceeding 1.5 GHz multi-core architectures. Their primary commercial purpose centers on capturing viewer engagement data to monetize through subscription revenue shares and targeted advertising insertion. Android TV dominates platform type volume through Google's licensure model, while Roku competes aggressively in North American retail channels with low-cost hardware bundling. Voice-controlled interfaces represent the fastest-expanding user interface category as natural language processing integration reduces navigation friction for content discovery.
The Federal Communications Commission governs broadband infrastructure standards that directly determine streaming quality thresholds for platform operators, while the EU AI Act imposes algorithmic transparency obligations on recommendation engines deployed across European territories. California's Consumer Privacy Act creates compliance complexity for advertising-based platforms processing viewer behavioral data across state lines. Stakeholders must monitor regulatory fragmentation between data localization requirements and cross-border content licensing frameworks as platform operators scale internationally.
Market Dynamics
Algorithmic content recommendation engines face intensifying transparency mandates under the EU AI Act, forcing platform operators to rearchitect data processing pipelines and disclosure frameworks while maintaining engagement metrics.
Growth Catalysts
- Streaming service proliferation:Residential households across the United States are abandoning linear broadcast subscriptions, creating installed base expansion for connected TV hardware and embedded platform software.
- EU AI Act compliance requirements:European algorithmic transparency obligations are accelerating investment in explainable recommendation systems and auditable content curation infrastructure.
- Voice interface integration:Natural language processing capabilities embedded in remote controls and far-field microphone arrays are reducing content discovery friction for demographic segments less comfortable with traditional navigation paradigms.
Market Restraints
- Display panel supply concentration:South Korean and Chinese manufacturers control advanced OLED and QD-OLED substrate production, creating vulnerability for platform operators dependent on premium hardware differentiation.
- Cross-border data localization:Fragmented national requirements for viewer behavioral data storage are multiplying compliance infrastructure costs for advertising-supported platform business models.
- Silicon fabrication bottlenecks:Multi-core processor architectures exceeding 1.5 GHz face foundry capacity constraints, limiting hardware refresh cycles and platform upgrade velocity.
Strategic Opportunities
- India broadband infrastructure expansion:Fiber-to-the-home deployment and affordable data tariffs are creating first-time smart TV adoption among price-sensitive consumer segments previously excluded from connected television ecosystems.
- Healthcare and wellness applications:Camera-enabled biometric monitoring integrated with smart TV platforms opens subscription revenue streams in remote patient observation and fitness coaching verticals.
- Connected TV advertising migration:Brand budgets shifting from linear broadcast to programmatic insertion create margin expansion for platform operators with advanced audience segmentation and measurement capabilities.
Industry Challenges
- Machine learning engineer scarcity:Talent competition with pure-play technology firms complicates in-house development of competitive recommendation algorithms and natural language processing systems.
- Content licensing fragmentation:Territory-specific streaming rights and exclusivity windows force platform operators to maintain complex geographic content availability matrices and dynamic geo-blocking infrastructure.
- Legacy broadcast integration:Hybrid tuner and IP-delivered content unification demands sustained engineering investment as transitional markets maintain dual consumption patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart TV Platforms Market |
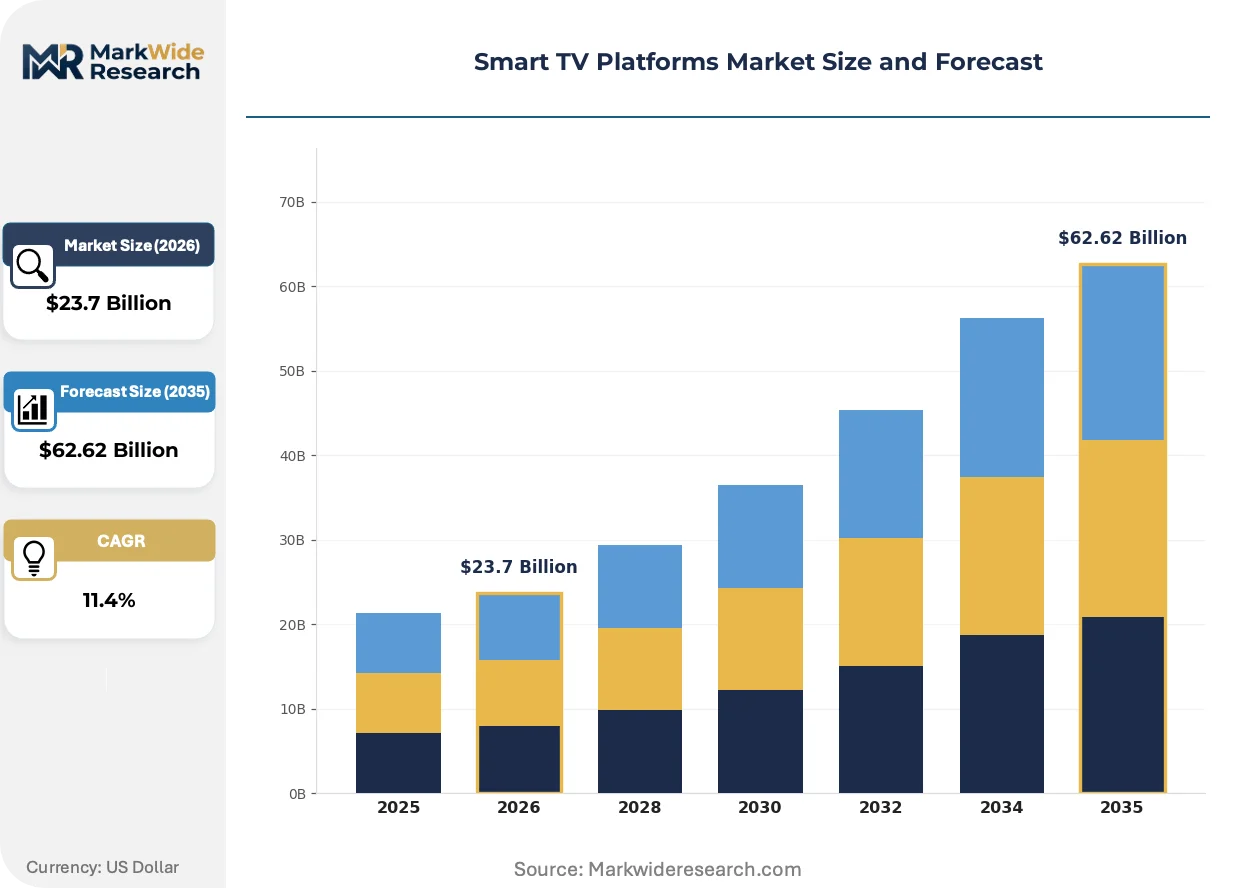
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Android TV, Roku, Tizen, webOS Content Type: Streaming Services, On-Demand, Live TV, Software Applications User Interface: Voice-Controlled, Touch, Remote-Operated, Gesture-Based End User: Consumers, Retailers, Advertisers, Service Providers |
| Companies Covered | Google, Samsung Electronics, LG Electronics, Roku Inc., Amazon, Sony Corporation, Hisense, TCL Technology, Vizio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart TV Platforms Market Trends and Innovations
Convergence between artificial intelligence inference at the edge and cloud-orchestrated content delivery is redefining hardware-software boundary lines across smart TV platform architectures.
On-device machine learning accelerators are enabling real-time content personalization without round-trip latency to centralized data centers. Premium television manufacturers are embedding neural processing units capable of 4-8 TOPS performance in 2024 hardware refreshes. This distributed intelligence architecture is rendering obsolete the previous generation of thin-client streaming sticks dependent entirely on cloud-side recommendation engines.
The EU AI Act's algorithmic transparency provisions are mandating documented explainability for content ranking systems deployed across European territories. Platform operators must now maintain technical documentation demonstrating how viewer behavioral signals influence recommendation outputs. Connected TV advertising segments operating behavioral targeting models face the steepest compliance reconfiguration timelines and audit preparation burdens.
Subscription fatigue among United States households is fragmenting content budgets across multiple streaming services rather than consolidating around single-platform bundles. Consumers are rotating subscriptions monthly based on release calendars, forcing platform operators to invest in churn prediction models and dynamic retention pricing. This behavioral pattern is most pronounced among 25-40 year old demographics in coastal metropolitan markets with abundant broadband competition and lower switching costs.
Smart TV Platforms Market Segmentation
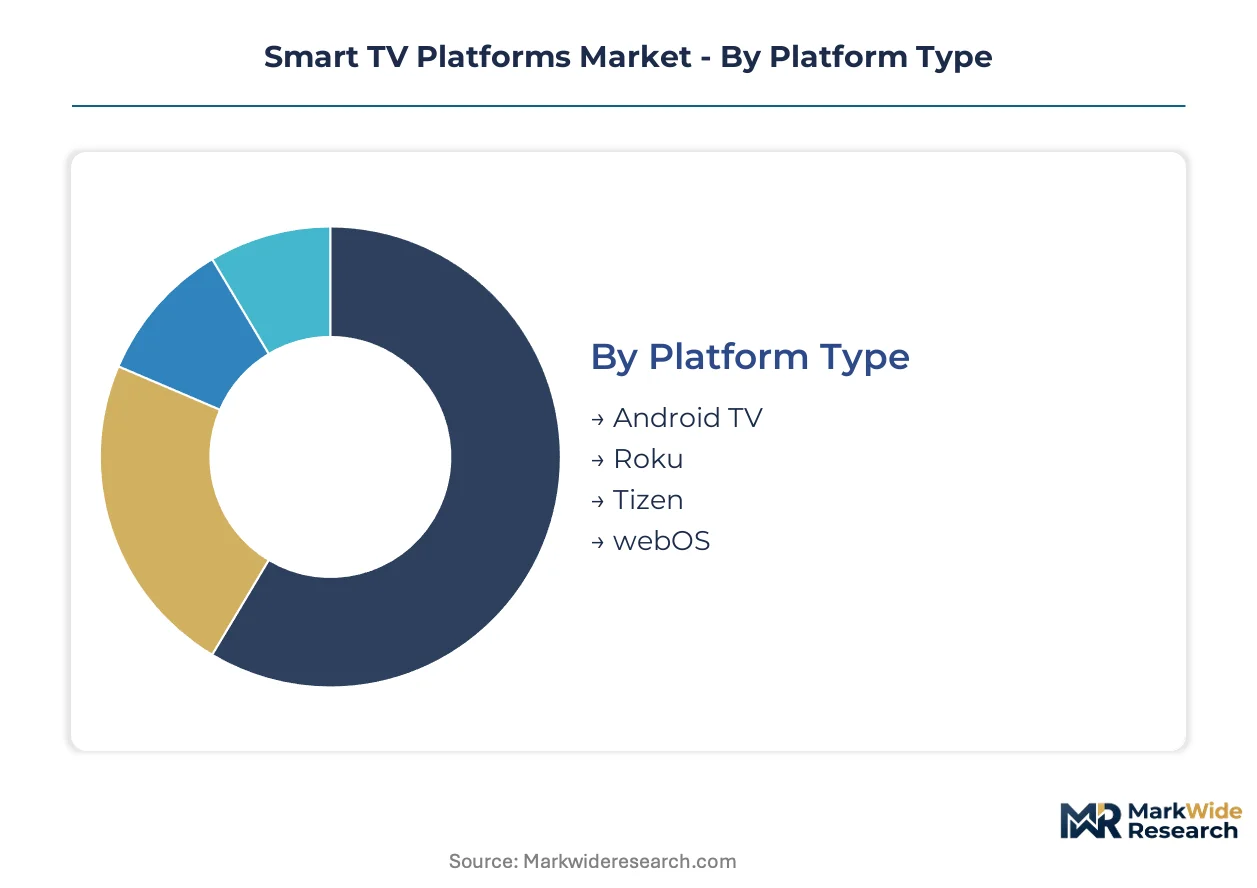
Smart TV platform segmentation reveals divergent monetization models and technical requirements across software environments, content delivery modes, and user interaction paradigms. Platform operators calibrate engineering investment and partnership structures based on segment-specific engagement patterns and revenue sharing mechanics.
Platform Type:
After-sales service intensity varies sharply across platform ecosystems, with licensed operating systems demanding continuous security patching and third-party application compatibility management while proprietary stacks require dedicated developer relations and content partnership maintenance.
- Android TV:Google's licensure model enables rapid manufacturer deployment through standardized SDK frameworks and Play Store application distribution. Demand concentrates among Chinese and Indian television OEMs seeking low-friction software integration without captive engineering investment, though Google Services compliance creates recurring certification overhead.
- Roku:This vertically controlled platform combines proprietary hardware reference designs with advertising-revenue sharing agreements. North American retail channels represent the primary demand concentration, driven by aggressive low-cost streaming stick bundling and connected TV advertising inventory aggregation.
- Tizen:Samsung Electronics maintains exclusive distribution across its global display manufacturing output, enabling tight hardware-software optimization for QD-OLED and Neo QLED performance tiers.
- webOS:LG Electronics anchors this Linux-derived environment through premium OLED display specialization and streaming aggregator partnerships differentiated by content curation interfaces.
Android TV holds the largest share; momentum sits with Roku in North American advertising-supported deployments.
Content Type:
Cost tier differentiation separates high-investment original programming infrastructure from lightweight application delivery models with minimal content acquisition expenditure.
- Streaming Services:Subscription video-on-demand platforms command the highest revenue per user through exclusive licensed and original content libraries. United States residential households drive demand concentration as cord-cutting accelerates migration from linear broadcast infrastructure, though content licensing fragmentation across territories complicates global platform scaling.
- On-Demand:Transactional and ad-supported rental models capture occasional viewers without subscription commitment. Emerging market penetration expands most quickly where credit card ownership remains limited and carrier billing integration enables micro-transaction accessibility.
- Live TV:Internet-delivered linear programming replicates traditional broadcast consumption patterns for sports and news verticals.
- Software Applications:Gaming, fitness, and utility applications extend platform engagement beyond video consumption with lower infrastructure intensity.
Streaming Services holds the largest share; momentum sits with Software Applications in healthcare and wellness verticals.
User Interface:
Volume concentration shifts toward reduced-friction interaction modes as demographic expansion beyond early-adopter segments demands accessibility accommodation.
- Voice-Controlled:Natural language processing integration through far-field microphone arrays and remote control embedded microphones reduces navigation friction for content discovery. Demand concentrates among aging demographics and accessibility-focused deployments where traditional menu hierarchies create interaction barriers, with Amazon Alexa and Google Assistant SDK licensing enabling rapid OEM integration.
- Touch:Direct screen interaction persists in commercial and hospitality installations with specialized mounting configurations.
- Remote-Operated:D-pad and pointer-based navigation remains standard for lean-back living room consumption contexts.
- Gesture-Based:Camera-enabled motion control captures niche fitness and gaming applications with biometric monitoring extension potential.
Remote-Operated holds the largest share; Voice-Controlled is expanding most quickly through smart speaker ecosystem convergence.
End User:
Customer type determines platform feature prioritization, with advertising-supported business models demanding granular behavioral analytics infrastructure absent from consumer-direct subscription configurations.
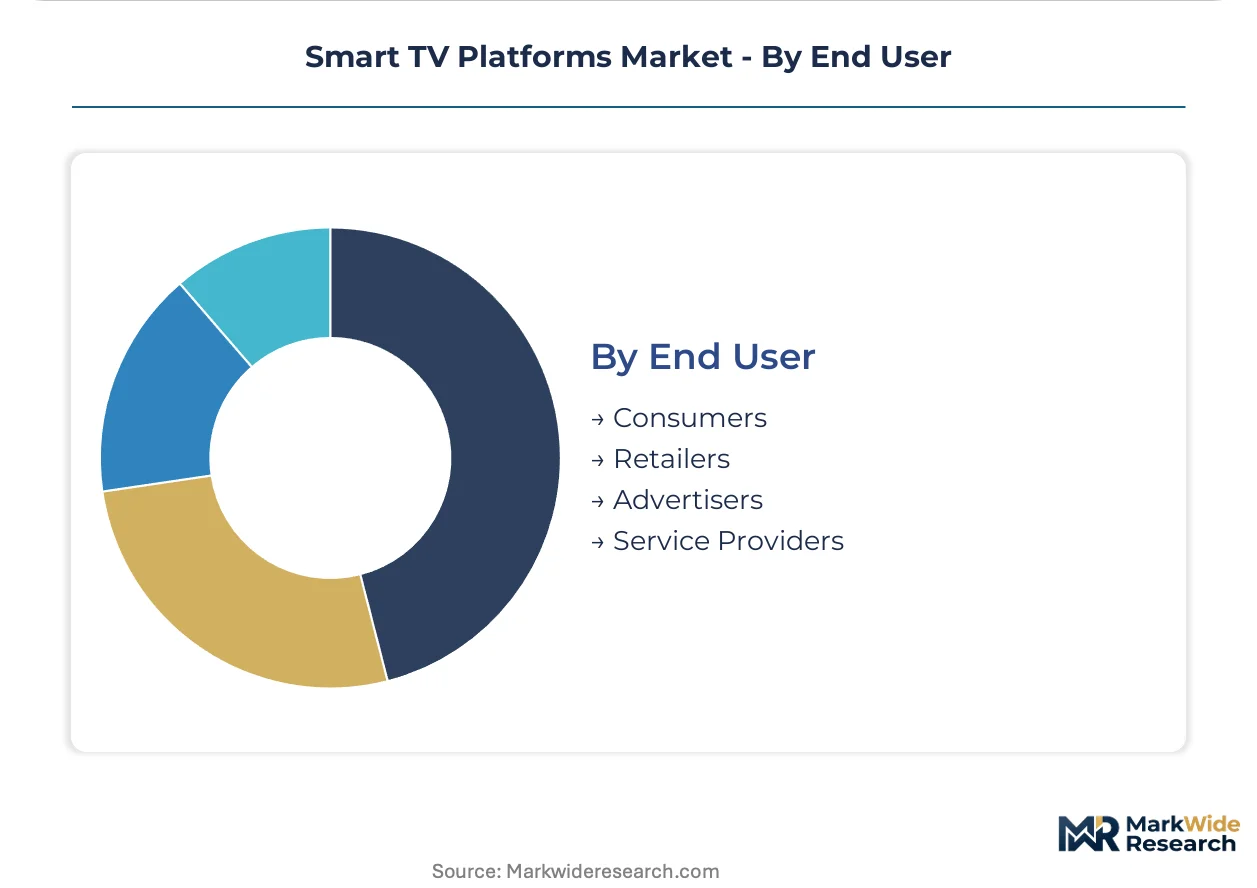
- Consumers:Residential households represent the foundational demand segment with platform selection driven by content library breadth, hardware price positioning, and ecosystem integration with existing mobile and smart home devices. United States coastal metropolitan markets exhibit highest platform switching frequency as subscription rotation behavior fragments loyalty across multiple services.
- Advertisers:Programmatic insertion demand concentrates among brands migrating budgets from linear broadcast to connected TV addressability, requiring advanced audience segmentation and cross-platform measurement capabilities.
- Retailers:Electronics merchants leverage platform partnerships for promotional content placement and private-label streaming service bundling.
- Service Providers:Telecommunications and broadband operators deploy white-label platform integrations to reduce subscriber churn through video service bundling.
Consumers holds the largest share; Advertisers demonstrate steepest expansion trajectory as connected TV measurement infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC governs broadband infrastructure standards that directly determine streaming quality thresholds for platform operators in the United States, while the EU AI Act imposes algorithmic transparency obligations on recommendation engines deployed across European territories.
United States
Cord-cutting behavior and connected TV advertising budgets migrating from linear broadcast infrastructure drive platform deployment acceleration. The FCC's broadband infrastructure standards determine streaming quality thresholds for platform operators. Coastal metropolitan markets exhibit highest platform switching frequency as subscription rotation behavior fragments loyalty across multiple services.
South Korea
Display panel and semiconductor supply chain reconfiguration supports integrated smart TV platform ecosystems. The Korea Communications Commission regulates broadcasting and communications infrastructure standards. Samsung Electronics leverages vertical control over OLED and QD-OLED manufacturing in Suwon and Gumi industrial clusters to sustain proprietary Tizen OS distribution.
China
Television OEMs seeking low-friction software integration without captive engineering investment concentrate demand for licensed operating systems. The Cyberspace Administration of China imposes data localization requirements for viewer behavioral data processing. Shenzhen and Dongguan manufacturing hubs host production lines for Android TV-integrated hardware targeting domestic and export markets.
Germany
EU AI Act compliance requirements accelerate investment in explainable recommendation systems and auditable content curation infrastructure. The Federal Network Agency oversees telecommunications and broadcasting regulation. Berlin and Munich technology clusters host engineering centers developing algorithmic transparency documentation for European market deployment.
India
Fiber-to-the-home deployment and affordable data tariffs create first-time smart TV adoption among price-sensitive consumer segments. TRAI regulates broadcasting and cable services with emerging framework attention to OTT platform classification. Bengaluru and Hyderabad technology corridors concentrate software development talent for platform localization and regional content aggregation partnerships.
Smart TV Platforms Market Competitive Landscape
Vertically integrated electronics conglomerates and advertising-optimized streaming specialists split the market into distinct competitive spheres. Platform licensing models from technology licensors enable rapid manufacturer deployment, while proprietary stack operators maintain tight hardware-software optimization. Two strategic archetypes dominate: captive ecosystem builders controlling full manufacturing-to-software stacks, and horizontal platform licensors monetizing through services revenue share. Competitive moves concentrate on content partnership exclusivity arrangements and voice assistant ecosystem integration.
Within the captive ecosystem tier, Samsung Electronics and LG Electronics exemplify vertical integration strategies through proprietary operating system distribution tied to display manufacturing output. Google occupies a position as the dominant horizontal platform licensor through Android TV deployment across third-party hardware OEMs. Roku Inc. anchors the advertising-optimized specialist archetype with vertically controlled hardware reference designs and connected TV inventory aggregation. These three companies represent the primary strategic positioning vectors that other market participants must navigate or partner around.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Roku Inc. |
| Amazon |
| Sony Corporation |
| Hisense |
| TCL Technology |
| Vizio |
| Others |
Pricing and Supply Chain Analysis
Suwon and Gumi industrial clusters in South Korea concentrate QD-OLED and Neo QLED substrate manufacturing, granting Samsung Electronics captive cost advantages that translate into pricing power across premium television tiers where display performance commands brand premiums.
Pricing Analysis
North American retail channels exhibit wider price spreads than Asian direct-to-consumer markets due to connected TV advertising revenue subsidization. Three-tier pricing structure across premium, standard, and economy levels differentiates hardware based on neural processing unit performance and content partnership exclusivity. Cost compression in economy tiers is intensifying because Chinese OEMs leverage Android TV licensure to bypass proprietary engineering investment. Price-sensitive first-time adopters in India and Southeast Asia drive volume, while least-sensitive buyers cluster in United States coastal metropolitan markets seeking ecosystem integration with existing smart home infrastructure.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for platform operators dependent on Shenzhen and Dongguan manufacturing hubs. Taiwan, South Korea, and China concentrate advanced semiconductor foundry capacity for multi-core processors exceeding 1.5 GHz, while OLED substrate production rests on South Korean and Chinese chemical vapor deposition equipment. Single-source vulnerability persists in neural processing unit IP licensing from ARM and Synaptics. Distribution runs through electronics retail chains, telecommunications bundling agreements, and direct-to-consumer e-commerce platforms with regional fulfillment center localization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where installed base network effects and regulatory entrenchment under the EU AI Act create durable competitive positions for established platform operators with compliant algorithmic infrastructure.
For Market Incumbents: Entrench proprietary recommendation engine architectures through accelerated EU AI Act documentation investment before compliance deadlines tighten. Deepen captive supply of display panel capacity in South Korean industrial clusters to insulate against Chinese substrate pricing volatility. Voice assistant ecosystem integration represents the critical lever for reducing subscriber churn as subscription rotation behavior fragments United States household loyalty. For New Entrants and Emerging Players: Healthcare and wellness verticals in aging European and North American demographics represent the most penetrable entry point for camera-enabled biometric monitoring applications with lower content licensing overhead than streaming aggregation. India's fiber-to-the-home expansion corridors offer white-space deployment for white-label platform integrations with telecommunications operators seeking video bundling differentiation. Partner with regional content aggregators rather than competing for exclusive streaming rights against capitalized incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform operators with on-device machine learning accelerator integration and explainable recommendation system documentation already filed with European regulators. Long-term viability across the projection horizon hinges on algorithmic transparency compliance rather than hardware refresh velocity. Acquisition targets should demonstrate completed EU AI Act technical documentation and established partnerships with at least two major streaming aggregators. The signal to watch is regulatory enforcement action against non-compliant behavioral targeting models in connected TV advertising segments.| Strategic Initiative | Industry Significance |
|---|---|
| On-Device ML Accelerator Integration | Neural processing units enable real-time personalization without cloud latency, displacing thin-client streaming sticks. |
| EU AI Act Compliance Documentation | Explainable recommendation system audits create regulatory moats against non-compliant advertising-optimized competitors. |
| Voice Assistant Ecosystem Partnership | Amazon Alexa and Google Assistant SDK licensing reduces friction for aging demographics and accessibility-focused deployments. |
| Healthcare Application Platform Extension | Camera-enabled biometric monitoring opens subscription revenue streams in remote patient observation verticals. |
| Regional Content Aggregation Licensing | Partnerships with India and Southeast Asian streaming services enable localization without exclusive content acquisition costs. |
Research Methodology
Desk research of SEC filings from connected TV hardware manufacturers, FCC broadband infrastructure reports, and EU regulatory transparency databases preceded structured interviews with platform engineering directors, streaming service partnership leads, connected TV advertising operations managers, and telecommunications bundling strategists. Primary fieldwork validated secondary data on algorithmic recommendation system architectures and content licensing fragmentation patterns. Bottom-up television shipment modeling triangulated against top-down advertising revenue projections across the analysis window.
Assumption sets held fixed include prevailing EU AI Act enforcement timelines, FCC broadband quality thresholds, and South Korean display panel capacity expansion plans, while variables included India fiber-to-the-home deployment velocity and United States subscription rotation behavioral persistence. The analytical framework segmented volume and value across platform type, content delivery mode, user interface paradigm, and end-user archetype throughout the forecast period. CAGRs derived from installed base replacement cycles, streaming service proliferation curves, and connected TV advertising budget migration patterns.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending, broadband infrastructure investment commitments, or cross-border data localization enforcement would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory compliance timelines and hardware refresh elasticity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Profiling Floats Market
Others
Saudi Arabia Cat Food Market
Others
Mobile Computer Cart Market
Others
Global Pumpkin Candles Market
Others
US 3D Printing Construction Market
Others
Cremation Furnace Market
Others
Aerospace Software Testing Market
Others
High-Performance Films Market
Others
Rope Market
Others
Shear Testing Equipment Market
Others
UAE Location-Based Services Market
Others
Aircraft Lighting Market
Others
India Home Automation Market
Others
Mexico Retail Market
Others
Radar Speed Signs Market
Others
Mexico 3D Printing Construction Market