
 Couscous Market | 2026-2036
Couscous Market Size, Share, and Industry Trends Forecast 2026-2036
Couscous Market Analysis
Recipe-based subscription kits and chef-curated meal bundles is broadening how couscous reaches end consumers beyond conventional retail. Ebro Foods, S.A. leverages its Mediterranean milling infrastructure to sustain consistent semolina supply across European markets. Tipiak S.A. anchors its competitive position through frozen and ambient prepared couscous formats in French retail channels. Barilla G. e R. Fratelli S.p.A. extends its pasta manufacturing expertise into whole-grain and flavored couscous variants for health-oriented shoppers.
Couscous denotes steamed granules of durum wheat semolina, traditionally formed by rolling moistened semolina into small pellets and steaming until light and fluffy, with instant variants pre-cooked and dried for reduced preparation time. The product serves as a staple carbohydrate across North African, Middle Eastern, and increasingly Western European cuisines. Traditional couscous occupies mature volume pools in ethnic retail and food service, while instant formats capture faster growth in convenience-driven households and online retail channels. Whole grain segments concentrate margin pools through premium positioning in specialty stores and health-focused supermarkets.
EFSA labeling standards and EU Green Deal agricultural targets shape durum wheat sourcing and carbon footprint disclosure across European supply chains. Morocco's national food safety authority and CODEX-aligned export certification govern access to international markets from the Maghreb production base. USDA organic and non-GMO verification programs influence North American import specifications and retail placement. Stakeholders must monitor evolving clean-label requirements and origin-traceability mandates as procurement criteria tighten across major import jurisdictions.
Market Dynamics
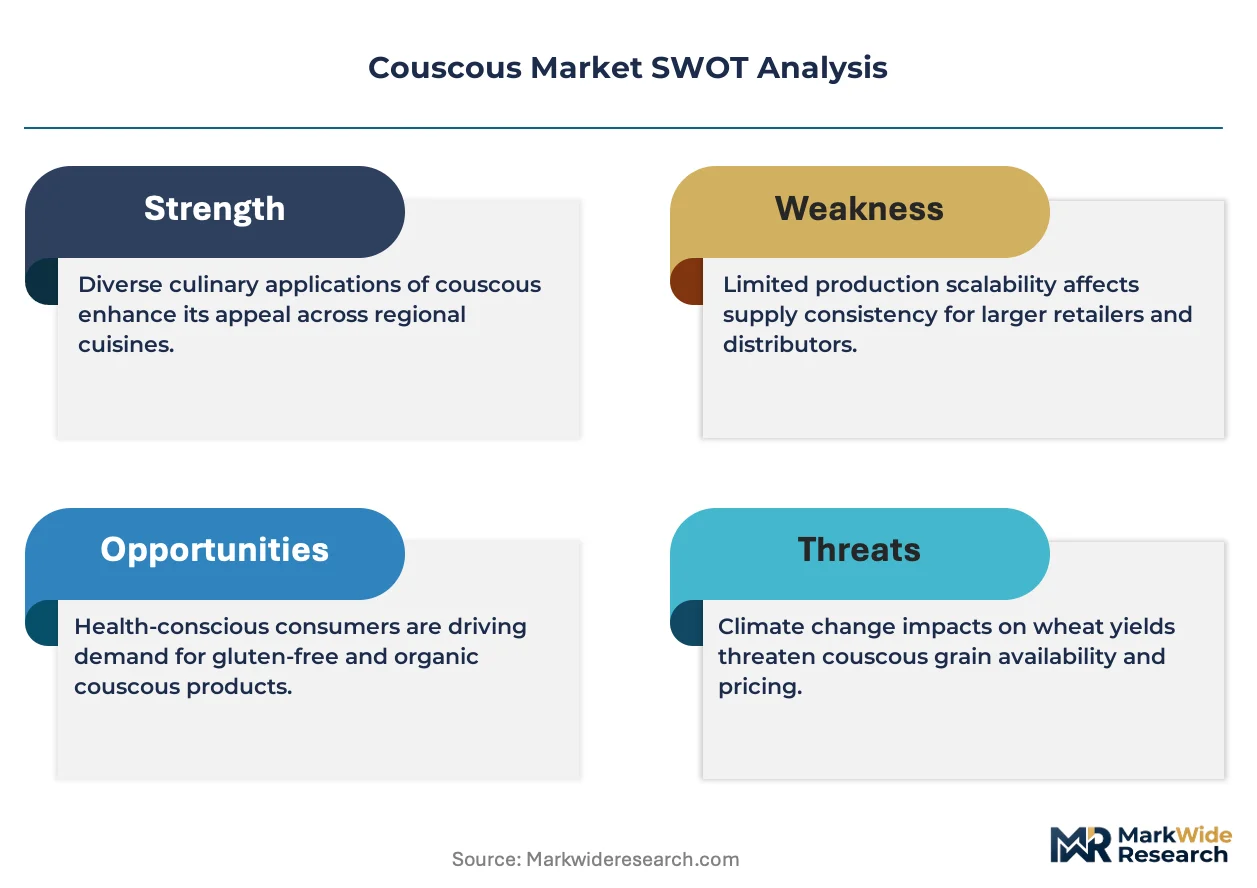
EU Green Deal agricultural targets are forcing durum wheat suppliers to restructure carbon disclosure and origin-traceability systems across Mediterranean supply chains, compressing margins for non-compliant millers while advantaging certified Moroccan and Italian clusters.
Growth Catalysts
- EFSA Clean-Label Mandates:Ingredient disclosure requirements under EU food safety frameworks are pushing reformulation toward shorter, recognizable component lists that favor traditional semolina-based products over additive-heavy alternatives.
- Steam-injection milling:Advanced pre-cooking technologies are reducing hydration variability and cutting production cycle times for instant couscous formats in industrial facilities.
- French retail consolidation:Hypermarket chains are expanding dedicated world-food aisles that allocate premium shelf space to North African staple categories.
Market Restraints
- Durum wheat price volatility:Climate stress on Canadian Prairie and Black Sea harvests is transmitting input cost spikes directly to semolina processors.
- Morocco production concentration:Artisanal cooperatives and industrial mills cluster in the Marrakech-Safi corridor, creating single-source vulnerability for European import contracts.
- Quinoa and bulgur substitution:Health-positioned grains are capturing carbohydrate occasions in meal-kit and food-service channels.
Strategic Opportunities
- German organic retail expansion:Discounters and full-range supermarkets are adding North African product lines to satisfy demand for Mediterranean diet components.
- Carbon farming incentives:EU Common Agricultural Policy eco-schemes are subsidizing regenerative durum cultivation that qualifies for premium export certification.
- Chef-curated subscription channels:Direct-to-consumer recipe platforms are bypassing traditional retail markups for heritage grain products.
Industry Challenges
- Semolina grading expertise scarcity:Mill operators lack sufficient trained personnel to evaluate granule size distribution for consistent steaming performance.
- CODEX alignment timelines:Moroccan exporters face extended certification delays when reconciling national food safety authority standards with importer country requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Couscous Market |
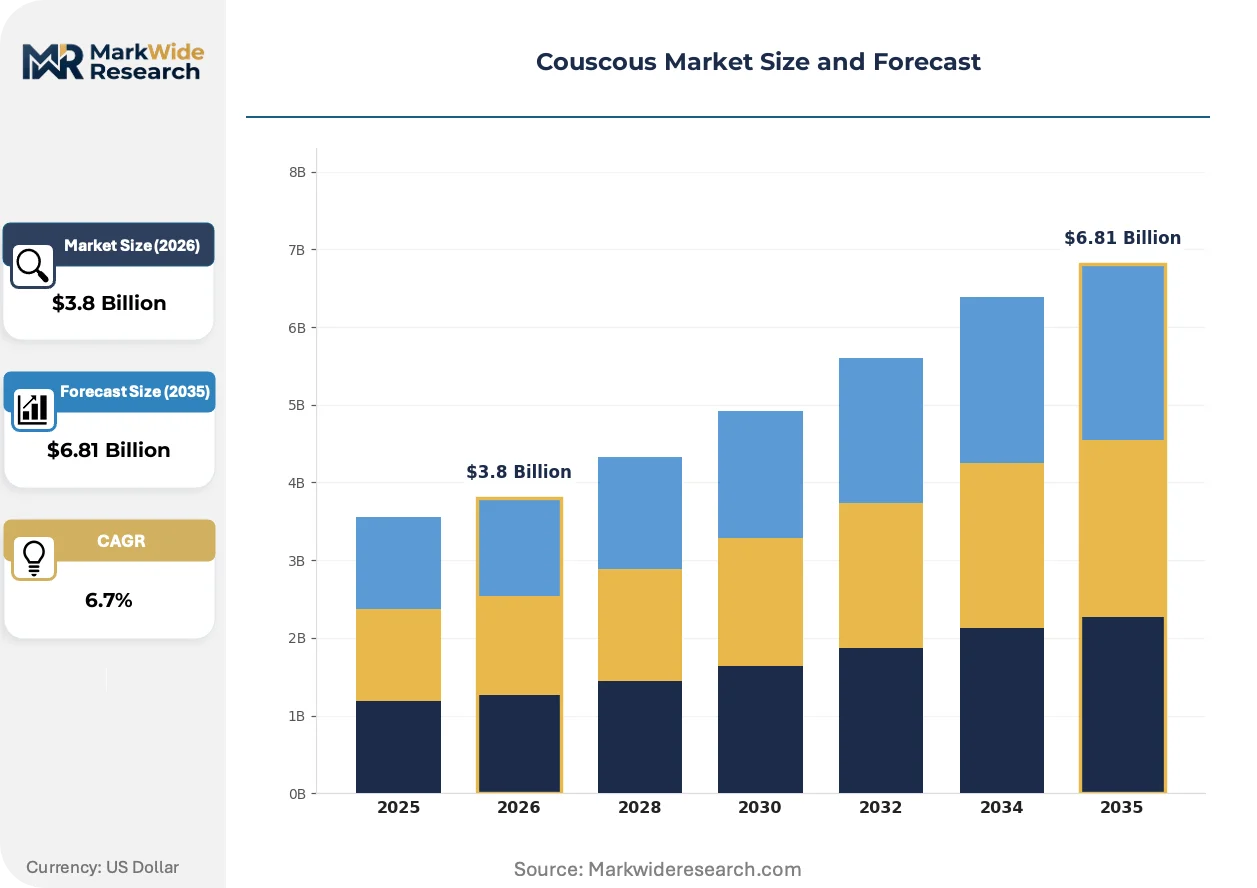
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional, Instant, Whole Grain, Flavored Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Food Service Packaging Type: Bags, Boxes, Bulk, Ready-to-eat End User: Households, Restaurants, Catering Services, Food Manufacturers |
| Companies Covered | Ebro Foods, S.A., Tipiak S.A., Barilla G. e R. Fratelli S.p.A., US Durum Products Ltd., PANZANI SAS, Roland Foods, LLC, BIA S.p.A., Al'Fez by AB World Foods Ltd., Dari Couspate, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Couscous Market Emerging Trajectories
Digital traceability infrastructure and alternative protein blending are reshaping how couscous manufacturers demonstrate provenance and nutritional value to institutional buyers and retail gatekeepers.
Blockchain-enabled lot tracking is decentralizing supply chain verification by enabling Moroccan cooperatives to bypass centralized export documentation and present harvest-to-package provenance directly to French and German retail procurement teams. Small-scale producers in the Atlas Mountains are adopting distributed ledger systems at accelerating rates. This technology shift is compressing the role of traditional import intermediaries who previously controlled origin certification.
EU Green Deal carbon farming certification is restructuring agricultural input protocols by mandating soil carbon measurement and reduced synthetic fertilizer application for durum wheat entering European value chains. Italian millers sourcing from Puglia and Sicily are restructuring supplier contracts to include emissions verification clauses. Premium organic segments in German and Dutch markets are responding fastest, with shelf placement contingent on verified carbon scores.
Meal-kit assembly platforms are fragmenting traditional retail distribution by inserting curated ingredient bundles between manufacturers and end consumers. North African recipe specialists in Paris and Marseille are disintermediating supermarket channels through direct subscription relationships. This channel shift is most visible in urban French and Belgian markets where time-compressed households prioritize convenience over store selection.
Couscous Market Segmentation
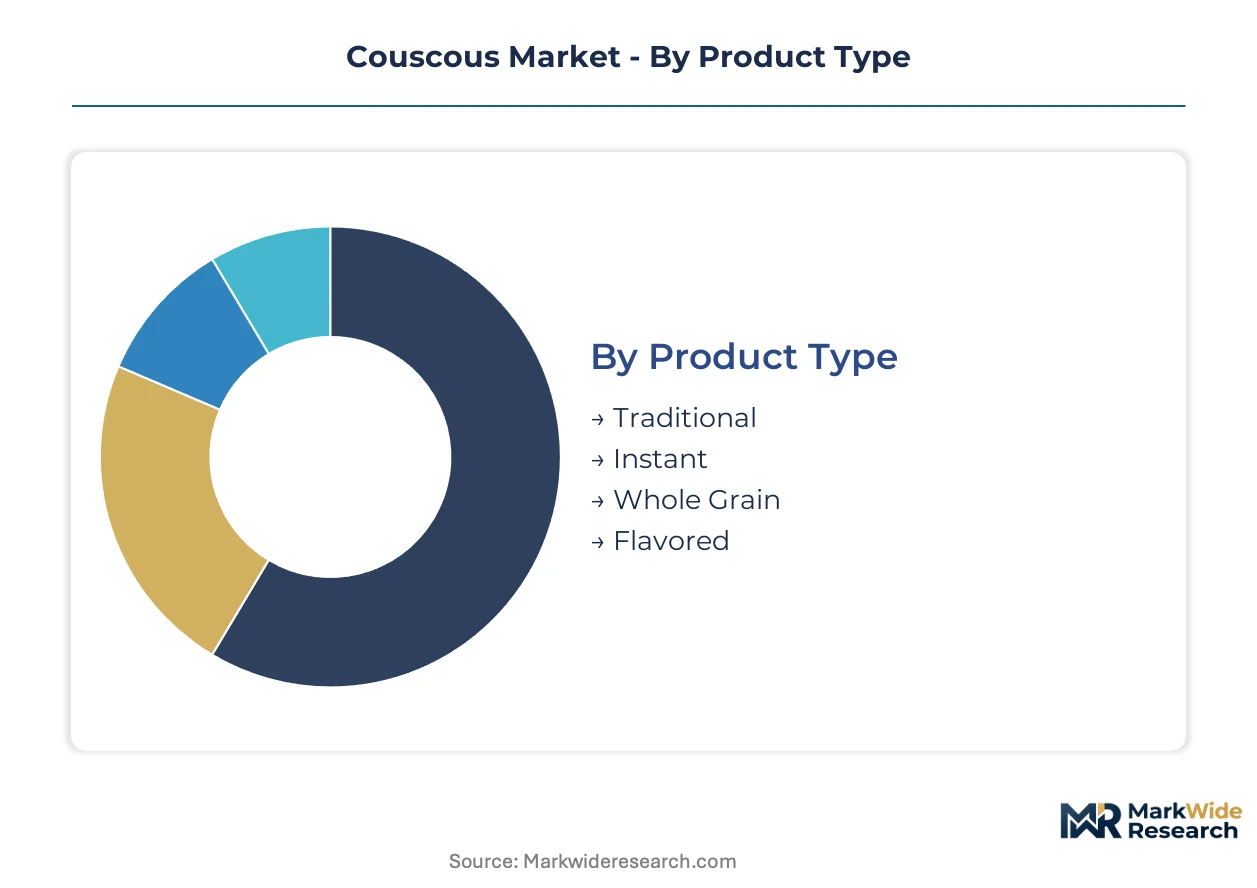
Segmentation in the couscous market reveals how preparation convenience, retail channel dynamics, and institutional procurement patterns create distinct competitive arenas. Manufacturers must align formulation, packaging, and distribution strategies to the specific requirements of each segment cluster.
Product Type:
Upgrade cycles in this category track shifting household time constraints and health-positioning priorities rather than equipment replacement schedules.
- Traditional:Steamed granules of durum wheat semolina prepared through labor-intensive rolling and steaming methods. Demand concentrates in North African ethnic retail channels across France, Belgium, and the Netherlands, where heritage preparation methods command authenticity premiums.
- Instant:Pre-cooked and dried semolina pellets requiring only hot water rehydration. Volume pools in French and German supermarket convenience aisles are deepening as time-compressed urban households abandon stovetop preparation.
- Whole Grain:Semolina incorporating bran and germ fractions for elevated fiber content. German organic retail chains and Dutch health-food specialists are expanding shelf space for these premium-positioned variants.
- Flavored:Couscous base infused with spice blends, vegetable powders, or herb formulations during milling. Paris-based meal-kit platforms and Marseille restaurant suppliers are driving procurement of saffron, harissa, and herb-infused formats.
Traditional couscous sits at the top of the volume ranking, with whole grain climbing the fastest as Mediterranean diet positioning gains traction in German-speaking markets.
Distribution Channel:
Channel selection in this market stratifies sharply by purchase occasion frequency and basket composition requirements.
- Supermarkets:Full-range and hypermarket chains dominate procurement of standard instant and traditional formats through centralized category management. French retailers Carrefour and Auchan maintain dedicated world-food aisle allocations that consolidate volume for Moroccan export consortia.
- Online Retail:E-commerce platforms capture bulk pantry stocking and subscription replenishment occasions. Amazon France and specialized North African grocery sites are expanding ambient and frozen couscous SKUs with next-day delivery guarantees.
- Specialty Stores:Ethnic grocers and organic food shops concentrate demand for artisanal, heritage-grain, and small-batch couscous varieties. Brussels and Lyon independent retailers source directly from Atlas Mountain cooperatives.
- Food Service:Restaurant chains, institutional caterers, and contract food operators purchase industrial-format couscous in bulk. Moroccan and Tunisian restaurant groups across Marseille and Paris drive consistent high-volume procurement of traditional preparation formats.
Supermarkets command the largest volume share, though online retail is gaining share fastest as subscription models penetrate French and Belgian urban households.
Packaging Type:
Packaging economics in this category track handling efficiency requirements across retail and institutional supply chains.
- Bags:Flexible polypropylene or paper laminates dominate ambient retail formats. French supermarket private-label programs specify resealable bag constructions for instant couscous to preserve texture through multiple use occasions.
- Boxes:Rigid paperboard cartons with inner pouch protection command premium shelf positioning. German and Austrian retailers favor boxed formats for gift-oriented and organic product lines.
- Bulk:Large-format sacks and totes serve food manufacturers and high-volume food service operators. Italian pasta processors purchase Moroccan semolina in bulk for captive couscous production.
- Ready-to-eat:Pre-portioned, microwaveable containers target immediate consumption occasions. French convenience store chains and railway catering services are expanding chilled and shelf-stable ready-to-eat couscous salads.
Bags generate the highest unit volumes, with ready-to-eat formats showing the steepest expansion trajectory as grab-and-go consumption spreads through French travel retail.
End User:
End-user segmentation maps directly to preparation time availability and batch size requirements.
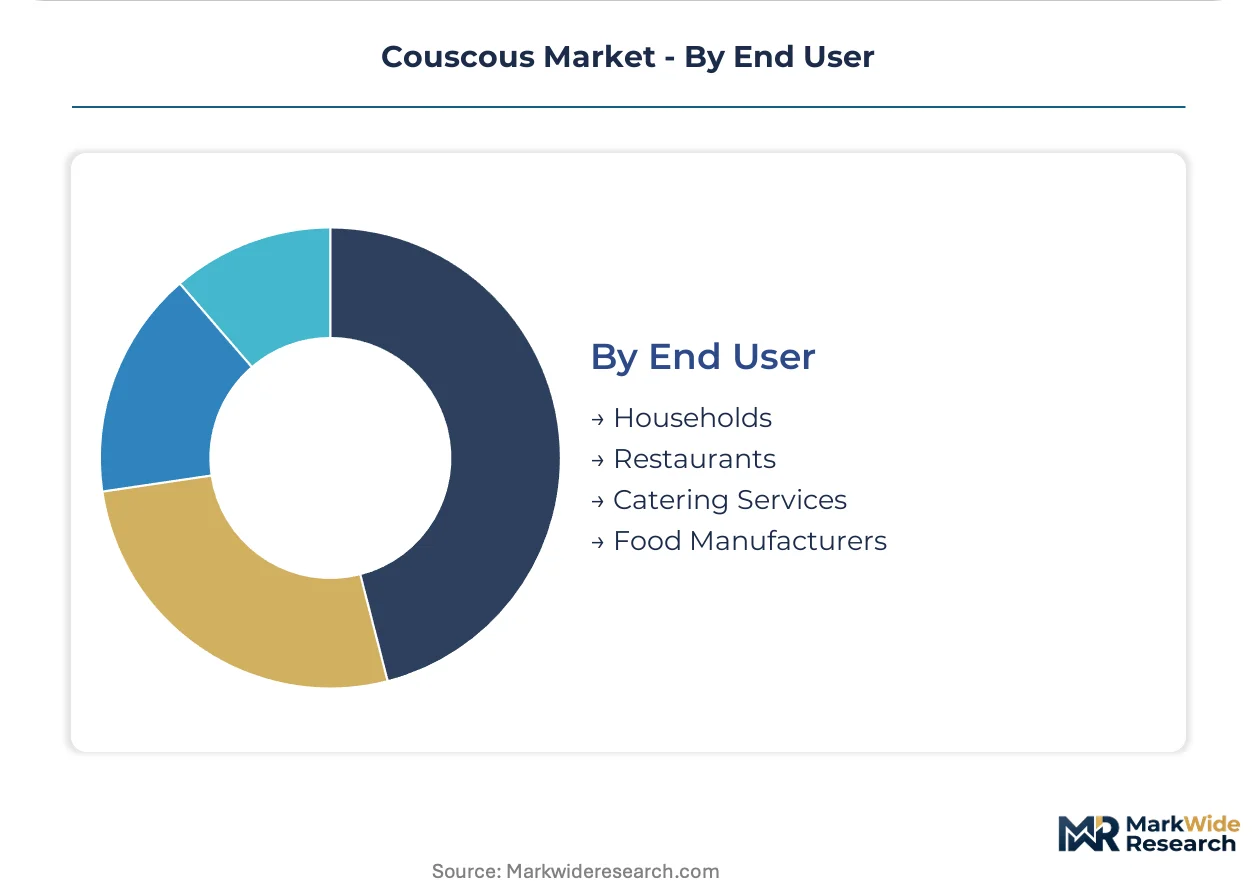
- Households:Individual and family consumers purchasing for home preparation. Urban French households with dual-income profiles are shifting from traditional to instant formats while maintaining weekly couscous consumption frequency.
- Restaurants:Full-service and quick-service operators incorporating couscous into menu offerings. North African restaurant clusters in Paris, Lyon, and Brussels maintain demand for traditional preparation methods despite labor intensity.
- Catering Services:Event and contract caterers requiring scalable, hold-stable carbohydrate solutions. Corporate catering operators across the Benelux region specify instant couscous for buffet applications.
- Food Manufacturers:Processed food companies using couscous as ingredient input. Italian and Spanish ready-meal producers incorporate couscous into Mediterranean diet-positioned frozen entrees.
Households anchor absolute demand volume, while food manufacturers are climbing fastest as couscous penetrates European ready-meal and frozen dinner categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping couscous production geography as EFSA disclosure requirements and EU Green Deal carbon standards create compliance cost differentials between Moroccan export clusters and European processing facilities.
Morocco
Restaurant procurement from Paris and Marseille drives bulk import demand for traditional preparation formats. The country's national food safety authority enforces CODEX-aligned export certification that governs European market access. Artisanal cooperatives and industrial mills concentrate in the Marrakech-Safi corridor where blockchain-enabled traceability systems are displacing centralized export documentation.
France
Hypermarket chains expand dedicated world-food aisles that consolidate volume for North African staple categories. ANSM and DGCCRF labeling enforcement under EU frameworks mandates shorter ingredient lists and origin disclosure. Paris-based meal-kit platforms and Marseille restaurant suppliers anchor procurement for saffron and harissa-infused couscous variants.
Germany
Discounters and full-range supermarkets add North African product lines to satisfy Mediterranean diet component demand. EU Common Agricultural Policy eco-schemes subsidize regenerative durum cultivation that qualifies couscous for premium organic retail placement. Berlin and Hamburg distribution hubs handle rising volumes of whole-grain and carbon-certified imports from Moroccan cooperatives.
Italy
Pasta manufacturing expertise extends into whole-grain and flavored couscous variants for health-oriented European shoppers. EFSA clean-label mandates push reformulation toward recognizable semolina-based products over additive-heavy alternatives. Millers in Puglia and Sicily restructure supplier contracts to include emissions verification clauses for German and Dutch premium segments.
Belgium
Brussels independent retailers source artisanal and heritage-grain varieties directly from Atlas Mountain cooperatives bypassing traditional import intermediaries. EU food labeling regulations reshape ingredient disclosure requirements across Benelux corporate catering channels. Antwerp logistics facilities handle transshipment for French and German retail procurement consolidation.
Couscous Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with Mediterranean milling conglomerates commanding retail shelf space while regional processors serve food-service and private-label channels. Market structure tilts toward consolidated upstream semolina supply and fragmented downstream formulation. Three archetypes dominate: vertically integrated grain-to-package operators, specialty ethnic-food marketers, and industrial ingredient suppliers. Capacity expansion and portfolio diversification represent the dominant competitive vectors as players respond to clean-label reformulation pressures and carbon-disclosure mandates.
Within the vertically integrated tier, Ebro Foods S.A. and Barilla G. e R. Fratelli S.p.A. exemplify Mediterranean milling infrastructure leveraged across European retail markets. Among specialty format specialists, Tipiak S.A. occupies a position anchored in frozen and ambient prepared couscous distribution through French hypermarket channels. These three entities represent distinct strategic postures: semolina supply security, manufacturing scale, and retail channel specialization respectively.
| Leading Market Players |
|---|
| Ebro Foods, S.A. |
| Tipiak S.A. |
| Barilla G. e R. Fratelli S.p.A. |
| US Durum Products Ltd. |
| PANZANI SAS |
| Roland Foods, LLC |
| BIA S.p.A. |
| Al'Fez by AB World Foods Ltd. |
| Dari Couspate |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between EU Green Deal carbon-certified Moroccan semolina and conventional Black Sea durum wheat manifests in both pricing premiums and supply chain routing decisions. Buyers in German organic retail channels absorb higher landed costs for verified low-carbon inputs, while commodity instant formats compete on volume scale through centralized hypermarket procurement.
Pricing Analysis
Distributor margin layers in French retail channels compress as Carrefour and Auchan consolidate world-food aisle negotiations through centralized category management. Three-tier pricing structure across premium organic, standard instant, and economy bulk formats reflects certification grade and volume scale differentiation. Pricing pressure stems from durum wheat cost volatility transmitted from climate-stressed Canadian Prairie harvests. Food manufacturers exhibit highest price sensitivity due to thin conversion margins in ready-meal applications, while specialty ethnic retailers absorb premiums for artisanal provenance.
Supply Chain Analysis
Durum wheat supply rests on Moroccan, Italian, and Canadian production clusters with divergent carbon certification status. Raw material dependencies include semolina grade specifications, steam-injection pre-cooking equipment, and flexible packaging laminates. Single-source vulnerability concentrates in the Marrakech-Safi corridor where artisanal cooperatives and industrial mills cluster for European export contracts. Distribution runs through Antwerp logistics facilities for Benelux transshipment and direct Marseille port reception for French retail consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal compliance costs in Italian and German processing facilities exceed Moroccan carbon-farming subsidy advantages, creating margin capture opportunities for certified Maghreb exporters.
For Market Incumbents: Anticipate quinoa and bulgur substitution threats in meal-kit channels by deepening backward integration into Atlas Mountain cooperative supply. Secure blockchain-enabled traceability infrastructure ahead of EFSA origin-disclosure tightening. Add regenerative durum cultivation capacity in Morocco's Marrakech-Safi corridor to qualify for EU Common Agricultural Policy eco-scheme premiums.
For New Entrants and Emerging Players: Enter via German organic retail expansion where discounters and full-range supermarkets under-index on North African product lines relative to Mediterranean diet demand. Target Brussels and Lyon independent specialty stores for direct cooperative sourcing relationships bypassing traditional import intermediaries. Deploy chef-curated subscription channels as the primary go-to-market angle for heritage-grain positioning.
For Investors and Strategic Acquirers: Consolidation pressure builds where semolina grading expertise scarcity fragments quality consistency across mid-scale Moroccan millers. Long-term viability favors vertically integrated grain-to-package operators with captive Moroccan supply and EU carbon certification. Target acquisition archetype: Atlas Mountain cooperatives with distributed ledger traceability deployment. Watch EFSA clean-label enforcement intensity as the signal for premium-tier margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Moroccan Cooperative Supply | Secures carbon-certified durum wheat access ahead of EU Green Deal sourcing mandates tightening. |
| Blockchain Traceability Infrastructure Deployment | Enables Atlas Mountain producers to bypass centralized export documentation for French retail procurement. |
| Steam-Injection Milling Capacity Expansion | Reduces hydration variability for instant couscous formats serving time-compressed urban households. |
| Chef-Curated Subscription Channel Launch | Disintermediates supermarket markups through direct Paris and Marseille meal-kit platform relationships. |
| EU Organic and Carbon Certification Investment | Qualifies shelf placement in German Aldi and Lidl premium tiers where verified scores gate access. |
Methodological Framework
Multiple input streams — primary interviews with Moroccan mill operators, French category buyers, and Italian pasta manufacturing executives; customs and trade flow databases; EFSA regulatory filings — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from EU agricultural subsidy records, CODEX export certification documentation, and North African cooperative financial disclosures. Stakeholder roles engaged included procurement leads at European hypermarket chains, technical R&D directors at Mediterranean milling conglomerates, and supply planners at meal-kit assembly platforms.
Data-stream reconciliation across product type, distribution channel, packaging format, and end-user segmentation dimensions anchored volume and value outputs throughout the forecast period. CAGRs were derived from segment-level growth pattern analysis applied to baseline consumption metrics. Industry-specific forecast inputs incorporated durum wheat harvest yield projections and EFSA clean-label enforcement timelines.
Inputs from Moroccan national food safety authority certification registries and EU Common Agricultural Policy eco-scheme enrollment data were available through the study window; gaps in real-time blockchain traceability adoption rates introduce uncertainty bands around premium-tier penetration assumptions. Forecasts reflect documented assumptions on regulatory alignment timelines and climate stress propagation through Black Sea and Canadian Prairie growing regions. A small set of triggers — EFSA disclosure mandate acceleration, EU carbon border adjustment mechanism expansion, and durum wheat germplasm innovation rates — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Smart Badge Market
Others
Buchner Funnels Market
Others
Crystal Growth Equipment Market
Others
Dried Fruit Extracts Market
Others
CAR T Cell Therapy Market
Others
Air Separation Plant Market
Others
Chip Card Scanners Market
Others
Induced Pluripotent Stem Cells (Ipscs) Market
Others
Durian Fruit Market
Others
Video Encoder Market
Others
Global Sports and Fitness Wears Market
Others
Android STB and TV Market
Others
Over the Top Devices and Services Market
Others
Global Phablets and Superphones Market
Others
North America Micro Market
Others
Storage Dewars Market