
 Vegetable Carbon Market | 2026-2036
Vegetable Carbon Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetable Carbon Market Analysis
REACH is recalibrating the cost-of-entry calculus for vegetable carbon suppliers seeking European market access. DDW The Color House leverages its vertical integration across charred vegetable raw material sourcing to sustain price competitiveness under tightening purity mandates. Chr. Hansen Holding A/S anchors its position through specialized E-number certification pathways for food-grade carbon blacks. Sensient Technologies differentiates via R&D intensity in low-ash powdered carbon formulations for premium cosmetics applications.
Vegetable carbon comprises carbonized plant material—typically coconut shells, wood, or peat—processed through controlled pyrolysis and activation to achieve specific surface areas exceeding 500 square meters per gram for adsorptive functionality. Its primary commercial purpose centers on coloration, filtration, and detoxification across food, pharmaceutical, and environmental remediation systems. Powdered carbon dominates food industry colorant applications due to its dispersion properties and E153 compliance, while granular carbon captures expanding margin pools in municipal water treatment infrastructure. Activated carbon grades from coconut precursors represent the fastest-growing product type as manufacturers prioritize renewable feedstock credentials and superior micropore distribution.
EFSA maintains stringent specifications on polycyclic aromatic hydrocarbon limits in vegetable carbon colorants, directly constraining supplier qualification and batch-release protocols for European food manufacturers. The EPA and FDA operate parallel oversight frameworks for activated carbon deployed in drinking water and pharmaceutical processing, creating multi-jurisdictional compliance burdens for exporters. Stakeholders must monitor evolving EFSA re-evaluation timelines for E153 authorization, as any restriction would force immediate reformulation investments across beverage and confectionery portfolios.
Market Dynamics
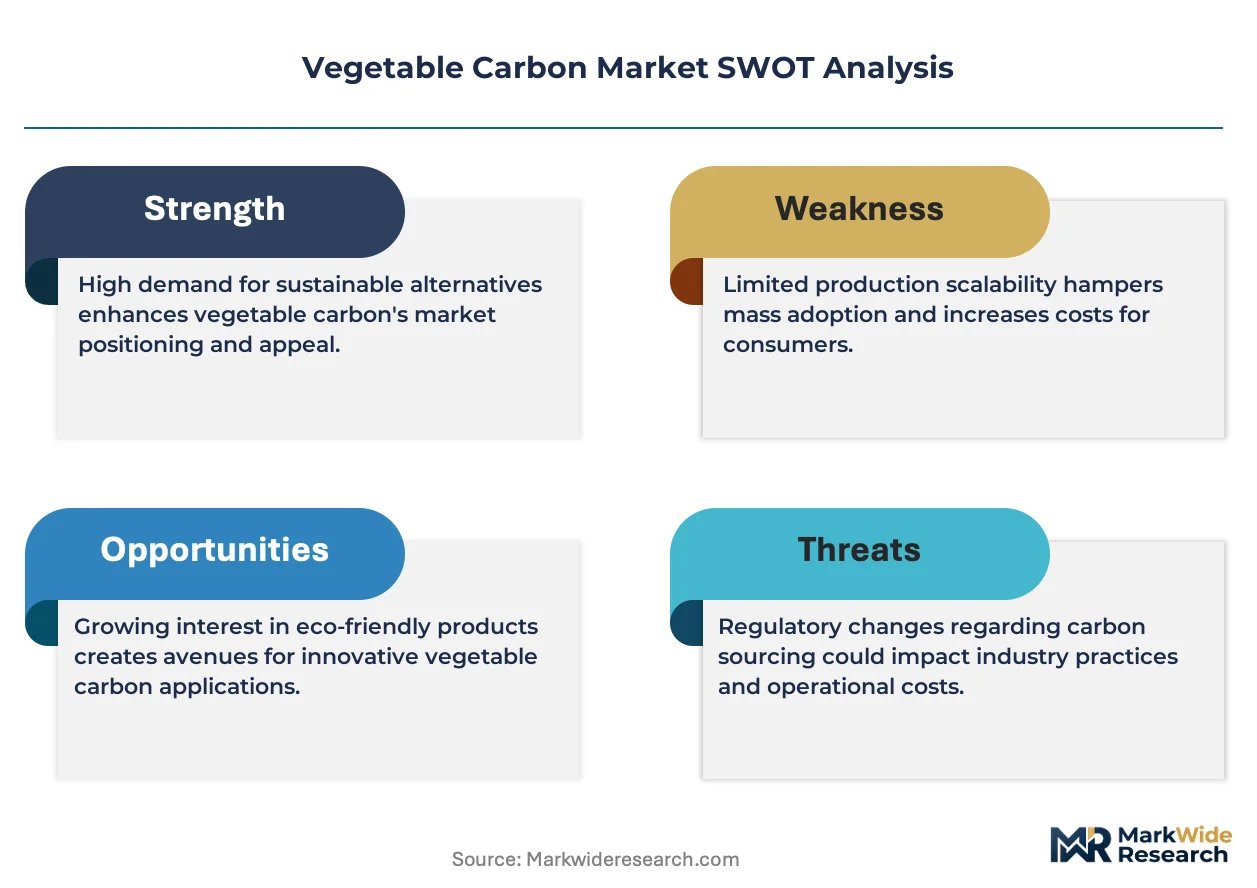
EFSA's polycyclic aromatic hydrocarbon limits for E153 certification are forcing suppliers to rebuild pyrolysis protocols from feedstock sourcing through activation, compressing margins for non-integrated producers while rewarding captive coconut shell processors.
Growth Catalysts
- REACH registration mandates:European chemical safety protocols are accelerating qualification timelines for food-grade carbon entrants, filtering out speculative suppliers and stabilizing pricing for compliant incumbents.
- Coconut shell activation:Renewable precursor sourcing is displacing peat-based production in premium colorant applications as manufacturers pursue carbon-negative credentials for Scope 3 reporting.
- Municipal water infrastructure:Granular activated carbon replacement cycles are tightening across German and French treatment facilities, pulling high-porosity grades into multi-year procurement contracts.
Market Restraints
- Feedstock concentration:Indonesian and Philippine coconut shell supply dominates precursor availability, exposing processors to monsoon-related harvest volatility and port congestion.
- PAH testing burden:EFSA batch-release protocols require third-party laboratory verification for every production lot, adding fixed compliance costs that scale poorly for small-batch cosmetic applications.
- Mineral carbon substitution:Petroleum-derived carbon blacks retain cost advantages in non-food industrial filtration, capping vegetable carbon penetration in bulk water treatment tenders.
Strategic Opportunities
- Pharmaceutical detoxification:Activated carbon hemoperfusion cartridges for acute poisoning treatment represent an underpenetrated therapeutic segment with premium pricing potential.
- EU Green Deal procurement:Public-sector buying mandates for bio-based materials are creating preferential tender scoring for renewable-credential carbon in French and Dutch environmental remediation projects.
- Powder-to-pellet conversion:Dust-free handling formats are opening beverage manufacturing lines previously blocked by occupational exposure limits on conventional powdered E153.
Industry Challenges
- Pyrolysis engineering talent:Specialized reactor design expertise for controlled carbonization remains concentrated among retiring European equipment specialists, constraining capacity expansion.
- Multi-jurisdictional dossier management:Simultaneous FDA food-contact notification, EPA drinking water certification, and EFSA re-evaluation maintenance is fragmenting regulatory affairs resources at mid-scale suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetable Carbon Market |
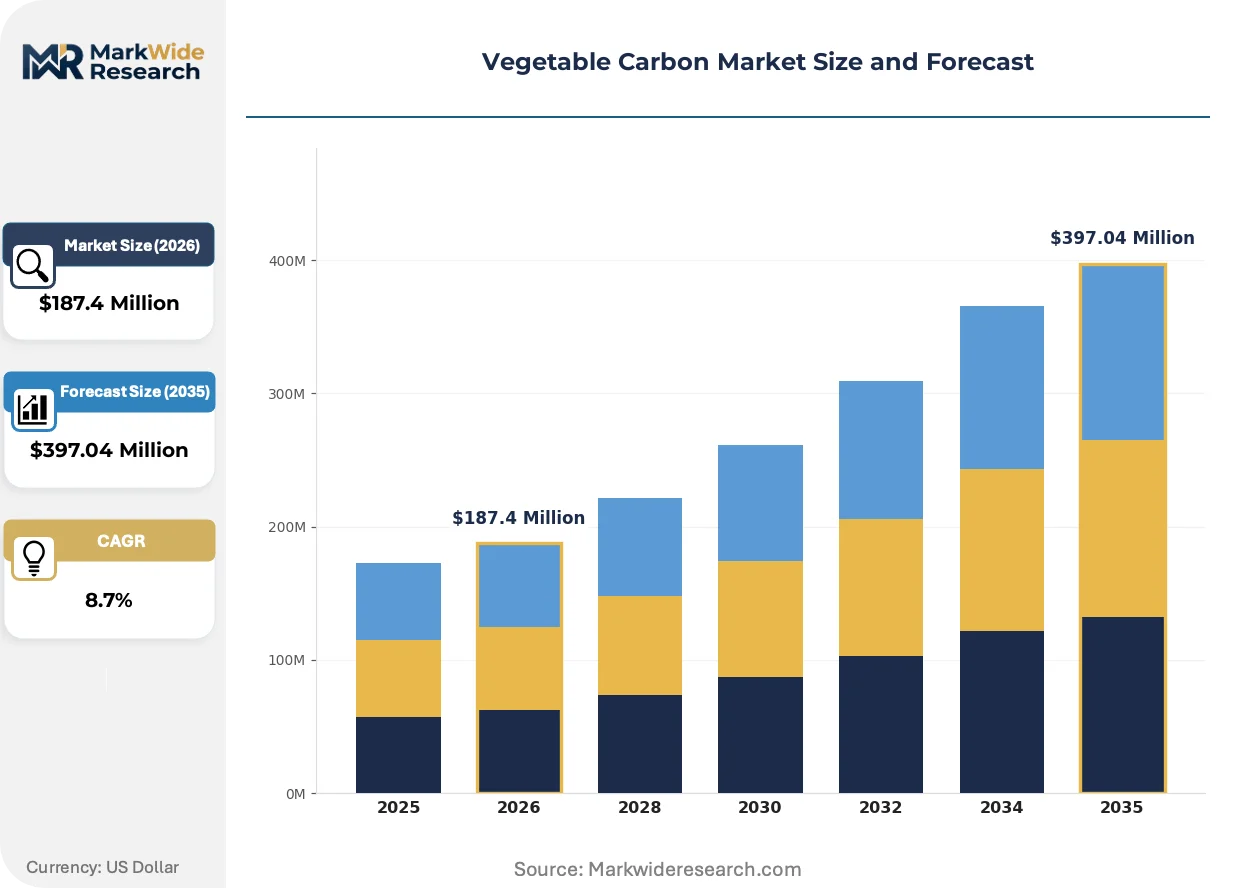
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Carbon, Charcoal, Powdered Carbon, Granular Carbon Application: Filtration, Adsorption, Water Treatment, Air Purification End User: Food Industry, Cosmetics, Pharmaceuticals, Agriculture Distribution Channel: Online Retail, Direct Sales, Wholesale, Supermarkets |
| Companies Covered | DDW The Color House, Chr. Hansen Holding A/S, Sensient Technologies, Naturex, IFC Solutions, Kolorjet Chemicals, Roha Dyechem, GNT Group, Univar Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetable Carbon Market Emerging Trajectories
Continuous activation reactor technology is compressing capital recovery periods while digital traceability platforms are redefining batch documentation standards across pharmaceutical and food-grade supply chains.
Small-scale steam-activation units installed at coconut processing cooperatives are decentralizing production geography away from centralized Malaysian and Sri Lankan carbonization hubs. Artisanal food manufacturers in Denmark and Sweden are sourcing directly from these village-scale facilities, bypassing traditional distributor markups while securing single-origin E153 certification. This distributed model is compressing lead times for specialty cosmetic carbon grades and enabling micro-lot customization previously uneconomical at industrial scale.
REACH substance evaluation workflows are extending registration data requirements to include nano-scale carbon particle characterization, forcing reformulation of legacy powdered colorants. German chemical distributors are pre-emptively screening supplier portfolios for compliance-ready documentation packages. The beverage concentrate segment is responding by consolidating procurement around vertically integrated producers with in-house toxicology testing capabilities.
Certification-driven specification is displacing price-first procurement in premium confectionery and nutraceutical channels. French and Italian chocolate manufacturers are requiring E153 suppliers to demonstrate FSSC 22000 and organic handling credentials alongside standard food-additive compliance. This behavioral shift is most visible in the artisanal bakery segment, where clean-label positioning now mandates vegetable carbon over synthetic alternatives regardless of unit cost differentials.
Vegetable Carbon Market Segmentation
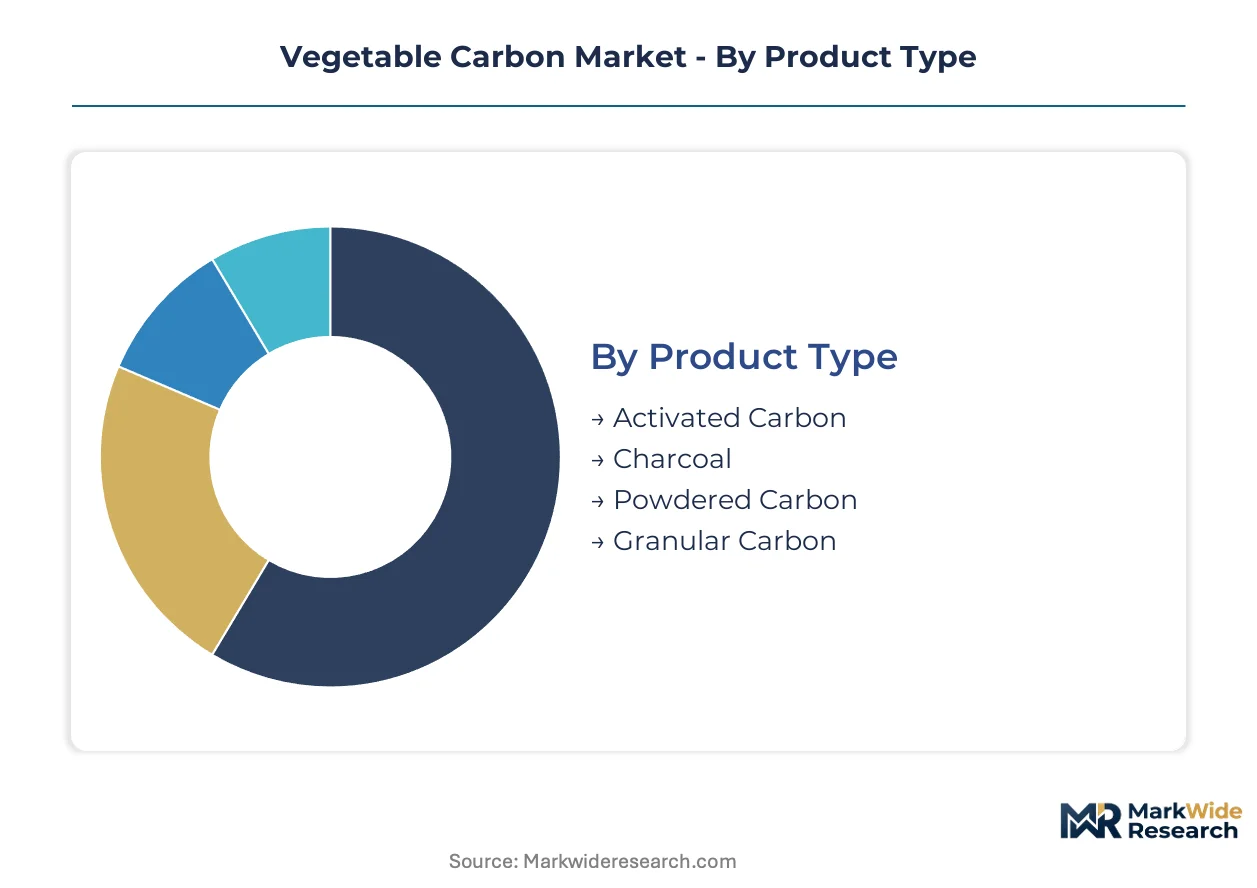
Segmentation in vegetable carbon markets tracks how pyrolysis specifications, regulatory certification tiers, and end-use purity mandates fragment procurement behavior. Buyers prioritize surface area metrics for filtration contracts while colorant applications demand E153 batch compliance above technical performance.
Product Type:
Surface area requirements and activation intensity drive procurement premiums across industrial versus food-grade applications.
- Activated Carbon:Steam-activated material achieving 500-1500 square meters per gram surface area dominates municipal water treatment infrastructure in Germany and France. Multi-year procurement contracts from utilities lock in volume commitments for high-porosity coconut shell grades.
- Powdered Carbon:Finely milled E153-compliant pigment disperses uniformly in confectionery and beverage matrices. Danish and Swedish artisanal food manufacturers source directly from village-scale cooperatives to secure single-origin certification for clean-label positioning.
- Charcoal:Lower-activation material serves barbecue fuel and metallurgical applications with minimal processing overhead.
- Granular Carbon:Sized pellets optimize packed-bed filtration in fixed-bed reactor configurations for industrial gas processing.
Activated carbon leads on scale; powdered carbon leads on momentum.
Application:
Regulatory jurisdiction determines specification stringency, with drinking water and food contact facing the most intensive compliance burdens.
- Filtration:Liquid and gas-phase separation applications require tailored pore size distributions matched to contaminant molecular weight. EPA drinking water certification and EFSA food-contact protocols create divergent testing requirements for suppliers serving both markets.
- Water Treatment:Granular activated carbon replacement cycles are tightening across German and French municipal facilities. Procurement is consolidating around producers with in-house toxicology testing capabilities to satisfy REACH documentation requirements.
- Adsorption:Surface-binding applications in pharmaceutical detoxification and chemical recovery demand ultra-high purity grades with controlled ash content below five percent.
- Air Purification:Volatile organic compound capture in industrial ventilation and indoor air quality systems utilizes pelletized carbon for low-pressure-drop bed configurations.
Water treatment commands the largest contract values; pharmaceutical adsorption offers the steepest expansion trajectory.
End User:
Certification depth and traceability requirements stratify pricing power across consumer-facing versus industrial buyers.
- Food Industry:E153 colorant applications in confectionery, bakery, and beverage manufacturing require polycyclic aromatic hydrocarbon testing for every production lot. French and Italian chocolate manufacturers now mandate FSSC 22000 and organic handling credentials alongside standard food-additive compliance.
- Pharmaceuticals:Activated carbon hemoperfusion cartridges for acute poisoning treatment represent an underpenetrated therapeutic segment. FDA drug master file requirements and European Pharmacopoeia compliance create substantial barriers to entry for non-specialized suppliers.
- Cosmetics:Low-ash powdered carbon formulations for premium skincare and oral care products prioritize dust-free handling formats to meet occupational exposure limits.
- Agriculture:Soil amendment and livestock feed applications utilize lower-grade carbonized materials with reduced activation intensity and corresponding cost structures.
Food industry procurement leads on volume scale; pharmaceuticals leads on margin expansion.
Distribution Channel:
Order size and certification complexity determine channel economics, with bulk industrial buyers bypassing intermediaries while specialty grades retain distributor value-add.
- Direct Sales:Municipal water utilities and multinational food manufacturers negotiate multi-year supply agreements directly with integrated producers. REACH registration mandates favor incumbent suppliers with established regulatory affairs infrastructure.
- Wholesale:Regional distributors aggregate demand from mid-scale cosmetics and agricultural processors, providing batch documentation and logistics consolidation.
- Online Retail:Small-volume specialty grades for artisanal food producers and research laboratories move through digital platforms with certificate-of-analysis downloads.
- Supermarkets:Consumer packaged goods including activated carbon supplements and water filtration cartridges reach end users through retail shelf placement.
Direct sales dominates contract value; wholesale maintains the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vegetable carbon production first achieved industrial scale in European charring facilities during the early twentieth century, with German and French processors pioneering controlled pyrolysis techniques for food-grade applications. This technical heritage continues to shape regulatory standards and manufacturing practices across the industry's primary demand centers.
Germany
Municipal water utilities in North Rhine-Westphalia and Bavaria drive granular activated carbon procurement through multi-year replacement contracts for treatment infrastructure. ECHA REACH registration mandates filter supplier qualification, favoring incumbents with established regulatory affairs capabilities. The Cologne-Düsseldorf industrial corridor hosts specialized reactor engineering firms that supply carbonization equipment globally.
France
Artisanal chocolate manufacturers in Île-de-France and Rhône-Alpes now require FSSC 22000 and organic handling credentials alongside standard E153 compliance for clean-label positioning. The EU Green Deal creates preferential tender scoring for bio-based carbon in environmental remediation projects led by French public-sector buyers. Lyon-based distributors are pre-emptively screening supplier portfolios for REACH nano-scale documentation readiness.
United States
EPA drinking water certification requirements for activated carbon create parallel compliance burdens distinct from EFSA protocols, fragmenting dossier management for exporters. FDA food-contact notification pathways govern E153 importation for beverage and confectionery manufacturing concentrated in the Midwest and Northeast. California's Proposition 65 enforcement adds state-level toxicology testing requirements for cosmetic-grade carbon formulations.
Indonesia
Coconut shell harvest volatility from monsoon patterns in Sulawesi and Sumatra exposes precursor supply to port congestion and price swings. The country's national food safety regulator aligns export certification with destination market requirements for EU and US-bound shipments. Surabaya and Makassar processing clusters are installing village-scale steam-activation units to decentralize production geography.
United Kingdom
Artisanal bakery and nutraceutical manufacturers in Greater London and the Midlands consolidate procurement around vertically integrated producers with in-house toxicology testing capabilities. The UK's post-EU chemicals regulatory framework maintains REACH-equivalent standards for E153 importation. Manchester-based cosmetics formulators prioritize dust-free pelletized carbon formats to meet occupational exposure limits previously blocking powdered E153 usage.
Vegetable Carbon Market Vendor Landscape
The competitive structure tilts toward vertically integrated specialists with captive coconut shell processing capabilities. Three to five incumbent suppliers control the majority of E153-certified production capacity, while mid-scale regional processors compete on lead time and micro-lot customization. The dominant archetypes comprise: integrated plantation-to-pigment operators, specialized pharmaceutical-grade refiners, and distributed artisanal-scale cooperatives. Competitive moves concentrate on backward integration into precursor supply and geographic expansion through distributor partnerships in high-growth pharmaceutical and cosmetics segments.
Among European-anchored pigment specialists, DDW The Color House and Chr. Hansen Holding A/S occupy positions exemplifying the integrated archetype, with captive control over charred vegetable raw material sourcing. Sensient Technologies represents the R&D-intensive tier, differentiated by formulation capabilities in low-ash powdered grades. These three names anchor the competitive landscape without exhaustively mapping all active participants.
| Leading Market Players |
|---|
| DDW The Color House |
| Chr. Hansen Holding A/S |
| Sensient Technologies |
| Naturex |
| IFC Solutions |
| Kolorjet Chemicals |
| Roha Dyechem |
| GNT Group |
| Univar Solutions |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between E153-compliant food pigment and industrial filtration carbon creates parallel pricing architectures that reshape supplier economics. Premium batch-release protocols for European confectionery manufacturers command substantial markups over municipal water treatment contracts, while coconut shell precursor sourcing constraints compress margins for non-integrated processors serving commodity segments.
Pricing Analysis
Testing-inclusive versus testing-excluded quotation structures dominate procurement negotiations across buyer archetypes. Pharmaceutical-grade carbon hemoperfusion cartridges and premium cosmetic formulations extract maximum value through bundled toxicology documentation and FSSC 22000 certification, while municipal utilities drive hard volume discounts on granular activated carbon replacement cycles. Cost compression in commodity water treatment grades intensifies as Indonesian port congestion elevates landed precursor costs. Artisanal food manufacturers exhibit lowest price sensitivity, prioritizing single-origin traceability and organic handling credentials over unit economics.
Supply Chain Analysis
EU Green Deal domestic-content preferences for bio-based materials in French and Dutch environmental remediation tenders are redirecting procurement toward European-registered suppliers with REACH-compliant documentation. Coconut shell harvests from Indonesia and the Philippines anchor precursor availability, while Malaysian and Sri Lankan carbonization hubs retain concentration in activated carbon production. Feedstock volatility from monsoon patterns in Sulawesi and Sumatra creates single-source vulnerability for non-diversified processors. Distribution runs through direct sales channels for municipal utilities and multinational food manufacturers, with wholesale intermediaries serving mid-scale cosmetics and agricultural processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in pharmaceutical detoxification and premium cosmetic applications, where E153 batch compliance and low-ash formulation capabilities support sustainable pricing power above commodity water treatment tiers.
For Market Incumbents: Deploy captive coconut shell processing infrastructure to defend against peat-based carbon displacement and mineral carbon substitution threats in industrial filtration. Lock in multi-year municipal water treatment replacement contracts across German and French utilities before REACH registration mandates filter additional competitors. Prioritize in-house toxicology testing capabilities to consolidate procurement from artisanal bakery and nutraceutical manufacturers requiring FSSC 22000 credentials.
For New Entrants and Emerging Players: Digital platform distribution for micro-lot specialty grades offers immediate channel access without incumbent distributor relationships. Village-scale steam-activation units in Indonesian cooperatives present the most penetrable supply geography, enabling direct sourcing relationships with Danish and Swedish clean-label food manufacturers. Pursue pharmaceutical hemoperfusion cartridge partnerships as the highest-margin white-space target, leveraging FDA drug master file pathways as competitive differentiation.
For Investors and Strategic Acquirers: Consolidation pressure builds where pyrolysis engineering talent scarcity constrains capacity expansion among European equipment specialists. Five-to-ten-year viability favors vertically integrated plantation-to-pigment operators with captive precursor supply and established E-number certification pathways. Watch EFSA E153 re-evaluation timelines as the critical inflection signal, where authorization restrictions would force immediate reformulation investments and supplier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coconut Shell Processing | Captive precursor supply insulates margins from Indonesian monsoon volatility and port congestion. |
| Pharmaceutical-Grade Refining Capacity Expansion | FDA drug master file capabilities unlock premium pricing in acute poisoning hemoperfusion applications. |
| REACH Nano-Scale Documentation Investment | Pre-emptive compliance with ECHA substance evaluation workflows secures German chemical distributor relationships. |
| Powder-to-Pellet Format Conversion | Dust-free handling opens beverage manufacturing lines previously blocked by occupational exposure limits. |
| Village-Scale Cooperative Partnership Network | Distributed production geography compresses lead times for specialty cosmetic carbon micro-lot customization. |
Methodological Framework
Direct dialogue with carbonization plant managers, E153 procurement leads at European confectionery manufacturers, REACH regulatory affairs specialists, and municipal water utility engineering directors grounded qualitative findings. Secondary validation drew from EFSA food-additive re-evaluation dossiers, ECHA registration databases, EPA drinking water certification records, and customs trade data tracking coconut shell precursor flows. Bottom-up segment sizing triangulated against top-down market envelope estimates across product type, application, and end-user dimensions.
Segment-level value projections across the analysis window applied activation intensity tiers, surface area specifications, and certification-grade premiums as core modeling parameters. CAGRs derived from trend extrapolation of coconut shell displacement patterns, municipal infrastructure replacement cycle timing, and pharmaceutical adsorption penetration trajectories. Forecast inputs incorporated EU Green Deal procurement mandate implementation pace and EFSA batch-release protocol evolution.
The model assumes a particular technology adoption path; alternative pathways for continuous activation reactor technology or distributed village-scale production would alter the outlook for incumbent processor margins and geographic supply concentration. Forecasts reflect documented assumptions regarding REACH registration timeline adherence and E153 authorization continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
5G Devices Market
Others
Africa 3D Printing Construction Market
Others
Free Space Optics (FSO) Market
Others
Aircraft Cameras Market
Others
India Smart Home Market
Others
Bitcoin Mining Hardware Market
Others
Smart-Connected Power Plug Socket Market
Others
Dry Washer Market
Others
Global Microcontroller Embedded Systems Market
Others
Solar Animal Repellent Market
Others
Bamboo Straws Market
Others
Deflectometer Market
Others
Global Contactless Biometrics Technology Market
Others
Green Technologies Market
Others
Server Market
Others
Aircraft Switches Market