
 3D IC and 2.5D IC Market | 2026-2036
3D IC and 2.5D IC Market Size, Share, and Industry Trends Forecast 2026-2036
3D IC and 2.5D IC Market Outlook
ISO 9001 and IATF 16949 qualification cycles for automotive-grade 2.5D interposers is unwinding the competitive field, favoring incumbents with multi-year certification track records. Taiwan Semiconductor Manufacturing Company anchors advanced silicon interposer capacity with unmatched yield discipline. Samsung Electronics leverages its memory-foundry integration to control HBM supply chains. Intel Corporation sustains domestic packaging ambitions through its New Mexico and Arizona expansion footprint.
3D IC and 2.5D IC denote multi-die integration architectures where chips are stacked vertically or bridged laterally through silicon interposers and through-silicon vias, achieving interconnect densities exceeding 10,000 wires per square millimeter for bandwidth-critical workloads. Through-Silicon Via technology dominates capital allocation due to its indispensability for high-bandwidth memory stacks, while Fan-Out Packaging captures the fastest expansion trajectory as Apple and Qualcomm migrate mobile processors toward substrate-less designs. High-Performance Computing and Artificial Intelligence applications concentrate the highest margin pools, with networking equipment trailing as a mature, price-sensitive adopter.
The U.S. Department of Commerce's export control frameworks and the EU Chips Act are bifurcating equipment supply chains, forcing foundries to qualify redundant tooling lines for China-excluded versus China-inclusive production networks. Japan's METI coordinates domestic packaging consortia through subsidy programs targeting post-CMOS integration leadership. Stakeholders must decide whether to absorb the capital burden of dual-track compliance or cede geographic market segments to regionally captive competitors.
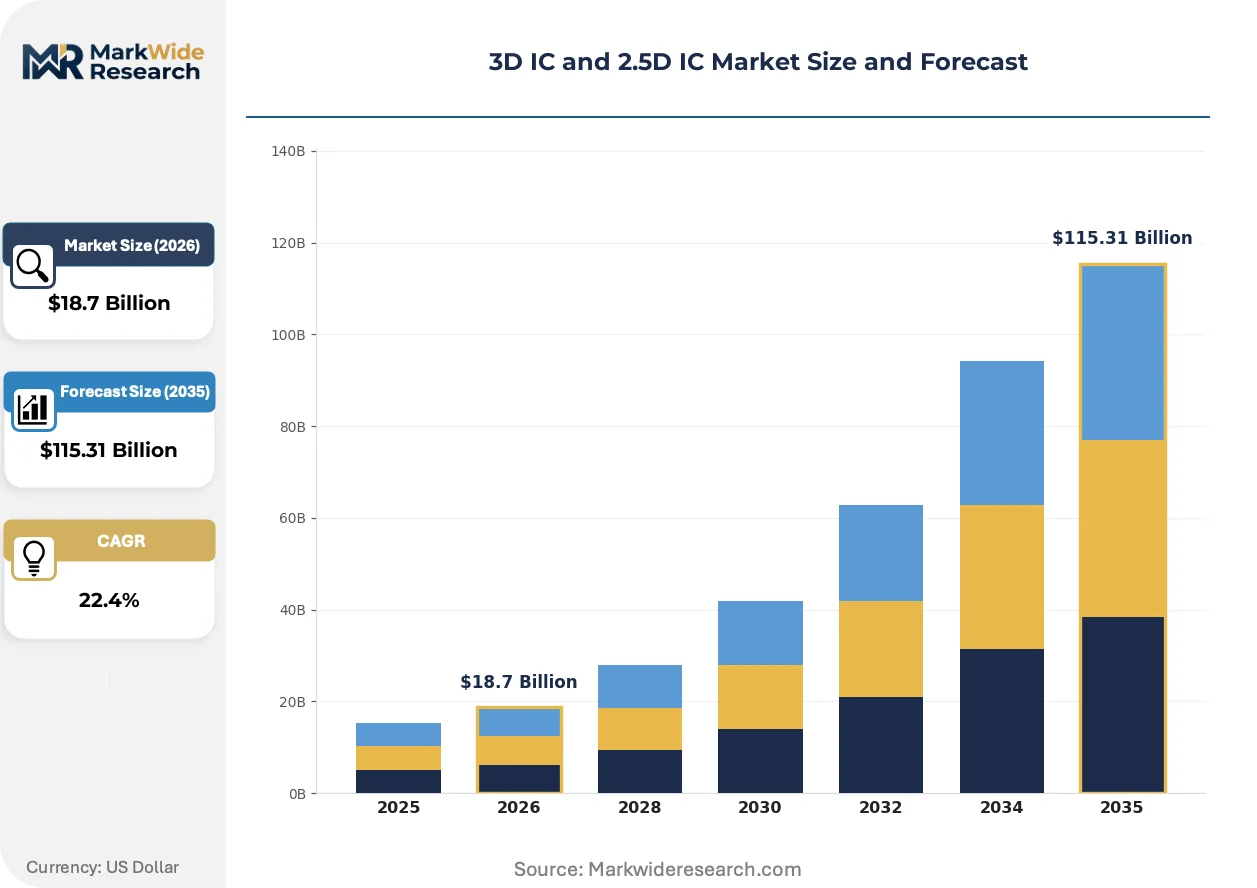
Market Dynamics
Artificial intelligence training clusters are absorbing advanced packaging capacity at unprecedented rates, compressing lead times for HBM interposers and forcing foundries to prioritize high-margin silicon over legacy automotive contracts.
Growth Catalysts
- CHIPS Act capital flows:The U.S. Department of Commerce's export control frameworks are redirecting foundry investment toward domestic interposer fabrication, creating captive supply for defense and hyperscale compute.
- HBM stack proliferation:Through-Silicon Via technology dominates capital allocation due to its indispensability for high-bandwidth memory stacks in generative AI accelerators.
- Automotive qualification pipelines:ISO 9001 and IATF 16949 certification cycles for automotive-grade 2.5D interposers are locking in multi-year supplier relationships with established yield discipline.
Market Restraints
- Silicon interposer yield volatility:Defect density in large-area interposers above 2,500 square millimeters destroys margin at current wafer costs.
- Taiwan supply concentration:Hsinchu Science Park corridor hosts over 70 percent of advanced CoWoS capacity, creating single-point vulnerability to seismic or geopolitical disruption.
- Organic substrate substitution:Fan-Out Panel Level Packaging is capturing mobile processor volumes below 500 gigabytes per second bandwidth requirements.
Strategic Opportunities
- Japan packaging consortia:METI subsidy programs targeting post-CMOS integration leadership are creating domestic advanced packaging ecosystems outside Taiwan supply chains.
- Substrate-less mobile migration:Apple and Qualcomm processor roadmaps are accelerating Fan-Out Packaging adoption for handset form-factor constraints.
- EU Chips Act localization:European foundry investments in Dresden and Leuven are qualifying redundant interposer lines for China-excluded production networks.
Industry Challenges
- Dual-track equipment qualification:Foundries must absorb capital burden of redundant tooling lines for China-excluded versus China-inclusive production networks.
- Thermal-structural co-design complexity:Stacked die architectures require simultaneous optimization of TSV density, microbump pitch, and underfill reliability across heterogeneous integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D IC and 2.5D IC Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Integrated Circuits, 2.5D Integrated Circuits, System-in-Package, Through-Silicon Via, Package-on-Package Technology: Silicon Interposer, TSV-Based Stacking, Wafer-Level Packaging, Fan-Out Packaging, Embedded Die Technology Application: High-Performance Computing, Mobile Devices, Artificial Intelligence, Consumer Electronics, Networking Equipment End User: OEMs, Semiconductor Foundries, Original Design Manufacturers, Fabless Companies, Assembly & Test Providers |
| Companies Covered | Samsung Electronics, Taiwan Semiconductor Manufacturing Company, Intel Corporation, ASE Technology Holding, Amkor Technology, Broadcom, Texas Instruments, United Microelectronics Corporation, JCET Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D IC and 2.5D IC Market Strategic Shifts
Hybrid bonding and wafer-to-wafer stacking architectures are compressing interconnect pitch below 10 micrometers, enabling logic-on-logic integration that was previously unattainable with microbump technologies.
Hybrid bonding is displacing thermocompression microbumping for high-performance compute die-to-die interfaces. NVIDIA and AMD are transitioning next-generation AI accelerators to copper-to-copper direct bond interfaces for power and bandwidth density. This displacement is collapsing the traditional OSAT role in high-end interposer assembly, concentrating margin capture at foundry-level front-end processes.
EU Chips Act domestic content thresholds are mandating European-sourced interposer substrates for public procurement above specified contract values. This industrial policy is forcing non-European foundries to establish licensed packaging partnerships with Dresden and Leuven facilities. Automotive and aerospace compute modules are most affected, with suppliers accelerating JIS and ISO qualification transfers to EU-based lines.
Hyperscale cloud providers are consolidating procurement around turnkey advanced packaging contracts that bundle design, interposer fabrication, assembly, and test under single-source agreements. Traditional OSATs are losing direct customer relationships as foundries capture the full value stack. This concentration is most visible in North American AI training cluster deployments, where Microsoft, Amazon, and Google are negotiating multi-year capacity reservations directly with TSMC and Intel Foundry Services.
3D IC and 2.5D IC Market Segmentation
Segmentation in advanced packaging reveals how architectural choices cascade through equipment requirements, regulatory qualification paths, and margin capture. Each dimension—product architecture, integration technology, application workload, and customer type—imposes distinct technical constraints and competitive dynamics.
Product Type:
Regulatory frameworks differentiate these architectures through reliability standards and export control classifications, with defense-grade applications demanding traceable supply chains for stacked die configurations.
- 3D Integrated Circuits:Vertical die stacking with through-silicon vias achieves the highest interconnect density for AI training accelerators. NVIDIA and AMD roadmaps prioritize this architecture for next-generation data center deployments where power-bandwidth tradeoffs dominate design constraints.
- 2.5D Integrated Circuits:Silicon interposer bridging enables heterogeneous integration of logic and memory without full vertical stacking. TSMC's CoWoS platform anchors this segment, with automotive-grade qualifications under IATF 16949 locking in supplier relationships for advanced driver-assistance systems.
- System-in-Package:Multi-die integration within a single enclosure targets mobile form-factor constraints. Apple deploys SiP extensively in wearable products where board area limitations override pure performance optimization.
- Through-Silicon Via:Vertical interconnect technology enabling the thinnest possible die stacks. HBM memory suppliers depend on TSV fabrication for bandwidth density in generative AI clusters.
- Package-on-Package:Stacked package configurations combining logic and memory without interposer substrates. Qualcomm leverages PoP for mid-tier smartphone processors where cost sensitivity limits silicon interposer adoption.
2.5D Integrated Circuits handles the majority of throughput; Fan-Out Packaging is the fastest mover on share.
Technology:
Cost tier differentiation separates these approaches, with front-end-like processes commanding premium pricing against backend assembly alternatives.
- Silicon Interposer:Large-area silicon substrates with redistribution layers provide the highest wiring density for high-performance computing interposers. Yield volatility in interposers exceeding 2,500 square millimeters constrains foundry margins despite strong demand from hyperscale cloud providers.
- TSV-Based Stacking:Vertical vias etched through silicon wafers enable the thinnest possible die interconnects. Samsung's memory-foundry integration secures captive supply for HBM3E stacks in AI accelerators.
- Wafer-Level Packaging:Processing at full wafer scale before singulation reduces handling costs for high-volume mobile processors. This technology concentrates in Taiwan's Hsinchu corridor alongside leading-edge foundry capacity.
- Fan-Out Packaging:Substrate-less redistribution eliminates organic laminate costs for space-constrained applications. Apple migrated its flagship mobile processors to fan-out configurations, compressing OSAT margins while expanding foundry assembly revenue.
- Embedded Die Technology:Die integration within organic substrates suits automotive modules requiring under-the-hood reliability. ISO 26262 functional safety qualifications extend development cycles for embedded die suppliers targeting powertrain controllers.
Silicon Interposer captures the dominant share of revenue; Fan-Out Packaging is expanding most quickly as mobile migration accelerates.
Application:
Application segmentation tracks directly to thermal design power thresholds and bandwidth requirements, with AI workloads imposing the most stringent integration constraints.
- High-Performance Computing:Server processors and accelerators demanding the highest interconnect density available. Intel's Ponte Vecchio and AMD's MI300 series exemplify this segment's multi-chip module complexity.
- Mobile Devices:Handset and tablet processors where form-factor constraints override absolute performance. Apple's A-series and M-series chips drive fan-out packaging adoption through substrate-less designs.
- Artificial Intelligence:Training and inference accelerators absorbing advanced packaging capacity at unprecedented rates. Microsoft, Amazon, and Google negotiate multi-year capacity reservations directly with foundries for this application.
- Consumer Electronics:Wearables, gaming consoles, and smart home devices with moderate bandwidth requirements. Nintendo and Sony console processors utilize 2.5D integration for graphics memory interfaces.
- Networking Equipment:Switch and router silicon where latency sensitivity meets volume pricing pressure. Cisco and Juniper procurement emphasizes cost discipline over bleeding-edge integration density.
Artificial Intelligence commands the highest margins; Consumer Electronics delivers the steepest volume expansion trajectory.
End User:
Customer type determines whether packaging remains captive within foundry walls or flows to outsourced assembly and test providers.
- OEMs:System manufacturers with internal packaging capabilities, primarily in defense and aerospace. Northrop Grumman and Raytheon maintain captive facilities for ITAR-controlled programs.
- Semiconductor Foundries:Integrated device manufacturers and pure-play foundries capturing advanced packaging margin. TSMC and Intel Foundry Services dominate this category through front-end process integration.
- Original Design Manufacturers:Electronics manufacturing services providers assembling packaged components into finished systems. Foxconn and Pegatron handle packaging procurement for major consumer brands.
- Fabless Companies:Chip designers without fabrication assets, dependent on foundry packaging partnerships. NVIDIA and AMD exemplify this model, with packaging specifications tightly coupled to architectural roadmaps.
- Assembly & Test Providers:Traditional OSATs losing high-end share to foundry integration. ASE and Amkor retain strength in legacy wirebond and mid-range flip-chip segments.
Semiconductor Foundries control the highest-value integration; Fabless Companies are gaining procurement leverage fastest as AI demand concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kaohsiung-Taichung high-speed rail corridor and Taoyuan International Airport's cargo terminals underwrite Taiwan's dominance in advanced packaging logistics, while the U.S. Interstate 10 corridor and Port of Long Beach anchor North American interposer distribution networks.
United States
Hyperscale cloud providers in Virginia and Oregon are absorbing silicon interposer capacity for AI training clusters. The CHIPS Act directs Department of Commerce funding toward domestic CoWoS-equivalent fabrication in Arizona and New Mexico. Intel's Rio Rancho facility and TSMC's Phoenix expansion are qualifying large-area interposer lines for defense and enterprise compute procurement.
Taiwan
TSMC and ASE anchor the densest 3D IC ecosystem globally, with Hsinchu Science Park hosting over seventy percent of advanced CoWoS capacity. The National Science and Technology Council coordinates METI-aligned subsidy programs for post-CMOS integration research. Taichung's precision machinery corridor supplies die-bonding and inspection equipment to Hsinchu foundries.
South Korea
Samsung Electronics leverages memory-foundry integration to control HBM3E supply chains for generative AI accelerators. The Ministry of Trade, Industry and Energy channels funding through the K-Chips Act toward advanced packaging R&D consortia. Pyeongtaek's semiconductor cluster houses captive TSV fabrication for high-bandwidth memory stacks.
Japan
Tokyo Electron and Shin-Etsu Chemical supply critical equipment and materials to hybrid bonding process lines. METI's post-CMOS integration subsidies are assembling domestic packaging consortia in Kyoto and Ibaraki. Tsukuba's National Institute of Advanced Industrial Science and Technology hosts wafer-to-wafer bonding research for sub-10 micrometer interconnect pitch.
China
Domestic foundries are qualifying organic substrate alternatives to silicon interposers for bandwidth requirements below 500 gigabytes per second. MIIT's integrated circuit industry guidelines prioritize fan-out panel level packaging for mobile processor localization. Shanghai's Zhangjiang Hi-Tech Park houses JCET Group's advanced packaging expansion for consumer electronics volume.
3D IC and 2.5D IC Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and customer access dimensions, with market structure consolidating around foundry-integrated packaging and fragmenting among legacy OSATs. Memory-foundry hybrids and pure-play interposer fabricators represent distinct strategic archetypes. Capacity reservation agreements and hybrid bonding technology licensing constitute the dominant competitive moves as margin capture shifts upstream.
Among Asia-Pacific-based fabricators, Taiwan Semiconductor Manufacturing Company and Samsung Electronics exemplify the foundry-integrated archetype, while ASE Technology Holding occupies a position bridging high-volume assembly and advanced interposer test. Intel Corporation anchors the Western captive packaging vector through domestic expansion. These three entities represent the concentration points where AI accelerator procurement and automotive qualification pipelines intersect.
| Leading Market Players |
|---|
| Samsung Electronics |
| Taiwan Semiconductor Manufacturing Company |
| Intel Corporation |
| ASE Technology Holding |
| Amkor Technology |
| Broadcom |
| Texas Instruments |
| United Microelectronics Corporation |
| JCET Group |
| Others |
Value Chain & Pricing Dynamics
Wafer-scale processing economics at Taiwan's Hsinchu corridor compress unit costs for silicon interposers above 2,500 square millimeters, establishing price floors that marginal competitors in Japan and the United States cannot match without subsidy support. This scale concentration feeds directly into procurement leverage for hyperscale cloud providers negotiating multi-year capacity reservations.
Pricing Analysis
Volume-discount tiering structures separate hyperscale cloud providers securing multi-year capacity reservations from automotive OEMs locked into IATF 16949 qualification pipelines. Price differentiation centers on certification grade and volume scale, with defense-grade ITAR-traceable interposers commanding substantial premiums over commercial equivalents. Cost compression in mid-tier fan-out packaging is intensifying because Apple and Qualcomm procurement shifts toward substrate-less designs eliminate organic laminate costs. Automotive ADAS suppliers exhibit the highest price sensitivity due to ISO 26262 functional safety qualification burdens, while AI accelerator designers prioritize bandwidth density over unit economics.
Supply Chain Analysis
Port congestion at Taoyuan International Airport and Kaohsiung harbor container availability constrain inbound logistics costs for die-bonding equipment and precision inspection tools destined for Hsinchu Science Park. Geographic supply concentration centers on Taiwan, South Korea, and the United States, with Japan supplying critical hybrid bonding equipment from Tokyo Electron. Raw material dependencies include high-purity silicon wafers, photoresist chemicals, and copper redistribution layer sputtering targets. Single-source vulnerability to seismic disruption in the Hsinchu-Taichung corridor represents the dominant structural risk. Distribution runs through foundry-direct channels for advanced interposers, bypassing traditional OSAT relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against organic substrate substitution below 500 gigabytes per second bandwidth thresholds, where fan-out panel level packaging threatens silicon interposer volumes in mobile and consumer applications.
For Market Incumbents: Consolidate hybrid bonding process control through backward integration into copper-to-copper direct bond equipment supply. Capture IATF 16949 automotive qualification pipelines before ISO 26262 functional safety requirements extend to advanced driver-assistance systems. The priority lever rests on yield discipline in large-area interposers exceeding 2,500 square millimeters, where defect density destroys margins at current wafer costs. For New Entrants and Emerging Players: Anchor in Japan's METI-subsidized post-CMOS integration consortia, where Kyoto and Ibaraki packaging ecosystems remain underdeveloped relative to Taiwan's Hsinchu corridor. Target European automotive compute modules affected by EU Chips Act domestic content thresholds mandating European-sourced interposer substrates. The penetrable entry point lies in licensed packaging partnerships with Dresden and Leuven facilities for China-excluded production networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among semiconductor foundries with captive advanced packaging integration, where multi-year capacity reservations from Microsoft, Amazon, and Google de-risk capital intensity. Long-term viability across the analysis window hinges on hybrid bonding technology licensing positions rather than legacy microbump assembly assets. The acquisition target archetype comprises memory-foundry hybrids controlling HBM3E supply chains. The signal to watch is TSMC CoWoS capacity expansion announcements as a proxy for AI training cluster demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Bonding Technology Licensing | Copper-to-copper direct bond interfaces displace microbump assembly for NVIDIA and AMD AI accelerators. |
| Automotive Qualification Pipeline Investment | IATF 16949 certification cycles lock in multi-year supplier relationships for advanced driver-assistance systems. |
| Domestic Interposer Fabrication Expansion | CHIPS Act funding redirects foundry investment toward Arizona and New Mexico CoWoS-equivalent lines. |
| Capacity Reservation Agreement Structuring | Hyperscale cloud providers negotiate multi-year contracts directly with TSMC and Intel Foundry Services. |
| Fan-Out Packaging Migration | Apple and Qualcomm processor roadmaps accelerate substrate-less adoption for handset form-factor constraints. |
Study Parameters
The analysis maps silicon interposer fabrication, TSV-based stacking, wafer-level packaging, and fan-out redistribution architectures, each validated through foundry process engineers, OSAT operations directors, hyperscaler procurement leads, and automotive Tier 1 supplier packaging specialists. Primary interview data triangulates against secondary sources including SEC 10-K filings, SEMI equipment market data, Department of Commerce export control notifications, and EU Chips Act implementation guidelines. Bottom-up capacity utilization models reconcile with top-down semiconductor capital expenditure forecasts.
Consistency checks validate volume and value outputs against external benchmarks including foundry revenue disclosures, equipment vendor order backlogs, and hyperscaler infrastructure capex allocations across the projection horizon. Segmentation dimensions modeled encompass product architecture, integration technology, application workload thermal design power thresholds, and customer type procurement structure. CAGRs derive from capacity expansion announcements, yield improvement trajectories, and substitution elasticity estimates for organic substrate alternatives. Industry-specific forecast inputs include HBM3E stack proliferation rates and hybrid bonding process adoption curves.
Material uncertainties — geopolitical disruption to Taiwan supply chains, organic substrate substitution acceleration, and automotive qualification timeline extensions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding yield discipline maintenance and equipment qualification dual-track compliance costs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Europe Analog IC Market
IC (Integrated Circuits)
Global Power Management IC (PMIC) Market
IC (Integrated Circuits)
Global SRAM and ROM Design IP Market
IC (Integrated Circuits)
United States Integrated Circuits Market
IC (Integrated Circuits)
Global Photonic Integrated Circuits (PIC) Market
IC (Integrated Circuits)
Lithium Battery Charger Ics Market
IC (Integrated Circuits)
Taiwan Analog Integrated Circuits Market
IC (Integrated Circuits)
Japan Integrated Circuit (IC) Market
IC (Integrated Circuits)
Application Specific Integrated Circuit Market
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
Digital Audio IC Market
IC (Integrated Circuits)
Logic IC Market
IC (Integrated Circuits)
Digital IC Market
IC (Integrated Circuits)
Automotive Special Purpose Logic IC Market
IC (Integrated Circuits)
Reset Integrated Circuit (IC) Market
IC (Integrated Circuits)
Rugged IC Market