
 Global Interface IC Market | 2026-2036
Global Interface IC Market Size, Share, and Industry Trends Forecast 2026-2036
Global Interface IC Market Foresight
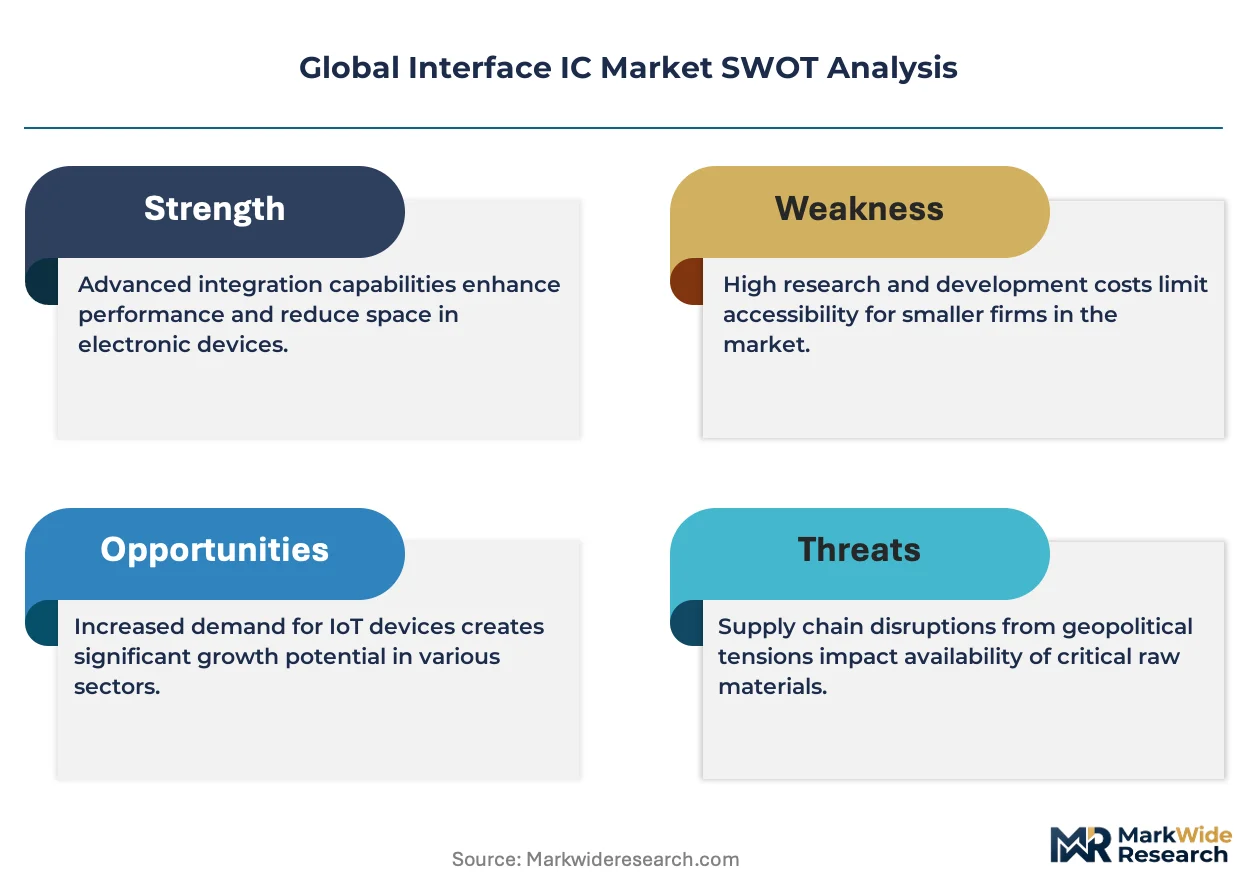
Automotive electronics is expanding as the dominant demand vertical for interface ICs, displacing traditional consumer electronics procurement patterns. Texas Instruments leverages its broad CMOS portfolio to anchor automotive-qualified level shifter supply. Infineon Technologies dominates high-reliability bus transceiver segments through in-house fab control. Renesas Electronics specializes in multiplexers for transportation control systems, sustaining design-win momentum across tier-one module suppliers.
Interface ICs are mixed-signal integrated circuits that translate voltage levels, buffer data lines, and route signals between dissimilar logic families, typically operating across supply ranges from 1.2 V to 5.5 V with propagation delays below 10 nanoseconds. Their primary purpose is ensuring signal integrity and protocol compatibility between processors, sensors, and actuators in multi-voltage electronic systems. CMOS technology leads volume production due to low static power draw, while BiCMOS variants command margin pools in aerospace systems requiring combined speed and noise immunity. Data buffers represent the fastest-growing product type as data center backplanes and telecommunications equipment multiply high-speed signal distribution nodes.
FDA device regulations in the US shape interface IC specifications for medical instrumentation through electromagnetic compatibility and isolation requirements. ECHA REACH restrictions in Europe constrain halogenated flame retardants in IC packaging materials, forcing substrate redesigns. China's GB standards and MIIT directives mandate domestic certification for telecommunications equipment components, altering market access pathways. Stakeholders must monitor how divergent regional substance regulations and interface protocol standards reshape qualification costs and supplier eligibility across end-use verticals.
Market Dynamics
Automotive platform electrification is compressing signal routing architectures into fewer discrete components, forcing interface IC suppliers to consolidate voltage translation, buffering, and protocol conversion into single-package solutions that reduce board space and BOM complexity across EV powertrain modules.
Growth Catalysts
- EU REACH substance restrictions:Halogenated flame retardant bans in semiconductor packaging are accelerating substrate material innovation, creating qualification windows for suppliers with lead-free and halogen-free process capabilities.
- Electric vehicle signal density:Battery management systems and inverter controls multiply isolated communication channels per vehicle, expanding unit demand for automotive-qualified bus transceivers and galvanic isolators.
- China domestic fab expansion:Local sourcing mandates under MIIT telecommunications directives are redirecting procurement of level shifters and voltage translators toward indigenous suppliers with GB-certified production lines.
Market Restraints
- 300mm silicon wafer cost volatility:Raw substrate pricing fluctuations compress gross margins for fabless interface IC designers locked into long-term foundry contracts without pass-through clauses.
- Automotive qualification timeline:AEC-Q100 Grade 1 certification cycles extending 18-24 months delay revenue recognition for new product introductions and freeze out smaller competitors lacking capital reserves.
- Integrated SoC substitution:Advanced microcontrollers with embedded level-shifting I/O banks are absorbing discrete interface functions in cost-sensitive consumer electronics, eroding addressable market for standalone translators.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor assembly and testing are attracting interface IC packaging investments to serve domestic automotive and industrial equipment demand.
- Space-grade radiation-hardened variants:Satellite constellation deployments and lunar exploration programs create premium-margin demand for SEL-immune bus transceivers with extended temperature ranges.
- USB4/Thunderbolt 4 signal conditioning:High-speed data center interconnects require redriver and retimer ICs that compensate for PCB trace losses, opening adjacent product categories for established interface suppliers.
Industry Challenges
- Mixed-signal design talent scarcity:Experienced analog IC architects capable of optimizing propagation delay and power consumption simultaneously command premium compensation and extend hiring cycles.
- Multi-protocol certification stacking:Simultaneous compliance with USB-IF, PCI-SIG, and MIPI Alliance specifications for universal interface products multiplies validation engineering headcount and test equipment capex.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Interface IC Market |
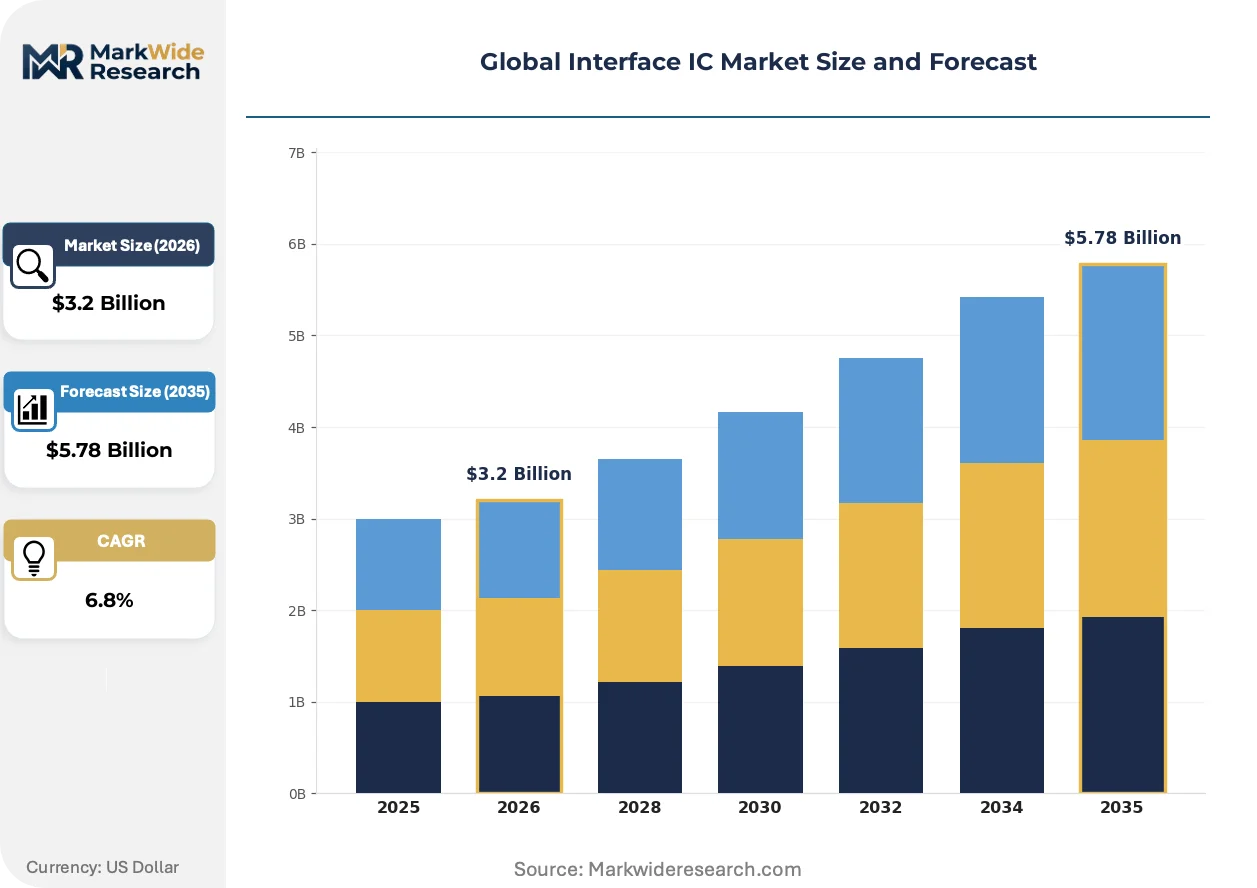
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Level Shifters, Bus Transceivers, Multiplexers, Programmable Interface, Data Buffers, Comparators Technology: CMOS, Bipolar, BiCMOS, TTL, ECL, RTL Application: Consumer Electronics, Aerospace Systems, Telecommunications Equipment, Semiconductor Manufacturing, Instrumentation, Transportation Control End User: OEMs, System Integrators, Contract Manufacturers, Research Laboratories, Defense Contractors, Academic Institutions |
| Companies Covered | STMicroelectronics, Renesas Electronics, Texas Instruments, Broadcom, Microchip Technology, Analog Devices, Infineon Technologies, Marvell Technology, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Interface IC Market Shifts & Advancements
Silicon integration trajectories and protocol standardization are compressing discrete component counts while expanding functional density, reshaping how interface ICs are specified, procured, and qualified across end-use verticals.
Integrated signal conditioning with adaptive equalization is unifying redriver and retimer functions into single-die solutions for PCIe Gen5 and USB4 backplanes. Hyperscale data center operators are deploying these consolidated devices to extend trace lengths without sacrificing signal integrity. This unification is collapsing the historical separation between physical layer conditioning and protocol-aware buffering, enabling tier-one ODMs to reduce component count by 40% in high-speed interconnect designs.
ECHA REACH Annex XVII restrictions on halogenated compounds in electrical equipment are forcing substrate material transitions across European-bound semiconductor shipments. Mold compound suppliers are qualifying epoxy resins with phosphorus-based flame retardants that meet UL94 V-0 ratings without bromine or chlorine content. Medical instrumentation manufacturers in Germany and France are absorbing 8-12% packaging cost premiums to maintain CE marking compliance and EU market access.
Automotive tier-one module suppliers are consolidating vendor bases and demanding system-level signal integrity guarantees rather than discrete component specifications. Procurement teams at German and Japanese automakers now require interface IC suppliers to validate complete communication链路 performance across temperature and voltage corners. This specification shift favors semiconductor houses with in-house application engineering teams capable of co-designing with customer PCB layouts.
Global Interface IC Market Segmentation
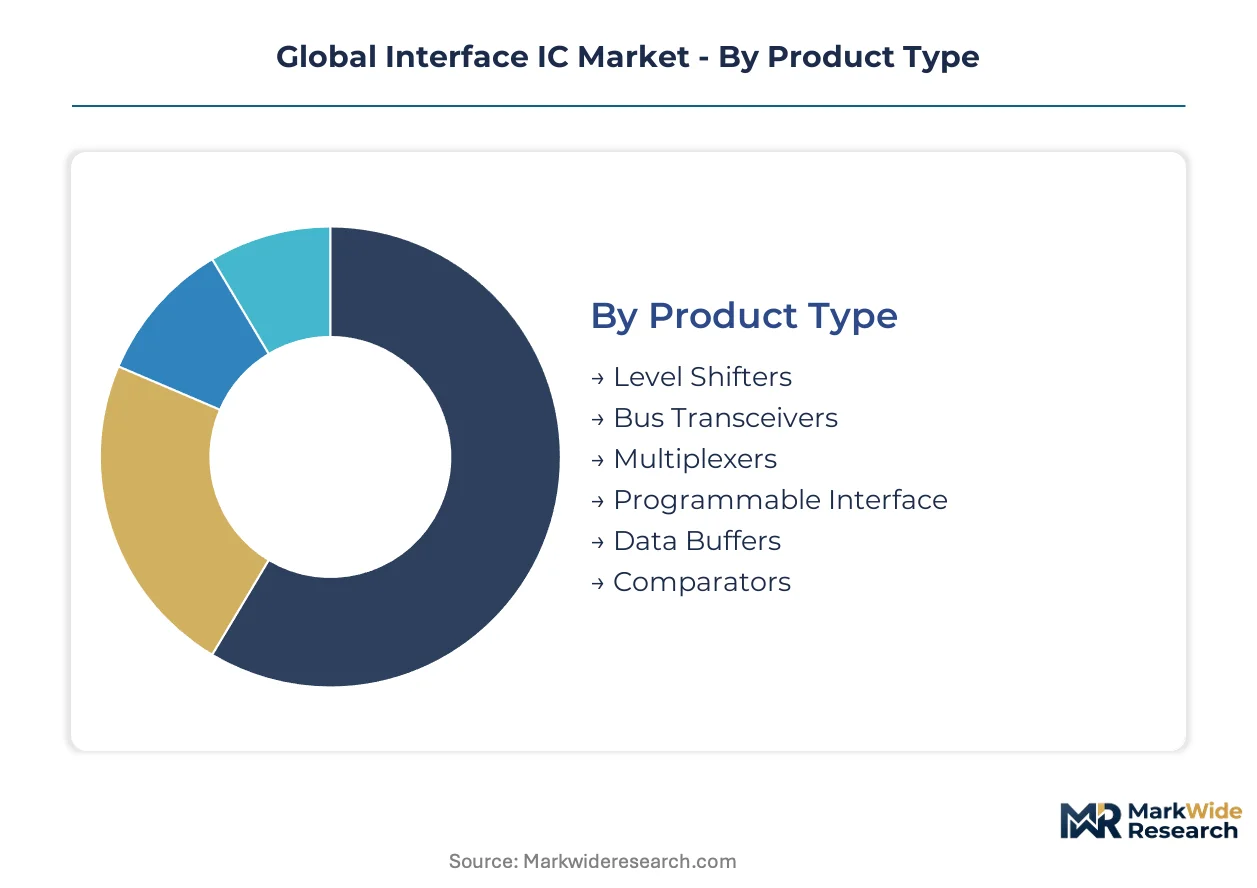
Interface IC procurement patterns diverge sharply across voltage requirements, signal speeds, and qualification tiers. Segmentation reveals how automotive electrification concentrates demand in automotive-qualified categories while data center expansion pulls high-speed buffering solutions.
Product Type:
Volume production concentrates in standardized voltage translators, while premium margins attach to specialized buffering and isolation functions.
- Level Shifters:CMOS-based translators bridge 1.2 V to 5.5 V logic families with propagation delays below 5 nanoseconds. Demand clusters in China where domestic fab expansion drives local sourcing for telecommunications equipment and consumer electronics assembly.
- Bus Transceivers:Bidirectional buffers with tri-state outputs enable shared data bus architectures in multi-master systems. Automotive battery management systems and inverter controls in Germany and Japan multiply isolated CAN and LIN channel requirements per vehicle platform.
- Multiplexers:Analog switches route signals between multiple inputs and single outputs based on digital select lines.
- Programmable Interface:Field-configurable logic arrays adapt to protocol variations without hardware redesign.
- Data Buffers:High-drive output stages regenerate clock and data signals across extended PCB traces.
- Comparators:Differential amplifiers with digital outputs detect threshold crossings in sensor interface circuits.
Mature deployment sits with Level Shifters. Newer deployment is concentrated in Data Buffers.
Technology:
Process selection trades static power dissipation against switching speed and noise immunity, with cost tiers separating consumer from industrial and aerospace applications.
- CMOS:Complementary MOS pairs deliver sub-microamp static current draw across wide supply ranges. Dominates volume production for portable electronics and IoT edge devices where battery life determines competitive positioning.
- BiCMOS:Combines bipolar transistors for analog precision with CMOS density for digital integration. Commands premium pricing in aerospace systems requiring combined bandwidth and radiation tolerance for satellite bus interfaces.
- Bipolar:NPN/PNP transistor pairs achieve faster switching than CMOS at comparable geometry nodes.
- TTL:Transistor-transistor logic maintains legacy compatibility in industrial control systems.
- ECL:Emitter-coupled logic provides sub-nanosecond propagation for high-speed instrumentation.
- RTL:Resistor-transistor logic persists in educational kits and vintage equipment replacement.
CMOS captures the steepest expansion trajectory as voltage scaling and power constraints dominate new designs.
Application:
End-use concentration splits between high-volume consumer procurement and long-lifecycle industrial qualification tracks.
- Automotive Electronics:Battery management systems, inverter controls, and ADAS sensor fusion multiply isolated communication channels per electric vehicle. EU REACH substance restrictions on halogenated flame retardants force packaging redesigns for European-bound shipments.
- Telecommunications Equipment:Baseband processing and optical line termination demand high-speed signal conditioning with protocol-aware buffering. China's MIIT directives mandate GB certification for domestic network infrastructure deployments.
- Consumer Electronics:Smartphones and wearables drive unit volume in sub-2V level shifting applications.
- Aerospace Systems:Satellite payloads and avionics require extended temperature ranges and single-event latchup immunity.
- Semiconductor Manufacturing:Test equipment and probe stations utilize precision comparators for parametric verification.
- Instrumentation:Medical devices and laboratory equipment demand isolation barriers meeting FDA electromagnetic compatibility requirements.
Automotive Electronics and Telecommunications Equipment together anchor procurement volume, with Transportation Control representing the fastest-growing trajectory as rail and marine electrification accelerates.
End User:
Customer type determines contract structure, with OEMs negotiating multi-year supply agreements while research buyers prioritize technical evaluation access.
- OEMs:Original equipment manufacturers specify interface ICs at the platform architecture stage, locking in suppliers for vehicle or equipment program lifecycles. German and Japanese automakers now require system-level signal integrity validation across temperature corners.
- Defense Contractors:Military program offices mandate traceable supply chains and domestic wafer fabrication for strategic systems. US DoD Trusted Foundry requirements restrict sourcing for radiation-hardened bus transceivers.
- System Integrators:Subcontractor procurement teams aggregate demand across multiple OEM programs.
- Contract Manufacturers:Foxconn, Jabil, and Flex manage component sourcing for brand-label electronics.
- Research Laboratories:CERN, NASA, and national labs procure small quantities with extensive documentation requirements.
- Academic Institutions:University engineering programs drive educational kit volume with minimal margin contribution.
OEMs dominate revenue concentration. Defense Contractors represent the highest margin capture per unit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate interface IC packaging and testing capacity, with government-backed industrial parks in Suzhou and Wuxi offering 15-year tax holidays for semiconductor assembly investments. This fiscal architecture redirects supply chain gravity toward domestic fab ecosystems.
China
MIIT telecommunications directives mandate GB certification for network infrastructure components, redirecting procurement toward indigenous suppliers. Domestic fab expansion in Shanghai and Hefei drives local sourcing of bus transceivers for 5G base stations and EV powertrains. Suzhou Industrial Park hosts concentrated back-end testing capacity serving tier-one automotive module suppliers.
United States
FDA electromagnetic compatibility requirements shape interface IC specifications for medical instrumentation and diagnostic equipment. Defense contractors in Arizona and Texas face Trusted Foundry restrictions on radiation-hardened components for satellite systems. Silicon Valley design houses anchor fabless innovation in high-speed signal conditioning for data center interconnects.
Germany
ECHA REACH Annex XVII halogenated flame retardant bans force substrate material transitions in semiconductor packaging. Automotive OEMs in Stuttgart and Munich now require system-level signal integrity validation across temperature corners. Bavaria's semiconductor cluster specializes in automotive-qualified level shifters for battery management systems.
Japan
METI industrial policy supports domestic production of high-reliability bus transceivers for transportation control systems. Renesas Electronics maintains design-win momentum across tier-one module suppliers in Nagoya and Hiroshima. Kyushu fabrication facilities concentrate BiCMOS process capabilities for aerospace and satellite applications.
India
PLI scheme incentives for semiconductor assembly and testing attract interface IC packaging investments to serve domestic automotive demand. Karnataka and Tamil Nadu host emerging back-end facilities targeting industrial equipment and telecommunications equipment markets. DGFT import substitution policies accelerate local procurement of voltage translators for consumer electronics assembly.
Global Interface IC Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with IDM houses controlling automotive qualification pipelines and fabless designers capturing data center socket opportunities. Market structure tiers around three archetypes: integrated device manufacturers with captive fabs, fabless specialists with foundry partnerships, and diversified semiconductor conglomerates with broad CMOS portfolios. Competitive moves concentrate on automotive certification stacking and substrate material qualification for EU REACH compliance.
Within the integrated device manufacturer tier, Texas Instruments and Infineon Technologies exemplify divergent approaches to automotive signal routing. Texas Instruments leverages broad CMOS portfolio breadth to anchor level shifter supply across multiple voltage translation requirements. Infineon Technologies occupies a position emphasizing in-house fab control for high-reliability bus transceiver segments. Renesas Electronics represents the transportation specialization vector, sustaining design-win momentum through multiplexers and protocol conversion devices.
| Leading Market Players |
|---|
| STMicroelectronics |
| Renesas Electronics |
| Texas Instruments |
| Broadcom |
| Microchip Technology |
| Analog Devices |
| Infineon Technologies |
| Marvell Technology |
| NXP Semiconductors |
| Others |
Supply & Pricing Matrix
AEC-Q100 certification tiers bifurcate interface IC procurement into automotive-qualified premium lanes and consumer-grade commodity channels, with Grade 1 parts commanding three-to-fourfold price multiples over commercial temperature variants while concentrating supply through IDM houses with captive fab capacity in Germany, Japan, and the United States.
Pricing Analysis
Lead-time-driven pricing stratification rewards inventory positioning, with 52-week committed capacity securing 15-20% discounts against spot-market premiums for automotive-grade bus transceivers. Contract-based long-term offtake agreements dominate OEM procurement, while spot purchasing persists in consumer electronics assembly. Price differentiation hinges on AEC-Q100 grade attainment and in-house fab control, with fabless designers absorbing foundry margin compression. Cost compression in commercial-grade level shifters is intensifying because Chinese domestic suppliers are expanding 300mm CMOS capacity. Contract manufacturers exhibit highest price sensitivity; defense contractors least.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive demand, while distribution partners serve fragmented industrial and consumer accounts. Geographic supply concentration centers on Taiwan for front-end wafer fabrication, China for back-end assembly and testing, and Germany for automotive-qualified packaging. Raw material dependencies include 300mm silicon wafers, gold wire bonding materials, and halogen-free epoxy mold compounds. Single-source vulnerability persists in automotive-grade substrate supply following ECHA REACH restrictions. Distribution runs through authorized distributors for qualification-critical applications and open-market brokers for commercial-grade volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECHA REACH substance restrictions erect a cost-of-compliance barrier that favors incumbent suppliers with qualified halogen-free packaging processes, freezing out capital-constrained entrants unable to absorb 18-24 month automotive certification timelines.
For Market Incumbents: Acquire specialized substrate material suppliers to secure halogen-free mold compound supply chains ahead of REACH enforcement deadlines. Consolidate AEC-Q100 certification pipelines through backward integration into automotive-grade testing facilities. Counter integrated SoC substitution threats by embedding signal conditioning expertise into system-level reference designs for tier-one module suppliers. For New Entrants and Emerging Players: USB4/Thunderbolt 4 redriver architectures offer technology-first entry into data center interconnect markets with shorter qualification cycles than automotive tracks. Target India's PLI-subsidized packaging corridors for cost-competitive assembly of industrial-grade voltage translators. Pursue white-label partnerships with contract manufacturers serving China's MIIT-mandated telecommunications infrastructure deployments. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified semiconductor conglomerates seeking automotive signal routing capabilities. Long-term viability favors targets with dual-use aerospace-automotive qualification portfolios and in-house BiCMOS process expertise. Monitor MIIT domestic sourcing mandate enforcement as inflection signal for Chinese supplier valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Certification Stacking | Simultaneous AEC-Q100 and ISO 26262 attainment opens German and Japanese OEM supply positions. |
| Halogen-Free Packaging Transition | Phosphorus-based flame retardant qualification preserves EU market access against REACH Annex XVII bans. |
| India PLI Assembly Investment | Karnataka and Tamil Nadu facilities capture domestic automotive demand under import substitution policies. |
| USB4 Signal Conditioning Development | Redriver-retimer integration addresses hyperscale data center trace length extension requirements. |
| Radiation-Hardened Product Line Extension | SEL-immune bus transceivers serve satellite constellation deployments and lunar exploration programs. |
Research Methodology
Document review covered SEC semiconductor filings, ECHA regulatory guidance, and MIIT telecommunications directives, complemented by interviews with automotive platform engineers, tier-one module supplier procurement leads, fabless IC design house executives, and foundry capacity planning managers. Secondary validation drew from customs trade databases, AEC council membership records, and hyperscaler capex disclosures. Bottom-up unit demand modeling triangulated against top-down semiconductor market sizing across the analysis window.
Cross-referencing historical shipment patterns against expert panel input informed the projection framework. Segmentation dimensions modeled include product type, process technology, end-use application, and regional regulatory cluster. CAGRs derived from slope analysis of normalized growth trajectories. Industry-specific forecast inputs incorporated electric vehicle platform rollout schedules and 5G base station deployment cadence.
Several conditions sit outside the modeled scope, including geopolitical trade restriction escalations, foundry capacity allocation disruptions, and unannounced integrated SoC architectural shifts. Forecasts reflect documented assumptions regarding automotive electrification penetration and REACH enforcement timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Consumer Special Purpose Logic IC Market
IC (Integrated Circuits)
NFC Reader Ics Market
IC (Integrated Circuits)
Global Consumer Standard Logic IC Market
IC (Integrated Circuits)
Asia Pacific Logic IC Market
IC (Integrated Circuits)
Integrated Circuit Market
IC (Integrated Circuits)
Logic IC Market
IC (Integrated Circuits)
Display Driver IC Market
IC (Integrated Circuits)
Global General Purpose Analog IC Market
IC (Integrated Circuits)
3D Integrated Circuit Market
IC (Integrated Circuits)
Global Semiconductor Timing IC Market
IC (Integrated Circuits)
Gate Driver IC Market
IC (Integrated Circuits)
Digital Audio IC Market
IC (Integrated Circuits)
Digital IC Market
IC (Integrated Circuits)
Europe Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Americas Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Application Specific Automotive Analog IC Market