
 Estrogen Replacement Therapy (ERT) Market | 2026-2036
Estrogen Replacement Therapy (ERT) Market Size, Share, and Industry Trends Forecast 2026-2036
Estrogen Replacement Therapy (ERT) Market Foresight
Subscription-based patient monitoring and adherence programs are repositioning how pharmaceutical companies monetize ERT beyond the initial prescription. Pfizer Inc. leverages its established cardiovascular co-marketing infrastructure to sustain physician engagement with hormone therapy portfolios. Bayer AG anchors its competitive stance through specialized transdermal manufacturing capabilities that differentiate patch-based offerings from oral alternatives. Novo Nordisk A/S navigates the regulatory complexity of bioidentical formulations while competing on endocrine therapy integration.
Estrogen Replacement Therapy comprises pharmaceutical formulations delivering estradiol, estrone, or conjugated estrogens through systemic or local routes to restore declining endogenous hormone levels in peri- and post-menopausal patients. The primary commercial purpose centers on vasomotor symptom relief, urogenital atrophy prevention, and osteoporosis risk reduction, with transdermal patches achieving preferred status among patients with hepatic metabolism concerns. Oral administration retains structural dominance in volume terms due to decades of clinical familiarity and broad generic availability, though transdermal delivery captures expanding margin pools as patients and payers prioritize cardiovascular safety profiles. Homecare distribution channels are accelerating fastest as direct-to-patient pharmacy models reduce clinic dependency for refill maintenance.
The FDA maintains stringent labeling requirements for estrogen-containing products through its Division of Bone, Reproductive and Urologic Products, while the EMA's Pharmacovigilance Risk Assessment Committee periodically reviews thromboembolic signal data across hormone therapy classes. These frameworks elevate the cost of post-market surveillance compliance and restrict promotional claims to evidence-supported indications. Stakeholders must monitor evolving biosimilar pathways for complex hormone formulations and assess whether compounding pharmacy oversight tightening will redirect demand toward manufactured alternatives.
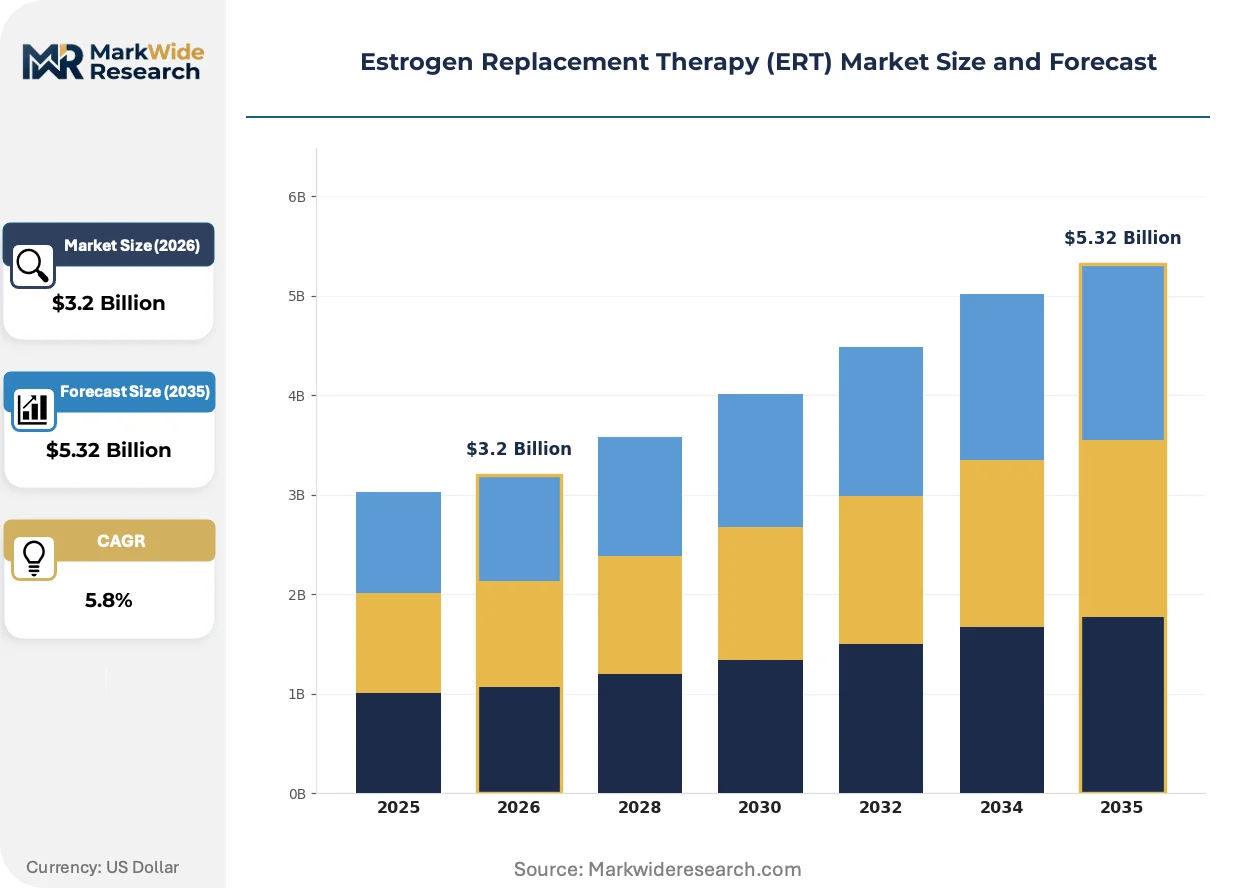
Market Dynamics
Patient preference for cardiovascular-sparing delivery routes is compressing oral estrogen volumes while expanding transdermal manufacturing capacity investments across contract development organizations.
Growth Catalysts
- Aging demographics in Germany:Federal reimbursement pathways for menopausal hormone therapy sustain prescription volumes through statutory health insurance coverage expansion.
- FDA labeling guidance updates:Revised safety communication frameworks enable clearer risk-benefit discussions between physicians and symptomatic patients.
- Transdermal patch technology:Steady-state estradiol delivery avoids first-pass hepatic metabolism, attracting patients with lipid metabolism concerns.
Market Restraints
- Plasma-derived raw material concentration:Conjugated estrogen sourcing depends on limited North American equine facility capacity, creating supply vulnerability.
- EMA thromboembolic surveillance:Pharmacovigilance Risk Assessment Committee periodic reviews elevate post-market study costs and restrict promotional latitude.
- Bioidentical compounding substitution:Non-standardized pharmacy formulations capture price-sensitive patients outside regulated manufacturing quality systems.
Strategic Opportunities
- Direct-to-patient pharmacy channels:Subscription-based adherence programs in homecare settings reduce clinic dependency for refill maintenance.
- EMA biosimilar pathway development:Emerging regulatory frameworks for complex hormone formulations create entry routes for specialized manufacturers.
- Integrated endocrine portfolios:Co-development with diabetes and thyroid therapeutic lines leverages existing physician access infrastructure.
Industry Challenges
- Specialized formulation chemist scarcity:Transdermal adhesive matrix development requires polymer science expertise concentrated in limited geographic talent pools.
- Multi-jurisdiction label harmonization:Divergent FDA and EMA indication language complicates global clinical trial design and regulatory submission sequencing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Estrogen Replacement Therapy (ERT) Market |
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.32 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pills, Patches, Gels, Implants Mode of Administration: Oral, Transdermal, Intravenous, Vaginal End User: Clinics, Hospitals, Homecare, Pharmacies Distribution Channel: Retail, Online, Hospital Pharmacies, Wholesalers |
| Companies Covered | Pfizer Inc., Bayer AG, AbbVie Inc., Novartis AG, Novo Nordisk A/S, Teva Pharmaceutical Industries Ltd., Merck & Co., Inc., Eli Lilly and Company, Viatris Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Estrogen Replacement Therapy (ERT) Market Shifts & Advancements
Delivery mechanism innovation and regulatory transparency initiatives are converging to reshape competitive advantage in hormone replacement, with patient safety data accessibility becoming a core differentiator.
Microneedle array patches for intradermal estradiol delivery is rewriting the boundary between transdermal convenience and injection precision. Early adopters in concierge menopause practices are piloting these devices for patients with adhesive sensitivity or irregular absorption from conventional patches. The technology is compressing the gap between patient self-administration preference and clinical confidence in dose reliability.
EMA's strengthened pharmacovigilance signal detection mandates for hormone therapies are accelerating investment in real-world evidence infrastructure across European marketing authorization holders. Manufacturers must now maintain active surveillance systems capable of detecting rare thromboembolic events in heterogeneous patient populations. Smaller portfolio companies without existing epidemiology partnerships face disproportionate compliance cost burdens relative to diversified pharmaceutical groups.
Patient-initiated therapy switching based on cardiovascular safety profile comparisons is disrupting traditional physician-driven prescription continuity. Online menopause communities and direct-to-consumer lab monitoring services enable self-directed formulation changes, particularly in markets with pharmacy substitution rights. This pattern concentrates in English-speaking markets with high digital health literacy and established private prescription delivery infrastructure.
Estrogen Replacement Therapy (ERT) Market Segmentation
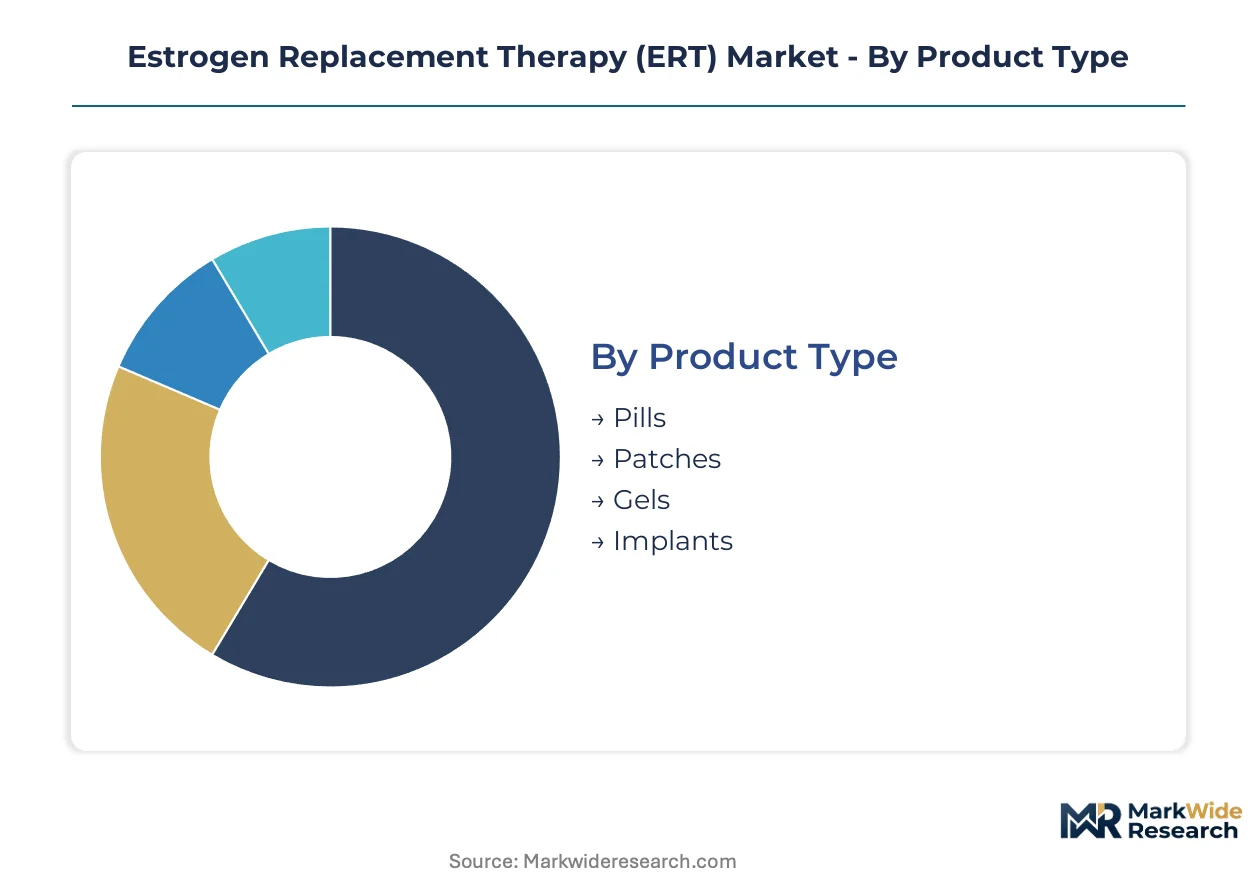
ERT segmentation reflects divergent patient risk profiles and reimbursement pathways. Route-specific formulation decisions increasingly drive prescribing behavior rather than brand loyalty alone.
Product Type:
Patient cardiovascular risk tolerance determines formulation selection, with hepatic metabolism concerns elevating non-oral alternatives.
- Pills:Oral conjugated estrogens and estradiol tablets dominate prescription volumes through decades of clinical familiarity and broad generic availability. Demand concentrates in markets with established statutorily reimbursed oral formularies, though first-pass liver effects constrain use in patients with lipid abnormalities.
- Patches:Transdermal estradiol delivery systems achieve preferred status among patients seeking steady-state hormone levels without hepatic processing. Germany's aging demographics and reimbursement pathway clarity support sustained patch volume expansion in homecare settings.
- Gels:Metered-dose topical estradiol formulations offer application flexibility for patients with adhesive sensitivity or irregular patch absorption patterns.
- Implants:Subcutaneous pellet systems provide extended-release delivery for patients prioritizing long-acting convenience over dose adjustability.
Volume sits with pills; growth tilts toward patches.
Mode of Administration:
Route selection increasingly follows cardiovascular safety evidence rather than historical prescribing patterns.
- Oral:First-pass hepatic metabolism generates active estrone metabolites, creating lipid profile considerations that constrain use in patients with cardiovascular risk factors.
- Transdermal:Direct systemic estradiol absorption bypasses hepatic processing, attracting patients and physicians prioritizing thromboembolic risk minimization.
- Intravenous:Hospital-administered estradiol formulations serve acute menopausal symptom management in surgical or oncology contexts.
- Vaginal:Localized estrogen delivery targets urogenital atrophy with minimal systemic exposure, capturing patients with isolated local symptoms.
Oral routes retain prescription dominance; transdermal administration captures expanding margin pools.
End User:
Care setting migration reflects patient preference for reduced clinic dependency and direct pharmacy access.
- Clinics:Specialized menopause practices manage complex cases requiring dose titration and comorbidity coordination.
- Hospitals:Inpatient settings handle acute hormonal interventions and surgical menopause management.
- Homecare:Self-administered transdermal and oral regimens reduce facility visits through direct-to-patient pharmacy models.
- Pharmacies:Community dispensing channels serve stable maintenance prescriptions with pharmacist counseling support.
Homecare settings demonstrate the steepest expansion trajectory as patient monitoring programs shift adherence support outside clinical facilities.
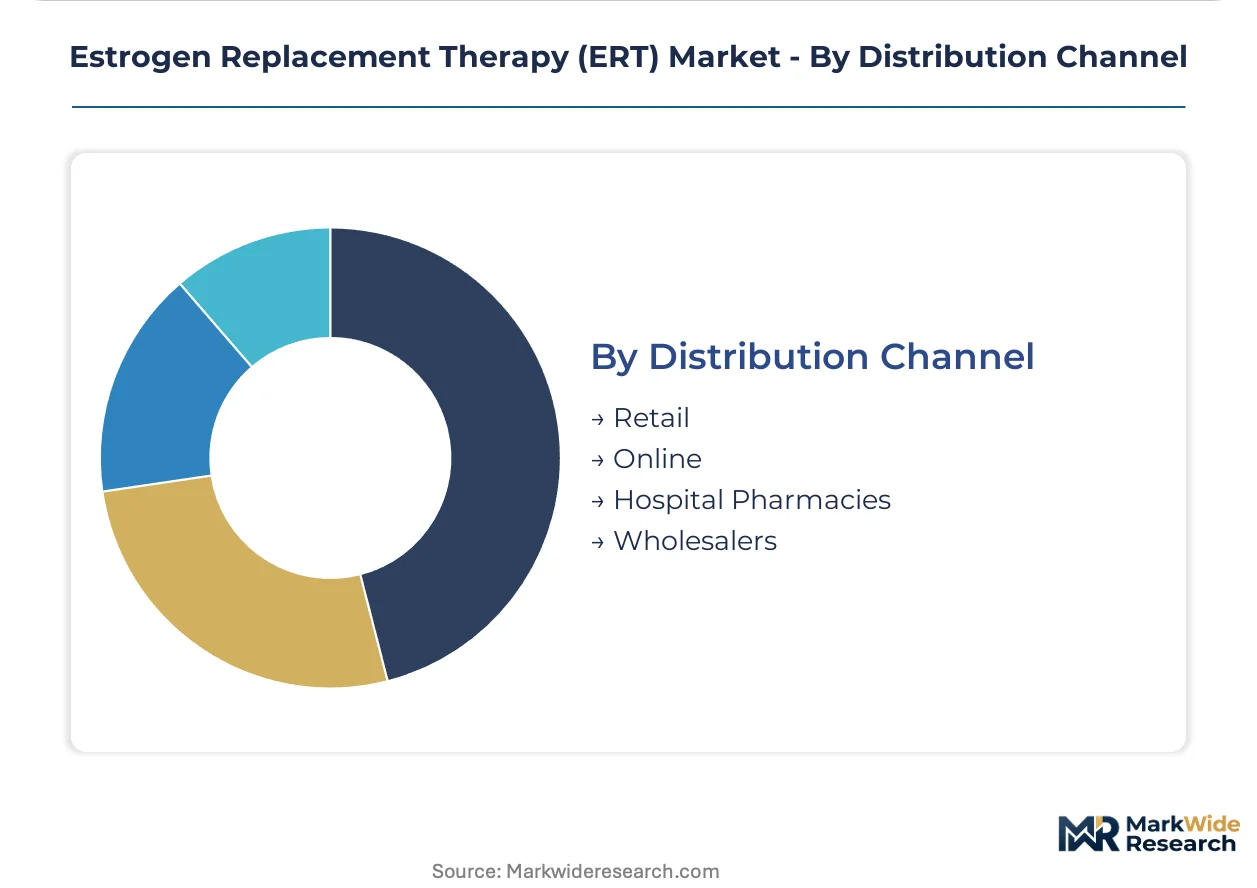
Distribution Channel:
Channel strategy determines refill persistence and patient data capture for pharmacovigilance compliance.
- Retail:Brick-and-mortar pharmacy networks maintain broad geographic coverage for immediate prescription fulfillment.
- Online:Direct-to-patient platforms enable subscription-based adherence programs with automated refill scheduling.
- Hospital Pharmacies:Institutional dispensing captures inpatient initiation and discharge prescription continuity.
- Wholesalers:Distribution intermediaries manage inventory flow to fragmented retail and pharmacy networks.
Retail channels retain structural volume; online distribution gains share fastest through integrated patient monitoring services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of conjugated estrogens concentrates in North American equine facilities, while patient consumption tilts toward aging populations in Western Europe and East Asia. Distribution networks bridge this geographic divide through temperature-controlled logistics and direct-to-patient pharmacy models.
United States
FDA labeling guidance revisions and concierge menopause practices in California and New York drive formulation preference toward transdermal delivery. The FDA's Division of Bone, Reproductive and Urologic Products maintains stringent post-market surveillance requirements that elevate compliance costs for marketing authorization holders. Boston's biotech corridor hosts real-world evidence infrastructure investments supporting pharmacovigilance signal detection.
Germany
Statutory health insurance reimbursement clarity and Bavaria's specialized transdermal manufacturing base sustain prescription volume leadership across Europe. The Federal Joint Committee (G-BA) evaluates menopausal hormone therapy for inclusion in the statutory benefits catalog, shaping physician prescribing incentives. Baden-Württemberg's polymer science talent pools concentrate adhesive matrix development expertise for next-generation patch technologies.
Japan
PMDA's periodic re-evaluation of hormone therapy risk profiles and Tokyo's aging female demographic create demand for low-dose transdermal options. METI's pharmaceutical industry revitalization policies support domestic manufacturing capacity for estradiol formulations. Osaka's medical device cluster incubates microneedle array technologies for intradermal hormone delivery.
United Kingdom
NHS England's menopause care pathway standardization and London's digital health infrastructure enable patient-initiated therapy switching based on cardiovascular safety data. The MHRA's post-Brexit regulatory autonomy permits accelerated approval timelines for novel delivery mechanisms. Cambridge's life sciences cluster attracts real-world evidence platform investments from European marketing authorization holders.
Australia
TGA's streamlined prescription medicine registration processes and Melbourne's telehealth expansion support direct-to-patient pharmacy channel growth. The Pharmaceutical Benefits Advisory Committee evaluates estradiol formulations for subsidy listing, influencing patient out-of-pocket costs. Sydney's private menopause clinics pioneer subscription-based adherence monitoring programs for transdermal regimens.
Estrogen Replacement Therapy (ERT) Market Competitive Landscape
Capital-heavy producers with captive manufacturing assets compete with asset-light portfolio licensors relying on contract development organizations for formulation supply. The market structure tilts toward consolidated pharmaceutical groups with diversified endocrine therapy portfolios, though specialized transdermal manufacturers retain defensible positions in patch technology. Three archetypes dominate: integrated Big Pharma with cardiovascular co-marketing infrastructure, specialized hormone therapy houses with polymer science capabilities, and generic manufacturers competing on oral formulation cost. Competitive moves center on real-world evidence partnerships for pharmacovigilance compliance and direct-to-patient pharmacy channel integration for refill persistence.
Among integrated pharmaceutical groups, Pfizer Inc. and Bayer AG exemplify divergent strategic positioning within hormone therapy portfolios. Pfizer leverages established cardiovascular therapeutic infrastructure to sustain physician engagement across menopausal and cardiology specialties simultaneously. Bayer anchors competitive stance through specialized transdermal manufacturing capabilities that differentiate patch-based offerings from commodity oral alternatives. Novo Nordisk A/S occupies a distinct position navigating bioidentical formulation regulatory complexity while competing on endocrine therapy integration with diabetes and thyroid portfolios. These three represent how scale, specialization, and therapeutic adjacency create differentiated competitive positions without direct product-for-product confrontation.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Bayer AG |
| AbbVie Inc. |
| Novartis AG |
| Novo Nordisk A/S |
| Teva Pharmaceutical Industries Ltd. |
| Merck & Co., Inc. |
| Eli Lilly and Company |
| Viatris Inc. |
| Others |
Supply & Pricing Matrix
Plasma-derived conjugated estrogen sourcing from North American equine facilities commands premium pricing tiers downstream, with limited facility capacity concentrating supply leverage among manufacturers holding long-term offtake agreements. This input scarcity propagates through formulation costs, stratifying final product pricing across branded, authorized generic, and economy segments.
Pricing Analysis
Margin tightening in oral conjugated estrogen tiers reflects generic saturation and statutory reimbursement compression in Germany and the United States. Three-tier pricing structure across premium transdermal patches, standard oral tablets, and economy generic alternatives separates cardiovascular safety-profiled formulations from commodity oral options. Price differentiation rests on FDA bioequivalence certification status and polymer science complexity in adhesive matrix development. Hospital procurement committees exhibit lowest price sensitivity due to formulary continuity requirements, while cash-pay patients in direct-to-patient pharmacy channels drive hardest negotiation.
Supply Chain Analysis
Temperature-controlled logistics costs for estradiol formulations escalate with distribution distance from North American equine plasma collection sites to European and East Asian manufacturing. Supply concentrates in the United States, Germany, and Japan, with Baden-Württemberg polymer science clusters and Osaka medical device corridors anchoring downstream formulation. Raw material dependencies include equine plasma, estradiol active pharmaceutical ingredient, and specialized silicone adhesive polymers. Single-source vulnerability in North American equine facility concentration exposes manufacturers to animal health regulatory restrictions. Distribution runs through direct-to-patient pharmacy platforms, hospital pharmacies, and wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Limited North American equine facility capacity constrains conjugated estrogen supply, propping pricing power for incumbents holding captive sourcing agreements. This structural bottleneck justifies defensive consolidation around raw material security.
For Market Incumbents: Acquire polymer science formulation capabilities in Baden-Württemberg or equivalent adhesive matrix expertise clusters to secure transdermal patch differentiation. Bioidentical compounding pharmacy substitution threatens branded volume; counter through vertical integration into direct-to-patient pharmacy channels with subscription-based adherence programs. EMA pharmacovigilance signal detection mandates elevate compliance costs that favor scaled epidemiology infrastructure. For New Entrants and Emerging Players: Launch via online direct-to-patient pharmacy models bypassing traditional hospital formulary gatekeepers. Microneedle array intradermal delivery technology represents the most penetrable white-space segment, with concierge menopause practices in California and New York piloting adoption. Target Germany's statutory reimbursement clarity for fastest volume accumulation. Differentiate through cardiovascular safety profile marketing rather than me-too oral formulations. For Investors and Strategic Acquirers: FDA Division of Bone, Reproductive and Urologic Products labeling guidance revisions are the leading indicator that transdermal delivery routes will capture expanding margin pools. Long-term viability favors diversified endocrine therapy portfolios with diabetes and thyroid therapeutic adjacencies. Acquisition target archetype: specialized transdermal manufacturers with captive polymer science expertise and EMA marketing authorization holder status. Watch for real-world evidence infrastructure investments as signal of pharmacovigilance compliance readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA biosimilar framework for complex hormones creates entry routes for specialized manufacturers. |
| Backward Integration | Captive equine plasma sourcing secures conjugated estrogen supply against North American facility constraints. |
| Direct-to-Consumer Launch | Subscription-based adherence programs in homecare settings reduce clinic dependency for refill maintenance. |
| Manufacturing Scale-Up | Transdermal patch capacity expansion in Bavaria leverages polymer science talent concentration. |
| Reimbursement Strategy | Federal Joint Committee evaluation alignment shapes physician prescribing incentives in Germany. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. FDA 510(k) submissions, EMA marketing authorization applications, ClinicalTrials.gov entries, and statutory health insurance reimbursement databases provided validation. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated against manufacturer-reported segment revenues.
Granularity-level modeling operated at formulation type, administration route, end-user setting, and distribution channel dimensions across the analysis window. CAGRs were derived from log-linear trend fitting to historical prescription data and forward projection of demographic and reimbursement drivers. Forecast inputs included aging female population trajectories, statutory insurance coverage expansion policies, and transdermal technology adoption curves in cardiovascular risk-managed patient populations.
Regulatory guidance revisions, equine facility supply disruptions, and bioidentical compounding pharmacy enforcement shifts are the dominant revision risks to projection assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Dipeptidyl Peptidase-4 (DPP-4) Inhibitors Market
Pharmaceuticals
Global Nasal Drug Delivery Technology Market
Pharmaceuticals
Oral Anticoagulant Market
Pharmaceuticals
Injectable Benzodiazepine Market
Pharmaceuticals
Global Anti Epileptic Drugs for Pediatrics Market
Pharmaceuticals
Anticancer Drugs Market
Pharmaceuticals
Global Ethical Pharmaceuticals Market
Pharmaceuticals
US Generic Injectables Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Global Endometriosis Drugs Market
Pharmaceuticals
OTC Dry Eye Drops Market
Pharmaceuticals
Artificial Intelligence in Drug Screening Market
Pharmaceuticals
Global Pediatric Electrolyte Solutions Market
Pharmaceuticals
Flumazenil Market
Pharmaceuticals
Asia-Pacific Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Montelukast Market