
 Sweden Pharmaceutical Market | 2026-2036
Sweden Pharmaceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Pharmaceutical Market Outlook
Good Manufacturing Practice certification is rotating as the decisive gatekeeper for market participation in Sweden. AstraZeneca leverages its Cambridge-Södertälje R&D corridor to sustain biologics pipeline density. Swedish Orphan Biovitrum anchors rare disease portfolio strength through specialized plasma fractionation capabilities. Roche competes on diagnostic-pharmaceutical integration, extending its position in companion therapy ecosystems.
Sweden pharmaceuticals encompass chemically synthesized and biologically derived medicinal products formulated for disease prevention, diagnosis, treatment, or physiological modification, with active pharmaceutical ingredients typically requiring purity thresholds exceeding 99.5 percent and stability validation across defined temperature bands. These products serve healthcare systems through therapeutic intervention, disease management protocols, and population-level health outcomes improvement. Prescription drugs dominate value generation through patented small-molecule and biologic therapies, while generics capture volume share as patent cliffs mature across cardiovascular and neurology portfolios. Oncology biologics command premium positioning within therapy area segmentation, reflecting Sweden's concentrated hematology and immuno-oncology research infrastructure. Injectable delivery modes concentrate margin pools in hospital and long-term care channels, where cold chain logistics and clinical administration protocols create higher barriers to substitution.
The Swedish Medical Products Agency enforces EU MDR-aligned device-drug combination standards, while the Dental and Pharmaceutical Benefits Agency TLV governs reimbursement thresholds that directly shape commercial launch sequencing. EMA centralized procedures streamline multi-national access but impose extended review timelines for novel biologics. Stakeholders must monitor TLV health economic assessments and MPA post-market surveillance intensification as determinants of portfolio prioritization and market entry timing.
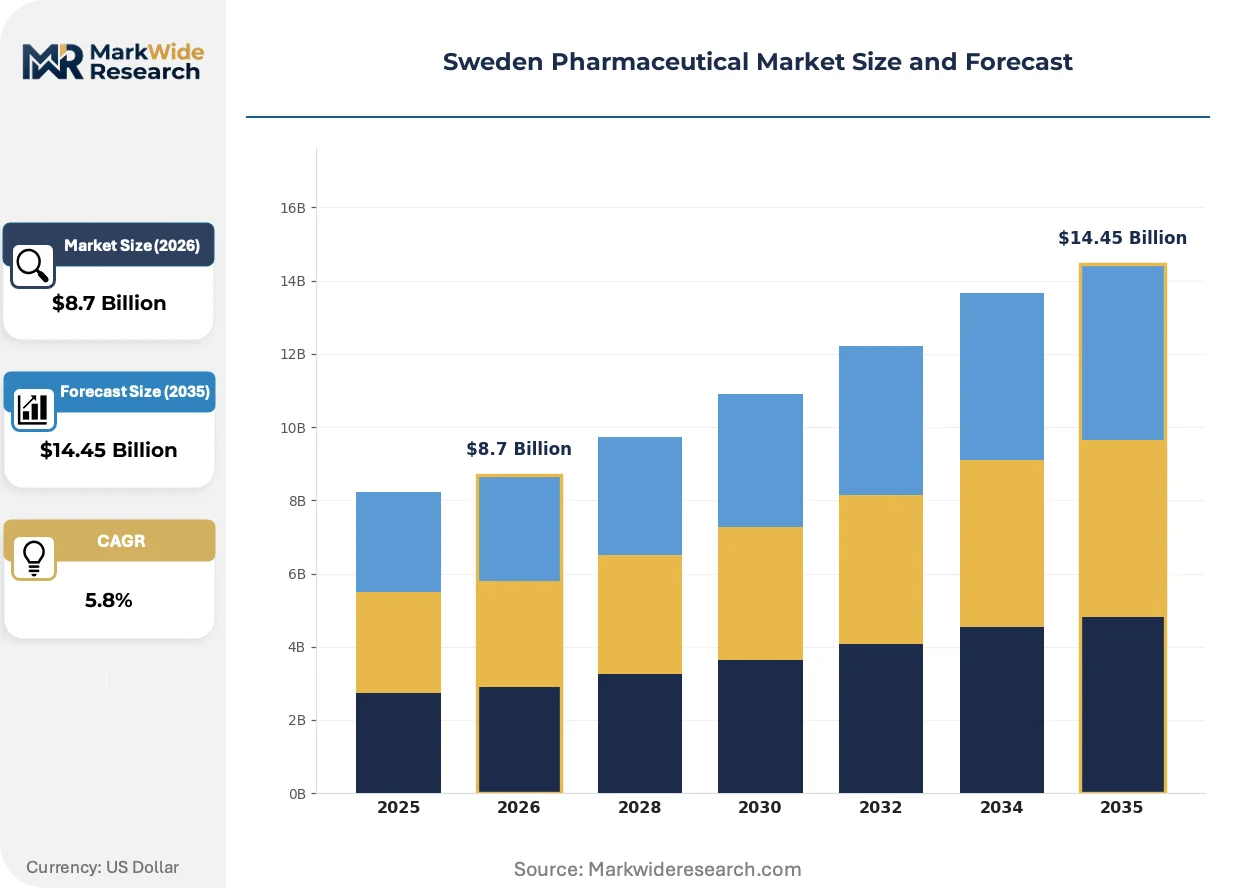
Market Dynamics
Hospital procurement consolidation around specialty biologics is compressing commercial timelines for novel therapies, while the Swedish Medical Products Agency's intensified pharmacovigilance protocols extend post-approval surveillance obligations.
Growth Catalysts
- EMA Centralized Procedures:Streamlined multi-national access accelerates launch sequencing for biologics developers targeting Nordic markets simultaneously.
- Stockholm Life Sciences Cluster:Clinical trial density and manufacturing co-location attract concentrated R&D investment from plasma fractionation specialists.
- Companion Diagnostics Integration:Diagnostic-pharmaceutical convergence creates premium positioning opportunities in hematology and immuno-oncology portfolios.
Market Restraints
- TLV Reimbursement Thresholds:The Dental and Pharmaceutical Benefits Agency's health economic assessments create extended commercial launch delays for high-cost therapies.
- Cold Chain Infrastructure Concentration:Injectable biologics dependency on specialized logistics limits distribution reach beyond Stockholm and Gothenburg corridors.
- EU MDR Device-Drug Alignment:Combination product standards impose dual compliance burdens that extend development timelines for novel delivery systems.
Strategic Opportunities
- Skåne Region Expansion:Underpenetrated southern Sweden markets present whitespace for rare disease therapy access programs.
- Plasma-Derived Portfolio Diversification:Specialized fractionation capabilities enable expansion into immunology and coagulation factor markets.
- Digital Therapeutic Adjacencies:Software-as-medical-device convergence with prescription therapies creates reimbursement pathway innovation potential.
Industry Challenges
- Pharmacovigilance Talent Scarcity:Post-market surveillance expertise gaps strain compliance teams facing intensified MPA reporting obligations.
- Biologics Manufacturing Capex Intensity:Single-use bioreactor investments and cleanroom expansion requirements constrain mid-cap participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Pharmaceutical Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Drugs, Over-the-Counter, Biologics, Generics Therapy Area: Oncology, Cardiovascular, Neurology, Infectious Diseases End User: Hospitals, Clinics, Retail Pharmacies, Long-term Care Facilities Delivery Mode: Oral, Injectable, Topical, Inhalation |
| Companies Covered | Roche, Swedish Orphan Biovitrum, AstraZeneca, Camurus, Orifarm Group, Pfizer, Novo Nordisk, BioArctic, Novartis, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Pharmaceutical Market Strategic Shifts
Continuous manufacturing platforms and real-world evidence integration are compressing traditional development-to-commercialization timelines across Swedish pharmaceutical operations.
Single-use bioreactor systems are displacing stainless-steel infrastructure in biologics production facilities. Contract manufacturers in Uppsala and Södertälje corridors are adopting these platforms at accelerated pace. This shift is displacing capital-intensive fixed-asset strategies while enabling rapid product changeover for multi-product facilities.
The EU Medical Device Regulation's device-drug combination standards impose stricter clinical evidence requirements on delivery system innovators. Swedish manufacturers must demonstrate biocompatibility and performance validation beyond prior directive thresholds. Pre-filled syringe and auto-injector categories face the most pronounced compliance timeline extensions.
Hospital pharmacy consolidation is compressing supplier negotiation cycles and standardizing formulary access protocols. Regional procurement alliances in Västra Götaland and Skåne are displacing individual hospital purchasing autonomy. This concentration is most visible in oncology and immunology biologics categories where volume commitments determine tiered access terms.
Sweden Pharmaceutical Market Segmentation
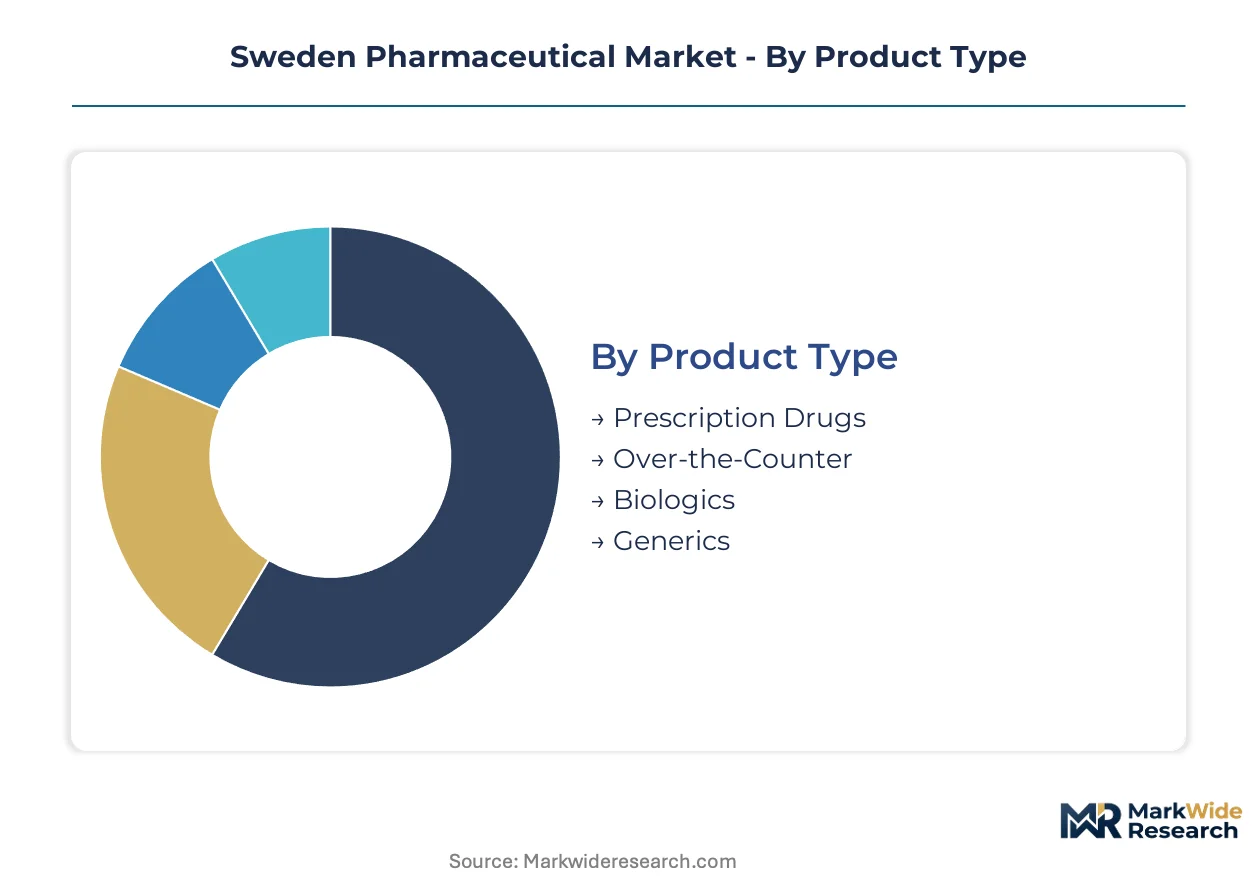
Swedish pharmaceutical distribution channels fragment sharply across product categories. Hospital procurement alliances concentrate biologics volume, while retail pharmacies handle prescription drug fulfillment. Understanding channel-segment alignment determines pricing power and access strategy.
Product Type:
Hospital pharmacy consolidation routes specialty biologics through centralized procurement, while retail channels dominate prescription fulfillment and over-the-counter transactions.
- Prescription Drugs:Patented small-molecule and biologic therapies requiring physician authorization and TLV reimbursement clearance. Stockholm's life sciences cluster concentrates R&D investment here, with hospital formulary committees gating commercial access.
- Biologics:Large-molecule therapies produced through recombinant DNA or hybridoma technologies, demanding cold chain logistics and specialized administration protocols. Injectable delivery modes concentrate margin pools in hospital and long-term care channels where clinical oversight creates substitution barriers.
- Over-the-Counter:Self-medication products available without prescription through retail pharmacy and grocery channels. Consumer health positioning emphasizes convenience access over clinical differentiation.
- Generics:Bioequivalent alternatives to off-patent originator compounds, competing on price and pharmacy substitution protocols. Volume share concentrates in cardiovascular and neurology portfolios as patent cliffs mature.
By volume, Generics leads. By growth pace, Biologics is climbing the fastest.
Therapy Area:
Cost tier stratification separates premium biologic oncology from commoditized cardiovascular generics, with reimbursement thresholds determining commercial viability across each tier.
- Oncology:Hematology and immuno-oncology biologics command premium positioning, supported by Sweden's concentrated research infrastructure and companion diagnostics integration. TLV health economic assessments create extended launch timelines for novel therapies.
- Cardiovascular:Mature therapeutic area with significant generic penetration following patent expirations on major statin and antihypertensive franchises. Volume concentration in primary care channels.
- Neurology:Specialty therapies addressing multiple sclerosis, epilepsy, and neurodegenerative conditions with growing biologic component. Regional procurement alliances standardize formulary access.
- Infectious Diseases:Antimicrobial and antiviral portfolios facing stewardship pressures and resistance surveillance requirements from the Swedish Medical Products Agency.
By revenue concentration, Oncology dominates. By access expansion potential, Neurology shows the steepest trajectory.
End User:
Customer type determines procurement autonomy, with consolidated hospital alliances displacing individual purchasing authority for high-value biologics.
- Hospitals:Tertiary care institutions administering complex biologics through centralized pharmacy operations. Västra Götaland and Skåne regional procurement alliances compress supplier negotiation cycles.
- Clinics:Outpatient specialty centers handling infusion therapies and chronic disease management with intermediate procurement flexibility.
- Retail Pharmacies:Community and chain dispensaries fulfilling prescription and over-the-counter demand with standardized substitution protocols.
- Long-term Care Facilities:Nursing homes and assisted living centers requiring simplified dosing regimens and adherence support programs.
By procurement volume, Hospitals lead. By channel expansion activity, Long-term Care Facilities are gaining share fastest.
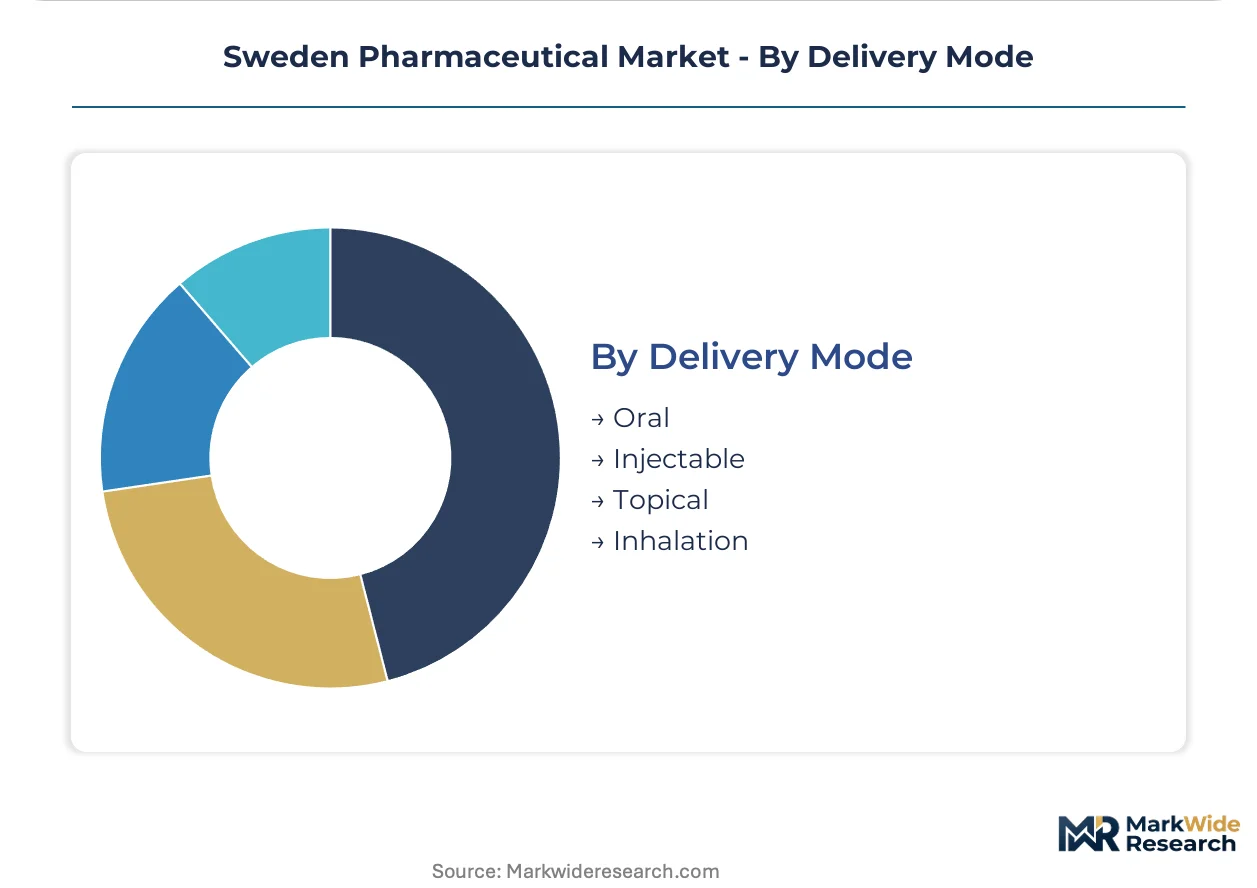
Delivery Mode:
Supply concentration in cold chain infrastructure limits distribution reach for temperature-sensitive formats beyond Stockholm and Gothenburg corridors.
- Injectable:Parenteral formulations including pre-filled syringes and auto-injectors facing EU MDR device-drug combination compliance extensions. Cold chain dependency restricts geographic coverage.
- Oral:Tablets and capsules dominating volume through retail pharmacy fulfillment with minimal logistics complexity and broad geographic reach.
- Topical:Transdermal and dermal preparations for localized therapy with manufacturing concentration in Uppsala contract manufacturing corridors.
- Inhalation:Pulmonary delivery systems requiring device-therapy integration and patient training protocols, concentrated in respiratory specialty centers.
By prescription volume, Oral formulations lead. By margin expansion, Injectable delivery is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sweden's national reimbursement framework and regional procurement consolidation create divergent market access conditions across its healthcare regions. The Dental and Pharmaceutical Benefits Agency's TLV health economic assessments apply uniformly, yet hospital pharmacy autonomy varies significantly by geography.
Stockholm Region
Karolinska University Hospital's procurement alliance dominates specialty biologics acquisition for hematology and immuno-oncology therapies. The Swedish Medical Products Agency maintains its headquarters here, intensifying pharmacovigilance oversight for manufacturers seeking early market entry. Stockholm's life sciences cluster concentrates clinical trial operations and plasma fractionation manufacturing in Solna and Huddinge corridors.
Västra Götaland
Sahlgrenska University Hospital anchors western Sweden's biologics consumption through regional formulary standardization. The county council's consolidated purchasing authority compresses supplier negotiation timelines for oncology and immunology portfolios. Gothenburg's proximity to Danish logistics hubs enables cold chain distribution efficiency for temperature-sensitive injectables.
Skåne Region
Underpenetrated rare disease therapy access creates whitespace for plasma-derived product expansion in southern Sweden. Skåne University Hospital's procurement flexibility exceeds Stockholm's centralized model, offering faster commercial pathway validation. Malmö's proximity to Copenhagen's pharmaceutical corridor attracts cross-border clinical trial participation.
Uppsala County
Contract manufacturing concentration around Uppsala Biomedical Centre supports single-use bioreactor adoption for multi-product facilities. The region's academic hospital procurement maintains independent formulary authority distinct from regional alliance structures. Uppsala University's clinical pharmacology unit generates real-world evidence supporting TLV reimbursement submissions.
Östergötland
Linköping University Hospital's regional procurement alliance standardizes neurology biologics access across southeastern Sweden. The county's intermediate population density tests distribution models for cold chain-dependent therapies beyond major urban corridors. Local pharmacy networks maintain stronger independent substitution protocols than consolidated metropolitan systems.
Sweden Pharmaceutical Market Competitive Environment
Listed leaders compete with private specialists across reimbursement negotiation capabilities and plasma fractionation infrastructure. The market structure concentrates around three archetypes: integrated biopharmaceutical conglomerates with diagnostic-pharmaceutical convergence, rare disease specialists with captive plasma supply, and mid-cap innovators with regional manufacturing anchoring. Consolidation pressures favor M&A activity targeting specialized fractionation capabilities, while capacity expansion concentrates in Uppsala and Södertälje corridors.
Among integrated biopharmaceutical conglomerates, Roche exemplifies diagnostic-therapy ecosystem positioning. Swedish Orphan Biovitrum occupies the rare disease specialist archetype with plasma-derived portfolio concentration. AstraZeneca represents the R&D-intensive multinational with Cambridge-Södertälje corridor leverage. These three anchors illustrate divergent strategic postures within Sweden's tightened regulatory and reimbursement environment.
| Leading Market Players |
|---|
| Roche |
| Swedish Orphan Biovitrum |
| AstraZeneca |
| Camurus |
| Orifarm Group |
| Pfizer |
| Novo Nordisk |
| BioArctic |
| Novartis |
| Others |
Value Chain & Pricing Dynamics
EU MDR device-drug combination standards gate both supplier qualification and price differentiation simultaneously, forcing delivery system innovators to absorb extended compliance costs that compress mid-tier margins while premium-certified formats sustain markup power.
Pricing Analysis
Certification level creates the primary spread between pre-filled syringe and auto-injector formats, with EU MDR-validated delivery systems commanding premium positioning against legacy device categories. TLV reimbursement thresholds stratify access across oncology biologics tiers, with hospital formulary committees exercising concentrated negotiation leverage on non-differentiated portfolios. Pricing pressure stems from regional procurement alliance consolidation in Västra Götaland and Skåne, where volume commitments extract deeper discounts from suppliers lacking companion diagnostic integration. Generic substitution protocols render retail pharmacy channels most price-sensitive, while hospital biologics procurement maintains lowest sensitivity due to clinical administration barriers.
Supply Chain Analysis
Just-in-time inventory strategies dominate single-use bioreactor operations in Uppsala and Södertälje corridors, with strategic plasma stockpiles anchoring Swedish Orphan Biovitrum's rare disease fractionation capabilities. Active pharmaceutical ingredient sourcing draws from India, China, and Switzerland, with recombinant protein production concentrated in Swedish manufacturing hubs. Cold chain logistics dependency on specialized temperature-controlled infrastructure creates single-source vulnerability for injectable biologics distribution. Distribution runs through regional hospital pharmacy alliances in Stockholm, Gothenburg, and Malmö, with retail pharmacy networks handling oral formulation fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face intensifying substitution pressure from biosimilar entrants targeting expiring biologic patents, requiring defensive portfolio restructuring to sustain margin pools.
For Market Incumbents: Consolidate companion diagnostic partnerships to lock in hematology and immuno-oncology formulary positioning against biosimilar erosion. Deepen backward integration into plasma fractionation capabilities to secure captive supply for rare disease portfolios. Prioritize TLV health economic assessment pre-submission engagement to compress reimbursement timeline risk. For New Entrants and Emerging Players: Lead with digital therapeutic adjacencies in Skåne Region long-term care facilities, where reimbursement pathway innovation potential exceeds Stockholm's saturated hospital procurement environment. Target neurology biologics access expansion in Östergötland, where regional procurement flexibility permits faster commercial pathway validation than consolidated metropolitan alliances. Deploy software-as-medical-device convergence with prescription therapies to differentiate beyond commodity formulation competition. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across single-use bioreactor manufacturing infrastructure, favoring asset-light contract development and manufacturing organization partnerships over greenfield facility investment. Five-to-ten year viability concentrates on plasma-derived portfolio diversification and diagnostic-therapy integration capabilities. Acquisition target archetype: mid-cap innovators with regional manufacturing anchoring in Uppsala or Södertälje corridors. Signal to watch: TLV reimbursement decision velocity on novel biologics as inflection indicator for commercial timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Roche's diagnostic-pharmaceutical convergence locks hematology formulary access against biosimilar substitution. |
| Plasma Fractionation Capacity Expansion | Swedish Orphan Biovitrum's specialized capabilities anchor rare disease portfolio defensibility. |
| EMA Centralized Procedure Optimization | Streamlined multi-national access accelerates Nordic launch sequencing for biologics developers. |
| Regional Procurement Alliance Engagement | Västra Götaland and Skåne consolidated purchasing authority compresses supplier negotiation timelines. |
| Real-World Evidence Generation | Uppsala University's clinical pharmacology unit supports TLV reimbursement submission validation. |
Study Parameters
The analysis maps prescription drugs, biologics, generics, and over-the-counter segments, each validated through formulary directors, hospital procurement managers, regulatory affairs leads, and payer access specialists. Primary interviews combined with secondary validation from EMA centralized procedure filings, TLV reimbursement decision databases, ClinicalTrials.gov records, and hospital procurement alliance contracts. Bottom-up product-level modeling triangulated against top-down regional healthcare expenditure benchmarks.
Consistency checks validated volume and value outputs against external regulatory filing trajectories and regional procurement volume disclosures across the projection horizon. Segmentation dimensions modeled include therapy area, delivery mode, end user channel, and regional regulatory cluster. CAGRs derived from patent expiry schedules, biosimilar entry timelines, and TLV reimbursement pathway velocity. Forecast inputs incorporated single-use bioreactor adoption rates and plasma fractionation capacity expansion plans.
Underlying assumptions cover EMA approval timeline stability and TLV health economic assessment methodology continuity, with deviation risk concentrated in pharmacovigilance reporting obligation intensification. Forecasts reflect documented assumptions on regional procurement alliance consolidation pace and cold chain infrastructure investment levels. Revision becomes warranted when biosimilar substitution rates or MPA post-market surveillance requirements cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Vitiligo Drugs Market
Pharmaceuticals
North America Pharmaceutical Warehousing Market
Pharmaceuticals
Rabeprazole Sodium Market
Pharmaceuticals
PAP and Paracetamol Market
Pharmaceuticals
Nasal Antihistamines Market
Pharmaceuticals
Anticancer Drugs Market
Pharmaceuticals
India Nicotine Replacement Therapy Market
Pharmaceuticals
Sporanox Market
Pharmaceuticals
Australia Pharmaceuticals Market
Pharmaceuticals
Pharmaceutical Pellets Market
Pharmaceuticals
SGLT2 Inhibitors Market
Pharmaceuticals
Articaine Hydrochloride Market
Pharmaceuticals
Pain Management Drugs Market
Pharmaceuticals
Nefopam Hydrochloride Injection Market
Pharmaceuticals
Pantoprazole Market
Pharmaceuticals
US Pharmaceutical Warehousing Market