
 Pharma PLM Market | 2026-2036
Pharma PLM Market Size, Share, and Industry Trends Forecast 2026-2036
Pharma PLM Market Outlook
The EU Green Deal's pharmaceutical sustainability reporting requirements is recalibrating how life sciences firms manage product lifecycle data across manufacturing and supply chains. Thermo Fisher Scientific leverages its instrument-to-software integration to anchor PLM workflows within laboratory environments. Dassault Systèmes BIOVIA differentiates through molecular modeling capabilities embedded in its platform architecture. SAP Life Sciences competes by extending ERP-native traceability into regulated pharmaceutical operations.
Pharma PLM encompasses software systems that manage product data, processes, and documentation across drug discovery, development, manufacturing, and commercialization, typically incorporating electronic signatures, audit trails, and version control to ensure data integrity in regulated environments. These platforms serve the primary purpose of maintaining compliance-ready records while accelerating time-to-market for therapeutics. Cloud-based deployments are capturing the fastest expansion as pharmaceutical companies prioritize scalable infrastructure for multi-site collaboration. Regulatory compliance applications command the deepest margin pools due to mandatory validation requirements and recurring audit demands. Oncology represents the most data-intensive product type segment, driving specialized PLM configurations for complex biologics tracking.
The FDA enforces 21 CFR Part 11 standards for electronic records, while the EMA's Annex 11 guidelines shape validation protocols for European submissions, and ISO 13485 quality management requirements extend into combination product lifecycle oversight. These frameworks collectively mandate audit trails, data integrity controls, and electronic signature capabilities that define core PLM procurement criteria. Stakeholders must evaluate platform architectures for their capacity to adapt to evolving pharmacovigilance data formats and emerging real-world evidence integration requirements.
Market Dynamics
The FDA's 21 CFR Part 11 electronic records mandate is compressing validation timelines and forcing pharmaceutical companies toward cloud-native PLM architectures that embed audit trails and electronic signatures by design.
Growth Catalysts
- EMA Annex 11 validation protocols:European drug developers must maintain audit-ready documentation systems, accelerating replacement of paper-based quality management with validated digital platforms.
- Biotech clinical trial complexity:Oncology and gene therapy pipelines generate massive structured and unstructured data volumes that exceed spreadsheet-based tracking capacities.
- Cloud infrastructure scalability:Multi-site pharmaceutical operations require real-time collaboration across distributed R&D and manufacturing facilities without on-premise hardware constraints.
Market Restraints
- Validation cost structure:FDA 21 CFR Part 11 compliance requires extensive IQ/OQ/PQ documentation and third-party audit fees that burden mid-cap drug developers with limited IT budgets.
- Technical debt in legacy ERP:Decades-old SAP and Oracle implementations resist API-based PLM integration without expensive middleware layers and custom code remediation.
- Substitution by point solutions:Specialized electronic trial master file systems and quality management software fragment procurement decisions away from integrated PLM suites.
Strategic Opportunities
- Real-world evidence integration:Post-market surveillance data streams from EHR systems and wearables create demand for PLM modules that bridge clinical and commercial lifecycle phases.
- EU Green Deal sustainability reporting:Pharmaceutical manufacturers must trace carbon footprint and circular economy metrics across supply chains, requiring new PLM data capture layers.
- AI-assisted regulatory writing:Natural language generation tools that auto-populate submission documents represent an emerging capability gap in current platform offerings.
Industry Challenges
- CSV talent scarcity:Computer system validation specialists with pharmaceutical domain expertise command premium salaries and extended recruitment cycles.
- Multi-system integration complexity:PLM platforms must synchronize with LIMS, ERP, and CTMS environments without creating data integrity vulnerabilities during migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharma PLM Market |
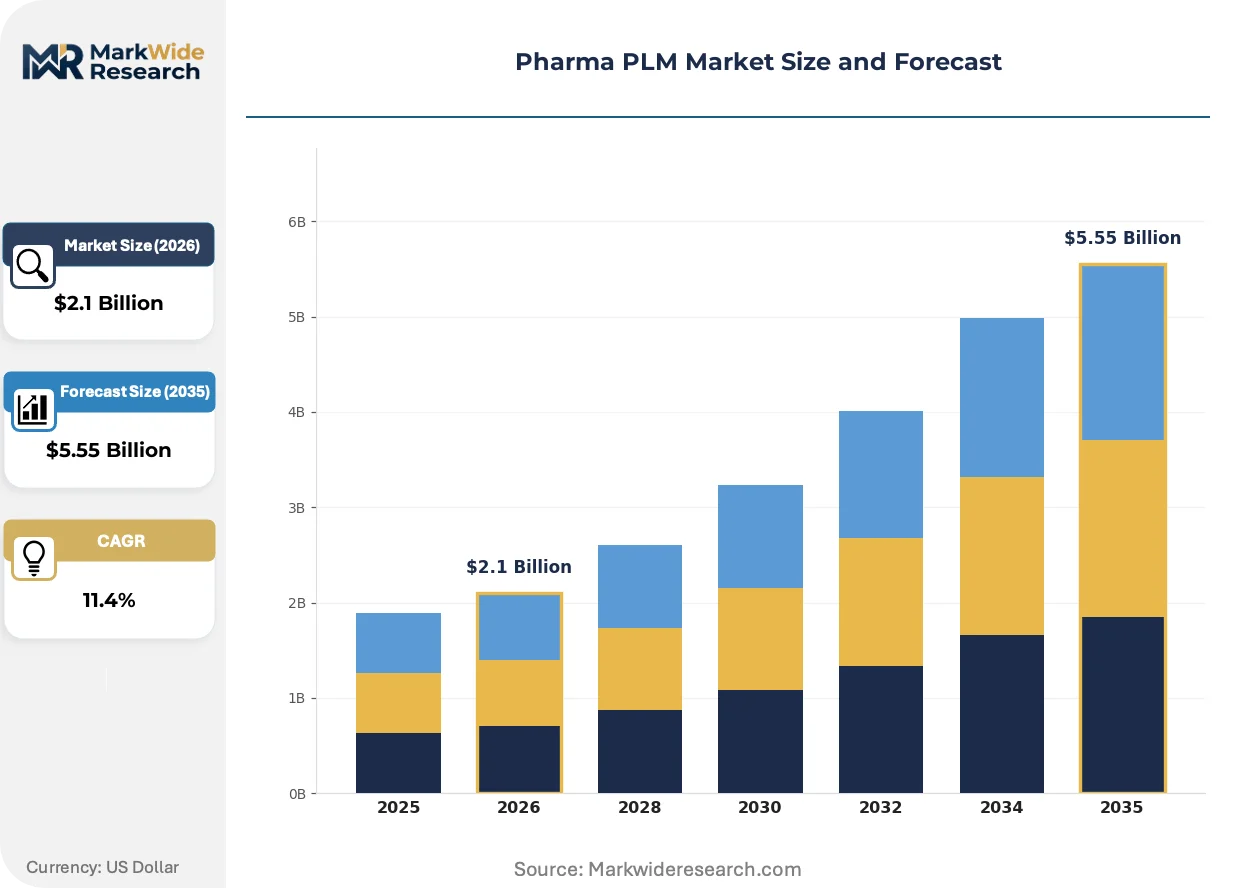
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oncology, Cardiovascular, Neurology, Infectious Diseases Application: Drug Development, Regulatory Compliance, Quality Management, Clinical Trials End User: Pharmaceutical Companies, Contract Research Organizations, Biotech Firms, Academic Institutions Technology: Cloud-Based, On-Premise, Mobile Solutions, Data Analytics |
| Companies Covered | Thermo Fisher Scientific, Medidata Solutions, Veeva Systems, Percepture, Oracle, SAP Life Sciences, IQVIA, Pyra Life Sciences, Dassault Systèmes BIOVIA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharma PLM Market Strategic Shifts
Artificial intelligence and sustainability mandates are rewiring how pharmaceutical firms architect product data systems, shifting competitive advantage toward platforms that automate compliance rather than merely document it.
Digital thread technology is unifying molecular design, clinical manufacturing, and commercial production data into continuous information flows. Large molecule developers in oncology and cell therapy adopt these architectures fastest due to batch complexity and CMO handoff frequency. This unification is compressing tech transfer timelines from months to weeks by eliminating manual data reconciliation between disconnected systems.
The EU AI Act's risk classification framework for medical software is forcing PLM vendors to embed algorithmic transparency and bias documentation into quality management modules. Drug developers deploying machine learning for formulation optimization must now maintain training data provenance and model version control as auditable records. European operations face the steepest compliance curve as notified bodies develop assessment protocols for AI-enabled manufacturing decisions.
Pharmaceutical procurement teams now demand outcome-based validation support rather than perpetual license models with separate professional services. Mid-cap biotechs negotiate contracts where vendors assume ongoing CSV documentation and audit response burdens. This shift concentrates most visibly in the United States, where venture-backed drug developers prioritize operational expenditure predictability over capital-heavy on-premise deployments.
Pharma PLM Market Segmentation
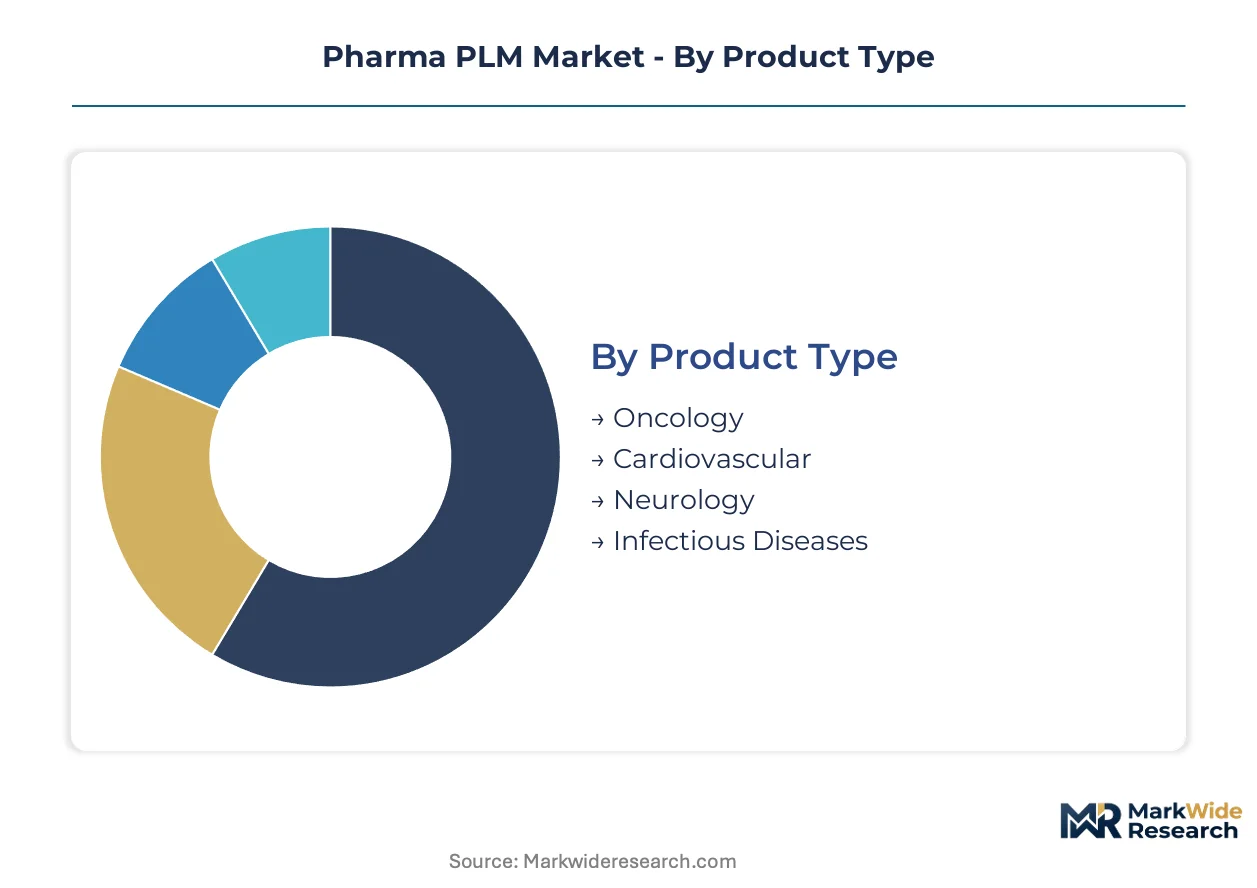
Pharma PLM procurement hinges on matching platform capabilities to the data intensity and regulatory exposure of specific therapeutic programs. Segmentation reveals where validation budgets concentrate and which technology architectures command premium positioning across the development lifecycle.
Product Type:
Oncology pipelines drive the most complex PLM configurations due to biologics manufacturing complexity and multi-site trial coordination.
- Oncology:Cell therapy and antibody-drug conjugate programs generate massive batch records, stability data, and CMO handoff documentation that overwhelm legacy tracking systems. Demand concentrates in Boston and San Diego biotech clusters where CAR-T developers manage distributed manufacturing networks.
- Cardiovascular:Large-scale outcomes trials spanning thousands of sites require PLM modules with robust investigator portal integration and adverse event workflow management. European sponsors face EMA Annex 11 documentation burdens for post-market cardiovascular safety surveillance.
- Neurology:Rare disease indications with limited patient populations prioritize patient registry integration and longitudinal data capture within PLM frameworks.
- Infectious Diseases:Pandemic response programs and antimicrobial development utilize accelerated validation pathways for rapid platform deployment.
Volume sits with Cardiovascular due to trial scale; growth tilts toward Oncology as biologics pipelines expand.
Application:
Regulatory compliance applications absorb the deepest implementation budgets due to mandatory validation and recurring audit demands.
- Regulatory Compliance:FDA 21 CFR Part 11 and EMA Annex 11 mandates force electronic signature, audit trail, and data integrity controls into core platform architecture. Submission-ready document compilation and health authority correspondence tracking command specialized module procurement.
- Drug Development:Formulation optimization, tech transfer, and CMC documentation workflows require PLM integration with LIMS and manufacturing execution systems. Multi-site R&D teams prioritize real-time collaboration tools for molecular design data sharing.
- Quality Management:Deviation tracking, CAPA management, and change control processes demand closed-loop integration with ERP quality modules.
- Clinical Trials:eTMF alignment, investigator site file management, and protocol amendment versioning compete with standalone CTMS solutions for procurement dollars.
Margin pools favor Regulatory Compliance; expansion accelerates fastest in Drug Development as biotechs compress timeline-to-IND.
End User:
Organizational scale and outsourcing intensity determine whether buyers prioritize integrated suites or specialized point solutions.
- Pharmaceutical Companies:Top-20 drug developers deploy enterprise PLM as backbone systems connecting discovery through commercial manufacturing, often layering specialized modules atop SAP or Oracle ERP foundations. Validation teams maintain internal CSV capabilities for continuous audit readiness.
- Biotech Firms:Venture-backed developers favor cloud-native platforms with subscription pricing and vendor-managed validation to preserve capital for clinical execution. Boston and South San Francisco clusters show highest adoption velocity.
- Contract Research Organizations:CROs serving multiple sponsors demand multi-tenant architectures with strict data segregation and sponsor-specific configuration management.
- Academic Institutions:University medical centers and research institutes prioritize grant compliance documentation and technology transfer to commercial partners over full GxP validation.
Deployment volume concentrates in Pharmaceutical Companies; Biotech Firms represent the steepest adoption trajectory as funding flows into oncology and gene therapy.
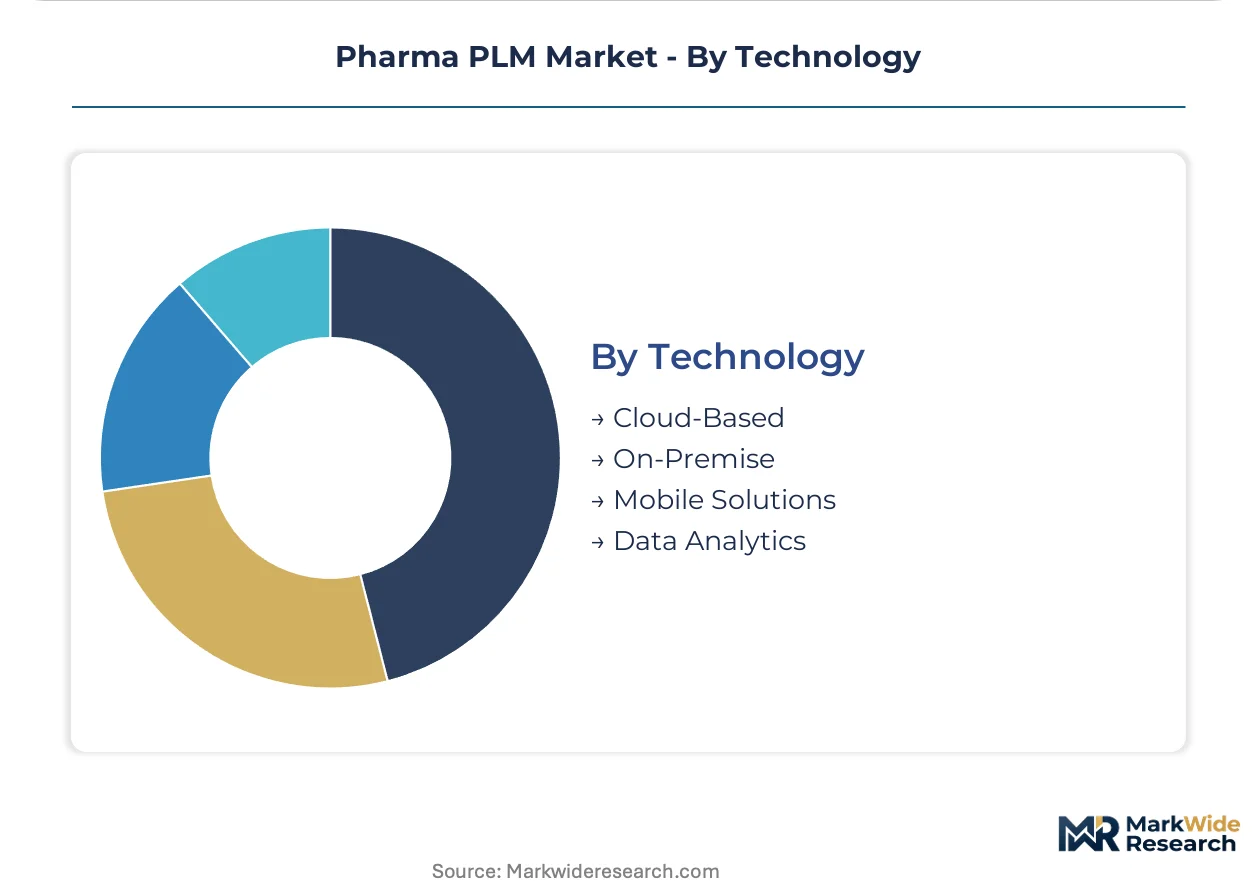
Technology:
Infrastructure decisions increasingly favor operational expenditure models over capital-intensive on-premise deployments.
- Cloud-Based:Multi-tenant SaaS architectures eliminate hardware maintenance burdens and enable rapid scaling for Phase III trial surges. FDA guidance on cloud validation has reduced procurement friction for regulated workloads.
- On-Premise:Data residency requirements and legacy ERP integration constraints sustain demand among top-tier pharmaceutical manufacturers with established data center operations.
- Mobile Solutions:Tablet-based electronic signatures and offline-capable field data capture support manufacturing floor and clinical site workflows.
- Data Analytics:Embedded visualization and predictive quality modules extend PLM value into process optimization and risk-based monitoring.
Installed base remains On-Premise; Cloud-Based platforms are climbing the fastest as mid-cap developers prioritize agility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors pharmaceutical PLM procurement activity through its concentration of CAR-T developers and gene therapy ventures managing distributed manufacturing networks across multiple continents.
United States
FDA 21 CFR Part 11 mandates compress validation timelines for electronic records and signatures, driving cloud-native platform adoption among venture-backed biotechs. The agency's guidance on computerized systems reduces procurement friction for regulated SaaS workloads. San Diego's oncology cluster shows particular intensity as antibody-drug conjugate developers coordinate multi-site CMO handoffs.
Germany
EMA Annex 11 protocols enforce audit-ready documentation standards that accelerate replacement of paper-based quality management systems. The EU AI Act's risk classification framework forces algorithmic transparency into manufacturing quality modules. Baden-Württemberg's pharmaceutical machinery corridor integrates instrument-to-software validation workflows for export-oriented drug manufacturers.
Switzerland
Swissmedic's stringent GxP inspection practices elevate platform validation requirements for combination product lifecycle oversight. ISO 13485 quality management standards extend into medical device-pharmaceutical convergence. Basel's pharmaceutical headquarters cluster demands enterprise-grade traceability spanning discovery through commercial manufacturing operations.
United Kingdom
MHRA post-Brexit regulatory divergence creates dual-track validation requirements for sponsors maintaining both FDA and UK market access. The country's pharmacovigilance data format evolution pressures PLM architectures toward adaptable submission document compilation. London's contract research organization density drives multi-tenant platform procurement with strict sponsor data segregation.
India
CDSCO's tightening data integrity enforcement for export-oriented generic manufacturers pushes validated digital system adoption. The country's PLI scheme for pharmaceuticals incentivizes technology upgrades across active pharmaceutical ingredient production. Hyderabad's vaccine and biologics manufacturing cluster shows accelerating cloud platform procurement for cost-efficient multi-site coordination.
Pharma PLM Market Competitive Environment
Premium-margin players sit above commodity-margin players across regulatory validation depth and molecular modeling specialization. The vendor base organizes into three tiers: enterprise ERP extenders, cloud-native life sciences specialists, and instrument-integrated platform providers. Consolidation pressure intensifies as mid-cap biotechs demand vendor-managed computer system validation rather than perpetual licenses. Strategic moves concentrate on API-based ERP integration partnerships and AI-assisted regulatory writing module development.
Within the instrument-integrated tier, Thermo Fisher Scientific exemplifies hardware-to-software workflow anchoring. Among cloud-native specialists, Veeva Systems and Dassault Systèmes BIOVIA occupy positions representing SaaS agility versus molecular modeling depth. These three entities illustrate how competitive positioning fragments across validation burden assumption, scientific data management, and manufacturing execution connectivity.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Medidata Solutions |
| Veeva Systems |
| Percepture |
| Oracle |
| SAP Life Sciences |
| IQVIA |
| Pyra Life Sciences |
| Dassault Systèmes BIOVIA |
| Others |
Value Chain & Pricing Dynamics
Computer system validation labor costs cascade through Pharma PLM pricing tiers, with premium vendor-managed CSV packages commanding three-to-five-fold multiples over self-validated SaaS subscriptions as biotech procurement teams trade capital for compliance certainty.
Pricing Analysis
Outcome-based pricing anchored to audit-readiness guarantees now dominates enterprise procurement, separating vendors assuming recurring CSV documentation burdens from those transferring validation risk to buyers. Price differentiation hinges on FDA 21 CFR Part 11 pre-validation depth and EMA Annex 11 protocol completeness, with European submissions demanding premium tiers. Pricing pressure stems from mid-cap biotechs negotiating vendor-managed validation into subscription fees rather than perpetual licenses. Venture-backed developers in Boston and San Francisco show highest price sensitivity, while top-20 pharmaceutical manufacturers prioritize audit-defensibility over cost.
Supply Chain Analysis
CSV specialist scarcity in Hyderabad and Bangalore constrains implementation capacity for export-oriented generic manufacturers adopting validated digital systems. Platform development concentrates in the United States, Germany, and Switzerland, with cloud infrastructure provisioning resting on hyperscaler data centers in Ireland, Singapore, and Virginia. Supply chain risk centers on single-source vulnerability for specialized regulatory compliance modules integrating with legacy ERP systems. Distribution runs through direct enterprise sales teams supplemented by systems integration partners possessing pharmaceutical domain expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharma PLM is consolidating around vendors capable of absorbing validation burdens, with FDA enforcement timelines forcing mid-tier players toward acquisition or exit.
For Market Incumbents: Hedge against point-solution fragmentation by embedding AI-assisted regulatory writing modules directly into core platform architecture. Deepen backward integration into instrument-to-software validation workflows through partnerships with laboratory equipment manufacturers. Defensive moves must address Thermo Fisher Scientific's hardware-anchored positioning and Veeva Systems' cloud-native agility in biotech procurement cycles. For New Entrants and Emerging Players: Cloud-native eTMF alignment tools represent the most penetrable white-space, as antibody-drug conjugate developers seek modular alternatives to integrated suites. Target academic medical centers prioritizing grant compliance documentation over full GxP validation, then bridge toward commercial technology transfer partnerships. Go-to-market positioning should emphasize rapid deployment timelines measured in weeks rather than quarters. For Investors and Strategic Acquirers: Distressed-cycle entries favor cloud-native specialists with established FDA pre-validation packages in the United States and Germany, where EMA Annex 11 complexity sustains premium pricing. Long-term viability requires vendor-managed CSV capabilities becoming standard rather than differentiated. Watch CDSCO enforcement intensity in India as inflection indicator for export-oriented generic manufacturer upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Regulatory Writing Module | Natural language generation for FDA submission documents addresses capability gaps in current platform offerings. |
| Vendor-Managed CSV Partnership | Outcome-based validation support shifts audit response burdens from biotech IT teams to platform providers. |
| Instrument-to-Software Integration | Thermo Fisher Scientific's laboratory hardware anchoring creates defensive moats against pure-play SaaS entrants. |
| Multi-Tenant CRO Architecture | Strict sponsor data segregation capabilities capture procurement from London's contract research organization density. |
| EU Green Deal Compliance Layer | Carbon footprint traceability modules address emerging pharmaceutical sustainability reporting requirements. |
Study Parameters
Multi-period observation of FDA 483 warning letter trends and EMA inspection deficiency patterns anchored the trend analysis, supplemented by interviews with regulatory affairs leads, CSV specialists, biotech CIOs, and CRO quality directors. Secondary validation drew from FDA Form 483 databases, EMA GMP inspection reports, ClinicalTrials.gov protocol amendments, and SAP Oracle ERP life sciences extension documentation. Bottom-up triangulation across vendor revenue disclosures and top-down cross-check against pharmaceutical IT spending surveys ensured analytical consistency.
Input-output matrices mapped deployment model, organization scale, therapeutic area data intensity, and regional regulatory cluster against platform adoption velocities across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with aggregate market expansion. Forecast inputs incorporated cloud infrastructure cost curves, FDA guidance evolution on computerized systems, and biotech venture funding flow patterns by therapeutic area.
The model holds under stable FDA 21 CFR Part 11 enforcement intensity and continued EMA Annex 11 protocol stability; deviation in CDSCO data integrity crackdown severity or EU AI Act implementation timelines would shift generic manufacturer and European AI-enabled manufacturing adoption trajectories respectively. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Calcium Channel Blocker Market
Pharmaceuticals
Antiepilepsy Drugs Market
Pharmaceuticals
Netherlands Pharmaceutical Market
Pharmaceuticals
Emergency Contraceptive Pills Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market
Pharmaceuticals
Inhaled Nitric Oxide Market
Pharmaceuticals
Anticholinergic Drugs Market
Pharmaceuticals
Propafenone Hcl Extended Release Capsules Market
Pharmaceuticals
Global Recombinant Vaccines Market
Pharmaceuticals
Global Immunomodulators Market
Pharmaceuticals
Liver Fibrosis Drugs Market
Pharmaceuticals
Peptide-Based Cancer Therapeutics Market
Pharmaceuticals
Sweden Pharmaceutical Market
Pharmaceuticals
Peptic Ulcer Drugs Market
Pharmaceuticals
Influenza Antiviral Market
Pharmaceuticals
Antidepressants Market