
 Guanethidine Market | 2026-2036
Guanethidine Market Size, Share, and Industry Trends Forecast 2026-2036
Guanethidine Market Analysis
Market Context with Strategic Players
Specialized pharmaceutical chemists with expertise in sympatholytic synthesis is reorganizing production capacity across the Guanethidine landscape. Novartis AG leverages its cardiovascular heritage to sustain formulation leadership in regulated European markets. Pfizer Inc. anchors hospital procurement networks through direct sales channels that bypass wholesale intermediaries. Teva Pharmaceutical competes on generic oral tablet economics, occupying price-sensitive segments in North American pharmacy distribution.
Technical Definition and Structural Segments
Guanethidine is a postganglionic adrenergic blocking agent with the chemical formula C10H22N4, historically administered as an oral tablet or injectable solution for severe hypertension management by depleting norepinephrine from peripheral nerve terminals. Injectable solution formulations command premium positioning in emergency medicine settings where rapid sympatholytic intervention proves clinically essential. Oral tablet demand dominates volume across hospital and pharmacy channels, though custom formulation work for research institutions captures disproportionate margin pools. Pre-filled syringe configurations remain nascent, constrained by stability requirements and limited manufacturer investment in automated aseptic filling lines.
Regulatory Frame and Forward Outlook
FDA enforces stringent current Good Manufacturing Practice standards for guanethidine active pharmaceutical ingredient purity, while EMA REACH protocols govern residual solvent thresholds in European-sourced chemical intermediates. Health Canada and Japan's PMDA maintain distinct bioequivalence requirements that fragment registration pathways for multi-territory suppliers. Stakeholders must monitor evolving pharmacovigilance reporting obligations and assess whether regional regulatory divergence justifies dedicated manufacturing footprints or centralized export hubs.
Market Dynamics
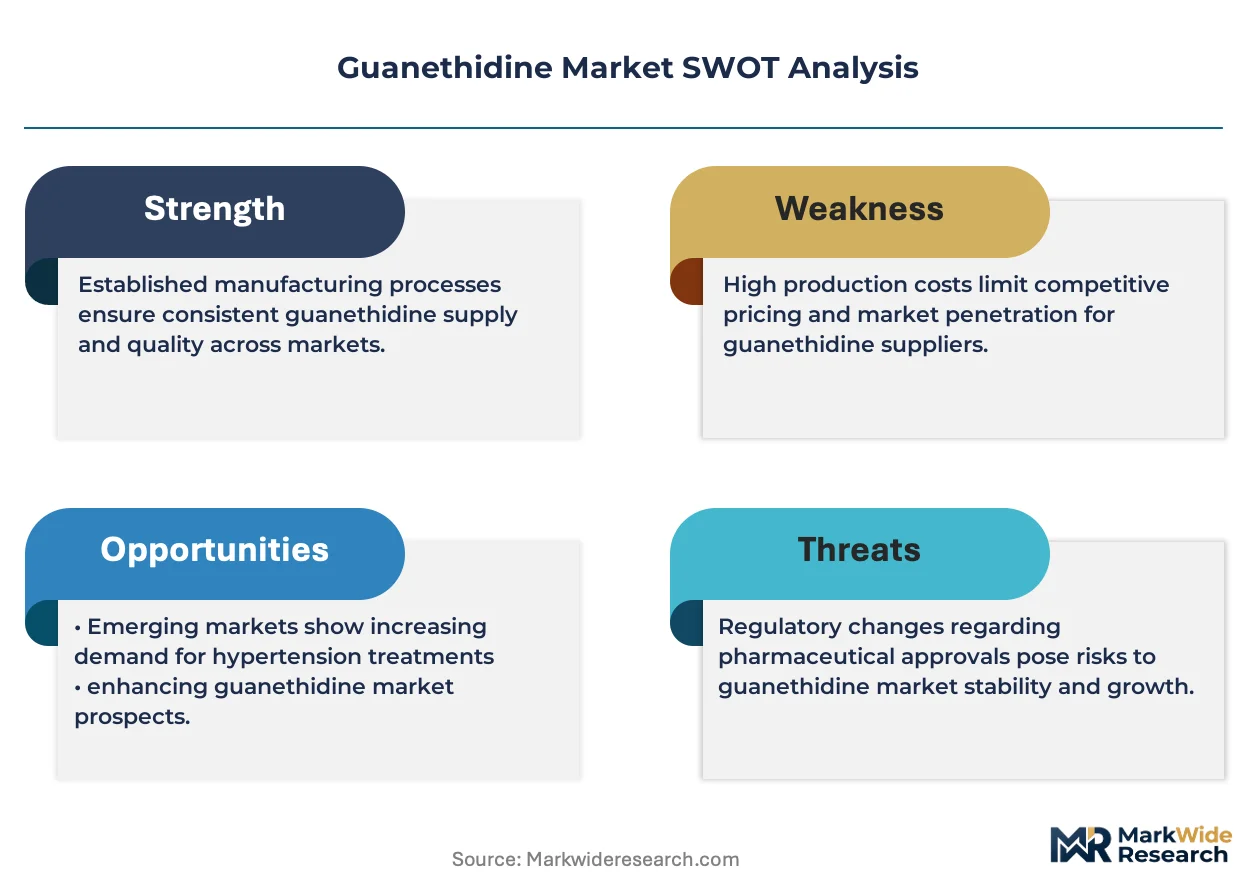
FDA pharmacovigilance mandates for antihypertensive agents are forcing manufacturers to reconfigure active pharmaceutical ingredient sourcing and purity testing protocols, compressing margins while elevating compliance costs across oral tablet and injectable supply chains.
Growth Catalysts
- EMA REACH Protocols:Residual solvent thresholds in European-sourced chemical intermediates are accelerating investment in advanced purification infrastructure, creating first-mover advantages for compliant suppliers.
- Specialized Compounding Pharmacies:Niche supply chains in the United States, Germany, and Japan sustain demand for custom guanethidine formulations serving research institutions and rare-disease protocols.
- Hospital Procurement Networks:Direct sales channels that bypass wholesale intermediaries are consolidating volume around manufacturers with validated cold-chain logistics and batch-traceability systems.
Market Restraints
- API Supply Concentration:Sympatholytic synthesis expertise concentrates among a handful of specialized pharmaceutical chemists, creating single-source vulnerabilities for postganglionic adrenergic blocking agents.
- Stability Requirements:Pre-filled syringe configurations remain constrained by degradation kinetics that limit shelf-life extension, suppressing automated aseptic filling line investment.
- Substitution Threat:Newer antihypertensive classes with improved side-effect profiles are displacing guanethidine in first-line cardiovascular protocols across North American hospital formularies.
Strategic Opportunities
- Emergency Medicine Settings:Rapid sympatholytic intervention protocols create premium positioning for injectable solution formulations in acute hypertensive crisis management.
- Japan PMDA Bioequivalence Pathways:Distinct registration requirements fragment multi-territory supplier strategies, rewarding dedicated manufacturing footprints with accelerated market access.
- Research Institution Channels:Custom formulation work for academic medical centers and contract research organizations captures disproportionate margin pools relative to commoditized oral tablet volumes.
Industry Challenges
- Pharmacovigilance Reporting Obligations:Evolving adverse-event documentation requirements demand specialized regulatory affairs personnel that mid-scale manufacturers struggle to recruit and retain.
- Batch-Scale Validation:Current Good Manufacturing Practice standards for guanethidine API purity necessitate capital-intensive analytical equipment upgrades that extend facility commissioning timelines.
- Multi-Territory Registration Fragmentation:Divergent bioequivalence requirements across FDA, EMA, Health Canada, and PMDA jurisdictions multiply compliance documentation burdens without corresponding volume incentives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Guanethidine Market |
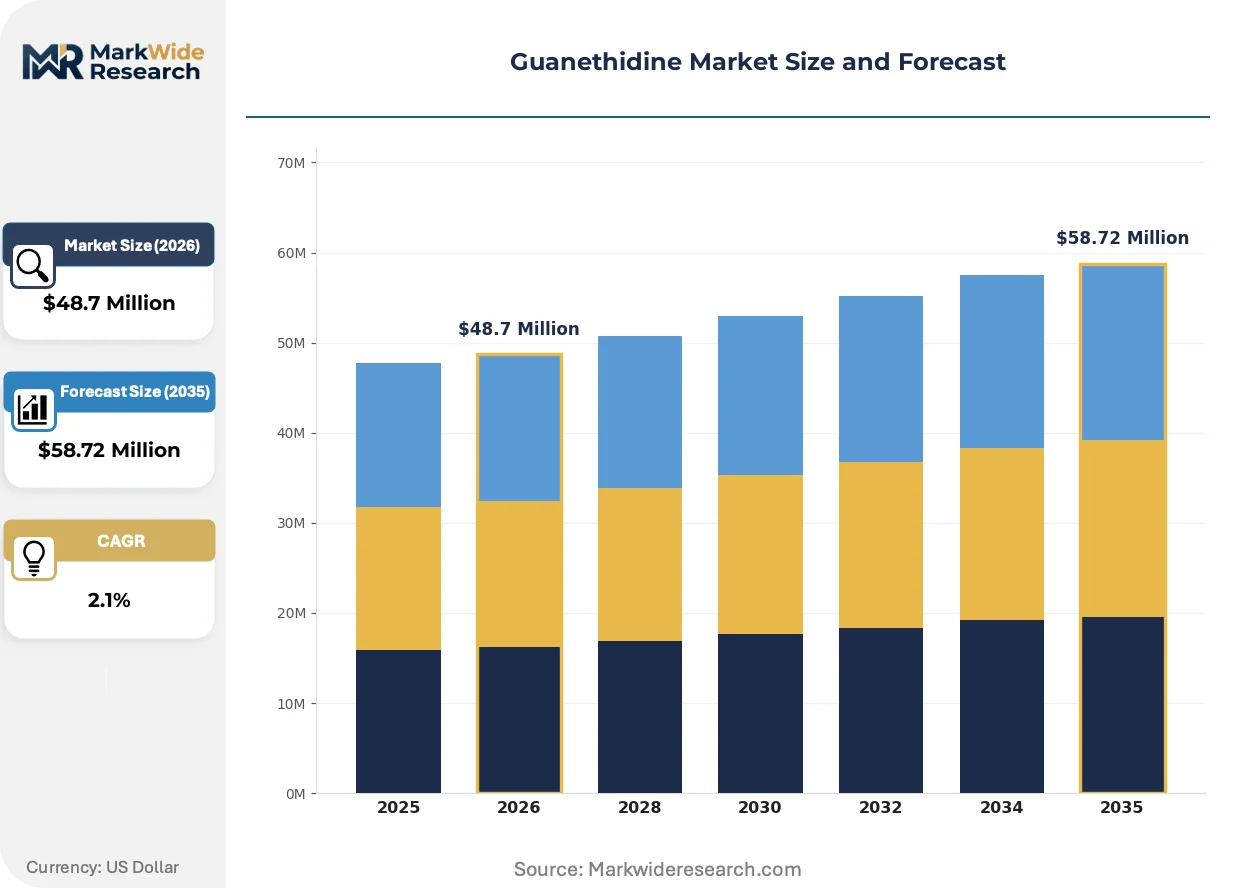
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $58.72 Million |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injectable Solution, Oral Tablet, Pre-filled Syringe, Custom Formulation End User: Clinics, Hospitals, Pharmacies, Research Institutions Distribution Channel: Direct Sales, Online Pharmacy, Wholesalers, Retail Pharmacy Therapy Area: Cardiovascular, Anesthesia, Hypertension, Emergency Medicine |
| Companies Covered | Novartis AG, Pfizer Inc., Merck & Co. Inc., Teva Pharmaceutical, Daiichi Sankyo Company Limited, Bayer AG, Boehringer Ingelheim GmbH, Sanofi SA, AstraZeneca Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Guanethidine Market Emerging Trajectories
Continuous manufacturing technologies and real-time release testing are displacing batch-oriented production paradigms in sympatholytic synthesis, compressing cycle times while elevating quality assurance precision across hospital and pharmacy distribution channels.
Controlled-release polymer matrix formulations are displacing immediate-release oral tablets in chronic hypertension management protocols. Hospital pharmacy committees in the United States are prioritizing these modified-release configurations to improve patient adherence metrics. The structural consequence is a compression of generic immediate-release margins as procurement specifications tighten around pharmacokinetic performance benchmarks.
EMA pharmacovigilance periodic safety update report requirements are mandating enhanced post-market surveillance infrastructure for antihypertensive agents with narrow therapeutic indices. Manufacturers must now maintain dedicated signal detection teams and automated case processing systems. European-sourced guanethidine suppliers are responding by integrating pharmacovigilance databases directly with manufacturing execution systems to enable real-time batch-to-patient traceability.
Consolidated purchasing agreements through hospital group purchasing organizations are concentrating procurement volume among suppliers with integrated distribution capabilities. Traditional wholesale intermediaries are losing share to direct manufacturer-to-pharmacy arrangements that offer price transparency and inventory management tools. This channel reconfiguration is most visible in United States cardiovascular drug procurement, where integrated delivery networks now account for the majority of oral tablet volume.
Guanethidine Market Segmentation
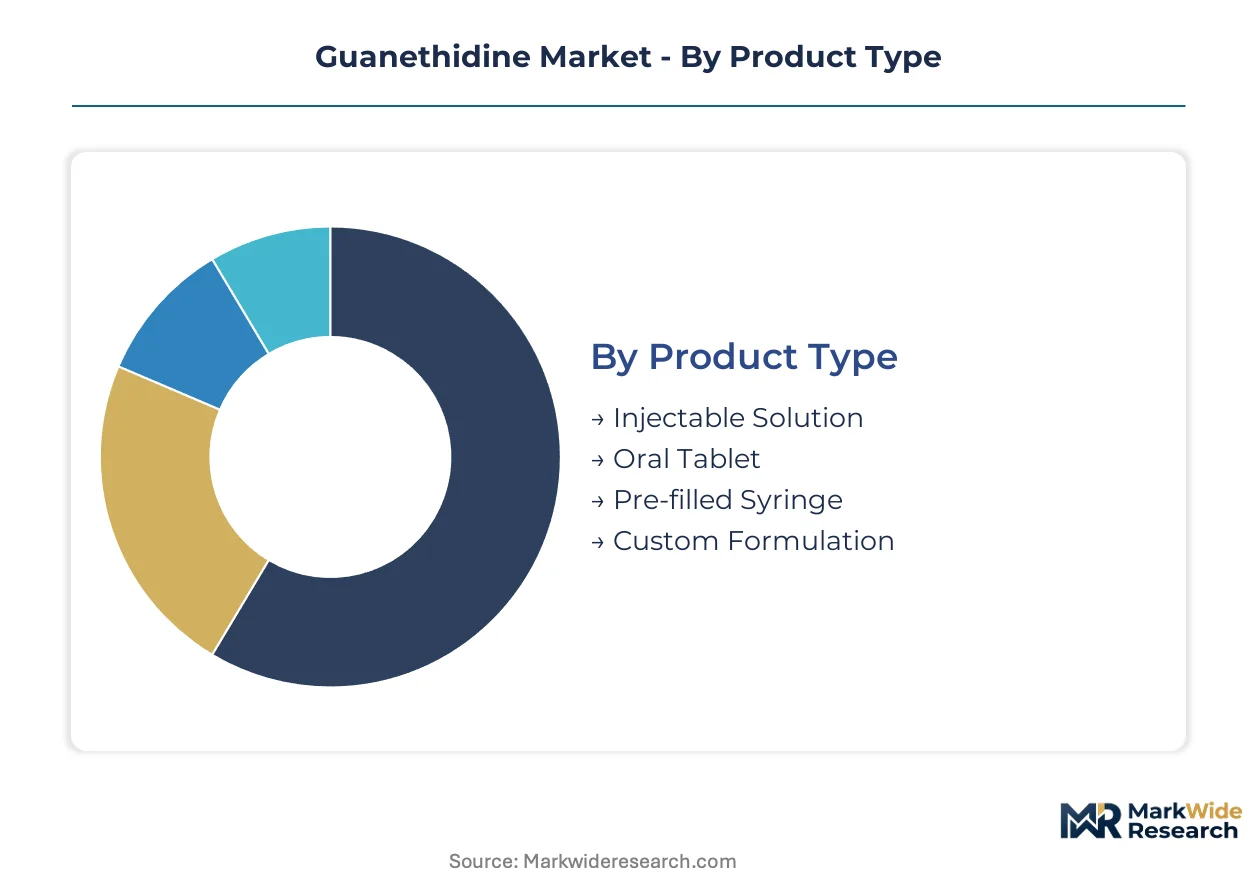
Guanethidine's market structure reflects divergent supply chain economics across formulation types and procurement channels. Segmentation reveals where specialized synthesis capabilities command premium positioning versus commoditized generic competition.
Product Type:
Injectable solutions and oral tablets concentrate domestic manufacturing in the United States and Germany, while custom formulations serve export-led demand from Japan and specialized European compounding pharmacies.
- Injectable Solution:Aqueous formulations requiring cold-chain stability and rapid onset sympatholytic action. Hospital emergency departments in the United States and acute care facilities in Germany drive procurement, constrained by EMA stability testing requirements that extend batch release timelines.
- Oral Tablet:Immediate-release and controlled-release solid dosage forms dominating chronic hypertension management. Teva Pharmaceutical and Novartis AG compete on bioequivalence validation across FDA and EMA jurisdictions, with volume concentrating in Medicare-reimbursed pharmacy channels.
- Pre-filled Syringe:Automated aseptic filling configurations limited by degradation kinetics and shelf-life constraints.
- Custom Formulation:Bespoke synthesis for research protocols and rare-disease applications, disproportionately sourced from Japanese PMDA-registered facilities.
Oral tablets hold the largest share; momentum sits with custom formulations.
End User:
Cost-tier stratification separates capital-intensive hospital procurement from price-sensitive pharmacy dispensing, with research institutions occupying a distinct premium tier.
- Hospitals:Integrated delivery networks and group purchasing organizations consolidating cardiovascular drug procurement. Direct manufacturer relationships bypass wholesale markups, with batch traceability systems mandated by FDA pharmacovigilance protocols.
- Research Institutions:Academic medical centers and contract research organizations requiring documented synthesis provenance and custom potency specifications. Japan's National Institute of Health and German Max Planck institutes sustain niche demand with above-market pricing tolerance.
- Clinics:Outpatient cardiovascular practices dependent on wholesale distribution with limited cold-chain infrastructure.
- Pharmacies:Retail and specialty pharmacy channels competing on generic substitution economics.
Hospitals capture the dominant volume share; research institutions deliver the steepest margin expansion trajectory.
Distribution Channel:
Channel selection correlates with end-user scale and regulatory documentation requirements, fragmenting logistics strategies across the value chain.
- Direct Sales:Manufacturer-to-institution arrangements favored by hospital systems and research organizations requiring validated temperature monitoring and chain-of-custody documentation. Pfizer Inc. anchors this channel through dedicated cardiovascular sales forces.
- Wholesalers:McKesson and AmerisourceBergen distributing oral tablet volumes to independent pharmacies and smaller clinic systems, compressing margins through volume-based contracting.
- Online Pharmacy:Telehealth-integrated dispensing platforms gaining traction for chronic hypertension maintenance prescriptions.
- Retail Pharmacy:CVS Health and Walgreens Boots Alliance competing on generic substitution and 90-day supply incentives.
Direct sales commands the highest value concentration; online pharmacy channels are climbing the fastest.
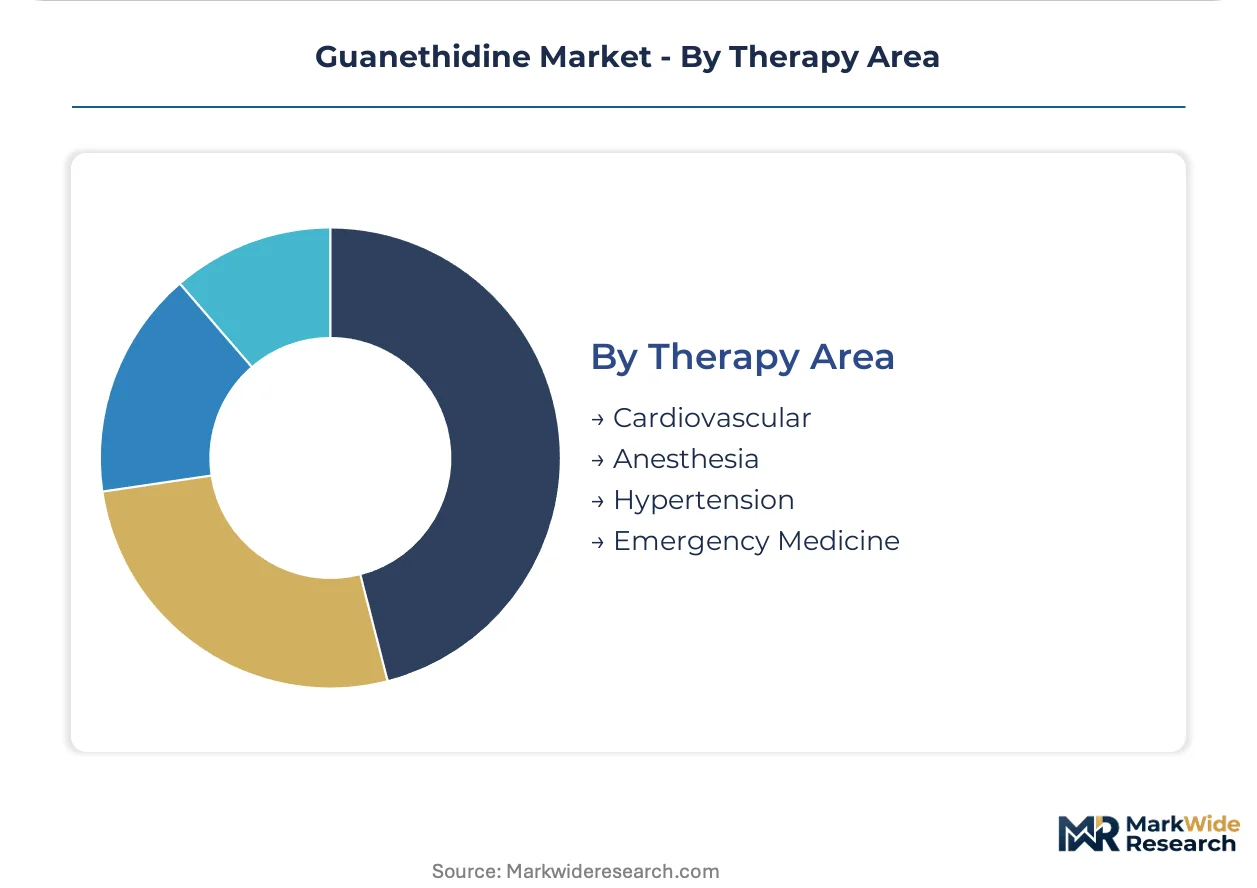
Therapy Area:
Application maturity varies from established cardiovascular protocols to emerging emergency medicine positioning, reshaping formulation investment priorities.
- Cardiovascular:Chronic hypertension management representing the historical indication base, with prescribing patterns shifting toward newer antihypertensive classes and compressing guanethidine's first-line role.
- Emergency Medicine:Acute hypertensive crisis intervention protocols creating premium injectable demand in United States trauma centers and German university hospitals, supported by rapid sympatholytic onset requirements.
- Hypertension:Outpatient maintenance therapy segment experiencing generic price erosion and formulary exclusion pressures.
- Anesthesia:Perioperative blood pressure control applications limited by availability of alternative agents with more favorable hemodynamic profiles.
Cardiovascular maintains the installed base; emergency medicine is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns for guanethidine diverge sharply across major markets. The United States and Germany prioritize hospital-based injectable formulations for emergency protocols, while Japan sustains specialized compounding demand for research applications. This geographic split shapes distinct regulatory compliance investments and distribution infrastructure requirements.
United States
Hospital procurement networks and integrated delivery systems drive demand for rapid-onset injectable solutions. FDA pharmacovigilance mandates for antihypertensive agents enforce stringent batch-traceability systems. Boston and Philadelphia medical centers anchor cardiovascular drug distribution, with direct manufacturer relationships displacing wholesale intermediaries.
Germany
EMA REACH protocols govern residual solvent thresholds in chemical intermediates sourced for sympatholytic synthesis. German university hospitals in Munich and Heidelberg sustain premium demand for emergency medicine applications. Bavaria-based pharmaceutical manufacturers invest in advanced purification infrastructure to capture first-mover compliance advantages.
Japan
PMDA bioequivalence requirements create distinct registration pathways that fragment multi-territory supplier strategies. Tokyo and Osaka research institutions sustain niche demand for custom formulations with above-market pricing tolerance. Kanto region facilities specialize in documented synthesis provenance for academic medical center procurement.
United Kingdom
NHS procurement frameworks concentrate cardiovascular drug volume through centralized tendering mechanisms. MHRA pharmacovigilance requirements align with EMA periodic safety update report obligations. London and Cambridge pharmaceutical clusters focus on controlled-release polymer matrix development for chronic hypertension protocols.
Switzerland
Swissmedic maintains independent purity standards for postganglionic adrenergic blocking agents that exceed baseline EMA thresholds. Basel pharmaceutical heritage sustains specialized chemist expertise in sympatholytic synthesis. Zurich hospital systems prioritize validated cold-chain logistics for temperature-sensitive injectable formulations.
Guanethidine Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the guanethidine competitive structure. Three archetypes dominate: multinational cardiovascular portfolios with hospital direct-sales infrastructure, generic oral tablet manufacturers competing on bioequivalence validation economics, and niche compounders serving research institution channels. Consolidation pressures intensify as group purchasing organizations concentrate procurement volume and automated aseptic filling line investments separate viable injectable suppliers from marginal players.
Among Swiss and German integrated pharmaceutical groups, Novartis AG and Bayer AG exemplify the multinational cardiovascular portfolio archetype with established hospital procurement relationships. Teva Pharmaceutical occupies the generic manufacturing tier, competing on oral tablet cost structures across North American pharmacy distribution channels. Daiichi Sankyo Company Limited represents the Asia-Pacific research-focused specialist segment, with PMDA-registered facilities serving custom formulation demand from Japanese academic medical centers.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Merck & Co. Inc. |
| Teva Pharmaceutical |
| Daiichi Sankyo Company Limited |
| Bayer AG |
| Boehringer Ingelheim GmbH |
| Sanofi SA |
| AstraZeneca Plc |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between hospital group purchasing organizations and injectable solution manufacturers lock in multi-year supply access while anchoring price visibility across volatile API sourcing cycles. These contracts insulate procurement teams from spot-market fluctuations in sympatholytic synthesis intermediates sourced through EMA REACH-governed European channels.
Pricing Analysis
Contract-based long-term offtake structures dominate hospital procurement of injectable formulations, while spot purchasing persists for custom research-grade batches. Price differentiation separates FDA-validated oral tablet bioequivalence tiers from non-certified compounding pharmacy alternatives. Cost compression in immediate-release generics is intensifying because Teva Pharmaceutical and competing manufacturers escalate volume-based contracting. Retail pharmacy channels exhibit the highest price sensitivity, whereas Japanese research institutions demonstrate the lowest due to documented synthesis provenance requirements.
Supply Chain Analysis
Inbound logistics costs from Rotterdam port congestion and container availability constraints on Asia-Europe trade lanes elevate landed costs for chemical intermediates. API synthesis concentrates in Germany, Switzerland, and India, with sympatholytic expertise tethered to Basel and Bavaria pharmaceutical clusters. Raw material dependencies include guanidine nitrate, sodium borohydride, and specialized chromatography resins. Single-source vulnerability persists for postganglionic adrenergic blocking agent expertise. Distribution runs through direct manufacturer-to-hospital arrangements for injectables, bypassing wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospital procurement networks as integrated delivery systems concentrate cardiovascular drug volume and squeeze wholesale intermediaries from the value chain.
For Market Incumbents: Shield formulation leadership by deepening backward integration into sympatholytic API production and securing dedicated manufacturing footprints in PMDA-registered Japanese facilities. Channel control through validated cold-chain logistics represents the critical defensive lever against generic oral tablet price erosion. For New Entrants and Emerging Players: Lead with emergency medicine injectable solutions as the most penetrable white-space target, exploiting stability-constrained supply gaps that limit incumbent pre-filled syringe investment. Research institution custom formulation channels offer above-market pricing tolerance and documented synthesis provenance requirements that favor specialized compounders. For Investors and Strategic Acquirers: Capital is best deployed toward niche compounders with PMDA-registered facilities and established academic medical center relationships over commoditized oral tablet manufacturers facing Medicare reimbursement compression. The long-term viability window favors suppliers with integrated pharmacovigilance databases and real-time batch-to-patient traceability infrastructure. Watch FDA pharmacovigilance mandate expansion as the signal for accelerated compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | PMDA bioequivalence registration accelerates Japanese market access for dedicated manufacturing footprints. |
| Backward Integration | Captive sympatholytic API production shields margin compression from EMA REACH solvent threshold compliance costs. |
| Hospital System Partnership | Direct manufacturer relationships with integrated delivery networks bypass wholesale intermediaries and anchor volume. |
| Manufacturing Scale-Up | Automated aseptic filling line investment separates viable injectable suppliers from stability-constrained marginal players. |
| Pipeline Diversification | Controlled-release polymer matrix development captures procurement specification shifts in chronic hypertension protocols. |
Methodological Framework
Cross-validation between regulatory filing databases and hospital procurement records anchors the qualitative findings on supply chain concentration. Primary interviews with regulatory affairs leads, hospital procurement managers, formulary directors, and specialized pharmaceutical chemists combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up volume modeling and top-down market sizing triangulate demand estimates.
Sensitivity analysis around API sourcing cost assumptions and regulatory compliance timeline scenarios stress-tests projection robustness across the analysis window. Segmentation dimensions modeled include formulation type, end-user channel, distribution structure, and regional regulatory cluster. CAGRs derive from historical volume trajectory analysis and forward-looking procurement specification evolution. Forecast inputs incorporate pharmacovigilance reporting obligation expansion and controlled-release formulation adoption curves.
The analysis sits within stated boundaries; outcomes outside EMA REACH enforcement intensity, FDA batch-traceability mandate scope, or Japanese research institution funding levels would require recalibration. Forecasts reflect documented assumptions around hospital procurement consolidation pace and generic substitution elasticity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Topical Drugs CDMO Market
Pharmaceuticals
Veterinary Pain Management Drugs Market
Pharmaceuticals
Global Pharmaceuticals Market
Pharmaceuticals
Anti-Radiation Drugs Market
Pharmaceuticals
Cough Syrup Market
Pharmaceuticals
Antiretroviral (ARV) Agents Market
Pharmaceuticals
Global Pharmacy Benefit Management (PBM) Market
Pharmaceuticals
G Protein Coupled Receptors (Gpcrs) Market
Pharmaceuticals
PAP and Paracetamol Market
Pharmaceuticals
Tuberculosis Therapeutics Market
Pharmaceuticals
Ramipril Market
Pharmaceuticals
Global Atherosclerosis Drugs Market
Pharmaceuticals
Lactated Ringers Injection Market
Pharmaceuticals
Global General Anesthesia Drugs Market
Pharmaceuticals
Zoldonat Injection Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting Therapeutics Market