
 Asia-Pacific Skin Packaging for Fresh Meat Market | 2026-2036
Asia-Pacific Skin Packaging for Fresh Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Skin Packaging for Fresh Meat Market Outlook
China's GB standards for food contact materials is shifting procurement criteria toward high-barrier, FDA-compliant films across the region's meat processing sector. Amcor plc leverages its regional film manufacturing footprint to sustain supply contracts with major Australian beef exporters. Dow anchors its position through proprietary ionomer resins that dominate vacuum-sealing applications in Japan and South Korea. Klöckner Pentaplast competes on thermoforming web thickness consistency, a specification prized by Thai and Vietnamese processors scaling automated lines.
Asia-Pacific skin packaging for fresh meat employs coextruded multilayer films, typically EVOH or PA tie layers sandwiched between PE or ionomer skins, thermoformed over meat cuts under vacuum to create oxygen-excluding, retail-ready trays that extend chilled shelf life. Polymer films lead value capture due to their tunable gas-barrier properties and compatibility with high-speed thermoforming lines, while composite structures gain share in premium export segments where dual-ovenable or microwaveable formats command price premiums. Modified atmosphere technology segments expand fastest as Japanese and Australian retailers adopt gas-flushed trays for case-ready beef, though vacuum sealing still dominates volume in China's wet-market-to-supermarket transition.
Japan's METI enforces strict shelf-life labeling and cold-chain accountability rules that elevate packaging performance requirements above baseline ASEAN norms. Australia's FSANZ standards for primary food contact materials create a compliance benchmark that Malaysian and Indonesian exporters must meet for market access. China's SAMR and GB 4806 series impose migration limits and substance-positive lists that filter out non-compliant film suppliers. Stakeholders must monitor divergence between Japan's JIS standards and China's GB harmonization timeline to anticipate reformulation costs and qualification delays.
Market Dynamics
Supermarket chains across Southeast Asia are expanding chilled meat sections and forcing packaging upgrades that prioritize extended shelf life and retail-ready presentation over traditional wet-market formats. This retail modernization is compressing procurement cycles and elevating barrier-film specifications across the region's meat processing clusters.
Growth Catalysts
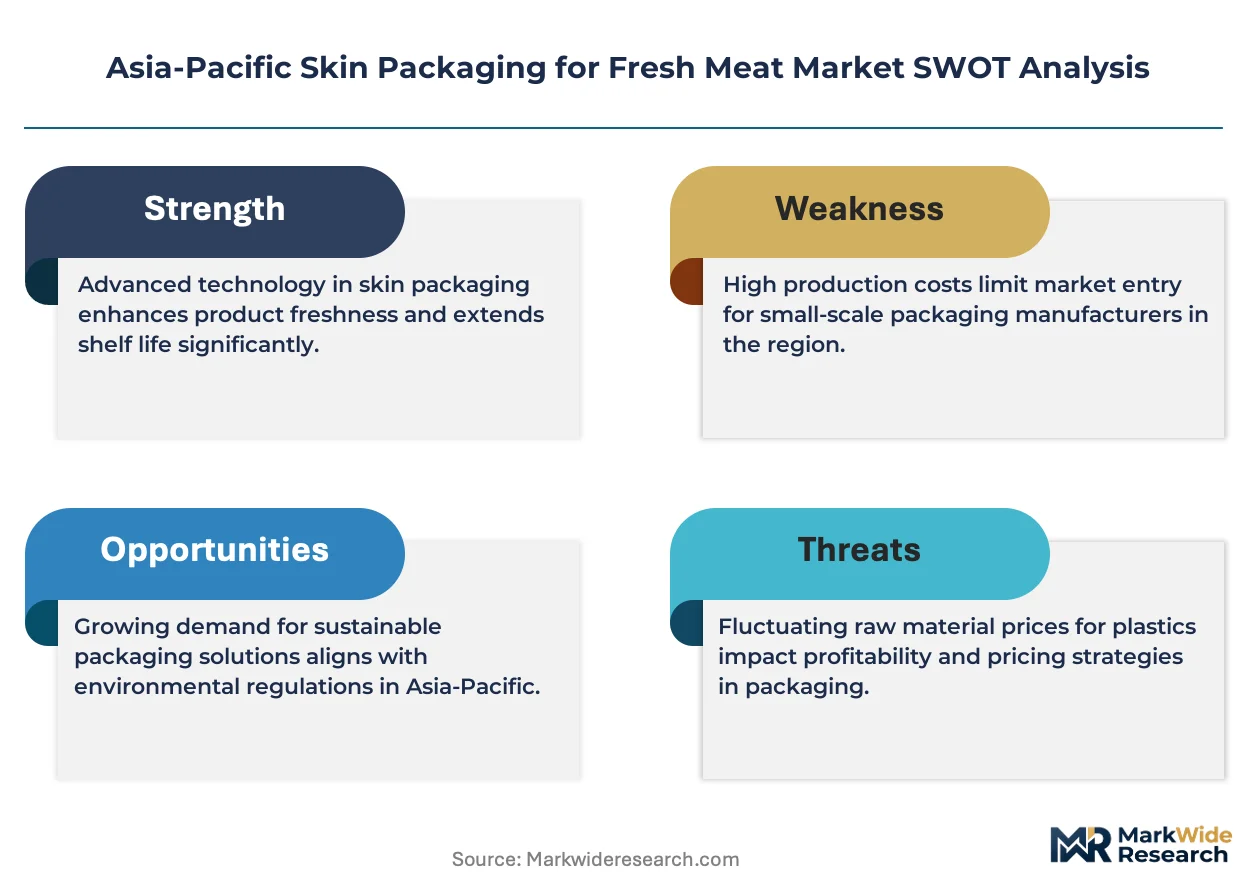
- China's GB 4806 tightening:Migration limits and substance-positive lists under SAMR oversight are filtering out non-compliant film suppliers and upgrading procurement criteria toward high-barrier, FDA-compliant films.
- Japanese retail modernization:METI shelf-life labeling and cold-chain accountability rules elevate packaging performance requirements above baseline ASEAN norms, driving premium film adoption.
- EVOH barrier technology:Coextruded multilayer films with oxygen-excluding properties are enabling case-ready beef formats that extend chilled shelf life for automated supermarket distribution.
Market Restraints
- Ionomer resin supply concentration:Proprietary resin supply for vacuum-sealing applications concentrates among specialty chemical producers, creating input cost volatility for film converters.
- Thai-Vietnamese processor scaling friction:Thermoforming web thickness consistency requirements strain mid-tier processors upgrading to automated lines, delaying qualification timelines.
- Alternative format substitution:Modified atmosphere gas-flushed trays are capturing premium export segments, compressing volume growth for conventional vacuum skin formats in Australia's beef export channels.
Strategic Opportunities
- Indonesian wet-market conversion:Underpenetrated chilled meat infrastructure creates white space for barrier-film suppliers as modern retail expands beyond Jakarta and Surabaya processing clusters.
- Dual-ovenable composite structures:Microwaveable and oven-ready formats command price premiums in premium export segments where Japanese and Australian retailers differentiate case-ready offerings.
- Malaysian exporter compliance arbitrage:FSANZ-aligned film qualification enables Malaysian and Indonesian processors to access Australian market entry while regional competitors lag certification.
Industry Challenges
- Thermoforming technician scarcity:Automated line operation and web calibration expertise concentrates in eastern China and Thailand, constraining Vietnamese and Indonesian processor scaling.
- Dual certification timeline compression:JIS standard divergence from China's GB harmonization timeline forces reformulation costs and qualification delays for suppliers serving both markets.
- Legacy wet-market infrastructure:Cold-chain gaps in China's interior provinces and Indonesia's outer islands fragment distribution and complicate shelf-life guarantee enforcement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Skin Packaging for Fresh Meat Market |
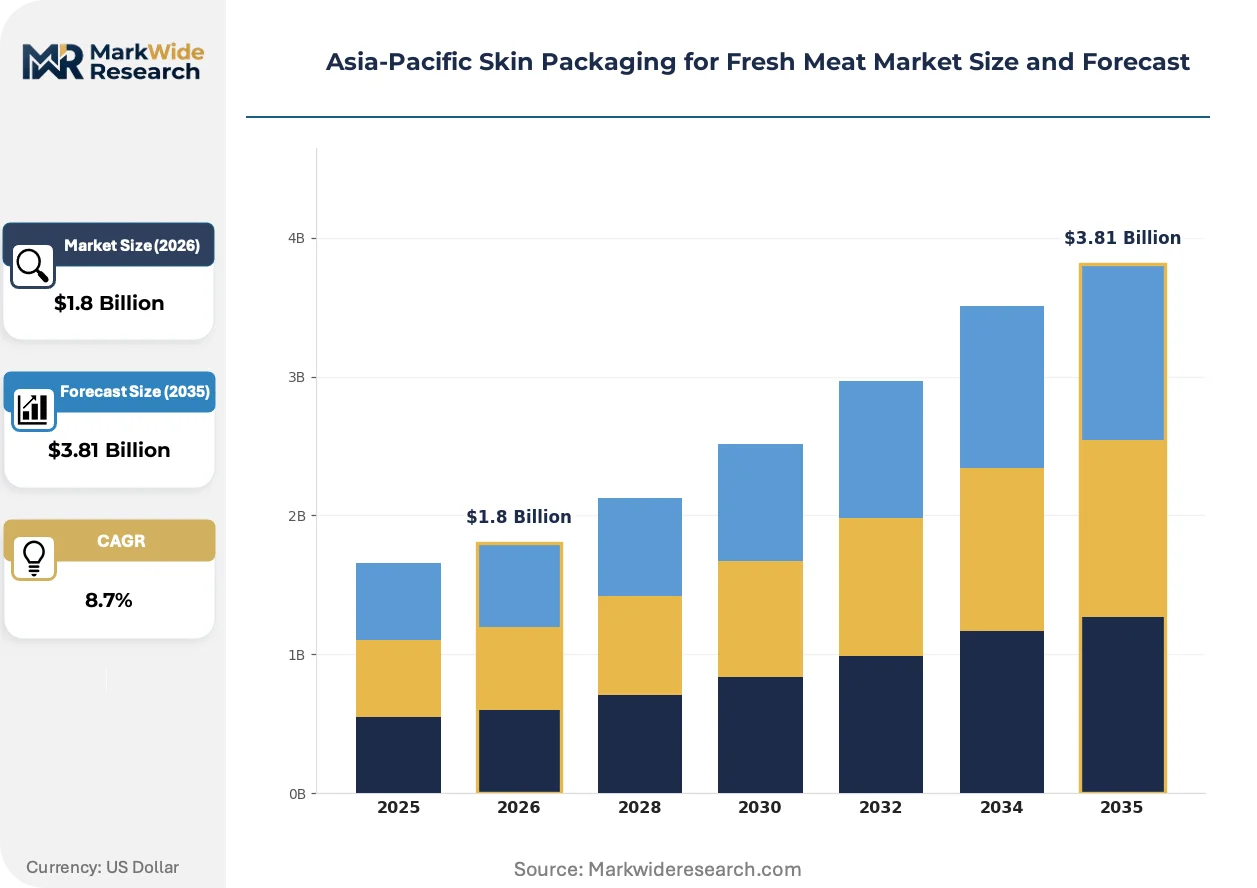
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer, Paperboard, Aluminum, Composite Form: Rolls, Sheets, Pouches, Bags End User: Retail, Wholesale, Food Service, Processors Technology: Thermoforming, Vacuum Sealing, Modified Atmosphere, Others |
| Companies Covered | Green Packaging Material (Jiangyin) Co., Ltd., Dow, Caspak Australia, Amcor plc, Klöckner Pentaplast, Promivision Packaging (China) Co., Ltd., MULTIVAC, JASA Packaging Solutions, Plantic, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Skin Packaging for Fresh Meat Market Strategic Shifts
Active packaging technologies and regulatory harmonization pressures are reshaping film formulation priorities across the region's meat processing sector. Material scientists and equipment suppliers are racing to align barrier performance with diverging national compliance timelines.
Smart indicator films incorporating time-temperature and freshness sensors are converging with high-barrier EVOH structures to create intelligent packaging that communicates shelf-life status directly to retailers and consumers. Japanese supermarket chains and Australian beef exporters are piloting these formats at scale. This convergence is compressing the qualification window for conventional passive barrier films and forcing suppliers to integrate sensing chemistry into coextrusion lines.
China's SAMR is accelerating GB standards harmonization with international food contact frameworks, imposing substance-positive lists and migration testing protocols that exceed legacy ASEAN norms. Domestic film converters must reformulate tie-layer chemistries and document compliance across expanded testing matrices. Malaysian and Indonesian exporters targeting Australian market access are pre-emptively adopting FSANZ-aligned specifications to avoid exclusion as Chinese standards tighten.
Retail buyer concentration in Thailand and Vietnam is consolidating procurement decisions toward integrated meatpackers operating captive thermoforming lines. Independent processors are losing share to vertically integrated supermarket suppliers who internalize film specification and equipment investment. This channel shift is most visible in Bangkok and Ho Chi Minh City where Central Retail and Masan Group are absorbing regional processing capacity into owned-and-operated chilled meat networks.
Asia-Pacific Skin Packaging for Fresh Meat Market Segmentation
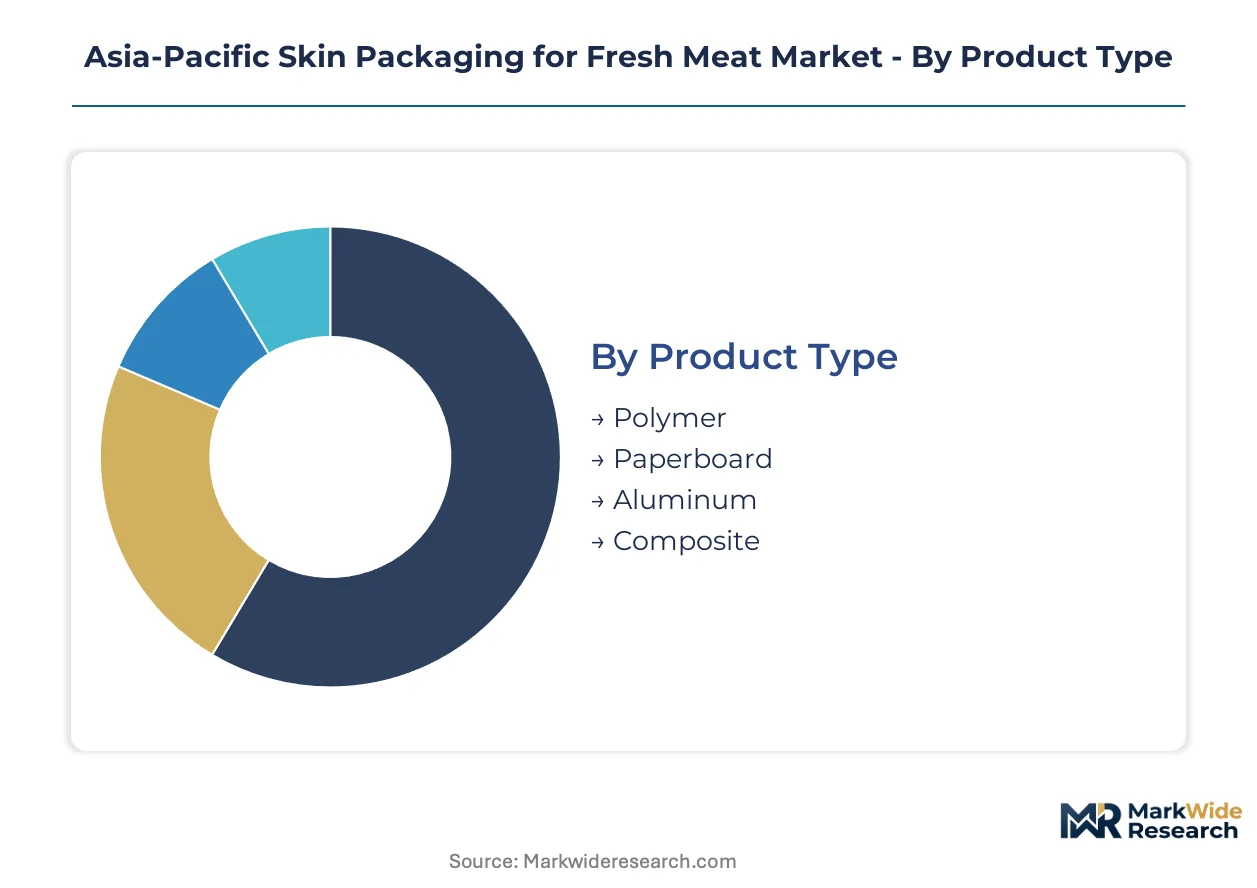
Skin packaging segmentation across Asia-Pacific reflects divergent upgrade cycles between mature retail markets and wet-market conversion zones. Procurement specifications split sharply between automated thermoforming lines in Thailand and manual operations in Indonesia's outer islands.
Product Type:
Material substitution cycles accelerate where GB 4806 migration limits and FSANZ primary contact standards force reformulation of legacy film structures.
- Polymer:Coextruded multilayer films with EVOH or PA tie layers dominate vacuum-sealing applications across Japanese and Australian beef export channels. Eastern China's processing clusters around Shanghai and Jiangsu specify these for high-speed thermoforming compatibility.
- Composite:Dual-ovenable and microwaveable structures command price premiums in Japanese retail modernization and Australian case-ready beef segments. Barrier performance must reconcile with oven-release properties.
- Paperboard:Fiber-based substrates serve wet-market transition formats in Vietnam and Indonesia where cost sensitivity overrides barrier requirements.
- Aluminum:Foil laminates retain niche share in premium halal beef exports from Malaysia to Middle Eastern markets.
Volume placements concentrate in Polymer; the faster expansion belongs to Composite.
Form:
Equipment investment patterns determine form factor adoption, with automated line density in Bangkok and Ho Chi Minh City favoring continuous feed formats.
- Rolls:Continuous web formats align with high-volume thermoforming operations at vertically integrated Thai and Vietnamese processors. Web thickness consistency specifications strain mid-tier converters scaling automated lines.
- Sheets:Pre-cut formats serve smaller Indonesian and Philippine processors lacking roll-handling equipment. Manual loading tolerances dominate procurement criteria.
- Pouches:Pre-formed vacuum pouches capture food service and wholesale segments in China's wet-market-to-supermarket transition.
- Bags:Side-seal formats persist in legacy wet-market distribution across Indonesia's outer islands where cold-chain gaps fragment shelf-life guarantees.
Rolls dominate throughput economics; Pouches gain share fastest where retail modernization compresses procurement cycles.
End User:
Channel consolidation in Southeast Asian retail is internalizing packaging decisions within captive meatpacking operations.
- Retail:Supermarket chains across Thailand and Vietnam are expanding chilled meat sections and forcing barrier-film upgrades. Central Retail and Masan Group absorption of regional processing capacity elevates specification control.
- Processors:Independent meatpackers in eastern China and Australia face qualification pressure as integrated competitors capture volume.
- Wholesale:Traditional distribution channels in Indonesia and Philippines lag cold-chain investment, constraining shelf-life extension adoption.
- Food Service:Restaurant and institutional buyers in urban China and Japan prioritize portion-control formats over barrier performance.
Retail commands specification authority; Processors face the steepest margin compression from captive supply integration.
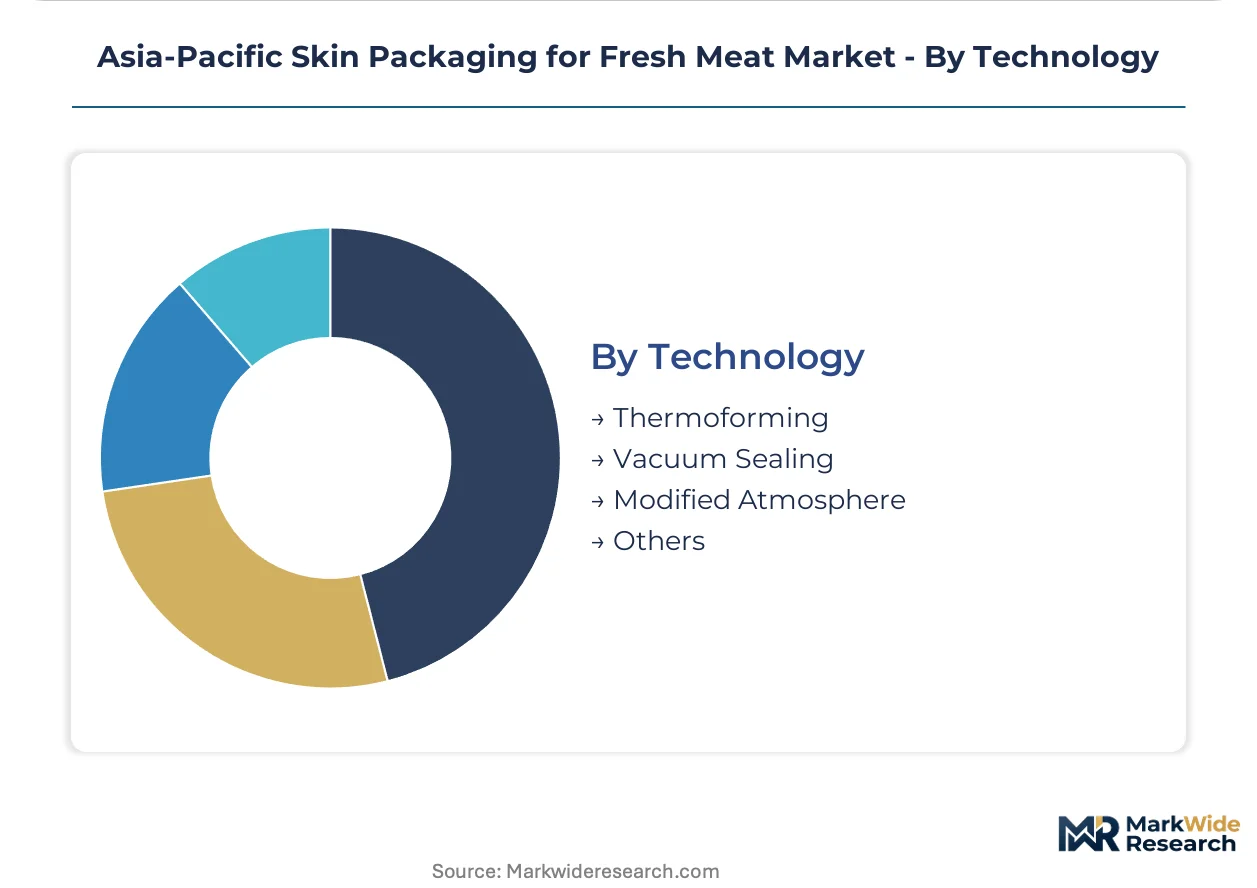
Technology:
Regulatory divergence between Japan's METI shelf-life labeling and China's GB harmonization timeline fragments equipment qualification priorities.
- Vacuum Sealing:Conventional vacuum skin formats retain volume dominance in China's wet-market transition and mid-tier ASEAN processing. Ionomer resin supply concentration creates input cost volatility for film converters.
- Modified Atmosphere:Gas-flushed trays are capturing premium export segments in Australian beef channels and Japanese retail case-ready formats. Cold-chain accountability rules elevate performance requirements.
- Thermoforming:Automated line scaling in Thailand and Vietnam strains technician availability for web calibration expertise.
- Others:Active packaging with time-temperature indicators pilots in Japanese supermarket chains and Australian beef export channels.
Vacuum Sealing anchors installed base; Modified Atmosphere climbs the fastest where premium retail formats justify gas-flush infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the Asia-Pacific skin packaging demand, with Jiangsu province processing clusters consuming the majority of high-barrier EVOH films for chilled beef distribution.
China
Supermarket expansion in tier-one cities drives film specification upgrades from wet-market formats. SAMR's GB 4806 series imposes migration limits that filter non-compliant suppliers. Eastern processing corridors around Shanghai and Jiangsu dominate thermoforming line density.
Japan
METI shelf-life labeling rules elevate barrier performance above ASEAN baselines for case-ready beef. Cold-chain accountability requirements compress qualification windows for film converters. Kanto region retailers pilot smart indicator films at scale.
Australia
FSANZ standards create compliance benchmarks for premium beef export channels. Gas-flushed modified atmosphere trays capture share in Japanese and domestic retail segments. Queensland and New South Wales processing hubs invest in automated thermoforming infrastructure.
Thailand
Central Retail's vertical integration absorbs regional processing capacity into captive chilled meat networks. Thermoforming web thickness consistency requirements strain mid-tier converters scaling automated lines. Bangkok corridor dominates equipment technician concentration.
Indonesia
Wet-market conversion lags in outer islands beyond Jakarta and Surabaya clusters. Cold-chain gaps fragment shelf-life guarantee enforcement for barrier film adoption. Modern retail expansion creates white space for high-barrier suppliers as infrastructure improves.
Asia-Pacific Skin Packaging for Fresh Meat Market Competitive Environment
Premium-margin players sit above commodity-margin players across barrier technology tiers, with EVOH coextrusion specialists commanding pricing power over commodity PE converters. The vendor base spans three strategic archetypes: integrated multinational film producers with regional manufacturing footprints, specialized thermoforming equipment suppliers with captive resin partnerships, and domestic Chinese converters leveraging local raw material access. Competitive moves concentrate on backward integration into ionomer resin production and geographic expansion through distributor partnerships in underpenetrated Southeast Asian markets.
Among Asia-Pacific-based suppliers, Green Packaging Material (Jiangyin) Co., Ltd. and Promivision Packaging (China) Co., Ltd. occupy positions within the domestic converter tier serving cost-sensitive wet-market transition segments. Dow represents the specialty chemical archetype through proprietary resin supply relationships. Amcor plc anchors the integrated multinational tier with regional film manufacturing scale. Klöckner Pentaplast exemplifies European-headquartered players competing on thermoforming web consistency specifications prized by Thai and Vietnamese processors.
| Leading Market Players |
|---|
| Green Packaging Material (Jiangyin) Co., Ltd. |
| Dow |
| Caspak Australia |
| Amcor plc |
| Klöckner Pentaplast |
| Promivision Packaging (China) Co., Ltd. |
| MULTIVAC |
| JASA Packaging Solutions |
| Plantic |
| Others |
Value Chain & Pricing Dynamics
Thermoforming technician concentration in eastern China and Thailand widens labor-cost spreads between premium automated lines and manual operations in Vietnam and Indonesia. This skill geography compresses margins for mid-tier processors while rewarding integrated suppliers with captive calibration expertise.
Pricing Analysis
Yield-guaranteed pricing for high-barrier EVOH films anchors value capture in Australian beef export channels and Japanese retail case-ready segments. Three-tier pricing structure across premium, standard, and economy levels separates FSANZ-certified composite structures from commodity PE-ionomer vacuum films and paperboard wet-market formats. Cost compression in mid-tier polymer grades is intensifying because Thai and Vietnamese processors scale automated lines simultaneously. Wet-market transition buyers in Indonesia and the Philippines exhibit highest price sensitivity; Japanese supermarket chains and Australian beef exporters show lowest.
Supply Chain Analysis
Ionomer resin supply rests on Dow's proprietary production and a narrow base of Japanese and South Korean specialty chemical producers. Coextruded multilayer films draw from EVOH feedstock anchored in Japan and ethylene-based skins from Chinese petrochemical corridors. Single-source vulnerability in ionomer chemistry exposes converters to input cost volatility when resin allocation tightens. Distribution runs through vertically integrated meatpackers in Bangkok and Ho Chi Minh City, with independent processors in Jakarta and Manila relegated to distributor-mediated channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific skin packaging for fresh meat sits in a technology-transition phase as modified atmosphere gas-flush systems displace conventional vacuum formats in premium retail and export channels.
For Market Incumbents: Anchor market position through backward integration into ionomer resin production or captive thermoforming equipment partnerships. Defend against modified atmosphere substitution by accelerating smart indicator film pilots with Japanese retailers. Prioritize dual JIS-GB certification investment to preempt qualification delays as Chinese standards tighten. For New Entrants and Emerging Players: GB 4806 harmonization in China opens a window for FSANZ-aligned film suppliers to capture Malaysian and Indonesian processor upgrading. Target underpenetrated chilled meat infrastructure in Indonesia's outer islands beyond Jakarta and Surabaya clusters. Enter through equipment-plus-film bundling partnerships with regional distributors lacking technical service depth. For Investors and Strategic Acquirers: Re-rating potential sits with EVOH coextrusion specialists given barrier-film specification upgrades across Southeast Asian retail modernization. Long-term viability favors suppliers with demonstrated JIS qualification and regional manufacturing footprint. Watch modified atmosphere adoption rates in Australian beef exports as inflection signal for vacuum format displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ionomer Resin | Proprietary resin supply secures margin control against specialty chemical concentration in Japan and South Korea. |
| Dual Certification Investment | Simultaneous JIS and GB 4806 qualification preempts reformulation costs for suppliers serving both markets. |
| Smart Indicator Film Pilot Expansion | Time-temperature sensor integration with EVOH structures captures Japanese retailer premium positioning. |
| Equipment-Plus-Film Bundling | Technical service partnerships penetrate Indonesian and Vietnamese mid-tier processor scaling friction. |
| Regional Distributor Acquisition | Channel control in underpenetrated Southeast Asian markets accelerates wet-market conversion capture. |
Study Parameters
Trade databases, regulatory filings, and industry association reports formed the secondary backbone for this analysis. Primary interviews with thermoforming equipment technicians, film procurement managers at meatpackers, regulatory compliance officers, and supermarket category buyers validated secondary findings. Bottom-up volume modeling triangulated against top-down value estimates derived from customs data and processing capacity surveys.
Historical trendline analysis of film consumption per chilled meat tonnage informed projection assumptions across the analysis window. Segmentation modeling incorporated product type, form factor, end-user channel, and technology tier dimensions. CAGRs were derived from equipment installation rates and retail modernization timelines. Forecast inputs included SAMR enforcement intensity for GB 4806 and METI shelf-life labeling adoption curves.
Caveats apply where ionomer resin supply disruptions or accelerated modified atmosphere substitution could materially shift the outlook. Forecasts reflect assumptions about cold-chain infrastructure buildout in Indonesia and regulatory harmonization timelines between Japan and China. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Pizza Box Market
Food Packaging
Cornstarch Packaging Market
Food Packaging
Produce Packaging Market
Food Packaging
Lightweight Food Container Market
Food Packaging
On the Go Food Packaging Market
Food Packaging
PVDC Coating Food Packaging Market
Food Packaging
Pet Food Packaging Market
Food Packaging
Asia Pacific Food Packaging Market
Food Packaging
India Food and Beverage Packaging Market
Food Packaging
Food Packaging Market
Food Packaging
Drink Carrier and Trays Market
Food Packaging
Desserts Packaging Market
Food Packaging
Food Tub Packaging Market
Food Packaging
APAC Frozen Food Packaging Market
Food Packaging
Disposable Hot Cups & Lids Market
Food Packaging
Self-Heating Food Packaging Market