
 Produce Packaging Market | 2026-2036
Produce Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Produce Packaging Market Outlook
Food service providers is bifurcating demand away from traditional wholesale bulk formats toward portion-controlled, retail-ready packaging. Amcor plc leverages its global film extrusion network to supply high-barrier lidding for modified-atmosphere trays. Smurfit Westrock anchors European corrugated produce box supply through integrated pulp and paper assets. Sealed Air differentiates via automated produce packaging systems that reduce labor at packhouse operations.
Produce packaging encompasses containers, wraps, and cushioning structures engineered from polyethylene films, molded pulp, or corrugated fiberboard to protect fruits and vegetables from mechanical damage, moisture loss, and ethylene-driven spoilage during post-harvest handling and retail display. Clamshells dominate value contribution due to their transparency and stackability in refrigerated retail cases, while biodegradable films represent the fastest-expanding material category as compostability certifications become a procurement filter. Polypropylene trays sustain margin pools in pre-cut and value-added produce segments where dimensional stability and microwave compatibility command price premiums.
The EU Packaging and Packaging Waste Regulation (PPWR) mandates minimum recycled content thresholds that reshape resin procurement strategies across European converters. FDA food-contact substance notifications govern barrier coatings and antimicrobial additives in the United States, directly affecting cross-border product qualification timelines. Stakeholders must monitor how divergent extended producer responsibility schemes across Germany, France, and Italy reshape cost allocation between brand owners and packaging suppliers.
Market Dynamics
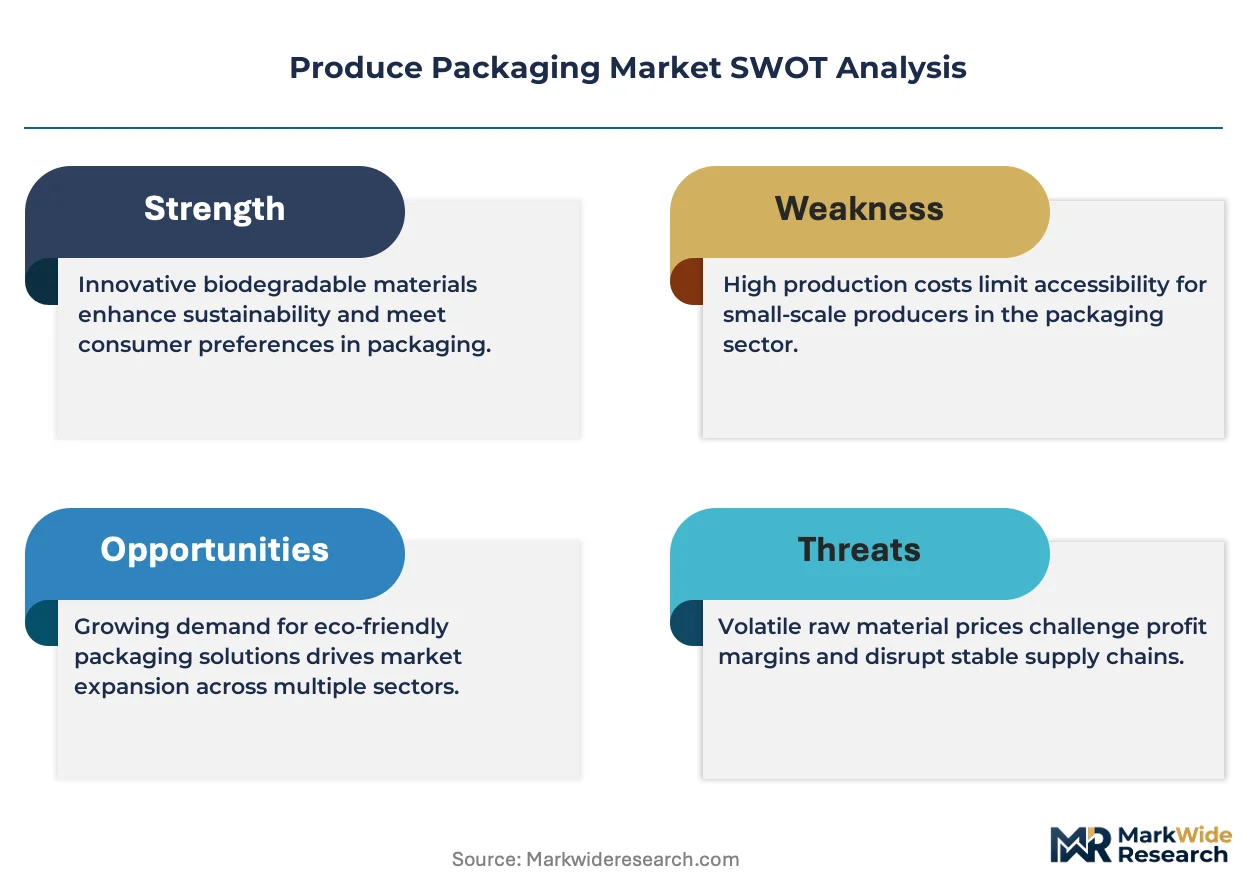
The EU Packaging and Packaging Waste Regulation is compressing virgin resin demand across European converters while simultaneously elevating certified compostable materials to procurement-mandatory status in premium produce segments.
Growth Catalysts
- Modified-atmosphere tray adoption:Food service providers in Germany and France are replacing bulk wholesale formats with portion-controlled retail-ready packaging for pre-cut produce.
- REACH-compliant barrier coatings:ECHA-registered oxygen scavenger films enable shelf-life extension for berries and leafy greens without violating substance restrictions.
- Italian retailer investment:Coop Italia and Conad are mandating vented clamshell specifications that synchronize packhouse automation with refrigerated display requirements.
Market Restraints
- Recycled-content resin scarcity:Post-consumer polyethylene supply concentrates in German and Dutch reprocessing facilities, creating procurement bottlenecks for converters in Southern Europe.
- Compostable film performance ceiling:PLA-based structures exhibit moisture sensitivity above 85% relative humidity, limiting application to dry-skin produce categories.
- Extended producer responsibility cost allocation:France's Citeo scheme imposes differentiated fees that compress margins on lightweight flexible formats versus rigid alternatives.
Strategic Opportunities
- Polish and Romanian retail modernization:Discounter expansion in Warsaw and Bucharest creates first-mover advantage for shelf-life extension packaging suppliers.
- Smart label integration:RFID-enabled temperature-logging labels converge with blockchain traceability platforms to command price premiums in organic produce channels.
- EU Green Deal farm-to-fork funding:Horizon Europe grants subsidize packhouse automation upgrades that reduce food loss through improved breathable film specifications.
Industry Challenges
- Multilayer film separation expertise:Mechanical recycling infrastructure lacks capacity to process metallized or adhesive-laminated structures, constraining circular-economy claims.
- Antimicrobial additive compliance timelines:EFSA novel food evaluations for chitosan-based coatings extend qualification cycles beyond typical product development windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Produce Packaging Market |
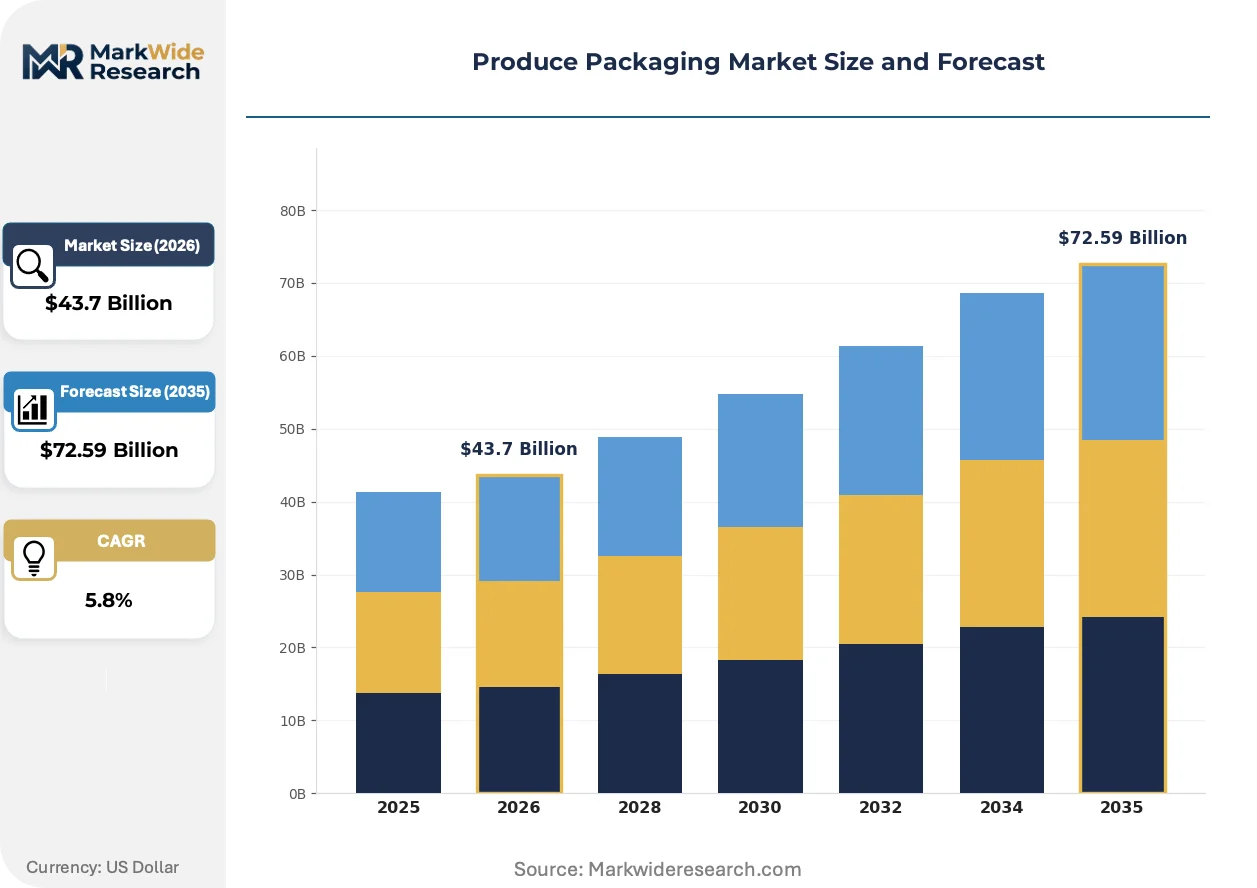
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $72.59 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Plastic Bags, Clamshells, Trays, Cartons Material: Polyethylene, Polypropylene, Paper, Biodegradable Films End User: Retailers, Wholesalers, Restaurants, Food Service Providers Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesale Markets |
| Companies Covered | Amcor plc, Smurfit Westrock, Mondi, Sealed Air, Sonoco Products Company, International Paper Company, WestRock Company, Packaging Corporation of America, Berry Global Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Produce Packaging Market Strategic Shifts
Active and intelligent packaging systems are migrating from pharmaceutical cold chains into fresh produce logistics, embedding sensors that communicate remaining shelf life directly to retail reorder systems.
Bio-based barrier films derived from agricultural residues are bifurcating material procurement between petrochemical-dependent incumbents and cellulose nanofiber specialists. Berry packers in Huelva and Murcia are piloting these structures for export shipments to Northern Europe. The technology is bifurcating competitive positioning between converters with captive pulp assets and those locked into long-term polyethylene contracts.
The EU Packaging and Packaging Waste Regulation mandates minimum recycled content thresholds that escalate through 2030, forcing resin procurement restructuring across European film extruders. Italian and Spanish converters face particular strain given limited domestic mechanical recycling capacity. Smaller packagers are responding through consortium purchasing agreements that aggregate volume for food-grade recycled pellet access.
Retailers are consolidating produce packaging specifications around modular clamshell platforms that accommodate multiple SKUs through interchangeable label configurations. This standardization compresses converter development cycles while elevating importance of rapid label-changeover capabilities. The shift is most visible in German discount channels where Aldi and Lidl enforce unified secondary packaging dimensions across supplier bases.
Produce Packaging Market Segmentation
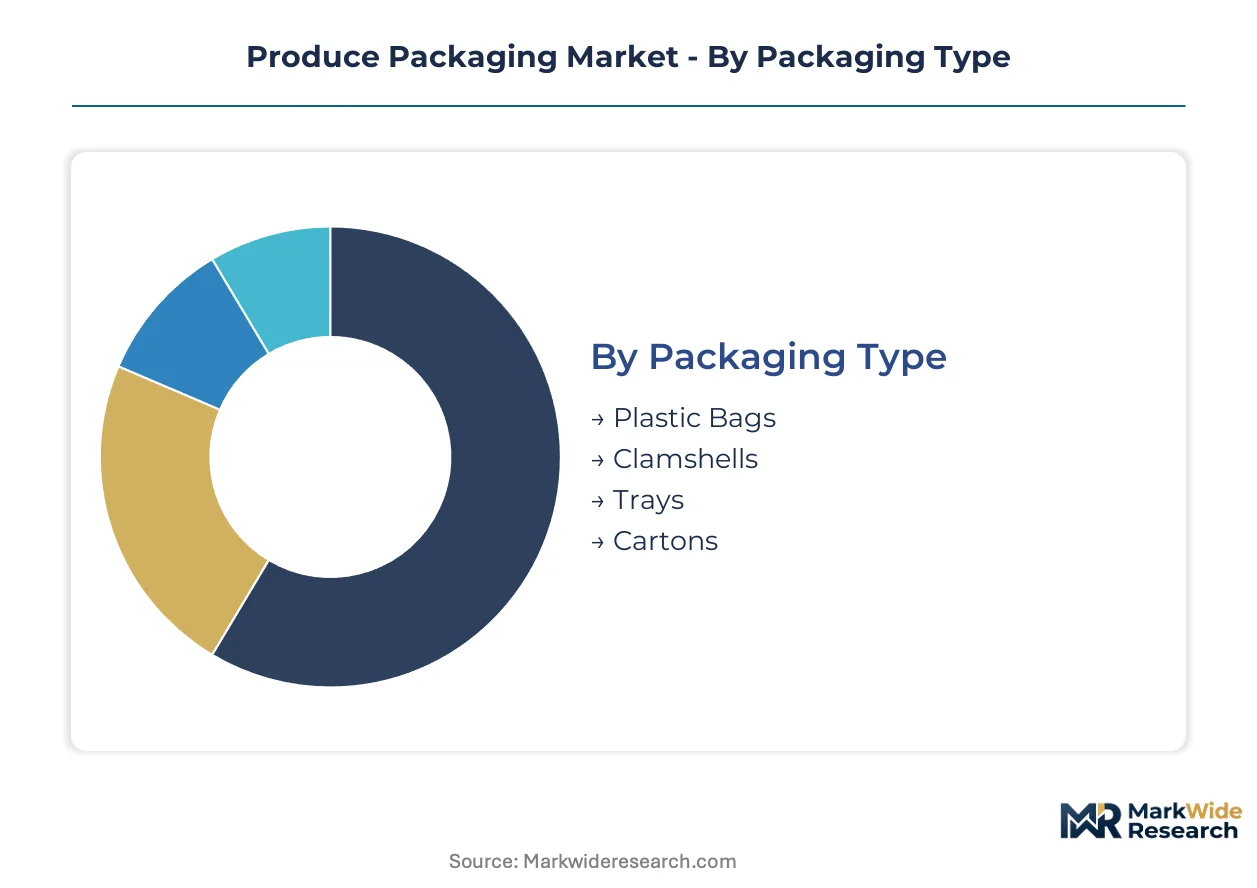
Segmentation in produce packaging reveals how material specifications, distribution pathways, and end-user automation requirements create divergent margin pools. Understanding these divisions exposes where converters can defend pricing power against commodity resin volatility.
Packaging Type:
German and French retail consolidation favors export-ready formats with standardized dimensions, while Southern European packhouses still accommodate domestic wholesale bulk configurations.
- Clamshells:Thermoformed polyethylene terephthalate structures with integral hinged lids provide optical clarity for retail produce display. Demand concentrates in German discount channels where Aldi and Lidl enforce unified secondary packaging dimensions across supplier bases, compressing converter development cycles.
- Trays:Injection-molded polypropylene platforms with modified-atmosphere lidding enable shelf-life extension for pre-cut vegetables. Food service providers in France and Italy are replacing bulk wholesale formats with these portion-controlled retail-ready structures.
- Plastic Bags:Perforated polyethylene film sacks dominate wholesale movement of root vegetables and bulk greens through Dutch auction systems and Spanish Mercamadrid.
- Cartons:Corrugated fiberboard boxes with vented designs protect soft fruit during export shipments from Huelva and Murcia to Northern European distribution centers.
Clamshells hold the largest share; momentum sits with trays as food service automation expands.
Material:
Cost tier stratification separates premium certified-compostable grades from commodity virgin resins, with recycled-content intermediates commanding mid-tier positioning.
- Polyethylene:Linear low-density films dominate breathable bag applications for leafy greens, with German and Dutch reprocessing facilities supplying post-consumer feedstock to converters facing EU Packaging and Packaging Waste Regulation mandates.
- Biodegradable Films:Polylactic acid and polyhydroxyalkanoate structures earn procurement-mandatory status in premium organic produce segments where compostability certifications filter supplier selection.
- Polypropylene:Biaxially oriented films provide dimensional stability for microwave-compatible pre-cut produce trays in value-added segments.
- Paper:Molded pulp cushioning and corrugated containment serve berry export logistics from Southern Spain through integrated pulp and paper asset networks.
Polyethylene retains volume leadership; biodegradable films are climbing the fastest as retailer sustainability procurement criteria tighten.
End User:
Customer type determines automation compatibility requirements, with centralized packhouse operations demanding conveyor-ready formats distinct from loose wholesale handling.
- Retailers:German chains Coop Italia and Conad mandate vented clamshell specifications that synchronize packhouse automation with refrigerated display requirements.
- Food Service Providers:Contract caterers and institutional kitchens in France drive modified-atmosphere tray specifications for pre-cut portion control.
- Wholesalers:Dutch auction houses and Italian Mercato Ortofrutticolo di Bologna still absorb bulk corrugated formats for downstream breaking and repacking.
- Restaurants:Independent operators purchase through cash-and-carry channels with minimal packaging specification leverage.
Retailers command the largest specification influence; food service providers are gaining share fastest as centralized procurement consolidates.
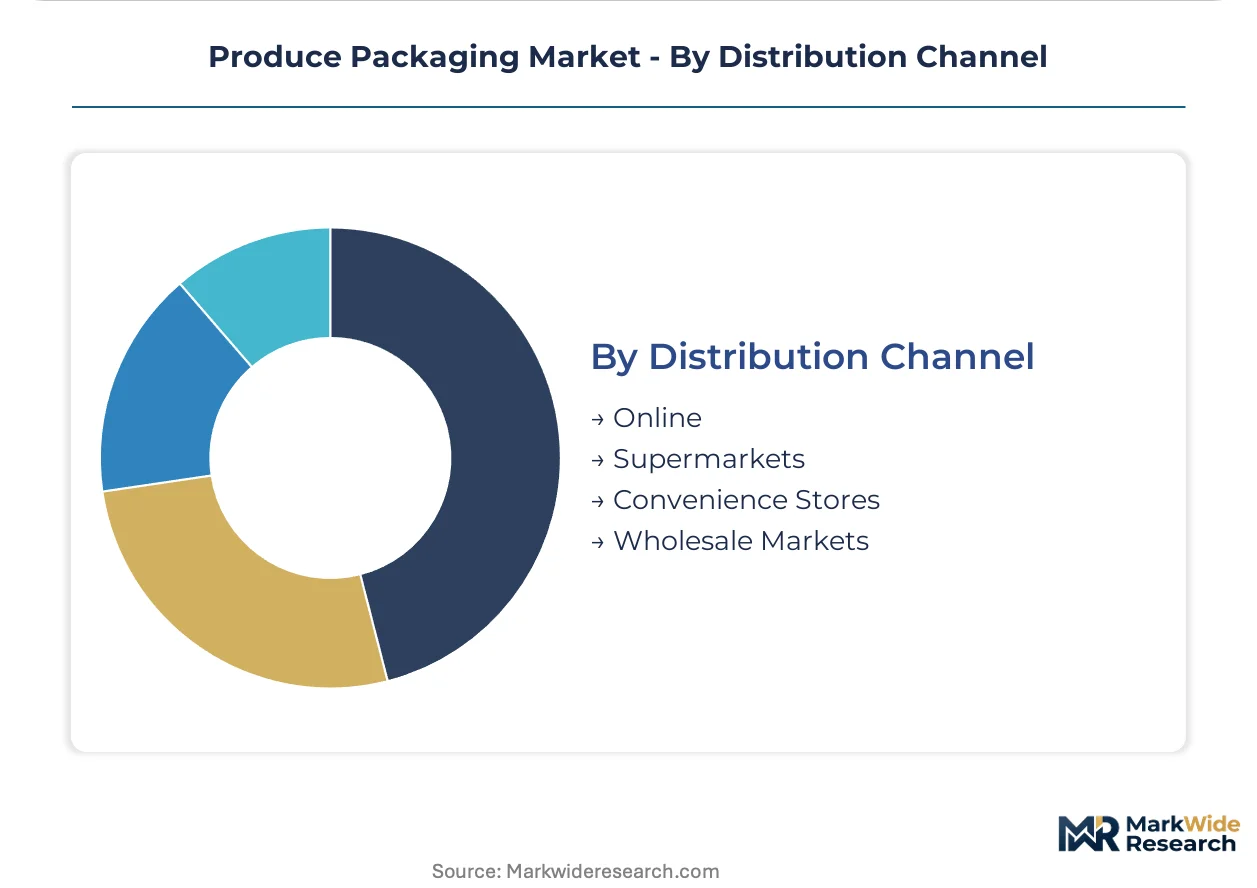
Distribution Channel:
Volume concentration varies sharply between automated supermarket replenishment systems and fragmented convenience store ordering patterns.
- Supermarkets:German and French hypermarket chains enforce modular clamshell platforms accommodating multiple SKUs through interchangeable label configurations.
- Wholesale Markets:Physical auction and terminal markets in Rotterdam, Milan, and Barcelona handle bulk corrugated movement for downstream breaking.
- Online:Direct-to-consumer produce subscription services in Paris and Berlin demand insulated box formats with gel packs for last-mile temperature maintenance.
- Convenience Stores:Small-format urban retail in Italian city centers absorbs single-serve clamshells through independent distributor networks.
Supermarkets dominate volume; online channels are expanding most quickly as urban delivery infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold chain infrastructure anchors European produce distribution, handling reefer containers from Iberian growing regions and distributing modified-atmosphere packaging specifications across the continent.
Germany
Aldi and Lidl enforce unified clamshell dimensions across supplier bases, compressing converter development cycles. The EU Packaging and Packaging Waste Regulation mandates escalating recycled-content thresholds through 2030. The Rhine-Main packhouse cluster around Frankfurt synchronizes automation with refrigerated retail display requirements.
France
Contract caterers drive modified-atmosphere tray specifications for pre-cut portion control in institutional kitchens. Citeo's extended producer responsibility scheme imposes differentiated fees that compress margins on lightweight flexible formats. The Rungis wholesale market terminal handles bulk corrugated movement for downstream breaking and repacking.
Italy
Coop Italia and Conad mandate vented clamshell specifications that synchronize packhouse automation with refrigerated display requirements. EFSA novel food evaluations for chitosan-based coatings extend qualification cycles beyond typical product development windows. The Emilia-Romagna processing corridor concentrates berry export logistics through integrated pulp and paper networks.
Spain
Berry packers in Huelva and Murcia pilot bio-based barrier films derived from agricultural residues for export shipments to Northern Europe. Limited domestic mechanical recycling capacity strains resin procurement under EU Packaging and Packaging Waste Regulation mandates. The Almería greenhouse complex generates demand for breathable film specifications in high-humidity growing environments.
Netherlands
Dutch auction systems absorb perforated polyethylene film sacks for bulk greens movement through terminal markets. German and Dutch reprocessing facilities supply post-consumer feedstock to converters facing recycled-content mandates. The Westland greenhouse cluster drives specifications for shelf-life extension packaging in tomato and pepper export logistics.
Produce Packaging Market Competitive Environment
Concentration sits with integrated packaging conglomerates possessing captive pulp assets and global film extrusion networks. Three structural tiers separate multinational converters with full material portfolios, regional specialists in corrugated containment, and automation-focused equipment suppliers. M&A activity targets reprocessing capacity in Germany and the Netherlands, while strategic partnerships secure food-grade recycled pellet access for Southern European converters facing supply bottlenecks.
Among integrated packaging conglomerates, Amcor plc and Smurfit Westrock exemplify archetypes with global reach and captive material assets. Sealed Air occupies a position representing the automation-focused tier, supplying systems that reduce labor at packhouse operations. These three companies anchor competitive positioning across film extrusion, corrugated supply, and automated packaging equipment respectively.
| Leading Market Players |
|---|
| Amcor plc |
| Smurfit Westrock |
| Mondi |
| Sealed Air |
| Sonoco Products Company |
| International Paper Company |
| WestRock Company |
| Packaging Corporation of America |
| Berry Global Group, Inc. |
| Others |
Value Chain & Pricing Dynamics
Post-consumer polyethylene substitution for virgin resin simultaneously shifts procurement geography toward German and Dutch reprocessing clusters and compresses margin structures for Southern European converters facing EU Packaging and Packaging Waste Regulation compliance deadlines.
Pricing Analysis
Volume-discount tiering structures separate multinational retail chains commanding pallet-scale pricing from independent packhouses purchasing on spot terms. Three-tier pricing stratification across premium certified-compostable grades, mid-tier recycled-content intermediates, and economy virgin resin reflects certification grade and volume scale as primary differentiation drivers. Pricing pressure stems from extended producer responsibility fee differentials that disadvantage lightweight flexible formats in France's Citeo scheme. Food service providers exhibit lowest price sensitivity due to shelf-life extension value capture, while wholesale cash-and-carry channels absorb maximum cost compression.
Supply Chain Analysis
Just-in-time resin procurement dominates German and French converter operations, while Spanish and Italian packagers maintain strategic stockpiles against recycled-content pellet scarcity. Geographic supply concentration centers on Germany, the Netherlands, and Belgium for post-consumer polyethylene reprocessing. Raw material dependencies include linear low-density polyethylene resin, polylactic acid for compostable grades, and thermoformed polyethylene terephthalate sheet. Single-source vulnerability concentrates in German mechanical recycling infrastructure serving cross-border demand. Distribution runs through Rotterdam cold chain terminals into Aldi and Lidl consolidated replenishment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as German discount chains consolidate produce packaging specifications across unified secondary packaging dimensions, fragmenting converter pricing leverage.
For Market Incumbents: Secure captive pulp assets in Iberian agricultural residue networks to defend against bio-based barrier film substitution threatening polyethylene-dependent margins. Lock in long-term offtake agreements with Dutch and German reprocessing facilities before recycled-content pellet scarcity intensifies under escalating EU Packaging and Packaging Waste Regulation thresholds. For New Entrants and Emerging Players: Lead with compostable film certification in premium organic produce segments where retailer procurement mandates filter supplier selection. Target Polish and Romanian retail modernization corridors where discounter expansion outpaces incumbent converter footprint. Deploy rapid label-changeover capabilities as the primary go-to-market wedge against rigid incumbent tooling cycles. For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation recycled-content mandates reshape the acquisition landscape toward German and Dutch mechanical recycling capacity. Long-term viability favors targets with integrated reprocessing assets and food-grade pellet certification infrastructure. Watch Citeo scheme fee recalibration as the signal indicating margin compression inflection for flexible format exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reprocessing | Captive post-consumer polyethylene supply secures EU Packaging and Packaging Waste Regulation compliance for Southern European converters. |
| Compostable Film Certification Investment | Polylactic acid and polyhydroxyalkanoate validation unlocks procurement-mandatory status in Coop Italia and Conad organic produce specifications. |
| Packhouse Automation Partnership | RFID-enabled temperature-logging integration with blockchain traceability commands price premiums in Berlin and Paris subscription channels. |
| Consortium Purchasing Agreement | Aggregated volume access to food-grade recycled pellets mitigates procurement bottlenecks for Italian and Spanish mid-tier converters. |
| Modular Clamshell Platform Standardization | Interchangeable label configurations compress development cycles for Aldi and Lidl unified secondary packaging dimension requirements. |
Study Parameters
A standing panel of packhouse operations directors, retail category buyers at German and French chains, corrugated plant managers, and food service procurement leads provided ongoing calibration across the study period. Primary interview data combined with secondary validation from EU Packaging and Packaging Waste Regulation implementation trackers, ECHA substance registration databases, and customs trade flow records. Bottom-up converter capacity assessments triangulated against top-down retail packaging spend estimates.
Consistency checks validated volume and value outputs against external benchmarks including reprocessing facility throughput disclosures and retail shelf-space allocation data. The analytical framework modeled packaging type, material grade tier, end-user automation requirements, and distribution channel concentration across the projection horizon. CAGRs derived from segmented growth rate application to baseline value estimates, incorporating modified-atmosphere tray adoption curves and biodegradable film penetration assumptions specific to organic produce channel expansion.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or alternative bio-based material breakthroughs would require recalibration. Forecasts reflect documented assumptions regarding recycled-content pellet supply elasticity and retailer specification consolidation trajectories. Revision becomes warranted when German and Dutch reprocessing capacity utilization crosses thresholds triggering cross-border supply rationing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
North America PET Food Packaging Market
Food Packaging
Processed Meat Packaging Market
Food Packaging
Pizza Box Market
Food Packaging
Global Ambient Food Packaging Market
Food Packaging
Pet Beverage Packaging Market
Food Packaging
PCR Packaging for Food and Beverages Applications Market
Food Packaging
Food and Drink Packaging Market
Food Packaging
PVDC Food Packaging Market
Food Packaging
Fresh Produce Trays Market
Food Packaging
Poultry Packaging Market
Food Packaging
Egg Cartons Market
Food Packaging
Cereal Packaging Market
Food Packaging
Frozen Food Packaging Market
Food Packaging
On the Go Food Packaging Market
Food Packaging
United States Frozen Food Packaging Market
Food Packaging
Europe Frozen Food Packaging Market