
 India Food and Beverage Packaging Market | 2026-2036
India Food and Beverage Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
India Food and Beverage Packaging Market Foresight
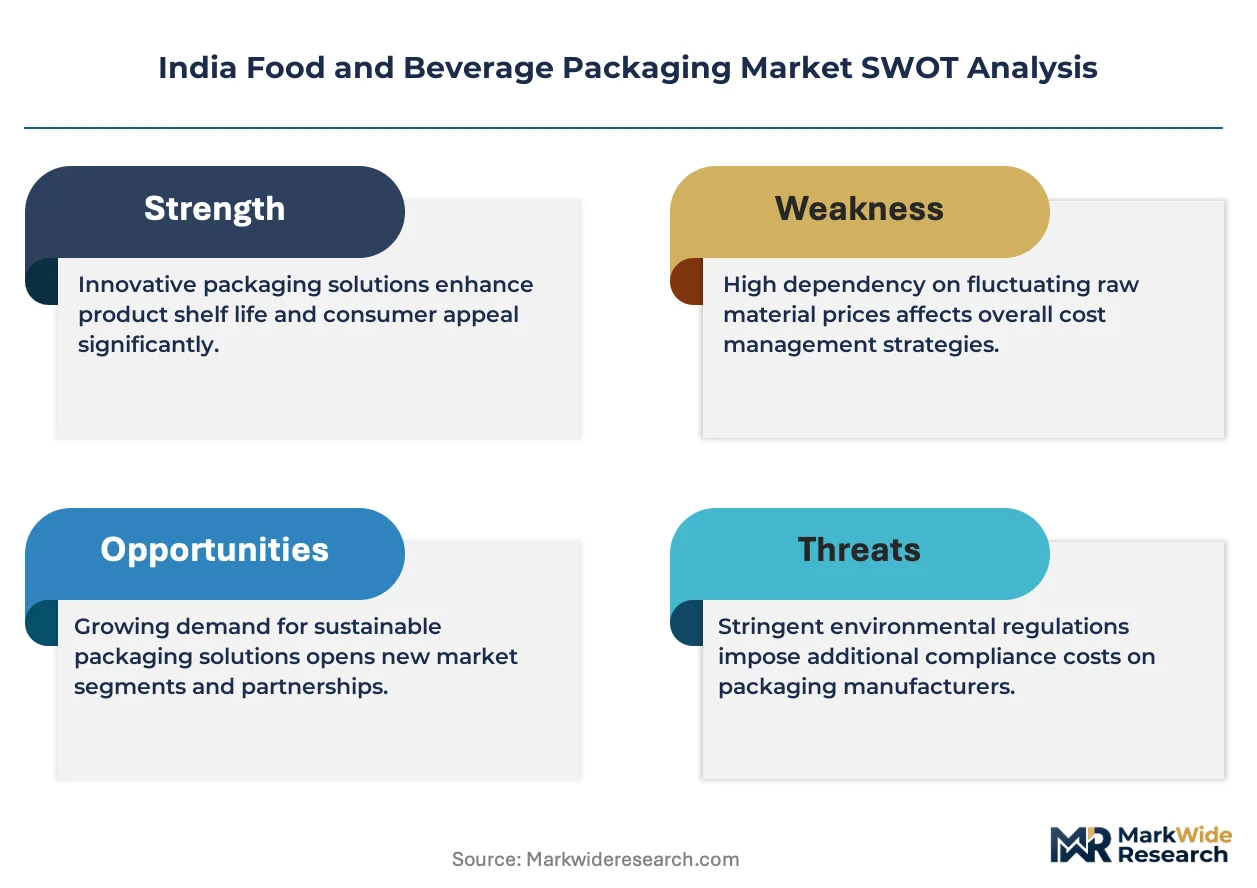
Multi-source procurement among dairy and edible oil brands is realigning supplier relationships across India's packaging value chain. UFlex Ltd leverages integrated film manufacturing to control substrate costs for flexible formats. Huhtamaki India Ltd anchors its position through specialty barrier coatings for ambient shelf-stable foods. TCPL Packaging Ltd competes on gravure printing scale for branded consumer goods labels and cartons.
Food and beverage packaging encompasses engineered containment systems—ranging from multilayer polymer pouches to metallized laminates and thermoformed trays—designed to preserve organoleptic properties, extend shelf life, and comply with migration limits under FSSAI contact-materials standards. Flexible packaging leads volume in spices, snacks, and liquid dairy due to material efficiency and transport economics, while rigid formats retain dominance in carbonated beverages and premium spirits where glass and metal preserve brand positioning. Pouches within flexible systems are gaining fastest in single-serve condiments and ready-to-cook gravies as convenience formats penetrate tier-two cities.
FSSAI notification standards for food-contact plastics, BIS certification for packaging materials, and state-level plastic waste management directives in Maharashtra and Tamil Nadu collectively shape material substitution timelines and recyclability investments. Compliance with extended producer responsibility mandates is redirecting capital toward mono-material structures and post-consumer recycled content integration. Stakeholders must monitor evolving EPR enforcement thresholds and substrate-neutral taxation proposals that could alter the cost structure between plastic, paper, and metal alternatives.
Market Dynamics
Extended producer responsibility mandates under India's Plastic Waste Management Rules are compressing material substitution timelines and forcing capital reallocation toward mono-material structures and recycled content integration across the packaging value chain.
Growth Catalysts
- Urban convenience formats:Single-serve condiment pouches and ready-to-cook gravy packs are penetrating tier-two cities as working households prioritize meal preparation speed.
- FSSAI contact-materials standards:Migration limit enforcement for food-contact plastics is professionalizing supplier qualification and consolidating demand toward certified converters.
- Maharashtra-Gujarat industrial corridor concentration:Dairy and snack processing clusters in these states are generating localized packaging demand that attracts film manufacturing investments.
Market Restraints
- Ethylene and propylene feedstock volatility:Polymer substrate costs swing with crude-linked naphtha pricing, squeezing converter margins on fixed-price annual contracts.
- Metallized barrier film supply concentration:Vacuum metallization capacity clusters among a handful of western Indian producers, creating bottleneck risk for ambient shelf-stable formats.
- Multi-layer laminate recyclability limitation:Current mechanical recycling infrastructure cannot separate PET/PE/foil composites, limiting circular economy claims.
Strategic Opportunities
- Post-consumer recycled content mandates:Draft BIS standards for recycled plastics in food-contact applications will create first-mover advantage for rPET and rPP integrators.
- E-commerce direct-to-consumer channels:D2C snack and spice brands require damage-resistant, printable formats that bypass traditional retail shelf aesthetics.
- Biopolymer substrate convergence:PLA and PHA compatibility with existing flexible packaging lines is opening pilot-scale substitution in premium organic product segments.
Industry Challenges
- Gravure cylinder engraving skill scarcity:High-definition print quality demands specialized craft labor that training institutes are not replenishing at replacement rates.
- Legacy extrusion line retrofit complexity:Mono-material structure transitions require screw and die modifications that disrupt production schedules during qualification periods.
- EPR registration and audit documentation:State-level plastic waste management authorities impose varying reporting formats that complicate pan-Indian compliance operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Food and Beverage Packaging Market |
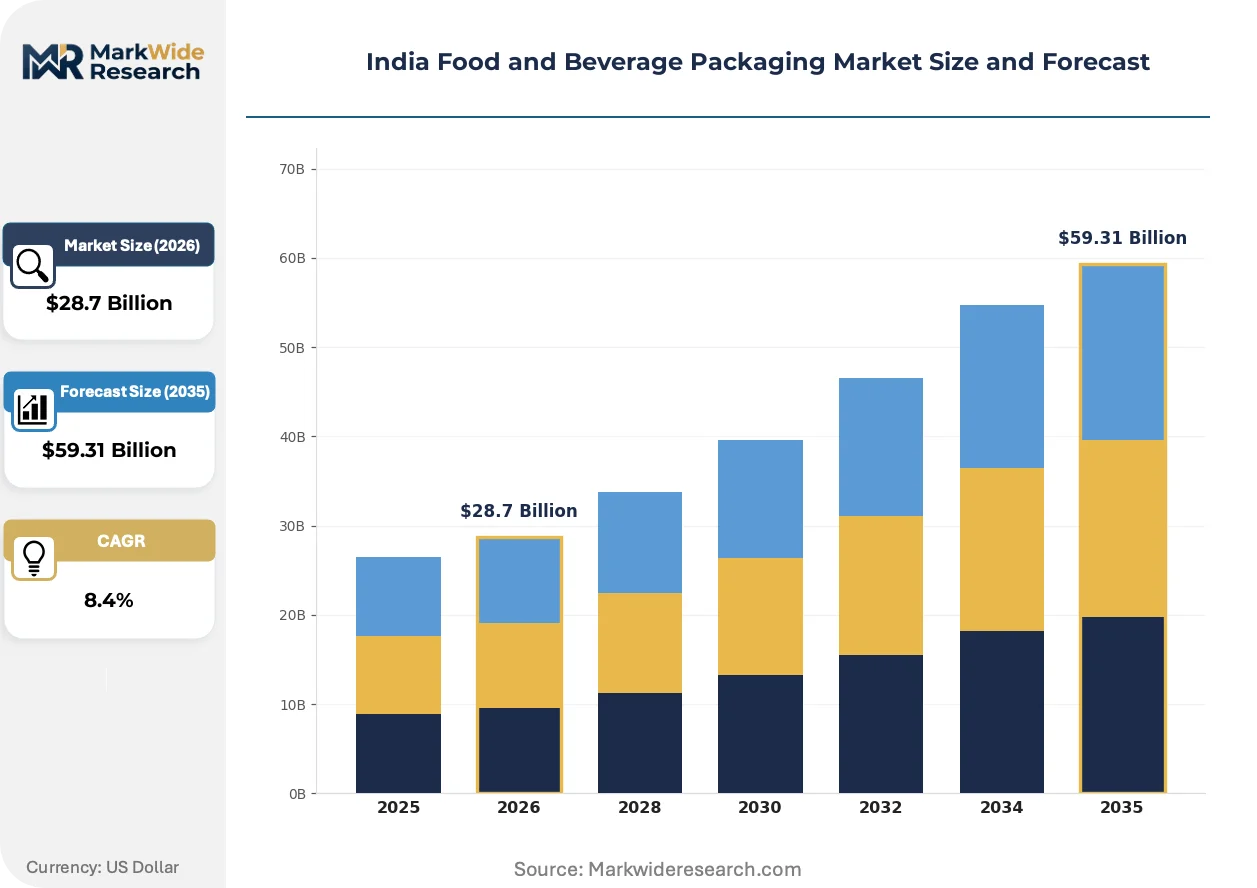
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Cans, Pouches, Boxes Material: Plastic, Paper, Metal, Glass End User: Restaurants, Retailers, Food Processors, Beverage Manufacturers Packaging Type: Flexible, Rigid, Vacuum Sealed, Thermoformed |
| Companies Covered | UFlex Ltd, Parekhplast India Limited, Essel Propack Ltd, Huhtamaki India Ltd, Pearl Polymers Ltd, AGI Greenpac Ltd, TCPL Packaging Ltd, EPL Limited, Manjushree Technopack Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Food and Beverage Packaging Market Shifts & Advancements
Digital printing and smart packaging technologies are collapsing minimum order quantities and enabling batch-level traceability, while regulatory pressure on plastic waste accelerates material science investment across substrate categories.
Digitally printed flexible packaging is decentralizing production economics for regional dairy and snack brands that previously faced prohibitive cylinder costs for short-run SKUs. Mid-sized processors in Karnataka and Telangana are adopting web-fed inkjet systems for seasonal promotional packs. This technology is decentralizing converter geography away from traditional gravure centers toward distributed, on-demand manufacturing nodes.
FSSAI's evolving food-contact plastics notification standards are tightening migration testing protocols for aromatic amines and heavy metals in printed laminates. Converter investments in solvent-free adhesive systems and electron beam curing are accelerating to preempt compliance gaps. Spices and masala mixes, with their aggressive oleoresin content, face the steepest reformulation timelines under these standards.
Quick commerce fulfillment models are compressing packaging specification cycles as Blinkit, Zepto, and Swiggy Instamart demand damage-proof, stackable formats for 10-minute delivery promises. Traditional corrugated secondary packaging is giving way to flexible primary packs with reinforced seals. Metro Indian consumers in Mumbai, Delhi, and Bangalore are driving volume for these engineered convenience formats.
India Food and Beverage Packaging Market Segmentation
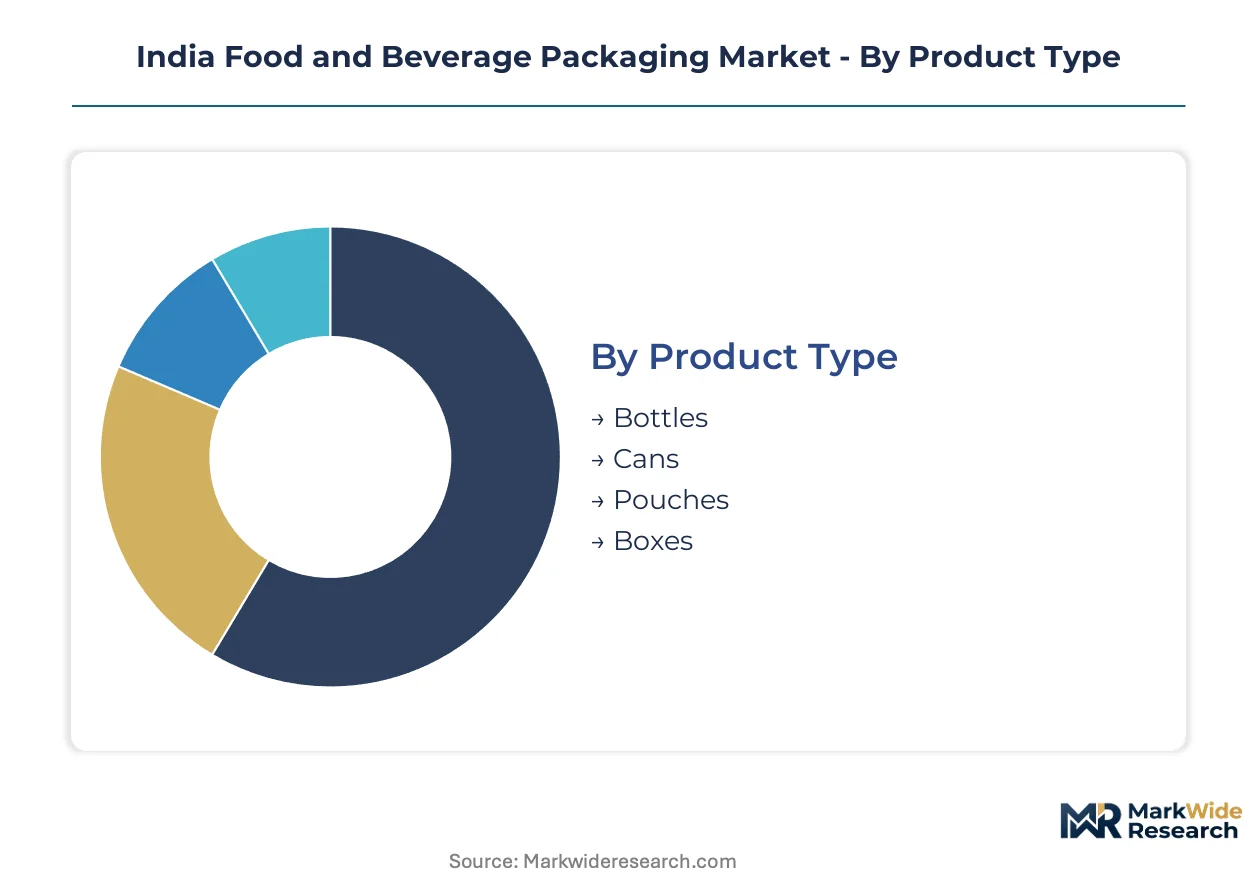
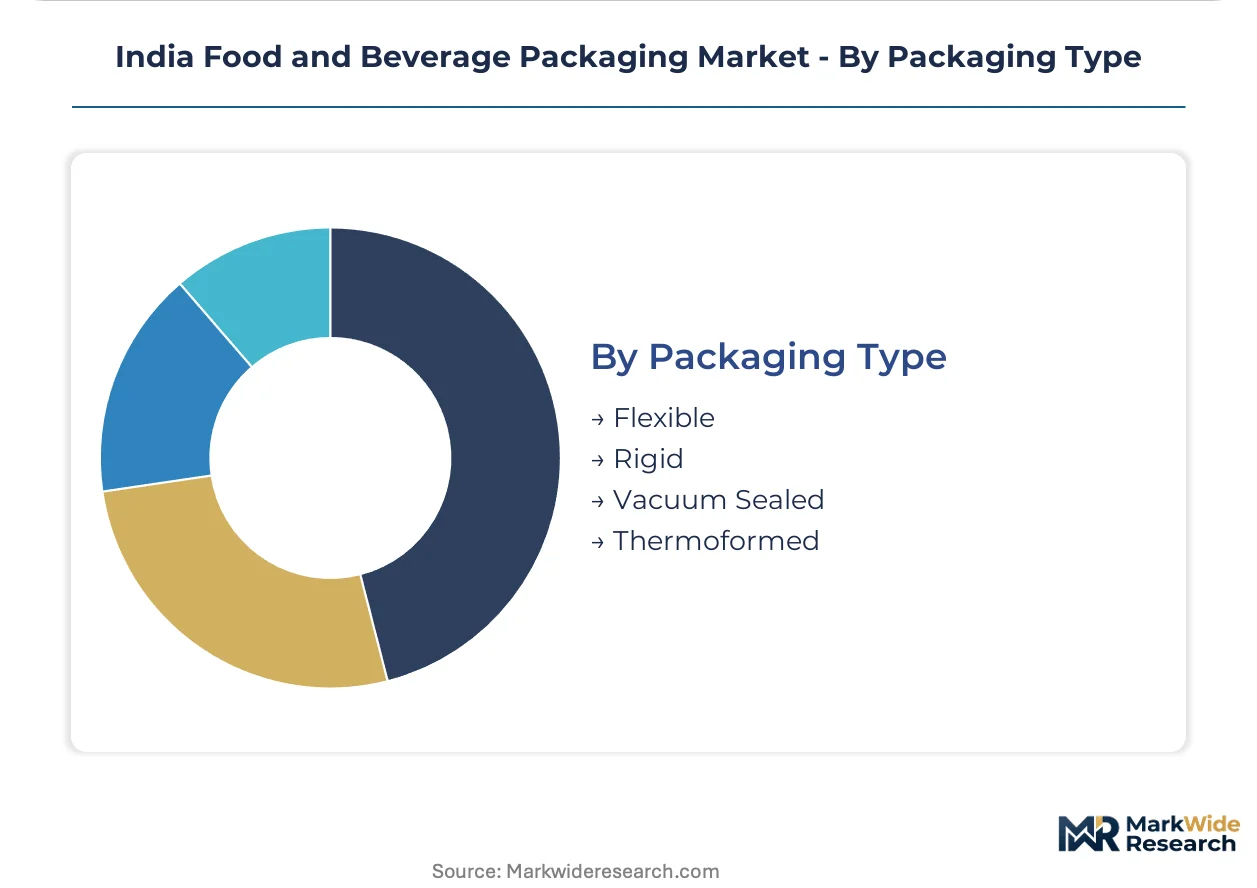
Segmentation in India's food and beverage packaging market reveals how substrate choices, format requirements, and end-user specifications create distinct procurement clusters. Each dimension carries different margin profiles and compliance burdens under FSSAI and BIS frameworks.
Product Type:
Replacement cycles vary dramatically across product type categories, with beverage bottles and condiment pouches turning over fastest due to single-use consumption patterns.
- Bottles:PET and HDPE blow-molded containers dominate carbonated drinks, edible oils, and dairy beverages. Maharashtra's beverage bottling corridors drive concentrated demand for lightweight, high-clarity PET with oxygen scavenger additives.
- Pouches:Multilayer laminates with metallized barriers enable ambient shelf stability for spices, snacks, and ready-to-cook gravies. Tier-two city convenience adoption is accelerating stand-up pouch specifications with resealable zipper closures.
- Cans:Two-piece aluminum and three-piece tinplate formats preserve carbonation in soft drinks and beer while supporting premium positioning for sparkling water.
- Boxes:Folding cartons and corrugated secondary packaging protect dry goods and gift assortments, with gravure-printed litho-laminated boards serving branded confectionery.
Bottles sits at the top of the volume ranking, with Pouches climbing the fastest.
Material:
Cost tier differentiation separates commodity substrates from performance-engineered alternatives, with recycled content mandates now restructuring procurement premiums.
- Plastic:Polyethylene, polypropylene, and PET films offer material efficiency and seal integrity for flexible formats. FSSAI migration limit enforcement is disqualifying non-certified converters from food-contact supply chains.
- Metal:Aluminum and tinplate deliver absolute barrier properties for oxygen-sensitive beverages and thermally processed foods. Western India's metallization capacity concentration creates supply vulnerability for ambient shelf-stable formats.
- Paper:Kraft boards and molded fiber formats gain share in quick-commerce secondary packaging as Blinkit and Zepto reject corrugated bulk for last-mile efficiency.
- Glass:Premium spirits and craft beverages retain bottle formats for brand heritage positioning, though transport economics limit distribution radius.
Plastic commands the highest shipment volumes, while Paper gains share fastest under EPR-driven substitution pressure.
End User:
Customer type determines specification complexity, with food processors demanding the most stringent barrier performance and traceability documentation.
- Food Processors:Dairy cooperatives and spice grinders require multilayer laminates with tailored moisture and oxygen barriers. Gujarat and Maharashtra processing clusters generate localized film manufacturing investment.
- Beverage Manufacturers:Carbonated soft drink and bottled water producers specify PET with acetaldehyde control and hot-fill compatibility for aseptic lines.
- Retailers:Private label sourcing from Reliance Retail and DMart pressures converters on minimum order quantities and print versioning flexibility.
- Restaurants:Food service disposables face shifting specifications as quick-service chains adopt paper-based alternatives to plastic under state-level bans.
Food Processors anchor material demand, with Beverage Manufacturers expanding most quickly on bottled water and functional drink proliferation.
Packaging Type:
Application requirements separate formats by shelf-life extension needs, with vacuum and modified-atmosphere systems commanding technology premiums over standard barriers.
- Flexible:Roll-fed and pre-made pouch formats achieve material efficiency ratios below rigid alternatives. Spices and snacks in Karnataka and Telangana drive digital print adoption for short-run promotional cycles.
- Rigid:Injection-molded tubs and thermoformed trays protect fresh produce and dairy with structural integrity for automated handling lines.
- Vacuum Sealed:Evacuated barrier pouches extend refrigerated meat and cheese shelf life, requiring specialized film coextrusion with nylon or EVOH core layers.
- Thermoformed:APET and CPET trays serve ready-meal segments with dual-ovenable compatibility, though mono-material transitions complicate legacy line retrofits.
Flexible leads absolute volume, with Vacuum Sealed gaining share fastest on processed meat and cheese format expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between states are redirecting flexible packaging investments toward jurisdictions with streamlined EPR registration and faster BIS certification timelines. Maharashtra and Gujarat maintain concentration advantages, while Karnataka and Telangana emerge as alternative production nodes.
Maharashtra
Mumbai-Pune industrial belt hosts India's densest cluster of gravure printing and metallization capacity. FSSAI's migration limit enforcement for food-contact plastics has professionalized converter qualification here. Dairy cooperatives in Nashik and Nagpur generate sustained demand for multilayer barrier films.
Gujarat
Anand and Vadodara dairy processing corridors anchor flexible pouch consumption for liquid milk and fermented products. The state's plastic waste management authority offers consolidated EPR documentation portals that reduce compliance overhead. Petrochemical feedstock proximity from Reliance Jamnagar complex stabilizes polymer substrate costs for local converters.
Karnataka
Bengaluru's quick-commerce fulfillment density is accelerating specification cycles for damage-resistant snack packaging. State-level incentives for packaging machinery manufacturing under the Karnataka Industrial Policy attract film extrusion investments. Mysuru and Mangaluru spice processing units drive seasonal digital print demand for promotional SKU versioning.
Tamil Nadu
Chennai-Coimbatore belt concentrates thermoformed tray production for ready-meal and fresh produce segments. The Tamil Nadu Plastic Waste Management Rules impose stricter post-consumer recycled content thresholds than neighboring states. Sriperumbudur electronics manufacturing spillover is creating hybrid demand for food-contact cleanroom packaging standards.
Telangana
Hyderabad's pharmaceutical packaging expertise is cross-pollinating into high-barrier food applications. The state's single-window clearance system for BIS certification compresses new product qualification timelines. Medak and Sangareddy industrial zones are attracting blown film investments to serve Deccan plateau dairy and edible oil processors.
India Food and Beverage Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty barrier coatings and digital print compatibility. The market structures around three distinct capability clusters: integrated film manufacturers controlling substrate costs, gravure-scale converters serving branded consumer goods, and mid-sized specialists in quick-commerce responsive formats. Competitive moves concentrate on mono-material line retrofits and solvent-free adhesive system upgrades.
Among integrated flexible packaging producers, UFlex Ltd exemplifies backward control over polymer substrate supply chains. Huhtamaki India Ltd occupies a position within specialty barrier coating segments for ambient shelf-stable applications. TCPL Packaging Ltd represents gravure-scale print capacity serving branded label and carton requirements.
| Leading Market Players |
|---|
| UFlex Ltd |
| Parekhplast India Limited |
| Essel Propack Ltd |
| Huhtamaki India Ltd |
| Pearl Polymers Ltd |
| AGI Greenpac Ltd |
| TCPL Packaging Ltd |
| EPL Limited |
| Manjushree Technopack Ltd |
| Others |
Supply & Pricing Matrix
Quick-commerce procurement specifications from Blinkit and Zepto are compressing order cycles and forcing converters toward flexible, short-run production formats that sacrifice scale economies for responsiveness. This demand-side shift is fragmenting pricing power across India's packaging value chain.
Pricing Analysis
Crude-linked naphtha volatility passes through to polyethylene and polypropylene substrate costs, squeezing converter margins on fixed-price annual contracts with dairy and snack processors. Three-tier pricing structure across premium, standard, and economy levels separates FSSAI-certified barrier laminates from commodity films and ungraded alternatives. Pricing pressure stems from Reliance Jamnagar petrochemical proximity in Gujarat, which stabilizes input costs for local converters while distant competitors absorb freight premiums. Private label retailers exhibit highest price sensitivity, while premium spice exporters prioritize migration-compliant certification over unit cost.
Supply Chain Analysis
Metallized barrier film capacity rests on a handful of western Indian producers clustered in Maharashtra and Gujarat, creating single-source vulnerability for ambient shelf-stable formats. Polymer substrates draw from Reliance's Jamnagar complex and imported Saudi and Singaporean resin streams. Distribution runs through dairy cooperative procurement networks in Nashik and Nagpur, snack processor hubs in Bengaluru, and quick-commerce fulfillment centers in Mumbai and Delhi. Tariff exposure on specialty adhesive imports from Germany and Japan compounds formulation cost uncertainty.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSSAI's tightening migration limit enforcement for food-contact plastics functions as a regulatory compounder, consolidating procurement toward certified converters and disqualifying informal suppliers from legitimate supply chains.
For Market Incumbents: Anchor market position through solvent-free adhesive system upgrades and mono-material line retrofits that preempt compliance gaps. Defend against emerging digital print specialists by investing in electron beam curing capacity for spice and masala mix applications. Prioritize backward integration into rPET and rPP feedstock streams ahead of draft BIS recycled content mandates. For New Entrants and Emerging Players: Regional dairy brands in Karnataka and Telangana face prohibitive gravure cylinder costs for short-run promotional SKUs, creating white-space opportunity for web-fed inkjet converters. Target quick-commerce responsive formats with damage-resistant, stackable primary packs that bypass traditional retail shelf aesthetics. Pursue pilot-scale biopolymer substitution in premium organic segments where PLA and PHA compatibility commands technology premiums. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-sized specialists possessing digital print infrastructure and quick-commerce channel relationships. Long-term viability favors converters with demonstrated FSSAI certification compliance and solvent-free adhesive capabilities. Watch EPR enforcement threshold announcements as the critical signal for capital reallocation timing toward mono-material structures.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Line Retrofit | Enables FSSAI-compliant recyclable structures ahead of EPR mandate escalation. |
| Solvent-Free Adhesive Upgrade | Preempts migration limit enforcement gaps for aggressive oleoresin spice applications. |
| Post-Consumer Recycled Content Integration | Positions converters for draft BIS rPET and rPP standards in food-contact applications. |
| Digital Print Capacity Addition | Serves Karnataka and Telangana dairy brands with short-run promotional flexibility. |
| Quick-Commerce Format Engineering | Captures Blinkit and Zepto procurement specifications for damage-resistant primary packs. |
Research Methodology
Bottom-up food processor and beverage manufacturer modeling reconciled against top-down polymer substrate and converter capacity tracking forms the analytical core. Primary interviews with dairy cooperative procurement managers, snack brand supply chain heads, flexible packaging plant engineers, and FSSAI regulatory affairs specialists combined with secondary validation from BIS certification databases, FSSAI notification records, customs polymer import data, and state-level plastic waste management authority filings. Triangulation across these sources ensures segment-level precision.
Historical trendline analysis of substrate cost pass-through, converter margin compression, and regulatory compliance investment patterns established baseline growth trajectories. The projection framework models volume and value across product type, material grade, end-user category, and packaging format dimensions, with CAGRs derived from trend extrapolation adjusted for EPR enforcement intensity and quick-commerce penetration rates. Forecast inputs include polymer feedstock price volatility indices and gravure cylinder engraving labor availability metrics.
Underlying measurement precision varies by segment; flexible pouch and digital print adoption carry tighter precision than thermoformed tray and glass bottle categories due to data availability asymmetry. Forecasts reflect documented assumptions on EPR threshold timing and biopolymer cost convergence. Feedstock volatility, metallization capacity bottlenecks, and state-level EPR documentation fragmentation warrant ongoing watch as revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Spreads and Toppings Packaging Market
Food Packaging
Lightweight Food Container Market
Food Packaging
PCR Packaging for Food and Beverages Applications Market
Food Packaging
United States Frozen Food Packaging Market
Food Packaging
Microwaveable Liquid Food Packaging Market
Food Packaging
Pie Packaging Market
Food Packaging
Spices, Dry Seasoning Mix, and Herbal Extract Packaging Market
Food Packaging
On the Go Food Packaging Market
Food Packaging
North America Frozen Food Packaging Market
Food Packaging
Cupcake Containers Market
Food Packaging
Food Packaging Market
Food Packaging
Disposable Food Containers Market
Food Packaging
Disposable Hot Cups & Lids Market
Food Packaging
Frozen Food Packaging Market
Food Packaging
Poultry Packaging Market
Food Packaging
North America PET Food Packaging Market