
 Cornstarch Packaging Market | 2026-2036
Cornstarch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Cornstarch Packaging Market Outlook
EU Green Deal enforcement is shifting the cost-of-entry calculus for conventional plastic alternatives across European manufacturing. NatureWorks LLC leverages its biopolymer expertise to sustain supply chain leadership in PLA resin production. Novamont S.p.A. anchors its position through proprietary Mater-Bi technology and Italian production scale. BioPak competes aggressively across foodservice channels with certified compostable product lines.
Cornstarch packaging comprises biodegradable materials derived from maize starch, typically blended with PLA or PBAT to achieve tensile strength between 15-40 MPa and thermal stability up to 55°C for food-contact applications. Films and bags dominate current volume given their penetration in fresh produce wrapping and e-commerce shipping, while containers command premium pricing due to higher material thickness and molding complexity. Food Industry end users represent the most mature demand pool, whereas E-Commerce channels exhibit the fastest expansion as fulfillment centers adopt void-fill loose fill alternatives to polystyrene.
EMA food-contact safety assessments, REACH chemical compliance protocols, and EU Green Deal carbon-border adjustments collectively shape material certification timelines and cross-border market access for cornstarch packaging suppliers. France's AGEC anti-waste law and Italy's CONAI packaging consortium fees further differentiate national compliance burdens within Europe. Stakeholders must monitor composting infrastructure build-out rates and certification harmonization between national schemes to align capacity investments with actual end-of-life processing availability.
Market Dynamics
The EU Green Deal is compressing compliance timelines for conventional plastic alternatives while composting infrastructure build-out lags material innovation cycles across European manufacturing corridors.
Growth Catalysts
- EU Green Deal carbon-border adjustments:France's AGEC anti-waste law mandates plastic reduction targets for foodservice operators, accelerating certified compostable packaging substitution in fresh produce retail.
- Food Industry procurement mandates:Restaurant chains and grocery retailers now specify biodegradable void-fill materials for e-commerce fulfillment, displacing expanded polystyrene from shipping channels.
- Composting infrastructure clustering:Germany, France, and Italy maintain the densest industrial composting facility networks, creating geographic pull for cornstarch packaging end-of-life processing.
Market Restraints
- Maize feedstock price volatility:Agricultural commodity swings directly compress resin cost structures for PLA and PBAT blend formulations.
- Thermal performance ceiling:Current cornstarch-based materials exhibit thermal stability limits near 55°C, restricting hot-fill and microwaveable food-contact applications.
- REACH chemical compliance timelines:ECHA substance evaluation protocols extend certification cycles for novel biopolymer additives, delaying cross-border market access.
Strategic Opportunities
- E-Commerce fulfillment channel expansion:Void-fill loose fill demand from automated distribution centers represents underpenetrated volume potential for starch-based alternatives to synthetic cushioning.
- Italy CONAI packaging consortium incentives:National fee structures favor compostable materials, creating regulatory tailwind for domestic production scale.
- PBAT-PLA blend optimization:Converging polymer science advances with blown film extrusion equipment upgrades enable thinner-gauge high-performance barrier films.
Industry Challenges
- Industrial composting certification fragmentation:Divergent national verification schemes between TÜV Austria, DIN CERTCO, and CIC create compliance complexity for pan-European suppliers.
- Biopolymer processing skill scarcity:Thermoforming and injection molding technicians trained on petroleum-based resins require retraining for starch-based material handling parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cornstarch Packaging Market |
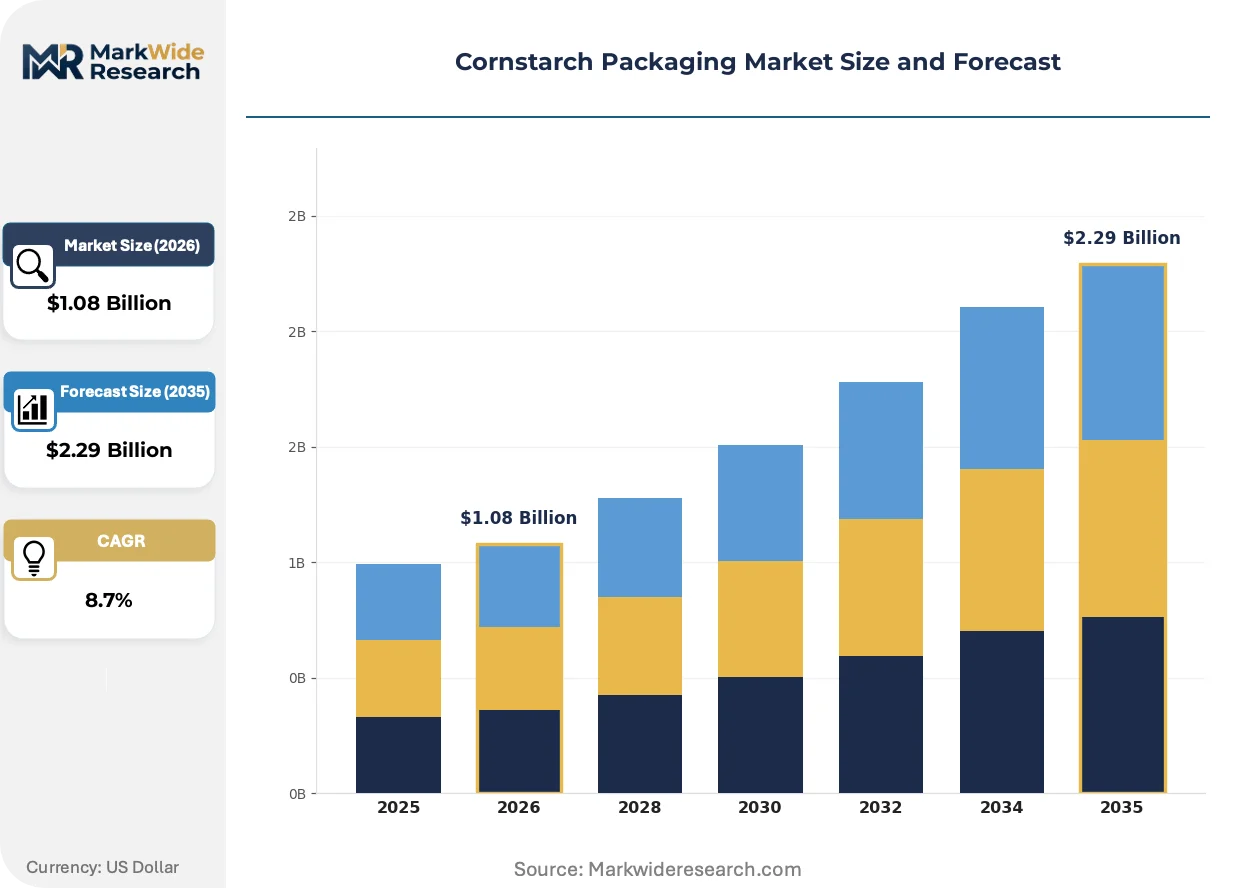
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $2.29 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Loose Fill, Bags, Films, Containers Application: Food Packaging, Biodegradable Products, Industrial Uses, Retail Packaging End User: Food Industry, E-Commerce, Retailers, Waste Management Distribution Channel: Direct Sales, Online Retail, Wholesale, Specialty Stores |
| Companies Covered | Team Recycler Malaysia, NatureWorks LLC, BioPak, Novamont S.p.A., Total Corbion PLA bv, Packnwood, L&P Packaging Ltd., Easy Green Eco Packaging Co., Ltd., Good Start Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cornstarch Packaging Market Strategic Shifts
Material science breakthroughs and enforcement tightening across European waste frameworks are compressing the viable window for conventional plastic packaging in food-contact applications.
Multilayer coextrusion technology is decentralizing barrier performance capabilities previously concentrated in petroleum-based films. Mid-size converters in the Netherlands and Belgium now deploy blown film lines capable of oxygen transmission rates below 5 cm³/m²/day for fresh protein packaging. This capability diffusion erodes the technical moat held by legacy flexible packaging specialists.
France's AGEC law enforcement is tightening material traceability requirements for foodservice packaging. Operators must now document compostability certifications for disposable tableware, driving procurement systems toward pre-approved supplier lists. Quick-service restaurant chains represent the most affected segment, with procurement departments restructuring vendor qualification protocols.
Certification-driven procurement preferences are fragmenting supplier concentration in food packaging channels. Buyers now weight TÜV OK Compost INDUSTRIAL and HOME labels equally with unit economics, compressing incumbent synthetic film margins. Germany's retail grocery sector exhibits the most pronounced shift, with private-label packaging specifications now mandating biodegradable alternatives for produce categories.
Cornstarch Packaging Market Segmentation
Cornstarch packaging suppliers configure production assets around distinct performance requirements and certification thresholds that vary sharply by product form and buyer procurement protocols. Segmentation reveals where material science investments concentrate versus where commoditization pressures dominate.
Product Type:
Buyers differentiate primarily by load-bearing requirements and barrier performance specifications rather than unit cost alone.
- Films:Multilayer coextrusion delivers oxygen transmission below 5 cm³/m²/day for fresh protein wrapping. Netherlands and Belgium converters now deploy blown film lines that displace legacy petroleum-based barriers in German retail produce specifications.
- Containers:Thermoformed vessels require higher material thickness and complex molding parameters, commanding premium positioning for prepared meal and foodservice applications where thermal stability to 55°C suffices.
- Bags:Penetration concentrates in fresh produce retail and e-commerce shipping where DIN CERTCO certification satisfies French AGEC compliance mandates.
- Loose Fill:Void-fill alternatives to expanded polystyrene attract automated fulfillment center procurement with lower density requirements and static-free handling properties.
Volume sits with Films; growth tilts toward Containers.
Application:
End-of-life processing infrastructure availability determines viable addressable market by application corridor.
- Food Packaging:Restaurant chains and grocery retailers now specify compostable tableware under France's AGEC law, with procurement departments restructuring vendor qualification around TÜV OK Compost INDUSTRIAL labels.
- Biodegradable Products:Agricultural mulch films and horticultural containers leverage Italy's CONAI packaging consortium fee structures that favor certified compostable materials.
- Retail Packaging:Private-label specifications in German grocery now mandate biodegradable alternatives for produce categories, compressing incumbent synthetic film margins.
- Industrial Uses:Manufacturing component wrapping and protective dunnage adopt starch-based formulations where ECHA REACH compliance timelines for novel additives have stabilized.
Revenue concentrates in Food Packaging; certification harmonization unlocks Industrial Uses.
End User:
Procurement sophistication and volume scale separate enterprise buyers from fragmented smaller accounts.
- Food Industry:Quick-service restaurant chains restructure supplier lists around material traceability requirements, with fresh produce retail exhibiting the most pronounced specification shifts.
- E-Commerce:Automated distribution centers represent underpenetrated demand for starch-based void-fill, displacing polystyrene from shipping channels as fulfillment operators hit sustainability targets.
- Retailers:German and French grocery private-label mandates now require compostable packaging for specified produce categories, driving volume through pre-approved supplier networks.
- Waste Management:Industrial composting facility operators influence upstream material specifications through certification requirements that vary between TÜV Austria, DIN CERTCO, and CIC verification schemes.
Contract value peaks with Food Industry; E-Commerce climbs the fastest.
Distribution Channel:
Channel selection reflects buyer scale and technical support requirements for material handling parameter training.
- Direct Sales:Large foodservice chains and grocery retailers negotiate frame contracts with technical service attachments for thermoforming and injection molding retraining from petroleum-based resin handling.
- Wholesale:Mid-size converters and packaging distributors aggregate demand across smaller food manufacturers and regional retail chains.
- Online Retail:Specialty biodegradable products and small-volume loose fill reach artisan food producers and boutique e-commerce operators.
- Specialty Stores:Catering supply and restaurant equipment channels serve independent operators with certified compostable tableware meeting local anti-waste law specifications.
Transaction volume flows through Wholesale; margin capture favors Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's CONAI packaging consortium fee structures and Germany's dense industrial composting networks create geographic pull for cornstarch packaging capacity investments. France's AGEC anti-waste law enforcement tightens material traceability requirements, while Dutch and Belgian converters deploy advanced coextrusion capabilities. Regulatory differentiation across national schemes fragments certification compliance burdens for pan-European suppliers.
Germany
Fresh produce retail chains and quick-service restaurant procurement departments mandate DIN CERTCO-certified compostable packaging. The country's national packaging consortium fees incentivize material substitution away from conventional plastics. Industrial composting facility concentration in Bavaria and North Rhine-Westphalia supports end-of-life processing availability for starch-based films and containers.
France
AGEC law enforcement requires foodservice operators to document compostability certifications for disposable tableware, restructuring vendor qualification protocols. The national anti-waste regulatory framework mandates plastic reduction targets with specific compliance timelines. Paris-based procurement departments for major grocery chains now specify biodegradable alternatives for private-label produce packaging.
Italy
CONAI packaging consortium fee structures favor certified compostable materials, creating direct cost advantages for cornstarch-based products. Novamont's proprietary Mater-Bi technology anchors domestic production scale in the Lombardy and Piedmont industrial corridors. Agricultural mulch film demand from Emilia-Romagna horticultural operations leverages national incentive structures for biodegradable alternatives.
Netherlands
Mid-size converters deploy multilayer blown film lines capable of oxygen transmission rates below 5 cm³/m²/day for fresh protein packaging. The country's logistics hub position serves German and French retail supply chains with just-in-time delivery requirements. Rotterdam-area distribution centers increasingly specify starch-based void-fill materials for e-commerce fulfillment sustainability targets.
Belgium
Coextrusion technology diffusion enables barrier performance capabilities previously concentrated in petroleum-based films. The country's converter base supplies French quick-service restaurant chains with certified compostable tableware meeting AGEC traceability requirements. Brussels-based regulatory proximity facilitates ECHA REACH compliance coordination for novel biopolymer additive certifications.
Cornstarch Packaging Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct technology and certification vectors. Market structure exhibits tiered concentration: biopolymer resin producers anchor upstream supply, mid-size converters dominate film and container fabrication, and branded foodservice distributors capture downstream margin. Strategic archetypes include proprietary technology licensors, toll-manufacturing specialists, and private-label house brands. Capacity expansion and certification portfolio diversification constitute the dominant competitive moves as compliance timelines compress.
Within the biopolymer technology tier, NatureWorks LLC and Novamont S.p.A. exemplify divergent geographic anchoring strategies. NatureWorks occupies a position tied to North American PLA resin production scale, while Novamont represents European-focused Mater-Bi technology deployment. Total Corbion PLA bv sits within the joint-venture archetype combining petrochemical and biotech parent capabilities. BioPak exemplifies the downstream-integrated foodservice distributor model with certified compostable product line concentration. These three named entities—NatureWorks LLC, Novamont S.p.A., and BioPak—anchor distinct competitive positioning vectors without overlapping strategic territory.
| Leading Market Players |
|---|
| Team Recycler Malaysia |
| NatureWorks LLC |
| BioPak |
| Novamont S.p.A. |
| Total Corbion PLA bv |
| Packnwood |
| L&P Packaging Ltd. |
| Easy Green Eco Packaging Co., Ltd. |
| Good Start Packaging |
| Others |
Value Chain & Pricing Dynamics
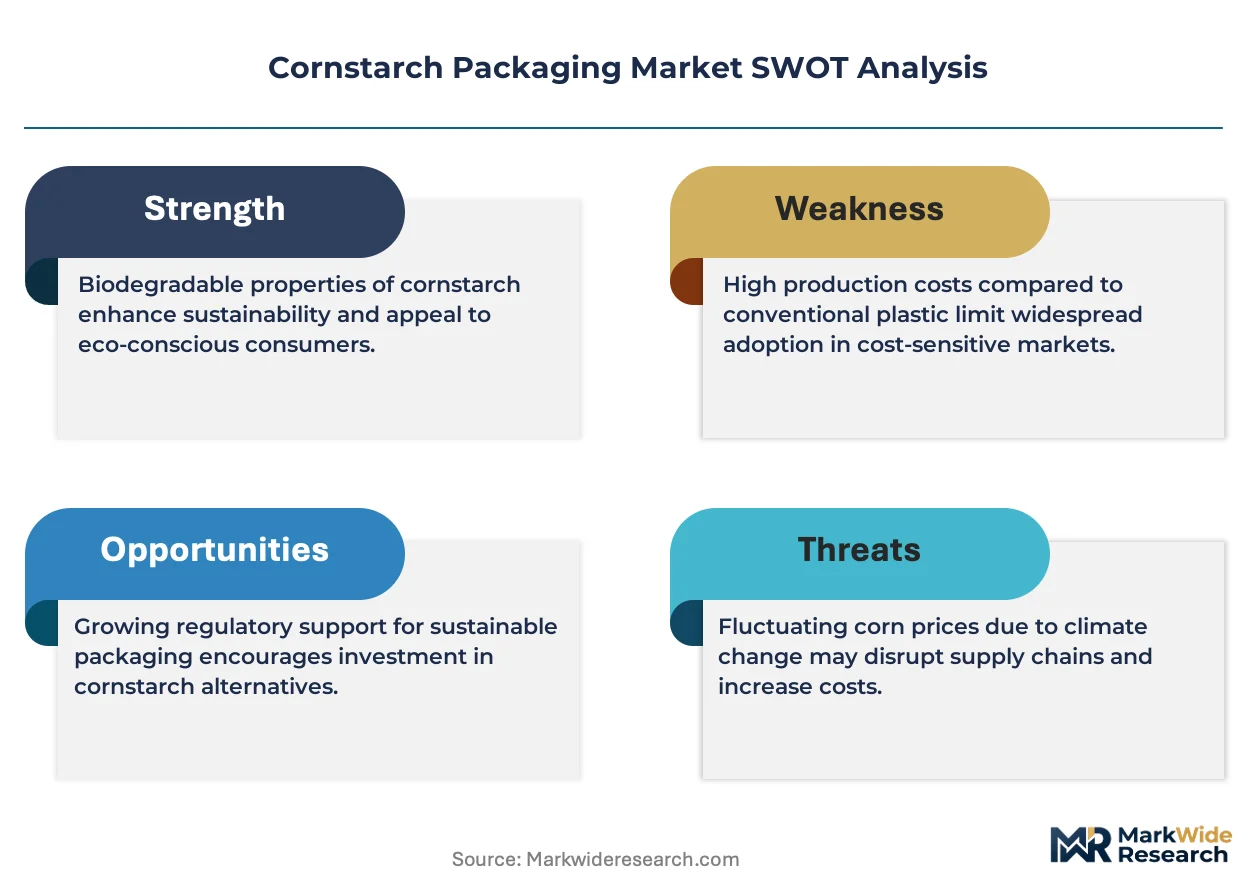
Maize feedstock costs transmit directly from agricultural commodity exchanges through PLA and PBAT resin pricing tiers, with Dutch and Belgian converters absorbing volatility through long-term offtake contracts while Italian producers leverage CONAI fee structures to offset raw material swings.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to DIN CERTCO-certified film orders from German retail procurement departments, while spot inventory of standard-grade loose fill commands minimal markup. Three-tier pricing structure across premium, standard, and economy levels separates TÜV OK Compost INDUSTRIAL-labeled containers from uncertified alternatives and commodity starch blends. Pricing pressure stems from maize price volatility compressing resin margins, particularly for mid-size converters without backward integration into biopolymer production. Quick-service restaurant chains exhibit highest price sensitivity due to procurement volume mandates, whereas pharmaceutical and fresh protein packaging buyers prioritize barrier performance over unit cost.
Supply Chain Analysis
Workforce availability for blown film extrusion and thermoforming operations concentrates in the Netherlands, Belgium, and northern Italy, where technical training programs for starch-based material handling have expanded. Resin production draws from NatureWorks facilities and Novamont's Lombardy operations, with compounding and conversion distributed across mid-size Dutch and Belgian processors. Single-source vulnerability exists for PLA resin supply given limited European production scale relative to demand growth. Distribution runs through direct frame contracts with large foodservice chains and wholesale aggregators serving regional retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over composting certification pathways and biopolymer resin supply determines margin capture and customer lock-in.
For Market Incumbents: Lock in resin supply security through long-term offtake agreements with PLA producers or captive compounding capacity, while expanding TÜV and DIN CERTCO certification portfolios to preempt regulatory fragmentation. Novamont's Mater-Bi technology licensing and NatureWorks distribution networks represent consolidation templates. Defend against mid-size converter encroachment by embedding technical service teams for thermoforming retraining at major foodservice accounts. For New Entrants and Emerging Players: Begin with e-commerce void-fill loose fill segments where automated fulfillment center procurement lacks established supplier relationships and sustainability targets create rapid qualification pathways. Netherlands-based distribution hubs serving German retail chains offer geographic white space with logistics advantages. Pursue private-label partnerships with grocery retailers seeking AGEC-compliant produce packaging alternatives. For Investors and Strategic Acquirers: CONAI packaging consortium fee structure adjustments in Italy are the leading indicator that national incentive alignment is accelerating compostable material substitution. Mid-size converters with multilayer coextrusion capabilities and established DIN CERTCO certification represent prime acquisition targets. Long-term viability hinges on composting infrastructure build-out rates matching material innovation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive PLA supply secures margin control against maize price volatility for Dutch converters. |
| Certification Portfolio Expansion | Dual TÜV and DIN CERTCO labels unlock pan-European procurement qualification for Italian producers. |
| Technical Service Embedding | On-site thermoforming retraining at French quick-service chains locks in multi-year supply contracts. |
| Void-Fill Product Line Launch | Starch-based loose fill displaces polystyrene from Rotterdam-area fulfillment center sustainability programs. |
| Joint Venture with Composting Operators | Partnerships with Bavaria industrial composting facilities secure end-of-life processing guarantees for German retail. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with biopolymer plant managers, procurement leads at German grocery retailers, technical R&D directors at Dutch converters, and composting facility operators. ECHA substance evaluation protocols, EU Green Deal implementation guidance, and national packaging consortium fee schedules provided regulatory context. Bottom-up demand modeling across foodservice, e-commerce, and retail channels triangulated against top-down resin production capacity estimates.
Granularity-level framing centered on product type, application corridor, and end-user procurement sophistication, with cross-segment variation in composting infrastructure availability modeled at national resolution. CAGRs derived from logistic growth curve fitting to historical adoption patterns, adjusted for regulatory enforcement timeline acceleration. Forecast inputs included maize price volatility scenarios and industrial composting facility build-out projections across Germany, France, and Italy.
Underlying measurement precision varies by segment; food packaging applications carry tighter precision than emerging industrial uses due to established procurement data availability. Forecasts reflect assumptions regarding EU Green Deal enforcement consistency and certification harmonization progress. Material deviation in maize feedstock pricing, composting infrastructure deployment, or REACH additive approval timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Bamboo Plate Market
Food Packaging
Food Punnets Market
Food Packaging
Egg Cartons Market
Food Packaging
Ready Meals Packaging Market
Food Packaging
PVDC Coating Food Packaging Market
Food Packaging
Transparent Food Packaging Market
Food Packaging
Global Disposable Plates Market
Food Packaging
Food and Drink Packaging Market
Food Packaging
Food Can Market
Food Packaging
Lightweight Food Container Market
Food Packaging
Food Tub Packaging Market
Food Packaging
Pizza Box Market
Food Packaging
North America Food Packaging Market
Food Packaging
Nordic Beverage Packaging Market
Food Packaging
Food Partition Trays Market
Food Packaging
Edible Oil Packaging Market