
 Food Tub Packaging Market | 2026-2036
Food Tub Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Food Tub Packaging Market Foresight
Ready-to-eat dairy and plant-based alternative demand is shifting the end-use mix toward higher-margin tub formats. Amcor plc leverages its global film and rigid plastics platform to supply barrier-enhanced tubs for extended shelf-life applications. Sonoco Products Company anchors North American dairy contracts through its composite can and rigid paperboard expertise. Huhtamaki OYJ competes in emerging markets with lightweight, decorated injection-molded tubs tailored to local brand aesthetics.
Food tub packaging denotes cylindrical, oval, or polygonal rigid containers—typically 100 ml to 5 L in capacity—engineered from thermoformed or injection-molded polymers, paperboard laminates, or aluminum, with hermetic sealing systems to protect against moisture ingress and oxidation. Polypropylene dominates material type selection due to its heat resistance and compatibility with in-mold labeling, though biodegradable plastics are gaining trial volumes in European private-label programs. Round tubs occupy the largest packaging type position across dairy and spreads, while multi-compartment tubs represent the fastest-growing configuration as snack manufacturers bundle dips, toppings, and bases in single-SKU offerings. Snap-on lids lead closure type adoption for resealability, yet tamper-evident lids command premium placement in retail channels where food safety assurance drives purchase decisions.
The FDA regulates direct food contact substances under 21 CFR, while the EU F-Gas Regulation and REACH constrain fluorinated barrier chemistries and additive migration limits respectively. India's FSSAI enforces packaging safety standards for dairy and processed foods, creating a multi-jurisdictional compliance burden for exporters. Stakeholders must monitor evolving extended producer responsibility frameworks and material certification schemes to secure market access and avoid reformulation delays.
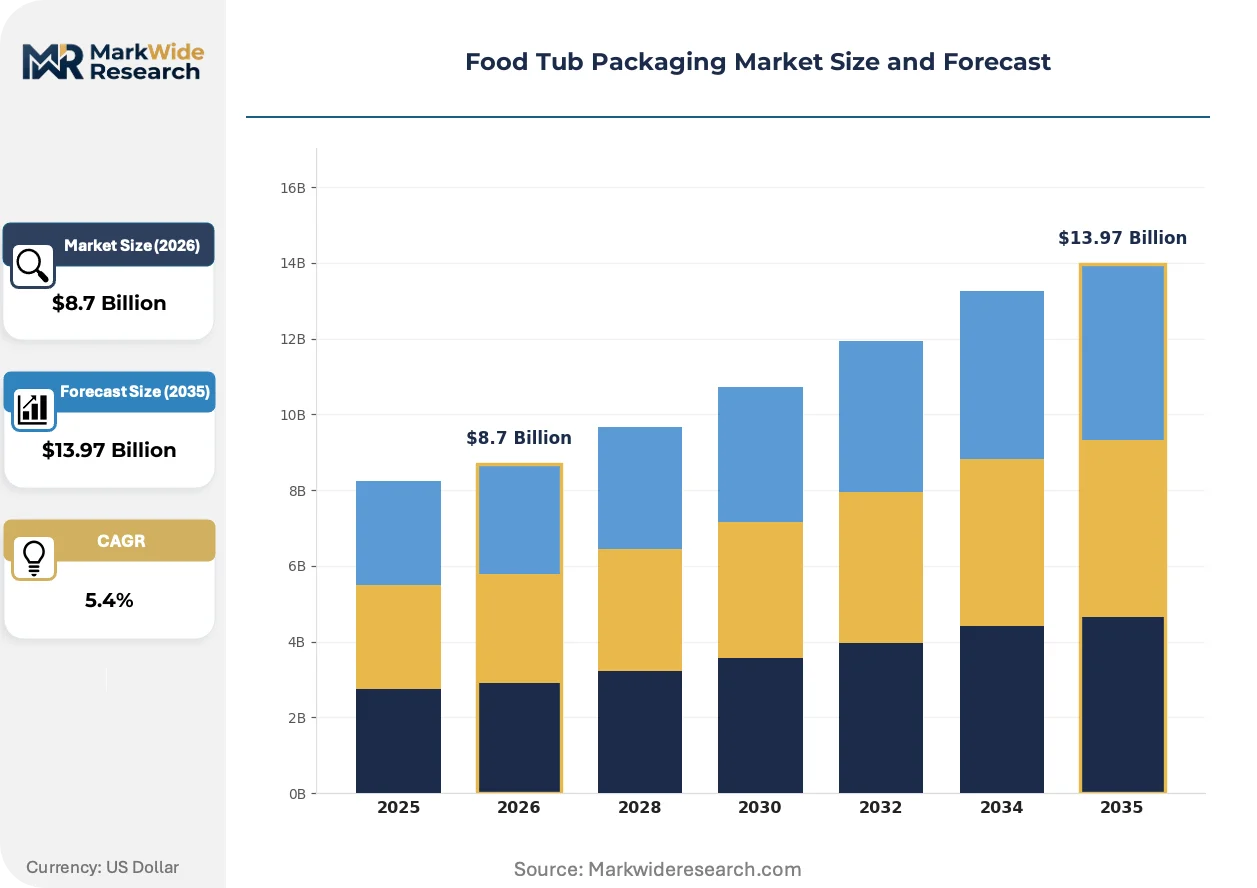
Market Dynamics
The EU Single-Use Plastics Directive is forcing dairy processors and food manufacturers to abandon conventional polypropylene tubs in favor of certified biodegradable alternatives, compressing reformulation timelines and supplier qualification windows across European supply chains.
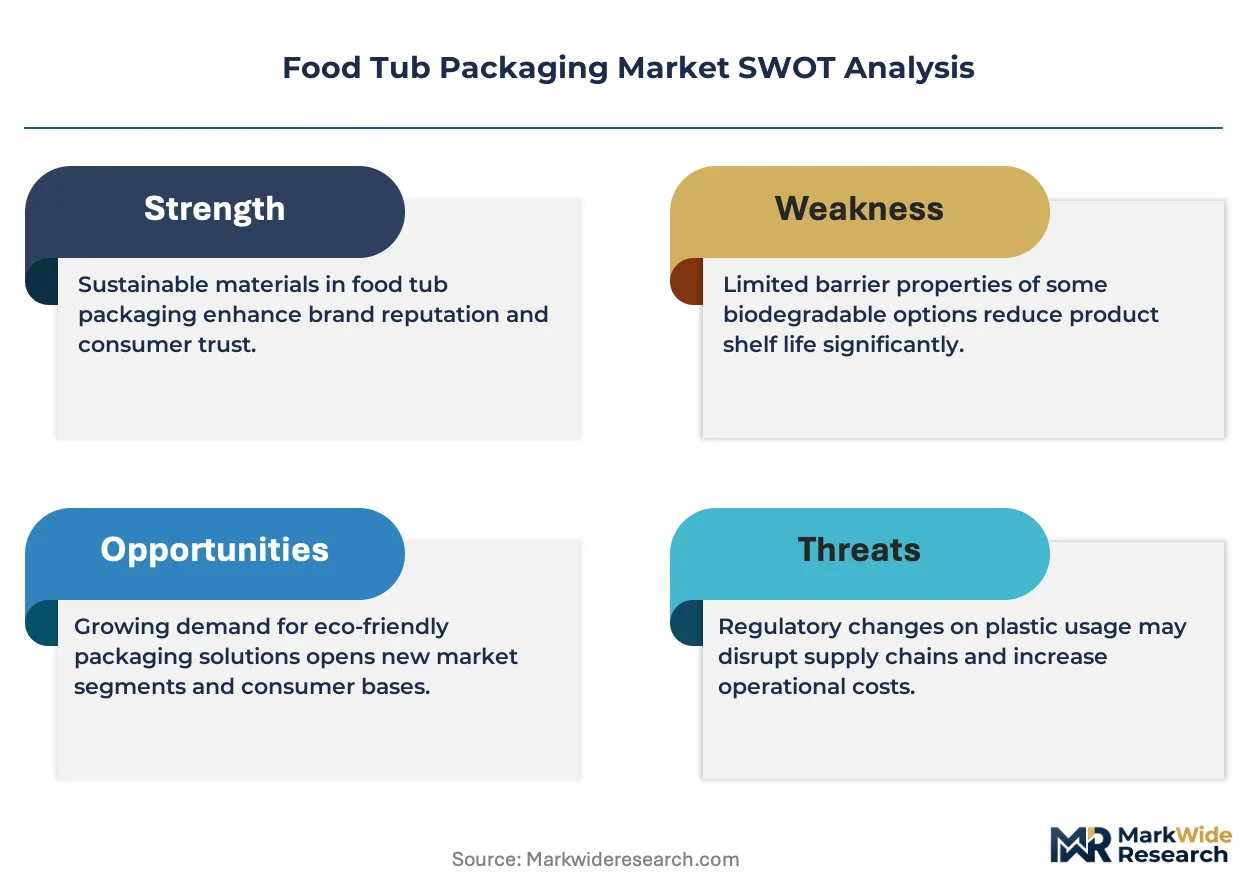
Growth Catalysts
- India's cold-chain expansion:Urban retail modernization and organized grocery penetration are pulling premium tub formats into mainstream dairy distribution, creating new volume anchors for injection-molded and thermoformed container suppliers.
- FSSAI packaging safety enforcement:India's tightening standards for dairy contact materials are disqualifying informal producers and consolidating demand around certified converters with documented migration testing capabilities.
- In-mold labeling adoption:Polypropylene tubs with integrated decoration are displacing sleeve-labeled alternatives in European private-label programs, reducing secondary packaging steps and enabling shelf-ready merchandising.
Market Restraints
- Biodegradable resin cost premiums:Polylactic acid and polyhydroxyalkanoate feedstocks trade at multiples of virgin polypropylene, compressing margins for converters serving price-sensitive European retail chains.
- Fluorinated barrier chemistry constraints:REACH and the EU F-Gas Regulation are restricting per- and polyfluoroalkyl substance use in high-barrier dairy applications, forcing reformulation of extended shelf-life tub structures without proven alternatives.
- Aluminum substitution in spreads:Grease-resistant paperboard tubs are capturing share in European margarine and butter segments, threatening rigid polymer demand in a historically core application.
Strategic Opportunities
- German biodegradable material standards:Emerging certification frameworks for industrial and home-compostable tubs are creating first-mover advantages for converters with validated biodegradation testing partnerships.
- Multi-compartment snack configurations:Manufacturers bundling dips, toppings, and bases in single-SKU offerings are driving demand for complex injection-molded tub geometries with integrated partition walls.
- Tamper-evident lid premiumization:Retail channels in India and Europe are awarding shelf placement premiums to tubs with visible integrity features, opening margin expansion for closure system innovators.
Industry Challenges
- Migration testing capacity bottlenecks:Laboratories qualified for EU 10/2011 and FSSAI additive migration protocols face six-month backlogs, delaying new product approvals and seasonal program launches.
- Legacy thermoforming asset stranding:Converters with deep investments in polypropylene sheet extrusion and pressure-forming lines face retrofit costs or obsolescence risk as biodegradable material processing requirements diverge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Tub Packaging Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polypropylene, Polystyrene, Polyethylene, Paperboard, Aluminum, Biodegradable Plastics Packaging Type: Round Tubs, Oval Tubs, Square Tubs, Rectangular Tubs, Multi-compartment Tubs Closure Type: Snap-on Lids, Peel-off Seals, Tamper-evident Lids, Hinged Lids, Shrink Bands End User Industry: Dairy Processors, Snack Manufacturers, Bakery Producers, Frozen Food Suppliers, Confectionery Makers |
| Companies Covered | Amcor plc, Sonoco Products Company, Huhtamaki OYJ, Berry Global Company, Magnum UK, Polyoak Packaging, Greiner Packaging, Pact Group Holdings Ltd, Parkers Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Tub Packaging Market Shifts & Advancements
Barrier engineering and decoration integration are compressing the traditional separation between primary containment and secondary branding functions, collapsing multiple conversion steps into single-pass tub production.
Thin-wall injection molding with sequential valve-gate control is modularizing dairy tub production, enabling converters to switch between 100 ml single-serve and 1 kg family formats on shared tool platforms. European yogurt processors are adopting these systems to reduce SKU-specific capital commitments. The technology is modularizing converter capacity allocation, allowing regional plants to serve fragmented brand portfolios without dedicated production lines.
REACH Annex XVII restrictions on intentionally added microplastics are reshaping European masterbatch formulations, compelling additive suppliers to validate non-polymeric alternatives for color and nucleation functions. Compounders serving the dairy tub segment are rebuilding formulation libraries to maintain food contact compliance. German and French converters face the tightest compliance windows as national enforcement agencies accelerate inspection protocols ahead of 2027 deadlines.
Indian quick-commerce channels are compressing order-to-delivery cycles for chilled dairy tubs from 24 hours to 90 minutes, forcing packers to pre-position decorated inventory closer to dark-store networks. Mumbai and Bangalore fulfillment hubs are demanding shelf-ready case counts and pallet configurations incompatible with traditional wholesale formats. Urban cold-chain density in these corridors is determining which converters capture share in the fastest-growing distribution channel.
Food Tub Packaging Market Segmentation
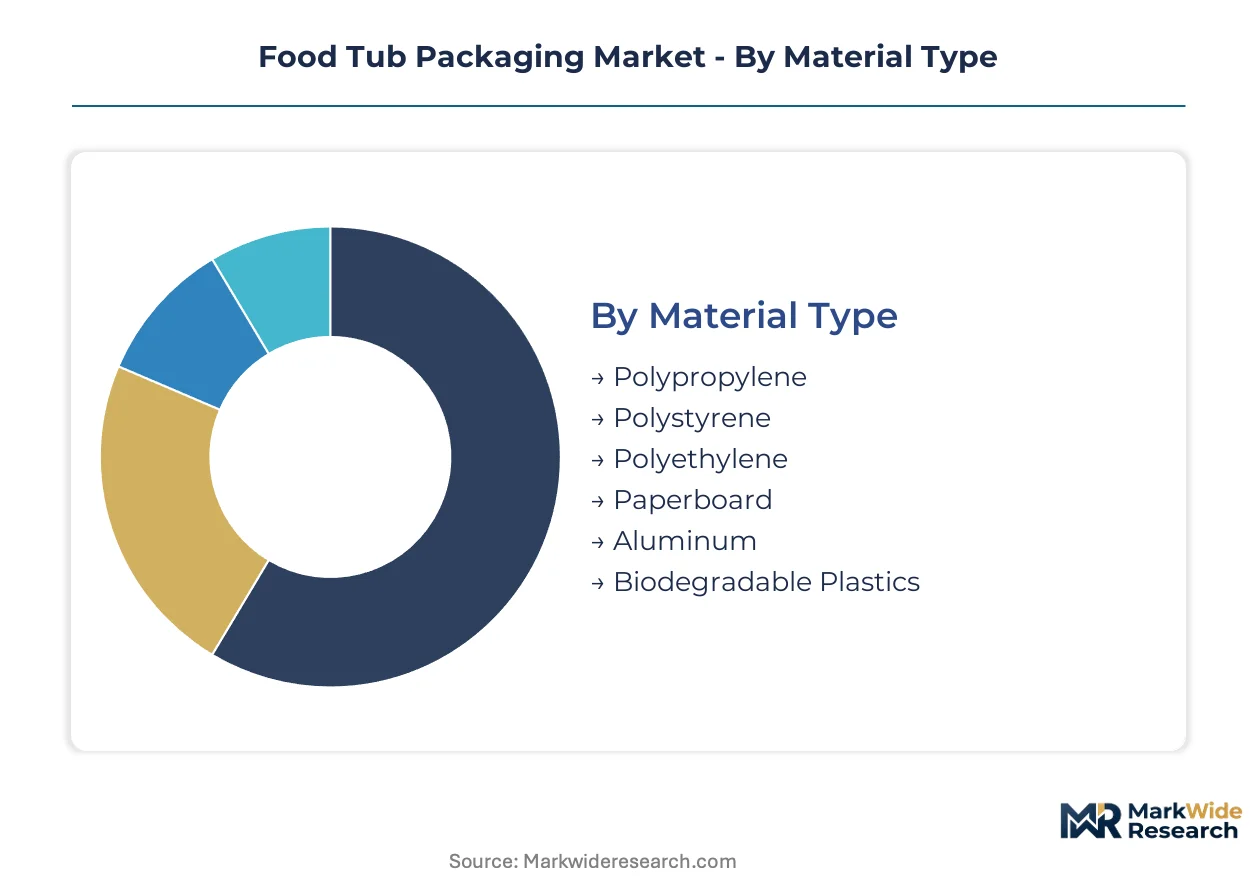
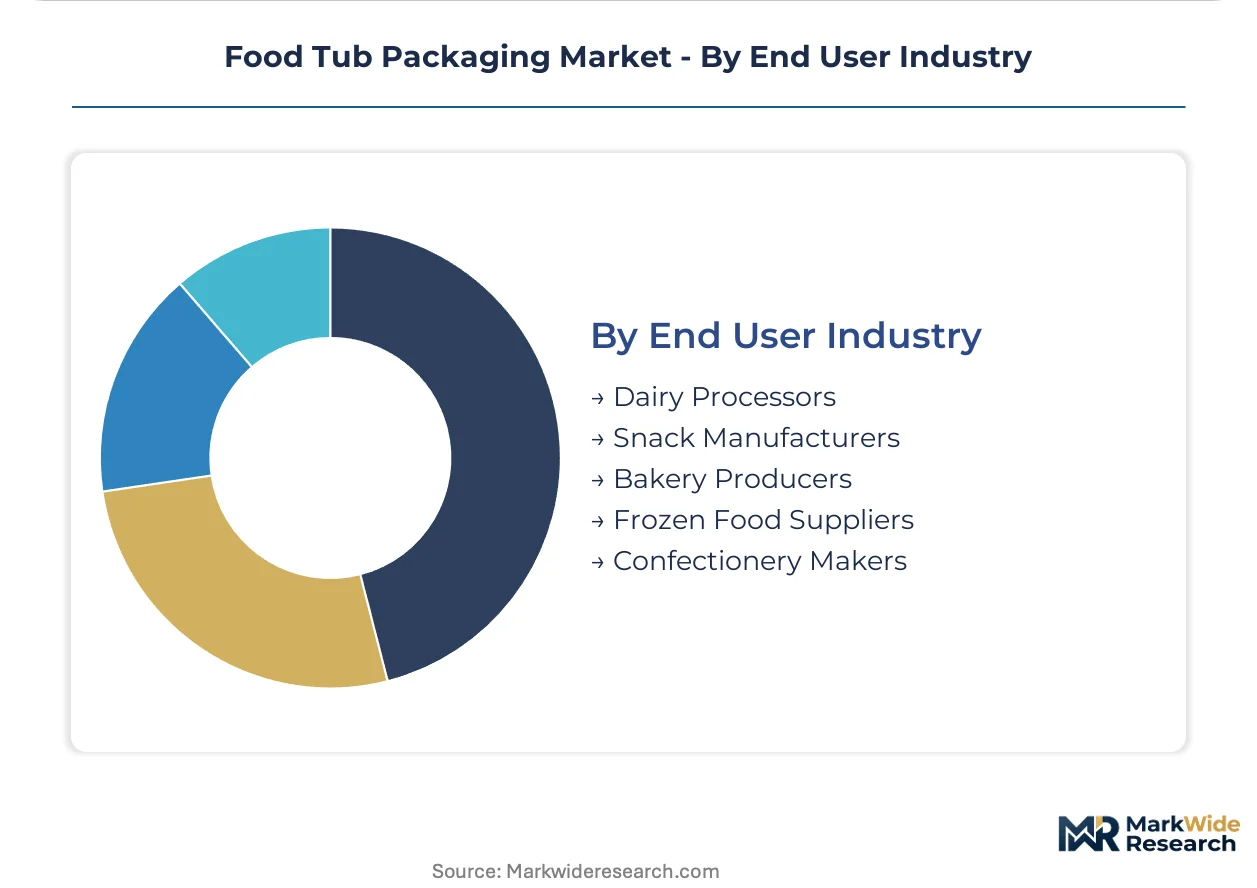
Food tub packaging segmentation reveals divergent margin structures across material chemistry and format geometry. Dairy processors and snack manufacturers drive distinct specification requirements, forcing converters to maintain parallel production capabilities.
Material Type:
Volume deployment clusters around commodity thermoplastics, while premium positioning attaches to certified biodegradable alternatives and barrier-enhanced substrates.
- Polypropylene:Heat-resistant polymer enables in-mold labeling integration and hot-fill dairy applications. Demand concentrates in European yogurt and spreadable cheese segments where extended shelf-life requirements dominate specification sheets.
- Biodegradable Plastics:Polylactic acid and polyhydroxyalkanoate formulations serve EU Single-Use Plastics Directive compliance programs. German retail chains are pulling trial volumes into private-label dairy lines ahead of certification deadline acceleration.
- Polystyrene:Crystal and high-impact grades occupy chilled dessert niches requiring clarity and dimensional stability.
- Polyethylene:Low-density formulations provide flexibility for squeeze-tub derivatives in condiment applications.
- Paperboard:Grease-resistant laminates capture European margarine and butter segments from rigid polymer incumbents.
- Aluminum:Premium spreads and specialty dairy formats leverage metal barrier properties for oxygen-sensitive contents.
Mature deployment sits with polypropylene across established dairy infrastructure. Newer deployment is concentrated in biodegradable plastics as regulatory compliance windows compress.
Packaging Type:
Format selection tracks filling line compatibility and retail shelf merchandising requirements rather than pure material cost optimization.
- Round Tubs:Rotationally symmetric geometry maximizes filling line throughput and minimizes seal variability. European dairy processors standardize on 125mm and 150mm diameters for yogurt and fromage frais production.
- Multi-compartment Tubs:Injection-molded partition walls enable single-SKU bundling of dips, toppings, and bases. Indian snack manufacturers are adopting these configurations for quick-commerce channels demanding meal-kit convenience.
- Oval Tubs:Elongated footprint differentiates premium spreads in refrigerated case placement.
- Square Tubs:Efficient pallet cube utilization drives adoption in foodservice and institutional dairy distribution.
- Rectangular Tubs:Modular stacking geometry suits frozen dessert and prepared meal applications.
Established infrastructure anchors round tub production across dairy heartlands. Format innovation is accelerating most quickly in multi-compartment configurations as snacking occasions fragment.
Closure Type:
Resealability and integrity assurance represent competing design priorities with divergent cost structures.
- Snap-on Lids:Polypropylene lid-and-rim systems provide repeatable resealability for multi-serve dairy formats. European private-label programs specify these for family-size yogurt and dessert applications.
- Tamper-evident Lids:Visible integrity features command shelf placement premiums in Indian organized retail where food safety assurance drives purchase decisions.
- Peel-off Seals:Foil laminates enable aseptic filling and extended ambient distribution for UHT dairy.
- Hinged Lids:Tethered closure designs reduce litter risk and support on-the-go consumption occasions.
- Shrink Bands:Secondary sleeve applications provide tamper evidence for gift and promotional formats.
Mainstream deployment clusters around snap-on lids for resealability functionality. Premium positioning is concentrating in tamper-evident systems as retail channel requirements tighten.
End User Industry:
Customer type determines specification complexity, with dairy processors maintaining the most stringent migration testing and barrier performance requirements.
- Dairy Processors:Yogurt, spreadable cheese, and dessert applications demand oxygen barrier performance and freezer-to-microwave thermal tolerance. FSSAI enforcement in India is consolidating demand around certified converters with documented EU 10/2011 testing capabilities.
- Snack Manufacturers:Dip, hummus, and prepared salad formats require grease resistance and high-definition decoration. Quick-commerce compression in Mumbai and Bangalore is forcing 90-minute order-to-delivery cycle compliance.
- Bakery Producers:Icing, frosting, and cream cheese formats specify moisture barrier and fat migration resistance.
- Frozen Food Suppliers:Ice cream and frozen dessert applications prioritize low-temperature impact resistance and condensation management.
- Confectionery Makers:Premium chocolate spread and specialty formats leverage metalized barrier structures for aroma retention.
Volume concentration remains with dairy processors across established cold-chain infrastructure. Specification complexity is expanding most steeply in snack manufacturing as channel fragmentation accelerates format diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany and the United States, while consumption growth concentrates in India and Southeast Asian markets where cold-chain infrastructure is expanding fastest.
Germany
Biodegradable material certification programs are accelerating converter qualification timelines for industrial compostable tubs. The country's national packaging regulator enforces strict biodegradation testing protocols under emerging DIN standards. Converter clusters in Bavaria and North Rhine-Westphalia are retrofitting thermoforming lines to process polylactic acid feedstocks for private-label dairy programs.
United States
Dairy processors in the Midwest and Northeast are demanding extended shelf-life barrier structures for Greek yogurt and specialty spreads. FDA regulates direct food contact substances under 21 CFR with migration testing requirements that favor established converters with documented compliance histories. Wisconsin and New York State host the densest concentrations of injection-molded tub production serving national distribution networks.
India
Urban cold-chain expansion in Mumbai, Bangalore, and Delhi-NCR is pulling premium tub formats into organized retail and quick-commerce channels. FSSAI enforces packaging safety standards for dairy contact materials that disqualify informal producers without migration testing capabilities. Converter capacity in Maharashtra and Gujarat is consolidating around certified suppliers capable of documented EU 10/2011-equivalent testing.
France
Grease-resistant paperboard tubs are capturing share in margarine and butter segments from traditional polymer formats. ANSM and national environmental agencies are accelerating inspection protocols for REACH Annex XVII microplastic restrictions ahead of 2027 deadlines. Industrial clusters in Île-de-France and Auvergne-Rhône-Alpes are rebuilding masterbatch formulation libraries to maintain food contact compliance.
China
Domestic dairy brands are adopting in-mold labeled polypropylene tubs for premium yogurt positioning in tier-one cities. SAMR and GB standards govern food contact material safety with evolving additive migration limits. Manufacturing concentration in the Yangtze River Delta and Pearl River Delta is serving both domestic consumption and export demand for barrier-enhanced container systems.
Food Tub Packaging Market Competitive Landscape
Top-tier vendors anchor global barrier film and rigid plastics supply, while mid-scale regional converters compete on decoration flexibility and local certification speed. The market exhibits tiered consolidation with three to five multinational material science groups controlling high-volume dairy contracts alongside specialized injection molders serving fragmented snack and prepared food segments. Strategic archetypes divide between integrated resin-to-container producers, decoration-technology specialists, and compliance-focused contract converters. Competitive moves concentrate on biodegradation certification partnerships and thin-wall molding technology licensing.
Among the named participants, Amcor plc and Sonoco Products Company occupy positions within the integrated materials tier, while Huhtamaki OYJ exemplifies the decoration-capable regional specialist archetype. These entities represent contrasting strategic postures: the first two anchor global supply relationships through multi-site production networks, while the third competes on localized brand aesthetics and emerging market responsiveness. Berry Global Company and Greiner Packaging sit within the European converter cluster where regulatory compliance investments are creating qualification barriers for smaller competitors. The collective positioning of these five entities illustrates how scale, geographic coverage, and certification depth are separating viable suppliers from margin-compressed challengers.
| Leading Market Players |
|---|
| Amcor plc |
| Sonoco Products Company |
| Huhtamaki OYJ |
| Berry Global Company |
| Magnum UK |
| Polyoak Packaging |
| Greiner Packaging |
| Pact Group Holdings Ltd |
| Parkers Packaging |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up converter specialists in Germany and the United States have compressed pricing discipline across European and North American dairy tub supply chains, linking margin protection to dual-source qualification mandates and certified migration testing investments. Their ownership structures enforce working capital efficiency that filters down to resin procurement and tool amortization schedules.
Pricing Analysis
Margin tightening in biodegradable-grade tub supply reflects polylactic acid and polyhydroxyalkanoate resin premiums trading at multiples of virgin polypropylene. Three-tier pricing structure across premium, standard, and economy levels separates EU Single-Use Plastics Directive-certified biodegradable formats from conventional polypropylene and unconverted paperboard alternatives. Price differentiation hinges on certification depth and documented EU 10/2011 migration testing. Price-sensitive European private-label retail chains squeeze converter margins, while premium Indian organized retail channels absorb tamper-evident lid premiums for food safety assurance.
Supply Chain Analysis
Dual-sourcing requirements from multinational dairy processors mandate qualified converter relationships across Germany, the United States, and India to mitigate single-source vulnerability from regional regulatory disruption. Raw material flows draw from Saudi petrochemical feedstocks for polypropylene, Brazilian sugarcane-derived polylactic acid, and Finnish wood pulp for grease-resistant paperboard laminates. Supply chain risk centers on REACH Annex XVII enforcement timelines compressing masterbatch reformulation windows. Distribution runs through regional dairy processor consolidation hubs in Wisconsin, Bavaria, and Maharashtra before final mile deployment to organized retail and quick-commerce dark stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards scale-driven consolidation as EU biodegradable certification deadlines and FSSAI enforcement in India force sub-scale converters without migration testing capabilities into exit or acquisition.
For Market Incumbents: Hedge against resin cost volatility through backward integration into polylactic acid compounding partnerships or captive polypropylene recycling streams. Defend share in European dairy by accelerating DIN-certified industrial compostable tub qualification ahead of smaller competitors facing six-month laboratory backlogs. Prioritize thin-wall injection molding technology licensing to modularize capacity across fragmented brand portfolios without dedicated production lines. For New Entrants and Emerging Players: FSSAI packaging safety enforcement in India opens a window for certified converters with documented EU 10/2011-equivalent testing capabilities to capture share from informal producers. Target Maharashtra and Gujarat dairy processor clusters where urban cold-chain expansion is pulling premium tub formats into quick-commerce channels. Lead with decoration-flexible in-mold labeling systems tailored to local brand aesthetics rather than commodity polypropylene supply. For Investors and Strategic Acquirers: Six-month migration testing laboratory backlogs are the leading indicator that certified converter capacity is becoming a scarce, defensible asset. Five-to-ten-year viability favors acquisition of mid-scale European or Indian converters with validated biodegradation testing partnerships and existing dairy processor qualification. Watch German DIN standard acceleration as the signal that industrial compostable certification depth will separate viable suppliers from margin-compressed challengers.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradation Certification Partnership | DIN and EU Single-Use Plastics Directive compliance secures private-label dairy contracts ahead of deadline acceleration. |
| Thin-Wall Injection Molding Licensing | Sequential valve-gate control technology enables format switching between single-serve and family-size tubs without dedicated lines. |
| Backward Integration into Compounding | In-house polylactic acid masterbatch formulation protects margins from resin premium volatility and REACH additive restrictions. |
| Quick-Commerce Distribution Pre-Positioning | Mumbai and Bangalore dark-store shelf-ready pallet configurations capture 90-minute order-to-delivery channel growth. |
| Migration Testing Capacity Expansion | EU 10/2011 and FSSAI-qualified laboratory investment reduces new product approval delays and seasonal program launch risk. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combining structured interviews with dairy procurement directors, converter plant managers, and food safety compliance officers with bottom-up and top-down triangulation. Primary fieldwork engaged migration testing laboratory technicians, quick-commerce fulfillment operators in Mumbai and Bangalore, and European retail category buyers. Secondary sources included EU 10/2011 additive migration databases, FSSAI packaging safety notifications, German DIN standard drafts, and U.S. FDA 21 CFR food contact substance registrations.
Granularity-level modeling tracked material type, packaging geometry, closure system, and end-use industry across the projection horizon, with segment-level CAGRs derived from volume deployment trajectories and value-per-unit shifts. The analytical framework incorporated cold-chain infrastructure expansion rates in Indian urban corridors, EU Single-Use Plastics Directive implementation phase-ins, and REACH Annex XVII enforcement acceleration timelines as industry-specific forecast inputs.
The model assumes a particular technology adoption path for biodegradable plastic processing; alternative pathways for polylactic acid thermoforming versus injection molding would alter the outlook for converter capital expenditure requirements. Forecasts reflect assumptions around regulatory deadline adherence and laboratory testing capacity expansion. Deviation in German national enforcement intensity or Indian quick-commerce order-to-delivery compression would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Desserts Packaging Market
Food Packaging
Ready Meals Packaging Market
Food Packaging
Food and Drink Packaging Market
Food Packaging
Cake Box Market
Food Packaging
Transparent Food Packaging Market
Food Packaging
Food Partition Trays Market
Food Packaging
Global Disposable Tableware Market
Food Packaging
Europe Food Packaging Market
Food Packaging
Nordic Beverage Packaging Market
Food Packaging
Honey Packaging Market
Food Packaging
Pet Beverage Packaging Market
Food Packaging
Hot Drinks Packaging Market
Food Packaging
Cupcake Containers Market
Food Packaging
Egg Packaging Market
Food Packaging
Spices, Dry Seasoning Mix, and Herbal Extract Packaging Market
Food Packaging
Seafood Packaging Market