
 PVDC Coating Food Packaging Market | 2026-2036
PVDC Coating Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
PVDC Coating Food Packaging Market Intelligence
The distribution model favoring large-volume contracts directly with food manufacturers is tilting the competitive balance toward integrated suppliers. Sealed Air leverages its Cryovac brand to offer complete packaging systems. Kureha Corporation sustains its market position through its deep expertise in PVDC resin production. Mondi Group competes by offering a diversified portfolio of both PVDC-coated and alternative barrier films.
PVDC coating food packaging involves applying a thin layer of polyvinylidene chloride onto substrates such as PET or BOPP films. This process creates an exceptional barrier against oxygen, moisture, and aroma transmission. Flexible films command the largest share among packaging types, used extensively for snacks and confectionery. Water-based coating technology is gaining traction over solvent-based methods due to lower VOC emissions.
Regulatory frameworks, including the US FDA's stipulations for food contact substances and the European Food Safety Authority's (EFSA) migration limits, govern material safety. These regulations create stringent performance and compliance hurdles for market participants. The central challenge for producers involves navigating the dual pressures of high-performance barrier requirements and the push for more sustainable, non-chlorinated packaging alternatives.
Market Dynamics
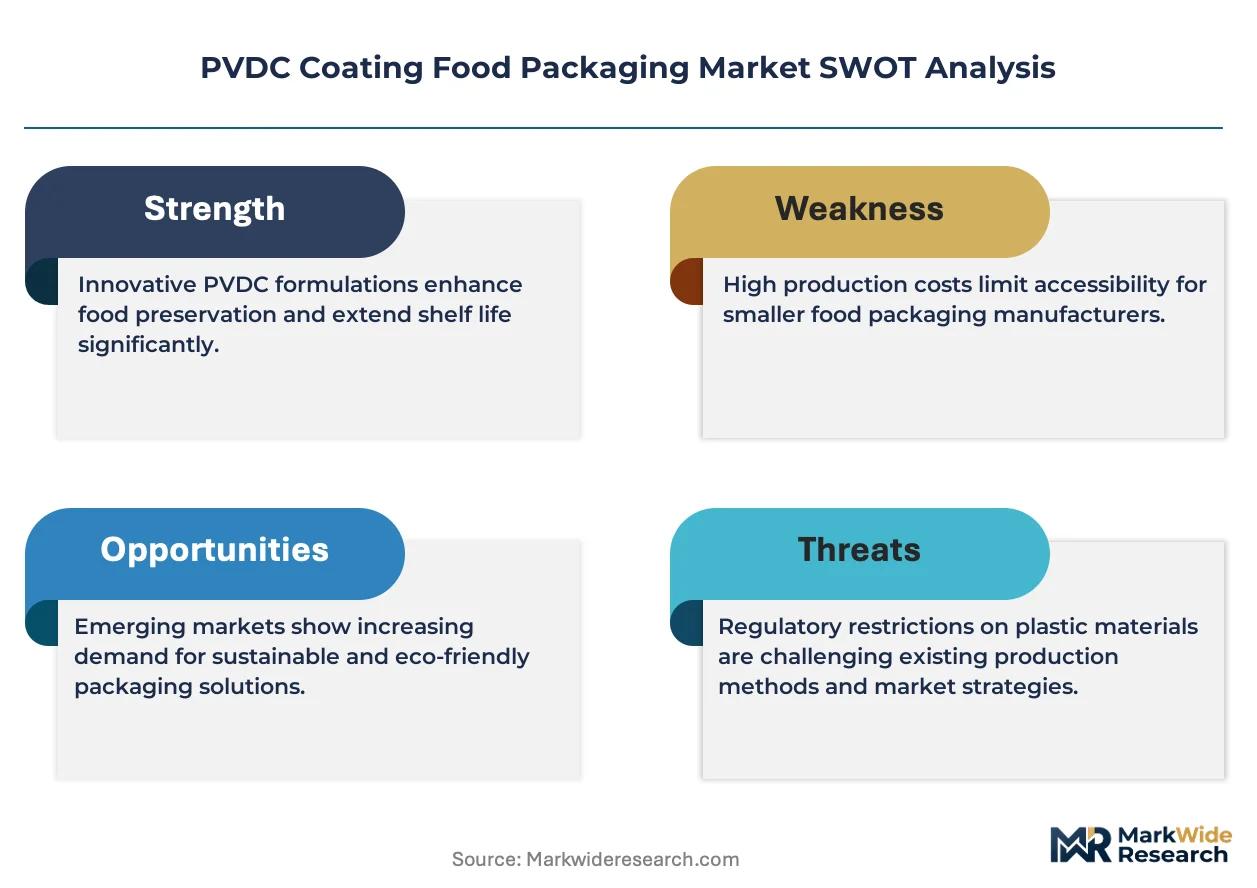
The central structural force shaping the PVDC coating food packaging market is the conflict between the material's unparalleled barrier performance and intensifying regulatory and consumer pressure to adopt non-chlorinated, more recyclable packaging alternatives. This dynamic compels innovation on two parallel tracks: improving PVDC's sustainability profile and developing competitive substitutes.
Growth Catalysts
- Dairy Product Preservation:The dairy sector's requirement for extended shelf life to reduce food waste and expand distribution reach provides a consistent demand pull for high-barrier materials like PVDC, particularly for cheese and yogurt packaging.
- China's Food Industry Scale:China's vast and expanding food processing industry, with its focus on packaged and convenience foods, represents a significant and geographically concentrated source of demand for PVDC-coated films.
- Water-Based Formulations:Advances in water-based PVDC coating technologies are lowering VOC emissions during application, helping manufacturers meet stricter environmental standards and mitigating some of the material's environmental critiques.
Market Restraints
- Environmental Scrutiny:Chlorinated polymers face sustained opposition from environmental groups and regulators, including frameworks like the EU Green Deal, which promotes circular economy principles and discourages materials perceived as difficult to recycle.
- Substitution from Alternative Polymers:The availability of high-performance, non-chlorinated barrier materials such as ethylene vinyl alcohol (EVOH) and various coated or co-extruded films presents a direct substitution threat in many applications.
- Resin Supply Concentration:The global production of PVDC resin is concentrated among a small number of chemical companies, creating potential for supply chain bottlenecks and significant pricing power that impacts downstream film converters.
Strategic Opportunities
- Recyclable Film Structures:Developing PVDC-coated mono-material film structures or effective delamination technologies that allow the barrier layer to be separated during recycling presents a significant opportunity to address end-of-life concerns.
- Southeast Asian Processed Foods:The growing middle class and increasing consumption of packaged foods in Southeast Asian nations offer an underpenetrated market for high-barrier packaging solutions to extend shelf life in humid climates.
- Pharmaceutical Blister Packaging:Expanding into high-value pharmaceutical applications, where PVDC’s superior moisture and gas barrier properties are critical for protecting sensitive medications, offers a pathway for margin expansion.
Industry Challenges
- Navigating Global Regulations:Manufacturers face the operational challenge of ensuring compliance with a complex and often divergent web of food contact regulations from bodies like the US FDA, Europe's EFSA, and China's SAMR.
- Capital Investment for Technology Transition:Upgrading production lines from older solvent-based coating systems to modern, lower-emission water-based technology requires significant capital expenditure, posing a barrier for smaller converters.
- Recycling Stream Incompatibility:The operational difficulty of integrating multi-layer PVDC films into existing municipal recycling streams, which are predominantly designed for mono-material plastics, remains a major hurdle to achieving circularity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVDC Coating Food Packaging Market |
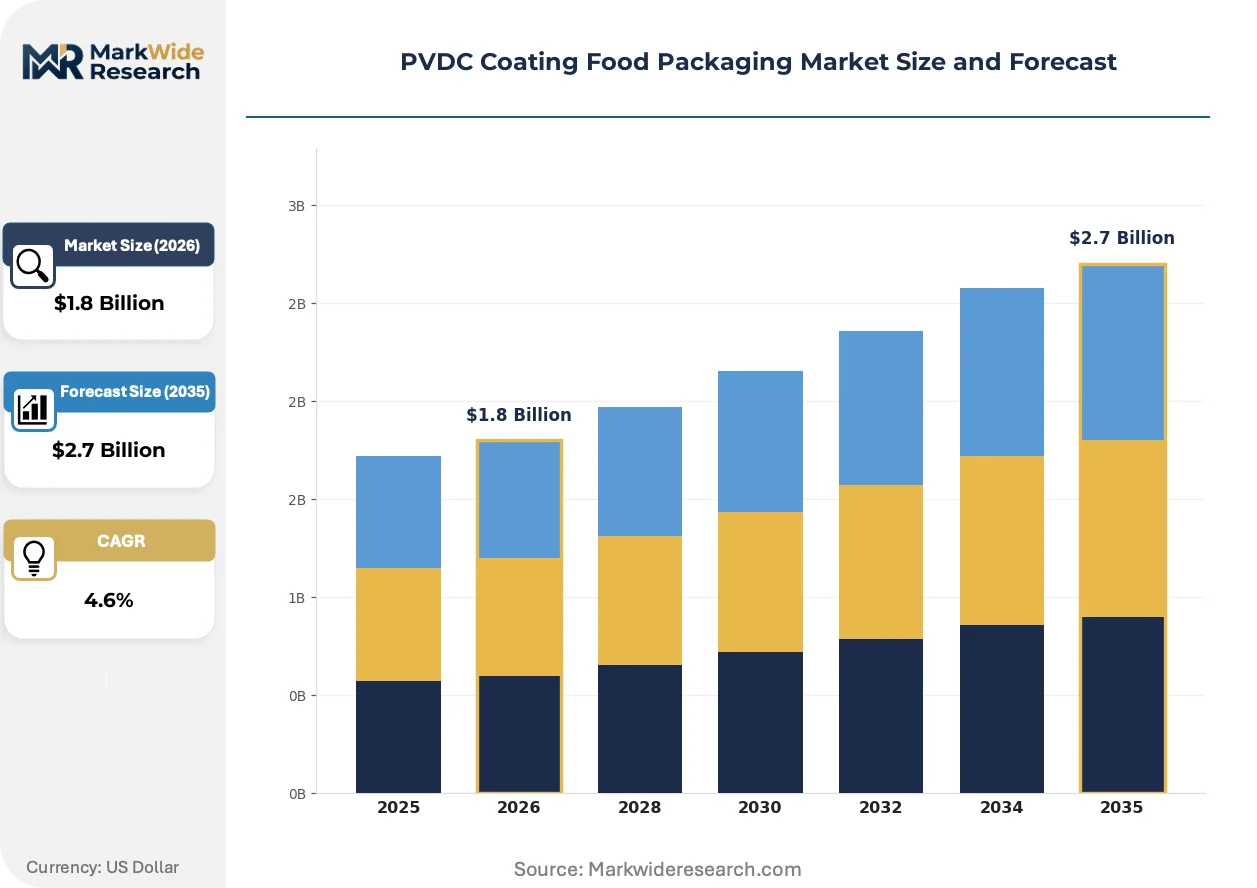
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Films, Rigid Containers, Pouches, Trays, Blisters Application: Bakery, Confectionery, Frozen Foods, Dairy Products, Snacks End User: Food Manufacturers, Foodservice Operators, Retail Chains, Catering Services Coating Technology: Solvent-Based, Water-Based, UV Curable, Extrusion Coating |
| Companies Covered | Cosmo Films, SKC, Cryovac, Kureha Corporation, Bilcare Solutions, Sealed Air, Krehalon, Mondi Group, Jindal Poly Films, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVDC Coating Food Packaging Market Strategic Shifts & Innovations
The market is defined by a fundamental push towards reconciling performance with sustainability. This is manifesting in the refinement of existing technologies to lessen their environmental impact while simultaneously exploring entirely new material science pathways to replace them in the long term.
Water-based PVDC coating technology provides a high-barrier layer while significantly reducing volatile organic compound (VOC) emissions compared to traditional solvent-based methods. Flexible packaging converters serving the snack and confectionery sectors are steadily adopting these aqueous dispersions to meet environmental regulations. The market's technological focus is migrating from legacy solvent-based systems to these more environmentally compliant formulations to maintain PVDC's position.
European Food Safety Authority (EFSA) regulations impose strict migration limits on substances that can transfer from packaging into food. This forces material suppliers and converters to conduct extensive testing and validation, increasing the cost and complexity of bringing new packaging formats to market. The retort pouch and hot-fill application segments are most affected, as elevated temperatures can accelerate the migration of chemical compounds.
A notable shift in buying behavior involves food manufacturers moving from procuring discrete packaging components to sourcing complete, integrated systems from a single supplier. This model disrupts traditional converters that specialize only in film or coating, favoring larger vendors who can provide the film, coating, and even the packaging machinery. This trend is particularly prominent within the North American processed meat industry, where supply chain efficiency is a primary competitive lever.
PVDC Coating Food Packaging Market Segmentation
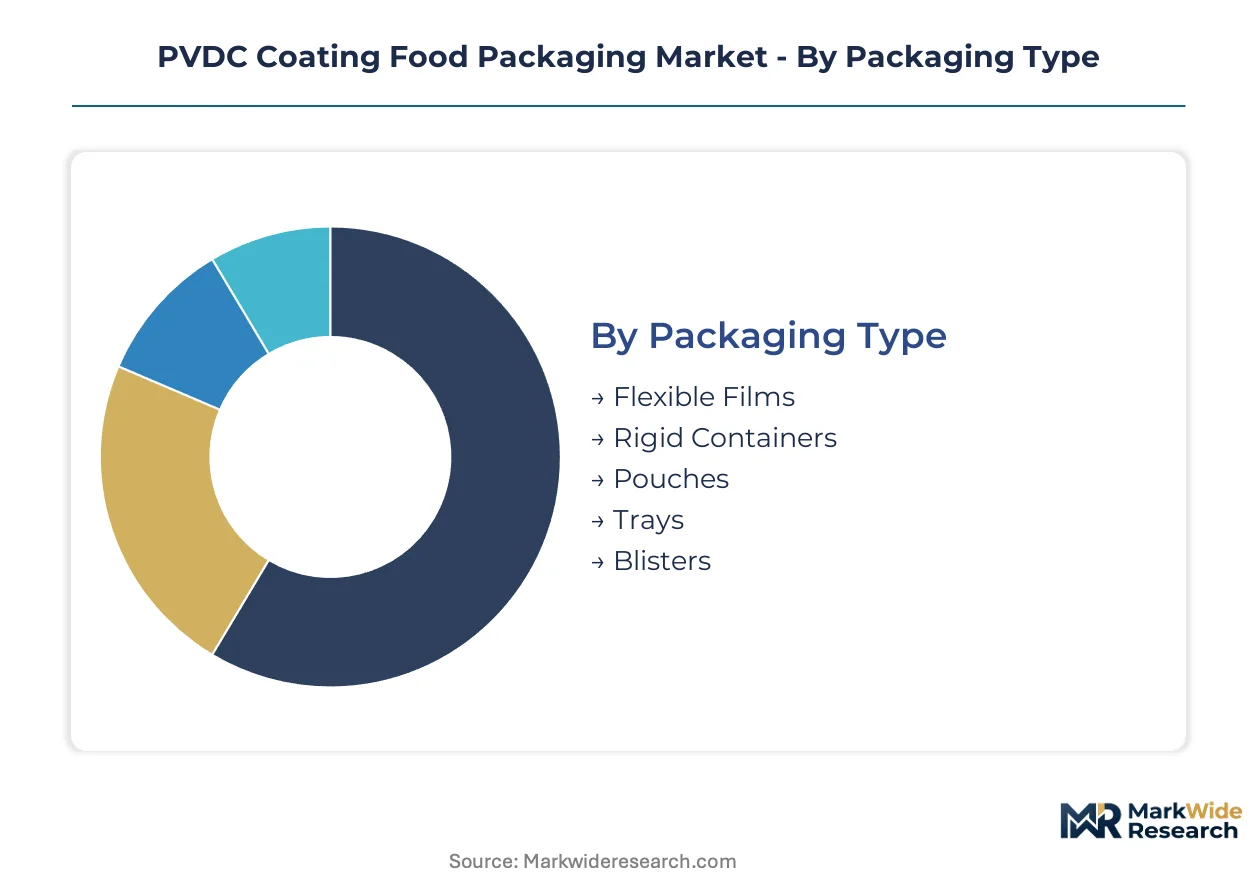
The PVDC coating food packaging market's segmentation reveals the diverse material requirements and application specificities across the food industry. Understanding these distinct segments helps identify key demand drivers and technological shifts influencing product development. This granular view highlights where innovation and investment are concentrating within the value chain.
Packaging Type:
Packaging formats for PVDC coatings exhibit varied consumption cycles, reflecting different product shelf-life requirements and distribution speeds.
- Flexible Films:These thin, pliable sheets, often made of PET or BOPP, receive PVDC layers to create superior oxygen and moisture barriers. Demand concentrates heavily in the snacks and confectionery sectors, where extended freshness is crucial for consumer appeal.
- Rigid Containers:PVDC coatings on rigid plastics or glass provide enhanced barrier properties for products requiring structural integrity and extended protection.
- Pouches:Multi-layer structures, frequently incorporating PVDC, offer convenience and extended shelf life for ready-to-eat meals, sauces, and pet food. The growing preference for flexible, lightweight packaging formats drives their adoption in emerging markets.
- Trays:Coated trays, particularly for fresh meat and dairy, leverage PVDC to prevent spoilage and maintain product quality throughout the cold chain.
- Blisters:Primarily used in pharmaceutical applications, PVDC-coated blister packs offer critical moisture protection for sensitive medications.
Flexible Films anchors the volume base while Pouches gains share at the steepest rate.
Application:
Applications for PVDC coating food packaging present diverse margin profiles, driven by product value, barrier requirements, and competitive intensity.
- Bakery:PVDC films protect baked goods like cakes and pastries from staling and moisture loss, preserving freshness.
- Confectionery:Candies and chocolates benefit from PVDC's barrier properties, which prevent moisture absorption and maintain product quality.
- Frozen Foods:PVDC coatings on packaging for frozen meals and vegetables help prevent freezer burn and maintain food quality during storage.
- Dairy Products:PVDC coatings are essential for cheese, yogurt, and other dairy items, providing critical oxygen and moisture barriers to prevent spoilage and extend shelf life. The dairy sector's focus on food waste reduction consistently pulls demand for high-performance packaging.
- Snacks:This segment extensively uses PVDC-coated flexible films to protect chips, nuts, and other savory snacks from moisture and oxygen ingress. Maintaining crispness and flavor integrity over long periods is a primary driver for PVDC adoption.
Dairy Products applications drive significant demand for extended shelf life, while the Snacks segment continues its broad-based expansion.
End User:
End-user segments for PVDC coating food packaging vary significantly by procurement scale and integration with packaging suppliers.
- Food Manufacturers:These entities represent the largest direct purchasers, often engaging in large-volume contracts for custom PVDC-coated films and systems. Their stringent quality control and supply chain efficiency requirements shape packaging innovation.
- Foodservice Operators:This segment procures PVDC-coated packaging for bulk ingredients and prepared meals, focusing on durability and barrier performance for extended use.
- Retail Chains:Increasingly, large retail chains specify packaging for their private label brands, influencing material choices and demanding sustainable barrier solutions. They prioritize shelf appeal and extended product freshness for in-store sales.
- Catering Services:Catering operations utilize PVDC packaging for transport and temporary storage of food, requiring reliable barrier properties to maintain freshness.
Food Manufacturers exert significant purchasing power, while Retail Chains increasingly influence packaging specifications for private label goods.
Coating Technology:
Coating technologies for PVDC reflect a transition toward more environmentally compliant and efficient application methods.
- Solvent-Based:Historically dominant, solvent-based PVDC coatings utilize organic solvents, offering excellent barrier performance but facing increasing pressure due to VOC emissions. Investment is shifting away from these legacy systems in regulated markets.
- Water-Based:This modern technology uses aqueous dispersions of PVDC, significantly reducing volatile organic compound (VOC) emissions during the coating process. Manufacturers are adopting water-based systems to meet environmental regulations and improve worker safety.
- UV Curable:UV-curable PVDC coatings offer fast curing times and lower energy consumption, finding niche applications where speed and specific barrier properties are critical.
- Extrusion Coating:This method integrates PVDC into multi-layer films during extrusion, providing a seamless barrier layer for various packaging applications.
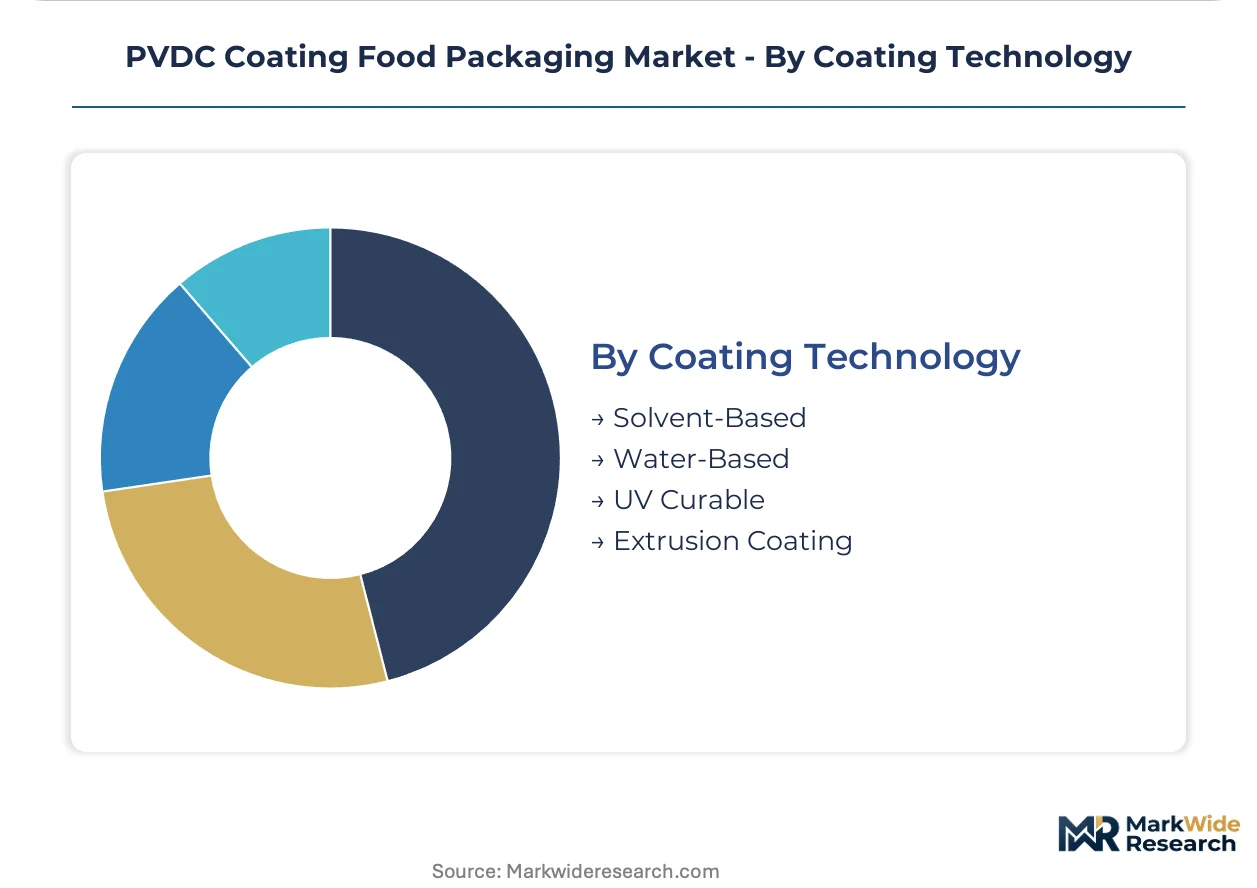
Water-Based formulations are steadily displacing Solvent-Based systems due to environmental pressures and regulatory shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global network of cold chain logistics, including refrigerated shipping lanes, underpins the widespread distribution of perishable food products. This infrastructure necessitates high-barrier packaging solutions like PVDC coatings to preserve food quality and extend shelf life during transit. Food manufacturers worldwide rely on these advanced materials to reach distant markets.
China
China's vast and expanding food processing industry, with its focus on packaged and convenience foods, drives significant demand for PVDC coatings. The State Administration for Market Regulation (SAMR) sets stringent food safety standards for packaging materials. The Yangtze River Delta region, a major manufacturing hub, sees significant investment in advanced packaging technologies.
United States
The United States' large processed food industry and consumer preference for convenience foods create consistent demand for PVDC-coated packaging. The US Food and Drug Administration (FDA) regulates food contact substances, ensuring material safety. The Midwest food processing belt, including Chicago, drives innovation in barrier packaging for diverse food products.
Germany
Germany's sophisticated food manufacturing sector places a strong emphasis on food safety and sustainability goals, impacting PVDC adoption. European Food Safety Authority (EFSA) migration limits directly influence packaging material selection in Germany. Bavaria, a center for advanced materials research, develops new water-based PVDC coating formulations.
India
India's rapidly urbanizing population and increasing consumption of packaged snacks and dairy products create a need for effective preservation in varied climates. The Food Safety and Standards Authority of India (FSSAI) establishes guidelines for food packaging materials. The National Capital Region (NCR), a major distribution hub, experiences rising demand for high-barrier flexible films.
Brazil
Brazil's large-scale dairy and meat production, coupled with a humid climate, requires robust moisture barriers for food packaging. Brazil's National Health Surveillance Agency (ANVISA) oversees food packaging material compliance. São Paulo, a key industrial and consumer market, sees significant adoption of PVDC-coated solutions for extended freshness.
PVDC Coating Food Packaging Market Key Industry Players
On the supply side, the industry is characterized by concentration among PVDC resin producers and fragmentation across downstream film converters. Integrated packaging solution providers offer complete systems, while specialized chemical companies focus on barrier resin innovation. Diversified film manufacturers compete by offering a range of coated and alternative barrier films. Strategic partnerships and technology licensing are common competitive moves to expand product portfolios.
Integrated suppliers leveraging strong brand recognition, such as Sealed Air with its Cryovac offerings, provide comprehensive packaging systems to food manufacturers. Specialized chemical companies, like Kureha Corporation, anchor the market through their deep expertise in PVDC resin production, providing foundational materials. Diversified packaging groups, exemplified by Mondi Group, occupy positions across both PVDC-coated and alternative barrier film segments, offering broad material portfolios to various end-users. These entities reinforce their market presence through continuous material science advancements and strategic customer engagement.
| Leading Market Players |
|---|
| Cosmo Films |
| SKC |
| Cryovac |
| Kureha Corporation |
| Bilcare Solutions |
| Sealed Air |
| Krehalon |
| Mondi Group |
| Jindal Poly Films |
| Others |
Cost & Logistics Intelligence
Commodity price volatility in key polymer feedstocks determines both pricing tier spreads and the overall supply chain shape for PVDC coating food packaging. This market navigates the dual pressures of high-performance barrier requirements and the push for more sustainable, non-chlorinated packaging alternatives.
Pricing Analysis
Volume-discount tiering structures dominate the PVDC coating food packaging market, reflecting the scale of orders from large food manufacturers. Price differentiation stems from the specific barrier performance required for applications like dairy, and the level of customization in film structures. Pricing softness reflects intense competition from alternative barrier materials and the pressure to meet sustainability mandates. Food manufacturers, particularly in the snacks segment, exhibit high price sensitivity due to their large procurement volumes.
Supply Chain Analysis
The upstream feedstock for PVDC resin production concentrates in a few global chemical companies, primarily in Japan, Germany, and the United States. This creates a single-source vulnerability for downstream film converters and packaging companies. Raw material dependencies include vinylidene chloride monomer for PVDC resin and base films like PET or BOPP. Distribution runs through integrated packaging solution providers and specialized film converters, who supply directly to food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents an early-cycle expansion story, driven by the consistent demand pull from the dairy sector for extended shelf life and reduced food waste.
For Market Incumbents:Build an intellectual property moat around advanced water-based PVDC coating technologies and recyclable film structures. This defends against the growing threat from high-performance non-chlorinated alternatives and strengthens market position. Invest in certifications for new PVDC formulations that meet stringent EFSA and FDA food contact regulations. Focus R&D on delamination technologies that improve the recyclability of PVDC-coated films.
For New Entrants and Emerging Players:Build out specialized capabilities in water-based PVDC coating applications, targeting underpenetrated markets like Southeast Asian processed foods. The pharmaceutical blister packaging segment offers a high-value niche with critical barrier requirements. A viable go-to-market angle involves offering sustainable, high-performance PVDC solutions that address specific regional climate challenges and regulatory demands.
For Investors and Strategic Acquirers:The EU Green Deal reshapes the acquisition landscape, favoring companies with proven sustainable barrier technologies or pathways to circularity. Long-term viability remains strong for firms specializing in high-barrier solutions where PVDC's performance is currently unmatched. Target acquisition archetypes include specialized water-based coating technology developers or companies with patented delamination processes. Quarterly review of material science breakthroughs and regulatory updates is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Water-Based PVDC R&D | Enhances environmental compliance and reduces VOC emissions for coating applications. |
| Develop Recyclable Mono-Material Structures | Addresses end-of-life concerns and aligns with circular economy principles. |
| Expand into Southeast Asian Markets | Captures growing demand for packaged foods in humid climates. |
| Secure Pharmaceutical Blister Packaging Contracts | Leverages superior barrier properties for high-value, sensitive medications. |
| Form Strategic Partnerships with Resin Producers | Ensures stable supply of PVDC resin and mitigates supply chain risks. |
Research Approach
Desk research of industry reports, regulatory filings, and academic literature preceded structured interviews with packaging engineers, food manufacturers, resin producers, and sustainability officers. This approach combined primary insights from industry stakeholders with secondary validation from publicly available data. Bottom-up and top-down triangulation ensured consistency across market sizing and forecasting models.
Assumption sets regarding global economic growth and regulatory stability were held fixed across the analysis window, while variations in raw material costs and technological adoption rates were modeled. The analytical framework segmented the market by packaging type, application, end-user, coating technology, and regional demand. Compound annual growth rates were derived from historical trends and projected market shifts, incorporating forecast inputs such as food processing industry growth and environmental regulation evolution.
Stress conditions across PVDC resin pricing and regulatory changes on chlorinated polymers were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding technological advancements and market dynamics. Quarterly review of material science breakthroughs and regulatory updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
PCR Packaging for Food and Beverages Applications Market
Food Packaging
Food and Drink Packaging Market
Food Packaging
Fresh Produce Trays Market
Food Packaging
Cupcake Containers Market
Food Packaging
Pie Packaging Market
Food Packaging
Probiotics Packaging Market
Food Packaging
Global Ambient Food Packaging Market
Food Packaging
Global Disposable Plates Market
Food Packaging
Desserts Packaging Market
Food Packaging
Food Partition Trays Market
Food Packaging
Disposable Hot Cups & Lids Market
Food Packaging
United States Frozen Food Packaging Market
Food Packaging
Food Punnets Market
Food Packaging
Nanotechnology for Food Packaging Market
Food Packaging
Transparent Food Packaging Market
Food Packaging
Asia-Pacific Skin Packaging for Fresh Meat Market