
 APAC Frozen Food Packaging Market | 2026-2036
APAC Frozen Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Frozen Food Packaging Market Outlook
Modular pouch-and-lid configurations is hardening as the dominant buyer preference across APAC frozen food channels, replacing monolithic box formats that limit microwave convenience. Amcor plc leverages its multi-layer film expertise to supply freezer-to-oven solutions for Australian retail chains. Sealed Air sustains technology leadership in vacuum skin packaging for premium seafood exports from Vietnam and Thailand. Berry Global Inc. anchors rigid container production through facilities in Malaysia and India, competing on scale against regional converters.
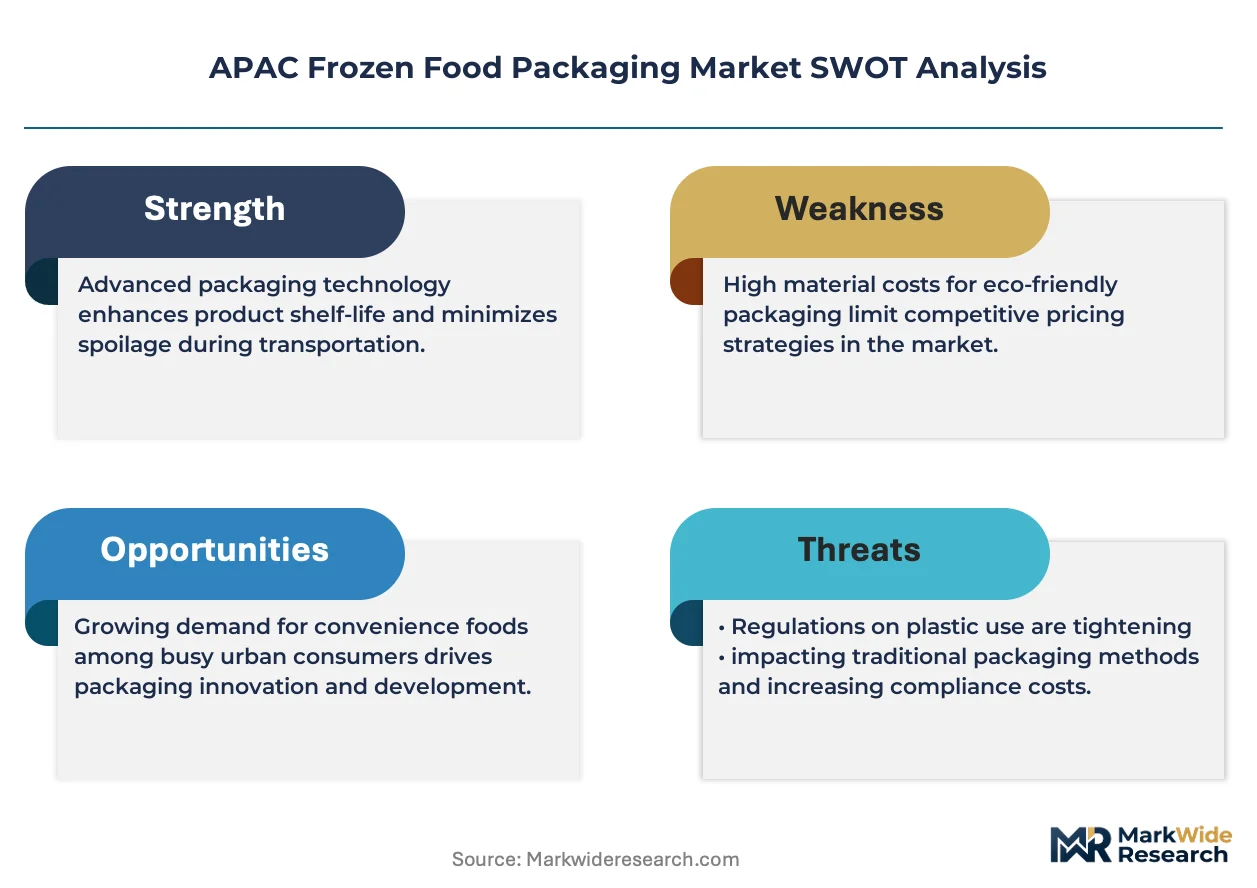
APAC frozen food packaging encompasses engineered barrier structures—typically multi-layer polyethylene terephthalate, ethylene vinyl alcohol copolymer, and oriented polypropylene laminates—designed to maintain sub-zero integrity, prevent ice-crystal nucleation, and preserve sensory quality across temperature fluctuations from blast freezing through retail display. Flexible packaging dominates volume for frozen vegetables and prepared meals due to logistics efficiency, while modified atmosphere packaging commands premium margins in seafood and ready-to-cook protein segments where shelf-life extension justifies higher unit costs. Composite materials are gaining share as brands seek to balance moisture barrier performance with sustainability positioning across Japanese and South Korean markets.
China's SAMR enforces GB standards for food-contact plastics in frozen applications, while India's BIS mandates specific migration limits for heavy metals and plasticizers in packaging destined for sub-zero storage. Japan's METI guidelines on recyclable packaging design are reshaping material selection for exporters targeting domestic retail compliance. Stakeholders must monitor evolving extended producer responsibility frameworks across Australia, South Korea, and Singapore, as these jurisdictions pilot deposit-return schemes that will redefine cost structures for multi-material frozen packaging formats.
Market Dynamics
Cold-chain infrastructure reliability improvements across Southeast Asia are unlocking frozen food distribution into previously unreachable urban corridors, forcing packaging specifications to harden against extended thaw-risk exposure during last-mile transit.
Growth Catalysts
- Quick Service Restaurant Expansion:Southeast Asian QSR chains are scaling frozen ingredient procurement as kitchen automation standardizes portion-controlled frozen inputs across Indonesia, Vietnam, and the Philippines.
- GB Standards Compliance:China's SAMR enforcement of stricter food-contact plastic migration limits for sub-zero applications is accelerating substrate upgrades among domestic converters serving frozen prepared meal brands.
- Barrier Film Innovation:Multi-layer EVOH laminates are penetrating mid-tier frozen vegetable segments previously served by monolayer polyethylene, preserving sensory quality through temperature fluctuation cycles.
Market Restraints
- Resin Supply Concentration:Ethylene vinyl alcohol copolymer feedstock depends heavily on petrochemical complexes in South Korea and Japan, creating input cost volatility when regional refinery utilization shifts.
- Recycling Infrastructure Gaps:Multi-material barrier structures face limited mechanical recycling pathways across APAC markets, with Japan's METI guidelines pressuring design-for-recyclability without matching collection-sorting capacity.
- Power Grid Reliability:Cold-chain integrity in Indonesia's urban corridor from Jakarta to Surabaya remains vulnerable to intermittent electricity supply, constraining frozen SKU distribution depth.
Strategic Opportunities
- Vietnam Seafood Export Premiumization:Vacuum skin packaging adoption for pangasius and shrimp value-added products commands margin expansion in EU and North American destination markets.
- India BIS Standard Alignment:Domestic converters achieving heavy metal and plasticizer compliance certification gain preferential access to modern retail frozen private label contracts.
- Microwaveable Format Convergence:Susceptor-equipped flexible pouches combining freezer storage with direct microwave heating are penetrating Australia's ready-meal channel, displacing rigid tray formats.
Industry Challenges
- Migration Testing Capacity:Laboratory certification backlog for GB standards and BIS compliance is extending product launch timelines by four to eight months for reformulated substrates.
- Converter Technical Workforce:Multi-layer coextrusion and adhesive lamination expertise concentrates in Malaysia and Thailand, creating talent scarcity for new entrants in India and Indonesia.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Frozen Food Packaging Market |
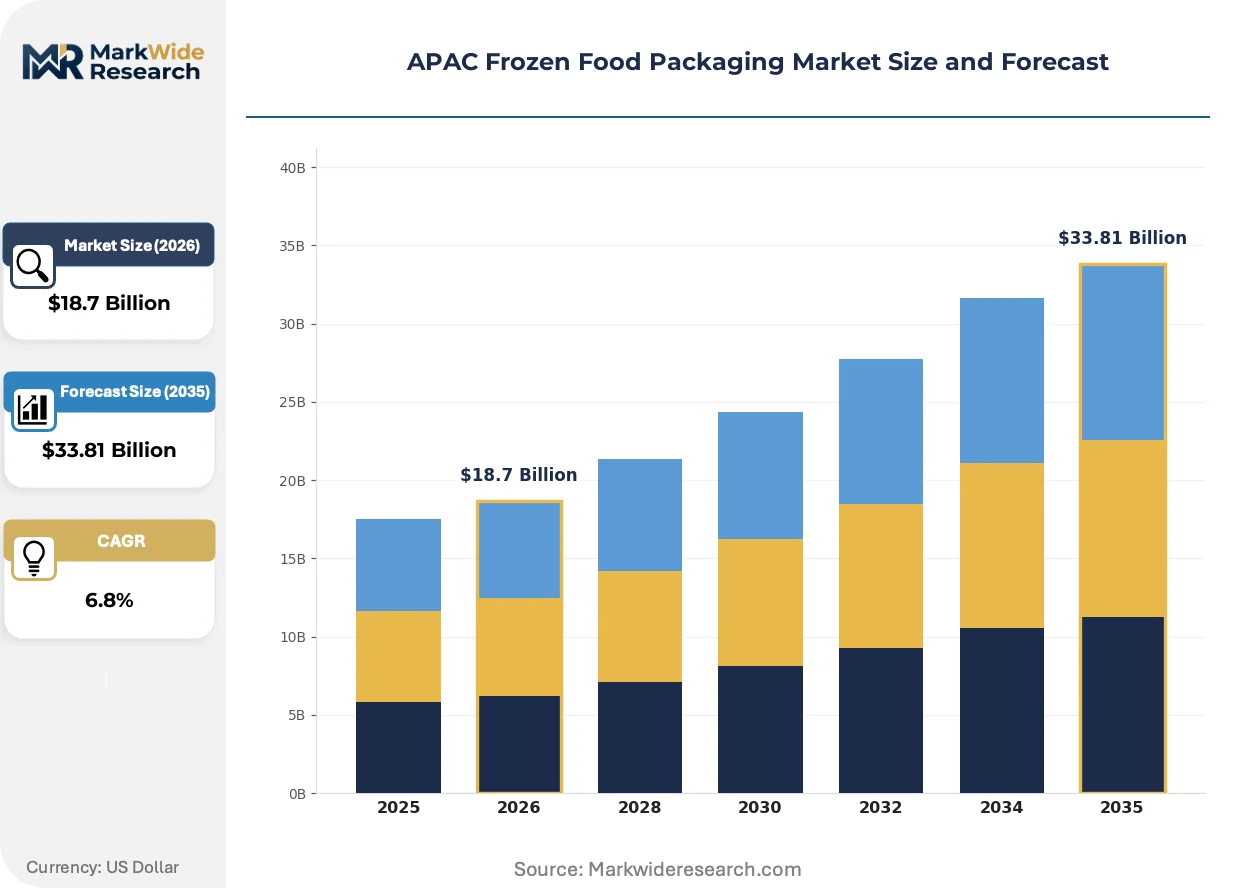
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Flexible Packaging, Rigid Containers, Vacuum Packs, Modified Atmosphere Packaging Material: Plastic, Paperboard, Aluminum, Composite Materials End User: Retail Chains, Hotels, Quick Service Restaurants, Food Distributors Closure Type: Sealable Bags, Snap-Lid Containers, Screw Caps, Pouches |
| Companies Covered | Amcor plc, Pactiv LLC, Ball Corporation, Genpak LLC, Graham Packaging Company, Sealed Air, Berry Global Inc., Sonoco Products Company, WestRock Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Frozen Food Packaging Market Strategic Shifts
Packaging format evolution and regulatory design mandates are compressing traditional material hierarchies, with functionality requirements now preceding cost optimization in buyer specifications across the region's frozen food channels.
Active-barrier film technology incorporating oxygen scavengers and moisture regulators is modularizing shelf-life extension capabilities previously achievable only through modified atmosphere rigid containers. Australian retail chains are specifying these structures for premium frozen protein lines, enabling case-ready merchandising without secondary overwrap. The technology is modularizing supply chain configurations by collapsing distribution center staging requirements and compressing inventory turns.
Japan's METI recyclable packaging design guidelines are mandating mono-material or easily separable multi-material constructions for frozen food exporters targeting domestic retail compliance. The policy is forcing laminate redesigns across Vietnamese and Thai seafood processors, with EVOH barrier layers now requiring compatible polyethylene tie layers for mechanical recycling stream acceptance. Premium seafood export segments are absorbing material cost premiums to maintain market access.
Modern retail procurement consolidation in Indonesia's Jakarta-Surabaya corridor is compressing supplier qualification cycles and unbundling legacy distributor relationships. Direct contracting between packaging converters and frozen food brand owners is displacing layered trading company structures, with specifications increasingly standardized across banner networks. The shift is most visible in frozen vegetable and prepared meal categories where private label penetration is deepening.
APAC Frozen Food Packaging Market Segmentation
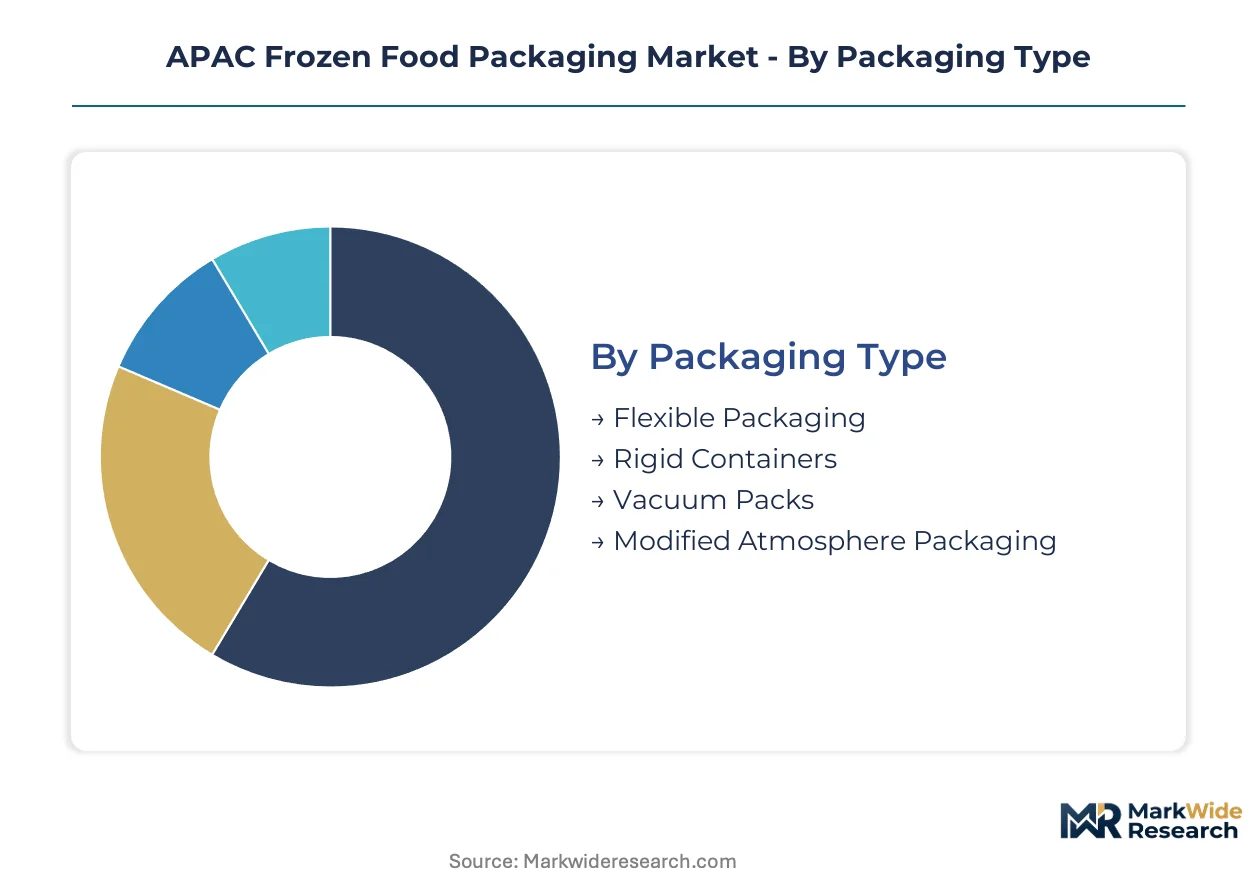
Segmentation in frozen food packaging reveals how compliance requirements and functional specifications diverge across buyer categories. Material selection and format design respond to distinct cold-chain exposures and regulatory thresholds rather than uniform cost optimization.
Packaging Type:
Certification burdens concentrate in modified atmosphere and vacuum formats where oxygen transmission rates demand laboratory validation against China's GB standards and Japan's METI recyclability guidelines. Flexible pouches face lighter compliance loads but must still demonstrate freezer-grade seal integrity under BIS migration limits for Indian retail entry.
- Flexible Packaging:Multi-layer polyethylene terephthalate and oriented polypropylene laminates dominate frozen vegetable and prepared meal logistics. Demand concentrates in Indonesia's Jakarta-Surabaya corridor where modern retail private label expansion favors lightweight, high-cube efficiency formats over rigid alternatives.
- Rigid Containers:Polypropylene and polyethylene terephthalate trays with snap-fit lids serve premium ready-to-cook proteins requiring stack stability and microwave compatibility. Australian retail chains specify these for case-ready merchandising despite higher unit cube and freight cost.
- Vacuum Packs:EVOH barrier films with vacuum-drawn skin layers command seafood export specifications from Vietnamese and Thai processors targeting EU premium markets.
- Modified Atmosphere Packaging:Gas-flushed rigid trays with high-barrier lidding films extend shelf life for value-added shrimp and pangasius products where spoilage risk justifies equipment capital investment.
Leading the category by volume: Flexible Packaging. Growing fastest: Modified Atmosphere Packaging.
Material:
Cost tiers separate commodity resin applications from engineered barrier constructions where EVOH copolymer and aluminum oxide coatings introduce step-function price premiums.
- Plastic:Polyethylene, polypropylene, and polyethylene terephthalate substrates form the baseline across all temperature grades. South Korean and Japanese petrochemical complexes supply EVOH feedstock for high-barrier segments, creating input cost volatility when regional refinery utilization shifts.
- Composite Materials:Multi-layer structures combining plastic, aluminum, and paperboard balance moisture barrier performance with sustainability positioning in Japanese and South Korean markets where METI guidelines pressure design-for-recyclability.
- Paperboard:Polyethylene-coated board for frozen pizza and bakery cartons offers printability and retail shelf presence at lower barrier performance than plastic alternatives.
- Aluminum:Foil laminates and semi-rigid trays provide absolute moisture and light barriers for premium seafood and ice cream applications where oxidation sensitivity demands maximum protection.
Lowest cost tier: Paperboard. Highest margin tier: Composite Materials.
End User:
Procurement scale and specification authority vary sharply across customer types, with QSR chains and retail private label operators driving standardization while hotel and distributor channels retain fragmented sourcing patterns.
- Quick Service Restaurants:Southeast Asian chains in Indonesia, Vietnam, and the Philippines specify portion-controlled frozen inputs with standardized pack sizes for kitchen automation compatibility. Procurement is shifting toward direct converter relationships as distributor markups compress.
- Retail Chains:Australian supermarket operators and Indonesia's modern retail banners specify microwaveable formats and active-barrier films for premium protein lines, collapsing traditional distributor layers through direct converter contracting.
- Food Distributors:Layered trading company structures persist in fragmented Indonesian and Indian wholesale channels where small-format retailers lack specification authority or volume consolidation.
- Hotels:Full-service and institutional foodservice operations in Thailand and Malaysia source frozen ingredients through procurement cooperatives with limited packaging influence beyond basic size and labeling requirements.
Highest specification authority: Retail Chains. Most fragmented procurement: Hotels.
Closure Type:
Functional performance requirements and consumer convenience expectations dictate closure selection, with resealability and microwave compatibility emerging as differentiating features in premium segments.
- Sealable Bags:Heat-sealed polyethylene and polypropylene bags with tear-notches dominate frozen vegetable and commodity protein volume. India's BIS compliance mandates specific migration limits for seal-layer adhesives in sub-zero storage applications.
- Snap-Lid Containers:Polypropylene tubs with audible-close lids serve ready-meal and prepared protein categories where resealability and stack stability support retail merchandising and home storage convenience.
- Pouches:Stand-up and flat pouches with zipper or press-to-close seals penetrate Australia's ready-meal channel where susceptor-equipped microwaveable formats displace rigid tray alternatives.
- Screw Caps:Limited to liquid and semi-liquid frozen products including sauces and dessert toppings where dispensing control outweighs cost premium versus snap-fit alternatives.
Widest application range: Sealable Bags. Fastest feature innovation: Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's Jakarta-Batang corridor anchors regional concentration through special economic zone incentives for cold-chain infrastructure, concentrating converter investment and frozen SKU distribution networks across Southeast Asia's largest consumer market.
China
Blast-freezing capacity expansion in Shandong and Jiangsu provinces drives substrate demand for prepared meal processors. SAMR enforces GB standards migration limits for food-contact plastics in sub-zero applications. Qingdao's port cluster processes premium seafood exports requiring EVOH barrier compliance for EU destination markets.
India
Modern retail private label expansion in Mumbai-Pune and Delhi-NCR corridors accelerates frozen vegetable packaging procurement. BIS mandates heavy metal and plasticizer compliance certification for sub-zero storage substrates. Gujarat's petrochemical belt supplies polyethylene feedstock for domestic converter operations.
Japan
METI recyclable packaging design guidelines reshape material specifications for frozen food exporters. Mono-material or easily separable multi-material constructions face mandatory compliance for domestic retail entry. Osaka-Kobe industrial zone concentrates laminate redesign expertise for Vietnamese and Thai seafood processors.
Vietnam
Pangasius and shrimp value-added export processing drives vacuum skin packaging adoption for premium EU and North American markets. Mekong Delta aquaculture clusters require barrier film specifications that withstand extended cold-chain exposure. Ho Chi Minh City's converter base scales technical workforce for multi-layer coextrusion operations.
Australia
Retail chain procurement consolidation specifies microwaveable formats and active-barrier films for premium protein lines. Susceptor-equipped flexible pouches displace rigid tray formats in ready-meal channels. Sydney-Melbourne logistics corridors demand freezer-to-oven substrate performance across temperature fluctuation cycles.
APAC Frozen Food Packaging Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across substrate tiers, with material science capabilities separating premium barrier film suppliers from commodity resin converters. The vendor base stratifies between multi-national integrated producers and regional trading company networks. Three archetypes dominate: integrated material-converter operations, technology-licensed regional specialists, and distributor-dependent local fabricators. Competitive moves concentrate on direct retail chain contracting and laboratory certification capacity expansion for GB standards and BIS compliance.
Among Australia and US-based diversified packaging groups, Amcor plc and Sealed Air occupy positions exemplifying integrated material science and vacuum barrier technology archetypes. Berry Global Inc. represents scale-driven rigid container production across Malaysian and Indian manufacturing footprints. These three anchors illustrate how technical workforce concentration in Malaysia and Thailand creates geographic capability clustering that new entrants in India and Indonesia struggle to replicate.
| Leading Market Players |
|---|
| Amcor plc |
| Pactiv LLC |
| Ball Corporation |
| Genpak LLC |
| Graham Packaging Company |
| Sealed Air |
| Berry Global Inc. |
| Sonoco Products Company |
| WestRock Company |
| Others |
Value Chain & Pricing Dynamics
Captive resin production in South Korea and Japan anchors pricing power for EVOH barrier film suppliers serving premium frozen seafood exports, while spot polyethylene buyers across Indonesia and India absorb volatility from naphtha-linked feedstock swings. Converter integration into upstream polymer supply determines margin resilience when regional refinery utilization shifts.
Pricing Analysis
Short lead-time premiums concentrate in EVOH laminates for Vietnamese pangasius exporters facing EU compliance deadlines, while spot inventory discounts penetrate commodity polyethylene segments serving Jakarta-Surabaya frozen vegetable distributors. Three-tier pricing structure across premium, standard, and economy levels separates certified GB-compliant substrates from BIS-aligned domestic grades and uncertified commodity resin. Cost compression in mid-tier flexible pouches is intensifying because Indonesian retail consolidation forces volume commitments from converters. Quick service restaurant chains exhibit highest price sensitivity due to standardized pack size requirements, while Australian retail chains show lowest sensitivity for active-barrier films enabling case-ready merchandising.
Supply Chain Analysis
Single-source vulnerability sits with South Korean and Japanese petrochemical complexes supplying EVOH copolymer feedstock for high-barrier frozen packaging applications. Raw material dependencies center on ethylene, vinyl alcohol monomers, and oriented polypropylene substrates sourced from regional refinery clusters. Tariff exposure on Chinese polymer imports into Australia and India creates input cost volatility for converters lacking backward integration. Distribution runs through direct converter-retail chain contracting in Australia's Sydney-Melbourne corridor and layered trading company networks across Indonesia's fragmented wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The APAC frozen food packaging market is navigating a technology-transition phase as active-barrier films incorporating oxygen scavengers displace modified atmosphere rigid containers across premium protein segments.
For Market Incumbents: Deploy laboratory certification capacity expansion as the primary lever against four-to-eight month GB standards and BIS compliance backlogs threatening product launch timelines. Incumbents should anchor backward integration into EVOH resin supply to defend margin position when South Korean petrochemical utilization shifts. Channel control through direct retail chain contracting in Indonesia's Jakarta-Surabaya corridor protects specification authority against distributor disintermediation. For New Entrants and Emerging Players: Mid-tier Indian frozen vegetable processors lacking BIS-compliant substrate access represent the most penetrable buyer archetype for certified domestic converters. New entrants should prioritize Gujarat-based polyethylene supply partnerships to secure feedstock proximity against Mumbai-Pune logistics costs. A technical workforce development angle targeting multi-layer coextrusion expertise scarcity in India and Indonesia enables differentiation from Malaysian and Thai incumbent clusters. For Investors and Strategic Acquirers: Exit pathways concentrate in technology-licensed regional specialists with demonstrated GB standards and METI recyclability compliance track records. Long-term viability across the analysis window favors converters with captive resin relationships or mono-material design capabilities aligning with Japan's mechanical recycling mandates. The signal to watch is Australia's adoption velocity of susceptor-equipped microwaveable pouches displacing rigid tray formats in ready-meal channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Resin Supply | South Korean petrochemical partnerships reduce feedstock volatility for barrier film converters. |
| Laboratory Certification Capacity Expansion | GB standards and BIS compliance testing backlog reduction accelerates product launch timelines. |
| Mono-Material Laminate Redesign | METI recyclability guideline alignment preserves Japanese retail market access for Vietnamese seafood exporters. |
| Direct Retail Chain Contracting | Indonesian modern retail procurement consolidation eliminates distributor markups in Jakarta-Surabaya corridor. |
| Technical Workforce Development Programs | Multi-layer coextrusion expertise scarcity in India and Indonesia creates capability moats against Malaysian competition. |
Study Parameters
Multi-period observation of cold-chain infrastructure expansion, regulatory compliance timeline shifts, and converter capacity utilization anchored the trend analysis, supplemented by interviews with packaging R&D directors, frozen food brand procurement managers, petrochemical supply planners, retail category buyers, and regulatory affairs specialists at BIS and SAMR. Secondary validation drew from customs trade data, SEC filings of diversified packaging groups, GB standards documentation, METI recyclable packaging guidelines, and cold-chain logistics operator disclosures. Bottom-up volume aggregation across packaging type, material, end user, and closure segments triangulated against top-down macroeconomic drivers.
Input-output matrices modeled demand as a function of QSR outlet expansion rates, modern retail private label penetration, and export seafood volume growth across the projection horizon. Segmentation dimensions included packaging format flexibility, barrier performance tier, geographic regulatory cluster, and buyer procurement scale. CAGRs were derived through regression analysis of historical substrate consumption against cold-chain reliability indices and regulatory implementation schedules. Forecast inputs incorporated EVOH resin price elasticity and laboratory certification queue lengths.
Revisions become necessary when China's SAMR accelerates GB standards enforcement timelines, when Australia's retail chains shift procurement specifications toward fully recyclable mono-material constructions, or when Indonesia's power grid reliability deteriorates beyond current Jakarta-Surabaya corridor baselines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Food and Drink Packaging Market
Food Packaging
Europe Food Packaging Market
Food Packaging
PET Food Trays Market
Food Packaging
Ambient Food Products Packaging Market
Food Packaging
Wooden Cutlery Market
Food Packaging
Meat, Poultry, and Seafood Packaging Market
Food Packaging
Fresh Produce Trays Market
Food Packaging
Microwaveable Liquid Food Packaging Market
Food Packaging
Food Can Market
Food Packaging
Frozen Seafood Packaging Market
Food Packaging
India Food and Beverage Packaging Market
Food Packaging
Spreads and Toppings Packaging Market
Food Packaging
Flexible Frozen Food Packaging Market
Food Packaging
Chocolate Bar Packaging Market
Food Packaging
Spices, Dry Seasoning Mix, and Herbal Extract Packaging Market
Food Packaging
Oven Bags and Pouches Market