
 On the Go Food Packaging Market | 2026-2036
On the Go Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
On the Go Food Packaging Market Outlook
Asset-light leasing models for converting equipment are rewriting competitive entry barriers in on-the-go food packaging, allowing smaller converters to access high-speed forming lines without capital-intensive ownership. Huhtamaki Oyj leverages its global hot-drink cup franchise to extend into complementary food-to-go formats across European cafés. Mondi Group anchors its position through integrated kraft paper operations that sustain margin control amid pulp volatility. Sealed Air Corporation differentiates via proprietary barrier technologies that compete with rigid alternatives in protein and prepared-meal applications.
On-the-go food packaging encompasses single-use containers, wraps, bags, and trays engineered for portability, thermal retention, and leak resistance, typically constructed from paperboard with polyethylene or PLA barrier layers, molded fiber, or oriented polypropylene films designed to withstand temperatures from freezer storage through microwave reheating. The material dimension reveals paper and fiber-based substrates as the fastest-growing structural category, driven by quick service restaurant commitments to eliminate expanded polystyrene and conventional plastic cutlery. Plastic retains dominant share in trays and lidded containers where oxygen barrier precision protects prepared proteins, though composites combining molded pulp with thin film barriers are capturing margin pools in premium delivery applications.
The FDA governs food-contact substance notifications under 21 CFR, while EPA regulations on per- and polyfluoroalkyl substances are eliminating legacy grease-resistant chemistries from paper packaging, forcing reformulation of microwaveable wraps and popcorn bags. The EU Green Deal's packaging waste reduction targets and REACH restrictions on single-use plastics are reshaping export compliance requirements for converters serving transatlantic quick service restaurant chains. Stakeholders must monitor evolving state-level extended producer responsibility frameworks and bio-based certification standards to anticipate which material platforms will secure preferential procurement status across major foodservice accounts.
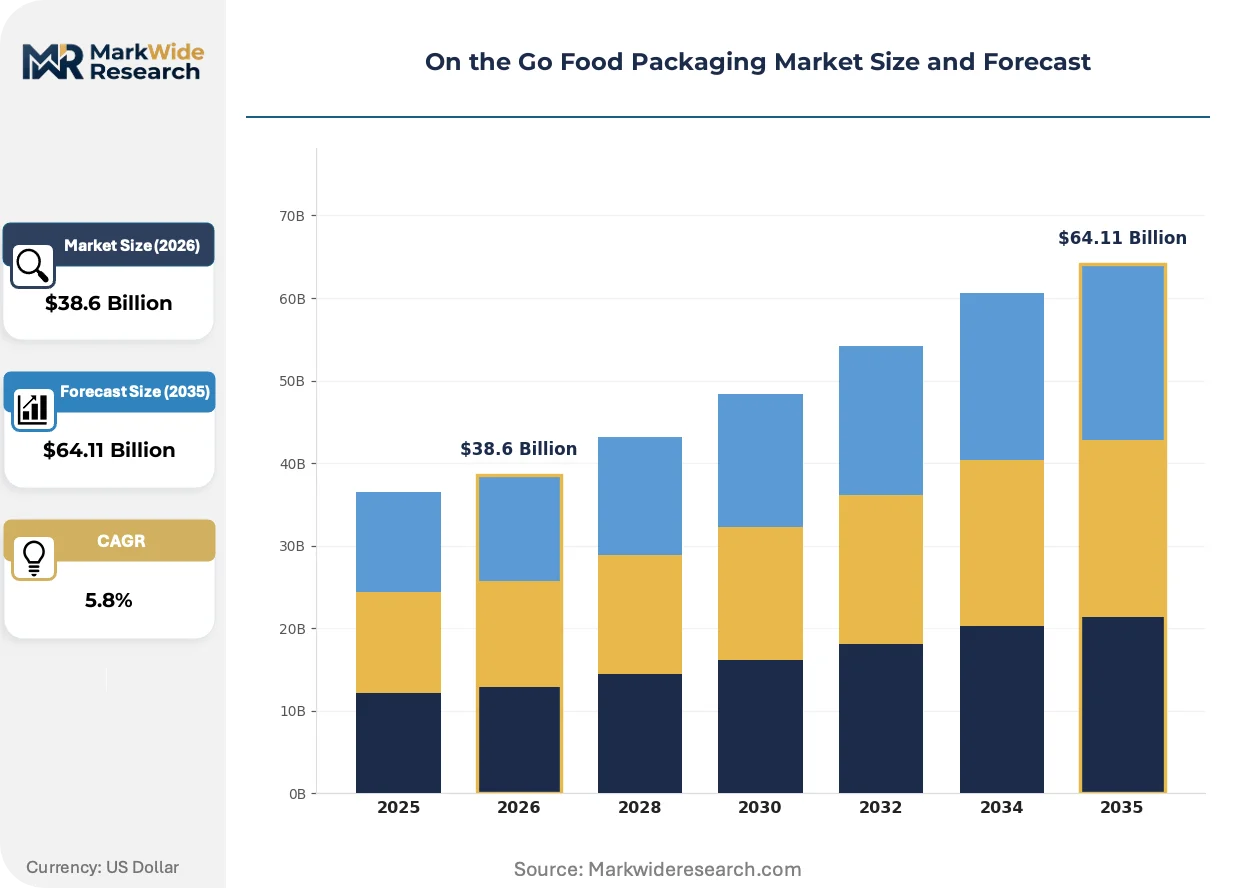
Market Dynamics
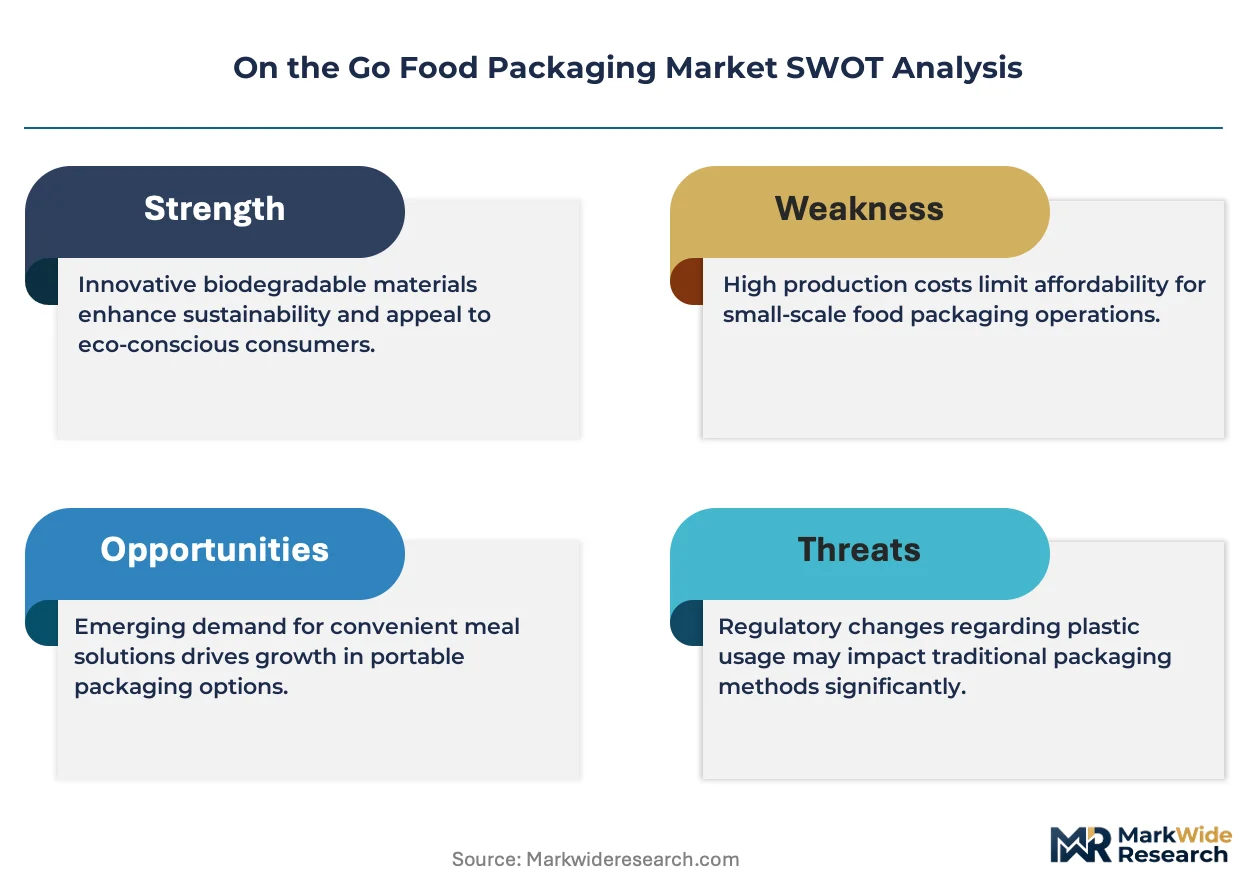
The EU Green Deal's packaging waste reduction mandates are forcing converters to abandon multilayer plastic laminates before fully amortized equipment cycles complete, triggering a capital reallocation race toward fiber-based barrier platforms.
Growth Catalysts
- Quick service restaurant grab-and-go expansion:Chains are retrofitting drive-through lanes and mobile-order pickup points, creating pull for single-serve containers with thermal retention properties.
- REACH single-use plastic restrictions:The EU framework bans expanded polystyrene food containers and oxo-degradable plastic cutlery, redirecting procurement toward molded fiber and PLA-coated paperboard alternatives.
- Microwaveable barrier films:Oriented polypropylene formulations with enhanced oxygen transmission rates are penetrating prepared protein delivery, extending shelf stability without rigid tray formats.
Market Restraints
- Pulp price volatility:Kraft fiber supply concentration in Nordic and Brazilian markets exposes converters to input cost swings that compress margin on fixed-price foodservice contracts.
- Per- and polyfluoroalkyl substance phaseout:EPA regulations eliminating legacy grease-resistant chemistries force reformulation of microwaveable popcorn bags and wraps, requiring 18-24 month requalification timelines.
- Barrier performance gaps:Molded fiber trays with thin film liners still leak under extended steam exposure, limiting adoption in sauced protein applications where rigid polypropylene dominates.
Strategic Opportunities
- India urban food delivery infrastructure:Swiggy and Zomato's dark kitchen networks are scaling insulated bag and sealed bowl procurement, creating demand for compostable alternatives ahead of formal BIS standards.
- Extended producer responsibility frameworks:State-level EPR legislation in California and New York is creating preferential procurement status for fiber-based packaging with certified post-consumer content.
- Active and intelligent packaging convergence:Time-temperature indicators integrated into lidding films are penetrating premium prepared-meal channels, enabling quality-based pricing differentiation.
Industry Challenges
- Compostable certification timelines:ASTM D6400 and EN 13432 testing protocols require 180-day industrial composting validation, delaying product launches and locking out early movers from QSR tenders.
- Legacy forming equipment incompatibility:Fiber-based substrates demand modified sealing temperatures and dwell times, forcing converters to choose between retrofitting existing lines or absorbing new capex for dedicated assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | On the Go Food Packaging Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $64.11 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Wraps, Bags, Trays Material: Paper, Plastic, Metal, Composites End User: Quick Service Restaurants, Retailers, Food Delivery Services, Cafés Size: Small, Medium, Large, Extra Large |
| Companies Covered | Amcor plc, Mondi Group, Sonoco Products Company, Berry Global Group, Smurfit Kappa Group, Sealed Air Corporation, Huhtamaki Oyj, Tetra Pak, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
On the Go Food Packaging Market Strategic Shifts
Material science breakthroughs and regulatory chemistry bans are converging to compress the viable technology set for portable food containment, privileging platforms that satisfy both performance and disposal compliance.
Barrier-coated molded fiber is migrating from premium café applications into mass-market quick service formats. Starbucks and Pret A Manger have validated the technology for hot beverage containment, and McDonald's franchisees in France and Germany are piloting the substrate for burger clamshells. The shift is migrating from niche sustainability positioning toward total cost parity with expanded polystyrene as pulp integration and forming speeds improve.
EPA action on per- and polyfluoroalkyl substances under the Toxic Substances Control Act is eliminating C6 and C8 fluorotelomer chemistries from grease-resistant paper packaging. Converters serving US popcorn and fast-casual wrap markets must reformulate with plant-based sizing agents or mineral oil barriers, extending product development cycles and raising material costs. The prepared protein segment is most affected, with microwaveable bag manufacturers accelerating migration to silicone-coated alternatives ahead of state-level disclosure mandates.
Dark kitchen consolidation is compressing packaging specification cycles from annual to quarterly reviews. Virtual brands operating through DoorDash and Uber Eats ghost facilities in Atlanta, London, and São Paulo now demand format flexibility—containers that nest for storage efficiency, withstand 45-minute delivery thermal profiles, and photograph well for digital menu presentation. The prepared-meal delivery vertical is where this behavioral shift is most visible, with procurement teams prioritizing Instagram-compatible aesthetics alongside functional performance.
On the Go Food Packaging Market Segmentation
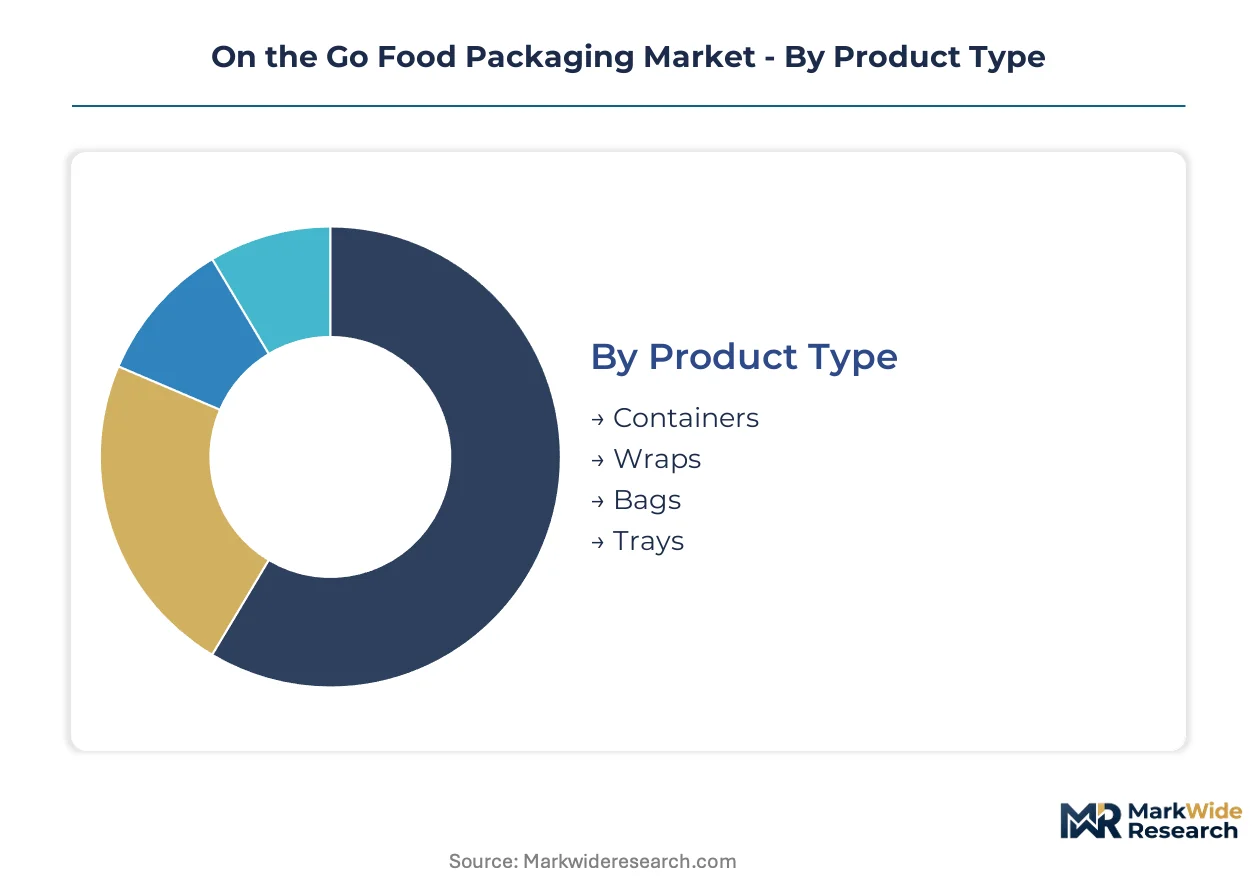
Segmentation in on-the-go food packaging reveals how material science, format engineering, and end-use logistics intersect to create distinct competitive arenas. Each dimension carries unique margin profiles, regulatory exposure, and equipment requirements that shape converter strategy.
Product Type:
Application requirements determine which formats capture volume in quick service and delivery channels.
- Containers:Clamshell and lidded designs dominate burger, sandwich, and bowl applications across US drive-through networks. Thermal retention specifications vary by menu category, with fried protein formats demanding higher insulative performance than cold deli alternatives.
- Wraps:Grease-resistant paper and film laminates serve burrito, flatbread, and handheld snack formats where fold integrity and moisture management compete. EPA regulations on fluorinated chemistries are forcing rapid reformulation of legacy popcorn and hot wrap substrates.
- Bags:Stand-up and pinch-bottom constructions handle fried snacks, bakery items, and grab-and-go retail formats with moderate barrier demands.
- Trays:Molded pulp and rigid plastic formats anchor prepared meal and protein applications where structural rigidity under steam exposure matters.
Containers command the established base. The steepest expansion runs through wraps as fluorochemistry bans accelerate material substitution cycles.
Material:
Cost tier positioning and regulatory compliance trajectories split procurement decisions across substrate categories.
- Paper:Kraft and paperboard substrates with PE or PLA barrier layers capture quick service commitments to eliminate expanded polystyrene. Starbucks and McDonald's procurement specifications in France and Germany are validating molded fiber for hot beverage and food containment.
- Plastic:Oriented polypropylene and PET retain dominance in lidded trays and high-barrier protein packaging where oxygen transmission precision protects shelf stability. REACH single-use plastic restrictions are compressing addressable volume in EU foodservice accounts.
- Metal:Aluminum trays and laminates serve premium prepared-meal and retort applications where microwave compatibility and extended shelf life justify higher unit costs.
- Composites:Molded pulp with thin film liners and paper-plastic laminates bridge performance gaps in delivery applications, though industrial composting certification timelines delay mass-market adoption.
Paper formats are climbing the fastest as EU Green Deal mandates and US state-level extended producer responsibility frameworks redirect procurement toward fiber-based alternatives.
End User:
Customer type determines specification cycles, volume concentration, and sustainability pressure intensity.
- Quick Service Restaurants:Drive-through retrofitting and mobile-order pickup expansion in the United States is pulling single-serve formats with standardized nesting and thermal retention properties. Chains specify quarterly format reviews as dark kitchen proliferation compresses product lifecycles.
- Retailers:Supermarket deli and convenience store grab-and-go sections demand price-competitive formats with modest barrier performance for short-turnover prepared foods.
- Food Delivery Services:Swiggy and Zomato's dark kitchen networks in India are scaling insulated bag and sealed bowl procurement ahead of formal BIS compostability standards.
- Cafés:Premium positioning justifies higher-cost molded fiber and barrier-coated paperboard for aesthetic differentiation in European urban markets.
Quick Service Restaurants anchor volume concentration. Food Delivery Services represent the most rapid specification evolution as dark kitchen consolidation accelerates format innovation cycles.
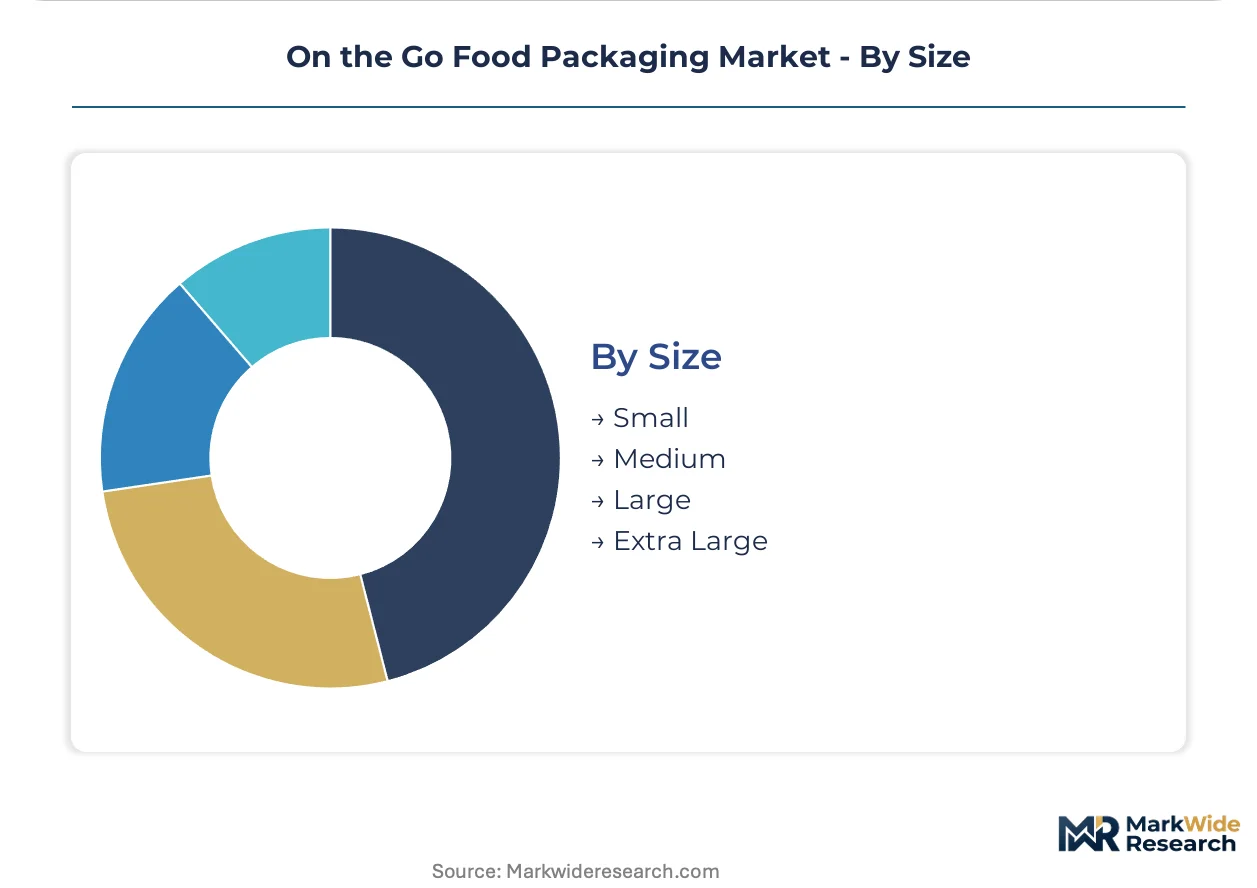
Size:
Volume tier segmentation aligns with portion economics, storage efficiency, and delivery logistics optimization.
- Small:Single-serve snack and beverage companion formats dominate US commuter culture applications where consumption occurs within 15 minutes of purchase.
- Medium:Standard entrée and combo meal specifications balance food volume with nesting density for back-of-house storage efficiency.
- Large:Family and shared formats serve delivery aggregation economics where multiple items travel in consolidated packaging.
- Extra Large:Catering and group order formats require reinforced structural properties for transport integrity over extended delivery windows.
Medium formats hold the core volume position. Small formats are gaining share fastest as snacking occasion fragmentation and single-serve premium positioning expand addressable demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in on-the-go food packaging reveal a pronounced trade imbalance favoring fiber-based substrate exporters in Nordic and North American markets, while Asia-Pacific converters absorb growing volumes of barrier-coated paperboard to serve quick service restaurant expansion. Regulatory divergence between jurisdictions is accelerating regional specialization in compliant material platforms.
United States
Urban commuter culture and drive-through infrastructure sustain the highest per-capita consumption of portable food formats globally. EPA regulations under the Toxic Substances Control Act are eliminating C6 and C8 fluorotelomer chemistries from grease-resistant paper packaging, forcing reformulation timelines of 18-24 months. Atlanta and Dallas-Fort Worth metro areas concentrate dark kitchen facilities where quarterly packaging specification reviews have become standard procurement practice.
Germany
McDonald's franchisees across France and Germany are piloting molded fiber burger clamshells as the EU Green Deal accelerates substitution away from expanded polystyrene. REACH restrictions on single-use plastics redirect procurement toward PLA-coated paperboard and compostable alternatives. The Rhine-Ruhr industrial corridor hosts integrated kraft paper operations that sustain margin control for converters serving transatlantic quick service restaurant chains.
India
Swiggy and Zomato's dark kitchen networks are scaling insulated bag and sealed bowl procurement ahead of formal BIS compostability standards. Urban food delivery infrastructure expansion creates demand for compostable alternatives in Mumbai, Bangalore, and Delhi-NCR. The absence of finalized industrial composting certification protocols leaves early movers vulnerable to tender lockout as regulatory frameworks crystallize.
China
Domestic quick service restaurant chains are retrofitting mobile-order pickup points, creating pull for single-serve containers with thermal retention properties. GB standards for food-contact materials govern barrier layer compliance, while provincial environmental regulations in Yangtze River Delta cities tighten plastic waste management requirements. Shanghai and Shenzhen manufacturing clusters specialize in oriented polypropylene formulations for microwaveable protein delivery applications.
Brazil
São Paulo's ghost kitchen proliferation is compressing packaging specification cycles from annual to quarterly reviews as virtual brands demand format flexibility. ANVISA regulations on food-contact substances shape import compliance for fiber-based substrates entering through Santos port. The southeastern industrial corridor around Campinas hosts converters adapting European molded fiber technologies for tropical humidity conditions in protein delivery applications.
On the Go Food Packaging Market Competitive Environment
On the supply side, the industry is consolidating around integrated paper and fiber-based substrate producers capable of controlling input costs through captive pulp supply, while specialized barrier technology developers occupy defensible niches in high-performance segments. Three strategic archetypes dominate: multinational converters with global hot-drink cup franchises extending into complementary food formats, integrated kraft paper operators leveraging upstream pulp control, and proprietary barrier technology specialists competing with rigid alternatives. Competitive intensity centers on M&A activity targeting regional forming equipment capacity and strategic partnerships securing preferred supplier status with quick service restaurant procurement teams.
Among Nordic and European-based integrated operators, Huhtamaki Oyj and Mondi Group exemplify contrasting strategic positions within the fiber-based migration. Huhtamaki occupies a position representing global hot-drink cup franchise extension into food-to-go formats, while Mondi anchors the integrated kraft paper archetype through upstream pulp operations. Sealed Air Corporation sits within the barrier technology specialist tier, competing with rigid alternatives through proprietary film formulations.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi Group |
| Sonoco Products Company |
| Berry Global Group |
| Smurfit Kappa Group |
| Sealed Air Corporation |
| Huhtamaki Oyj |
| Tetra Pak |
| WestRock Company |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Nordic kraft pulp mills is compressing fiber substrate pricing while simultaneously incentivizing converters to lock in long-term offtake agreements, creating divergent margin postures between integrated operators and merchant buyers dependent on spot markets.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across quick service restaurant procurement teams, with three-tier pricing structure across premium, standard, and economy levels differentiated by barrier performance certification and volume scale commitments. Price differentiation stems from FDA food-contact tier compliance and post-consumer recycled content certification under state-level extended producer responsibility frameworks. Cost compression in standard-grade molded fiber is intensifying because Brazilian pulp integration has expanded supply availability. Small-format converters serving dark kitchen virtual brands exhibit highest price sensitivity, while multinational quick service chains with dedicated procurement teams leverage volume scale for least sensitivity.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic planning for barrier film importers, reshaping sourcing patterns for oriented polypropylene formulations. Supply concentrates in Brazil, Sweden, and Finland for kraft pulp feedstock, while Germany and the United States host specialized converting equipment manufacturing. Raw material dependencies rest on Nordic softwood pulp, PLA resin from Thai agricultural feedstock, and silicone-coated release liners from Japanese chemical specialists. Single-source vulnerability in fluorochemistry-free grease-resistant sizing agents creates procurement risk as EPA regulations eliminate legacy chemistries. Distribution runs through regional converting hubs serving quick service restaurant distribution centers, with just-in-time delivery contracts compressing inventory buffers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized barrier-coating expertise represents the scarcest capability in this market, with fewer than a dozen converters globally possessing validated microwaveable film formulations that satisfy both FDA compliance and quick service restaurant thermal performance specifications.
For Market Incumbents: Build captive pulp supply moats through backward integration into Brazilian or Nordic fiber operations, insulating margin from input volatility while securing preferential status under emerging extended producer responsibility frameworks. Incumbents must defend against specialized barrier technology entrants by accelerating active packaging R&D investment and locking in multi-year exclusive supply contracts with top-ten quick service restaurant chains before requalification windows open. For New Entrants and Emerging Players: Build out compostable certification capabilities ahead of formal BIS standard finalization in India, where Swiggy and Zomato procurement teams currently lack qualified domestic suppliers for insulated delivery formats. The most penetrable white space sits in dark kitchen-specific container design combining nesting efficiency with Instagram-compatible aesthetics, with go-to-market execution best pursued through direct equipment-leasing partnerships with ghost kitchen facility operators in São Paulo and Atlanta. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated kraft paper operators with captive pulp supply and long-term quick service restaurant contracts indexed to commodity pass-through mechanisms. Over the extended viability window, acquisition targets should demonstrate proven barrier-coating R&D pipelines and established relationships with European regulatory bodies navigating EU Green Deal compliance. The critical inflection signal to monitor is state-level extended producer responsibility legislation adoption velocity in the United States, which will determine preferential procurement status for post-consumer certified fiber formats.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier-Coating R&D Investment | EPA fluorochemistry bans force 18-24 month reformulation cycles for microwaveable wraps and popcorn bags. |
| Backward Integration into Pulp Supply | Nordic and Brazilian kraft operations insulate margin from fiber price volatility compressing fixed-price contracts. |
| Compostable Certification Acceleration | ASTM D6400 and EN 13432 validation unlocks tender participation for EU and US quick service restaurant accounts. |
| Dark Kitchen Format Partnership | Atlanta and São Paulo ghost facilities demand quarterly specification reviews creating rapid product lifecycle turnover. |
| Extended Producer Responsibility Alignment | California and New York frameworks create preferential procurement status for post-consumer certified fiber content. |
Study Parameters
A standing panel of quick service restaurant procurement directors, converting equipment engineers, pulp trading specialists, and regulatory compliance officers provided ongoing calibration against operating reality throughout the study period. Primary interviews with fiber substrate technical directors and barrier film R&D leads were cross-referenced with secondary validation from FDA food-contact substance notifications, EPA Toxic Substances Control Act dockets, EU ECHA restriction proposals, and trade data from Nordic pulp export associations. Bottom-up volume modeling across format categories was reconciled with top-down spend analysis from quick service restaurant capital expenditure disclosures.
Scenario-bracketing framed low, base, and high cases across the projection horizon, with analytical outputs reflecting material substitution velocity under varying regulatory enforcement intensities. Segmentation dimensions modeled included product format, substrate material tier, end-user channel, and regional regulatory cluster. CAGRs were derived from trend extrapolation of historical volume trajectories adjusted for structural breakpoints including EU Green Deal implementation and EPA fluorochemistry phaseout timelines. Forecast inputs incorporated pulp futures curve movements, quick service restaurant unit expansion plans, and compostable certification approval pipelines.
Stress conditions across pulp price volatility bands, regulatory enforcement delay scenarios, and quick service restaurant format substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding barrier technology performance convergence and extended producer responsibility adoption velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Food Tub Packaging Market
Food Packaging
Reclosable Food Packaging Market
Food Packaging
Food Can Market
Food Packaging
Drink Carrier and Trays Market
Food Packaging
Lightweight Food Container Market
Food Packaging
Food and Drink Packaging Market
Food Packaging
Food Packaging Market
Food Packaging
APAC Canned Food Packaging Market
Food Packaging
Asia-Pacific Skin Packaging for Fresh Meat Market
Food Packaging
Burger Boxes Market
Food Packaging
Hot-Fill Food Packaging Market
Food Packaging
PVDC Food Packaging Market
Food Packaging
Food Green Packaging Market
Food Packaging
Egg Cartons Market
Food Packaging
Europe Food Packaging Market
Food Packaging
Seafood Packaging Market