
 Pizza Box Market | 2026-2036
Pizza Box Market Size, Share, and Industry Trends Forecast 2026-2036
Pizza Box Market Intelligence
The long-standing procurement model centered on individual Quick Service Restaurants is unwinding as large-scale Delivery Platforms centralize purchasing. International Paper leverages its vast production scale to serve these high-volume accounts. Smurfit Kappa Group differentiates through sustainable material innovations and custom-printed designs. Meanwhile, WestRock Company competes by offering a broad portfolio of packaging solutions across multiple end-use channels.
A pizza box is a specialized folding carton engineered to transport and deliver pizza while maintaining temperature and product integrity. Typically constructed from B-flute corrugated cardboard, its design manages steam and prevents grease saturation. Corrugated Cardboard remains the dominant Material Type due to its cost-effectiveness and structural strength. Within closure types, the standard Tuck Flap design leads in volume, but Peel & Seal options are gaining traction in premium applications for enhanced security.
Food contact material safety is governed by regulations from bodies like the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA). These frameworks dictate permissible materials and chemical migration limits, influencing the use of recycled content and adhesives. Stakeholders must monitor the evolving landscape of per- and polyfluoroalkyl substances (PFAS) restrictions, which directly impacts material choices for grease-resistant coatings.
Market Dynamics
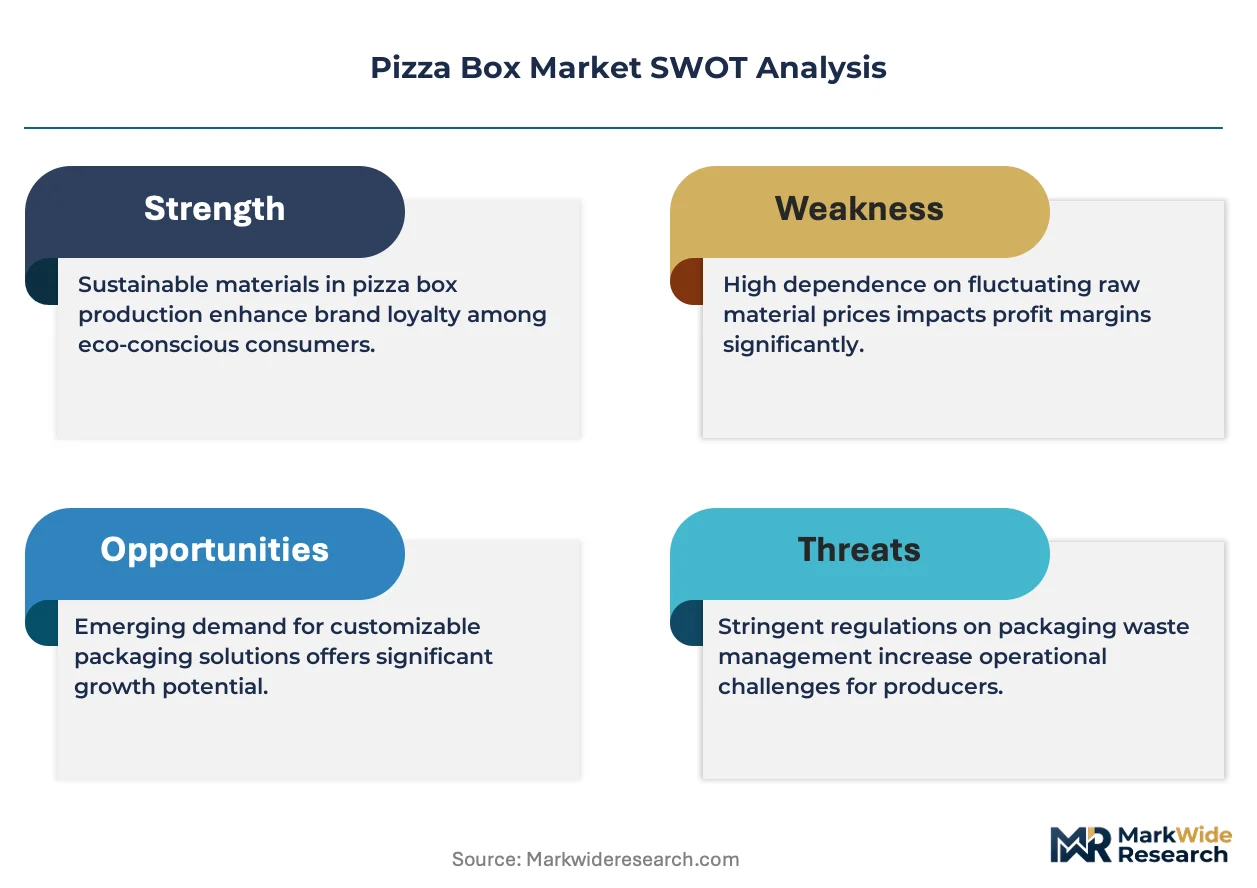
The central dynamic shaping the pizza box market is the tension between cost-efficiency demanded by high-volume delivery platforms and the rising regulatory and consumer pressure for sustainable, non-toxic materials, particularly concerning grease-resistant coatings.
Growth Catalysts
- Compostable Materials:The adoption of certified compostable fiber materials, driven by consumer preference for sustainable options, expands the market for premium, eco-friendly packaging solutions in quick-service restaurants.
- Ghost Kitchen Expansion:The proliferation of ghost kitchens and virtual restaurant brands, particularly in North American and European urban centers, creates consistent, high-volume demand for standardized and scalable packaging.
- Emerging Market Delivery:Rapid growth in food delivery ecosystems across Southeast Asia and Latin America provides new volume opportunities for pizza box manufacturers as local and international pizza chains expand their footprint.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of corrugated cardboard and recycled paper pulp, the primary raw materials, directly impact manufacturer margins and create pricing instability for end-users.
- Inconsistent Recycling Infrastructure:The inability of many municipal recycling facilities to process grease-contaminated cardboard limits the circularity of pizza boxes, leading to landfill waste and undermining sustainability claims.
- Technical Limitations:Standard B-flute corrugated designs struggle to maintain integrity with certain deep-dish or heavily topped pizzas, creating a performance gap that alternative packaging formats can exploit.
Strategic Opportunities
- Smart Packaging Integration:The development of boxes with integrated QR codes for marketing or freshness indicators for quality assurance offers a value-added service for premium pizza brands and delivery platforms.
- Regulatory Tailwinds:The EU's Packaging and Packaging Waste Regulation (PPWR) incentivizes the design of easily recyclable and reusable packaging, creating an opportunity for innovative, compliant fiber-based solutions.
- Adjacent Category Penetration:Adapting the classic pizza box design for other delivered foods, such as calzones, flatbreads, and large-format desserts, opens new revenue streams within the broader food service sector.
Industry Challenges
- PFAS Replacement:Reformulating grease-resistant coatings to comply with expanding PFAS restrictions from bodies like the FDA and EFSA requires significant R&D investment and extensive food-contact safety validation.
- Quality Control at Scale:Ensuring consistent structural integrity, print quality, and food-safe standards across millions of units for centralized delivery platform contracts presents a significant operational challenge for manufacturers.
- Design Trade-offs:Balancing the need for robust, protective structures that prevent crushing and heat loss with material reduction goals to lower costs and improve environmental footprints is a constant engineering challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pizza Box Market |
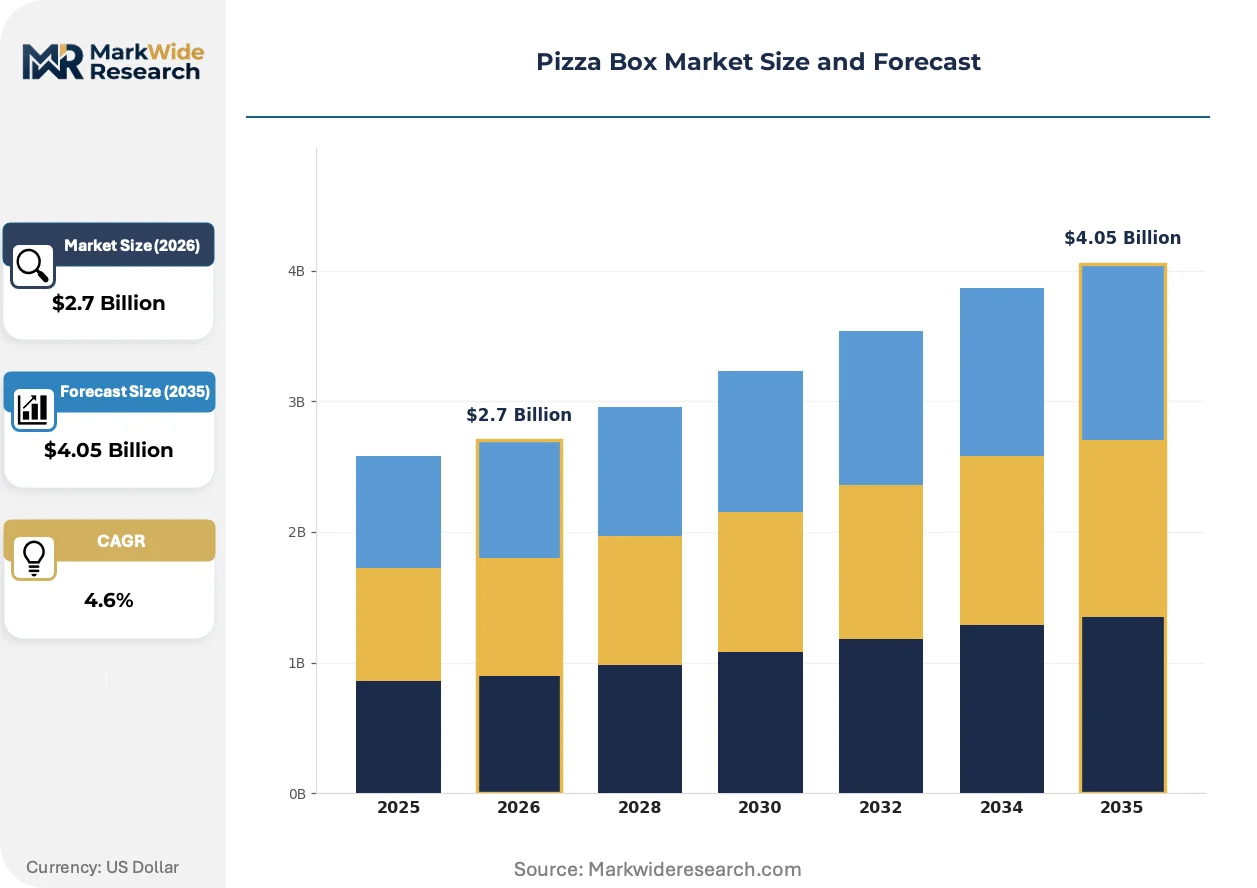
| Market Size in 2026 | $2.7 Billion |
| Market Size in 2035 | $4.05 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Corrugated Cardboard, Solid Fiberboard, Recycled Paperboard, Kraft Paper, Plastic Laminated, Compostable Fiber Closure Type: Tuck Flap, Lock Corner, Sleeve Style, Interlocking Tabs, Peel & Seal, Magnetic Closure End Use Channel: Quick Service Restaurants, Full Service Establishments, Food Trucks, Catering Services, Delivery Platforms, Event Organizers Size Capacity: Small (8-10 Inch), Medium (11-13 Inch), Large (14-16 Inch), Extra Large (17 Inch & Above) |
| Companies Covered | Smurfit Kappa Group, WestRock Company, International Paper, DS Smith, Georgia-Pacific, Mondi, Huhtamaki, New Method Packaging, Pakoro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pizza Box Market Strategic Shifts & Innovations
Material science and regulatory compliance are actively reshaping product design in the pizza box industry. The focus is shifting from a purely cost-driven approach to a balanced equation of performance, sustainability, and brand enhancement, directly influenced by consumer awareness and new legislation.
Molded fiber, produced from materials like sugarcane bagasse or bamboo, provides a premium, compostable packaging alternative. Boutique pizzerias and health-focused food chains are the primary adopters, using the distinct look and feel to signal a commitment to sustainability. This technology is supplanting traditional corrugated cardboard in high-value niches where environmental credentials justify a higher price point for consumers.
Restrictions on per- and polyfluoroalkyl substances (PFAS) in food packaging, particularly through state-level legislation in the United States, are forcing a market-wide reformulation of grease-resistant barriers. This shift compels manufacturers to adopt more expensive, PFAS-free alternatives such as clay-based coatings or bio-polymers to maintain market access. The entire supply chain, from chemical suppliers to box converters, must now invest in validating and certifying these new materials.
Customization as a tool for brand differentiation is becoming a standard expectation. Quick Service Restaurants and independent pizzerias are moving beyond generic stock boxes, demanding custom printing, unique structural shapes, and co-branded marketing elements in partnership with delivery aggregators. This trend is most visible in competitive urban markets in North America and Western Europe, where packaging is a critical touchpoint for customer engagement.
Pizza Box Market Segmentation
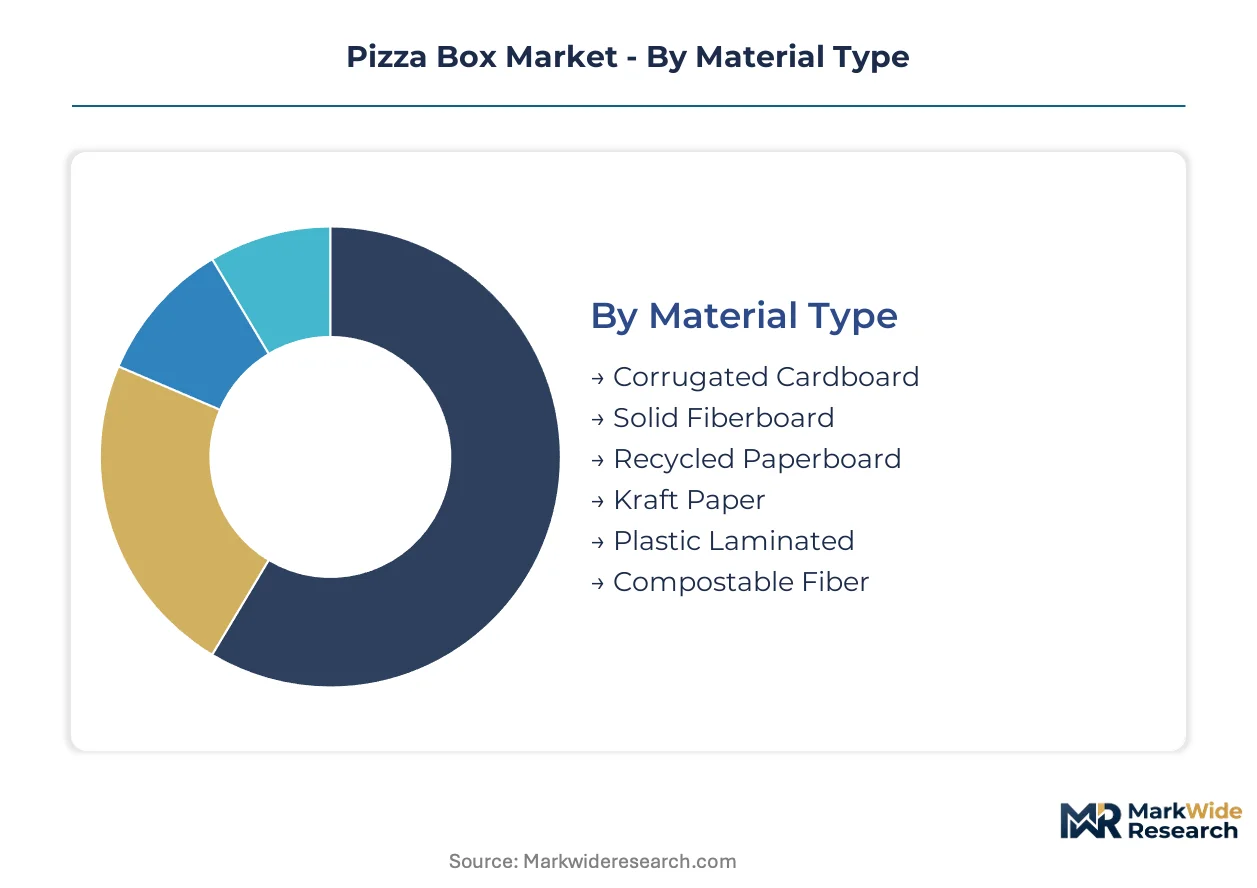
The pizza box market segments across material composition, closure mechanisms, end-user channels, and size capacities. Discerning these distinct categories allows manufacturers to tailor product development and sales strategies to specific customer requirements and regulatory landscapes.
Material Type:
Regulatory frameworks from bodies like the U.S. Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) significantly differentiate material choices for pizza boxes, influencing food contact safety and recyclability. These regulations dictate permissible materials and chemical migration limits, particularly concerning recycled content and adhesives.
- Corrugated Cardboard:This material consists of fluted sheets sandwiched between flat linerboards, providing excellent structural strength and insulation for pizza transport. Its cost-effectiveness drives high-volume demand from large quick service restaurant chains in North America.
- Compostable Fiber:Derived from renewable resources like sugarcane bagasse or bamboo, this material offers a fully biodegradable and compostable packaging solution. Boutique pizzerias and health-focused food chains in Western Europe adopt it to signal strong environmental commitments.
- Solid Fiberboard:Composed of multiple layers of paperboard, this material offers a smoother surface for printing and good rigidity, often used for smaller, premium pizza boxes.
- Recycled Paperboard:Manufactured from post-consumer waste, this material provides an environmentally conscious option, though its use is subject to strict food contact safety regulations.
- Kraft Paper:Known for its natural brown appearance and high tear resistance, Kraft paper is sometimes used as a liner or for specialty pizza box designs.
- Plastic Laminated:This material incorporates a thin plastic layer for enhanced grease and moisture resistance, though its recyclability is often compromised.
Established volume favors Corrugated Cardboard; emerging adoption favors Compostable Fiber.
Closure Type:
The security and convenience of the pizza box closure system differentiate product offerings, directly impacting delivery efficiency and consumer satisfaction. Closure types vary based on the desired level of product protection and ease of assembly for food service operations.
- Tuck Flap:This standard closure involves flaps that tuck into slots, offering a simple, cost-effective, and widely adopted solution for high-volume pizza deliveries. Quick service restaurants in the United States primarily utilize this design for its efficiency.
- Peel & Seal:Featuring an adhesive strip, this closure provides enhanced tamper evidence and security, gaining traction in premium delivery applications for brand protection. This option appeals to food delivery platforms seeking to ensure product integrity.
- Lock Corner:This design uses interlocking tabs at the corners to create a sturdy, self-locking structure, often seen in smaller, artisanal pizza boxes.
- Sleeve Style:A two-piece design where a pizza tray slides into a sleeve, offering a more premium presentation for specialty pizzas.
- Interlocking Tabs:Similar to lock corners but with more complex tab arrangements, these closures provide additional structural stability for heavier pizzas.
- Magnetic Closure:Offering a high-end, reusable feel, this closure type is reserved for luxury food packaging or promotional items, not common for everyday pizza delivery.
The Tuck Flap design holds the largest market share, while Peel & Seal options are expanding most quickly.
End Use Channel:
The scale and operational demands of different end-use channels significantly shape pizza box procurement, with centralized purchasing by large platforms contrasting with localized needs. Each channel requires specific packaging attributes tailored to its unique delivery and customer interaction models.
- Delivery Platforms:These entities require consistent, high-volume, and scalable packaging solutions for their extensive network of restaurants and ghost kitchens. Centralized procurement by platforms like Uber Eats in North America drives demand for standardized box specifications.
- Quick Service Restaurants:Individual QSRs, such as Domino's or Pizza Hut, demand efficient, branded packaging that supports rapid order fulfillment and local customer pickup. These restaurants prioritize cost-effectiveness and brand visibility on their boxes.
- Full Service Establishments:Dine-in restaurants offering pizza for takeout or leftover packaging require durable boxes that reflect their brand quality, often incorporating custom designs.
- Food Trucks:Mobile food operations need compact, sturdy, and easy-to-assemble boxes that can withstand varied environmental conditions and rapid service.
- Catering Services:For large orders, catering companies demand robust, stackable boxes that can maintain temperature and integrity during bulk transport to events.
- Event Organizers:Organizers often procure pizza boxes for concessions or specific events, prioritizing ease of handling and sometimes requiring co-branding opportunities.
Quick Service Restaurants represent the largest volume segment, while Delivery Platforms exhibit the steepest expansion trajectory.
Size Capacity:
Pizza box size capacity directly correlates with pizza dimensions and customer preferences, reflecting regional variations in pizza styles and portioning. This segmentation ensures efficient packaging for a diverse range of pizza products, from personal to family-sized options.
- Small (8-10 Inch):These boxes cater to individual servings or personal pizzas, popular in urban centers across Europe for single-person meals.
- Medium (11-13 Inch):This size accommodates standard medium-sized pizzas, a common choice for smaller groups or couples in many North American markets.
- Large (14-16 Inch):Designed for family-sized pizzas, this capacity is a staple for household consumption and larger gatherings, particularly in the United States.
- Extra Large (17 Inch & Above):These boxes serve oversized or specialty pizzas, often found in gourmet pizzerias or for promotional offerings.
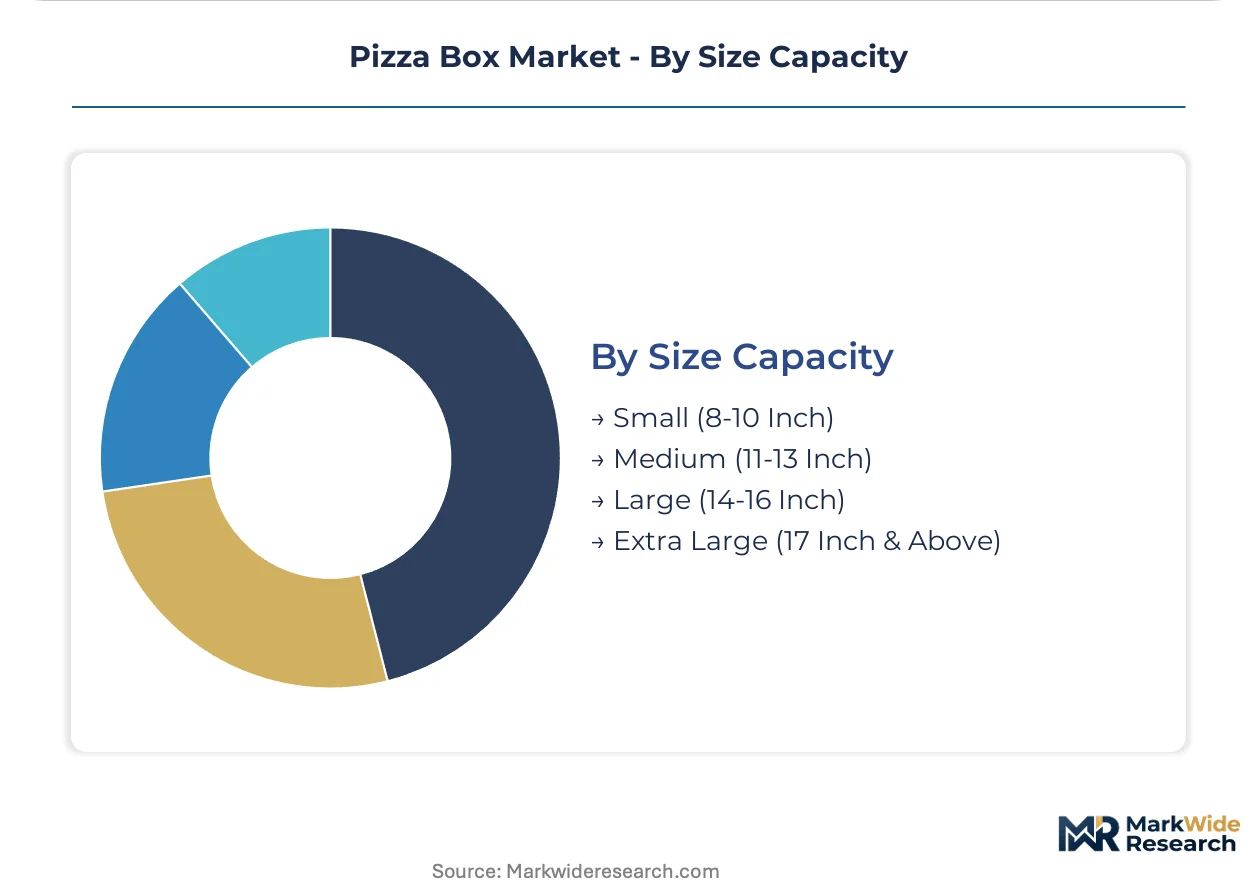
Large (14-16 Inch) sizes dominate sales volumes, with Small (8-10 Inch) growing in specific urban demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extensive logistics networks, particularly port infrastructure and road freight capabilities, underpin regional market dynamics for pizza boxes. These networks facilitate the efficient distribution of raw materials to manufacturing hubs and finished products to end-users. Local demand patterns, influenced by food delivery adoption and regulatory frameworks, further shape market growth across diverse geographies.
United States
High consumer demand for convenience foods and the mature food delivery ecosystem drive significant pizza box consumption. The U.S. Food and Drug Administration (FDA) regulations on food contact materials heavily influence packaging material choices. Major QSR chains and delivery platforms concentrate procurement in logistics hubs like Chicago and Dallas.
Germany
A strong focus on sustainability and robust recycling infrastructure underpins demand for eco-friendly pizza box solutions. The EU Green Deal and national packaging laws incentivize the design of easily recyclable and compostable packaging. Berlin and Munich are urban centers with high food delivery penetration, fostering localized demand.
China
Rapid expansion of online food delivery platforms and the proliferation of virtual kitchens fuel substantial volume growth. China's national standards (GB standards) for food packaging ensure material safety and quality control. Large manufacturing clusters in the Yangtze River Delta region serve both domestic and international markets.
India
The burgeoning urban population and increasing disposable incomes are boosting demand for packaged food and delivery services. The Food Safety and Standards Authority of India (FSSAI) regulates food packaging materials to ensure consumer safety. Cities like Mumbai and Bangalore exhibit high growth in quick service restaurant expansion.
Brazil
Urbanization trends and the rising popularity of food delivery apps contribute to sustained demand for pizza packaging. Brazil's national health surveillance agency (ANVISA) sets standards for food contact materials. São Paulo and Rio de Janeiro are key metropolitan areas experiencing significant growth in the food service sector.
Pizza Box Market Key Industry Players
Listed leaders compete with private specialists across scale and product differentiation in the pizza box market. The industry exhibits a tiered structure, with large integrated packaging companies alongside niche innovators. Strategic archetypes include global volume providers, sustainable material specialists, and custom design innovators. Dominant competitive moves involve capacity expansion to meet delivery platform demand and strategic partnerships for material innovation.
Among global packaging manufacturers, International Paper and Smurfit Kappa Group exemplify scale-driven operations, leveraging extensive production capabilities to serve high-volume accounts. WestRock Company also occupies a position as a broad portfolio provider across multiple end-use channels. These large entities often focus on cost-efficiency and standardized solutions for major delivery platforms and quick service restaurants.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| WestRock Company |
| International Paper |
| DS Smith |
| Georgia-Pacific |
| Mondi |
| Huhtamaki |
| New Method Packaging |
| Pakoro |
| Others |
Cost & Logistics Intelligence
Compostable fiber materials displacing traditional corrugated cardboard are reshaping supply geography toward agricultural waste-rich regions and introducing premium pricing tiers. This material substitution simultaneously drives localized production models and alters cost structures for packaging manufacturers.
Pricing Analysis
Volume-discount tiering structures dominate the pizza box market, reflecting the scale of procurement by large delivery platforms. Price differentiation stems from order volume for major quick-service restaurants and custom design complexity for smaller brands. Input cost volatility in recycled paper pulp and corrugated cardboard creates pricing pressure for manufacturers. Delivery platforms exhibit high price sensitivity, while premium pizzerias accept higher costs for sustainable materials or enhanced features.
Supply Chain Analysis
Inventory management for pizza boxes emphasizes just-in-time delivery due to bulk storage challenges and rapid turnover in quick-service environments. Corrugated cardboard production concentrates in China and the United States, while Brazil and India are expanding their fiber feedstock capacity. The supply chain relies heavily on virgin wood pulp and recycled paper pulp, making it vulnerable to commodity price volatility. Distribution runs through established logistics networks directly to delivery platform hubs and individual restaurant franchisees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pizza box market sits at a platform-economics inflection point as centralized delivery platforms standardize procurement and demand consistent packaging solutions. This shift necessitates new interoperability between manufacturers and logistics providers.
For Market Incumbents:Compound existing production scale to meet the consistent, high-volume demands of global delivery platforms. Invest in automated manufacturing processes to enhance cost efficiency and secure long-term supply agreements with major quick-service restaurant chains. Develop PFAS-free grease-resistant coatings through dedicated R&D to navigate evolving regulatory landscapes in the United States and Europe. Expand capabilities in compostable fiber production to counter the threat from sustainable material specialists.
For New Entrants and Emerging Players:Anchor in niche markets that prioritize sustainable materials and premium customization, such as boutique pizzerias in Western Europe. Target the growing segment of health-focused food chains in North American urban centers seeking eco-friendly packaging. Offer innovative molded fiber designs with unique branding opportunities to differentiate from commodity corrugated boxes. Penetrate new delivery platforms by providing specialized packaging for non-pizza delivered foods, expanding the product portfolio.
For Investors and Strategic Acquirers:The market sits at a consolidation phase that favors integrated packaging specialists with robust R&D in sustainable materials. Long-term viability remains strong, driven by the persistent growth of food delivery ecosystems over the next 5-10 years. Prioritize acquisition targets possessing advanced molded fiber technology or proprietary PFAS-free grease barrier formulations. The signal to watch is the widespread adoption of mandatory extended producer responsibility schemes in key European and North American markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Compostable Materials | Increases supply of eco-friendly options for brands targeting sustainability-conscious consumers. |
| R&D Investment in PFAS-Free Coatings | Ensures compliance with evolving food safety regulations from the FDA and EFSA, maintaining market access. |
| Strategic Partnerships with Delivery Platforms | Secures high-volume, long-term contracts and standardizes packaging specifications across large networks. |
| Development of Smart Packaging Solutions | Offers value-added features like QR codes for marketing, enhancing brand engagement and product traceability. |
| Geographic Diversification into Emerging Markets | Captures new demand from rapidly expanding food delivery ecosystems in Southeast Asia and Latin America. |
Research Approach
The analysis maps material types, closure mechanisms, and end-use channels, each validated through extensive primary interviews with packaging engineers, procurement managers, and food safety regulators. This primary data was then cross-referenced with secondary sources, including company annual reports, government publications from the FDA and EFSA, and industry trade association data. A rigorous bottom-up and top-down triangulation approach ensured the consistency and accuracy of market estimates.
Forecast outputs were rigorously checked for consistency against established industry benchmarks and macroeconomic indicators across the projection horizon. The analytical framework segmented the market by material type, closure type, end-use channel, size capacity, and regional adoption patterns. Compound annual growth rates were derived from historical growth trends and projected future demand drivers. Key forecast inputs included ghost kitchen expansion and evolving PFAS regulations.
Decision-makers should treat outputs as directional under base assumptions of stable raw material prices and consistent regulatory enforcement; material deviation would warrant model refresh. Unforeseen shifts in global trade policies or rapid technological breakthroughs could alter market trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Edible Oil Packaging Market
Food Packaging
Disposable Hot Cups & Lids Market
Food Packaging
Seafood Packaging Market
Food Packaging
Europe Canned Food Packaging Market
Food Packaging
Chocolate Packaging Market
Food Packaging
Food Partition Trays Market
Food Packaging
Food Punnets Market
Food Packaging
Spices, Dry Seasoning Mix, and Herbal Extract Packaging Market
Food Packaging
Foam Food Container Market
Food Packaging
Drink Carrier and Trays Market
Food Packaging
North America Canned Food Packaging Market
Food Packaging
Nordic Beverage Packaging Market
Food Packaging
Ambient Food Products Packaging Market
Food Packaging
Food Tub Packaging Market
Food Packaging
Europe Frozen Food Packaging Market
Food Packaging
Disposable Food Containers Market