
 Semiconductor LPCVD Furnaces Market | 2026-2036
Semiconductor LPCVD Furnaces Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor LPCVD Furnaces Market Insights
Aftermarket service revenue is fragmenting across installed-base tiers as tool complexity outpaces in-house maintenance capabilities at mature fabs. Applied Materials leverages its global parts logistics network to capture long-term service contracts. Tokyo Electron anchors its position through localized field engineering teams in East Asian manufacturing clusters. Kokusai Electric Corporation differentiates via proprietary chamber refurbishment protocols that extend furnace lifecycles.
Semiconductor LPCVD furnaces deposit thin films through thermal decomposition of precursor gases in controlled low-pressure environments, typically operating between 500°C and 900°C with batch capacities ranging from 25 to 200 wafers. These systems enable conformal nitride, oxide, and polysilicon layers critical to transistor gate stacks and isolation structures in integrated circuit fabrication. Vertical reactor configurations command premium positioning as memory manufacturers scale 3D NAND layer counts beyond two hundred tiers. Batch processing technology retains cost advantages for mature-node analog and power semiconductor production where throughput economics outweigh single-wafer precision. Silicon carbide deposition represents the fastest-growing technology segment, driven by electric vehicle power module foundries migrating from silicon substrates.
The EPA enforces stringent hazardous air pollutant limits on semiconductor manufacturing emissions, compelling furnace vendors to integrate abatement systems and alternative chemistries. Japan's METI coordinates domestic equipment standards through JIS certification pathways that govern thermal process tool safety and energy efficiency benchmarks. China's MEE implements dual carbon compliance audits that penalize high-temperature process tools lacking heat recovery architecture. Stakeholders must weigh regulatory capital requirements against the migration timeline from batch to single-wafer platforms.
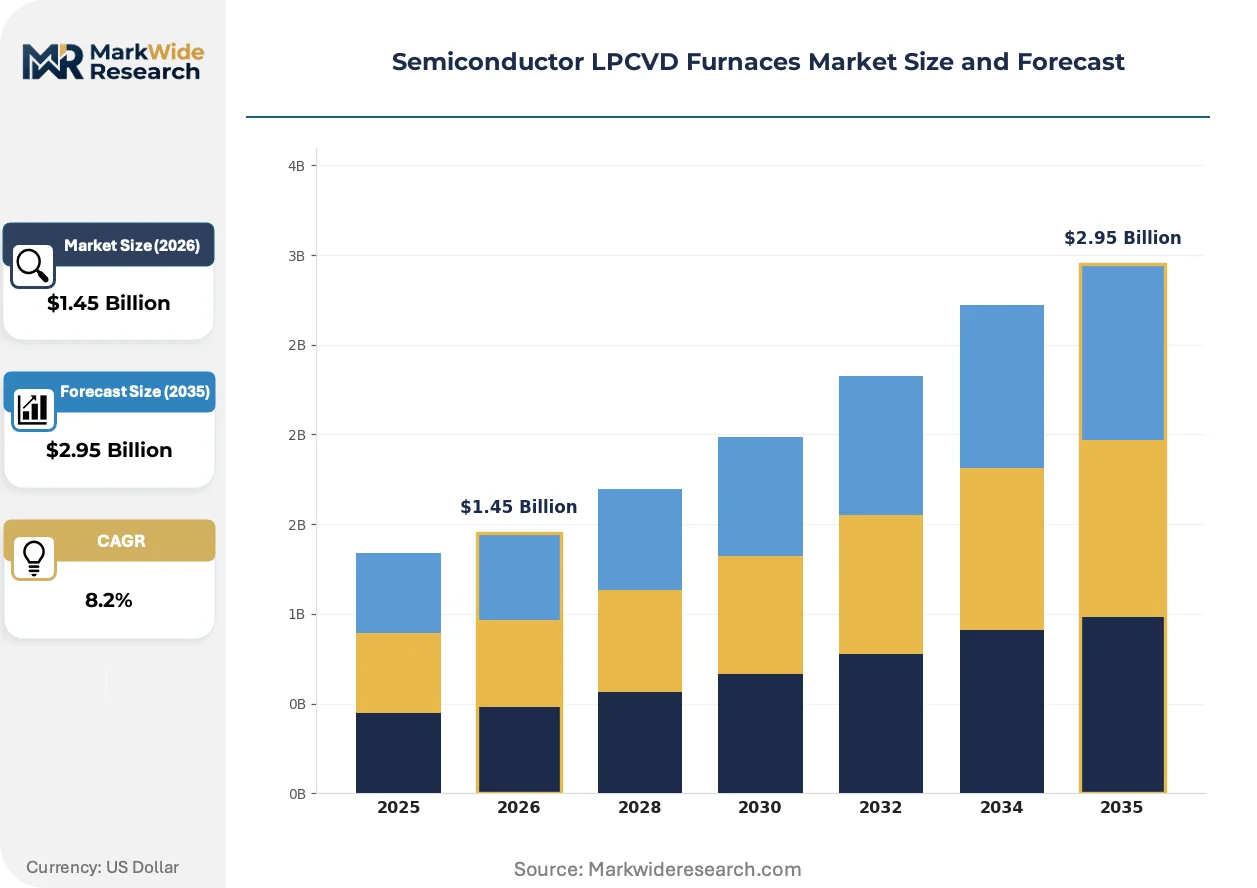
Market Dynamics
3D NAND layer stacking beyond two hundred tiers is compressing thermal process windows and forcing furnace vendors to retool vertical reactor architectures for atomic-scale uniformity control.
Growth Catalysts
- Dual carbon compliance audits:China's MEE enforcement is accelerating heat-recovery furnace retrofits across domestic foundry installations, pulling upgrade cycles forward by several quarters.
- Silicon carbide power modules:Electric vehicle traction inverter demand is expanding LPCVD capacity for SiC epitaxy deposition at automotive-qualified fabs.
- East Asian manufacturing clusters:Taiwan and South Korea concentrate advanced-node logic investment, sustaining premium equipment procurement velocity through the forecast window.
Market Restraints
- Helium supply concentration:Rare gas dependencies for wafer cooling systems expose tool operators to price volatility from Qatar and US extraction bottlenecks.
- EU F-Gas phasedown:Refrigerant restrictions on thermal management subsystems are extending qualification timelines for new furnace platforms bound for European cleanrooms.
- Single-wafer precision gap:Batch LPCVD systems face technical ceiling effects at sub-7nm nodes where atomic layer deposition tools capture critical layer formation.
Strategic Opportunities
- India's semiconductor PLI scheme:Greenfield fab incentives are creating first-mover advantage for furnace vendors establishing localized service infrastructure.
- Chamber refurbishment protocols:Proprietary recoating and component renewal services extend furnace lifecycles, capturing recurring revenue from mature-node operators.
- 5G mmWave RF front-ends:Gallium nitride-on-silicon deposition demand is opening adjacent process equipment applications beyond mainstream CMOS.
Industry Challenges
- Vacuum technology specialization:Turbo-molecular pump maintenance and dry-roughing expertise shortages are constraining in-house uptime capabilities at mid-scale fabs.
- Abatement system integration:EPA hazardous air pollutant limits require real-time emissions monitoring retrofits that complicate legacy furnace certification renewals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor LPCVD Furnaces Market |
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.95 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Wafer, Batch, Vertical, Horizontal Technology: Nitride, Oxide, Poly-Si, Silicon Carbide End User: Microelectronics, MEMS, Optoelectronics, Photovoltaics Installation: Clean Room, Research Facilities, Manufacturing Lines, Universities |
| Companies Covered | Kokusai Electric Corporation, Corning Incorporated, Applied Materials, NGK Insulators, Entegris, Lam Research, CoorsTek, Kyocera Corporation, Tokyo Electron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor LPCVD Furnaces Market Trends and Innovations
Thermal process equipment is pivoting toward energy-recovery architectures and predictive maintenance platforms as regulatory pressure and uptime economics converge on furnace operations.
Vertical reactor designs are migrating from horizontal tube configurations in memory fabrication facilities scaling 3D NAND architectures. Samsung and SK Hynix deployment timelines are compressing qualification cycles for multi-station cluster tools. This technology migration is enabling conformal deposition across extreme aspect-ratio structures while displacing legacy batch platforms from leading-edge capacity planning.
The EU F-Gas Regulation is tightening refrigerant phase-down schedules for thermal management equipment used in semiconductor manufacturing. Tool vendors must redesign chiller subsystems using alternative chemistries or sealed-cycle architectures. European-bound furnace shipments now face extended certification timelines, pushing procurement decisions toward compliant pre-certified platforms.
Aftermarket service unbundling is fragmenting long-term maintenance contracts across equipment tiers. Foundry operators are separating parts logistics from field engineering, creating openings for specialized refurbishment providers. This behavioral shift is most pronounced in Taiwan's Science Park clusters where multi-vendor tool mixes complicate single-source service dependencies.
Semiconductor LPCVD Furnaces Market Segmentation
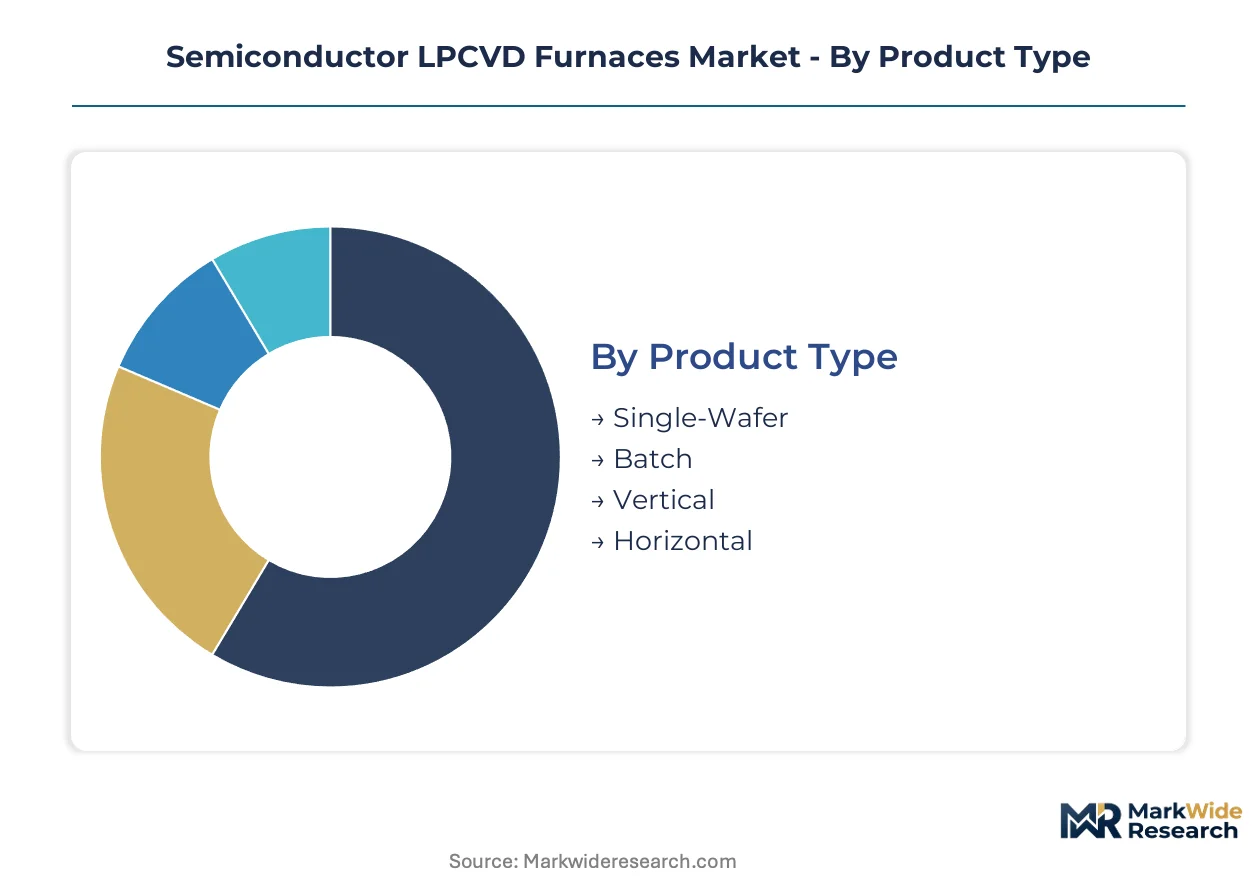
Equipment segmentation in the Semiconductor LPCVD Furnaces Market shapes aftermarket service intensity, spare parts forecasting, and field engineering deployment. Thermal process tool complexity varies sharply across reactor architectures, creating tiered maintenance ecosystems that vendors must navigate.
Product Type:
After-sales service intensity escalates with reactor sophistication, as vertical and single-wafer platforms demand specialized field engineering capabilities that batch systems rarely require.
- Vertical:Multi-station cluster tools achieve atomic-scale uniformity across extreme aspect-ratio structures in 3D NAND fabrication. Samsung and SK Hynix deployment timelines in South Korea compress qualification cycles and sustain premium spare parts procurement. By volume, batch systems lead. By growth pace, vertical configurations are ahead.
- Single-Wafer:Precision deposition at sub-7nm nodes demands real-time process control and dedicated chamber matching protocols. Taiwan's advanced-node foundries anchor procurement velocity as logic manufacturers migrate from batch platforms.
- Batch:Mature-node analog and power semiconductor production favors throughput economics over atomic precision.
- Horizontal:Legacy tube configurations face displacement from memory fabrication capacity planning.
Vertical reactor architectures command premium positioning as layer stacking requirements intensify.
Technology:
Deposition chemistry determines precursor gas handling complexity, abatement system specifications, and chamber refurbishment protocols across installed-base tiers.
- Silicon Carbide:Epitaxy deposition for electric vehicle power modules operates at elevated temperatures requiring specialized susceptor materials and thermal management. Automotive-qualified fabs in Germany and Japan are expanding capacity fastest.
- Nitride:Conformal silicon nitride layers form critical isolation structures and gate dielectrics in transistor stacks. Memory manufacturers in Taiwan and South Korea sustain dominant procurement share.
- Oxide:Thermal silicon dioxide deposition serves isolation and masking applications across mature technology nodes.
- Poly-Si:Polysilicon gate electrode formation retains relevance in specialty foundry processes.
By volume, nitride deposition leads. By expansion trajectory, silicon carbide is climbing fastest.
End User:
Customer type dictates equipment specification, certification requirements, and service contract structures across the installed base.
- Microelectronics:Foundry and IDM operations demand 24/7 uptime guarantees, predictive maintenance platforms, and rapid spare parts logistics. Taiwan's Science Park clusters concentrate the highest service contract density.
- MEMS:Sensor and actuator fabrication requires process flexibility for diverse substrate materials and release etch compatibility.
- Optoelectronics:Laser and photodetector manufacturing applies LPCVD to compound semiconductor heterostructures.
- Photovoltaics:Solar cell production favors batch throughput economics for antireflection coating deposition.
By volume, microelectronics leads. By service intensity per tool, MEMS is ahead.
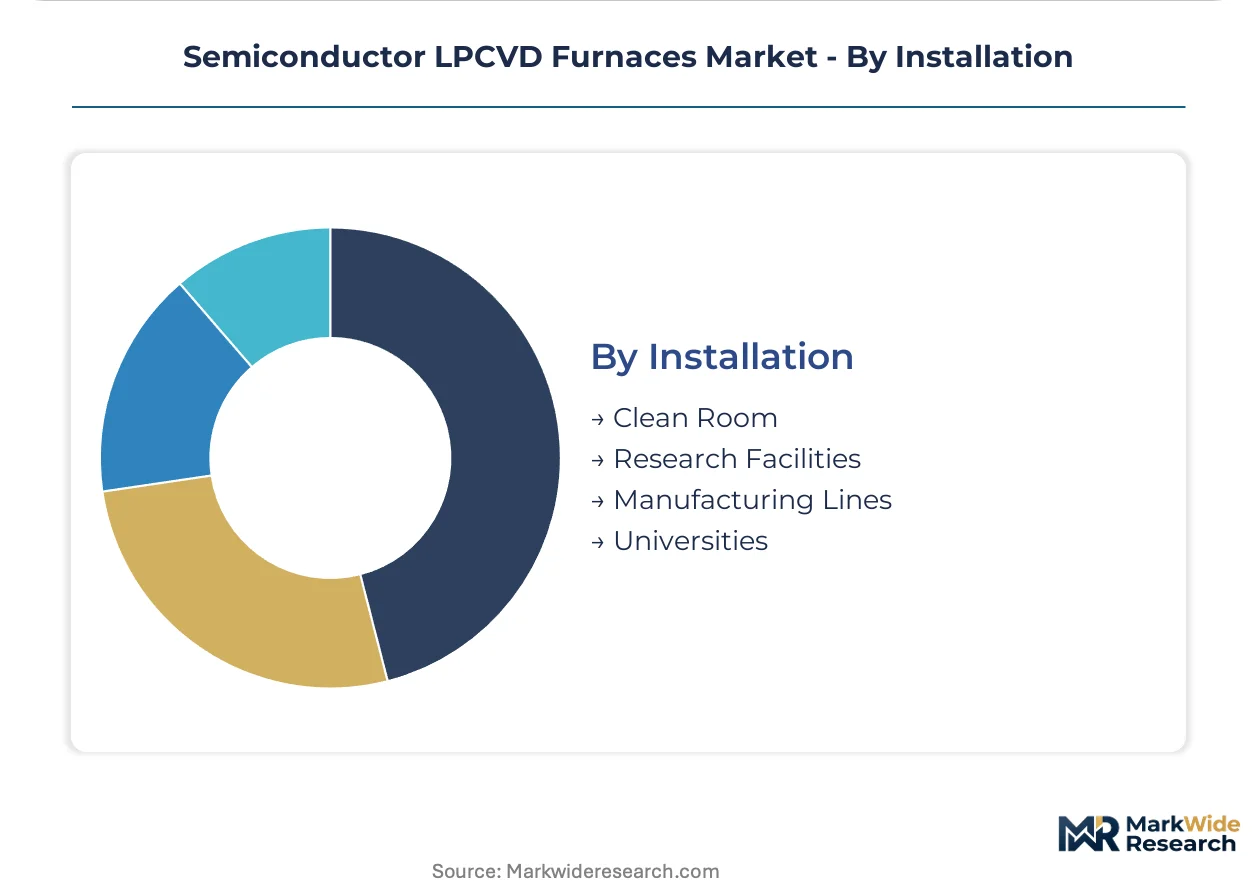
Installation:
Facility classification determines cleanroom classification requirements, regulatory compliance scope, and equipment qualification protocols.
- Manufacturing Lines:High-volume production environments integrate furnaces into automated material handling systems with statistical process control feedback. South Korean and German automotive-qualified fabs enforce the most stringent chamber matching specifications.
- Clean Room:ISO-classified environments for leading-edge logic and memory fabrication impose particle control and electrostatic discharge protocols.
- Research Facilities:Process development centers require rapid recipe switching capabilities and flexible precursor delivery.
- Universities:Academic installations prioritize training accessibility and multi-user safety interlocks over throughput optimization.
By volume, manufacturing lines lead. By equipment specification complexity, clean room installations are ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: East Asian fabs prioritize vertical reactor upgrades for 3D NAND stacking, while European and North American installations emphasize emissions-compliant retrofits over greenfield capacity.
China
Domestic foundries are accelerating heat-recovery furnace deployments ahead of MEE dual carbon compliance audits. MIIT coordinates equipment certification through GB standards that govern thermal process tool energy efficiency. Yangtze River Delta clusters in Shanghai and Wuxi concentrate the bulk of retrofit procurement as local DRAM and logic fabs expand 300mm capacity.
United States
EPA hazardous air pollutant enforcement is compelling abatement system integration across legacy tool installations. The CHIPS and Science Act directs federal incentives toward domestic cleanroom construction in Arizona and Texas. Intel's Ohio and Arizona fabs anchor procurement velocity for advanced-node vertical reactors through the forecast window.
Germany
Automotive-qualified SiC epitaxy capacity is expanding fastest in Bavaria and Saxony as EV traction inverter demand pulls equipment investment. The EU F-Gas Regulation tightens refrigerant phase-down schedules for thermal management subsystems. Dresden's Silicon Saxony cluster sustains premium equipment specification for power semiconductor foundries.
South Korea
Samsung and SK Hynix deployment timelines compress qualification cycles for multi-station cluster tools beyond two hundred 3D NAND tiers. METI-aligned JIS certification pathways govern safety benchmarks for Japanese-origin equipment imports. Pyeongtaek and Icheon manufacturing corridors concentrate dominant procurement share for memory-specific vertical reactor architectures.
Taiwan
TSMC and UMC operations sustain the highest service contract density globally as foundry operators unbundle maintenance across multi-vendor tool mixes. Science Park clusters in Hsinchu and Tainan enforce 24/7 uptime guarantees with predictive maintenance platform integration. Advanced-node logic investment at 3nm and below pulls single-wafer precision tool migration ahead of batch system retirement.
Semiconductor LPCVD Furnaces Market Competitive Landscape
Capability concentration sits with specialized furnace architects; scale advantage sits with diversified process equipment conglomerates. The vendor base organizes around three strategic archetypes: integrated thermal process platforms, ceramic component specialists, and aftermarket service pure-plays. Consolidation pressure favors M&A activity among ceramic susceptor and chamber material suppliers. Geographic expansion into India's PLI-subsidized greenfield fabs represents a second dominant competitive vector.
Within the integrated equipment tier, Applied Materials and Tokyo Electron exemplify scale-driven platform vendors with global service logistics networks. Kokusai Electric Corporation occupies a specialized position in batch vertical reactor architectures with proprietary refurbishment protocols. These three anchors represent divergent strategic postures: diversified thermal process breadth, localized East Asian field engineering density, and lifecycle extension services for mature-node operators.
| Leading Market Players |
|---|
| Kokusai Electric Corporation |
| Corning Incorporated |
| Applied Materials |
| NGK Insulators |
| Entegris |
| Lam Research |
| CoorsTek |
| Kyocera Corporation |
| Tokyo Electron |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta manufacturing clusters in Shanghai and Wuxi concentrate heat-recovery furnace retrofit capacity ahead of China's MEE dual carbon compliance audits. This geographic concentration grants domestic foundry operators pricing leverage over imported vertical reactor platforms while compressing margins for vendors lacking localized service infrastructure.
Pricing Analysis
Long-term service contracts dominate procurement structures for vertical reactor installations, with foundry operators binding equipment vendors to multi-year uptime guarantees and predictive maintenance platform integration. Price differentiation stems from JIS certification tier and after-sales service bundling intensity. Cost compression in batch system tiers is intensifying because mature-node analog fabs prioritize throughput economics over atomic-scale precision. Memory manufacturers scaling 3D NAND architectures exhibit the least price sensitivity, while photovoltaic cell producers remain most responsive to per-wafer throughput metrics.
Supply Chain Analysis
Extended payment terms from South Korean memory fabs are reshaping supplier financing structures for turbo-molecular pump and ceramic suspector manufacturers. Component sourcing draws from Japan, Germany, and the United States for specialized vacuum technology and thermal management subsystems. Single-source vulnerability concentrates in helium extraction from Qatar and US facilities for wafer cooling systems. Distribution runs through authorized service partners in Taiwan's Science Park clusters and direct OEM channels for greenfield installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
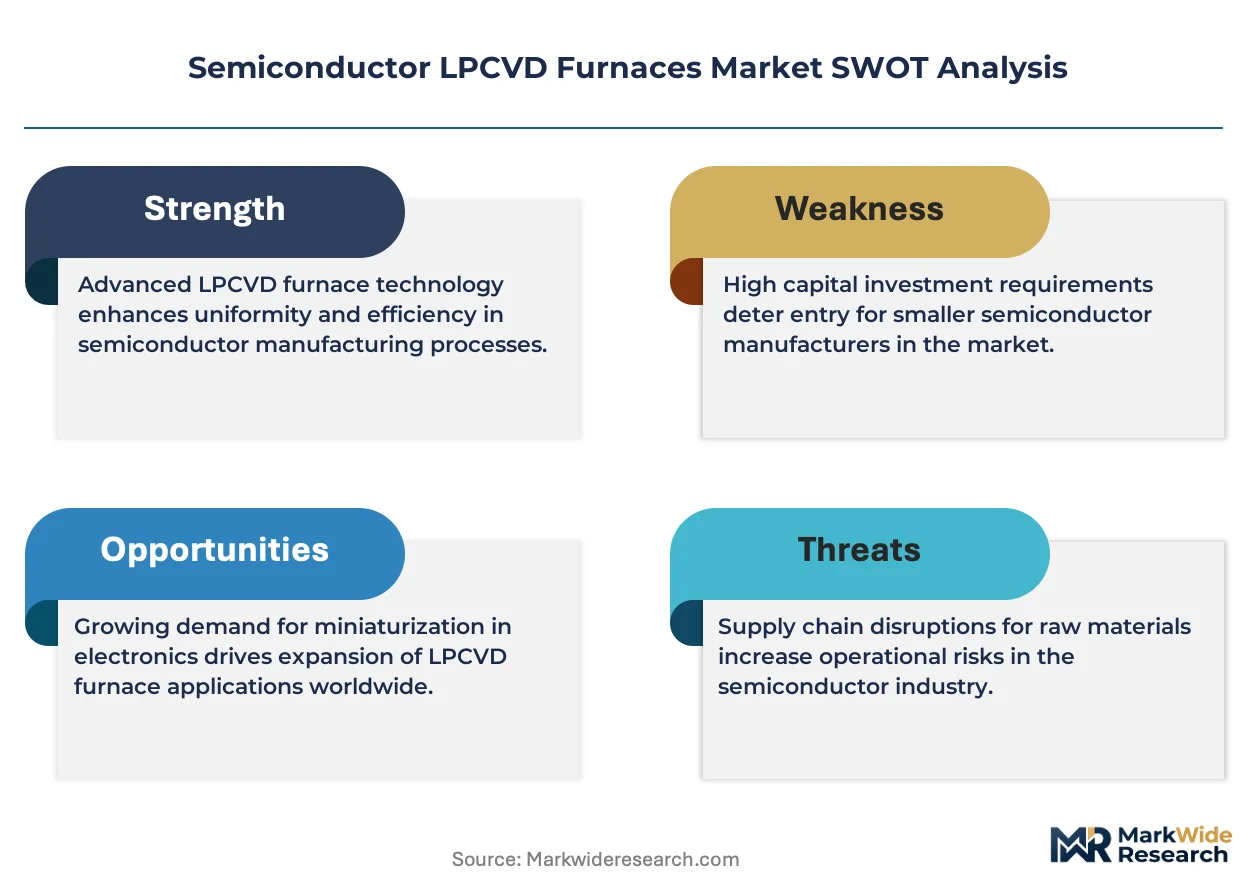
Single-wafer atomic layer deposition tools threaten batch LPCVD furnace relevance at sub-7nm nodes, forcing incumbent vendors to defend installed-base positions through lifecycle extension services.
For Market Incumbents: Entrench market position through proprietary chamber refurbishment protocols that extend furnace lifecycles at mature-node analog and power semiconductor fabs. Capture recurring revenue from heat-recovery retrofits ahead of China's MEE dual carbon compliance enforcement. Prioritize backward integration into ceramic susceptor manufacturing to secure supply chain control over specialized thermal components. For New Entrants and Emerging Players: India's semiconductor PLI scheme subsidized greenfield fabs represent the most penetrable entry point for furnace vendors establishing localized service infrastructure. Automotive-qualified SiC epitaxy deposition capacity in Germany and Japan offers secondary white-space for specialized vertical reactor architectures. Lead with predictive maintenance platform integration as the primary go-to-market angle to differentiate from established parts-logistics competitors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors aftermarket service pure-plays with proprietary refurbishment capabilities over capital-intensive equipment manufacturing. Long-term viability hinges on chamber recoating protocol IP and installed-base density in Taiwan and South Korea. Watch for inflection signals in 3D NAND layer stacking timelines beyond two hundred tiers, which compress qualification cycles and accelerate premium equipment procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Chamber Refurbishment Protocol Development | Proprietary recoating IP extends furnace lifecycles at mature-node operators, capturing recurring revenue streams. |
| Heat-Recovery Architecture Integration | MEE dual carbon compliance audits in China penalize high-temperature tools lacking energy recovery systems. |
| Predictive Maintenance Platform Deployment | Taiwan's Science Park clusters enforce 24/7 uptime guarantees through real-time process monitoring integration. |
| Ceramic Susceptor Manufacturing Integration | Backward integration into specialized thermal components reduces single-source dependency from Japanese suppliers. |
| Localized Service Infrastructure Establishment | India's PLI-subsidized greenfield fabs create first-mover advantage for vendors with domestic field engineering teams. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC equipment vendor filings, customs trade data, and national semiconductor industry association reports. Primary interviews engaged fab operations directors, thermal process tool procurement managers, aftermarket service heads, and chamber refurbishment technicians across Taiwan, South Korea, Germany, and China. Secondary validation drew from EPA hazardous air pollutant enforcement records, METI JIS certification databases, and MIIT GB standards documentation. Bottom-up installed-base modeling and top-down equipment spend forecasts were triangulated against foundry capex disclosure patterns.
Forecast inputs incorporate reactor architecture migration timelines, 3D NAND layer stacking roadmaps, and SiC epitaxy capacity buildouts across automotive-qualified fabs. Segmentation dimensions span product type, deposition technology, end-user category, and installation environment. CAGRs were derived from equipment procurement velocity indexed to foundry construction timelines and retrofit cycle compression. Regulatory enforcement calendars for EU F-Gas phase-down and China's dual carbon audits shaped regional demand weightings.
Stress conditions across helium supply disruption, sub-7nm node transition acceleration, and EU refrigerant restriction timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding memory manufacturer 3D NAND scaling commitments and automotive EV traction inverter demand trajectories. Macroeconomic contraction, unilateral tariff escalation, or breakthrough single-wafer deposition cost parity would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Acid Filling and Leveling Machine Market
Semiconductor Equipment
Thin Film Deposition Equipment Market
Semiconductor Equipment
Global Resist Processing Equipment Market
Semiconductor Equipment
Electrostatic Chucks Market
Semiconductor Equipment
Semiconductor Assembly Equipment Market
Semiconductor Equipment
Global Capacitor Winding Machines Market
Semiconductor Equipment
OLED Vacuum Evaporation Machine Market
Semiconductor Equipment
Global Sputtering Equipment Market
Semiconductor Equipment
Laser Micro Perforation Equipment Market
Semiconductor Equipment
China Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Africa Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
PVD Coaters Market
Semiconductor Equipment
Global Atomic Layer Deposition (ALD) Equipment Market
Semiconductor Equipment
300 Mm Front Opening Unified Pods (Foups) Market
Semiconductor Equipment
Selective Soldering Equipment Market
Semiconductor Equipment
4-Inch SiC Laser Annealing Equipment Market