
 Bit Error Rate Tester Market | 2026-2036
Bit Error Rate Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Bit Error Rate Tester Market Analysis
Multi-source procurement among telecommunications OEMs is consolidating around fewer qualified BER test suppliers with full portfolio coverage. Keysight Technologies leverages its PXI modular platform to sustain dominance in high-speed electrical testing. Anritsu Corporation anchors its position through coherent optical instruments calibrated to 800G standards. Rohde & Schwarz competes on RF signal integrity extensions for satellite and defense link validation.
A bit error rate tester quantifies the probability of erroneous bits in a digital data stream, typically resolving to bit-error ratios as low as 10^-12 through pattern generation and error detection circuitry operating at symbol rates exceeding 100 Gbaud. Its primary commercial purpose is certifying that transceivers, cables, and network elements meet specified performance thresholds before field deployment. Desktop testers occupy the mature revenue core where margin pools remain deepest for established vendors serving compliance laboratories. Rack-mount testers represent the fastest-growing configuration as hyperscale data centers integrate continuous line monitoring into production environments. Automated testers command premium positioning where EXFO and Spirent Communications embed machine-learning-driven pass-fail analytics.
The FCC in the United States mandates bit-error performance benchmarks for licensed microwave backhaul, while China's MIIT enforces GB standards for domestic optical transceiver certification. The EU AI Act and CSRD indirectly shape demand by requiring auditable network infrastructure documentation that BER test logs satisfy. Stakeholders must monitor whether emerging 1.6T coherent standards fragment calibration requirements or consolidate them under fewer protocol umbrellas.
Market Dynamics
Coherent optical technology upgrades and DSP integration are compressing instrument replacement cycles as telecommunications OEMs demand test equipment calibrated to 800G and emerging 1.6T standards. This technological forcing function is redrawing supplier qualification criteria and procurement consolidation patterns.
Growth Catalysts
- 5G backhaul deployment:Telecommunications carriers in the United States, China, and Germany are accelerating fiber-to-the-home and microwave backhaul investments that require BER certification before field activation.
- FCC microwave licensing:The United States regulator mandates bit-error performance benchmarks for licensed microwave backhaul, creating compliance-driven instrument refresh cycles among infrastructure operators.
- Hyperscale data center buildouts:Cloud service providers are integrating continuous line monitoring into production environments, expanding demand for rack-mount test configurations.
Market Restraints
- High-precision component costs:Pattern generation and error detection circuitry operating above 100 Gbaud requires specialized semiconductors subject to foundry allocation constraints.
- Supplier concentration:Qualified BER test suppliers with full portfolio coverage are consolidating around fewer vendors, reducing buyer negotiation leverage.
- Calibration fragmentation risk:Emerging 1.6T coherent standards may splinter calibration requirements across incompatible protocol umbrellas, complicating equipment interoperability.
Strategic Opportunities
- Machine-learning analytics integration:Automated testers embedding AI-driven pass-fail analytics command premium positioning in compliance laboratories and production environments.
- EU regulatory tailwinds:The EU AI Act and CSRD require auditable network infrastructure documentation that BER test logs satisfy, expanding addressable demand for traceable test data.
- Satellite and defense link validation:RF signal integrity extensions for non-terrestrial communications represent underpenetrated application space beyond traditional telecommunications.
Industry Challenges
- 100+ Gbaud signal integrity engineering:The specialized skill set required for high-speed electrical and coherent optical testing faces acute talent scarcity across instrument vendors and end-user laboratories.
- Legacy system integration:Hyperscale data centers must embed new rack-mount testers alongside existing monitoring infrastructure without disrupting continuous production operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bit Error Rate Tester Market |
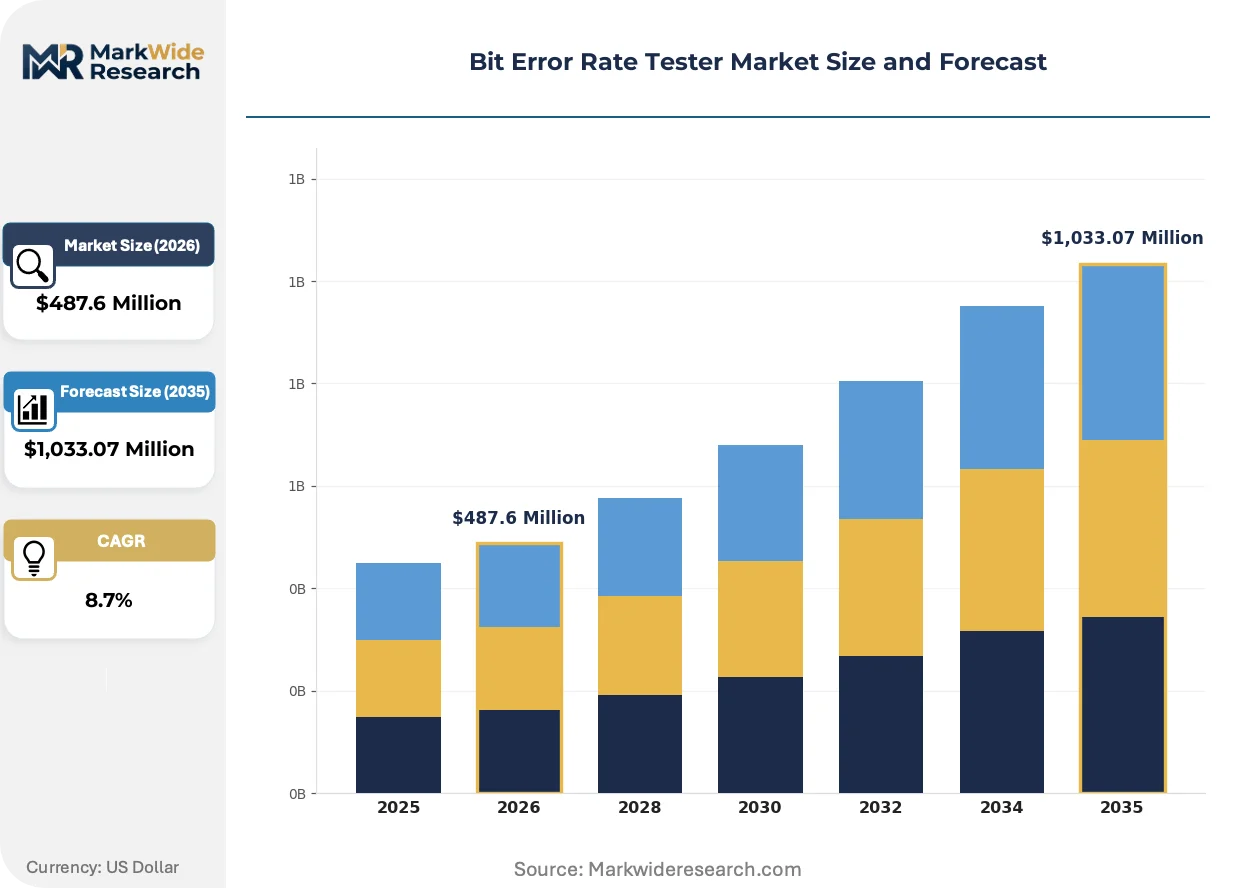
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Testers, Desktop Testers, Rack-Mount Testers, Automated Testers End User: Telecommunications Companies, Data Centers, Research Institutions, OEMs Technology: Coherent Optical Technology, Digital Signal Processing, Electrical Testing, Fiber Optics Application: Network Performance Testing, System Validation, Signal Integrity Testing, Compliance Testing |
| Companies Covered | Keysight Technologies, Anritsu Corporation, Tektronix, VIAVI Solutions, Rohde & Schwarz, Spirent Communications, EXFO, Ixia, NTS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bit Error Rate Tester Market Emerging Trajectories
Digital signal processing architectures are displacing analog front-ends in high-speed test equipment, enabling software-defined measurement flexibility that hardware-centric platforms cannot match. This architectural pivot is reshaping R&D roadmaps and buyer evaluation criteria simultaneously.
PXI modular platforms are converging with software-defined radio architectures to create reconfigurable test systems. Telecommunications OEMs and compliance laboratories are adopting these flexible configurations at accelerating pace. The convergence is compressing capital equipment refresh cycles by allowing firmware upgrades to extend instrument utility across multiple standard generations.
The EU AI Act and CSRD documentation mandates are forcing network infrastructure operators to maintain auditable test logs with machine-readable traceability. Equipment vendors must embed automated data export and cryptographic verification features. Data center operators in Germany and France are responding by specifying testers with integrated compliance reporting modules in procurement tenders.
Continuous line monitoring is displacing periodic batch testing in hyperscale production environments. Cloud service providers are unbundling after-sales service contracts and bringing calibration and maintenance in-house to reduce downtime exposure. This behavioral shift is most visible in United States and China data center clusters where facility-scale instrument deployments exceed 500 units per campus.
Bit Error Rate Tester Market Segmentation
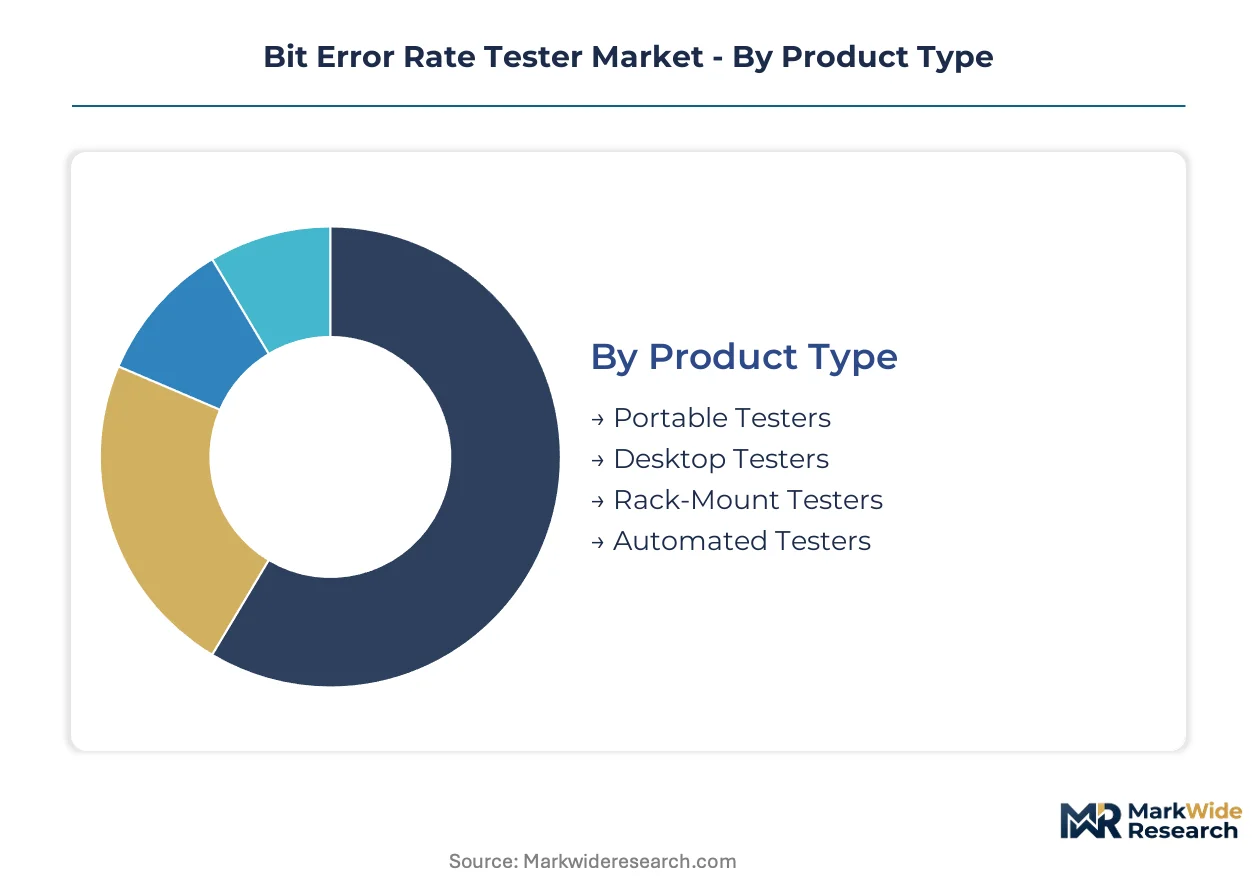
Segmentation in the Bit Error Rate Tester Market reveals how certification requirements, deployment environments, and signal complexity dictate procurement patterns. Test equipment buyers select configurations based on whether validation occurs in laboratory, production floor, or field conditions.
Product Type:
Certification burdens vary sharply across form factors, with rack-mount and automated configurations facing the most stringent FCC and MIIT documentation requirements for continuous monitoring deployments.
- Desktop Testers:These instruments integrate pattern generation and error detection circuitry in benchtop enclosures optimized for laboratory calibration workflows. Compliance laboratories in Germany and the United States concentrate procurement here, driven by FCC microwave licensing and EU AI Act documentation mandates that require traceable bit-error ratios down to 10^-12.
- Rack-Mount Testers:Designed for 19-inch equipment bays with remote management interfaces, these units support continuous line monitoring in hyperscale production environments. Cloud service providers in the United States and China specify these configurations for facility-scale deployments exceeding 500 units per campus.
- Portable Testers:Battery-operated field units with simplified interfaces for technician deployment at cell towers and fiber access nodes.
- Automated Testers:Systems embedding machine-learning-driven pass-fail analytics for high-throughput manufacturing lines.
Desktop testers sit at the top of the volume ranking, with rack-mount testers climbing the fastest.
End User:
Cost tier stratification separates capital-intensive hyperscale operators from budget-constrained research facilities, with telecommunications carriers occupying the premium procurement band.
- Telecommunications Companies:National carriers and mobile network operators drive instrument refresh cycles through 5G backhaul and fiber-to-the-home deployment mandates. Verizon, China Mobile, and Deutsche Telekom specify equipment calibrated to 800G coherent standards with DSP integration for optical transceiver certification.
- Data Centers:Hyperscale cloud providers unbundle after-sales service contracts and internalize calibration to reduce downtime exposure. Amazon Web Services, Microsoft Azure, and Alibaba Cloud dominate procurement volume for rack-mount configurations with continuous monitoring capabilities.
- Research Institutions:Universities and national laboratories acquire benchtop units for protocol development and standards body participation.
- OEMs:Optical transceiver manufacturers integrate BER testing into production lines for outgoing quality verification.
Telecommunications companies command the largest installed base, while data centers gain share fastest.
Technology:
Application requirements determine technology selection, with coherent optical and DSP architectures displacing legacy electrical testing in next-generation deployments.
- Coherent Optical Technology:Instruments employing dual-polarization quadrature amplitude modulation support symbol rates exceeding 100 Gbaud for 800G and emerging 1.6T transceiver validation. Telecommunications OEMs in China and Germany demand these platforms as national broadband initiatives accelerate fiber deployment.
- Digital Signal Processing:Software-defined measurement architectures enable firmware-upgradable flexibility across multiple standard generations. PXI modular platforms from Keysight Technologies leverage DSP to compress capital equipment refresh cycles in United States compliance laboratories.
- Electrical Testing:High-speed serial bus validation for chip-to-chip and backplane interconnects in server and storage equipment.
- Fiber Optics:Physical layer characterization for insertion loss, return loss, and optical power measurements in access network deployment.
Coherent optical technology anchors current revenue, with DSP integration expanding most quickly.
Application:
Customer type and margin structure differentiate application segments, with compliance testing commanding premium pricing due to documentation and auditability requirements.
- Compliance Testing:Formal certification workflows generating auditable test logs for regulator submission, including FCC microwave licensing and China's MIIT GB standards enforcement. The EU AI Act and CSRD expand addressable demand by mandating machine-readable traceability for network infrastructure documentation.
- Network Performance Testing:Pre-deployment validation of backhaul links, metro rings, and access networks before customer traffic activation. United States telecommunications carriers concentrate procurement here for licensed microwave infrastructure.
- System Validation:End-to-end verification of transceiver, cable, and network element interoperability in laboratory environments.
- Signal Integrity Testing:High-speed electrical characterization for PCB, connector, and cable assembly verification.
Network performance testing holds the largest volume position, with compliance testing showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecommunications equipment clusters in Shenzhen, Dongguan, and Shanghai anchor procurement volume for coherent optical test equipment calibrated to 800G standards. National broadband initiatives across multiple geographies sustain instrument replacement cycles as DSP integration reshapes buyer specifications.
United States
Verizon and AT&T drive rack-mount tester deployments for continuous line monitoring in hyperscale data centers exceeding 500 units per campus. The FCC mandates bit-error performance benchmarks for licensed microwave backhaul, compelling infrastructure operators into compliance-driven refresh cycles. Greater Boston and Austin metropolitan areas concentrate R&D facilities where PXI modular platforms undergo firmware validation.
China
China Mobile and China Telecom accelerate fiber-to-the-home buildouts requiring BER certification before field activation. MIIT enforces GB standards for domestic optical transceiver certification, creating regulatory pull for instruments resolving to 10^-12 bit-error ratios. The Yangtze River Delta manufacturing corridor hosts validation laboratories serving telecommunications OEMs upgrading to 1.6T coherent prototypes.
Germany
Deutsche Telekom specifies equipment with DSP integration for optical transceiver certification in 5G backhaul networks. The EU AI Act and CSRD mandate auditable network infrastructure documentation that BER test logs satisfy, expanding demand for traceable test data. Bavaria and Baden-Württemberg host compliance laboratories where desktop testers undergo calibration to emerging protocol umbrellas.
Japan
NTT and KDDI procure coherent optical instruments for metro ring validation before customer traffic activation. METI coordinates national broadband initiatives that sustain instrument replacement cycles among infrastructure operators. The Kanto region around Tokyo concentrates semiconductor test equipment development where 100+ Gbaud signal integrity engineering faces acute talent scarcity.
South Korea
SK Telecom and KT Corporation integrate continuous line monitoring into production environments for cloud service expansion. The central bank's infrastructure investment guidelines indirectly shape procurement criteria for rack-mount configurations. The Seoul Capital Area hosts validation facilities where automated testers with machine-learning-driven analytics undergo integration trials.
Bit Error Rate Tester Market Vendor Landscape
Global majors compete with regional champions across instrument calibration standards and modular platform architectures. The supplier base concentrates around vendors with full portfolio coverage spanning desktop, rack-mount, and automated configurations. Three archetypes dominate: PXI modular platform specialists, coherent optical instrument developers, and RF signal integrity extension providers. Competitive moves center on firmware-upgradeable flexibility and strategic partnerships for DSP integration roadmaps.
Among instrument developers with telecommunications focus, Keysight Technologies and Anritsu Corporation exemplify the coherent optical tier, while Rohde & Schwarz occupies a position within RF signal integrity extensions. Keysight Technologies represents the PXI modular platform archetype through its benchtop and rack-mount configurations. Anritsu Corporation anchors the high-speed optical segment with instruments addressing 800G and emerging 1.6T standards. Rohde & Schwarz sits within the defense and satellite validation niche where non-terrestrial communications demand specialized test protocols.
| Leading Market Players |
|---|
| Keysight Technologies |
| Anritsu Corporation |
| Tektronix |
| VIAVI Solutions |
| Rohde & Schwarz |
| Spirent Communications |
| EXFO |
| Ixia |
| NTS |
| Others |
Supply Flow & Price Mechanics
Hyperscale data center procurement consolidation around rack-mount configurations with continuous monitoring capabilities is compressing supplier margins and forcing component sourcing into longer-term contractual arrangements. FCC microwave licensing mandates and China's MIIT GB standards enforcement create specification rigidity that limits price elasticity for calibrated instruments resolving to 10^-12 bit-error ratios.
Pricing Analysis
Specialized semiconductor foundry costs for pattern generation and error detection circuitry operating above 100 Gbaud pass through directly to instrument pricing, with three-tier pricing structure across premium, standard, and economy levels stratifying by calibration grade and after-sales service bundling. Price differentiation centers on DSP integration depth and firmware-upgradeable flexibility across 800G and 1.6T standard generations. Cost compression in standard-tier desktop testers is intensifying because telecommunications OEMs are consolidating procurement around fewer qualified suppliers with full portfolio coverage. Research institutions exhibit the highest price sensitivity due to budget constraints, while hyperscale cloud providers prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Qualification gating by telecommunications OEMs and compliance laboratories restricts component supply to vendors certified for 100+ Gbaud signal integrity engineering, with concentration in the United States, Japan, and Germany for high-speed electrical testing subsystems. Raw material dependencies include indium phosphide semiconductors, precision ceramic substrates, and specialized optical modulators. Single-source vulnerability in coherent optical DSP chip supply creates bottleneck exposure when foundry allocation constraints tighten. Distribution runs through direct sales organizations serving national carriers and mobile network operators, with secondary channels for research institutions and smaller OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Bit Error Rate Tester Market functions as a stable compounder where telecommunications infrastructure refresh cycles and regulatory compliance mandates generate predictable replacement demand regardless of macroeconomic volatility.
For Market Incumbents: Cement dominance in coherent optical instrumentation by locking exclusive DSP integration partnerships with 1.6T standard development consortia, while acquiring specialized talent pools in 100+ Gbaud signal integrity engineering to defend against fabless entrants with software-defined architectures. Capacity addition in the Yangtze River Delta manufacturing corridor secures proximity to China Mobile and China Telecom procurement decision centers. For New Entrants and Emerging Players: Begin with satellite and defense link validation applications where RF signal integrity extensions face limited incumbent saturation and procurement cycles favor specialized protocols over full portfolio coverage. The most penetrable white-space sits in non-terrestrial communications test equipment for LEO constellation ground segment validation, approached through partnerships with national space agencies and defense contractors seeking alternatives to legacy supplier relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap instrument developers possessing coherent optical calibration capabilities but lacking hyperscale data center channel access, as cloud provider procurement consolidation creates acquisition currency for strategic buyers. The five-to-ten-year viability window favors platforms with firmware-upgradeable architectures that compress capital equipment refresh cycles. The signal to monitor is MIIT enforcement intensity for 1.6T GB standards, which would trigger instrument replacement waves across Chinese telecommunications OEMs.| Strategic Initiative | Industry Significance |
|---|---|
| DSP Integration Partnership | Secures roadmap alignment with 800G and 1.6T coherent standards development in China and Germany. |
| Machine-Learning Analytics Embedding | Commands premium positioning in EU compliance laboratories facing CSRD documentation mandates. |
| Hyperscale Channel Expansion | Captures rack-mount tester volume from AWS, Azure, and Alibaba Cloud facility-scale deployments. |
| Defense/Satellite Protocol Development | Opens underpenetrated non-terrestrial communications validation beyond traditional telecommunications. |
| In-House Calibration Service Internalization | Aligns with cloud provider behavioral shift to reduce downtime exposure and unbundle vendor contracts. |
Methodological Framework
Direct dialogue with telecommunications equipment procurement directors, compliance laboratory managers, optical transceiver manufacturing engineers, and DSP platform architects grounded the qualitative foundation, cross-referenced with FCC licensing databases, MIIT GB standards filings, hyperscaler capital expenditure disclosures, and semiconductor foundry capacity reports. Bottom-up instrumentation shipment estimates triangulated against top-down telecommunications infrastructure investment forecasts.
Segment-level projections across product type, end user, technology, and application dimensions over the projection horizon employed installed base depreciation modeling and replacement cycle analysis. CAGRs derived from regression against historical instrument refresh patterns correlated with coherent optical standard adoption curves and national broadband initiative spending trajectories.
Several conditions sit outside the modeled scope, including unanticipated 1.6T protocol fragmentation, foundry allocation shocks affecting 100+ Gbaud component supply, and geopolitical restrictions on test equipment export classifications. A model refresh is warranted upon material change in FCC or MIIT enforcement intensity for bit-error performance benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Hour Meter Market
Test and Measurement
Global Source Measure Unit Market
Test and Measurement
Battery Testing and Inspection Equipment Market
Test and Measurement
Global Digital Measurement Instruments Market
Test and Measurement
Wafer-Level Test and Burn-In [WLTBI] Market
Test and Measurement
North America Electrical Testing Services Market
Test and Measurement
Leak Testing Machine Market
Test and Measurement
Whiteness Meter Market
Test and Measurement
Thin Film Metrology Systems Market
Test and Measurement
Ultrasonic Thickness Gauge Market
Test and Measurement
Electrical Testing Services Market
Test and Measurement
Battery Test Equipment Market
Test and Measurement
Fingertip Pulse Oximeter Electronic Testers Market
Test and Measurement
Crock Meter Market
Test and Measurement
Ceramic Tester Market
Test and Measurement
Air Measuring Equipment Market