
 Asia Pacific Pet Milk Replacers Market | 2026-2036
Asia Pacific Pet Milk Replacers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Pet Milk Replacers Market Insights
The EU Green Deal is restructuring ingredient sourcing priorities across Asia Pacific pet nutrition supply chains. Mars Inc. leverages its manufacturing scale to sustain bulk powder production across multiple countries. DoggyMan H.A.Co.,Ltd anchors its position through specialized distribution networks in Japan. LILLELUND PTY LTD differentiates via veterinary-grade formulations targeting orphan marsupial and companion animal rehabilitation centers.
Asia Pacific pet milk replacers are nutritionally complete substitute formulas containing casein, whey protein, vegetable oils, and supplemented vitamins designed to match the fat and protein profiles of maternal milk for neonatal mammals. Spray-drying and wet-mix processing determine solubility and shelf stability for powdered variants. Powdered formats dominate volume due to extended storage life and lower freight costs across archipelagic markets. Pouches within packaging types represent the fastest-growing segment as single-serve convenience aligns with urban pet owner purchasing patterns. Kittens among end users command premium pricing relative to other neonatal categories.
Australia's national feed safety regulator enforces residue limits on dairy-derived ingredients, while China's SAMR monitors cross-border e-commerce claims for imported replacer products. Japan's Ministry of Agriculture, Forestry and Fisheries inspects quarantine compliance for animal-origin formulations entering through Tokyo and Osaka ports. Stakeholders must track evolving allergen labeling mandates and veterinary prescription requirements that could reshape channel access between pet stores and online platforms.
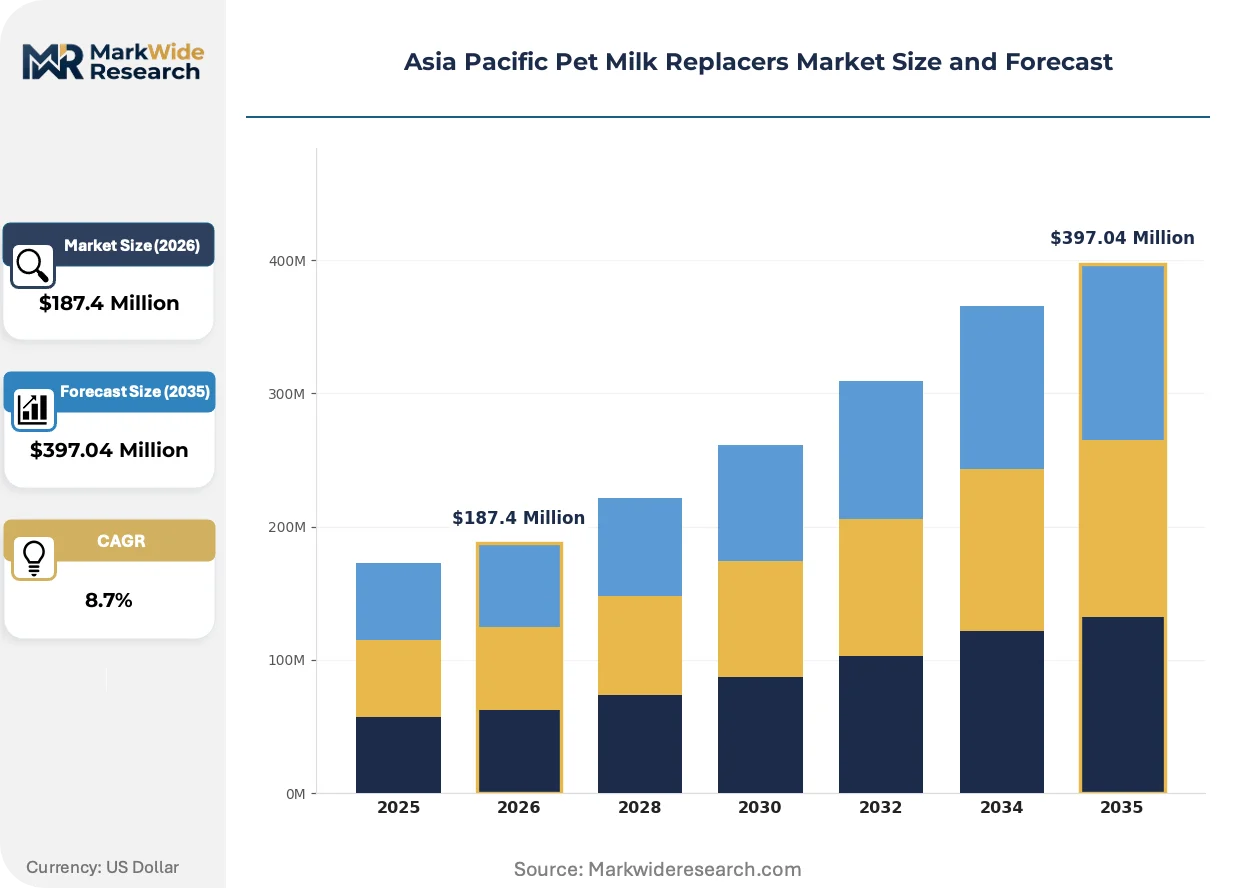
Market Dynamics
The Asia Pacific pet milk replacers market is tightening around veterinary prescription pathways and specialty retail consolidation, with China's GB standards and Australia's TGA residue mandates forcing reformulation investments that favor scaled manufacturers over commodity blenders.
Growth Catalysts
- China's GB standards tightening:Feed safety mandates for dairy-derived ingredients are accelerating product registration renewals and quality certifications among domestic and imported brands.
- Orphan marsupial rehabilitation:Australia's wildlife rescue centers generate specialized demand for species-specific protein and fat profiles unavailable in standard companion animal formulas.
- Spray-drying automation:Wet-mix processing upgrades are reducing moisture variability and extending shelf stability for archipelagic distribution to Indonesia and the Philippines.
Market Restraints
- Whey protein concentrate volatility:Dairy commodity price swings from New Zealand and Australian suppliers compress margin predictability for mid-tier brands.
- Single-source spray-drying capacity:Concentration of contract manufacturing in Victoria and New South Wales creates geographic supply risk during seasonal demand spikes.
- Japan's quarantine inspection backlog:MAFF port delays at Tokyo and Osaka extend lead times for animal-origin formulations, forcing working capital increases.
Strategic Opportunities
- Vietnam's emerging veterinary channel:Underpenetrated pet specialty retail and growing small animal clinics create first-mover positioning for orphan puppy and kitten nutrition.
- Pouch packaging conversion:Single-serve convenience formats are capturing urban pet owner purchasing patterns in Seoul, Shanghai, and Sydney apartment markets.
- EU Green Deal ingredient sourcing:Sustainable vegetable oil and plant protein alternatives are qualifying products for premium positioning in Australia's environmentally conscious companion animal segment.
Industry Challenges
- Veterinary nutritionist scarcity:Formulation expertise for neonatal mammal physiology is concentrated among retiring specialists in Australian universities and Japanese research institutes.
- Cross-border e-commerce compliance:China's SAMR claim verification and Australia's TGA parallel import monitoring require dedicated regulatory affairs staffing for platform sellers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Pet Milk Replacers Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered, Liquid, Ready-to-Use, Concentrate End User: Puppies, Kittens, Foals, Calves Packaging Type: Bottles, Tetra Packs, Cans, Pouches Distribution Channel: Online, Specialty Stores, Pet Stores, Supermarkets |
| Companies Covered | LILLELUND PTY LTD (Di-Vetelact), Wombaroo Food Products, Biolac, DoggyMan H.A.Co.,Ltd, Morinaga, Apetite Foods Group Pty Ltd, PEDIGREE, Woolworths Ltd, Mars Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Pet Milk Replacers Market Trends and Innovations
Processing automation and packaging format diversification are compressing production batch sizes while extending distribution reach across the Asia Pacific's fragmented retail landscape.
Automated wet-mix processing with inline fat homogenization is automating consistency control for powdered milk replacer production. Australian contract manufacturers are adopting these systems to reduce batch-to-batch protein variation. The technology is automating quality assurance labor and enabling smaller production runs for specialized wildlife rehabilitation formulas.
Australia's TGA residue limit enforcement for dairy-derived ingredients is tightening supplier qualification requirements. Domestic formulators must document veterinary drug absence through certified laboratory testing. Premium companion animal brands in Sydney and Melbourne are responding by securing captive supply agreements with verified New Zealand dairy cooperatives.
Urban pet owners in Japan and South Korea are compressing purchase cycles toward single-serve pouch formats through convenience store and online subscription channels. Specialty retailers in Tokyo's Shibuya and Seoul's Gangnam districts are reallocating shelf space from bulk powder canisters to trial-size assortments. This pattern is most visible among first-time kitten adopters seeking portion-controlled feeding without storage complexity.
Asia Pacific Pet Milk Replacers Market Segmentation
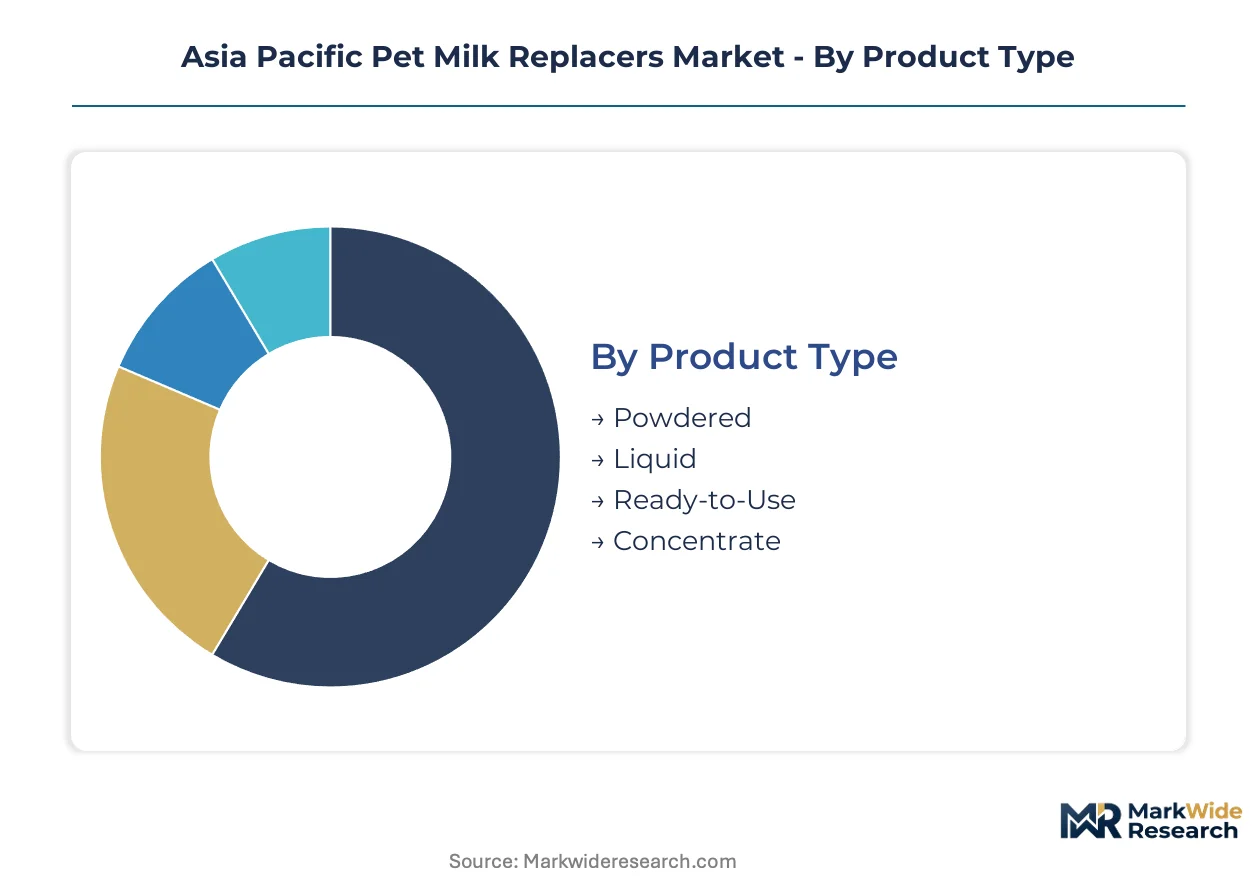
Pet milk replacer formulations vary sharply in shelf stability, preparation complexity, and species-specific protein profiles. Manufacturers balance standardized bulk production against specialized wildlife rehabilitation and premium companion animal niches across Australia's veterinary channels and China's e-commerce platforms.
Product Type:
Customization-vs-standardization tension runs deepest here: veterinary clinics demand batch-flexible concentrates while mass retail favors shelf-stable, scoop-and-mix powders.
- Powdered:Spray-dried casein-whey matrices with 12-18 month ambient stability dominate archipelagic logistics to Indonesia and the Philippines. Australian contract manufacturers in Victoria and New South Wales concentrate spray-drying capacity for this format, though single-source geographic concentration creates supply risk during seasonal demand spikes.
- Liquid:UHT-sterilized emulsions require cold chain integrity but eliminate reconstitution error for orphan marsupial rehabilitation centers. Demand concentrates in Australia's wildlife rescue networks where species-specific fat profiles exceed standard companion animal formulation capabilities.
- Ready-to-Use:Pre-mixed sterile emulsions for emergency veterinary settings carry premium positioning in Tokyo and Seoul specialty clinics.
- Concentrate:Dilution-flexible bases allow veterinary nutritionists to adjust osmolality for compromised neonates in Australian university teaching hospitals.
Leading the category by volume: Powdered. Growing fastest: Ready-to-Use.
End User:
Species physiology dictates protein-to-fat ratios and immunoglobulin supplementation levels, with companion animals commanding price premiums over livestock categories.
- Kittens:Taurine-enriched formulations with 8-10% fat emulsion match feline obligate carnivore metabolism. Urban pet owners in Seoul's Gangnam and Tokyo's Shibuya districts drive single-serve pouch demand for first-time adopters seeking portion-controlled feeding without storage complexity.
- Puppies:Whey-dominant proteins with lactose reduction for canine digestive tolerance. China's GB standards tightening on dairy-derived ingredients accelerates product registration renewals for imported puppy formulas through cross-border e-commerce channels.
- Foals:Equine-specific colostrum replacers with IgG standardization for thoroughbred breeding operations in Australia's Hunter Valley.
- Calves:Commodity-grade milk extenders for dairy herd supplementation in New Zealand-influenced supply chains.
Kittens command the steepest price premium per kilogram. Puppies deliver the largest absolute volume.
Packaging Type:
Format selection tracks retail channel fragmentation and urban storage constraints across the region's dense metropolitan corridors.
- Pouches:Single-serve aluminum-laminate sachets with tear-spout design. Convenience stores in Shanghai and Sydney apartment markets are reallocating shelf space from bulk canisters to trial-size assortments for subscription-channel subscribers.
- Bottles:HDPE containers with resealable caps for multi-feed households. Australian pet specialty retailers expand shelf space for orphan puppy and kitten nutrition products in Melbourne and Sydney premium segments.
- Tetra Packs:Aseptic brick formats for UHT liquid stability in Japanese veterinary hospital procurement.
- Cans:Metal containers for concentrate storage in bulk wildlife rehabilitation center pantries.
Pouches are climbing fastest in urban convenience channels. Bottles retain the largest installed base.
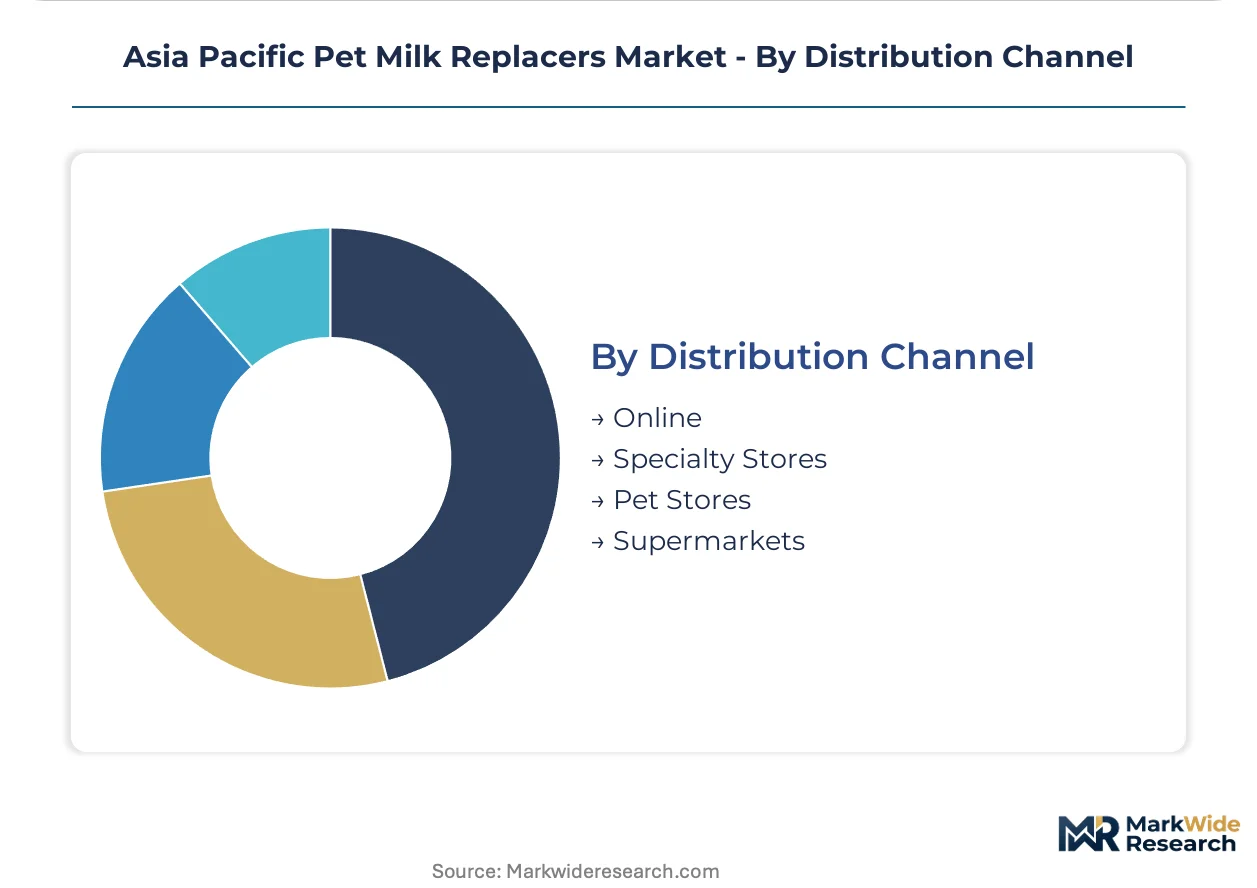
Distribution Channel:
Channel access is restructuring around regulatory compliance burdens and veterinary prescription pathway expansion.
- Specialty Stores:Staff-trained consultative selling with species-specific formulation guidance. Japan's Ministry of Agriculture, Forestry and Fisheries quarantine inspection backlogs at Tokyo and Osaka ports extend lead times, forcing working capital increases for specialty retailers stocking animal-origin formulations.
- Online:Cross-border e-commerce platforms face China's SAMR claim verification and Australia's TGA parallel import monitoring, requiring dedicated regulatory affairs staffing.
- Pet Stores:Mass-market powder canister placement in Australian and Japanese retail chains.
- Supermarkets:Limited SKU availability for emergency purchase in Seoul and Shanghai hypermarkets.
Specialty stores anchor premium positioning. Online channels are expanding most quickly in Vietnam's underpenetrated veterinary markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Melbourne and Sydney anchor Asia Pacific's pet milk replacer manufacturing, with spray-drying facilities in Victoria and New South Wales supplying archipelagic markets across Indonesia and the Philippines. Australia's wildlife rehabilitation networks and China's cross-border e-commerce platforms generate divergent demand patterns across the region.
Australia
Wildlife rescue centers in Queensland and New South Wales drive specialized demand for orphan marsupial formulas with species-specific protein profiles. The TGA enforces residue limits on dairy-derived ingredients, forcing domestic formulators to secure certified laboratory documentation. Spray-drying capacity concentrates in Victoria, creating geographic supply vulnerability during seasonal demand spikes.
China
Urban pet owners in Shanghai and Beijing purchase kitten and puppy replacers through cross-border e-commerce channels. The SAMR monitors import claims with tightening scrutiny under evolving GB feed safety standards. Domestic brands accelerate product registration renewals to maintain platform access against intensifying compliance requirements.
Japan
Specialty retailers in Tokyo's Shibuya and Osaka districts reallocate shelf space toward single-serve pouch formats for first-time kitten adopters. The Ministry of Agriculture, Forestry and Fisheries inspects quarantine compliance at Tokyo and Osaka ports, extending lead times for animal-origin formulations. Convenience store chains capture compressed purchase cycles through subscription-channel subscribers.
South Korea
Apartment-dwelling pet owners in Seoul's Gangnam district favor portion-controlled feeding solutions without storage complexity. The MFDS oversees feed safety compliance for imported dairy-derived products. Veterinary clinics in the Seoul Capital Area expand orphan puppy and kitten nutrition counseling services.
Vietnam
Small animal clinics in Ho Chi Minh City and Hanoi create first-mover positioning opportunities for veterinary-grade formulations. The country's national feed safety regulator develops import inspection protocols for animal-origin products. Pet specialty retail remains underpenetrated relative to online channel expansion.
Asia Pacific Pet Milk Replacers Market Competitive Landscape
The competitive structure tilts toward scaled manufacturers with captive dairy supply agreements and specialized distribution networks. Mid-tier commodity blenders face margin compression from whey protein concentrate volatility and reformulation investments driven by tightening GB standards and TGA residue mandates. Two strategic archetypes dominate: multinational nutrition conglomerates leveraging manufacturing scale across multiple countries, and regional specialists anchoring positions through veterinary-grade formulations and wildlife rehabilitation expertise. Competitive moves concentrate on spray-drying automation investments and pouch packaging conversion to capture urban convenience channels.
Within the regional specialist tier, LILLELUND PTY LTD exemplifies veterinary-grade positioning through Di-Vetelact-branded formulations targeting orphan marsupial rehabilitation centers. Mars Inc. represents the multinational archetype with bulk powder production sustained across dispersed manufacturing footprints. DoggyMan H.A.Co.,Ltd occupies a specialized distribution position within Japanese pet specialty retail networks. These three anchors illustrate the market's bifurcation between scale-driven commodity supply and niche expertise in species-specific neonatal nutrition.
| Leading Market Players |
|---|
| LILLELUND PTY LTD (Di-Vetelact) |
| Wombaroo Food Products |
| Biolac |
| DoggyMan H.A.Co.,Ltd |
| Morinaga |
| Apetite Foods Group Pty Ltd |
| PEDIGREE |
| Woolworths Ltd |
| Mars Inc. |
| Others |
Pricing and Supply Chain Analysis
Family-owned Australian contract manufacturers with multi-generational dairy cooperative ties anchor spray-drying capacity in Victoria and New South Wales, translating captive whey protein supply into pricing discipline that resists commodity volatility. Their ownership structure insulates long-term supplier relationships from quarterly margin pressure, reinforcing stability across archipelagic distribution networks.
Pricing Analysis
Value-based pricing anchored to neonatal survival outcomes and veterinary prescription compliance separates premium formulations from commodity powders. Three-tier pricing structure across veterinary-grade, specialty retail, and mass-market economy levels reflects certification burden and species-specific formulation complexity. Cost compression in mid-tier segments intensifies as China's GB standards force reformulation investments without corresponding price elasticity. Veterinary clinics demonstrate lowest price sensitivity due to outcome accountability, while mass-market puppy powder buyers in Southeast Asian e-commerce channels exhibit highest elasticity.
Supply Chain Analysis
Workforce availability constraints in Victorian spray-drying facilities and New South Wales wet-mix processing plants limit expansion velocity despite demand acceleration. Supply concentrates in Australia, with secondary blending capacity in New Zealand and emerging toll manufacturing in Vietnam. Raw material flows draw from New Zealand dairy cooperatives for whey protein concentrate, Australian vegetable oil processors for fat emulsions, and Malaysian packaging converters for pouch laminates. Single-source geographic concentration in Victoria creates supply vulnerability during seasonal wildlife rehabilitation demand spikes. Distribution runs through Australian contract manufacturers to Indonesian and Philippine pet specialty importers, with direct-to-clinic channels gaining share in Japan and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
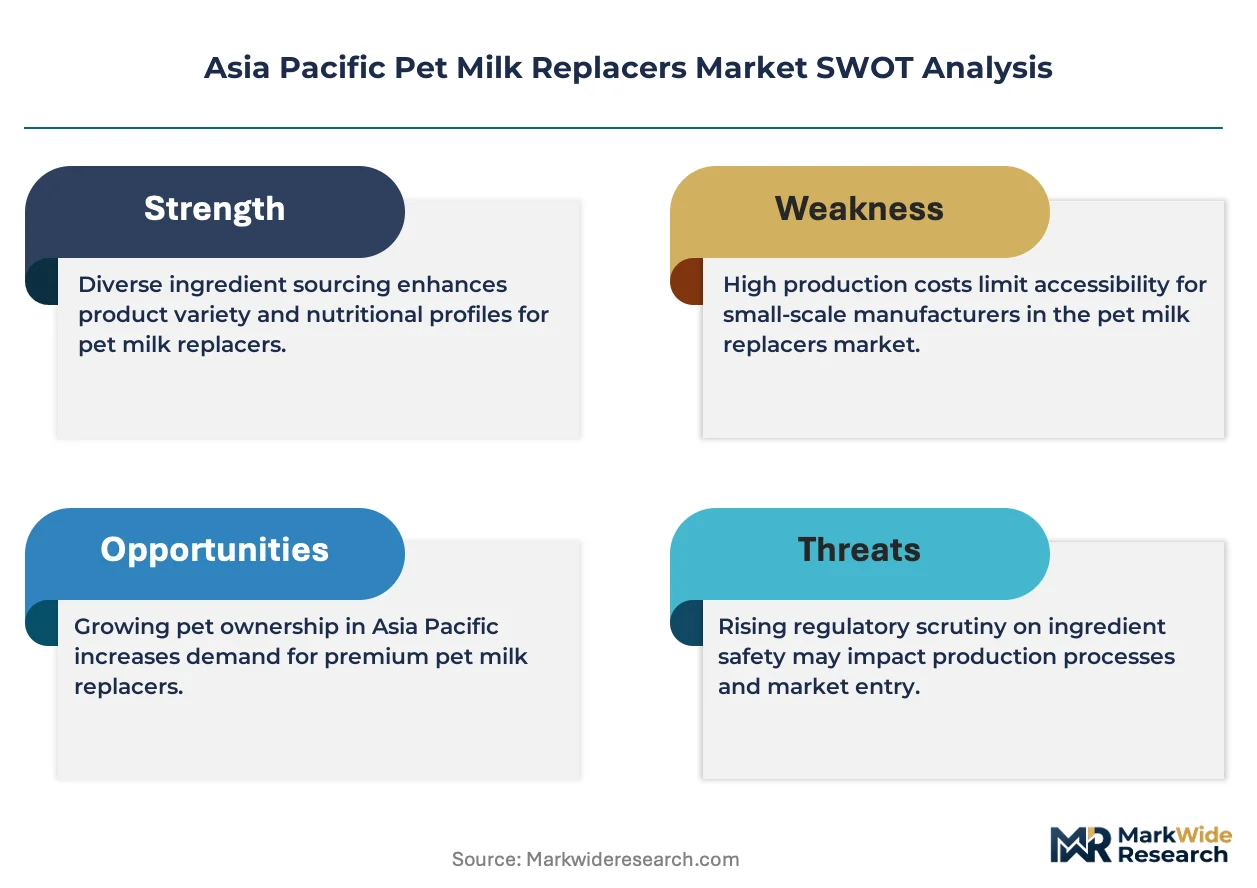
This market reads as a cost-of-compliance story where China's SAMR claim verification and Australia's TGA residue mandates erect barrier-to-entry moats favoring scaled players with dedicated regulatory affairs infrastructure.
For Market Incumbents: Cement market position by securing captive supply agreements with verified New Zealand dairy cooperatives ahead of TGA documentation requirements tightening. Expand spray-drying automation in Victoria to reduce batch-to-batch protein variation and enable smaller production runs for wildlife rehabilitation niches. Channel control through veterinary prescription pathway deepening offsets margin pressure from whey protein concentrate volatility.
For New Entrants and Emerging Players: Enter via Vietnam's underpenetrated small animal clinic network where pet specialty retail fragmentation creates first-mover positioning for orphan puppy and kitten nutrition. Target Ho Chi Minh City and Hanoi veterinary channels with regulatory-light import pathways before national feed safety protocols mature. Go-to-market leverage rests on mobile veterinary sampling units building clinician familiarity ahead of distributor consolidation.
For Investors and Strategic Acquirers: Distressed-cycle entries favor Australian wildlife rehabilitation specialists with veterinary-grade formulation libraries and MAFF-compliant export documentation to Japan. Long-term viability hinges on 5-10 year regulatory compliance capability amortization against commodity dairy input cycles. Signal to watch: MAFF inspection backlog reduction at Tokyo and Osaka ports indicating normalized working capital requirements for animal-origin formulation importers.
| Strategic Initiative | Industry Significance |
|---|---|
| Spray-Drying Automation Investment | Victorian manufacturers reduce protein variability to meet TGA batch consistency requirements. |
| Pouch Packaging Conversion | Single-serve formats capture Seoul and Shanghai apartment-dwelling pet owner convenience preferences. |
| Wildlife Rehabilitation Formula Expansion | Orphan marsupial specialization commands premium positioning in Queensland rescue center networks. |
| Vietnam Veterinary Channel Development | First-mover clinic relationships in Ho Chi Minh City preempt distributor consolidation. |
| EU Green Deal Ingredient Sourcing | Sustainable vegetable oil alternatives qualify products for Australia's environmentally conscious premium segment. |
Research Methodology
Independent corroboration across spray-drying facility operators, veterinary nutritionists at Australian universities, and pet specialty retail buyers in Tokyo underwrites the qualitative findings. Primary interviews engaged formulation scientists at contract manufacturers, regulatory affairs leads navigating SAMR and TGA pathways, wildlife rehabilitation center procurement managers, and cross-border e-commerce platform category directors. Secondary validation drew from Australian customs dairy derivative trade data, MAFF quarantine inspection disclosure reports, China's GB standards evolution notices, and SEC filings of disclosed pet nutrition conglomerates. Bottom-up volume modeling across product type, end user species, and packaging format triangulates against top-down category spend estimates from retail audit channels.
Rate-of-change decomposition across the analysis window isolates volume drivers from price mix effects in powdered versus liquid format transitions. Segmentation dimensions modeled include product type stability profile, end user species physiology requirements, packaging convenience tier, and distribution channel regulatory burden. CAGRs derive from logistic adoption curve fitting for automated processing penetration and urban single-serve format conversion. Industry-specific forecast inputs incorporate MAFF inspection throughput assumptions and GB standards implementation phasing for dairy-derived ingredient documentation.
Revisions become necessary when MAFF port processing capacity constraints persist beyond seasonal normalization, when China's SAMR escalates claim verification to batch-level laboratory testing, or when Australian wildlife rehabilitation funding cycles shift demand seasonality. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Global Bee Products Market
Specialty Foods
Global Truffle Market
Specialty Foods
Europe Gluten-Free Breakfast Cereals Market
Specialty Foods
Asia Pacific Cat Food Market
Specialty Foods
Cat Food Flavors Market
Specialty Foods
Aloe Vera Gel Market
Specialty Foods
Grain Free Dog Food Market
Specialty Foods
Vegan Dressing Market
Specialty Foods
Low Calorie Desserts Market
Specialty Foods
CBD Snacks Market
Specialty Foods
Global Hispanic Foods Market
Specialty Foods
Almond-Based Spreads Market
Specialty Foods
Low Calorie Popsicles Market
Specialty Foods
Natto Market
Specialty Foods
Middle East and Africa Yerba Mate Market
Specialty Foods
Global Sauerkrauts Market