
 Global Bee Products Market | 2026-2036
Global Bee Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bee Products Market Foresight
Apiarist workforce availability is bifurcating the competitive landscape between artisan-scale suppliers and industrial honey packers. Comvita Limited leverages its vertical integration from hive to shelf across New Zealand and Australian operations. Barkman Honey LLC sustains its position through geographic dominance in the North American clover honey belt. Dabur Ltd. differentiates via its Ayurvedic heritage and pharmacy-channel penetration across South Asian markets.
Bee products encompass honey, beeswax, royal jelly, propolis, and pollen—substances derived from Apis mellifera colonies through foraging, enzymatic transformation, and hive construction processes, valued for their antimicrobial, emollient, and nutritional bioactive compounds. Honey leads product type revenue due to its ubiquity in food and beverage formulations, while propolis extracts command premium positioning in skin care applications where antioxidant density drives formulation value. Royal jelly concentrates within the dietary supplements segment where lyophilization technology preserves 10-HDA potency for capsule and ampoule formats.
FDA dietary supplement regulations under DSHEA govern label claims for bee-derived nutraceuticals in the United States, while EFSA novel food assessments shape market access for royal jelly and propolis extracts across European Union member states. China's SAMR and GB standards enforce residue limits and authenticity testing that determine import eligibility for foreign honey suppliers. Stakeholders must monitor evolving pollinator protection policies and authenticity verification technologies as regulatory stringency and consumer transparency expectations converge.
Market Dynamics
The EU Green Deal's biodiversity mandates are tightening pesticide restrictions that directly affect colony health and product yields, forcing apiarists and packers to reconfigure supply relationships around residue compliance and pollinator protection protocols.
Growth Catalysts
- Novel food approvals:EFSA novel food assessments for royal jelly and propolis extracts are unlocking premium formulation channels across European Union member states, expanding addressable market for lyophilized concentrates.
- Cosmetic ingredient demand:South Korean cosmetics manufacturers are scaling propolis and royal jelly extract formulations, driving specification-grade procurement from integrated apiculture clusters.
- Shandong Province concentration:Integrated apiculture clusters in China's Shandong Province supply both domestic nutraceutical processors and export channels, creating hub-and-spoke efficiency in raw material sourcing.
Market Restraints
- Input cost volatility:Nucleus colony and queen bee pricing fluctuates with seasonal availability and climate stress, compressing margins for artisan-scale apiarists dependent on external breeding stock.
- Supply concentration risk:China's SAMR residue limits and GB authenticity standards create single-point regulatory dependency for foreign honey suppliers seeking import eligibility.
- Technical limitation:10-HDA potency degradation in non-lyophilized royal jelly limits shelf-stable distribution, constraining capsule and ampoule format economics.
Strategic Opportunities
- Underpenetrated geography:India's FSSAI regulatory pathway for Ayurvedic-positioned bee products remains underdeveloped relative to pharmacy-channel penetration potential across South Asian markets.
- Technology convergence:Blockchain traceability combined with isotope ratio mass spectrometry is enabling origin-verified honey positioning, differentiating premium tiers from blended commodity supply.
- Distribution innovation:Direct-to-apothecary channels in Germany and Switzerland bypass conventional grocery consolidation, capturing margin from pharmacy-grade propolis and pollen formulations.
Industry Challenges
- Apiarist workforce scarcity:Generational transition gaps in hive management expertise are bifurcating competitive positioning between artisan-scale suppliers and industrial honey packers with mechanized extraction.
- Certification timeline compression:DSHEA dietary supplement label claim substantiation for 10-HDA and flavonoid content requires extended FDA correspondence, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bee Products Market |
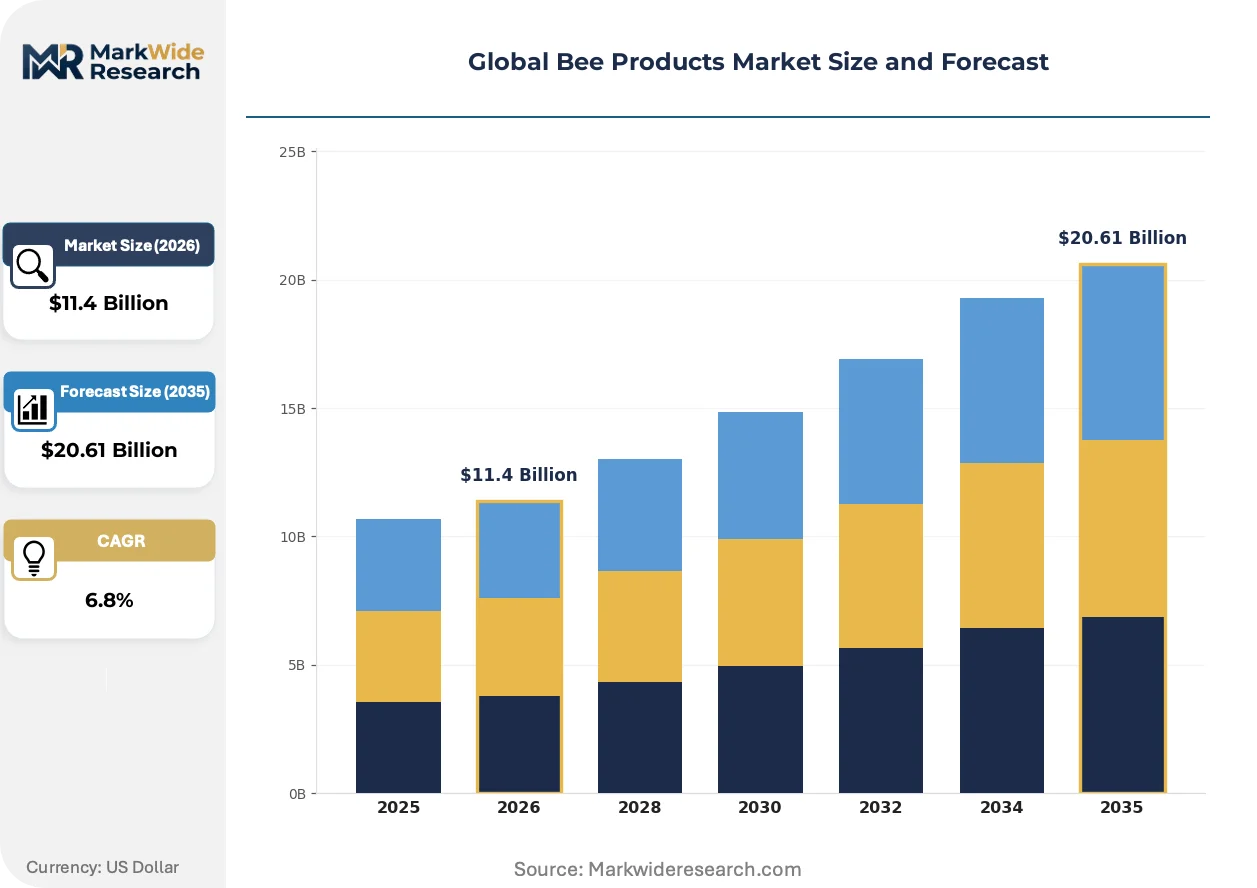
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Honey, Beeswax, Royal Jelly, Propolis, Pollen End Use Industry: Cosmetics, Food & Beverages, Pharmaceuticals, Nutraceuticals, Agriculture Distribution Channel: Supermarkets/Hypermarkets, Online Retailers, Specialty Stores, Pharmacies, Direct Sales Application: Skin Care, Dietary Supplements, Oral Care, Wound Healing, Veterinary Products |
| Companies Covered | Dadant & Sons Inc., Mann Lake Ltd., GloryBee, Capilano Honey Limited, Barkman Honey LLC, Comvita Limited, Y.S. Organic Bee Farms, Dabur Ltd., Betterbee Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bee Products Market Shifts & Advancements
Active ingredient preservation technologies and authentication protocols are reshaping competitive positioning across honey, royal jelly, and propolis supply tiers, compressing the viable window for undifferentiated commodity sourcing.
Lyophilization equipment for royal jelly processing is miniaturizing from industrial freeze-dryers to modular units deployable at cooperative scale. Mid-sized apiary associations in New Zealand and Australia are adopting these systems to preserve 10-HDA potency for capsule export. This distributed processing architecture is compressing the historical advantage of centralized pharmaceutical-grade facilities.
REACH chemical registration requirements for propolis resin extracts are tightening impurity disclosure thresholds across European Union member states. ECHA compliance costs are filtering smaller traders from bulk supply chains. Nutraceutical formulators are responding by consolidating procurement around vertically integrated hive-to-extract operators with captive analytical capabilities.
Buyer concentration among South Korean cosmetics conglomerates is rotating specification power toward finished goods manufacturers. Raw material suppliers must now certify polyphenol content and geographic origin prior to contract execution. This procurement pattern is most visible in Seoul-based R&D centers sourcing Manuka-grade propolis for anti-aging serum formulations.
Global Bee Products Market Segmentation
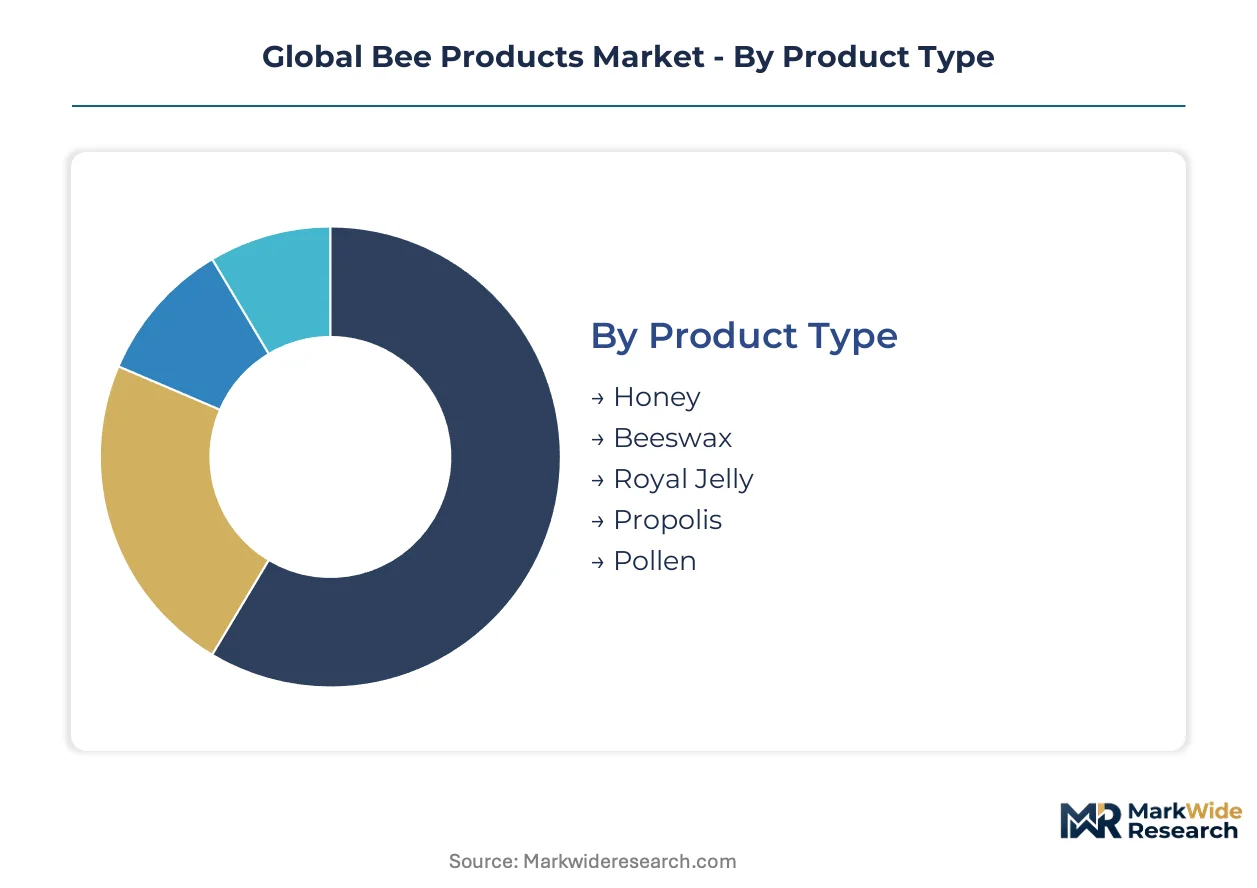
Segmentation in bee products markets separates commodity-grade bulk supply from specification-driven premium channels. Margin pools concentrate where bioactive potency certification commands formulation premiums in cosmetics and nutraceuticals.
Product Type:
Margin concentration tracks directly with processing complexity and bioactive standardization requirements across hive-derived outputs.
- Honey:Enzymatically transformed floral nectar with invertase-catalyzed sucrose hydrolysis. Demand concentrates in China's Shandong Province integrated clusters serving both domestic food processors and export channels under SAMR residue compliance protocols.
- Propolis:Resinous hive sealant with flavonoid and phenolic acid bioactivity. South Korean cosmetics manufacturers in Seoul R&D centers are scaling anti-aging serum formulations, rotating procurement power toward polyphenol-certified supply.
- Royal Jelly:Hypopharyngeal gland secretion with 10-HDA fatty acid marker. Lyophilization-dependent shelf stability limits distribution economics for non-pharmaceutical-grade suppliers.
- Beeswax:Secreted wax scales from worker bee abdominal glands. Candle and cosmetic emulsifier applications dominate volume offtake from North American clover belt apiaries.
- Pollen:Entomophilous flower microgametophytes packed in corbiculae. Sports nutrition and apitherapy segments in Germany and Switzerland drive pharmacy-channel procurement.
The dominant share belongs to Honey, while Propolis is closing the gap fastest.
End Use Industry:
Application-driven purity requirements fragment procurement specifications across food-grade, cosmetic-grade, and pharmaceutical-grade tiers.
- Food & Beverages:Largest volume sink for multifloral and monofloral honey varieties. EU Green Deal pesticide restrictions are tightening residue thresholds for colony-derived inputs into European formulations.
- Cosmetics:Premium positioning driver for propolis and royal jelly extracts. South Korean formulators specify geographic origin and polyphenol content prior to contract execution with raw material suppliers.
- Nutraceuticals:Lyophilized royal jelly capsules and propolis softgels dominate. EFSA novel food assessments govern market access for 10-HDA and flavonoid-positioned products across EU member states.
- Pharmaceuticals:Wound healing honey and API-grade extracts. FDA DSHEA label claim substantiation creates extended correspondence timelines for US market entry.
- Agriculture:Pollination services and hive product derivatives. Colony rental economics for orchard and seed crop pollination operate on separate pricing from product extraction revenue.
Food & Beverages holds the volume lead, though Cosmetics exhibits the steepest expansion trajectory.
Distribution Channel:
Channel selection determines margin capture versus authenticity verification burden, with direct and pharmacy routes preserving premium positioning.
- Pharmacies:Germany and Switzerland apothecary channels bypass grocery consolidation. Propolis and pollen formulations command pharmacy-grade premiums through trained staff recommendation.
- Specialty Stores:Manuka honey and single-origin varietals. Blockchain traceability combined with isotope ratio mass spectrometry enables origin-verified positioning against blended commodity supply.
- Online Retailers:Direct-to-consumer lyophilized royal jelly and subscription honey. China's e-commerce platforms integrate SAMR authenticity verification into listing requirements.
- Supermarkets/Hypermarkets:Blended and private-label honey at price-competitive tiers. Consolidated buyer power compresses supplier margins toward commodity extraction economics.
- Direct Sales:Apiary-tourist and farmers-market channels. Artisan-scale suppliers leverage hive-visit transparency against industrial packer scale advantages.
Supermarkets/Hypermarkets retain the broadest reach, yet Pharmacies are gaining share fastest among premium-positioned suppliers.
Application:
Functional claim substantiation requirements stratify formulation investment and regulatory pathway complexity.
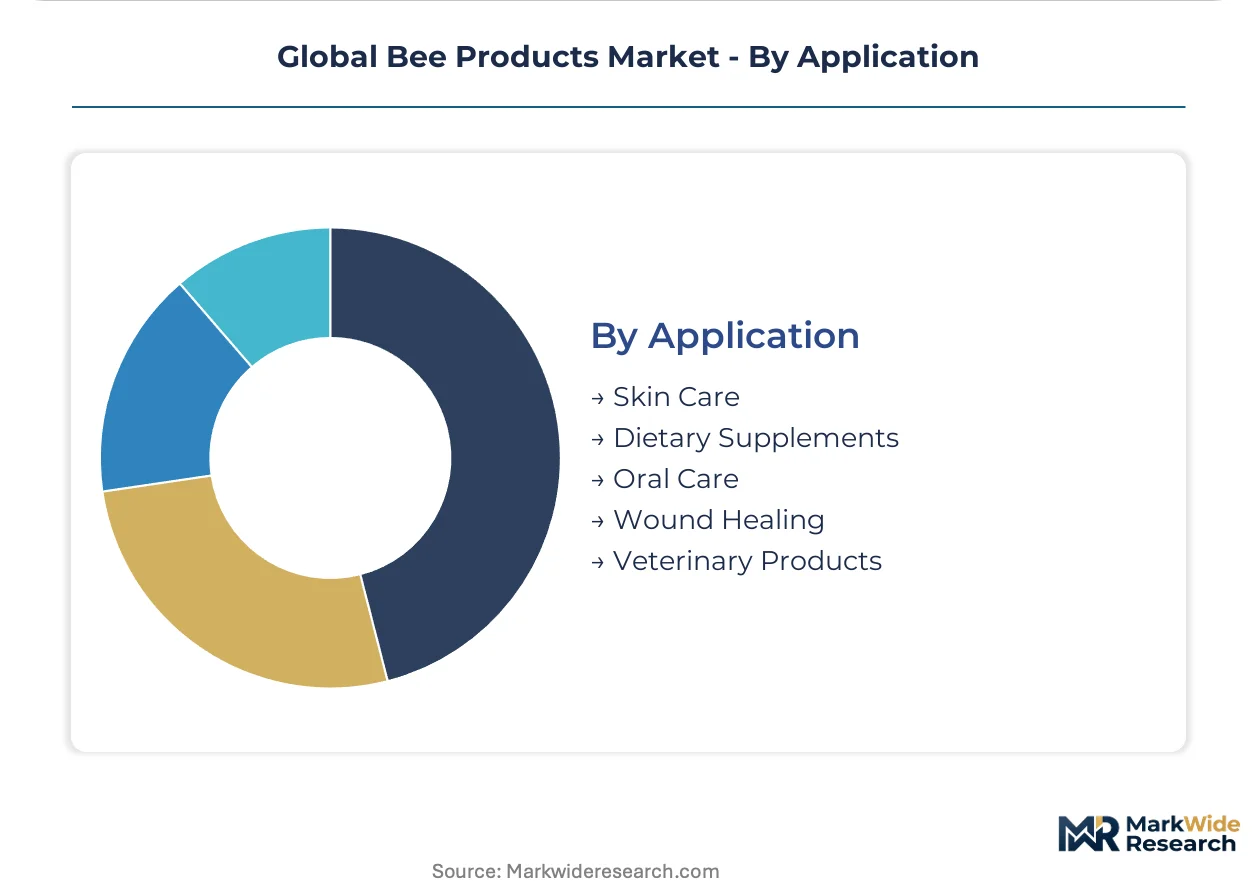
- Skin Care:Propolis anti-aging serums and honey humectant bases. South Korean cosmetics conglomerates concentrate R&D procurement specification power in Seoul-based innovation centers.
- Dietary Supplements:Royal jelly 10-HDA capsules and propolis immune support. Lyophilization technology preserves bioactive potency for shelf-stable distribution formats.
- Wound Healing:Medical-grade honey dressings with antimicrobial certification. Australia's TGA and Health Canada PMRA govern device-drug boundary classifications.
- Oral Care:Propolis mouthwash and honey-based throat preparations. Pharmacy-channel penetration in German-speaking markets drives specification-grade demand.
- Veterinary Products:Hive product supplements for livestock and companion animals. Regulatory pathways remain underdeveloped relative to human application standards.
Skin Care captures the dominant formulation value, while Dietary Supplements is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in New Zealand Manuka honey commands premiums unattainable by Argentine bulk exporters, creating a structural asymmetry that rewards origin-verified supply chains over commodity volume plays.
China
Shandong Province integrated apiculture clusters supply domestic nutraceutical processors and export channels under SAMR residue compliance protocols. GB standards enforce authenticity testing that determines import eligibility for foreign honey suppliers. Qingdao-based extraction facilities are scaling lyophilization capacity for royal jelly concentrate exports.
South Korea
Seoul-based cosmetics R&D centers specify polyphenol content and geographic origin prior to propolis contract execution. MFDS cosmetic ingredient regulations govern anti-aging serum formulation claims. Busan-Ulsan manufacturing corridors are absorbing specification-grade procurement from Australian and New Zealand hive-to-extract operators.
Germany
Apothecary channels bypass grocery consolidation to capture margin from pharmacy-grade propolis and pollen formulations. EFSA novel food assessments shape market access for royal jelly extracts across EU member states. Bavarian apiary cooperatives are deploying modular lyophilization units to preserve 10-HDA potency for capsule export.
United States
North American clover honey belt operations sustain geographic dominance through mechanized extraction at industrial scale. FDA DSHEA dietary supplement label claim substantiation creates extended correspondence timelines for 10-HDA-positioned product launches. Pacific Northwest artisan-scale suppliers leverage hive-visit transparency against commodity packer economics.
India
Ayurvedic heritage positioning drives pharmacy-channel penetration across South Asian markets. FSSAI regulatory pathways for bee-derived nutraceuticals remain underdeveloped relative to formulation potential. Maharashtra and Karnataka processing clusters are integrating backward into captive apiary networks to secure residue-compliant raw material.
Global Bee Products Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with lyophilization-equipped specialists commanding premium tiers while mechanized extractors dominate commodity volume. The vendor base stratifies across three tiers: vertically integrated hive-to-shelf operators, geographic-dominant regional packers, and heritage-positioned Ayurvedic formulators. Consolidation pressure concentrates among mid-scale apiary associations seeking analytical capabilities for ECHA REACH compliance. Dominant competitive moves include backward integration into captive breeding stock and blockchain-enabled origin verification deployment.
Within the heritage-formulation tier, Dabur Ltd. occupies a position exemplifying Ayurvedic-channel penetration across South Asian pharmacy networks. Among Antipodean operators, Comvita Limited represents vertically integrated hive-to-shelf architecture spanning New Zealand and Australian extraction facilities. At the North American scale-driven end, Barkman Honey LLC anchors geographic dominance in the clover belt through mechanized extraction infrastructure.
| Leading Market Players |
|---|
| Dadant & Sons Inc. |
| Mann Lake Ltd. |
| GloryBee |
| Capilano Honey Limited |
| Barkman Honey LLC |
| Comvita Limited |
| Y.S. Organic Bee Farms |
| Dabur Ltd. |
| Betterbee Inc. |
| Others |
Supply & Pricing Matrix
Mechanized extraction scale in North American clover belt operations compresses unit economics for commodity honey, while lyophilization-equipped specialists in New Zealand and Australia command 10-HDA potency premiums that artisan-scale apiarists cannot match. This bifurcation concentrates margin pools upstream with technology-enabled processors and downstream with pharmacy-channel formulators, leaving mid-scale packers exposed to input cost volatility from nucleus colony and queen bee pricing fluctuations.
Pricing Analysis
Configured-to-order pricing for polyphenol-certified propolis extracts diverges sharply from standard bulk honey spot markets. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and geographic origin verification, with South Korean cosmetics manufacturers paying specification premiums for Seoul R&D center contracts. Cost compression in standard-grade multifloral honey intensifies because supermarket buyer consolidation extracts supplier concessions. Industrial honey packers exhibit highest price sensitivity, while pharmacy-channel propolis formulators demonstrate inelastic demand for EFSA novel food assessed extracts.
Supply Chain Analysis
Port congestion on Asia-Pacific trade lanes elevates inbound logistics costs for lyophilized royal jelly concentrate shipments from Qingdao extraction facilities to European nutraceutical processors. Raw material supply concentrates in China, New Zealand, and Argentina, with hive product extraction drawing from nucleus breeding stock, floral forage availability, and seasonal colony strength. Single-source vulnerability to China's SAMR residue limit enforcement creates regulatory chokepoint exposure for foreign honey suppliers. Distribution runs through integrated apiculture clusters in Shandong Province, direct-to-apothecary channels in Germany, and consolidated grocery retail in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-derived emollient and antimicrobial substitutes in cosmetics formulations threaten propolis and royal jelly premium positioning, forcing incumbents to defend bioactive potency certification as non-replicable differentiation.
For Market Incumbents: Secure captive apiary networks in residue-compliant zones to insulate against China's SAMR enforcement volatility and EU Green Deal pesticide restriction expansion. Deepen backward integration into queen breeding operations to reduce nucleus colony cost exposure. Invest in modular lyophilization deployment at cooperative scale to preserve 10-HDA potency advantages against centralized pharmaceutical-grade competitors.
For New Entrants and Emerging Players: Lead with blockchain-enabled origin verification for single-origin varietals in specialty retail channels where transparency commands premium positioning against blended commodity supply. Target India's underdeveloped FSSAI regulatory pathway for Ayurvedic-positioned bee products, exploiting pharmacy-channel penetration gaps that Dabur Ltd. has not fully saturated. Deploy direct-to-apothecary distribution in German-speaking markets to bypass grocery consolidation economics.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors lyophilization-equipped hive-to-extract operators with ECHA REACH compliance capabilities over undifferentiated commodity packers. Long-term viability hinges on regulatory certification moats and geographic origin verification infrastructure rather than scale alone. Monitor EFSA novel food assessment timelines as inflection indicator for royal jelly and propolis extract market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capacity Expansion | Preserves 10-HDA potency for capsule export formats against non-lyophilized degradation limits. |
| Blockchain Traceability Deployment | Enables isotope ratio mass spectrometry origin verification for Manuka-grade premium positioning. |
| Captive Apiary Network Integration | Secures residue-compliant raw material supply under tightening EU Green Deal pesticide restrictions. |
| EFSA Novel Food Assessment Investment | Unlocks pharmacy-channel market access for royal jelly extracts across EU member states. |
| Direct-to-Apothecary Channel Development | Bypasses grocery consolidation to capture margin from pharmacy-grade propolis formulations in Germany. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, EFSA novel food submission records, and SAMR GB standard documentation. Primary interviews incorporated apiary cooperative managers, cosmetics R&D procurement leads at Seoul-based innovation centers, pharmacy-channel category buyers in Germany and Switzerland, and regulatory affairs specialists navigating DSHEA label claim substantiation. Secondary validation drew from FDA dietary supplement enforcement letters, ECHA REACH registration databases, and FSSAI nutraceutical pathway guidance. Bottom-up hive production estimates and top-down formulation demand aggregation were cross-referenced for triangulation.
Segmentation dimensions modeled include product type, end-use industry, distribution channel, and application across the analysis window. The quantitative framework projected value expansion by mapping lyophilization technology adoption curves, EFSA novel food approval velocities, and cosmetics formulation procurement specification tightening. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic drivers including pollinator protection policy evolution and premium channel penetration trajectories.
Forecasts assume regulatory continuity in FDA DSHEA enforcement, EFSA novel food assessment protocols, and China's SAMR residue limit frameworks; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Postbiotic Pet Food Market
Specialty Foods
Edible Mushroom Market
Specialty Foods
Halal Market
Specialty Foods
Low Fat and Low Carb Foods Market
Specialty Foods
Curculin Market
Specialty Foods
Hairball Cat Food Market
Specialty Foods
Carbonic Maceration Market
Specialty Foods
Grain Free Dog Food Market
Specialty Foods
Zhacai Market
Specialty Foods
Military Forces Ready to Eat Meals Market
Specialty Foods
Asia-Pacific Free from Food Market
Specialty Foods
Global Cordyceps Militaris Market
Specialty Foods
Human Grade Pet Food Market
Specialty Foods
Tunisia Couscous Market
Specialty Foods
Vegetarian Tacos Market
Specialty Foods
Low Calorie Chocolate Desserts Market