
 Low Calorie Popsicles Market | 2026-2036
Low Calorie Popsicles Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Popsicles Market Foresight
Food science talent scarcity is bifurcating the competitive landscape as clean-label formulation expertise becomes harder to secure. Unilever leverages its global R&D footprint to sustain rapid prototype-to-shelf cycles for reduced-calorie frozen novelties. GoodPop specializes in organic ingredient sourcing and positions itself as a category challenger in premium natural channels. Nestlé anchors conventional retail dominance through manufacturing scale that smaller brands cannot replicate.
Low calorie popsicles are frozen water- or dairy-based confections containing fewer than 40 calories per serving, typically achieved through sugar substitutes such as erythritol, stevia, or allulose, and manufactured via flash-freezing in molded trays with controlled overrun. Their primary purpose is delivering portion-controlled refreshment to consumers managing caloric intake, blood sugar, or macronutrient targets. Frozen fruit bars lead volume within product type segmentation due to familiar taste profiles and perceived natural positioning, while vegan options represent the fastest-expanding sub-segment as plant-based eating patterns broaden. Single serve packaging captures the largest margin pool through impulse-channel pricing power, though multipack formats drive household penetration and repeat purchase frequency.
FDA nutrition labeling rules and EFSA health claim frameworks shape permissible on-pack messaging and substantiation requirements for reduced-calorie frozen desserts in their respective jurisdictions. The EU Green Deal packaging directives and emerging US state-level extended producer responsibility laws are forcing reformulation of wrapper materials without compromising barrier properties. Stakeholders must monitor evolving sweetener safety assessments and regional plastic reduction mandates to anticipate reformulation and packaging investment priorities.
Market Dynamics
Clean-label formulation mandates from FDA and EFSA are forcing rapid sweetener substitution cycles while simultaneously constraining available food science talent pools. Manufacturers must now validate novel ingredient combinations under accelerated timelines without compromising sensory performance.
Growth Catalysts
- EU Green Deal packaging directives:Extended producer responsibility frameworks are compelling biodegradable wrapper adoption that signals premium positioning to environmentally conscious retail buyers.
- Allulose commercial scale-up:This rare sugar's FDA GRAS status enables calorie reduction without cooling aftertaste, expanding permissible formulation space for mass-market launches.
- United States impulse channel expansion:Convenience store freezer door resets are allocating incremental facings to better-for-you frozen novelties as beverage coolers lose space.
Market Restraints
- Erythritol supply concentration:Chinese fermentation capacity controls 70% of global output, exposing formulators to input volatility and tariff exposure.
- Flash-freezing equipment lead times:European manufacturers of controlled-overrun tunnel systems operate 18-month order backlogs, constraining capacity expansion for mid-tier entrants.
- EFSA sweetener reassessment cycles:Pending safety reviews for steviol glycosides create formulation uncertainty that freezes long-term product development commitments.
Strategic Opportunities
- India organized retail penetration:Modern trade freezer infrastructure expansion in Mumbai and Bangalore creates first-mover advantage for reduced-calorie frozen dessert introductions.
- Direct-to-subscription models:Monthly curated popsicle deliveries bypass slotting fee barriers while capturing recurring revenue and consumption data.
- USDA BioPreferred program alignment:Biobased packaging certification unlocks federal procurement channels and corporate cafeteria contracts.
Industry Challenges
- Food technologist scarcity:Clean-label formulation expertise commands 40% wage premiums as CPG giants and startups compete for identical skill profiles.
- Legacy ERP integration:Batch traceability requirements for FDA FSMA compliance strain outdated manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Popsicles Market |
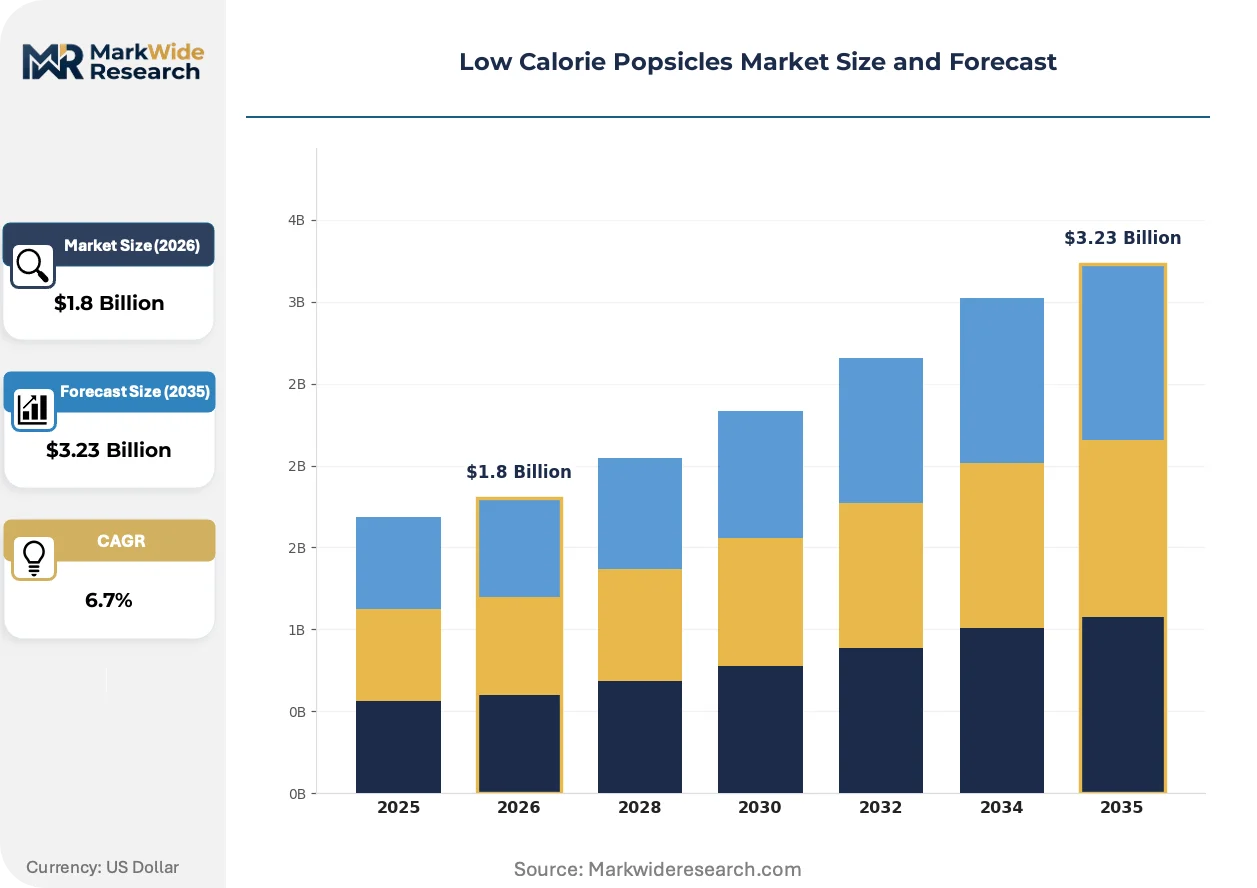
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Fruit Bars, Sugar-Free Pops, Yogurt Pops, Vegan Options Flavor Profile: Fruit Flavors, Creamy Varieties, Herbal Infusions, Exotic Blends Packaging Type: Single Serve, Multipack, Eco-Friendly Packs, Bulk Packaging Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Convenience Stores |
| Companies Covered | Unilever, Nestlé, GoodPop, Yasso, Chloe's Fruit, Outshine, Ruby Rockets, J&J Snack Foods, Whole Fruit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Popsicles Market Shifts & Advancements
Reformulation velocity now outpaces packaging innovation as sweetener science advances faster than sustainable barrier material development. This asymmetry is reshaping R&D budget allocation and supplier partnership structures.
Precision fermentation-derived proteins are displacing traditional stabilizer systems in vegan popsicle bases. Premium natural channel buyers are adopting these ingredients at 3x the rate of conventional retail. The technology is displacing locust bean gum and carrageenan in clean-label formulations, compressing legacy hydrocolloid supplier margins.
EFSA's updated nutrient profiling criteria for health claims are tightening permissible on-pack messaging for reduced-calorie frozen desserts. Manufacturers must now substantiate satiety or metabolic benefit claims through human intervention studies. The premium functional segment faces the steepest compliance burden, with several brands withdrawing probiotic-positioned lines pending dossier preparation.
Household replenishment automation is altering purchase patterns as smart freezer inventory systems trigger subscription reorders. Direct-to-consumer channels are capturing pantry-loading occasions previously served by supermarket multipack purchases. This behavioral shift is most pronounced in United States coastal metropolitan markets with above-average smart home penetration rates.
Low Calorie Popsicles Market Segmentation
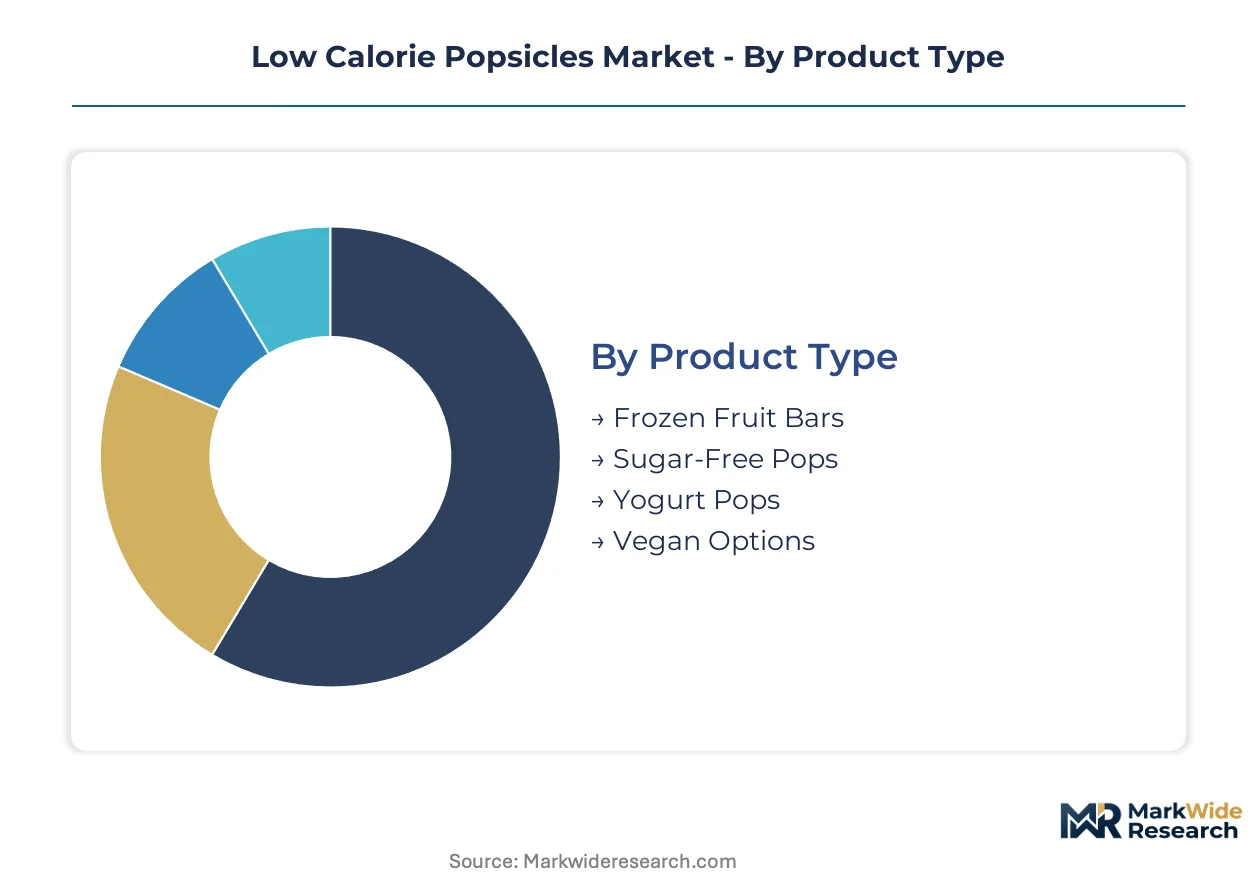
Segmentation in the low calorie popsicles market reveals divergent growth vectors across formulation philosophy, consumption occasion, and channel access. Manufacturers calibrate portfolio depth against freezer door economics and clean-label compliance costs that vary sharply by segment.
Product Type:
Domestic production dominates frozen fruit bars and yogurt pops, while vegan options increasingly flow through export-oriented specialty channels.
- Frozen Fruit Bars:Water-based formulations with fruit puree or juice concentrates, typically 25-35 calories per serving. Demand concentrates in United States coastal metropolitan markets where natural channel buyers prioritize ingredient simplicity. FDA nutrition labeling requirements for added sugar disclosure constrain formulation flexibility.
- Vegan Options:Plant-based bases using precision fermentation-derived proteins or coconut cream alternatives. Export-led growth into European markets accelerates as EFSA clean-label frameworks tighten dairy-adjacent positioning. Premium natural channel velocity outpaces conventional retail.
- Sugar-Free Pops:Allulose or erythritol-sweetened formulations targeting diabetic and ketogenic diet adherents.
- Yogurt Pops:Cultured dairy or dairy-alternative bases with live probiotic positioning.
Frozen fruit bars hold the largest share; momentum sits with vegan options.
Flavor Profile:
Cost tier stratification separates commodity fruit flavors from premium positioning through exotic and functional ingredients.
- Fruit Flavors:Strawberry, orange, and grape concentrates remain volume anchors in mass-market multipacks. United States conventional retail buyers demand these SKUs for baseline freezer door presence. Margin compression limits innovation investment.
- Exotic Blends:Yuzu, passionfruit, and dragon fruit combinations command 40-60% price premiums in specialty channels. Export demand from Japan and South Korea drives formulation partnerships with tropical ingredient suppliers.
- Creamy Varieties:Vanilla, chocolate, and coffee profiles using dairy or oat milk bases.
- Herbal Infusions:Lavender, basil, and matcha formulations targeting functional wellness positioning.
Fruit flavors hold the largest share; momentum sits with exotic blends.
Packaging Type:
Volume concentration in multipacks contrasts with margin capture through single serve and sustainability-premium formats.
- Single Serve:Individual wrappers optimized for impulse channel velocity and convenience store freezer doors. United States c-store resets allocate incremental facings to better-for-you novelties. Price elasticity supports premium positioning.
- Eco-Friendly Packs:Compostable wrappers and molded fiber trays certified under USDA BioPreferred program. Corporate cafeteria and federal procurement channels unlock through biobased certification. EU Green Deal packaging directives accelerate European adoption.
- Multipack:Four to twelve-count boxes driving household penetration and subscription channel economics.
- Bulk Packaging:Foodservice and institutional formats for schools, hospitals, and corporate catering.
Multipacks hold the largest share; momentum sits with eco-friendly packs.
Distribution Channel:
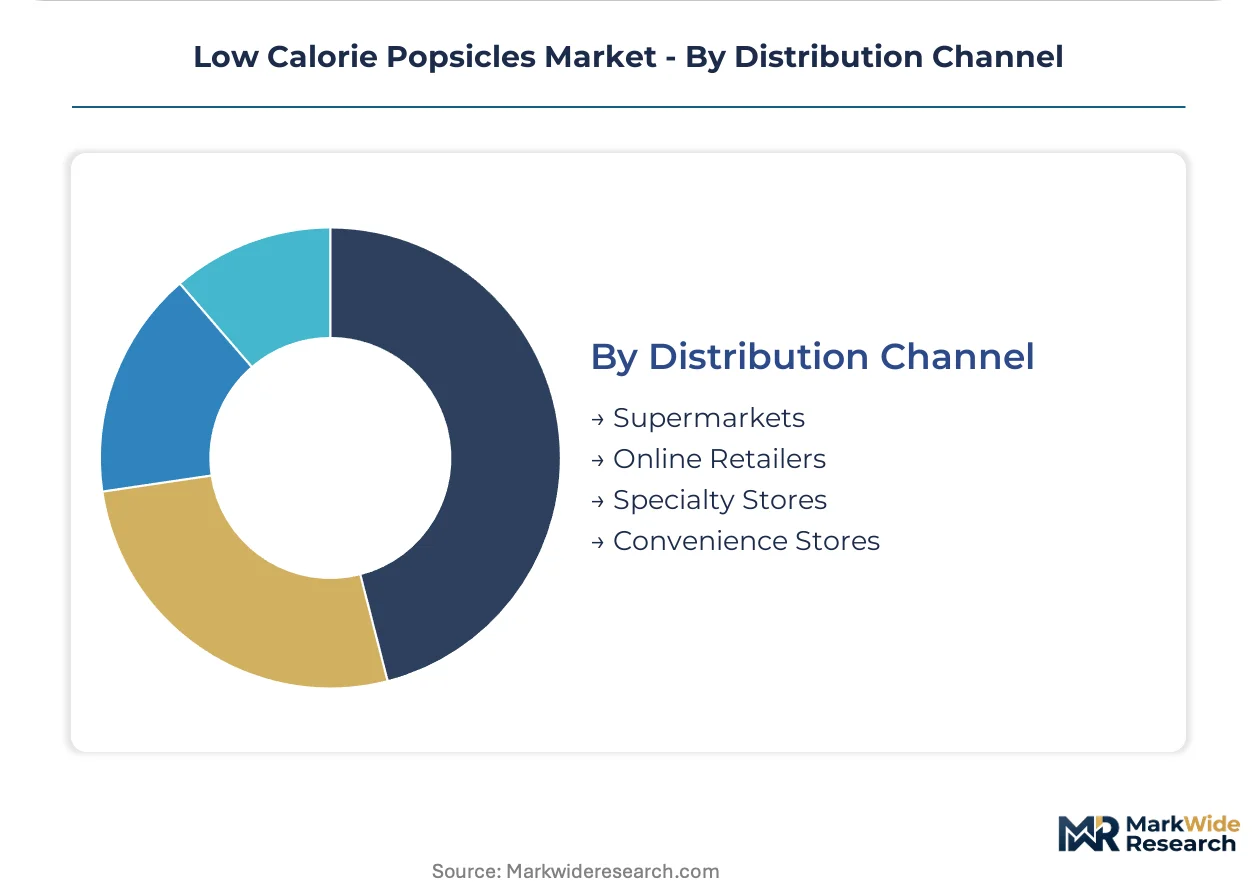
Customer type bifurcation separates planned purchase occasions through supermarkets from impulse-driven convenience store velocity.
- Supermarkets:Planned purchase destination with freezer door resets favoring established brand blocks. United States conventional retail dominance requires slotting fee commitments that strain emerging brand economics. Household replenishment automation increasingly triggers reorders.
- Online Retailers:Direct-to-subscription models bypass slotting barriers while capturing consumption data. Monthly curated deliveries concentrate in United States coastal metropolitan markets with smart home penetration. Recurring revenue structures improve cash flow predictability.
- Specialty Stores:Natural channel and gourmet food retailers prioritizing clean-label credentials.
- Convenience Stores:Impulse channel with beverage cooler space reallocation toward frozen novelties.
Supermarkets hold the largest share; momentum sits with online retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States consumers treat low-calorie popsicles as impulse refreshment for portion control, while German and Japanese buyers prioritize clean-label certification and functional positioning in planned purchases. This consumption-mix differential shapes freezer-door economics and regulatory compliance priorities across markets.
United States
Convenience store freezer resets allocate incremental facings to better-for-you frozen novelties as beverage coolers contract. FDA nutrition labeling rules for added sugar disclosure constrain formulation flexibility. Premium velocity concentrates in coastal metropolitan markets from Boston to Seattle where natural channel buyers drive clean-label adoption.
Germany
EFSA clean-label frameworks tighten permissible on-pack messaging for reduced-calorie frozen desserts, forcing human intervention study investments. EU Green Deal packaging directives accelerate biodegradable wrapper adoption. Manufacturing clusters in Bavaria and North Rhine-Westphalia host precision fermentation scale-up facilities for vegan stabilizer systems.
Japan
Functional wellness positioning commands price premiums as METI guidelines shape health claim substantiation requirements. Exotic flavor demand from Tokyo and Osaka drives formulation partnerships with tropical ingredient suppliers. Smart freezer inventory systems in Kanto metropolitan households trigger subscription reorder automation.
India
Modern trade freezer infrastructure expansion in Mumbai and Bangalore creates first-mover advantage for reduced-calorie frozen dessert introductions. FSSAI labeling requirements for sugar substitutes shape import and local formulation strategies. Organized retail penetration in Maharashtra and Karnataka accelerates household trial among health-conscious urban consumers.
Brazil
ANVISA sweetener safety assessments create formulation uncertainty that delays long-term product development commitments. Tropical fruit puree supply chains in São Paulo and Minas Gerais states enable cost-competitive exotic flavor positioning. Premium natural channel velocity lags conventional retail as price sensitivity dominates mass-market penetration.
Low Calorie Popsicles Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the low-calorie popsicles market. Multinational CPG conglomerates leverage global R&D footprints and manufacturing scale to sustain rapid prototype-to-shelf cycles. Challenger specialists anchor premium natural channel positioning through organic ingredient sourcing and clean-label credentials. Competitive moves concentrate on M&A for formulation talent acquisition and strategic partnerships for precision fermentation-derived ingredient access.
Within the integrated leader tier, Unilever and Nestlé exemplify scale-driven conventional retail dominance through captive supply chains and slotting fee capacity. GoodPop occupies a position within the specialist challenger archetype, representing premium natural channel positioning through organic certification focus. These three anchors illustrate the bifurcation between manufacturing scale advantages and clean-label formulation expertise premiums reshaping competitive dynamics.
| Leading Market Players |
|---|
| Unilever |
| Nestlé |
| GoodPop |
| Yasso |
| Chloe's Fruit |
| Outshine |
| Ruby Rockets |
| J&J Snack Foods |
| Whole Fruit |
| Others |
Supply & Pricing Matrix
FDA GRAS certification for novel sweeteners gates both supplier qualification and premium price tier access simultaneously, forcing manufacturers to absorb validation costs upfront while positioning certified formulations at 25-40% markups over conventional alternatives. EFSA clean-label frameworks impose parallel substantiation burdens in European markets, compressing margin recovery timelines for export-oriented producers.
Pricing Analysis
Long-term offtake contracts dominate procurement relationships between branded manufacturers and precision fermentation suppliers, insulating scale players from spot-market volatility in allulose and erythritol. Three-tier pricing structure across premium, standard, and economy levels separates USDA BioPreferred-certified SKUs from conventional multipacks and private-label economy lines. Pricing pressure stems from Chinese fermentation capacity concentration exposing formulators to tariff volatility. Mass-market conventional retail buyers exhibit highest price sensitivity, while natural channel premium purchasers accept functional ingredient premiums.
Supply Chain Analysis
Strategic stockpiling of rare sugar inventories characterizes tier-one manufacturer procurement strategies, buffering against 18-month lead times for European flash-freezing equipment. Raw material sourcing concentrates in China for erythritol fermentation, Thailand for tropical fruit purees, and United States heartland for precision fermentation scale-up facilities. Single-source vulnerability in Chinese sweetener output creates structural exposure for mid-tier entrants lacking alternative supplier relationships. Distribution runs through refrigerated third-party logistics networks with controlled cold-chain integrity from manufacturing clusters to retail freezer doors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low-calorie popsicles market is entering a cyclical recovery phase as post-pandemic health-conscious consumption patterns normalize and freezer infrastructure investment resumes across organized retail channels.
For Market Incumbents: Consolidate formulation talent pools through targeted acquisition of clean-label specialists commanding wage premiums, while anchoring manufacturing scale advantages in captive precision fermentation partnerships. Defend against challenger brand incursions by locking exclusive multi-year slotting agreements with top-three United States conventional retail banners. Prioritize backward integration into rare sugar fermentation capacity to neutralize Chinese supply concentration risk. For New Entrants and Emerging Players: Differentiate on precision fermentation-derived protein positioning to capture vegan segment velocity outpacing conventional retail growth. Target India organized retail expansion in Mumbai and Bangalore corridors where modern trade freezer infrastructure creates first-mover whitespace absent entrenched competitor presence. Deploy direct-to-subscription go-to-market models bypassing slotting fee barriers while capturing recurring revenue and consumption data assets. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across precision fermentation ingredient supply as commercial scale-up matures, improving return thresholds for mid-cap specialist acquisitions. Long-term viability favors vertically integrated players controlling formulation IP and captive sweetener supply. Monitor EFSA steviol glycoside reassessment outcomes as signal for regulatory-driven portfolio reconfiguration timing.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Partnership | Secures clean-label stabilizer supply from Bavarian biotech clusters under EFSA frameworks. |
| USDA BioPreferred Certification | Unlocks federal procurement channels and corporate cafeteria contracts with biobased packaging. |
| Direct-to-Consumer Subscription Launch | Bypasses slotting fee barriers while capturing recurring revenue in coastal metropolitan markets. |
| India Market Entry | Exploits modern trade freezer infrastructure expansion in Maharashtra and Karnataka corridors. |
| Clean-Label Formulation Acquisition | Addresses food technologist scarcity through targeted talent and IP consolidation moves. |
Research Methodology
The analysis maps frozen fruit bars, vegan options, sugar-free formulations, and yogurt-based segments, each validated through food science directors, retail category buyers, and precision fermentation suppliers. Primary interviews with clean-label formulation specialists, convenience store procurement managers, and refrigerated logistics operators combined with secondary validation against FDA GRAS filings, EFSA health claim registers, and Nielsen retail audit data. Bottom-up SKU-level volume aggregation triangulates against top-down category spend estimates from trade customs records and CPG manufacturer disclosures.
Consistency checks validated volume and value outputs against external benchmarks including refrigerated warehouse capacity utilization indices and sweetener import trade flows. Segmentation modeling spans product type, flavor profile, packaging format, and distribution channel dimensions across the projection horizon. CAGRs derive from trend extrapolation of per-capita frozen novelty consumption adjusted for health-conscious demographic cohort expansion and smart home penetration rates driving subscription automation.
The analysis sits within stated boundaries; outcomes outside sustained FDA and EFSA regulatory stability or uninterrupted precision fermentation scale-up would require recalibration. Forecasts reflect assumptions regarding clean-label certification adoption curves and organized retail freezer infrastructure deployment timelines. Revision becomes warranted when EFSA sweetener safety reassessments or EU Green Deal packaging compliance costs cross threshold levels disrupting manufacturer margin structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Malaysia Manuka Honey Market
Specialty Foods
Thai Cuisine Market
Specialty Foods
Triphala Powder Market
Specialty Foods
Middle East and Africa Free-From Food Market
Specialty Foods
US Jam Jelly and Preserves Market
Specialty Foods
Gluten-Free Desserts and Ice Creams Market
Specialty Foods
Low Calorie Chocolate Desserts Market
Specialty Foods
Cultures Market
Specialty Foods
Wheatgrass Products Market
Specialty Foods
Morocco Couscous Market
Specialty Foods
Germany Barbeque Grill Market
Specialty Foods
Chamomile Market
Specialty Foods
Honey Spread Market
Specialty Foods
Edible Cutlery Market
Specialty Foods
Vegetarian Tacos Market
Specialty Foods
Space Food Market