
 Low Calorie Desserts Market | 2026-2036
Low Calorie Desserts Market Size, Share, and Industry Trends Forecast 2026-2036
Low Calorie Desserts Market Foresight
Stevia extract is expanding its share in low calorie dessert formulations as brands reformulate away from artificial sweeteners to meet clean-label expectations. Danone S.A. leverages its dairy fermentation expertise to sustain a dominant position in European reduced-calorie yogurt desserts. Halo Top Creamery anchors its competitive identity on ultra-low calorie positioning in the premium frozen novelty segment. Unilever PLC competes through its global ice cream infrastructure, extending reformulation capabilities across multiple regional markets.
Low calorie desserts comprise frozen and refrigerated sweet products formulated with reduced caloric density through modified carbohydrate profiles, alternative sweeteners, and controlled fat content, typically achieving caloric reductions through sugar alcohols, high-intensity natural sweeteners, or fiber enrichment while maintaining acceptable sensory properties. Frozen yogurt leads product type demand due to its established health halo and probiotic positioning, though sugar-free gelato is gaining velocity in premium channels. Erythritol and monk fruit sweetener systems command higher formulation costs but attract margin pools in health food store and online retail channels where ingredient transparency drives purchasing decisions.
FDA nutrition labeling requirements and the EU Health Claims Regulation constrain permissible marketing language around reduced-calorie positioning, compelling manufacturers to substantiate reformulation investments with validated compositional data. The USDA organic seal and EU organic certification create parallel compliance pathways that influence sweetener sourcing and clean-label formulation priorities. Stakeholders must monitor evolving WHO guidance on non-sugar sweeteners and anticipate how pending FDA guidance on the definition of healthy could recalibrate permissible product positioning across retail and food service channels.
Market Dynamics
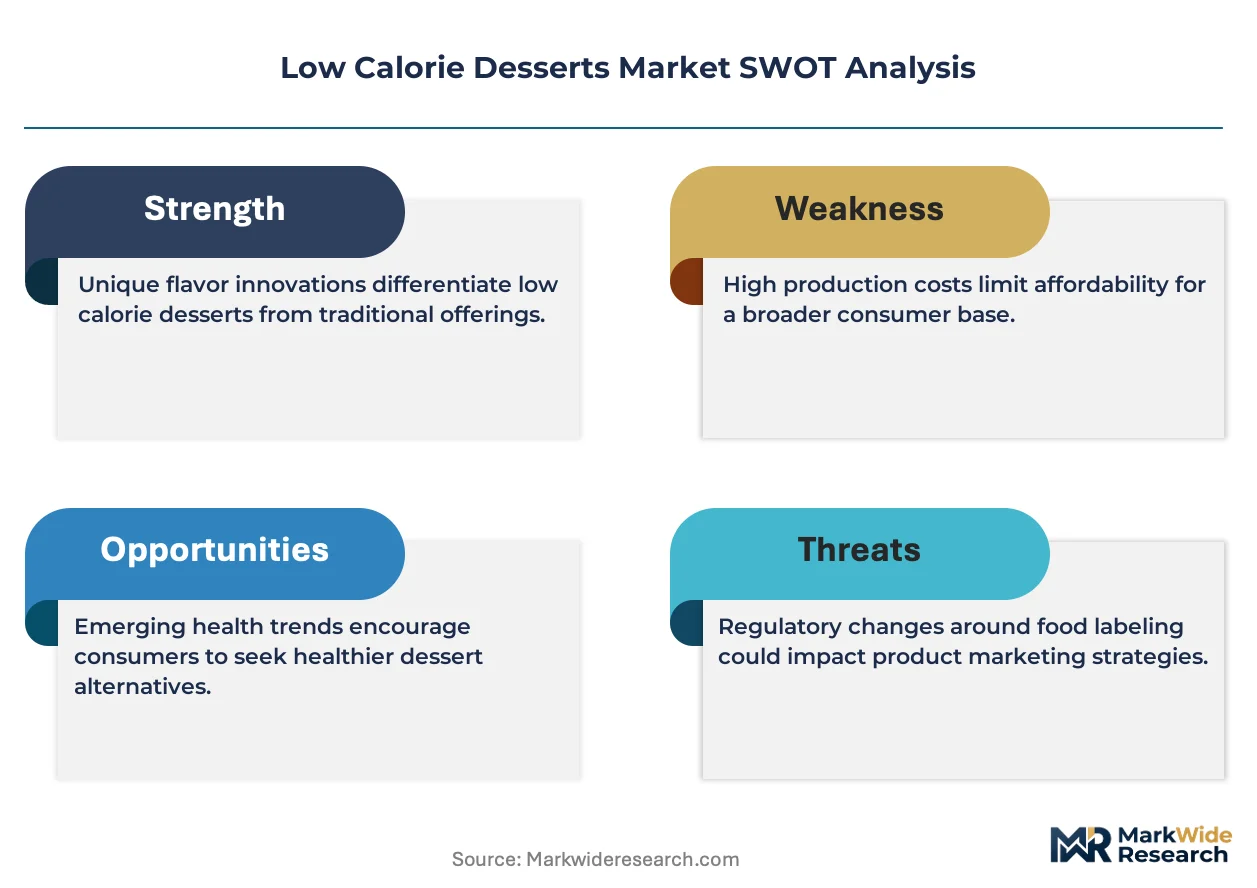
Reformulation pressure from FDA Nutrition Facts labeling rules and EU health claims regulations is compressing formulation cycles and forcing manufacturers to rebuild sweetener systems around natural alternatives, fundamentally restructuring competitive capabilities in reduced-calorie dessert production.
Growth Catalysts
- Clean-label mandates:FDA updated Nutrition Facts panels and EU health claims regulations compel brands to eliminate artificial sweeteners, accelerating natural stevia and monk fruit adoption across frozen novelties.
- Urban millennial concentration:Health-conscious consumers in dense metropolitan clusters in the United States, Germany, and Japan drive portion-controlled frozen yogurt and gelato velocity through premium retail channels.
- Fermentation technology maturation:Advanced dairy fermentation processes enable protein enrichment and sugar reduction simultaneously, expanding the functional positioning of refrigerated yogurt desserts.
Market Restraints
- Erythritol cost volatility:Supply concentration for high-purity sugar alcohols in Chinese manufacturing creates input price instability that compresses margins on premium clean-label formulations.
- Sensory ceiling effects:Current natural sweetener systems face technical limitations in replicating the freeze-thaw stability and mouthfeel of sucrose in frozen dessert matrices.
- EU regulatory friction:EFSA health claims authorization requirements restrict permissible marketing language around reduced-calorie positioning, limiting brand communication flexibility.
Strategic Opportunities
- Japanese functional foods convergence:Integration of FOSHU (Foods for Specified Health Uses) regulatory pathways enables probiotic and fiber-enriched dessert positioning in aging consumer segments.
- Direct-to-frozen distribution innovation:E-commerce cold-chain infrastructure expansion creates white-space channels for ultra-premium low-calorie gelato outside conventional grocery retail.
- USDA organic certification tailwind:Organic sweetener sourcing requirements align with clean-label priorities, opening margin pools in natural food store and specialty retail channels.
Industry Challenges
- Reformulation talent scarcity:Food scientists with specialized expertise in natural sweetener synergy and sensory masking remain concentrated at established dairy and ingredient suppliers, constraining in-house capability building.
- Dual certification complexity:Simultaneous compliance with FDA nutrition labeling and EU organic certification creates extended timeline risk for cross-Atlantic product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Desserts Market |
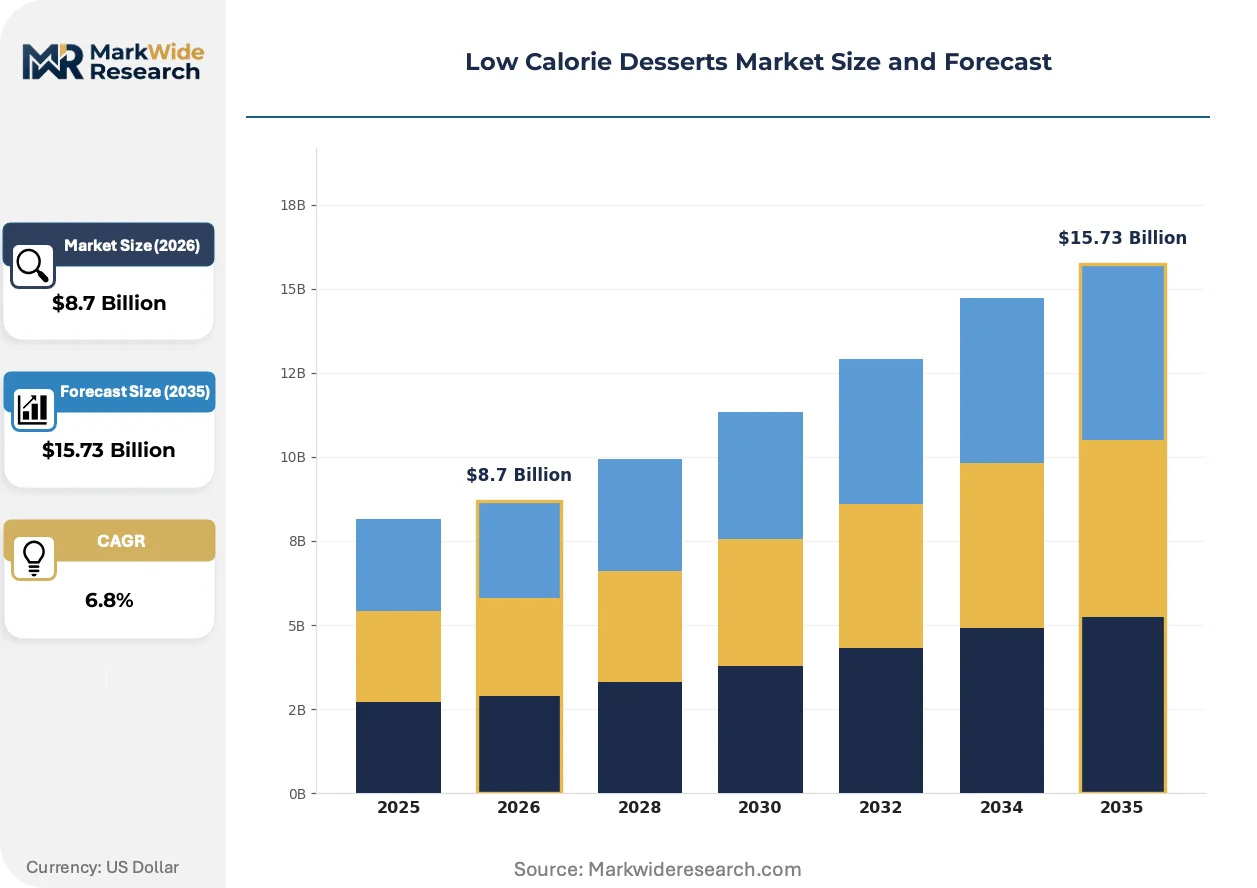
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Yogurt, Sugar-Free Gelato, Low Calorie Pudding, Fruit Sorbet Sweetener Type: Stevia, Erythritol, Monk Fruit, Sucralose Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Food Service Packaging Type: Plastic Containers, Pouches, Cups, Multi-Packs |
| Companies Covered | The Kraft Heinz Company, Danone S.A., Nestlé S.A., Halo Top Creamery, Grupo Bimbo, Unilever PLC, PepsiCo Inc., Mondelez International Inc., General Mills Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Desserts Market Shifts & Advancements
Natural sweetener system innovation and regulatory recalibration of health claims are compressing traditional formulation cycles while opening new positioning territories for functionally enhanced desserts.
Precision fermentation-derived proteins and customized stevia glycoside blends are rewriting the technical boundaries of sugar reduction in frozen applications. Premium brands and health-focused retailers are adopting these systems at accelerated pace to maintain sensory parity with conventional desserts. The technology is rewriting competitive moats by separating brands with captive formulation expertise from those dependent on commoditized ingredient supply.
EFSA's evolving guidance on non-sugar sweetener health claims and pending FDA definition of "healthy" are recalibrating permissible marketing frameworks. Manufacturers face compressed windows for substantiation investments as regulators narrow acceptable positioning language. Frozen novelty segments in Germany and France are most affected, with brands accelerating compositional validation studies to preempt claim restrictions.
Health-halo purchasing is rotating from simple calorie reduction toward functional benefit stacking including probiotics, fiber, and protein. Direct-to-consumer subscription models and specialty online grocers are displacing conventional supermarket frozen aisles as primary discovery channels for novel low-calorie formats. This behavioral shift is most visible in United States coastal urban markets where digitally native brands build trial through influencer-driven sampling programs.
Low Calorie Desserts Market Segmentation
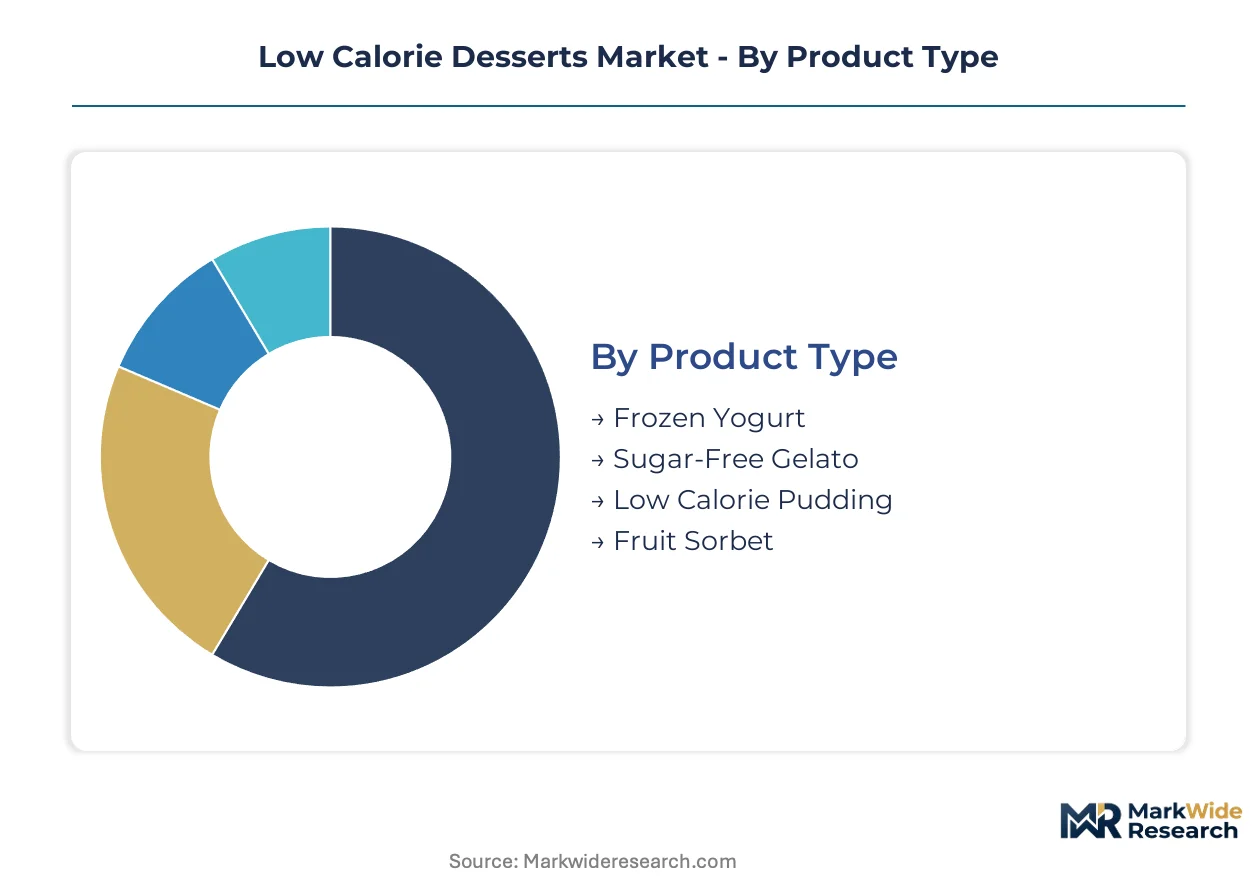
Low calorie desserts fragment across four distinct classification axes, each capturing different buyer priorities from sensory experience to ethical sourcing. Manufacturers must align formulation investments with channel-specific margin structures and regulatory exposure.
Product Type:
Buyers in this category differentiate primarily by consumption occasion and health-halo intensity, with probiotic positioning commanding premium tolerance.
- Frozen Yogurt:Fermented dairy base with live culture retention delivers the strongest functional health narrative in the category. Urban millennial clusters in the United States and Germany drive velocity through premium retail channels where probiotic claims justify price premiums over conventional ice cream.
- Sugar-Free Gelato:Dense, slow-churned Italian-style formulation achieves lower overrun than standard ice cream, enabling richer mouthfeel at reduced caloric density. Japanese and German markets show fastest adoption as consumers trade up from mass-market frozen novelties toward artisan positioning.
- Low Calorie Pudding:Refrigerated dairy or plant-based custard formats target portion-controlled snacking occasions with shelf-stable convenience.
- Fruit Sorbet:Water-based frozen dessert eliminates dairy entirely, appealing to vegan and allergen-sensitive segments with clean single-fruit ingredient decks.
Frozen yogurt leads volumes today; sugar-free gelato is gaining share fastest.
Sweetener Type:
Formulation costs and clean-label credibility separate buyers, with natural extraction methods commanding sourcing premiums over synthetic alternatives.
- Stevia:High-intensity glycoside extracts from Stevia rebaudiana enable 200-300x sweetness multiplication with zero glycemic impact. FDA GRAS status and EU food additive approvals position stevia as the default natural alternative for brands reformulating away from artificial systems.
- Erythritol:Sugar alcohol produced through corn-derived fermentation delivers bulk functionality with 0.2 kcal/g caloric density. Chinese manufacturing concentration creates input price volatility that compresses margins on premium clean-label formulations despite superior freeze-thaw stability.
- Monk Fruit:Mogroside extracts from Siraitia grosvenorii offer heat-stable sweetness with lingering licorice notes requiring flavor masking expertise.
- Sucralose:Chlorinated sucrose derivative maintains artificial sweetener cost leadership though facing accelerating clean-label displacement.
Stevia dominates new product development pipelines; monk fruit is climbing the fastest as brands seek differentiation beyond commodity natural positioning.
Distribution Channel:
Discovery behavior and cold-chain requirements segment buyers between impulse-driven physical retail and subscription-based digital channels.
- Supermarkets:Conventional grocery frozen aisles remain the volume anchor for established brands with slotting fee capacity and promotional programming infrastructure.
- Online Retail:Direct-to-consumer and specialty grocer platforms enable trial of ultra-premium formats outside conventional retail gatekeeping. United States coastal urban markets show strongest digital adoption where influencer-driven sampling programs build awareness.
- Health Food Stores:Natural channel retailers enforce ingredient transparency standards that validate organic certification and non-GMO positioning.
- Food Service:Restaurant and hospitality procurement prioritizes portion consistency and labor-minimal preparation over retail-style label claims.
Supermarkets retain volume leadership; online retail is expanding most quickly as cold-chain logistics mature.
Packaging Type:
Sustainability commitments and consumption occasion flexibility drive material selection and format geometry decisions.
- Plastic Containers:Recyclable PET and polypropylene tubs dominate frozen novelties with resealability and freezer durability. German packaging regulations and California extended producer responsibility laws are accelerating rPET content mandates.
- Pouches:Flexible film formats reduce shipping cube and enable single-serve squeezable consumption for on-the-go occasions.
- Cups:Portion-controlled rigid formats align with grab-and-go refrigerated dessert merchandising in convenience retail.
- Multi-Packs:Assorted flavor bundling drives household penetration through variety merchandising and per-unit value perception.
Plastic containers lead absolute volumes; pouches are gaining share fastest as brands target away-from-home consumption occasions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban millennial clusters in the United States, Germany, and Japan concentrate demand for portion-controlled frozen novelties with clean-label positioning. FDA and EFSA reformulation mandates reshape competitive capabilities across these markets.
United States
Health-conscious consumers in coastal metropolitan areas drive velocity for probiotic frozen yogurt and ultra-low-calorie frozen novelties. FDA updated Nutrition Facts labeling rules compel brands to eliminate artificial sweeteners and substantiate reduced-calorie claims with validated compositional data. Brooklyn and Los Angeles anchor the premium segment where digitally native brands build trial through influencer-driven sampling programs.
Germany
Discerning buyers in Berlin and Munich trade up from mass-market frozen desserts toward artisan sugar-free gelato with organic certification. EFSA health claims authorization requirements restrict permissible marketing language around reduced-calorie positioning, forcing accelerated compositional validation studies. The country's packaging regulations mandate accelerating rPET content in frozen novelty containers.
Japan
Aging consumer segments in Tokyo and Osaka propel demand for functional desserts with FOSHU regulatory pathway integration. METI oversight of Foods for Specified Health Uses enables probiotic and fiber-enriched positioning unavailable in conventional retail channels. Nagoya hosts specialized fermentation research facilities advancing dairy protein enrichment technologies.
United Kingdom
London's premium retail channels show fastest adoption of monk fruit-sweetened gelato formats as consumers prioritize ingredient transparency. The Food Standards Agency enforces strict compositional standards for reduced-sugar claims, aligning with EU-derived regulatory frameworks. Manchester and Birmingham concentrate health food store distribution where organic certification drives purchasing decisions.
France
Parisian consumers demonstrate strong price tolerance for clean-label frozen novelties featuring stevia and erythritol sweetener systems. ANSM and DGCCRF oversight of nutritional claims creates compliance complexity for cross-border product launches. Lyon anchors artisan gelato production with heritage dairy fermentation expertise adapted for reduced-calorie reformulation.
Low Calorie Desserts Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and cold-chain infrastructure. The market exhibits tiered concentration with multinational CPG conglomerates controlling mass retail distribution while specialized frozen novelty brands capture premium velocity through digital channels. Three archetypes dominate: dairy-centric fermentation specialists, global ice cream infrastructure operators, and digitally native ultra-low-calorie challengers. Competitive moves center on natural sweetener system licensing and direct-to-consumer cold-chain partnerships.
Within the dairy fermentation tier, Danone S.A. exemplifies European capability in probiotic refrigerated desserts, while Unilever PLC anchors global ice cream infrastructure with reformulation reach across multiple regional markets. Halo Top Creamery occupies the digitally native challenger position, building competitive identity on ultra-low-calorie premium frozen novelties.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Danone S.A. |
| Nestlé S.A. |
| Halo Top Creamery |
| Grupo Bimbo |
| Unilever PLC |
| PepsiCo Inc. |
| Mondelez International Inc. |
| General Mills Inc. |
| Others |
Supply & Pricing Matrix
Erythritol spot price volatility originating from Chinese fermentation facilities cascades through formulation tiers, compressing margins on clean-label frozen novelties while forcing tiered pricing separation between stevia-standardized premium lines and monk fruit-positioned ultra-premium assortments.
Pricing Analysis
Input-cost pass-through from concentrated erythritol supply in Chinese manufacturing feeds margin compression across mid-tier frozen dessert portfolios. Three-tier pricing structure across premium, standard, and economy levels separates organic-certified gelato from conventional reduced-calorie novelties and private-label economy tubs. Pricing pressure stems from fermentation capacity bottlenecks as brands accelerate natural sweetener reformulation. Mass-market supermarket buyers exhibit highest price sensitivity, while health food store channels tolerate sourcing premiums for transparent ingredient decks.
Supply Chain Analysis
Regional distribution centers in Chicago, Rotterdam, and Singapore anchor hub-and-spoke cold-chain networks for frozen novelty fulfillment. Manufacturing concentrates in the United States, Germany, and Japan where dairy fermentation infrastructure and regulatory expertise cluster. Raw material dependencies include stevia leaf extracts from Paraguay and Brazil, erythritol from Chinese corn fermentation, and monk fruit from Guangxi province. Single-source vulnerability in high-purity erythritol supply creates disruption risk for premium clean-label lines. Distribution runs through temperature-controlled logistics partnerships with frozen food specialists and direct-to-consumer cold-chain platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between FDA-regulated US formulation standards and EFSA's stricter health claims authorization creates cost-advantaged positioning for brands with dual-certification capabilities, enabling premium pricing in European channels while maintaining US volume scale.
For Market Incumbents: Deepen captive stevia glycoside sourcing through backward integration into South American extraction partnerships, defending margin position against emerging precision-fermentation sweetener challengers. Accelerate in-house fermentation R&D capacity in Nagoya or Lyon to reduce reliance on external formulation talent pools. Lock long-term cold-chain distribution contracts with regional logistics specialists before e-commerce infrastructure consolidation raises slotting costs.
For New Entrants and Emerging Players: Begin with direct-to-frozen subscription models targeting coastal US urban clusters where influencer-driven trial bypasses conventional supermarket gatekeeping. Exploit white-space in FOSHU-certified functional desserts for Japanese aging demographics, where regulatory pathways limit incumbent agility. Anchor initial positioning on single-origin organic certification to validate pricing premiums in natural channel retail.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier dairy fermenters possessing captive probiotic strain libraries and EU organic certification infrastructure. Long-term viability hinges on formulation IP moats rather than brand equity alone in a market recalibrating toward ingredient transparency. Watch EFSA authorization timelines for non-sugar sweetener health claims as the inflection signal for permissible marketing language expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Enables protein enrichment and sugar reduction simultaneously in refrigerated yogurt matrices. |
| Direct-to-Consumer Cold-Chain Partnership | Bypasses supermarket slotting fees while capturing premium margins in urban coastal markets. |
| Dual Certification Investment | Aligns FDA nutrition labeling with EU organic standards for cross-Atlantic product velocity. |
| Natural Sweetener Sourcing Integration | Reduces exposure to Chinese erythritol price volatility through captive stevia extraction. |
| FOSHU Regulatory Pathway Development | Unlocks functional positioning in Japanese aging segments with probiotic and fiber claims. |
Research Methodology
Bottom-up frozen dessert consumption modeling reconciled against top-down sweetener supply tracking forms the analytical core of this study. Primary interviews with category buyers at natural food retailers, formulation scientists at dairy ingredient suppliers, cold-chain logistics directors, and brand managers at digitally native frozen novelty companies combined with secondary validation from FDA GRAS notices, EFSA food additive opinions, USDA organic certification databases, and Nielsen retail audit data. Triangulation between demand-side consumption patterns and supply-side input cost structures ensures coherence across volume and value estimates.
Input-output matrix framing connects stevia and erythritol price indices to formulation cost structures across premium, standard, and economy product tiers. Segmentation dimensions modeled include product type, sweetener system, distribution channel, and packaging format alongside regional regulatory cluster variations. CAGRs derive from compounding annual growth assumptions anchored to urban millennial consumption velocity and natural sweetener adoption curves. Forecast inputs incorporate cold-chain infrastructure expansion rates and evolving WHO guidance on non-sugar sweeteners.
Several conditions sit outside the modeled scope, including abrupt regulatory reversals on permissible health claims, breakthrough synthetic sweetener approvals disrupting natural positioning, and climate-related crop failures in stevia or monk fruit cultivation regions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
North America Popping Boba/Juice Balls Market
Specialty Foods
Global Hispanic Foods Market
Specialty Foods
Low Fat and Low Carb Foods Market
Specialty Foods
Low Calorie Oatmeal Market
Specialty Foods
Almond-Based Spreads Market
Specialty Foods
Cat Food Toppings Market
Specialty Foods
Kelp Noodles Market
Specialty Foods
Cat Food Flavors Market
Specialty Foods
Asia-Pacific Alcohol-Infused Ice Cream Market
Specialty Foods
Vegan Salad Dressing Market
Specialty Foods
Middle East and Africa Yerba Mate Market
Specialty Foods
North American Jam, Jelly, and Preserve Market
Specialty Foods
Low Calorie Veggie Dip Market
Specialty Foods
Tahini Market
Specialty Foods
Triphala Powder Market
Specialty Foods
Coconut Butter Market