
 Natto Market | 2026-2036
Natto Market Size, Share, and Industry Trends Forecast 2026-2036
Natto Market Analysis
Japanese soybean processors is consolidating around traditional koji fermentation infrastructure to secure premium-grade natto supply. Ajinomoto Co. Inc leverages its amino acid research heritage to anchor high-purity nattokinase extraction for supplement channels. Mizkan Holdings sustains dominant retail shelf presence across East Asian supermarkets through controlled cold-chain logistics. Takanofoods Co. Ltd specializes in heritage strain preservation, competing on authenticity credentials rather than volume scale.
Natto denotes fermented whole soybeans inoculated with Bacillus subtilis var. natto, yielding a characteristic viscous polyglutamic acid matrix with nattokinase enzyme activity typically measured in fibrinolytic units per gram. The product serves cardiovascular wellness applications, probiotic gut health regimens, and umami-forward culinary preparations across institutional and household settings. Conventional natto retains volume leadership in Japanese domestic channels, while organic natto captures expanding margin pools in North American health food stores where consumers pay certification premiums. Frozen natto dominates export logistics, though diced natto grows fastest among meal-kit assemblers seeking portion-controlled ingredient formats.
Japan's Ministry of Health, Labour and Welfare enforces food sanitation law standards for fermented soy products, while the FDA classifies natto as a conventional food in the United States, creating divergent label claim boundaries for nattokinase marketing. The European Food Safety Authority evaluates novel food applications for non-traditional fermented soy strains, constraining import authorization timelines. Stakeholders must monitor evolving enzyme activity disclosure requirements and cold-chain integrity certifications as functional food regulators tighten substantiation standards.
Market Dynamics
Japan's Ministry of Health, Labour and Welfare maintains strict food sanitation standards that Japanese fermentation houses must navigate while scaling production for North American nattokinase supplement demand.
Growth Catalysts
- Cardiovascular wellness regimens:North American health enthusiasts seek nattokinase supplements for fibrinolytic enzyme activity, pulling demand from conventional soy processing channels into functional food retail.
- Probiotic gut health applications:Bacillus subtilis var. natto's viability through gastric transit attracts formulation interest from digestive wellness product developers.
- California's functional food retail corridor:Concentrated demand from Los Angeles and San Francisco health food stores creates premium pricing pools for organic-certified natto imports.
Market Restraints
- Soybean input cost volatility:Japanese domestic soybean production shortfalls force reliance on North American and Brazilian imports, exposing margins to commodity futures swings.
- Cold-chain infrastructure concentration:Frozen natto export viability depends on limited Japanese refrigerated port capacity, creating logistics bottlenecks during peak harvest windows.
- EFSA novel food authorization timelines:European import constraints for non-traditional fermented soy strains delay market entry for heritage strain variants.
Strategic Opportunities
- Meal-kit ingredient formats:Diced natto configurations address portion-control requirements among North American meal-kit assemblers seeking umami-forward components.
- US FDA conventional food classification:Regulatory clarity permits broader nattokinase label claims than Japanese pharmaceutical-grade restrictions allow.
- Heritage strain authentication:Traditional koji fermentation infrastructure supports premium positioning through controlled inoculum provenance documentation.
Industry Challenges
- Enzyme activity standardization:Fibrinolytic units per gram measurement protocols vary across testing laboratories, complicating quality assurance for supplement channel suppliers.
- Fermentation technician skill scarcity:Traditional Bacillus subtilis var. natto cultivation expertise concentrates among aging Japanese practitioners, constraining production scale replication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natto Market |
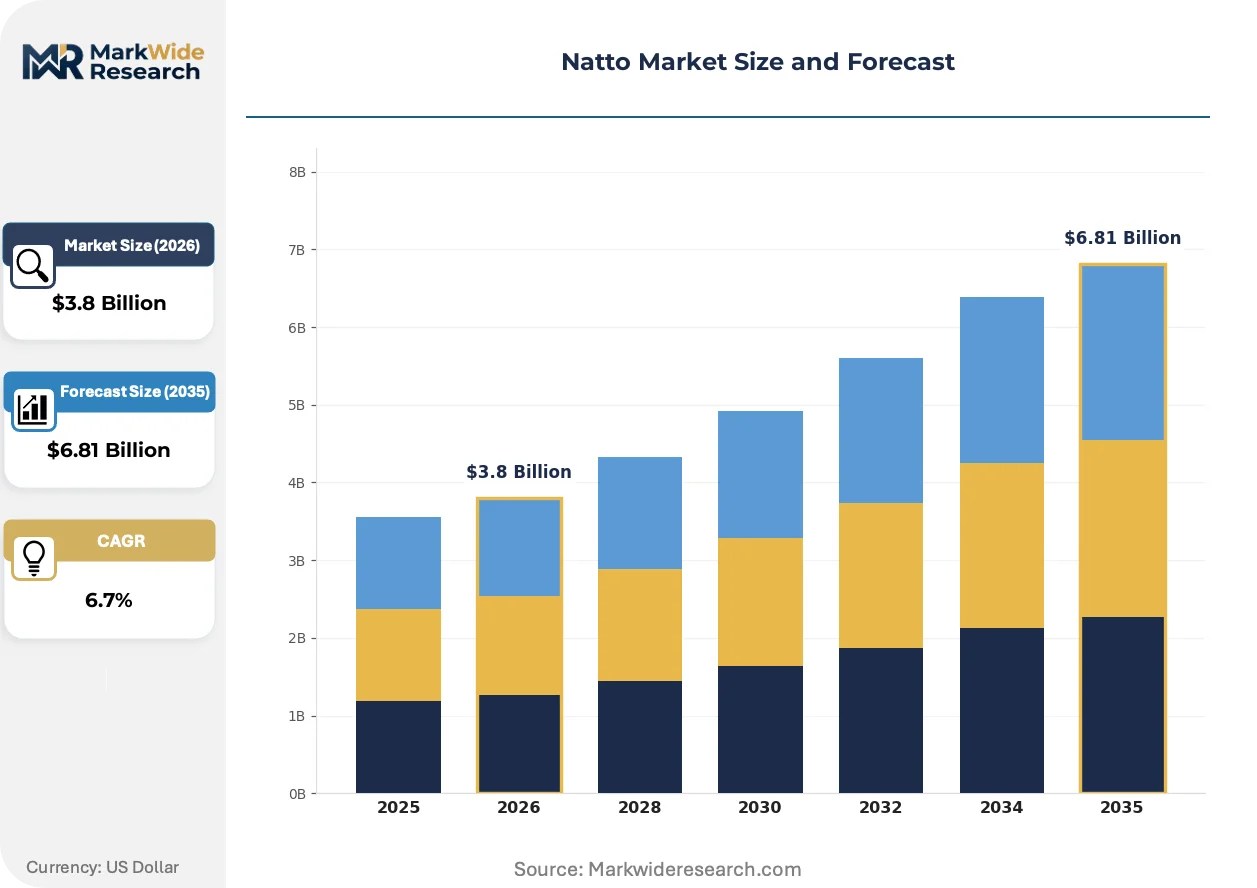
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Natto, Conventional Natto, Frozen Natto, Diced Natto Distribution Channel: Supermarkets, Online Retail, Health Food Stores, Local Markets End User: Households, Restaurants, Health Enthusiasts, Culinary Institutions Packaging Type: Single-Serve Packs, Bulk Packages, Glass Containers, Plastic Tubs |
| Companies Covered | Ajinomoto Co. Inc, MegumiNATTO Inc, Asahimatsu Foods Co. Ltd, CJ CheilJedang Corp, Shin Nihonmachi Co. Ltd, Mizkan Holdings, ASAICHIBAN Corp, Kikusui Food, Takanofoods Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natto Market Emerging Trajectories
Polyglutamic acid matrix stabilization techniques and enzyme preservation methods are reshaping how fermented soy products move from traditional consumption toward pharmaceutical-grade applications.
Freeze-dried nattokinase extraction technology is rewriting supply economics for cardiovascular supplement manufacturers. Pharmaceutical-grade enzyme processors in Osaka and Kyoto prefectures adopt lyophilization protocols that preserve fibrinolytic activity across 24-month shelf lives. This preservation advance compresses the cost gap between fresh-frozen natto and encapsulated supplement formats.
Japan's Ministry of Health, Labour and Welfare revised food additive standards for fermented soy polyglutamic acid in 2023, triggering reformulation across domestic natto processors. The regulatory adjustment permits higher viscosity thresholds in institutional foodservice channels. Hospital and school cafeteria suppliers now specify premium-grade products previously restricted to retail.
Direct-to-consumer subscription models displace conventional Asian supermarket distribution for North American buyers. California health food stores report declining shelf-turn rates as Seattle and Vancouver consumers shift toward monthly frozen deliveries. This channel rotation forces cold-chain logistics providers to reconfigure last-mile networks around residential freezer capacity rather than retail display cases.
Natto Market Segmentation
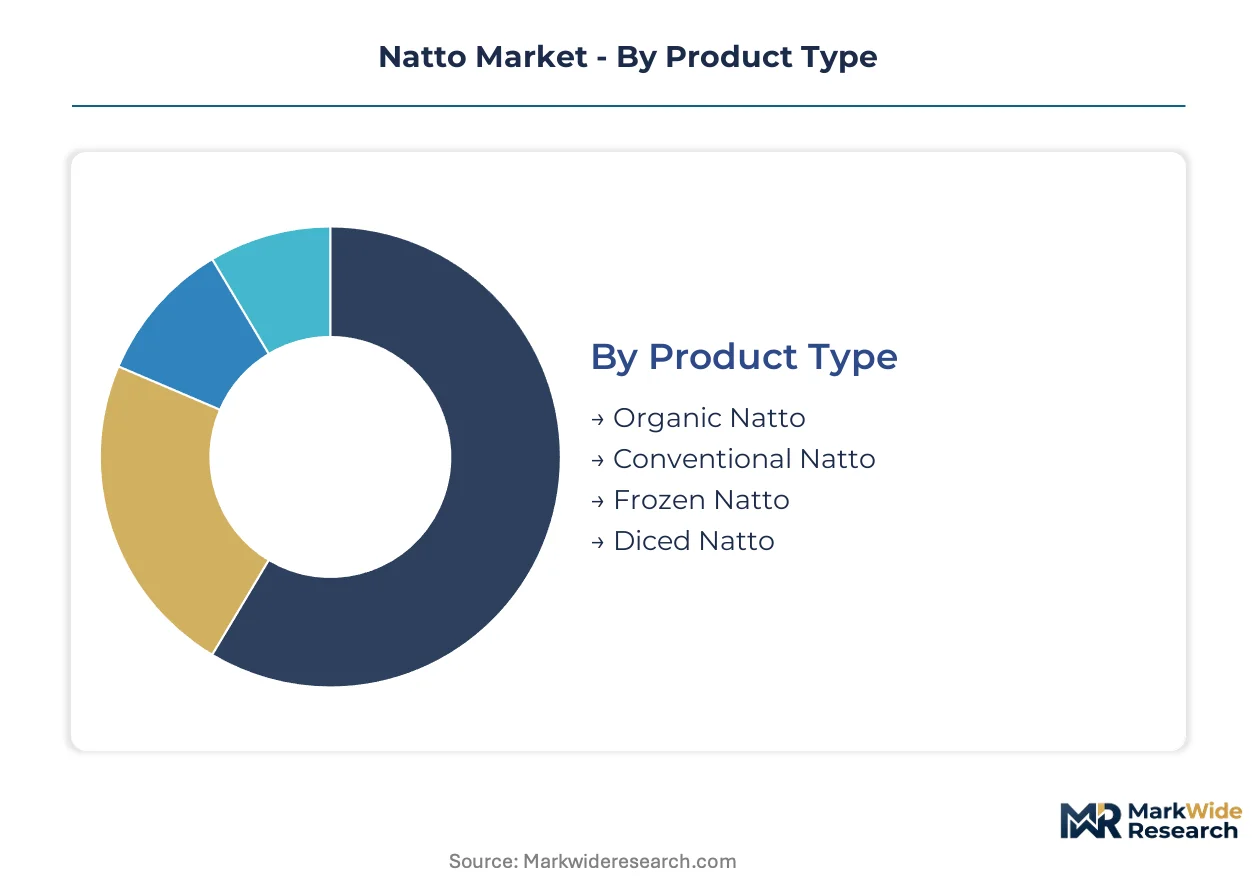
Natto's commercial landscape fractures along fermentation method, temperature stability, and consumer sophistication. Each segment carries distinct margin profiles and regulatory obligations that reshape competitive positioning across Japanese domestic and North American export channels.
Product Type:
Volume leadership sits with mass-market conventional formats, while organic and specialty frozen variants command premium pools in functional food retail.
- Conventional Natto:Whole fermented soybeans produced via industrial-scale Bacillus subtilis inoculation retain dominant share across Japanese household consumption. Institutional procurement in Tokyo and Osaka school cafeterias sustains baseline volume through standardized fibrinolytic activity specifications.
- Organic Natto:Certified non-GMO soybean fermentation targets California health food retail corridors where consumers pay substantiation premiums for nattokinase enzyme disclosure. Supply constraints from Japanese domestic organic soybean shortfalls limit scale replication.
- Frozen Natto:Cold-chain stabilization enables trans-Pacific export viability for Vancouver and Los Angeles Japanese supermarket networks. Refrigerated port capacity bottlenecks during peak harvest windows constrain expansion.
- Diced Natto:Portion-controlled formats serve North American meal-kit assemblers seeking umami-forward ingredient components with predictable portion economics.
Today's leader: Conventional Natto. Tomorrow's challenger: Organic Natto.
Distribution Channel:
Channel selection determines cold-chain investment intensity and nattokinase label claim permissibility under divergent national food law frameworks.
- Supermarkets:East Asian grocery chains in San Francisco and Los Angeles maintain dedicated freezer sections for heritage brand placement. Shelf-turn velocity depends on visible polyglutamic acid viscosity demonstration packaging.
- Online Retail:Direct-to-consumer subscription models displace conventional retail for Seattle and Vancouver buyers seeking monthly frozen deliveries with residential last-mile logistics.
- Health Food Stores:California functional food retail concentrates demand for organic-certified imports with enzyme activity laboratory documentation.
- Local Markets:Traditional Japanese morning markets sustain fresh natto consumption with same-day fermentation-to-sale cycles in rural prefectures.
Supermarkets anchor current volume. Online Retail is gaining share fastest.
End User:
User sophistication spans culinary traditionalists seeking umami depth to supplement-focused consumers prioritizing cardiovascular wellness substantiation.
- Households:Japanese domestic breakfast consumption sustains baseline demand for conventional sticky-texture preparations with rice pairings.
- Restaurants:Ramen and izakaya concepts in New York and Toronto incorporate natto as premium umami-forward topping for differentiated menu positioning.
- Health Enthusiasts:North American nattokinase supplement seekers drive organic import growth through fibrinolytic enzyme activity verification requirements.
- Culinary Institutions:Cooking schools and fermentation workshops specify heritage strain variants for authenticity credentialing in educational programming.
Households dominate current consumption. Health Enthusiasts show steepest expansion trajectory.
Packaging Type:
Packaging engineering directly impacts polyglutamic acid matrix preservation and enzyme activity degradation curves across distribution timelines.
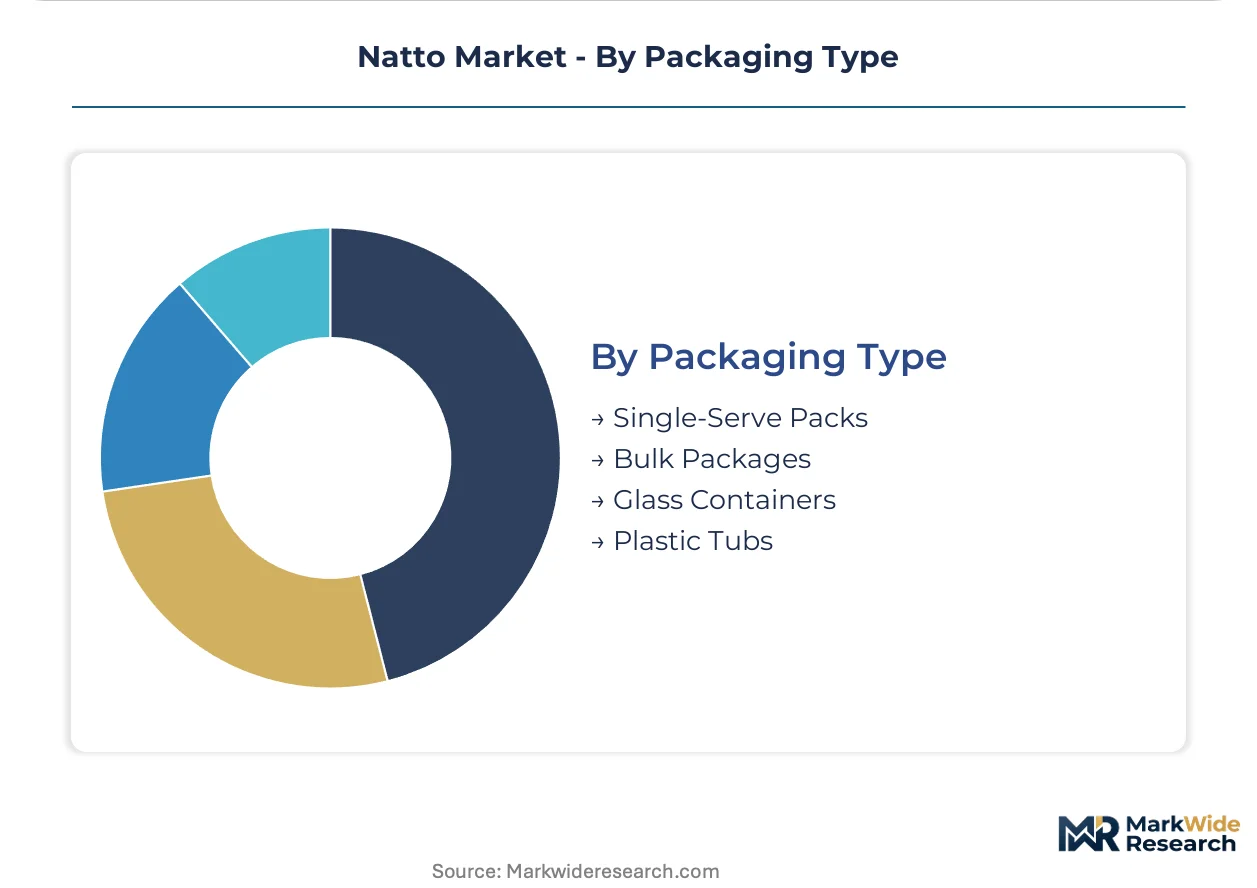
- Single-Serve Packs:Individual portion films with modified atmosphere sealing dominate Japanese convenience store channels. Portion control reduces waste in aging-demographic households.
- Bulk Packages:Foodservice-scale containers serve restaurant and institutional procurement with cost-per-gram optimization for high-volume operators.
- Glass Containers:Premium positioning in organic retail channels leverages perceived purity associations despite higher shipping weight penalties.
- Plastic Tubs:Standard retail format balances visibility, stackability, and cold-chain thermal mass for supermarket freezer display cases.
Plastic Tubs hold current volume leadership. Single-Serve Packs are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions with functional food classification clarity, creating arbitrage between Japan's pharmaceutical-grade restrictions and the United States' conventional food designation. Compliance cost differentials reshape where fermentation capacity expands versus where finished goods achieve premium pricing.
Japan
Domestic breakfast consumption sustains baseline volume for conventional sticky-texture preparations across Tokyo and Osaka metropolitan areas. The Ministry of Health, Labour and Welfare enforces strict food sanitation law standards that constrain nattokinase label claims to pharmaceutical-grade specifications. Kanto and Kansai industrial corridors concentrate heritage strain preservation expertise among aging fermentation practitioners.
United States
California health food retail corridors in Los Angeles and San Francisco drive organic-certified import demand with enzyme activity verification requirements. The FDA classifies natto as a conventional food, permitting broader nattokinase marketing claims than Japanese regulators allow. Seattle and Vancouver consumers accelerate direct-to-consumer subscription adoption, forcing cold-chain logistics reconfiguration around residential freezer capacity.
South Korea
Seoul Capital Area health enthusiasts seek cardiovascular wellness applications with documented fibrinolytic enzyme activity. The Ministry of Food and Drug Safety maintains novel food evaluation pathways for non-traditional fermented soy strains entering commercial channels. Busan-Ulsan port infrastructure supports refrigerated export consolidation for North American-bound frozen shipments.
Canada
Toronto and Vancouver Japanese supermarket networks sustain dedicated freezer sections for heritage brand placement with visible polyglutamic acid viscosity demonstrations. Health Canada evaluates fermented soy products under natural health product regulations, creating distinct authorization timelines from US conventional food pathways. British Columbia's Pacific coast logistics clusters handle trans-Pacific cold-chain distribution for meal-kit ingredient formats.
Germany
Berlin and Munich functional food retailers pilot organic natto placement among cardiovascular wellness product assortments. EFSA novel food authorization timelines constrain heritage strain variant market entry, delaying expansion for traditional koji fermentation products. Bavaria-based supplement distributors navigate enzyme activity standardization gaps across competing testing laboratory protocols.
Natto Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade extraction and meal-kit ingredient configurations. The market structure concentrates around Japanese fermentation houses with decades of Bacillus subtilis cultivation expertise, while Korean and North American processors compete on scale and format innovation. Two strategic archetypes dominate: heritage strain preservation specialists competing on authenticity credentials, and amino acid research heritage players anchoring high-purity enzyme extraction. Capacity expansion and direct-to-consumer channel development represent the dominant competitive moves across tier boundaries.
Within the heritage preservation archetype, Takanofoods Co. Ltd and Asahimatsu Foods Co. Ltd exemplify traditional koji fermentation infrastructure positioning. Ajinomoto Co. Inc occupies a distinct tier through amino acid research heritage that anchors pharmaceutical-grade nattokinase extraction capabilities. Mizkan Holdings represents the scale-driven retail presence vector with sustained supermarket shelf dominance. These three anchors illustrate how competitive positioning fragments across authenticity credentials, research heritage, and distribution scale rather than consolidating around unified capability sets.
| Leading Market Players |
|---|
| Ajinomoto Co. Inc |
| MegumiNATTO Inc |
| Asahimatsu Foods Co. Ltd |
| CJ CheilJedang Corp |
| Shin Nihonmachi Co. Ltd |
| Mizkan Holdings |
| ASAICHIBAN Corp |
| Kikusui Food |
| Takanofoods Co. Ltd |
| Others |
Supply Flow & Price Mechanics
Family-owned fermentation houses in Japan's Kanto and Kansai corridors anchor supply discipline through generational strain stewardship, translating heritage scarcity into premium-tier pricing power while constraining volume-scale discounting.
Pricing Analysis
Retailer markup layers in California health food corridors separate organic-certified imports from conventional frozen formats, with three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on nattokinase enzyme activity documentation and JAS organic certification grade. Pricing pressure stems from Brazilian and North American soybean input cost volatility squeezing processor margins. Health enthusiasts seeking cardiovascular wellness substantiation show lowest price sensitivity, while institutional foodservice procurement in Japanese school cafeterias operates at highest elasticity.
Supply Chain Analysis
Japan's Ministry of Health, Labour and Welfare food sanitation standards function as de facto domestic-content mandates, compelling heritage strain preservation within national borders. Geographic supply concentration centers on Japan, South Korea, and select North American contract fermentation facilities. Raw material dependencies draw from Brazilian non-GMO soybeans, Japanese domestic organic soybean shortfalls, and Bacillus subtilis var. natto culture banks. Single-source vulnerability concentrates in aging fermentation practitioner expertise. Distribution runs through refrigerated port infrastructure at Yokohama and Busan-Ulsan, with last-mile cold-chain reconfiguring around direct-to-consumer residential freezer capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natto's late-cycle quality story crystallizes around North American health enthusiasts paying certification premiums for nattokinase enzyme disclosure, displacing conventional soy processing channels.
For Market Incumbents: Lock in heritage strain authentication protocols through controlled inoculum provenance documentation, defending against Korean scale players and North American meal-kit format innovators. Deepen backward integration into Japanese domestic organic soybean cultivation to secure input supply against Brazilian futures volatility. Prioritize certification investment in JAS organic and nattokinase activity laboratory standards.
For New Entrants and Emerging Players: FDA conventional food classification in the United States opens a window for broader nattokinase label claims than Japanese pharmaceutical-grade restrictions permit. Target diced natto configurations for North American meal-kit assemblers seeking portion-controlled umami components. Pursue direct-to-consumer subscription go-to-market models with residential cold-chain logistics partnerships.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale fermentation houses with underutilized koji infrastructure and untapped export licensing. Long-term viability frames around 5-10 year cardiovascular wellness demand persistence and probiotic gut health regimen expansion. Target acquisition archetype: Japanese heritage strain preservation specialists with documented Bacillus subtilis cultivation expertise. Watch EFSA novel food authorization timeline acceleration as inflection signal for European market entry viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Strain Authentication Program | Controlled inoculum provenance documentation secures premium positioning against Korean scale competitors. |
| Freeze-Dried Nattokinase Extraction Scale-Up | Lyophilization protocol adoption by Osaka and Kyoto processors compresses fresh-frozen to supplement cost gaps. |
| Direct-to-Consumer Cold-Chain Reconfiguration | Residential freezer capacity logistics displace California health food store shelf-turn dependence. |
| Organic Certification Investment | JAS organic standards unlock California functional food retail corridor premium pricing pools. |
| Meal-Kit Ingredient Format Development | Diced natto configurations address portion-control requirements among North American assemblers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation house technical directors, California health food store category buyers, Japanese Ministry of Health regulatory affairs specialists, and cold-chain logistics operators with secondary validation. Secondary sources encompassed FDA food classification rulings, EFSA novel food submission databases, Japanese customs export records, and California Department of Public Health food safety filings. Bottom-up volume modeling and top-down value triangulation cross-validated segment outputs.
Segment-weighting approaches distributed value across fermentation method, temperature stability format, and distribution channel dimensions throughout the forecast period. CAGRs derived from elasticity-adjusted demand curves incorporating nattokinase supplement channel growth trajectories and organic certification penetration rates. Industry-specific inputs included fibrinolytic unit measurement protocol standardization progress and refrigerated port capacity expansion timelines.
Revisions become necessary when EFSA novel food authorization timelines accelerate, Japanese fermentation practitioner retirement waves intensify, or North American soybean input cost volatility exceeds historical bands. Forecasts reflect documented assumptions around cold-chain integrity maintenance and enzyme activity preservation technology adoption. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Miso Market
Specialty Foods
Europe Halal Food and Beverage Market
Specialty Foods
Jams, Jellies & Preserves Market
Specialty Foods
Halal Products Market
Specialty Foods
Coconut Butter Market
Specialty Foods
Europe Gluten-Free Breakfast Cereals Market
Specialty Foods
Fruit Dessert Market
Specialty Foods
Keto Low-Calorie Meals Market
Specialty Foods
Global Hispanic Foods Market
Specialty Foods
Asia-Pacific Tofu Market
Specialty Foods
Cultures Market
Specialty Foods
Dong Quai Market
Specialty Foods
Vegan Dressing Market
Specialty Foods
Poke Food Market
Specialty Foods
Europe Hummus Market
Specialty Foods
North America Popping Boba/Juice Balls Market