
 Asia Pacific Vegetable Oil Market | 2026-2036
Asia Pacific Vegetable Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Vegetable Oil Market Outlook
Palm oil is recalibrating product economics across the Asia Pacific edible oils complex as refiners substitute partially hydrogenated alternatives with higher-olein fractions to meet trans-fat reduction targets. Wilmar International Ltd leverages its integrated crushing-refining-logistics network across Indonesia and Malaysia to sustain margin capture from plantation to port. COFCO Group anchors Chinese soybean oil supply through its state-backed origination and crushing capacity along coastal processing corridors.
Asia Pacific vegetable oil encompasses triglyceride extracts derived from oilseed and palm fruit feedstocks, typically refined to free fatty acid levels below 0.05 percent and color specifications under 3.0 Red for food-grade applications, serving as primary lipid inputs for frying, baking, and oleochemical synthesis. Palm oil occupies the dominant volume position across the region due to Indonesian and Malaysian production scale, while biofuels application represents the fastest-expanding demand segment as Indonesia mandates B35 blending and Malaysia advances B20 programs. Refined form commands the premium margin pool relative to crude shipments, reflecting energy-intensive degumming, bleaching, and deodorization steps that remove phospholipids and oxidation precursors.
Indonesia's Ministry of Energy and Mineral Resources enforces biodiesel blending mandates that redirect palm oil flows from food channels into fuel, while Malaysia's Malaysian Sustainable Palm Oil certification scheme shapes export access for European and Indian buyers demanding deforestation-free supply chains. China's SAMR implements national food safety standards for vegetable oil labeling and contaminant limits that constrain small refiner participation. Stakeholders must monitor blending mandate adjustments and sustainability certification proliferation as these mechanisms increasingly determine which origins and product forms retain market access across the region's major consuming economies.
Market Dynamics
Indonesia's B35 biodiesel mandate is diverting palm oil volumes from food processing channels into fuel blending, compressing edible oil availability across Southeast Asian refineries and forcing price recalibration throughout the downstream supply chain.
Growth Catalysts
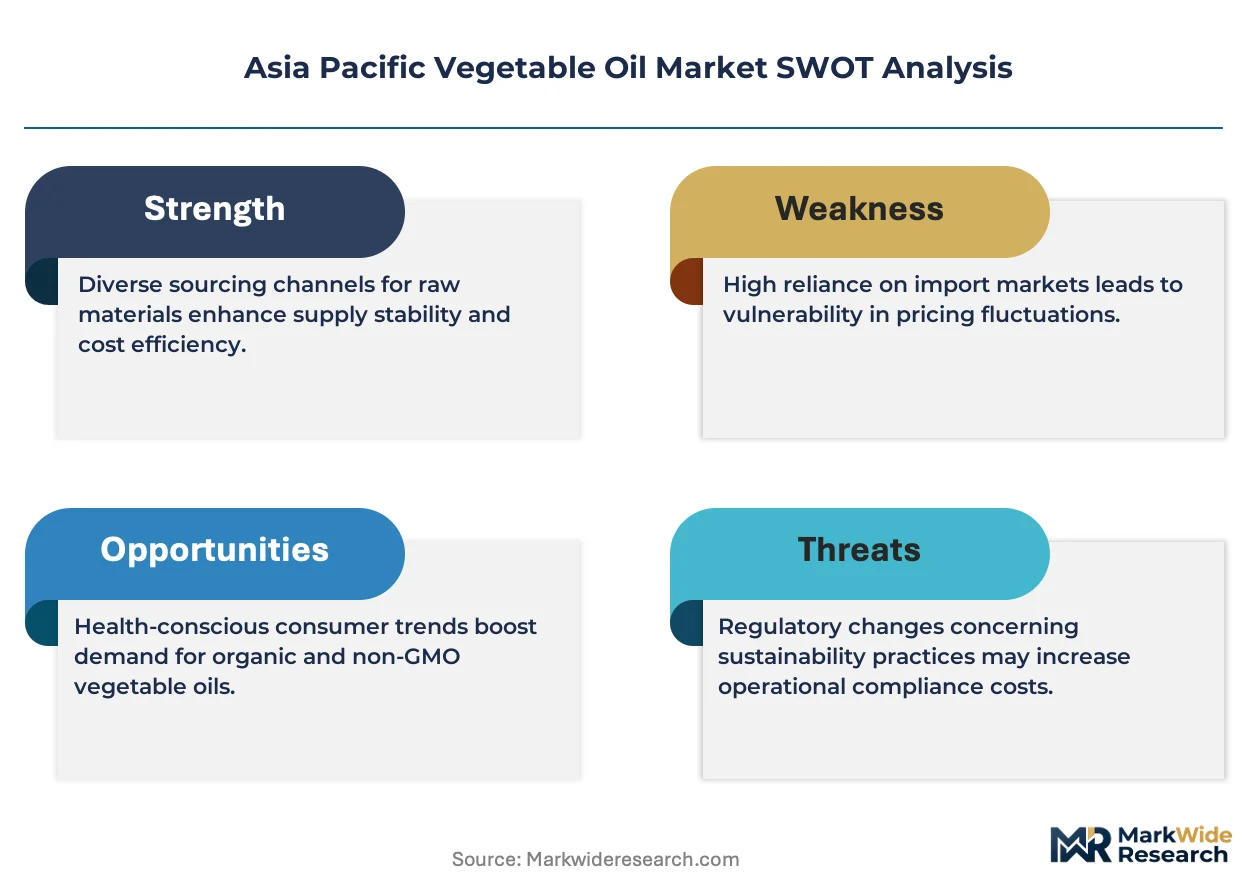
- FSSAI fortification mandates:India's mandatory vitamin A and D enrichment in edible oils is accelerating refinery upgrade cycles and creating premium product tiers for health-conscious urban consumers.
- High-olein palm fractions:Trans-fat reduction targets across ASEAN food processors are substituting partially hydrogenated oils with naturally stable olein variants, expanding specialty refining margins.
- Malaysian Sustainable Palm Oil certification:European and Indian buyers demanding deforestation-free supply chains are channeling procurement toward certified origins, reshaping export market access requirements.
Market Restraints
- Crude palm oil price volatility:Weather-driven production swings in Indonesian and Malaysian estates transmit directly into refinery feedstock costs, compressing margin predictability for downstream processors.
- Supply concentration risk:Over two-thirds of global palm oil originates from Indonesian and Malaysian plantation complexes, creating systemic vulnerability to El Niño drought cycles and export policy shifts.
- Technical limitation in cold-weather performance:Palm oil's high saturated fat content crystallizes below 20°C, restricting bakery and margarine applications in temperate Asian markets without expensive fractionation investment.
Strategic Opportunities
- Vietnam's underpenetrated retail sector:Modern trade expansion in Ho Chi Minh City and Hanoi corridors is creating branded packaged oil penetration potential as traditional wet market share erodes.
- Aviation biofuel offtake agreements:Singapore's sustainable aviation fuel mandates are opening long-term contracting windows for hydrotreated palm oil derivatives from Indonesian refiners.
- Blockchain-IoT traceability convergence:Integrated plantation-to-port tracking systems are enabling premium pricing for verified deforestation-free supply chains into European and Australian markets.
Industry Challenges
- Deodorization engineer scarcity:Refinery expansion across Indonesia and Malaysia is outstripping the pool of experienced process engineers capable of optimizing thermal bleaching and vacuum stripping operations.
- MSPO/RSPO certification timeline compression:Smallholder aggregation requirements and audit backlogs are delaying market access for mid-tier Malaysian processors seeking European retail contracts.
- Legacy refinery integration complexity:Retrofitting 1990s-era Malaysian facilities for high-olein fractionation requires simultaneous hydrogenation unit decommissioning and crystallization train installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Vegetable Oil Market |
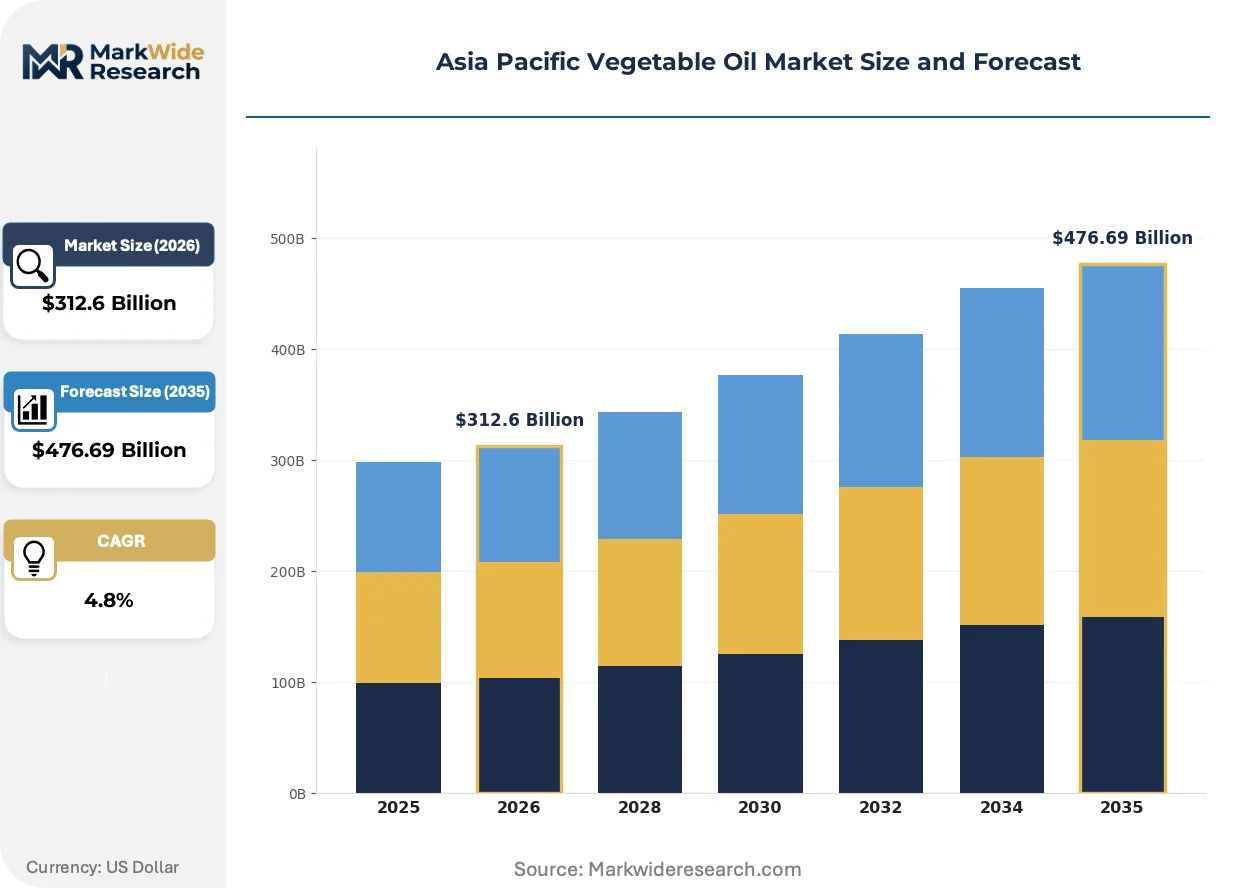
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $476.69 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soybean Oil, Palm Oil, Sunflower Oil, Canola Oil Application: Food Processing, Biofuels, Cosmetics, Industrial Form: Refined, Crude, Organic, Blended End User: Restaurants, Households, Bakeries, Food Manufacturers |
| Companies Covered | Wilmar International Ltd, COFCO Group, Musim Mas Holdings, Golden Agri-Resources Ltd, Fuji Oil Holdings Inc, Sime Darby Plantation, Adani Group, Cargill Inc, Archer Daniels Midland Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Vegetable Oil Market Strategic Shifts
Processing technology and certification protocols are converging to reshape competitive advantage across the Asia Pacific edible oils complex, with sustainability verification and functional ingredient specialization emerging as primary differentiation vectors.
Enzymatic interesterification is electrifying fat structuring capabilities for bakery and confectionery applications by enabling precise triglyceride repositioning without trans-fat generation. Malaysian and Indonesian specialty refiners are installing immobilized lipase reactor systems at commercial scale. This enzymatic approach is electrifying product formulation flexibility while eliminating hydrogenation infrastructure capex for mid-tier processors seeking clean-label positioning.
China's SAMR national food safety standards for vegetable oil labeling and contaminant limits are tightening refinery compliance burdens, particularly for 3-MCPD ester and glycidyl ester thresholds in infant formula applications. Coastal processors in Guangdong and Shandong are accelerating deodorization temperature optimization and double-refining investments. The infant nutrition segment is absorbing the steepest cost pass-through as international brands demand third-party laboratory verification for every import batch.
Foodservice operators across Singapore, Thailand, and urban India are consolidating procurement through integrated distributor platforms that bundle oil supply with waste collection and filtration equipment leasing. Traditional commodity brokers are losing share to these full-service providers that guarantee consistent quality specifications and inventory financing. This channel consolidation is most visible in quick-service restaurant chains where central kitchen standardization mandates eliminate spot-market purchasing flexibility.
Asia Pacific Vegetable Oil Market Segmentation
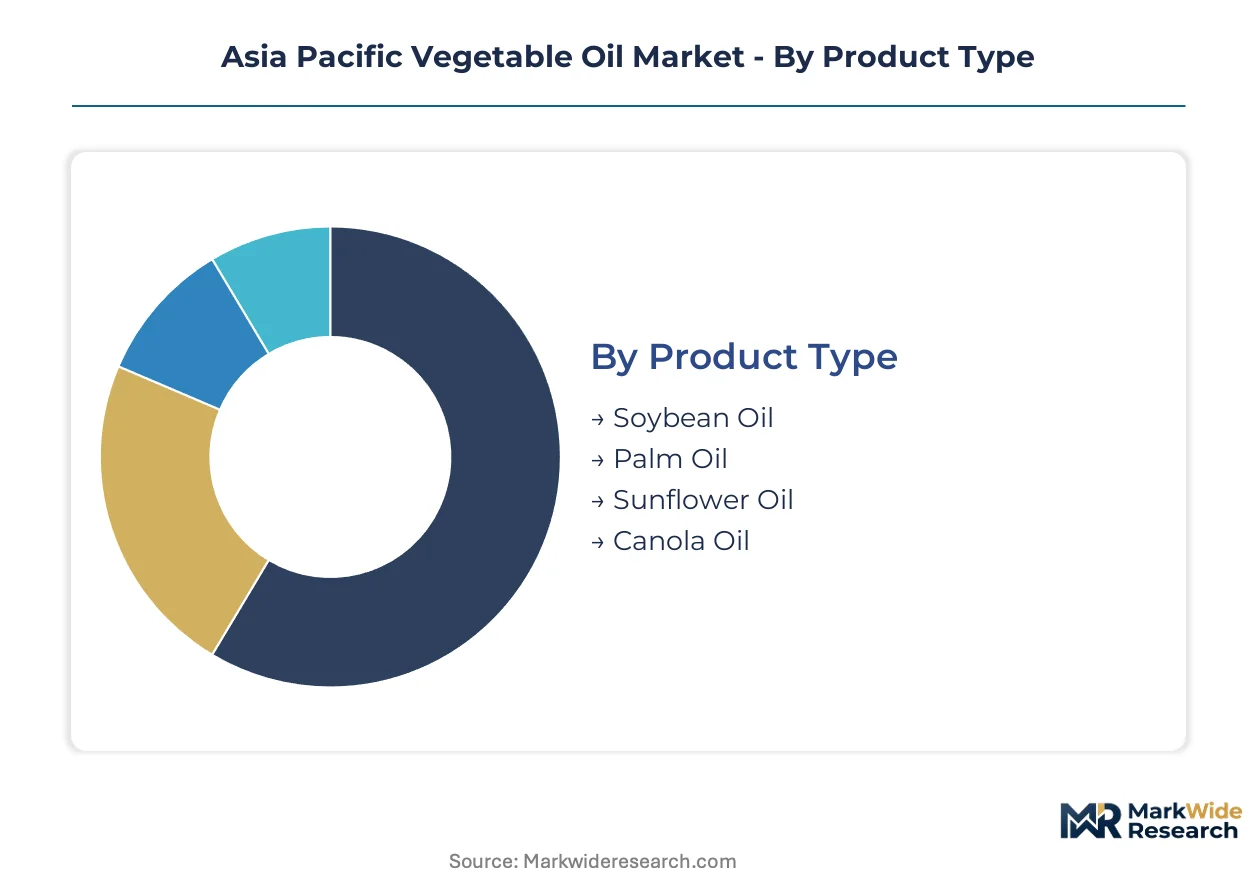
Segmentation in Asia Pacific vegetable oils reveals how supply chain configuration and end-use specifications fragment procurement strategies across the region. Refiners and traders must navigate divergent margin pools, certification requirements, and technical standards that vary sharply by product category and customer type.
Product Type:
Indonesian and Malaysian plantation complexes concentrate upstream supply, forcing downstream processors to align procurement with origin-specific sustainability protocols and fractionation capabilities.
- Palm Oil:Triglyceride extract from Elaeis guineensis fruit mesocarp, typically refined to free fatty acid levels below 0.05 percent and color specifications under 3.0 Red. Indonesian refiners serving B35 biodiesel mandates absorb plantation output that might otherwise enter food channels, tightening edible oil availability for Southeast Asian processors.
- Soybean Oil:Solvent-extracted or mechanically pressed oil from Glycine max seeds, characterized by linoleic acid content of 50-60 percent and natural antioxidant tocopherol levels. Chinese crushing capacity along coastal corridors in Shandong and Guangdong anchors regional supply, with COFCO Group's state-backed origination networks controlling import flows.
- Sunflower Oil:High-oleic variants from Helianthus annuus seeds deliver oxidative stability for extended frying cycles without hydrogenation.
- Canola Oil:Low-erucic acid rapeseed oil with favorable omega-3 to omega-6 ratios, primarily imported from Canadian origins for premium food processing applications in Japan and South Korea.
Palm oil absorbs the bulk of installed capacity; biodiesel application is expanding most quickly.
Application:
End-use economics diverge sharply between commodity food processing and specialized industrial channels, with biofuels mandates redirecting feedstock flows and reshaping refinery investment priorities.
- Food Processing:Refined oils for frying, baking, and margarine production meeting FSSAI fortification mandates in India and SAMR contaminant thresholds in China. ASEAN processors substitute high-olein palm fractions for partially hydrogenated alternatives to achieve trans-fat reduction targets without sacrificing oxidative stability.
- Biofuels:Fatty acid methyl esters and hydrotreated vegetable oils for diesel blending and aviation fuel. Indonesia's B35 mandate and Malaysia's B20 program divert palm oil volumes from food channels, compressing edible oil availability and forcing price recalibration throughout downstream supply chains.
- Cosmetics:Cosmetic-grade refined fractions with strict peroxide value and moisture specifications for emollient and surfactant applications.
- Industrial:Technical-grade oils for lubricant bases, metalworking fluids, and oleochemical feedstocks.
Food processing commands the dominant volume share; biofuels application is climbing the fastest.
Form:
Processing intensity determines margin capture, with energy-intensive refining steps creating tiered pricing structures that reward scale and technical capability.
- Refined:Degummed, bleached, and deodorized product meeting food-grade specifications with free fatty acid below 0.05 percent and moisture below 0.1 percent. Malaysian and Indonesian integrated refiners capture premium margins through plantation-to-port control, while smaller processors face deodorization engineer scarcity and certification backlogs.
- Crude:Unprocessed or minimally clarified oil retaining phospholipids, carotenoids, and oxidation precursors. Bulk shipments from Indonesian estates supply biodiesel plants and refineries with in-house fractionation capacity, trading at discounts that reflect downstream processing burden.
- Organic:Certified production excluding synthetic pesticides and fertilizers, commanding price premiums in European and Australian export markets.
- Blended:Custom-formulated mixtures combining palm olein with soft oils to achieve specific melting profiles and oxidative stability for bakery and confectionery applications.
Refined form absorbs the bulk of installed capacity; organic certification is gaining share fastest.
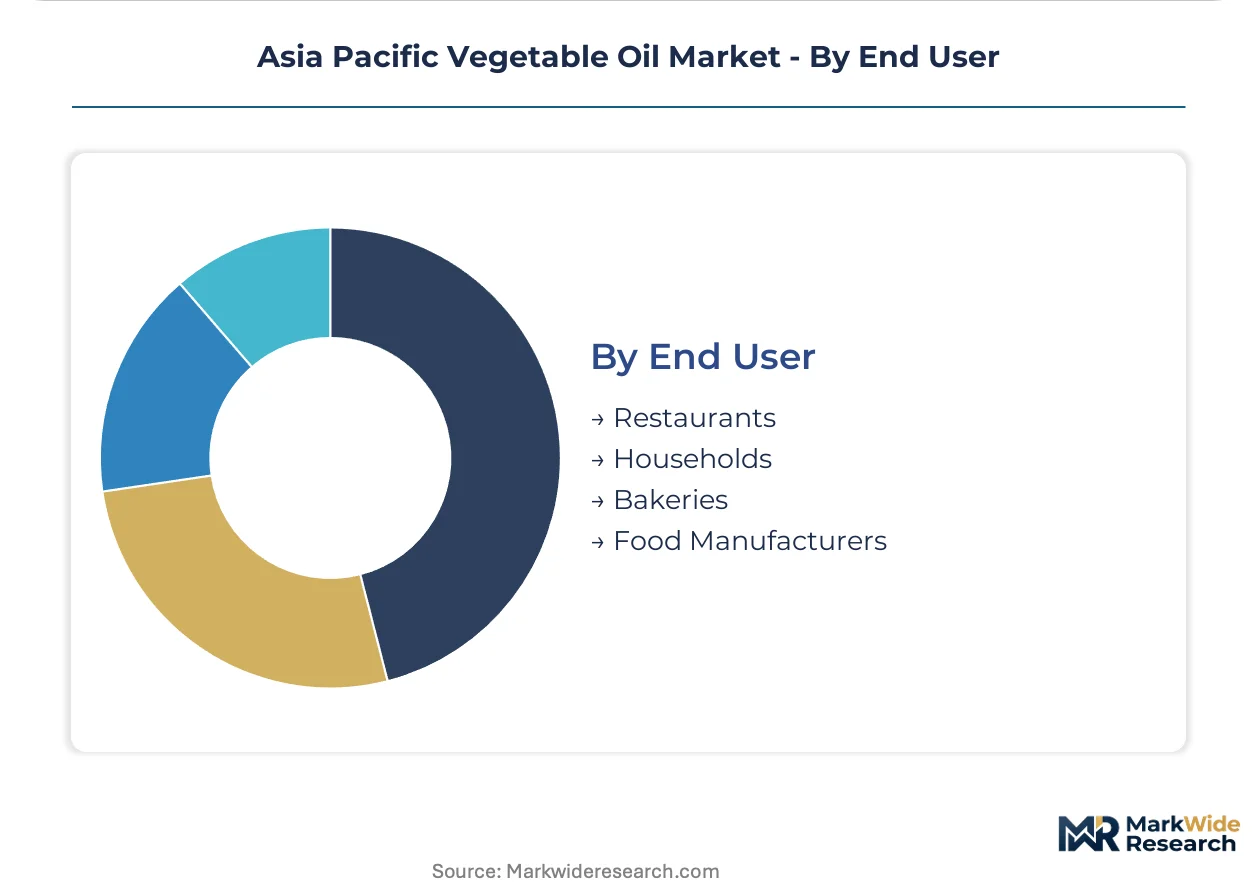
End User:
Channel consolidation and procurement centralization are reshaping how oils reach final consumers, with integrated platforms displacing traditional commodity brokers.
- Food Manufacturers:Industrial buyers with centralized procurement, strict specification requirements, and long-term contracting preferences. Quick-service restaurant chains in Singapore, Thailand, and urban India mandate central kitchen standardization that eliminates spot-market purchasing flexibility, favoring full-service distributors bundling supply with waste collection and filtration equipment leasing.
- Restaurants:Foodservice operators ranging from independent hawkers to chain outlets with varying volume and quality requirements. Modern trade expansion in Vietnam's Ho Chi Minh City and Hanoi corridors is creating branded packaged oil penetration potential as traditional wet market share erodes.
- Households:Retail consumers purchasing bottled oils through supermarkets, traditional trade, and e-commerce platforms.
- Bakeries:Specialized processors requiring specific melting profiles and oxidative stability for laminated doughs and cream fillings.
Food manufacturers absorb the bulk of installed capacity; restaurant channel consolidation is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia and Malaysia concentrate upstream palm oil supply while diverting growing volumes into biodiesel channels, tightening edible oil availability for food processors across Southeast Asian refineries.
Indonesia
B35 biodiesel mandates redirect plantation output from food manufacturing into fuel blending, compressing domestic edible oil stocks. The Ministry of Energy and Mineral Resources enforces blending quotas that reshape refinery investment priorities. Integrated crushing-refining complexes in Sumatra and Kalimantan serve both export biodiesel markets and domestic food processors.
Malaysia
Malaysian Sustainable Palm Oil certification requirements channel European and Indian procurement toward verified deforestation-free origins. The certification scheme shapes export access as buyers demand supply chain transparency. Peninsular Malaysian estates and Sabah processing clusters anchor production serving premium-tier export contracts.
China
Coastal crushing capacity in Shandong and Guangdong provinces anchors regional soybean oil supply through state-backed origination networks. SAMR national food safety standards tighten contaminant thresholds for 3-MCPD esters in infant formula applications. Yangtze River Delta refiners absorb steep compliance costs through double-refining investments and third-party laboratory verification.
India
FSSAI fortification mandates for vitamin A and D enrichment accelerate refinery upgrade cycles and create premium product tiers. Urban food manufacturers in Maharashtra and Gujarat consolidate procurement around health-positioned brands. The Delhi-NCR corridor concentrates distribution infrastructure serving quick-service restaurant chains with central kitchen standardization requirements.
Vietnam
Modern trade expansion in Ho Chi Minh City and Hanoi corridors erodes traditional wet market share, creating branded packaged oil penetration potential. Foodservice operators consolidate procurement through integrated distributor platforms bundling supply with filtration equipment leasing. Southern Vietnamese refiners face margin pressure from Indonesian biodiesel-driven feedstock competition.
Asia Pacific Vegetable Oil Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with plantation-integrated refiners commanding upstream margin capture while toll processors serve spot-market flexibility needs. The vendor base concentrates around Indonesian and Malaysian originators with crushing-refining-logistics networks, creating tiered access to sustainability-certified export channels. Three archetypes dominate: vertically integrated plantation-refiners, coastal toll processors with fractionation flexibility, and state-backed traders with origination control. Capacity expansion and certification compliance represent the dominant competitive moves as processors retrofit legacy facilities for high-olein production.
Among Singapore-headquartered integrated operators, Wilmar International Ltd exemplifies plantation-to-port control spanning Indonesian and Malaysian supply corridors. COFCO Group anchors Chinese soybean oil supply through state-backed coastal crushing networks. Musim Mas Holdings occupies a position within the Indonesian originator tier with integrated Sumatran complexes serving both biodiesel mandates and food-grade export specifications.
| Leading Market Players |
|---|
| Wilmar International Ltd |
| COFCO Group |
| Musim Mas Holdings |
| Golden Agri-Resources Ltd |
| Fuji Oil Holdings Inc |
| Sime Darby Plantation |
| Adani Group |
| Cargill Inc |
| Archer Daniels Midland Company |
| Others |
Value Chain & Pricing Dynamics
Backward integration into plantation assets anchors both supply security and pricing power for Indonesian and Malaysian refiners serving B35 biodiesel mandates and food-grade export contracts. This upstream control insulates integrated operators from feedstock volatility while compressing margins for toll processors dependent on spot crude palm oil purchases.
Pricing Analysis
Volume-mass crude shipments trade at discounts to refined products, while specialty high-olein fractions and certified-sustainable grades capture premium positioning. Price differentiation separates MSPO-certified origins from conventional supply, with European and Indian buyers absorbing sustainability premiums for deforestation-free verification. Pricing pressure stems from Indonesian biodiesel mandates diverting feedstock from food channels, tightening edible oil availability. Small refiners and toll processors exhibit highest price sensitivity due to deodorization engineer scarcity and certification audit backlogs.
Supply Chain Analysis
Deodorization engineer scarcity in Sumatran and Kalimantan processing clusters constrains refinery expansion timelines and fractionation capability buildout. Supply concentrates in Indonesian and Malaysian plantation corridors, with Chinese coastal crushing capacity anchoring soybean oil flows. Raw material dependencies include crude palm oil fruit bunches, imported soybeans, and specialized bleaching earths for contaminant removal. Single-source vulnerability to El Niño drought cycles threatens production continuity. Distribution runs through integrated plantation-to-port networks controlled by Wilmar International and Musim Mas Holdings, with spot-market toll processors serving flexible offtake needs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic interesterification systems are displacing legacy hydrogenation infrastructure across ASEAN specialty refineries, enabling trans-fat-free fat structuring without thermal processing. This technology transition rewards early movers with clean-label positioning and eliminates hydrogenation unit capex for mid-tier processors.
For Market Incumbents: Acquire immobilized lipase reactor capacity and crystallization train assets to defend fractionation margins against emerging enzymatic specialists. Secure MSPO certification ahead of European retail contract renewal cycles. Channel control through integrated distributor platforms bundling filtration equipment leasing absorbs foodservice procurement consolidation in Singapore and urban India.
For New Entrants and Emerging Players: The premium-to-economy price gap in Vietnam's branded packaged oil segment offers white-space penetration as modern trade expansion erodes wet market share. Target Ho Chi Minh City and Hanoi corridor retail consolidation through direct-store-distribution partnerships with emerging supermarket chains. Aviation biofuel offtake agreements from Singapore's sustainable aviation fuel mandates provide long-term contracting visibility for hydrotreated palm oil derivatives.
For Investors and Strategic Acquirers: Exit pathways concentrate in plantation-integrated refiners with MSPO certification and established European retail relationships, commanding valuation premiums over toll processors. Mid-tier Malaysian processors with audit backlogs and smallholder aggregation gaps represent distressed acquisition targets. Watch Indonesian biodiesel blending mandate adjustments as the primary inflection signal for feedstock availability and refinery margin direction.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Assets | Captive crude palm oil supply insulates Indonesian refiners from El Niño-driven feedstock volatility. |
| MSPO Certification Investment | European and Indian retail contracts increasingly require Malaysian Sustainable Palm Oil verification for market access. |
| Enzymatic Interesterification Deployment | Immobilized lipase systems enable trans-fat-free bakery applications without hydrogenation infrastructure. |
| Integrated Distributor Platform Expansion | Full-service providers bundling oil supply with filtration equipment leasing capture foodservice procurement consolidation. |
| Aviation Biofuel Offtake Agreements | Singapore's sustainable aviation fuel mandates open long-term contracting for hydrotreated palm oil derivatives. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Asia Pacific vegetable oil analysis. Primary interviews with refinery operations directors, plantation sustainability officers, FSSAI compliance consultants, and food manufacturer procurement leads combined with secondary validation from Indonesian Ministry of Energy biodiesel mandate disclosures, Malaysian Palm Oil Board production statistics, and SAMR food safety standard publications. Bottom-up volume modeling across product type, application, form, and end-user segments triangulated against top-down trade flow assessments.
Granularity-level modeling captured palm oil, soybean oil, sunflower oil, and canola oil at the product-type dimension; food processing, biofuels, cosmetics, and industrial at the application dimension; refined, crude, organic, and blended at the form dimension; and food manufacturers, restaurants, households, and bakeries at the end-user dimension. CAGRs across the analysis window derived from regression-based projection of feedstock availability, blending mandate trajectories, and certification adoption curves. Forecast inputs incorporated El Niño cycle probability, FSSAI fortification compliance cost pass-through, and MSPO audit completion rates.
Underlying measurement precision varies by segment; biodiesel application volumes carry tighter precision than organic certification flows given policy mandate visibility. Forecasts reflect assumptions on Indonesian B35 enforcement continuity, Malaysian MSPO audit capacity expansion, and Chinese soybean import tariff stability. Material deviation in biodiesel blending mandate adjustments, El Niño severity, or European deforestation regulation implementation timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Fats and Oils Market
Ingredients
Middle-East and Africa Vegetable Oil Market
Ingredients
Global Pulse Flours Market
Ingredients
Europe Vanilla Beans and Extract Market
Ingredients
USA Yeast Extracts Market
Ingredients
Yeast Peptide Market
Ingredients
Cocoa Derivatives Market
Ingredients
Biotech Ingredients Market
Ingredients
Homecare Ingredients Market
Ingredients
South America Fermented Ingredients Market
Ingredients
Global Gelatin Market
Ingredients
Heart Health Ingredients Market
Ingredients
Salad Oil Market
Ingredients
Volatile Fatty Acids Market
Ingredients
Millet Protein Market
Ingredients
Cooking Coconut Milk Market