
 Global Milk Replacers Market | 2026-2036
Global Milk Replacers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Milk Replacers Market Outlook
The Netherlands is reshaping European milk replacer production capacity through expanded spray-drying facilities and whey protein concentration infrastructure. Nutreco Holding NV leverages integrated premix-to-replacer formulations across multiple livestock species. Cargill Incorporated sustains global supply chain density through backward integration into dairy protein streams. CHS Inc. anchors North American farm cooperative distribution with direct-to-producer milk replacer programs.
Milk replacers are formulated nutritional substitutes composed of dairy-derived proteins, vegetable fats, vitamins, and minerals designed to mimic the compositional profile of whole milk for neonatal animals unable to nurse. Spray-drying and fat encapsulation processes determine solubility, digestibility, and shelf stability in commercial formulations. Powdered formulations dominate volume due to lower logistics costs and extended storage windows, while liquid concentrates capture margin pools in veterinary care applications where dosing precision commands premium positioning. Calves represent the largest end-user segment structurally, though pet-grade milk replacers are expanding fastest through specialty store and online channels.
USDA grading standards and FDA feed ingredient regulations govern protein claims and antibiotic inclusion in American milk replacer products, while EU REACH and EFSA frameworks restrict certain preservative chemistries and mandate detailed labeling across member states. China's NMPA and GB standards impose additional registration barriers for imported milk replacer formulations entering Asian markets. Stakeholders must monitor evolving veterinary prescription requirements and protein origin traceability mandates as these rules increasingly determine market access and product differentiation.
Market Dynamics
Spray-drying capacity concentration in the Netherlands and Wisconsin is compressing protein sourcing radii for milk replacer manufacturers, forcing feed compounders to secure whey permeate streams through multi-year tolling agreements rather than spot markets.
Growth Catalysts
- EU Farm to Fork Strategy:Protein origin traceability mandates under the Green Deal are accelerating certified supply chain investments among Dutch and German feed processors.
- Precision fermentation:Alternative protein streams from microbial biomass are reducing reliance on volatile whey powder markets for calf nutrition formulations.
- Integrated dairy cooperatives:Large-scale operators in the United States are consolidating calf-rearing units and standardizing milk replacer procurement across multi-state footprints.
Market Restraints
- Whey protein price volatility:Cheese production cycles in the European Union and New Zealand directly destabilize raw material costs for spray-dried formulations.
- Single-source spray-dryer dependence:Three facility clusters in the Netherlands handle over half of European milk replacer powder output, creating geographic concentration risk.
- Antibiotic residue thresholds:FDA Veterinary Feed Directive restrictions and EU EFSA maximum residue limits constrain medicated replacer formulation flexibility.
Strategic Opportunities
- Brazilian beef calf sectors:Underpenetrated pasture-based rearing systems in Mato Grosso and Goiás present volume expansion potential for imported milk replacer concentrates.
- Pet specialty retail channels:Premium-positioned puppy and kitten milk replacers are capturing margin pools through veterinary clinic and direct-to-consumer e-commerce routes.
- China NMPA registration harmonization:Streamlined GB standard alignment for imported dairy-derived feed ingredients is reducing market entry barriers for European and North American suppliers.
Industry Challenges
- Spray-drying engineering talent scarcity:Specialized knowledge in fat encapsulation and powder flow optimization is concentrating among retiring technicians at Dutch and Irish processing facilities.
- Legacy ERP integration:Batch traceability systems required for EU digital product passports are forcing mid-sized compounders to replace decades-old manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Milk Replacers Market |
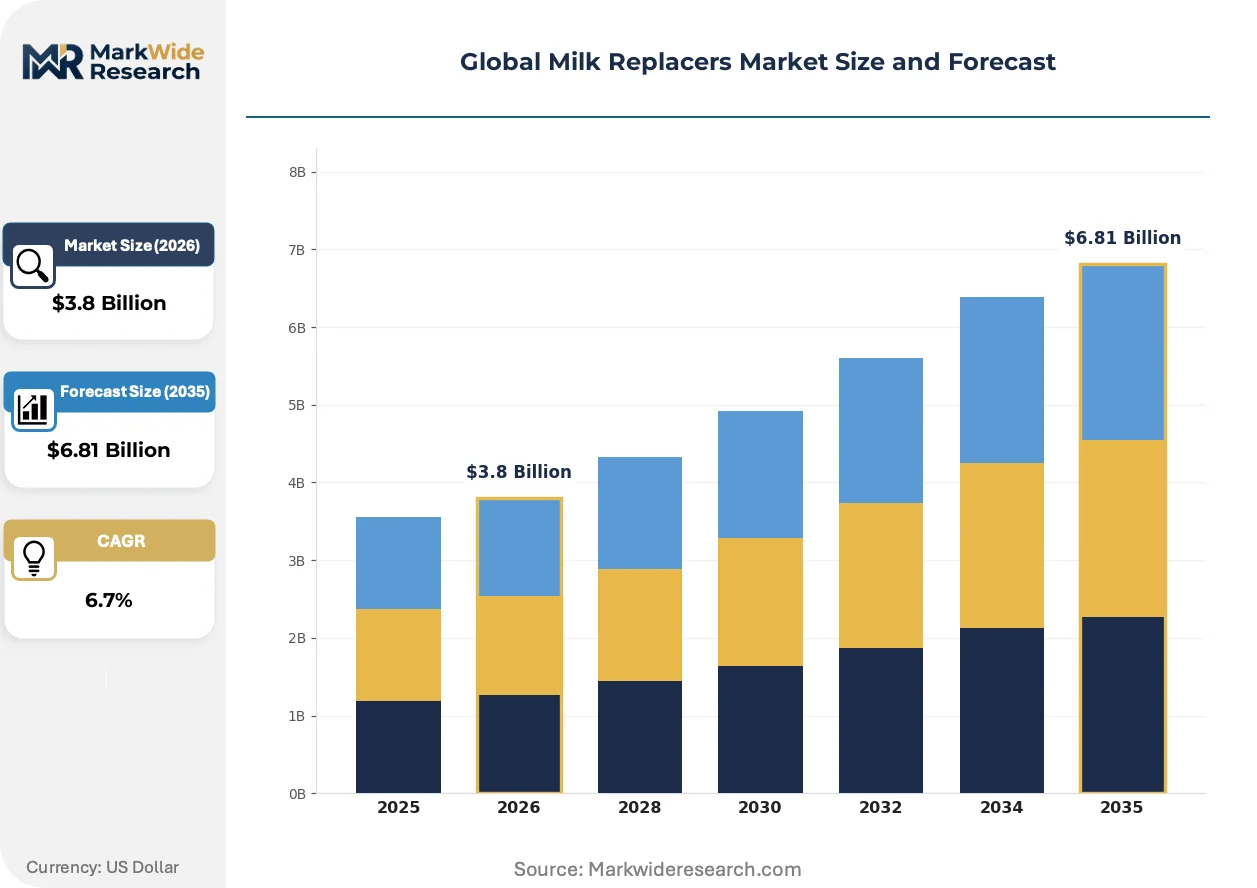
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered, Liquid, Concentrated, Ready-to-Feed End User: Infants, Calves, Kids, Pets Distribution Channel: Online, Supermarkets, Specialty Stores, Farm Supply Stores Application: Livestock Nutrition, Veterinary Care, Research, Emergency Feeding |
| Companies Covered | Nutreco Holding NV, Alltech Inc, Cargill Incorporated, Lactalis Group, Glanbia plc, Archer Daniels Midland Company, CHS Inc., BEWITAL agri GmbH & Co KG, Land O'Lakes Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Milk Replacers Market Strategic Shifts
Fat encapsulation chemistry and protein fractionation methods are converging to extend shelf stability while reducing mixing temperatures, reshaping formulation economics for both powdered and liquid concentrate segments.
Micro-encapsulated lipid systems using hydrogenated vegetable oil shells are replacing traditional spray-dried fat globules in premium calf milk replacers. Large-scale feedlot operators in the Texas Panhandle and California Central Valley are adopting these formulations to reduce clumping during automated feeding system deployment. The technology is hybridizing powder and liquid concentrate categories by enabling ambient-stable concentrates with powder-like logistics economics.
China's NMPA revised GB 13078 feed hygiene standards are mandating expanded mycotoxin testing panels for imported milk replacer ingredients. European exporters to Asian markets are restructuring supply chains to include third-party certified pre-shipment analysis at Rotterdam and Hamburg port facilities. Small-to-mid scale compounders lacking in-house testing infrastructure are ceding share to integrated multinationals with captive laboratory networks.
Veterinary clinics and specialty pet retailers are displacing traditional agricultural supply distributors for high-margin neonatal nutrition products. Puppy milk replacer buyers in France, Japan, and the United States are purchasing through subscription-based direct channels that bundle nutritional consultation with recurring delivery. This channel rotation is most pronounced in urban veterinary markets where dosing precision and brand trust override price sensitivity.
Global Milk Replacers Market Segmentation
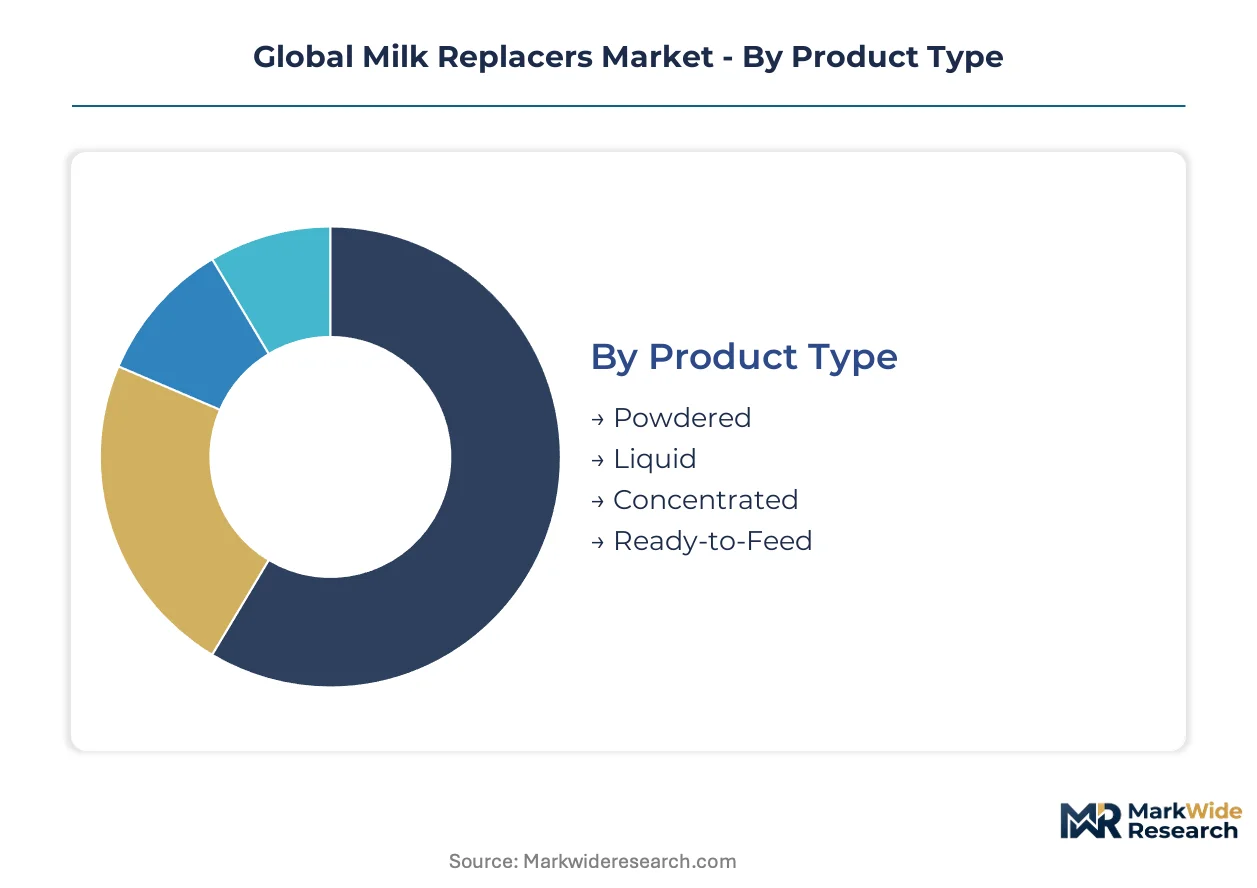
Milk replacer formulations diverge sharply across species physiology and distribution economics. Powdered products dominate bulk livestock procurement while liquid concentrates capture precision-dosing veterinary markets. Channel strategy separates commodity feedlot supply from premium pet nutrition retail.
Product Type:
Mature spray-drying infrastructure anchors the powdered segment while liquid innovations reshape dosing precision and shelf stability.
- Powdered:Spray-dried dairy proteins and encapsulated vegetable fats deliver extended storage windows and lower logistics costs. Texas Panhandle feedlot operators and Wisconsin dairy cooperatives drive bulk procurement of automated-feeder-compatible formulations. Powdered retains volume leadership; liquid holds the steepest expansion curve.
- Liquid:Pre-mixed emulsions eliminate reconstitution steps for neonatal veterinary emergencies and small-scale operations. French veterinary clinics and Japanese specialty pet retailers favor these for dosing accuracy in orphan puppy and kitten protocols.
- Concentrated:Reduced-water formulations bridge powder economics with liquid convenience for mid-scale calf-rearing units in Mato Grosso pasture systems.
- Ready-to-Feed:Sterile packaged complete nutrition targets research laboratories and emergency wildlife rehabilitation centers requiring zero preparation protocols.
Powdered formulations retain volume leadership; liquid concentrates hold the steepest expansion curve through veterinary and pet specialty channels.
End User:
Species-specific digestive physiology drives formulation divergence in protein fractionation and fat encapsulation chemistry.
- Calves:Ruminant-optimized casein-to-whey ratios and rumen bypass fat technologies dominate commercial volume. Large-scale operators in California Central Valley and Dutch integrated cooperatives standardize procurement across multi-state footprints. Calves retain volume leadership; pets hold the steepest expansion curve.
- Pets:Puppy and kitten milk replacers command premium positioning through veterinary clinic and direct-to-consumer subscription channels in France, Japan, and urban United States markets.
- Infants:Human-grade formulations face distinct regulatory pathways through FDA infant formula oversight and EFSA novel food assessments, separating this from livestock nutrition supply chains.
- Kids:Goat-specific lactose profiles and smaller batch scales serve niche smallholder operations in Alpine regions and emerging pasture systems.
Calves retain volume leadership; pets hold the steepest expansion curve through premium channel migration.
Distribution Channel:
Channel economics separate commodity bulk procurement from high-margin precision retail with divergent service requirements.
- Farm Supply Stores:Cooperative-affiliated distribution anchors North American bulk calf nutrition procurement with direct-to-producer programs. CHS Inc. and regional cooperative networks dominate this channel across Midwest dairy corridors. Farm supply retains volume leadership; online holds the steepest expansion curve.
- Online:Subscription-based direct channels bundle nutritional consultation with recurring delivery for urban veterinary markets and specialty pet owners.
- Specialty Stores:Premium-positioned neonatal nutrition products with brand trust and dosing precision credentials target discerning puppy and kitten buyers.
- Supermarkets:Limited shelf space constraints relegate milk replacers to seasonal orphan lamb and emergency pet care SKUs in rural retail footprints.
Farm supply stores retain volume leadership; online channels hold the steepest expansion curve through subscription model adoption.
Application:
Application scope spans commercial livestock productivity through specialized emergency and research protocols with distinct formulation standards.
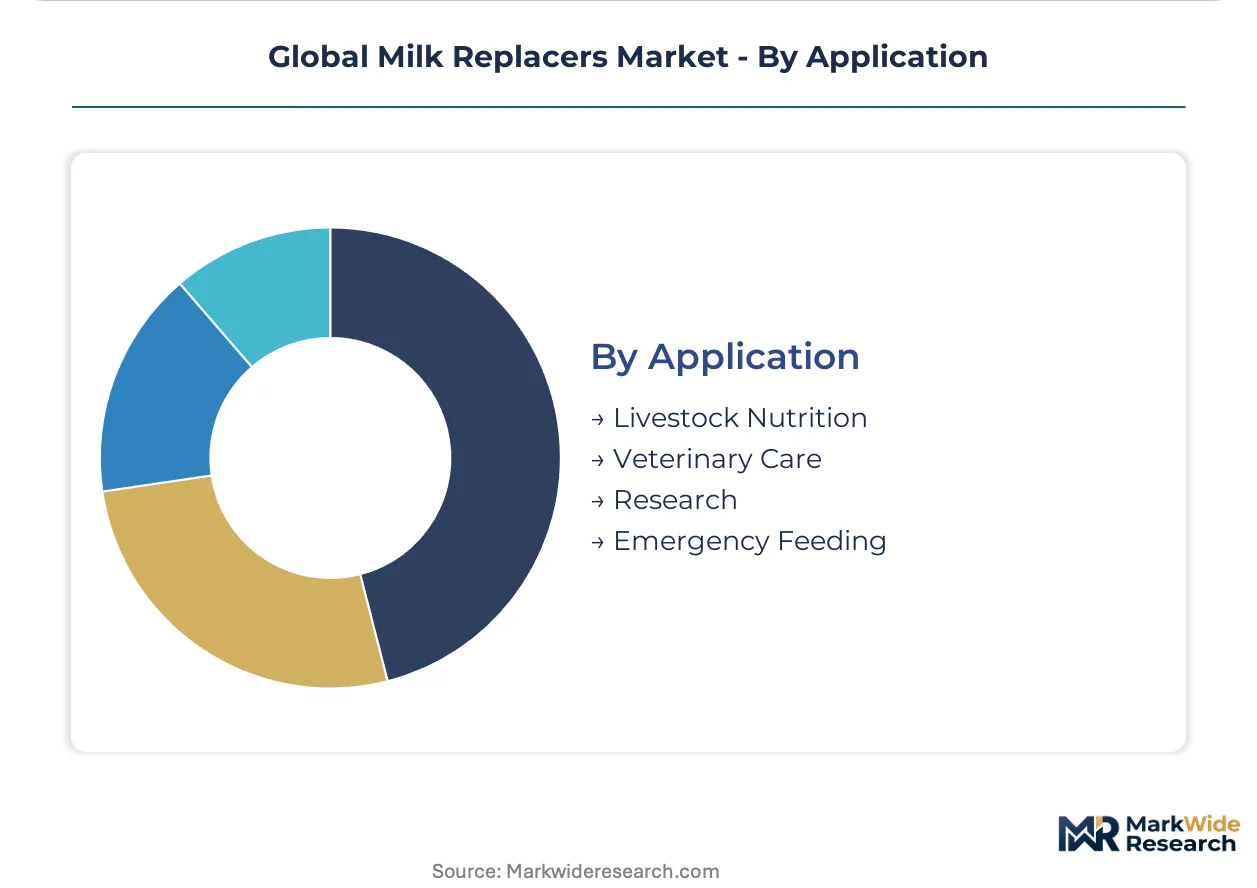
- Livestock Nutrition:Standardized calf-rearing formulations prioritize feed conversion ratios and weaning stress reduction in commercial dairy and beef operations. EU Farm to Fork protein traceability mandates are restructuring certified supply chain investments among Dutch and German feed processors. Livestock nutrition retains volume leadership; veterinary care holds the steepest expansion curve.
- Veterinary Care:Precision-dosed orphan neonatal protocols and critical care support command premium positioning through clinic-based dispensing.
- Research:Controlled-nutrition studies in academic and pharmaceutical settings require batch-consistent, contaminant-tested formulations with full documentation chains.
- Emergency Feeding:Wildlife rehabilitation and disaster response stockpiles demand extended-shelf-life formulations with rapid deployment logistics.
Livestock nutrition retains volume leadership; veterinary care holds the steepest expansion curve through precision-dosing premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam's deep-water port infrastructure and integrated cold-chain corridors underwrite the Netherlands' dominance in European milk replacer powder exports, with direct rail links to German compounders and French calf-rearing regions.
United States
Wisconsin dairy cooperatives and Texas Panhandle feedlot operators drive bulk procurement of automated-feeder-compatible formulations. FDA Veterinary Feed Directive restrictions constrain medicated replacer flexibility while USDA grading standards govern protein claims. California Central Valley integrated operators standardize calf-rearing protocols across multi-state footprints.
Netherlands
Dutch spray-drying clusters handle over half of European milk replacer powder output, compressing protein sourcing radii for compounders. EU Farm to Fork Strategy traceability mandates accelerate certified supply chain investments among Rotterdam and Zwolle processors. Eindhoven Region premix-to-replacer integration exemplifies vertical coordination across livestock species.
Germany
Bavarian and Lower Saxon feed processors secure whey permeate streams through multi-year tolling agreements rather than volatile spot markets. EFSA maximum residue limits and REACH framework restrictions shape preservative chemistry selections. Hamburg port facilities now host third-party certified pre-shipment mycotoxin testing for Asian export consignments.
China
NMPA revised GB 13078 feed hygiene standards mandate expanded mycotoxin testing panels for imported milk replacer ingredients. Yangtze River Delta dairy operations and northern pasture systems present volume expansion potential for European suppliers. Shanghai and Tianjin customs checkpoints enforce dual registration barriers for dairy-derived feed ingredients.
Brazil
Mato Grosso and Goiás pasture-based beef calf rearing systems remain underpenetrated by imported milk replacer concentrates. ANVISA veterinary product registration pathways differ from feed-grade approval channels, complicating market entry. São Paulo-based distributors increasingly bridge technical specification gaps between European exporters and regional cooperatives.
Global Milk Replacers Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in protein fractionation and fat encapsulation chemistry. The market structures around three tiers: multinational nutrition conglomerates with captive dairy protein streams, regional compounders dependent on tolling agreements, and niche veterinary formulation houses. Dominant competitive moves include backward integration into whey processing assets and strategic partnerships with automated feeding equipment manufacturers.
Among Dutch-anchored nutrition platforms, Nutreco Holding NV exemplifies integrated premix-to-replacer coordination across species. Cargill Incorporated represents the scale-driven archetype with global supply chain density through upstream dairy protein control. CHS Inc. anchors North American cooperative distribution with direct-to-producer program structures. These three occupy positions spanning formulation depth, geographic breadth, and channel penetration respectively.
| Leading Market Players |
|---|
| Nutreco Holding NV |
| Alltech Inc |
| Cargill Incorporated |
| Lactalis Group |
| Glanbia plc |
| Archer Daniels Midland Company |
| CHS Inc. |
| BEWITAL agri GmbH & Co KG |
| Land O'Lakes Inc |
| Others |
Value Chain & Pricing Dynamics
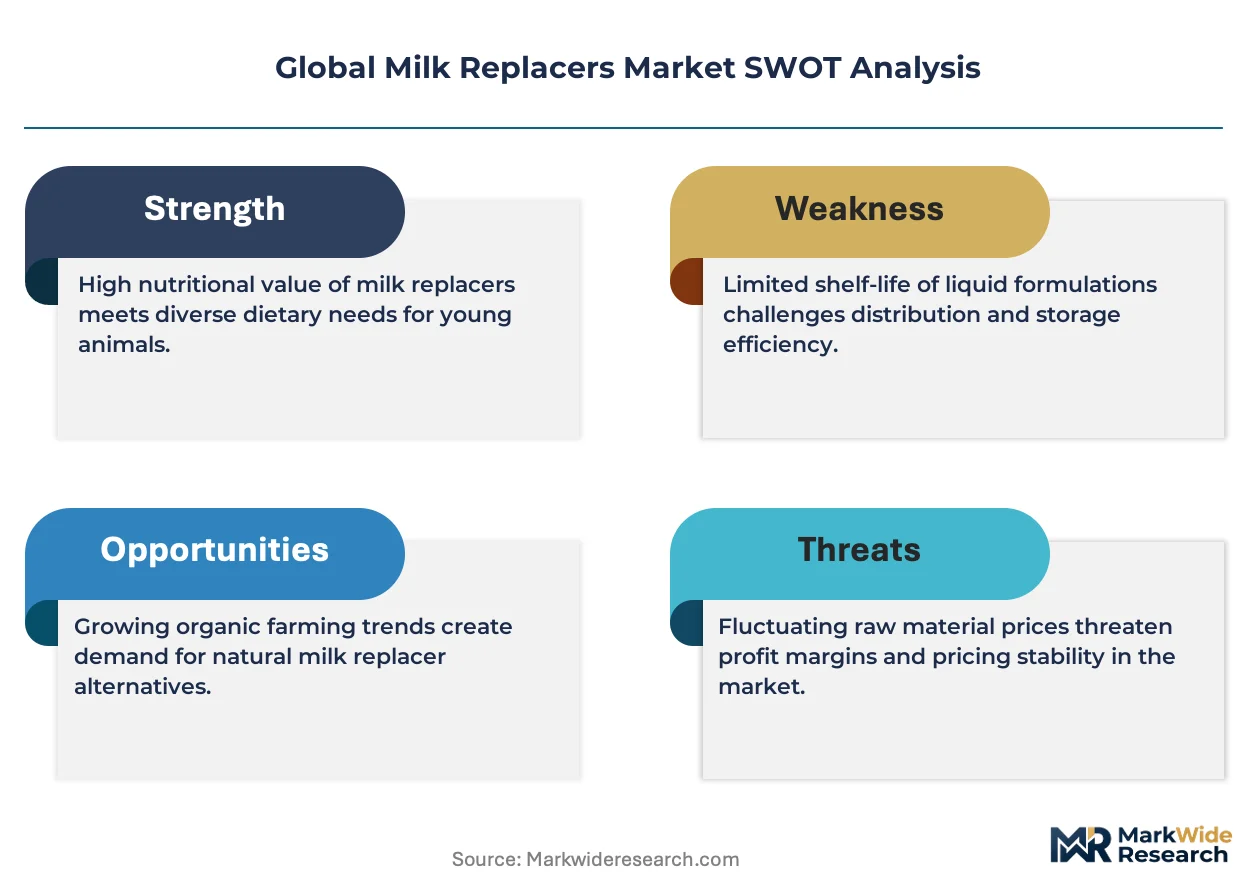
Underutilized spray-drying capacity in the Netherlands and Wisconsin is compressing tolling margins and forcing compounders toward multi-year protein sourcing contracts that lock in pricing predictability. This utilization dynamic rewards integrated operators with captive whey streams while squeezing spot-market-dependent compounders into defensive procurement postures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by formulation complexity and certification grade. Premium micro-encapsulated lipid systems command position through automated-feeder compatibility and extended ambient stability, while economy powdered formulations compete on logistics efficiency for bulk calf-rearing operations. Cost compression in standard-tier products is intensifying because whey protein price volatility from European and New Zealand cheese production cycles transmits directly into formulation economics. Large-scale feedlot operators exhibit lowest price sensitivity due to standardized procurement protocols, whereas small-to-mid scale compounders face acute margin pressure from testing infrastructure investments mandated by EU digital product passports.
Supply Chain Analysis
EU REACH framework restrictions on preservative chemistries and China's NMPA GB 13078 feed hygiene standards are reshaping cross-border ingredient flows through pre-shipment certification requirements. Manufacturing concentrates in the Netherlands, Germany, and the United States, with Dutch spray-drying clusters handling over half of European milk replacer powder output. Raw material flows draw from whey permeate streams, vegetable fat encapsulation inputs, and vitamin premix concentrates. Single-source spray-dryer dependence creates geographic concentration risk for European compounders. Distribution runs through cooperative-affiliated farm supply networks in North America and veterinary clinic channels in premium pet nutrition markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The milk replacers market is recovering from whey protein price cyclicality as cheese production normalizes and precision fermentation alternatives mature. This cyclical recovery favors operators with integrated protein streams over tolling-dependent compounders.
For Market Incumbents: Insulate formulation margins through backward integration into whey processing assets in Wisconsin and Dutch dairy corridors. Secure multi-year tolling agreements before capacity utilization tightens. Channel control through direct-to-producer programs at CHS Inc. and cooperative networks defends position against subscription-based pet nutrition entrants eroding veterinary clinic relationships.
For New Entrants and Emerging Players: Build out Brazilian beef calf operations in Mato Grosso and Goiás pasture systems where imported milk replacer concentrates remain underpenetrated. Target pet specialty retail channels in France and Japan through direct-to-consumer subscription models bundling nutritional consultation. Precision-dosing liquid concentrate formulations offer the most penetrable entry point against incumbent powdered volume dominance.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among veterinary clinic dispensing networks and subscription-based pet nutrition platforms. Long-term viability over a multi-year horizon rests on traceability-certified supply chains compliant with EU Farm to Fork mandates. Acquisition targets should demonstrate captive laboratory networks for mycotoxin testing and NMPA registration capabilities. Watch spray-drying engineering talent scarcity at Dutch and Irish facilities as an inflection indicator for operational risk premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Whey Processing | Cargill Incorporated and Nutreco Holding NV secure captive protein streams against volatile spot markets. |
| Precision Fermentation Partnership | Alternative protein streams from microbial biomass reduce formulation exposure to cheese production cycles. |
| Automated Feeder Equipment Alliance | Texas Panhandle operators standardize procurement through equipment-formulation bundling. |
| NMPA Registration Harmonization | Streamlined GB standard alignment reduces dual registration barriers for European suppliers entering China. |
| Subscription Channel Development | French and Japanese veterinary clinics capture recurring revenue through orphan neonatal nutrition protocols. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with spray-drying facility operators, veterinary nutritionists, cooperative procurement managers, and premix formulation chemists; and secondary validation through EU EFSA residue limit databases, USDA grading standard filings, FDA Veterinary Feed Directive guidance documents, and China NMPA GB standard registrations. Bottom-up volume triangulation across powdered, liquid, and concentrate formulations was cross-checked against top-down protein stream consumption estimates from whey processing trade data.
Forecast inputs across the analysis window incorporated species-specific formulation divergence, channel migration from farm supply to online subscription models, and regulatory pathway complexity across FDA, EFSA, and NMPA jurisdictions. Segmentation dimensions modeled include product type, end-user species physiology, distribution channel economics, and application scope from commercial livestock through veterinary emergency protocols. CAGRs were derived from protein demand elasticity estimates and calf-rearing unit consolidation trends.
Stress conditions across whey price volatility bands, spray-dryer capacity utilization thresholds, and antibiotic residue limit stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about precision fermentation adoption curves and EU digital product passport implementation timelines. Material shifts in China NMPA registration requirements or FDA Veterinary Feed Directive enforcement posture would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
North America Dairy Alternative Market
Dairy Alternatives
A2 Ice Cream Market
Dairy Alternatives
Asia-Pacific Sour Milk Drinks Market
Dairy Alternatives
North America Drinkable Yogurt Market
Dairy Alternatives
Asia-Pacific Coconut Milk Market
Dairy Alternatives
Dairy-Free Ice Creams Market
Dairy Alternatives
Soy Milk Market
Dairy Alternatives
Hempseed Milk Market
Dairy Alternatives
India Dairy Alternatives Market
Dairy Alternatives
Pea Milk Market
Dairy Alternatives
United States Non-Dairy Milk Market
Dairy Alternatives
Clarified Butter Market
Dairy Alternatives
Canada Dairy Alternatives Market
Dairy Alternatives
Dairy-Free Smoothies Market
Dairy Alternatives
South Korea Dairy Alternatives Market
Dairy Alternatives
Dairy Whiteners Market