
 CBD Snacks Market | 2026-2036
CBD Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
CBD Snacks Market Analysis
Hemp seed protein is rebalancing cost structures as manufacturers reduce reliance on isolate-based formulations. Charlotte's Web leverages its controlled supply chain to maintain batch consistency across gummy and chocolate lines. Diamond CBD competes through flavor innovation and SKU breadth. Medterra anchors its position with third-party testing protocols that satisfy health-conscious buyers.
CBD snacks are edible food products infused with cannabidiol extracted from hemp, typically containing 5–25 mg per serving and manufactured through lipid-based infusion or nano-emulsion processes to enhance bioavailability. These products serve commercial wellness and functional food applications where consumers seek non-psychoactive alternatives to traditional supplements. Gummies dominate current revenue contribution due to format familiarity and precise dosing. Cookies and bars represent the fastest-expanding product type as sports nutrition brands incorporate CBD into recovery-positioned offerings. Online retail captures the largest margin pool by eliminating intermediary markups while capturing direct consumer data.
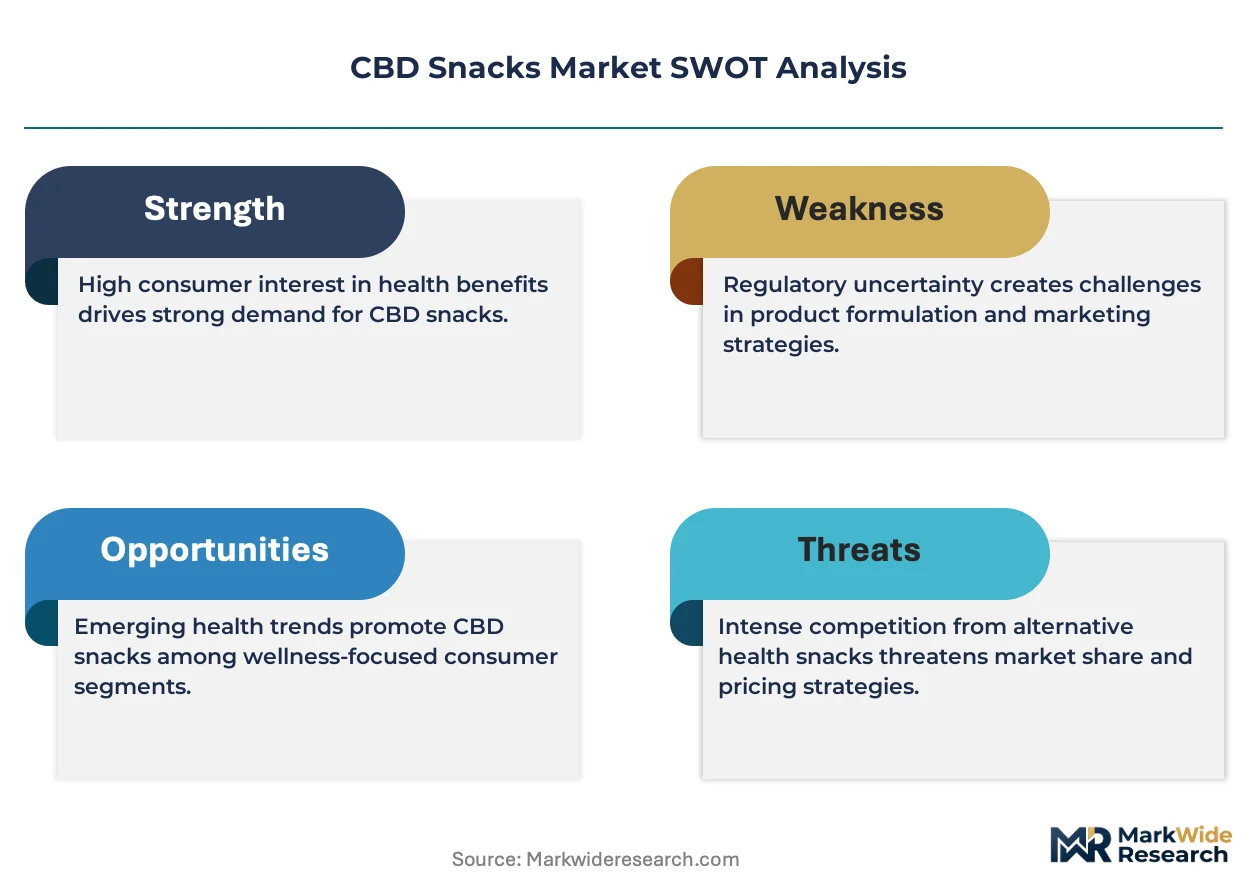
The FDA regulates CBD as a food additive under the Federal Food, Drug, and Cosmetic Act, creating compliance thresholds that favor established manufacturers with legal resources. The USDA oversees hemp cultivation standards through its interim final rule, which determines raw material legality for cross-state supply chains. State agriculture departments in Colorado and Oregon administer additional testing requirements that shape regional production concentration. Stakeholders must monitor pending FDA enforcement discretion updates to determine whether portfolio expansion into conventional retail channels justifies compliance investment.
Market Dynamics
The FDA's enforcement discretion on hemp-derived CBD food additives creates a bifurcated market where direct-to-consumer channels absorb compliance risk while conventional retail remains gated. Manufacturers navigate this uncertainty by diversifying formulation portfolios and building redundant supply chains across state jurisdictions.
Growth Catalysts
- USDA hemp cultivation standards:Interstate commerce provisions in the interim final rule enable raw material sourcing across Colorado, Oregon, and Kentucky growing regions. Multi-state supply networks reduce single-source dependency for CBD isolate and distillate inputs.
- Sports nutrition recovery applications:Protein bar and cookie formats incorporating 10–20 mg CBD per serving capture post-workout wellness spending. Athletic consumers treat CBD as a functional ingredient alongside electrolytes and branched-chain amino acids.
- Nano-emulsion processing:Lipid-based infusion technologies improve bioavailability to 35–50% versus standard oil-based formulations. Enhanced absorption rates support lower per-serving CBD doses without efficacy compromise.
Market Restraints
- CBD isolate price volatility:Hemp biomass oversupply in 2019–2021 compressed extraction margins and destabilized input cost forecasting. Extractors responded by shifting toward full-spectrum and broad-spectrum formulations with higher value retention.
- Colorado-Oregon supply concentration:Over 60% of US hemp cultivation and processing capacity clusters in these two states. Climate events or state-level regulatory changes propagate rapidly through national supply chains.
- FDA food additive prohibition:The agency's position that CBD cannot be marketed as a dietary supplement or food ingredient without NDIN approval blocks conventional grocery and mass retail distribution. Compliance costs favor capitalized incumbents over emerging entrants.
Strategic Opportunities
- Texas and Florida state frameworks:These populous markets lack comprehensive CBD food regulations, creating first-mover windows for compliant brands. Early entrants establish shelf-space relationships before federal clarity arrives.
- Functional beverage convergence:CBD-infused sparkling waters and ready-to-drink coffees merge snack adjacencies with hydration and caffeine categories. Format expansion captures consumption occasions beyond traditional edibles.
- Third-party certification differentiation:US Hemp Authority and NSF Certified for Sport labels command retail placement premiums. Certification investments signal quality assurance to risk-averse buyers.
Industry Challenges
- Formulation stability expertise:CBD degradation under heat, light, and oxidation requires specialized encapsulation and packaging engineering. Talent scarcity in food-cannabis hybrid R&D functions constrains product pipeline velocity.
- Batch-to-batch consistency protocols:Natural variance in hemp phytochemical profiles complicates standardized dosing claims. Manufacturers must implement extensive in-house and third-party testing to maintain label accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CBD Snacks Market |
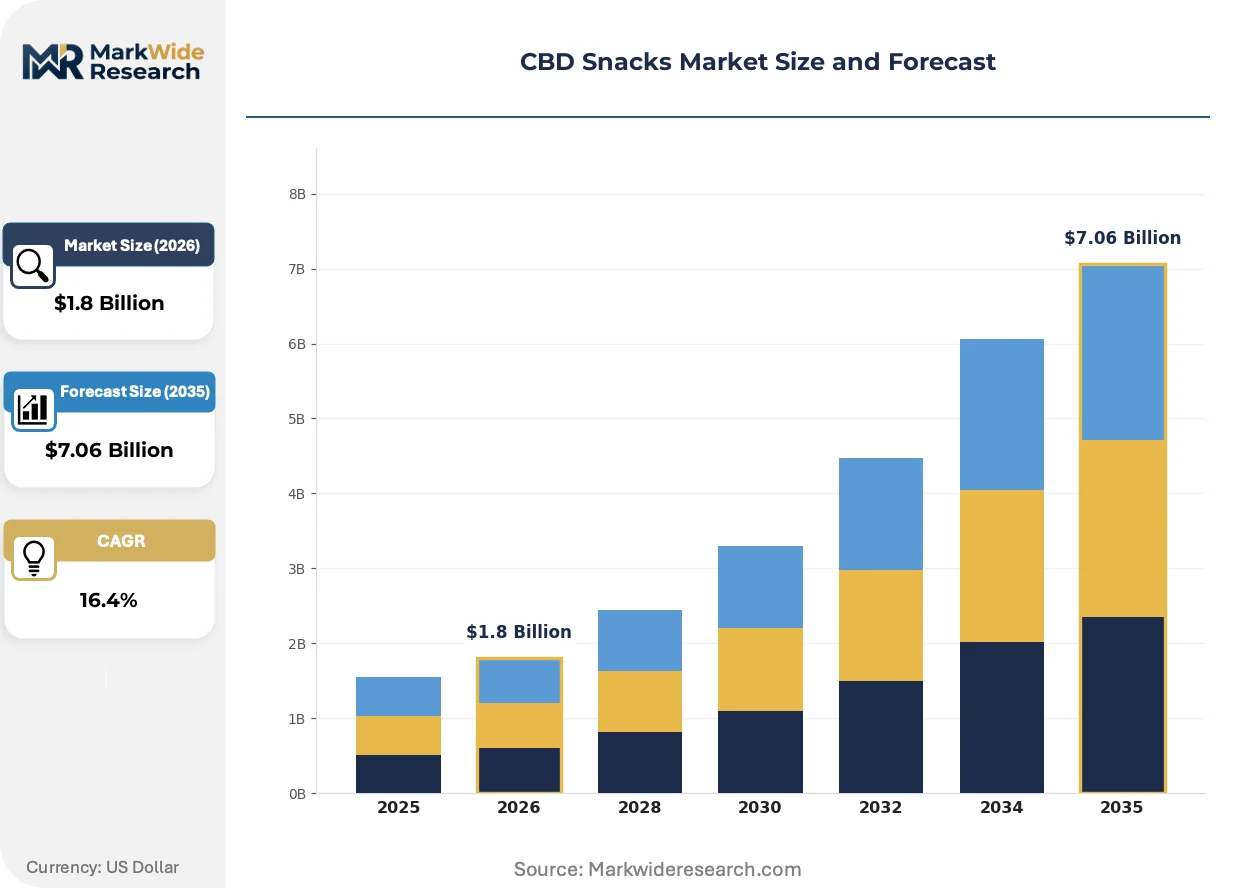
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gummies, Chocolates, Cookies, Bars Packaging Type: Resealable Bags, Boxes, Jars, Pouches Distribution Channel: Online Retail, Health Stores, Supermarkets, Specialty Shops Customer Type: Health-conscious Consumers, Athletes, Recreational Users, Wellness Seekers |
| Companies Covered | Charlotte's Web, Diamond CBD, Medterra, CBDfx, Weller, Green Roads, Hemp Bombs, Verma Farms, Lord Jones, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CBD Snacks Market Emerging Trajectories
Automation and precision dosing technologies are compressing production timelines while regulatory clarity efforts in key states reshape competitive entry barriers. Product format innovation accelerates as manufacturers seek differentiation beyond gummy saturation.
Nano-emulsion equipment is automating lipid-infusion processes that previously required manual monitoring and batch adjustment. Mid-tier manufacturers in California and Colorado adopt these systems to reduce labor costs and achieve particle-size consistency below 200 nanometers. Automated processing is compressing per-unit production costs and enabling scale without proportional quality-control headcount expansion.
The FDA's ongoing rulemaking on hemp-derived CBD enforcement discretion is forcing portfolio diversification strategies. Manufacturers maintain separate production lines for 50-state-compliant products versus state-legal formulations with higher cannabinoid content. Direct-to-consumer brands absorb the most acute compliance burden while awaiting retail channel clearance.
Subscription-based replenishment models are displacing single-transaction e-commerce for gummy and chocolate formats. Wellness-focused consumers in metropolitan markets prefer automated monthly deliveries with personalized dosing regimens. This behavioral shift concentrates customer lifetime value data with vertically integrated brands and reduces acquisition cost dependency on paid media.
CBD Snacks Market Segmentation
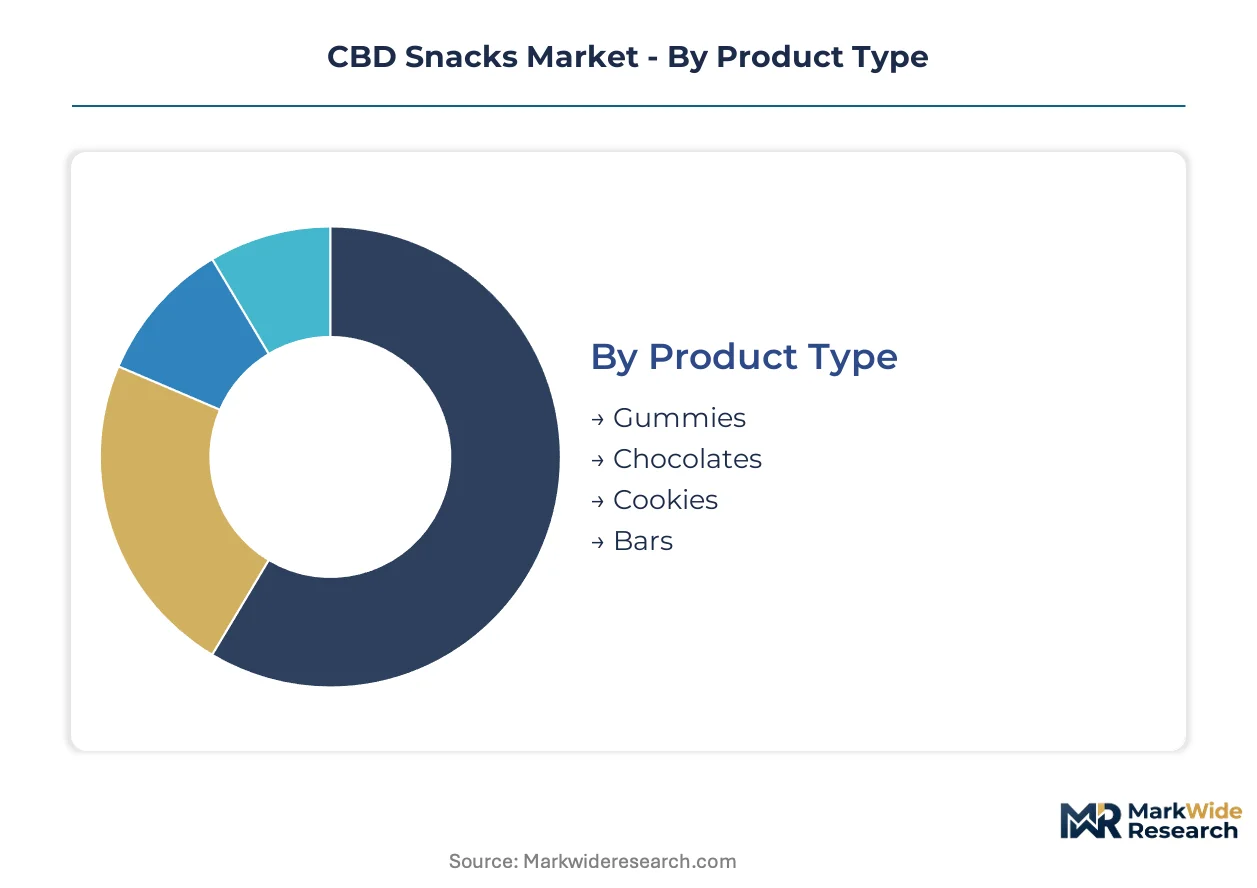
CBD snack manufacturers configure product portfolios across four distinct dimensions. Each segmentation layer determines pricing power, channel access, and compliance burden in this regulated food category.
Product Type:
Standalone edible formats dominate current production volumes, while embedded functional applications in sports nutrition accelerate fastest.
- Gummies:Gelatin or pectin-based matrices suspend 5–25 mg CBD per piece through lipid infusion or nano-emulsion. Format familiarity from conventional supplements drives adoption in United States direct-to-consumer channels, though gelatin stability challenges complicate warm-climate distribution.
- Bars:Protein-fortified formats integrate CBD isolate into nut butter or whey protein bases for post-workout positioning. Athletic consumers in Colorado and Oregon treat these as functional recovery tools alongside electrolyte replacement, with 10–20 mg standard doses matching sports nutrition labeling conventions.
- Chocolates:Cocoa butter matrices encapsulate CBD through conching-compatible lipid suspensions. Tempering requirements limit producer entry to confectionery specialists with climate-controlled facilities.
- Cookies:Baked goods face heat-degradation challenges requiring microencapsulation or post-bake spraying. Shelf-life constraints favor regional production models over national distribution.
Gummies lead volumes today; bars are gaining share fastest.
Packaging Type:
Cost tier differentiation separates premium preservation systems from commodity formats, with barrier properties determining shelf-life extension and regional shipping viability.
- Resealable Bags:Multi-layer laminates with oxygen scavengers protect CBD from oxidative degradation across 12–18 month shelf lives. Flexible format dominates e-commerce fulfillment for gummy and chocolate products.
- Jars:Amber or cobalt glass blocks UV-triggered cannabinoid breakdown in higher-margin chocolate and premium gummy lines. Weight and breakage risk limit these to health store and specialty retail.
- Boxes:Folding carton secondary packaging enables child-resistant compliance through CR-certified inserts. Unit economics favor multi-count SKUs in subscription replenishment models.
- Pouches:Single-serve metallized films support sampling programs and on-the-go consumption occasions. Lower per-unit cost attracts price-sensitive wellness seekers in emerging state markets.
Resealable bags capture the highest shipment volumes; jars command the steepest price premiums.
Distribution Channel:
Channel selection directly determines margin retention and regulatory exposure, with direct-to-consumer models absorbing compliance ambiguity that blocks conventional retail.
- Online Retail:Brand-controlled e-commerce captures first-party consumer data and eliminates intermediary markups. FDA enforcement discretion on hemp-derived CBD food additives concentrates compliant volume here as conventional grocery remains gated.
- Health Stores:Supplement-focused retailers with established CBD vendor relationships provide educated staff and third-party product verification. Regional chains in Texas and Florida lack comprehensive state frameworks, creating first-mover placement windows.
- Supermarkets:Mass retail distribution awaits FDA clarity on NDIN requirements for CBD as a food additive. Capitalized incumbents pre-position for channel opening through separate 50-state-compliant production lines.
- Specialty Shops:Cannabis-adjacent boutiques in Colorado and Oregon stock higher-cannabinoid formulations unavailable in interstate commerce. State-legal positioning captures experienced consumers seeking full-spectrum profiles.
Online retail leads transaction volumes today; health stores are expanding shelf space fastest.
Customer Type:
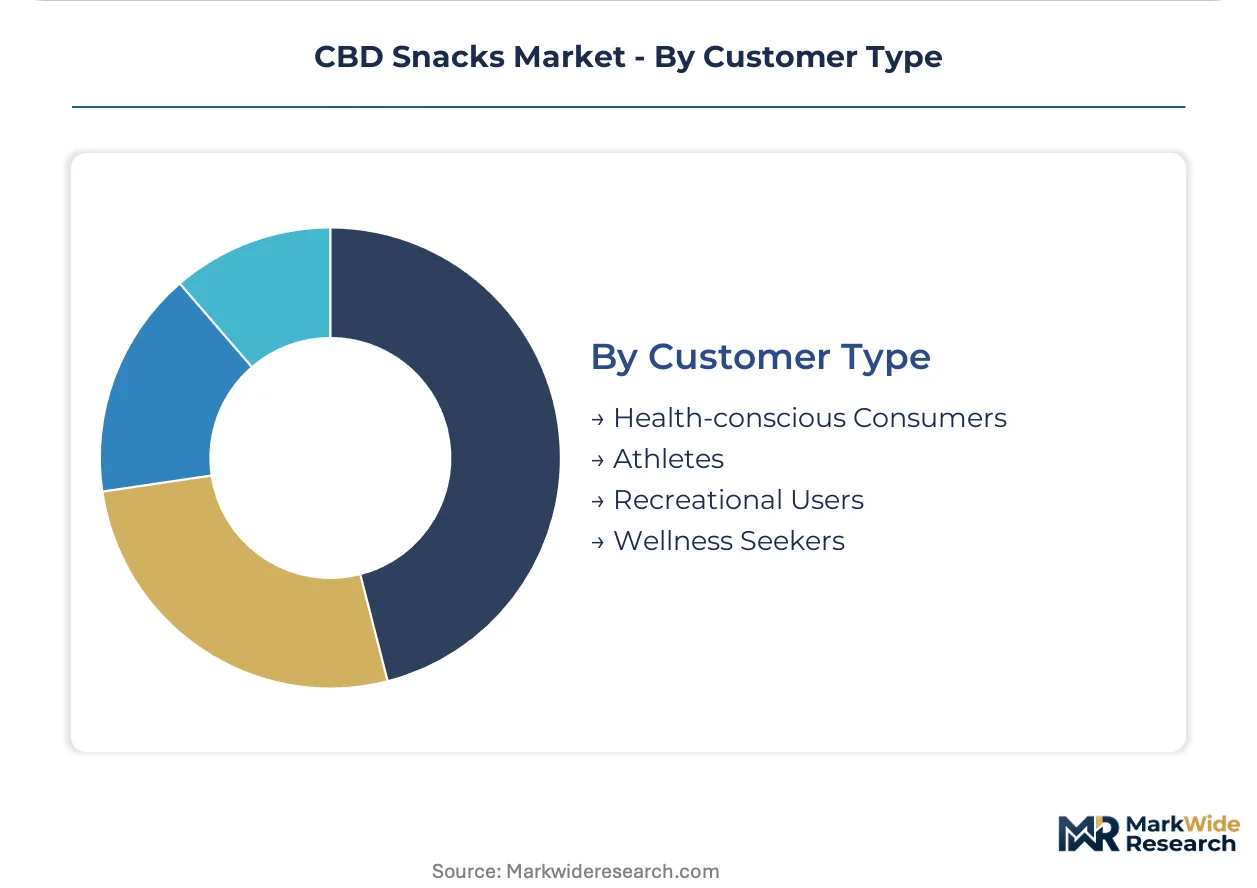
Application focus separates functional recovery use from general wellness consumption, with athletic positioning commanding formulation and certification premiums.
- Wellness Seekers:Metropolitan consumers pursue stress management and sleep support through daily microdosing regimens. Subscription replenishment models concentrate lifetime value with vertically integrated brands in direct channels.
- Athletes:Post-workout recovery applications integrate CBD with protein, electrolytes, and branched-chain amino acids. NSF Certified for Sport and US Hemp Authority labels command placement premiums in sports nutrition retail.
- Health-conscious Consumers:Clean-label preferences drive organic hemp sourcing and natural sweetener formulations. Third-party testing protocols satisfy risk aversion in this segment.
- Recreational Users:Experience-oriented consumption favors flavor innovation and novel formats over functional positioning. SKU breadth and limited-edition releases capture discretionary spending.
Wellness seekers dominate current purchasing; athletes are expanding the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Colorado's Front Range corridor anchors CBD snack manufacturing concentration, with extraction facilities and formulation labs clustering along the Denver-Boulder axis. State-level hemp frameworks in the United States, Canada, and select European jurisdictions determine where production infrastructure accumulates.
United States
State agriculture departments in Colorado and Oregon administer testing requirements that shape regional production concentration. The FDA's evolving enforcement discretion on hemp-derived CBD food additives blocks conventional retail distribution while direct-to-consumer channels absorb compliance risk. Texas and Florida lack comprehensive state frameworks, creating first-mover placement windows for compliant brands establishing shelf-space relationships.
Canada
Health Canada regulates CBD through the Cannabis Act, permitting infused food products within licensed frameworks that differ from US ambiguity. Provincial retail monopolies in Ontario and British Columbia control distribution, forcing manufacturers to navigate government wholesale procurement. British Columbia's Okanagan Valley hosts licensed cultivation operations supplying extraction inputs to Vancouver-area formulation facilities.
Germany
The Bundesinstitut für Arzneimittel und Medizinprodukte (BfArM) oversees novel food approvals for CBD ingredients under EU regulations. German consumers demonstrate strong preference for organic certification and third-party testing protocols. Berlin and Hamburg harbor the largest concentration of CBD food importers and white-label manufacturers serving pan-European distribution.
Switzerland
Swissmedic permits CBD products with less than 1% THC content, creating a permissive environment for food innovation absent in neighboring EU states. Zurich and Geneva host premium chocolate and confectionery specialists incorporating CBD into export-oriented product lines. The country's pharmaceutical manufacturing heritage supplies encapsulation and precision-dosing expertise to snack format developers.
United Kingdom
The Food Standards Agency requires novel food authorization for CBD extracts, with validated applications creating a compliance moat for established entrants. London's wellness retail ecosystem supports direct-to-consumer brand building and subscription model experimentation. Midlands-based contract manufacturers serve white-label demand from emerging European markets seeking UK-exported formulations.
CBD Snacks Market Vendor Landscape
Global majors compete with regional champions across formulation expertise and supply chain control dimensions. The vendor base separates into capitalized incumbents with legal resources, mid-tier specialists with controlled cultivation relationships, and white-label manufacturers serving emerging brand demand. Three archetypes dominate: vertically integrated hemp operators, sports nutrition crossovers, and confectionery specialists adapting CBD infusion capabilities. Portfolio diversification and redundant supply chains across state jurisdictions represent the dominant competitive moves as manufacturers navigate regulatory uncertainty.
Within the vertically integrated tier, Charlotte's Web and Diamond CBD exemplify contrasting approaches to supply chain architecture. Medterra occupies a position emphasizing third-party verification protocols. These three entities represent distinct strategic postures: controlled cultivation integration, flavor and format breadth, and certification-driven quality assurance respectively.
| Leading Market Players |
|---|
| Charlotte's Web |
| Diamond CBD |
| Medterra |
| CBDfx |
| Weller |
| Green Roads |
| Hemp Bombs |
| Verma Farms |
| Lord Jones |
| Others |
Supply Flow & Price Mechanics
Wellness-seeking subscription buyers in metropolitan United States markets anchor the dominant pricing model around recurring revenue tiers, with their lifetime value concentration enabling manufacturers to absorb higher per-unit fulfillment costs than transactional retail channels permit.
Pricing Analysis
CBD isolate and hemp biomass cost pass-through dominates manufacturer margin management, with three-tier pricing structure across premium, standard, and economy levels separating US Hemp Authority-certified SKUs from conventional third-party-tested lines and unverified white-label alternatives. Price differentiation rests on certification grade and volume scale, with NSF Certified for Sport badges commanding placement premiums in sports nutrition retail. Cost compression in economy-tier gummies is intensifying because hemp seed protein substitution reduces isolate dependency. Health-conscious consumers exhibit highest price sensitivity, while athletes demonstrate lowest elasticity due to recovery-positioning efficacy claims.
Supply Chain Analysis
Colorado and Oregon state agriculture department testing requirements function as de facto local-content rules, concentrating extraction and formulation capacity along the Denver-Boulder corridor and Willamette Valley while filtering out non-compliant raw material sources. Geographic supply concentration clusters in the United States, Canada, and Switzerland, with British Columbia's licensed cultivation and Swiss confectionery specialists providing alternative inputs. Raw material dependencies center on hemp biomass, CBD isolate and distillate, and nano-emulsion processing equipment. Single-source vulnerability propagates through the Colorado-Oregon corridor concentration, where climate events or state regulatory shifts transmit rapidly. Distribution runs through direct-to-consumer e-commerce channels that capture first-party data while circumventing FDA food additive prohibitions on conventional retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CBD snacks market functions as a geographic-arbitrage play, with Texas and Florida's absence of comprehensive state frameworks offering compliant brands lower regulatory compliance costs than FDA-gated conventional retail channels in California or New York.
For Market Incumbents: Hedge against FDA enforcement discretion tightening by maintaining parallel production lines for 50-state-compliant and state-legal formulations, while building redundant supply chains across Kentucky and Oregon growing regions to reduce Colorado concentration risk. Certification investment in US Hemp Authority and NSF protocols defends shelf-space relationships against emerging white-label competitors.
For New Entrants and Emerging Players: The USDA interim final rule's interstate commerce provisions open a window for compliant brands to establish Texas and Florida health store relationships before federal clarity arrives. White-space targets include functional beverage convergence in sparkling waters and ready-to-drink coffees, plus subscription-based replenishment models for personalized dosing regimens in metropolitan wellness markets.
For Investors and Strategic Acquirers: Sports nutrition crossovers are the most active acquirer in this space, seeking formulation expertise and controlled supply chain assets. Long-term viability over the next decade hinges on FDA NDIN pathway resolution. Acquisition target archetypes include mid-tier manufacturers with automated nano-emulsion capabilities and established third-party testing protocols. The signal to watch is FDA enforcement discretion updates that determine conventional retail channel viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Model Implementation | Captures wellness seeker lifetime value and reduces paid media dependency in direct channels. |
| Third-Party Certification Investment | US Hemp Authority and NSF labels command placement premiums in risk-averse retail segments. |
| Functional Beverage Line Extension | Sparkling waters and RTD coffees merge snack adjacencies with hydration consumption occasions. |
| Multi-State Supply Chain Redundancy | Kentucky and Oregon cultivation diversification reduces Colorado climate and regulatory concentration risk. |
| Nano-Emulsion Automation | Particle-size consistency below 200 nanometers improves bioavailability without proportional quality-control headcount expansion. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CBD extraction facility operators, sports nutrition brand managers, health store category buyers, and regulatory affairs specialists with secondary validation from FDA docket submissions, USDA hemp cultivation reports, state agriculture department testing protocols, and direct-to-consumer e-commerce transaction databases. Bottom-up SKU-level volume aggregation and top-down category spend analysis provided triangulation across data sources.
Segment-weighting across product type, distribution channel, customer application, and regional regulatory framework dimensions drove the analytical framework over the projection horizon. CAGRs were derived from normalized growth rate convergence across modeled segments, with forecast inputs including hemp biomass yield projections, nano-emulsion equipment adoption curves, and state-level cannabis framework maturity indices.
Revisions become necessary when FDA enforcement discretion shifts materially, hemp biomass oversupply cycles recur, or major state agriculture departments alter testing requirements. Forecasts reflect documented assumptions regarding regulatory timeline stability and consumer subscription retention patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Silver Food Market
Specialty Foods
Global Cocoa Nibs Market
Specialty Foods
Aloe Butter Market
Specialty Foods
Low-Fat Low-Calorie Desserts Market
Specialty Foods
Tunisia Couscous Market
Specialty Foods
Free-From Food Market
Specialty Foods
Cat and Dog Food Toppers Market
Specialty Foods
Fermented Black Beans Market
Specialty Foods
North America Popping Boba/Juice Balls Market
Specialty Foods
Vegetarian Taquitos Market
Specialty Foods
Therapeutic Dog Food Market
Specialty Foods
Dong Quai Market
Specialty Foods
Global Bee Products Market
Specialty Foods
Europe Hummus Market
Specialty Foods
Almond-Based Spreads Market
Specialty Foods
Reishi Mushroom Market