
 Global Sauerkrauts Market | 2026-2036
Global Sauerkrauts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sauerkrauts Market Outlook
Specialty store distribution is reconfiguring how artisanal sauerkraut brands reach health-conscious consumers. GLK Foods LLC leverages its bulk manufacturing infrastructure to supply both retail and food service channels. HENGSTENBERG GMBH & CO. KG anchors its position through deep roots in Central European fermentation traditions and retail dominance.
Sauerkraut denotes finely cut cabbage fermented by lactic acid bacteria, typically containing salt concentrations of 1.5% to 2.5% and achieving a final pH below 4.0 for shelf stability and probiotic preservation. The product serves commercial food manufacturing, food service preparation, and direct household consumption as a condiment, ingredient, or functional food. Organic Sauerkraut commands premium shelf positioning and tighter supply chains as consumers prioritize certified ingredients. Flavored Sauerkraut variants incorporating turmeric, jalapeño, or apple are capturing fastest-growing interest among younger demographics seeking sensory differentiation beyond traditional recipes.
USDA organic standards and EFSA food labeling frameworks shape ingredient sourcing transparency and probiotic claim substantiation across the United States and European Union. FDA food safety regulations govern acidified food manufacturing processes, while Germany's traditional food protections under EU quality schemes reinforce regional authenticity markers for imported products. Stakeholders must monitor evolving fermentation process definitions as regulators weigh probiotic health claims against emerging microbiome research standards.
Market Dynamics
Fermentation process standardization under evolving EFSA probiotic health claim frameworks is compressing formulation flexibility while forcing supply chain requalification across European and North American manufacturing footprints.
Growth Catalysts
- Gut microbiome research validation:Academic institutions and clinical research organizations are generating peer-reviewed data on lactic acid bacteria benefits, creating substantiation pathways for functional food positioning in Germany and the United States.
- Clean-label regulatory tailwinds:USDA organic certification expansion and EFSA ingredient transparency mandates are advantaging sauerkraut against preservative-laden condiment alternatives in retail shelf resets.
- Food service fermentation adoption:Commercial kitchens in Poland, the Czech Republic, and Austria are incorporating unpasteurized sauerkraut into menu formulations as consumer preference for authentic Central European cuisine intensifies.
Market Restraints
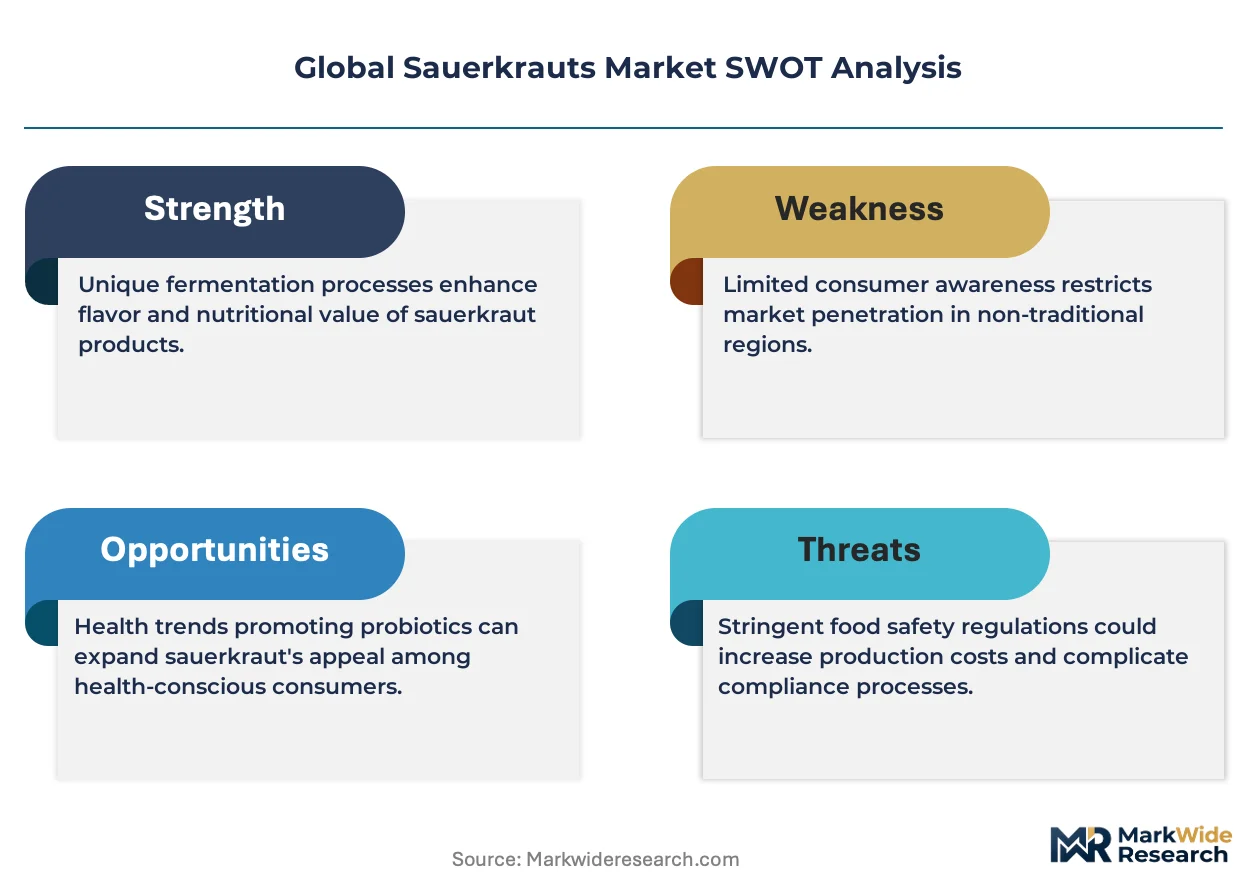
- White cabbage supply volatility:Weather-driven harvest fluctuations in Poland and Germany create input cost instability for bulk fermentation operations dependent on regional agricultural sourcing.
- Cold chain infrastructure gaps:Unpasteurized probiotic sauerkraut requires continuous refrigerated distribution, limiting penetration into developing markets with fragmented logistics networks.
- FDA acidified food compliance:21 CFR Part 114 manufacturing requirements impose specialized facility investments and process documentation burdens on small-scale artisanal producers.
Strategic Opportunities
- Functional beverage adjacencies:Sauerkraut brine repurposing into drinking vinegars and probiotic shots is opening shelf-stable product extensions with higher margin profiles than bulk vegetable formats.
- Direct-to-subscription channels:Refrigerated subscription box services bypass traditional retail slotting fees and enable recurring revenue capture among committed gut-health consumers in urban United States markets.
- EU quality scheme leverage:Germany's protected geographical indication frameworks for traditional fermented cabbage products create import differentiation barriers and premium pricing authorization for authentic regional producers.
Industry Challenges
- Microbiological consistency control:Maintaining viable probiotic counts through variable fermentation temperatures requires skilled production oversight that outpaces available technical workforce supply in expanding facilities.
- Organic certification timeline compression:Three-year land conversion requirements and annual audit cycles delay new supplier onboarding as demand for certified ingredients outpaces qualified acreage expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sauerkrauts Market |
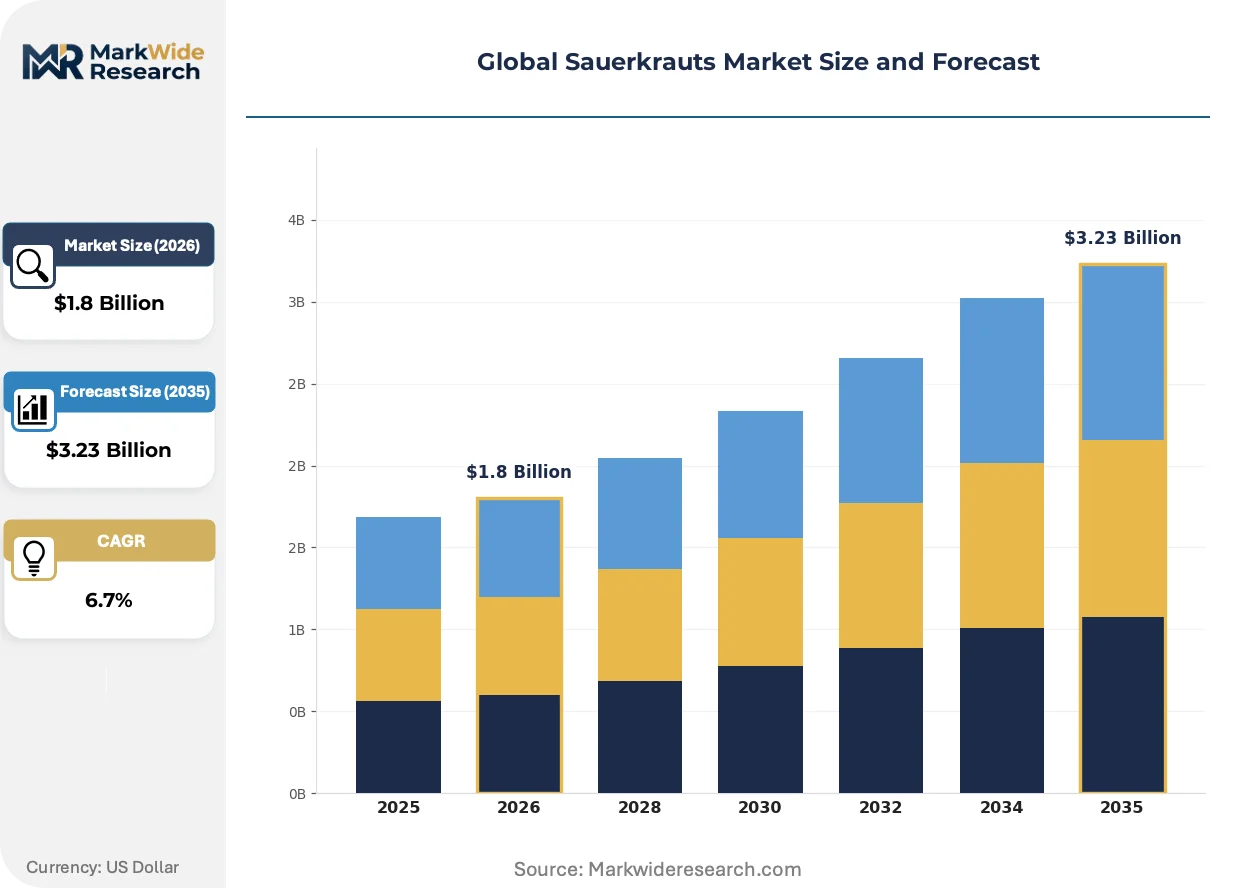
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Sauerkraut, Conventional Sauerkraut, Flavored Sauerkraut, Sauerkraut Juice Distribution Channel: Supermarkets, Online Stores, Specialty Stores, Food Service Packaging Type: Glass Jars, Plastic Containers, Pouches, Bulk Packaging End User: Households, Restaurants, Cafés, Food Manufacturers |
| Companies Covered | GLK Foods LLC, B&G Foods, Inc., HENGSTENBERG GMBH & CO. KG, Bubbies Fine Foods L.L.C., WILDBRINE, CHOI'S SAUERKRAUT CO., CJ CheilJedang Corp., The Brinery, Wasta Konserven Fischl GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sauerkrauts Market Strategic Shifts
Live culture preservation technologies and sensory format diversification are fragmenting traditional sauerkraut into distinct premium, functional, and convenience-positioned product architectures.
Controlled atmosphere packaging with modified gas flushing is collapsing the shelf-life differential between refrigerated and shelf-stable fermented vegetables. United States specialty retailers and meal-kit assemblers are adopting these materials at accelerating rates. The technology is collapsing historical channel boundaries that separated probiotic and pasteurized product distribution.
EFSA's ongoing evaluation of microbiome-related health claims under Regulation (EC) 1924/2006 is tightening evidentiary standards for probiotic marketing. Manufacturers must now commission human intervention studies to support digestive health assertions on labels. German and Austrian brands with established clinical research programs are capturing shelf space as competitors withdraw non-compliant claims.
Household purchasing of fermented foods through refrigerated e-grocery platforms is displacing conventional supermarket condiment aisle selection. Urban consumers in London, Berlin, and New York City are receiving temperature-controlled deliveries within two-hour windows. This pattern concentrates demand among digitally native demographics willing to pay premium prices for traceable, small-batch production.
Global Sauerkrauts Market Segmentation
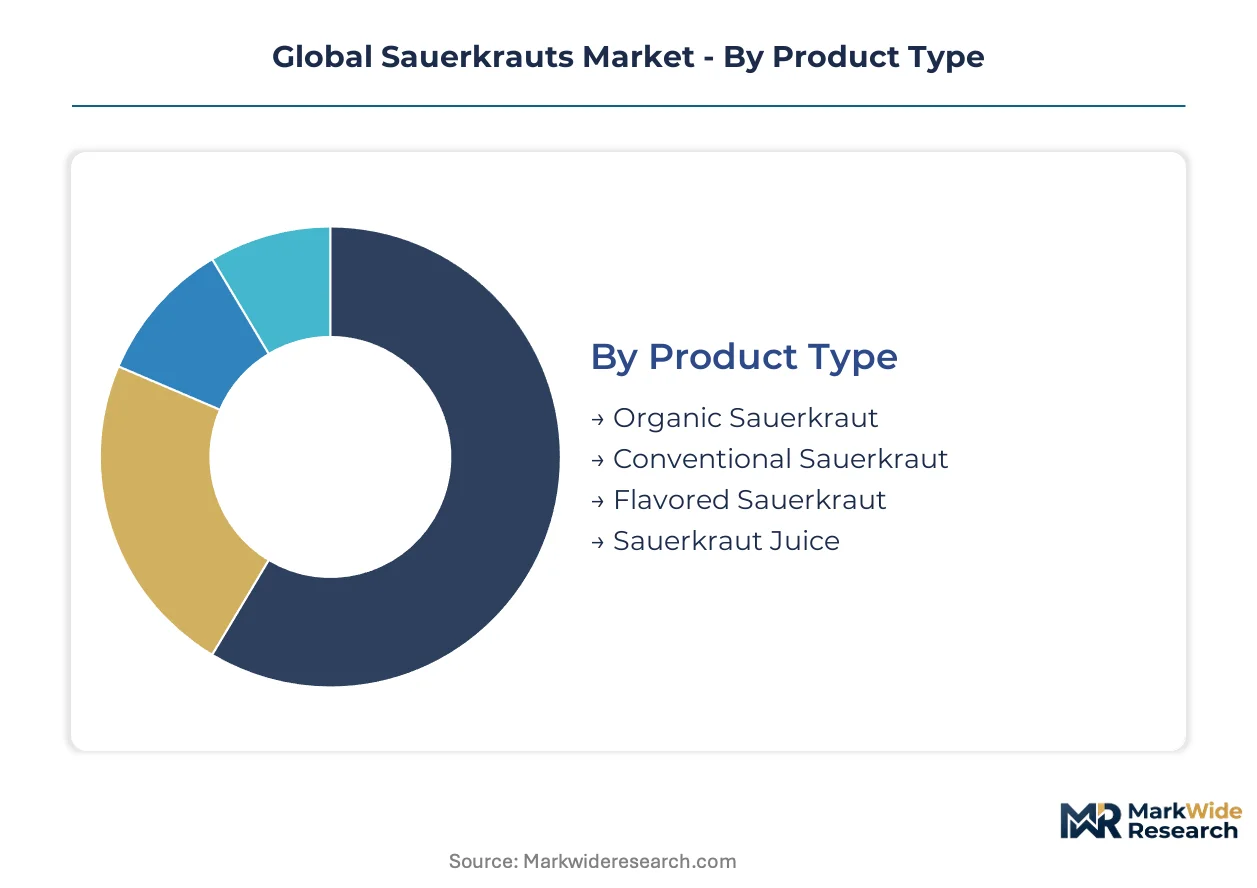
Sauerkraut manufacturers configure product architectures around fermentation certification, channel economics, and probiotic preservation requirements. Each segmentation dimension carries distinct margin profiles and regulatory compliance burdens that shape competitive positioning.
Product Type:
Cost tier stratification separates certified organic fermentation from commodity bulk production, with premium positioning commanding refrigerated distribution and extended aging protocols.
- Organic Sauerkraut:Certified cabbage sourced from three-year converted acreage undergoes unpasteurized fermentation with documented lactic acid bacteria counts. German households and United States coastal metro consumers drive demand as EFSA and USDA organic standards tighten ingredient traceability mandates.
- Conventional Sauerkraut:Standard white cabbage fermentation with pasteurization for ambient shelf stability dominates food service procurement in Poland and the Czech Republic. Price-sensitive institutional buyers prioritize volume consistency over live culture preservation.
- Flavored Sauerkraut:Turmeric, jalapeño, and apple infusions target younger United States demographics seeking sensory differentiation beyond traditional recipes.
- Sauerkraut Juice:Fermented brine repurposed into functional beverage formats captures probiotic beverage adjacency demand.
Conventional Sauerkraut holds installed capacity. Flavored Sauerkraut is rotating up the share rankings.
Distribution Channel:
Channel selection determines cold chain investment requirements and margin capture, with temperature-controlled logistics creating divergent cost structures across retail formats.
- Supermarkets:Mass retail placement demands pasteurized shelf-stable formats with extended best-before dating. German discounters and United States conventional grocers dominate volume throughput.
- Online Stores:Refrigerated e-grocery platforms in London, Berlin, and New York City enable direct-to-consumer probiotic positioning with subscription recurring revenue models.
- Specialty Stores:Independent natural food retailers in Austria and Switzerland curate small-batch unpasteurized selections for gut-health committed consumers.
- Food Service:Commercial kitchens across Central Europe incorporate bulk fermented cabbage into traditional menu formulations requiring consistent portion control.
Supermarkets anchor volume throughput. Online Stores are climbing the fastest.
Packaging Type:
Material selection balances probiotic viability protection against logistics economics, with modified atmosphere technologies collapsing historical shelf-life differentials.
- Glass Jars:Inert barrier properties preserve lactic acid bacteria viability for premium unpasteurized positioning in German and Austrian specialty retail. Higher unit costs limit mass-market penetration.
- Plastic Containers:Lightweight polyethylene terephthalate formats reduce freight costs for United States supermarket distribution of pasteurized conventional products.
- Pouches:Flexible controlled-atmosphere packaging extends refrigerated shelf life for meal-kit assemblers and subscription box services.
- Bulk Packaging:Food-grade pails and totes serve restaurant and food manufacturer procurement with minimal per-unit material overhead.
Plastic Containers dominate unit economics. Pouches are gaining share fastest.
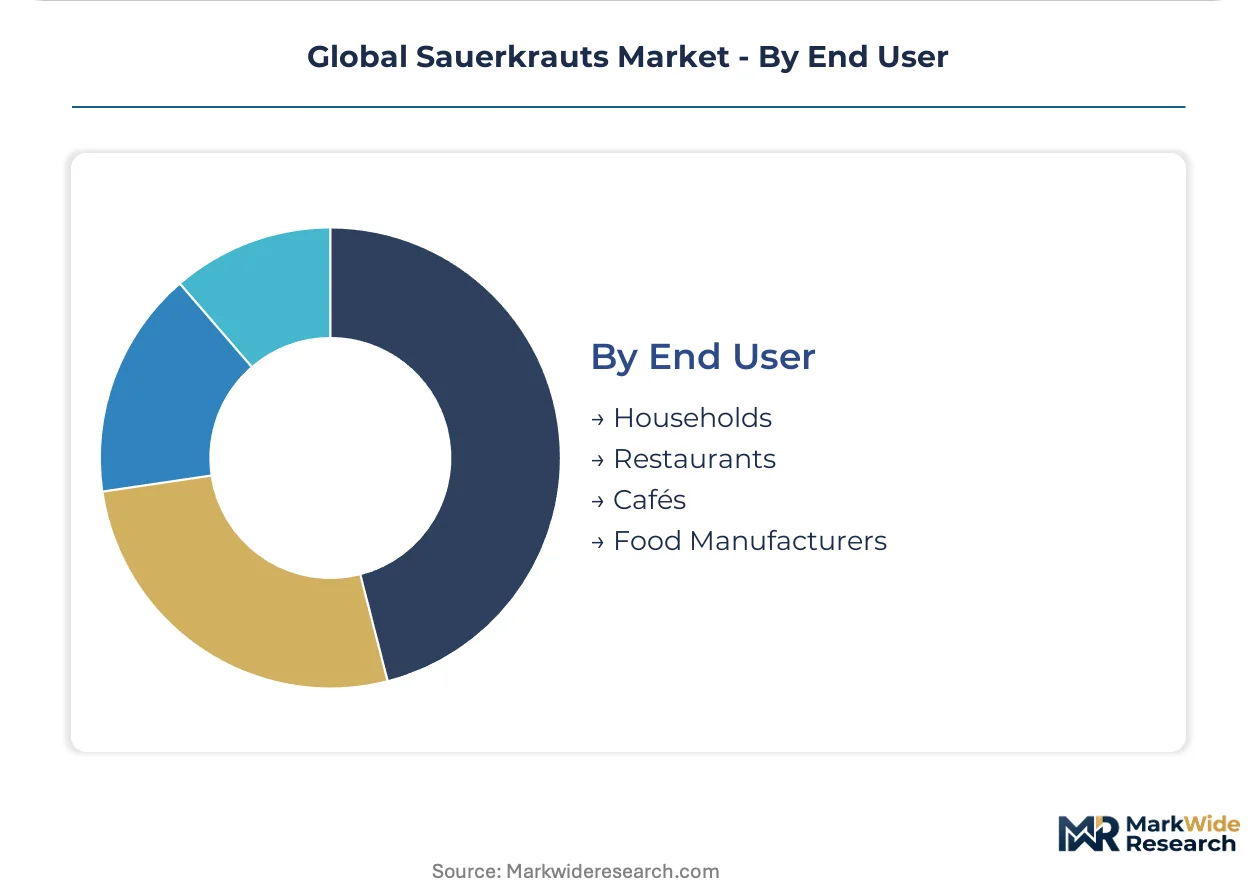
End User:
Customer type dictates formulation specifications, with household probiotic sensitivity diverging sharply from food manufacturing pH and acidity requirements.
- Households:Direct consumption as condiment or functional food drives refrigerated unpasteurized demand in United States urban markets and German traditional consumption regions.
- Restaurants:Central European cuisine authenticity requirements in Poland and Austria sustain bulk unpasteurized procurement for menu integration.
- Cafés:Health-forward independent operators in London and New York City incorporate fermented vegetables into bowl and sandwich formulations.
- Food Manufacturers:Processed meat and ready-meal producers require standardized acidity and moisture specifications for ingredient incorporation.
Households command premium pricing. Food Manufacturers anchor volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's refrigerated container terminals anchor Central European sauerkraut distribution, connecting Baltic cabbage suppliers to Atlantic export routes. Cold-chain rail corridors link Polish growing regions to German processing clusters. United States intermodal networks from Chicago to New York City enable temperature-controlled east-west logistics for probiotic products.
Germany
Traditional household consumption patterns sustain per-capita demand leadership, with multigenerational recipes driving repeat purchase loyalty. EFSA's evolving probiotic health claim frameworks under Regulation (EC) 1924/2006 tighten substantiation requirements for digestive wellness marketing. Bavarian fermentation facilities near Regensburg concentrate artisanal production, while Lower Saxony hosts bulk manufacturing operations serving food service export markets.
United States
Functional food positioning and gut health awareness campaigns drive new household penetration in coastal metropolitan markets. FDA acidified food regulations under 21 CFR Part 114 impose specialized facility investments and process documentation burdens on domestic producers. Brooklyn and Portland fermentation clusters incubate small-batch brands targeting subscription e-grocery channels with live-culture unpasteurized formats.
Poland
White cabbage agricultural concentration supplies raw material to German and Austrian processing operations, with harvest volatility creating input cost instability. EU quality scheme protections for traditional fermented foods reinforce regional authenticity markers for value-added exports. Łódź and Poznań processing corridors concentrate bulk fermentation capacity serving Central European food service procurement networks.
Austria
Independent natural food retailers curate small-batch unpasteurized selections for gut-health committed consumers in Vienna and Salzburg metropolitan areas. EFSA ingredient transparency mandates advantage domestic producers against preservative-laden import alternatives. Styrian agricultural cooperatives supply certified organic cabbage to specialty fermentation operations emphasizing three-year land conversion protocols.
United Kingdom
Refrigerated e-grocery platforms in London enable direct-to-consumer probiotic positioning with two-hour temperature-controlled delivery windows. Clean-label regulatory tailwinds from post-Brexit food standards evolution tighten ingredient disclosure requirements. Bristol and Manchester urban fermentation startups capture digitally native demographics through subscription recurring revenue models bypassing conventional retail slotting fees.
Global Sauerkrauts Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in fermentation substrate supply and culture propagation. The vendor base stratifies across three tiers: multinational condiment conglomerates with refrigerated distribution infrastructure, mid-scale regional processors serving food service accounts, and artisanal micro-producers targeting subscription channels. Two dominant competitive moves define current positioning: backward integration into organic cabbage acreage to secure three-year certified supply, and technology licensing partnerships for controlled-atmosphere packaging extending refrigerated shelf life.
Within the multinational tier, GLK Foods LLC and HENGSTENBERG GMBH & CO. KG exemplify divergent geographic anchoring strategies, with the former representing North American bulk manufacturing scale and the latter embodying Central European fermentation tradition. Among specialty producers, Bubbies Fine Foods L.L.C. occupies a position in the unpasteurized live-culture segment, while WILDBRINE sits within the flavored innovation vector targeting younger United States demographics. These four names illustrate how competitive positioning fragments across certification grade, thermal processing choice, and channel economics rather than concentrating around unified scale advantages.
| Leading Market Players |
|---|
| GLK Foods LLC |
| B&G Foods, Inc. |
| HENGSTENBERG GMBH & CO. KG |
| Bubbies Fine Foods L.L.C. |
| WILDBRINE |
| CHOI'S SAUERKRAUT CO. |
| CJ CheilJedang Corp. |
| The Brinery |
| Wasta Konserven Fischl GmbH & Co. KG |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Polish bulk fermentation facilities is compressing spot pricing for conventional white cabbage inputs while simultaneously pressuring artisanal producers to absorb cold-chain premiums or surrender margin. This utilization imbalance rewards scaled operators with backward integration into captive acreage and punishes uncommitted buyers facing harvest volatility.
Pricing Analysis
Three-tier pricing structure across premium unpasteurized, standard pasteurized, and economy food-service grades governs transaction economics. Certification tier under USDA organic standards and EFSA quality schemes drives 40-60% spreads between adjacent tiers. Cost compression in conventional bulk supply is intensifying because Polish harvest surplus is displacing German contract volumes. Food manufacturers anchor price sensitivity through volume offtake negotiations, while subscription-channel households exhibit minimal elasticity for traceable small-batch positioning.
Supply Chain Analysis
Upstream white cabbage cultivation draws from Polish growing regions, German contract farming networks, and Austrian organic cooperatives as primary feedstock sources. Fermentation substrate quality, salt procurement, and live-culture propagation supplies constitute critical input dependencies. Single-source vulnerability concentrates in Baltic climate-dependent harvest windows. Distribution runs through refrigerated intermodal corridors linking Lower Saxony processing clusters to Hamburg container terminals for Atlantic export.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sauerkraut market fragmentation creates multiple viable positioning niches as gut-health demand splinters across premium functional, authentic traditional, and convenience-oriented buyer archetypes.
For Market Incumbents: Harden supply security through backward integration into three-year certified organic acreage in Lower Saxony or Styria, insulating against EFSA tightening on ingredient traceability. Consolidate refrigerated distribution partnerships with e-grocery platforms in Berlin, London, and New York City before slotting fees escalate. Cold-chain infrastructure scarcity represents the primary defensive moat against commodity competitors. For New Entrants and Emerging Players: Flavored sauerkraut variants with turmeric or jalapeño infusions targeting United States coastal millennials represent the most penetrable entry point, as sensory differentiation commands 35-50% shelf-price premiums over traditional recipes. Direct-to-subscription channels bypass incumbent retail gatekeeping. Partner with meal-kit assemblers for controlled-atmosphere pouch distribution to minimize capital-intensive cold-chain buildout. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across live-culture preservation technology and certified organic land conversion. Over a 5-10 year viability window, acquisition targets with established EFSA-compliant clinical research programs and captive fermentation capacity offer defensive positioning. Monitor EFSA probiotic health claim enforcement actions as the signal for competitive shakeout timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Acreage | Three-year land conversion timelines lock out late entrants as EFSA traceability mandates tighten. |
| Controlled-Atmosphere Packaging Adoption | Modified gas flushing collapses shelf-life differentials between refrigerated and shelf-stable probiotic formats. |
| Direct-to-Subscription Channel Launch | Recurring revenue capture in urban United States markets bypasses conventional retail slotting fee structures. |
| Functional Beverage Line Extension | Sauerkraut brine repurposing into probiotic shots opens higher-margin adjacencies than bulk vegetable sales. |
| EU Quality Scheme Certification | Germany's protected geographical indication frameworks create import differentiation barriers for authentic regional producers. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with fermentation facility managers, organic certification auditors, refrigerated logistics coordinators, and specialty retail category buyers; and secondary validation through EFSA regulatory filings, USDA organic certification databases, customs trade records, and food service procurement contracts. Bottom-up volume triangulation across product type, distribution channel, and end-user segments was cross-checked against top-down macroeconomic demand modeling.
Forecast inputs span organic certification penetration rates, cold-chain infrastructure expansion, EFSA probiotic claim enforcement evolution, and household gut-health spending elasticity across the projection horizon. Segmentation dimensions modeled include fermentation certification grade, thermal processing method, packaging technology, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and supply-side capacity constraints.
Practitioners should monitor EFSA microbiome health claim rulings, Polish harvest yield volatility, and refrigerated e-grocery platform expansion rates for early signals requiring forecast revision. Cross-checking against Nielsen retail audit data and customs export volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Global Diet Food and Beverages Market
Specialty Foods
North America Alcohol-Infused Ice Cream Market
Specialty Foods
Asia-Pacific Free from Food Market
Specialty Foods
Carbonic Maceration Market
Specialty Foods
Luxury Cigar Market
Specialty Foods
Cat Food Toppings Market
Specialty Foods
GCC Halal Food Market
Specialty Foods
Halal Products Market
Specialty Foods
Space Food Market
Specialty Foods
Healthy Low-Fat Desserts Market
Specialty Foods
Global Ethnic Foods Market
Specialty Foods
Low Fat Hummus Market
Specialty Foods
Sea Moss Market
Specialty Foods
Mexico Guacamole Market
Specialty Foods
Low Calorie Chocolate Desserts Market
Specialty Foods
Global Pine Pollen Market