
 Pet Milk Replacers Market | 2026-2036
Pet Milk Replacers Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Milk Replacers Market Analysis
Aftermarket nutritional consulting and veterinary feeding protocol services is reconfiguring how value pools distribute across the pet milk replacers supply chain. Pet-Ag, Inc. leverages decades of species-specific formulation expertise to dominate veterinary clinic channels. Royal Canin sustains premium positioning through breed-targeted nutritional science. Cargill, Incorporated anchors supply security through backward integration into dairy protein sourcing and captive manufacturing infrastructure.
Pet milk replacers are nutritionally engineered substitutes formulated to match the macronutrient, immunoglobulin, and micronutrient profiles of maternal milk for neonatal animals unable to nurse, typically manufactured through spray-drying or wet-blending of dairy derivatives, vegetable fats, and supplemental amino acids to achieve specific protein-to-fat ratios and osmolality targets. The powdered product format occupies the dominant share of commercial volume due to extended shelf stability and lower logistics costs, while liquid ready-to-use formulations command premium positioning in emergency veterinary and high-turnover breeding environments. Puppies and kittens collectively represent the most commercially developed target animal segment, though foal and calf applications retain distinct margin pools tied to equine and livestock producer economics.
FDA Center for Veterinary Medicine oversight of feed ingredient safety and AAFCO model regulations for nutritional adequacy claims shape product development timelines and label compliance costs for manufacturers distributing in the United States. ISO 22000 and FSSC 22000 food safety management certifications increasingly function as baseline market access requirements for international suppliers seeking entry into North American and European retail and veterinary channels. Stakeholders must monitor evolving regulatory convergence between human food safety standards and pet nutrition frameworks as jurisdictions tighten cross-species manufacturing oversight.
Market Dynamics
Veterinary feeding protocol standardization is compressing product development cycles while elevating formulation complexity requirements for neonatal nutrition suppliers.
Growth Catalysts
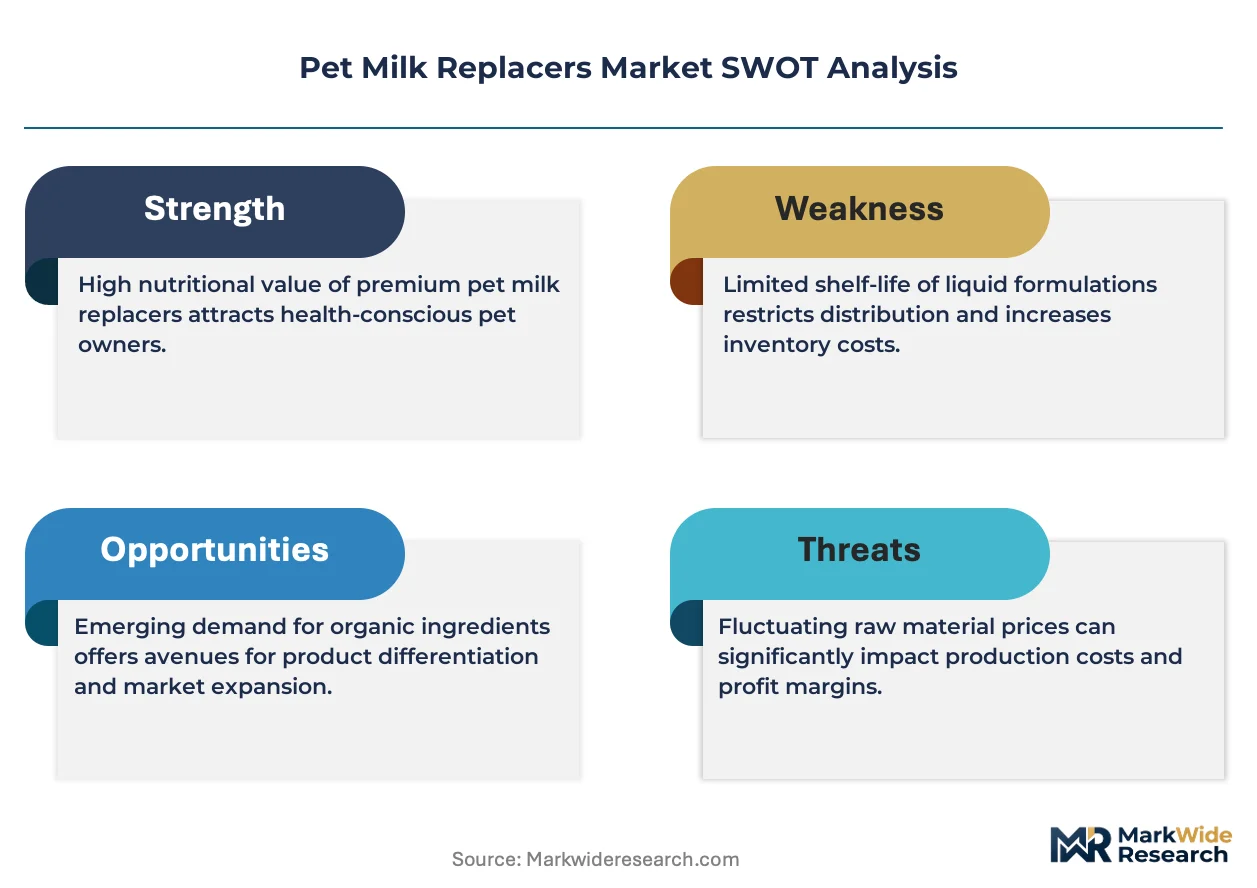
- AAFCO nutritional adequacy protocols:Tightening label claim verification in the United States is forcing manufacturers to invest in clinical validation studies, raising barriers for marginal entrants.
- Emergency veterinary channels:24-hour critical care facilities are consolidating purchasing power and demanding ready-to-use liquid formats with documented osmolality stability.
- Spray-drying infrastructure expansion:Dairy processing clusters in Wisconsin and California are repurposing human-grade drying capacity for specialty animal nutrition contracts.
Market Restraints
- Whey protein concentrate volatility:Dairy commodity price swings directly compress margin structures for powdered replacer formulations.
- FDA feed ingredient review timelines:Novel protein source approvals face 18-24 month evaluation windows, freezing innovation pipelines.
- Home-prepared milk substitute recipes:Breeder communities disseminating unverified formulations through social channels erode clinical credibility of commercial products.
Strategic Opportunities
- ISO 22000 certification gaps:Mid-tier suppliers in Eastern European markets lack food safety management credentials required for North American veterinary channel entry.
- Telemedicine veterinary platforms:Remote neonatal care consultations are creating direct-to-breeder subscription channels bypassing traditional distribution.
- Precision fermentation proteins:Cultured immunoglobulin and growth factor production is converging with conventional dairy processing to enable species-specific bioactive enrichment.
Industry Challenges
- Neonatal nutrition specialist scarcity:Veterinary schools produce fewer than 200 board-certified neonatologists annually across the United States, constraining technical support capacity.
- FSSC 22000 audit preparation:Smaller manufacturers face six-figure compliance investments to meet retail and export channel requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Milk Replacers Market |
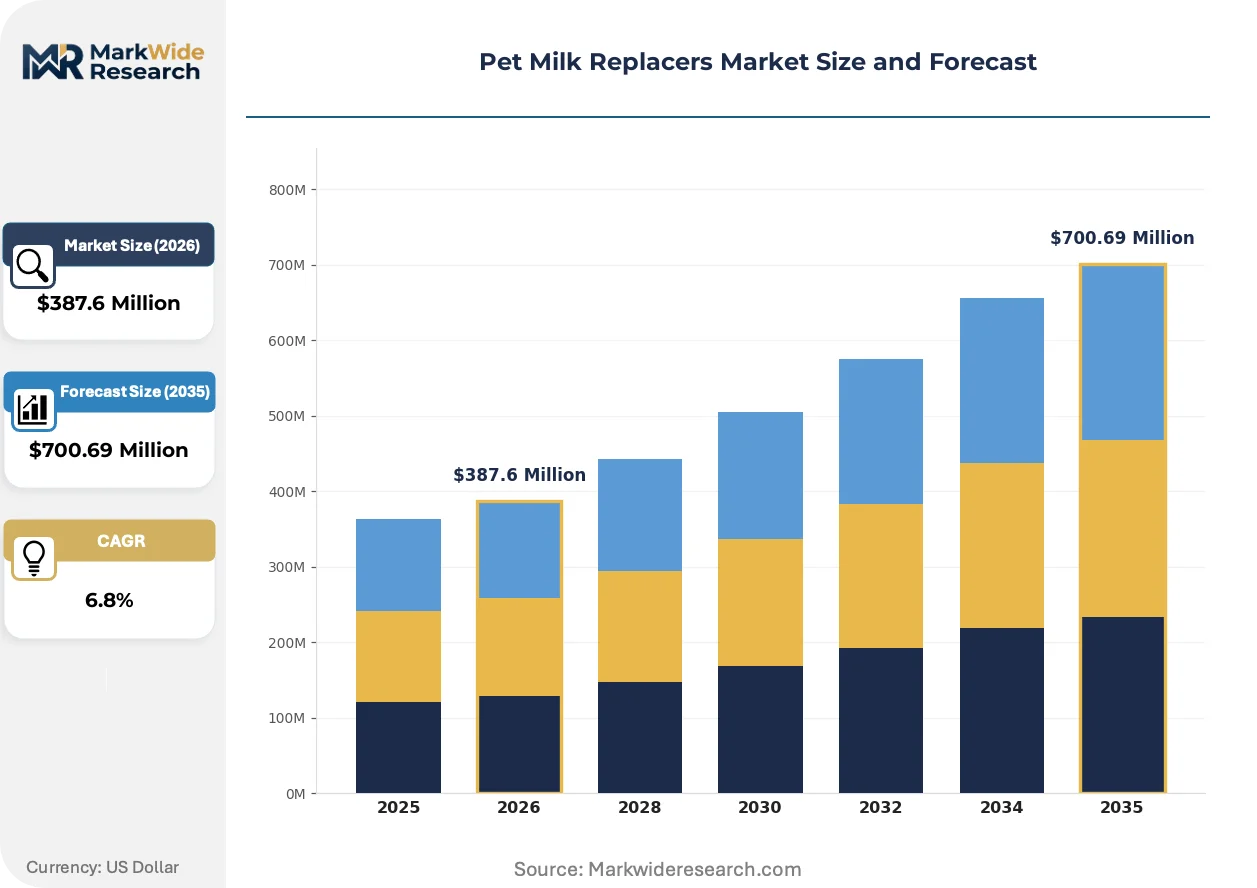
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered, Liquid, Concentrated, Ready-to-Use Target Animal: Puppies, Kittens, Foals, Calves Distribution Channel: Retail Stores, Online, Veterinary Clinics, Wholesale Brand Type: Premium, Standard, Generic, Others |
| Companies Covered | Pet-Ag, Inc., Manna Pro Products, LLC, Royal Canin, Beaphar, Grober Nutrition, Inc., Milk Products, Inc., Land O'Lakes, Cargill, Incorporated, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Milk Replacers Market Emerging Trajectories
Digital formulation platforms and bioactive ingredient sourcing are compressing traditional R&D timelines while fragmenting competitive advantage sources across the supply chain.
Precision fermentation is virtualizing immunoglobulin production for species-specific colostrum replacers. Veterinary teaching hospitals in the United States are piloting these bioactive-enriched formulations for immunocompromised neonates. This technology is virtualizing the supply structure for high-value protein fractions previously dependent on maternal milk pooling.
EU REACH chemical registration requirements are extending to novel lipid ingredients used in milk replacer emulsions. Manufacturers importing vegetable fat blends into European veterinary channels must now submit full toxicological dossiers. Specialty pet nutrition divisions are responding by consolidating supplier bases to pre-registered chemical vendors.
Breeder cooperative purchasing collectives are aggregating volume commitments and negotiating direct manufacturing contracts. Large-scale canine breeding operations in the southeastern United States are displacing distributor intermediaries with annual tender processes. This concentration is most visible in multi-state kennel networks operating 500-plus active breeding females.
Pet Milk Replacers Market Segmentation
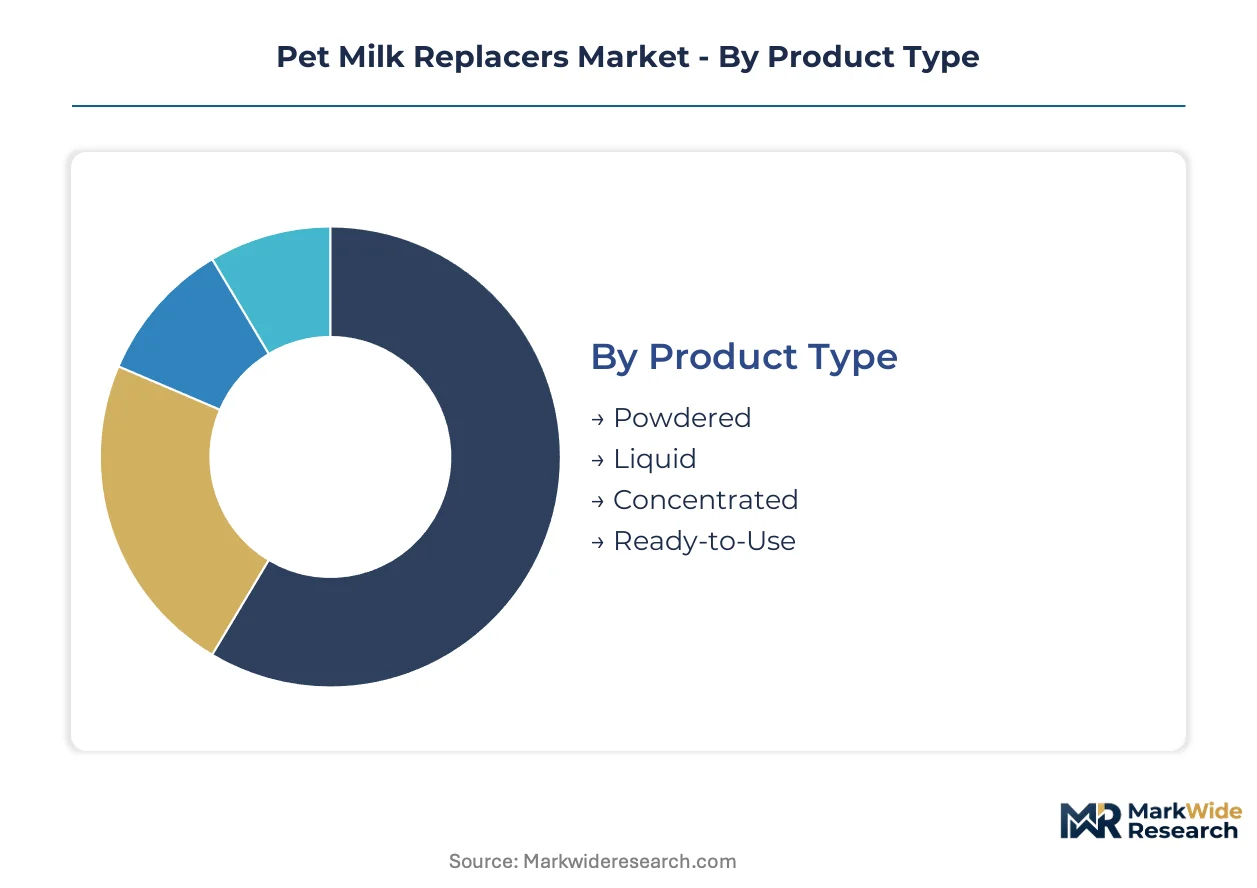
Pet milk replacer manufacturers engineer distinct formulations across product architectures to match the physiological windows and procurement rhythms of neonatal animal care. Segment boundaries reflect tension between shelf-life economics, clinical urgency, and breeder operational scale.
Product Type:
Powdered formulations turn inventory slowest while liquid formats cycle through emergency channels fastest, compressing working capital requirements for distributors.
- Powdered:Spray-dried dairy protein matrices with vegetable fat encapsulation achieve 18-24 month stability at ambient temperature. Breeder cooperatives in Wisconsin and Missouri consolidate annual procurement contracts around this format to minimize per-unit logistics burden.
- Liquid:Aseptically packaged emulsions with documented osmolality stability target 24-hour veterinary critical care facilities. Emergency channels in Texas and Florida demand documented cold-chain integrity with 72-hour post-opening viability.
- Concentrated:Reduced-moisture intermediates requiring dilution prior to feeding occupy niche positioning for mobile veterinary units.
- Ready-to-Use:Pre-diluted complete nutrition eliminates mixing error risk in high-turnover breeding environments.
Powdered dominates installed base. Liquid is where expansion concentrates.
Target Animal:
Species-specific formulation cycles correlate with breeding seasonality and veterinary specialization density.
- Puppies:Canine neonatal formulations emphasize immunoglobulin density and gastric acid buffering for altricial digestion. Large-scale kennel networks across Georgia and North Carolina drive volume concentration through direct manufacturing contracts.
- Kittens:Feline-specific protein-to-fat ratios and taurine fortification address obligate carnivore metabolism. Feline-focused veterinary clinics in California and New York sustain premium positioning through protocol standardization.
- Foals:Equine neonatal nutrition requires higher energy density and IgG thresholds tied to passive transfer failure risk in thoroughbred operations.
- Calves:Livestock producer economics favor cost-optimized formulations with antimicrobial supplementation for dairy replacement programs.
Puppies anchor current revenue concentration. Kittens are climbing the fastest as feline specialty practice expands.
Distribution Channel:
Channel selection determines margin capture and technical support intensity, with veterinary intermediaries commanding highest service overhead.
- Retail Stores:Mass-market shelf presence targets first-time pet owners with price-transparent positioning. Pet specialty chains in suburban markets consolidate planogram authority.
- Online:Direct-to-breeder subscription models bypass distributor markups through telemedicine platform integration. Digital channels are gaining share fastest among millennial breeder demographics.
- Veterinary Clinics:Protocol-driven procurement binds neonatal outcomes to specific formulation brands. Board-certified neonatologist density constrains technical support scalability.
- Wholesale:Distributor intermediaries aggregate fragmented breeder demand into manufacturing contracts with volume-tier pricing.
Veterinary clinics dominate premium value capture. Online is where channel expansion concentrates.
Brand Type:
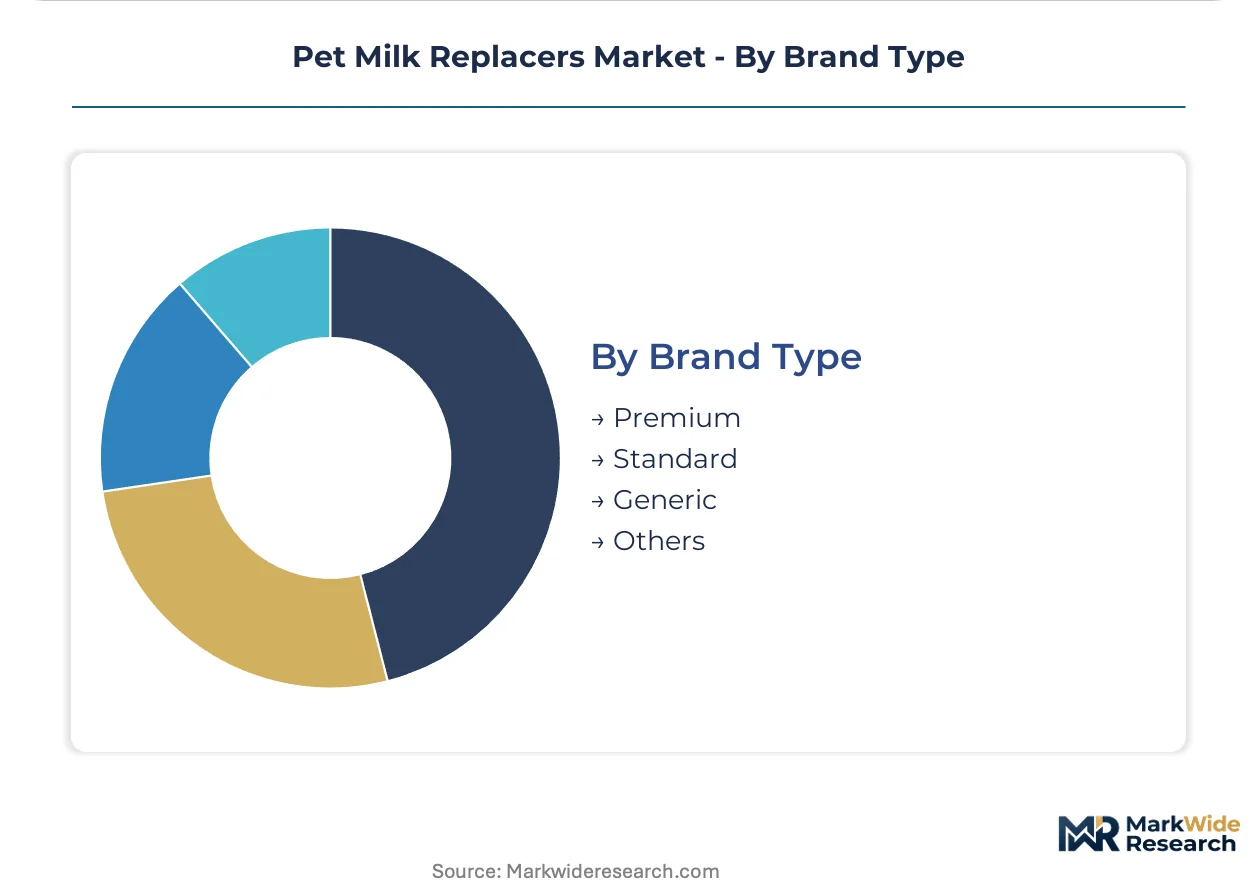
Brand tier stratification reflects certification grade, clinical validation investment, and ingredient sourcing transparency.
- Premium:AAFCO nutritional adequacy verification, species-specific bioactive enrichment, and veterinary endorsement programs define positioning. FDA feed ingredient review documentation supports label claim defensibility.
- Standard:Nutritionally complete formulations without breed-specific targeting occupy mid-market price positioning.
- Generic:Unbranded or private-label alternatives compete on per-unit cost for price-sensitive livestock applications.
- Others:Emerging precision fermentation and cultured protein entrants occupy pre-commercial positioning.
Premium dominates clinical channel penetration. Standard is where volume expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: veterinary protocol standardization drives premium liquid adoption in the United States, while European breeders favor certified powdered formats, and emerging markets prioritize cost-optimized livestock-grade formulations.
United States
Large-scale canine breeding operations in Georgia and North Carolina consolidate procurement through direct manufacturing contracts. FDA Center for Veterinary Medicine oversight of feed ingredient safety shapes label claim verification timelines. Wisconsin and California dairy processing clusters repurpose human-grade spray-drying capacity for specialty animal nutrition contracts.
Germany
Equine breeding operations in Lower Saxony sustain demand for high-IgG foal formulations with documented passive transfer thresholds. ECHA REACH chemical registration requirements extend to novel lipid ingredients in milk replacer emulsions. Bavaria-based veterinary teaching hospitals pilot precision fermentation bioactives for immunocompromised neonates.
United Kingdom
Feline specialty practices in London and Southeast England drive premium kitten formulation adoption with taurine fortification protocols. FSSC 22000 food safety certifications function as baseline market access requirements for retail channel entry. Midlands distribution hubs aggregate breeder cooperative volume commitments for annual tender processes.
China
Domestic pet ownership expansion in Shanghai and Beijing metro areas accelerates demand for nutritionally complete puppy and kitten replacers. SAMR dairy protein import regulations constrain formulation flexibility for foreign suppliers. Yangtze River Delta contract manufacturers develop species-specific osmolality targets for regional veterinary chains.
Brazil
Livestock producer economics in São Paulo and Minas Gerais favor cost-optimized calf replacers with antimicrobial supplementation. ANVISA veterinary product registration timelines extend market entry windows for novel protein sources. Southern Brazil dairy cooperatives backward integrate into captive milk replacer production for dairy replacement programs.
Pet Milk Replacers Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three distinct player clusters: veterinary-specialist formulators with decades of species-specific expertise, diversified nutrition conglomerates with captive dairy protein sourcing, and regional dairy cooperatives with surplus drying capacity. Strategic moves concentrate on spray-drying infrastructure partnerships and telemedicine platform integrations for direct breeder channel access.
Within the veterinary-specialist tier, Pet-Ag, Inc. and Royal Canin occupy positions defined by clinical protocol entrenchment and breed-targeted nutritional science respectively. Cargill, Incorporated anchors the diversified nutrition conglomerate archetype through upstream control over dairy protein supply chains. These three exemplify how competitive positioning fragments across formulation expertise, ingredient security, and channel-specific technical support intensity.
| Leading Market Players |
|---|
| Pet-Ag, Inc. |
| Manna Pro Products, LLC |
| Royal Canin |
| Beaphar |
| Grober Nutrition, Inc. |
| Milk Products, Inc. |
| Land O'Lakes |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Others |
Supply Flow & Price Mechanics
Whey protein concentrate volatility determines both the spread between premium and economy-tier pricing and the geographic clustering of spray-drying infrastructure. Dairy commodity price swings compress margins for powdered formulations while rewarding suppliers with backward integration into captive protein sourcing.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement for large-scale breeding operations, while spot purchasing persists among small kennels. Price differentiation rests on certification grade—AAFCO-verified premium tiers command substantial markups over unverified alternatives—and volume scale, with annual tenders compressing per-unit costs for multi-state networks. Cost compression in the standard tier is intensifying because home-prepared substitute recipes erode clinical credibility. Livestock-grade calf replacer buyers exhibit highest price sensitivity; veterinary clinic channels show lowest.
Supply Chain Analysis
Extended payment terms from distributor intermediaries strain working capital for mid-tier manufacturers lacking supply-chain finance facilities. Geographic supply concentration centers on the United States—Wisconsin and California dairy processing clusters—plus Germany and China for regional formulation. Raw material dependencies draw from whey protein concentrates, vegetable fat emulsions, and precision fermentation bioactives. Single-source vulnerability in immunoglobulin supply threatens species-specific colostrum replacer production. Distribution runs through veterinary clinic procurement protocols, breeder cooperative aggregators, and telemedicine platform subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat. FDA feed ingredient review timelines and AAFCO nutritional adequacy protocols create switching costs that bind veterinary clinics to validated suppliers.
For Market Incumbents: Build certification moats through accelerated AAFCO verification investments and FSSC 22000 credential expansion. Precision fermentation entrants threaten immunoglobulin supply dominance; respond by securing exclusive spray-drying partnerships in Wisconsin and California dairy clusters. Channel control through telemedicine platform integration locks in breeder subscription revenue. For New Entrants and Emerging Players: Pursue ISO 22000 certification gaps among Eastern European suppliers seeking North American veterinary channel entry. The most penetrable segment is online direct-to-breeder subscriptions integrated with remote neonatal care consultations. A telemedicine platform partnership go-to-market angle bypasses distributor markups and captures millennial breeder demographics. For Investors and Strategic Acquirers: AAFCO nutritional adequacy protocol tightening reshapes the acquisition landscape toward clinical-validation-heavy assets. Long-term viability favors precision fermentation capabilities converging with conventional dairy processing. Target acquisition archetypes: species-specific formulation specialists with veterinary teaching hospital pilot relationships. The signal to watch is FDA novel protein source approval velocity as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| AAFCO Nutritional Adequacy Certification | Clinical validation investments raise barriers against home-prepared substitute erosion. |
| Precision Fermentation Partnership | Cultured immunoglobulin production virtualizes supply for colostrum replacers. |
| Telemedicine Platform Integration | Direct-to-breeder subscriptions bypass distributor intermediaries and capture recurring revenue. |
| Spray-Drying Infrastructure Expansion | Wisconsin and California dairy clusters repurpose human-grade capacity for animal nutrition contracts. |
| FSSC 22000 Certification Investment | Food safety credentials unlock retail and export channel access for mid-tier suppliers. |
Methodological Framework
Desk research of FDA Center for Veterinary Medicine filings, AAFCO model regulation updates, and dairy commodity trade data preceded structured interviews with veterinary neonatologists, large-scale breeding operation procurement directors, and specialty animal nutrition formulators. Primary fieldwork combined with secondary validation from ISO certification registries and veterinary teaching hospital pilot study disclosures. Bottom-up volume modeling triangulated against top-down category spending estimates.
Assumptions held fixed include FDA feed ingredient review timelines and AAFCO nutritional adequacy protocol enforcement intensity; variables tested included whey protein concentrate price trajectories and precision fermentation bioactive cost curves. Segmentation dimensions spanned product format, target animal species, distribution channel, and brand tier. CAGRs derived from logistic diffusion modeling of veterinary protocol standardization and breeder cooperative purchasing concentration. Industry-specific inputs incorporated neonatologist board certification rates and spray-drying capacity utilization in dairy processing clusters.
Sensitivities concentrate around FDA novel protein source approval velocity, dairy commodity price volatility, and telemedicine platform regulatory classification. Forecasts reflect documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Food and Infant Formula
Parenteral Formula Market
Baby Food and Infant Formula
Infant Food Compliance Ready Fertility Input Market
Baby Food and Infant Formula
Human Milk Oligosaccharides in Infant Formula Market
Baby Food and Infant Formula
Vietnam Pet Food Market
Baby Food and Infant Formula
Indonesia Infant Nutrition Market
Baby Food and Infant Formula
Cow Milk Infant Formula Market
Baby Food and Infant Formula
Baby Formula Ingredients Market
Baby Food and Infant Formula
Infant Formula Market
Baby Food and Infant Formula
Middle-Aged and Elderly Milk Powder Market
Baby Food and Infant Formula
Europe Baby Food and Infant Formula Market
Baby Food and Infant Formula
North America Baby Food Market
Baby Food and Infant Formula
Asia Pacific Organic Baby Food Market
Baby Food and Infant Formula
Middle East and Africa Baby Food Market
Baby Food and Infant Formula
Canada Baby Food Market
Baby Food and Infant Formula
Infant Formula Milk Powder with A2 Beta-Casein Market
Baby Food and Infant Formula
South America Baby Food Market