
 Global Truffle Market | 2026-2036
Global Truffle Market Size, Share, and Industry Trends Forecast 2026-2036
Global Truffle Market Outlook
A capital-intensity divergence between plantation-scale cultivators and wild-foraging cooperatives is redrawing competitive boundaries in the truffle sector. Urbani Truffles leverages vertical integration from Italian sourcing to international distribution, controlling quality across the value chain. PLANTIN Truffles anchors its position through deep relationships with Provençal foragers, sustaining supply reliability despite climatic volatility. Tartufi Morra competes on brand heritage in Piedmont, where it dominates premium white truffle auctions.
Truffles are ectomycorrhizal fungi of the genus Tuber, forming symbiotic relationships with host tree roots and requiring specific soil pH between 7.5 and 8.3, adequate calcium content, and Mediterranean climate patterns for fruiting; they serve primarily as aromatic culinary ingredients commanding substantial price premiums in fine dining. Black truffles occupy the largest volume share due to successful cultivation in France, Spain, and Australia, though white truffles from Piedmont command the highest per-kilogram margins. Direct sales channels to Michelin-starred restaurants capture disproportionate value, while online sales represent the fastest-expanding distribution vector as authenticated digital marketplaces reduce intermediary layers.
The EU's Geographical Indication framework and France's Institut National de la Propriété Industrielle enforce origin labeling that constrains market access for non-designated suppliers, while the FDA's food safety protocols for imported fresh fungi shape US entry requirements. EFSA mycotoxin thresholds and national phytosanitary inspections from Italy's Ministry of Health further tighten compliance burdens for cross-border traders. Stakeholders must monitor climate adaptation in emerging cultivation zones and assess whether plantation yields from Australia and Chile will erode European price premiums before committing long-term supply contracts.
Market Dynamics
Plantation-scale cultivation is disrupting centuries-old wild-foraging dominance, as climate volatility and maturing inoculation techniques compress supply timelines and erode traditional cooperative pricing power.
Growth Catalysts
- EU Geographical Indication protections:Designation frameworks for Périgord and Alba varieties create premium pricing tiers that incentivize quality investment and deter commodity substitution.
- Gastronomy channel expansion:Michelin-starred restaurants in France, Italy, and the United States are embedding truffle-infused tasting menus as signature differentiators, anchoring sustained volume commitments.
- Inoculated oak and hazelnut cultivation:Controlled mycorrhizal plantation methods are shortening fruiting cycles from decades to years, unlocking supply scalability previously constrained by wild harvest unpredictability.
Market Restraints
- Calcium-rich soil scarcity:Truffle fruiting demands specific pH and mineral profiles found predominantly in Mediterranean limestone basins, limiting viable expansion geography.
- Provençal forager cooperative concentration:PLANTIN Truffles and similar intermediaries maintain captive supply relationships that block new entrants from securing reliable wild harvest volumes.
- Fresh fungi phytosanitary barriers:Italy's Ministry of Health inspection protocols and EFSA mycotoxin thresholds impose cross-border compliance costs that disproportionately burden small-scale exporters.
Strategic Opportunities
- Australian plantation maturation:Manjimup and Tasmania cultivation zones are approaching commercial scale, offering Southern Hemisphere counter-seasonal supply that could capture Q2-Q3 demand windows.
- Authenticated digital marketplaces:Blockchain-verified provenance platforms are collapsing intermediary layers between Piedmont harvesters and direct-to-chef procurement channels.
- Chilean Andean foothills development:Emerging cultivation in Bio Bío and Maule regions leverages Mediterranean climate analogs with lower land costs than European alternatives.
Industry Challenges
- Trained canine detection scarcity:Lagotto Romagnolo breeding and scent-conditioning expertise concentrates in Italian and French rural communities, creating talent bottlenecks for new plantation operators.
- Multi-year cultivation capex cycles:Inoculated orchard establishment requires sustained irrigation and soil amendment investment before any revenue-generating fruiting occurs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Truffle Market |
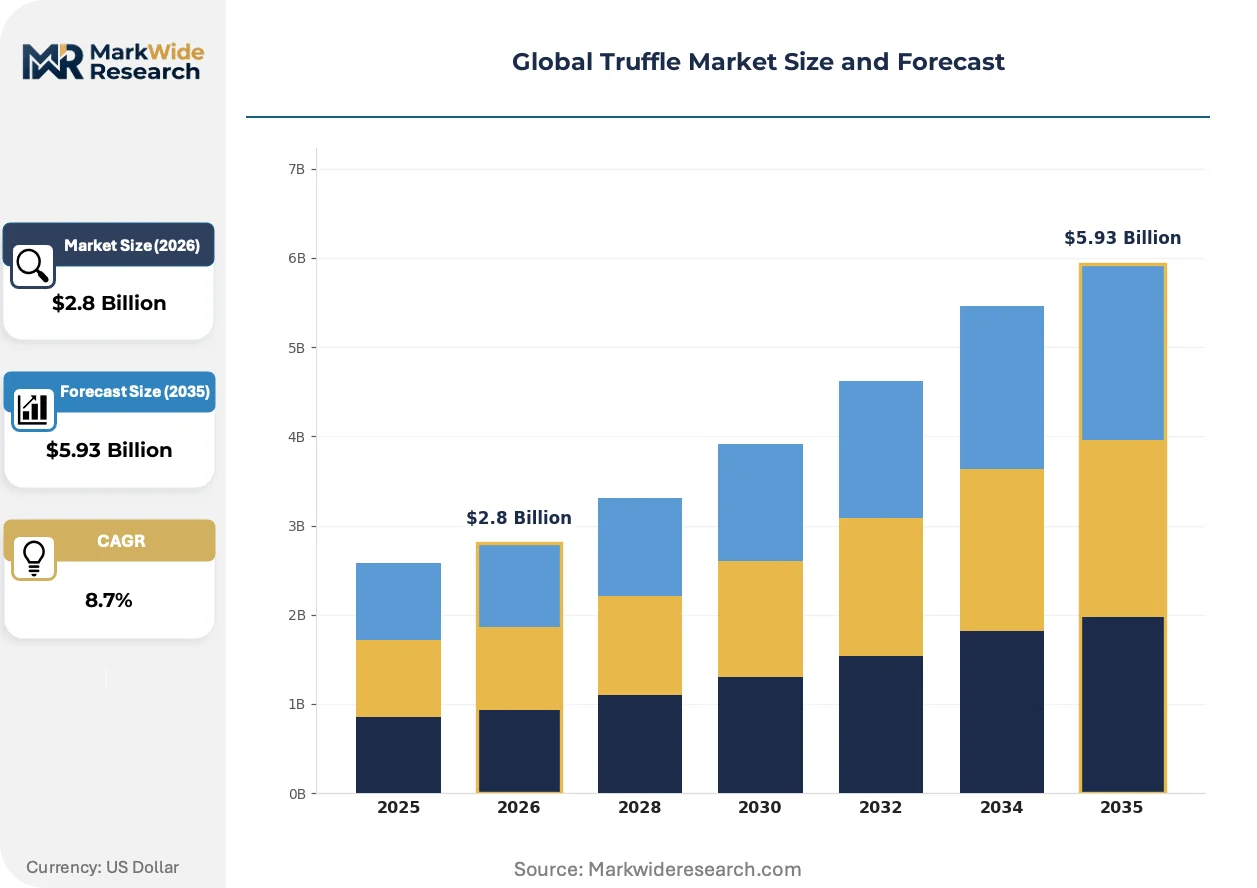
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Truffles, White Truffles, Summer Truffles, Bianchetto Truffles End User: Restaurants, Food Retailers, Online Marketplaces, Culinary Schools Distribution Channel: Direct Sales, Wholesalers, Online Sales, Specialty Stores Packaging Type: Vacuum Sealed, Jars, Cans, Bulk Packaging |
| Companies Covered | TruffleHunter, Inc., LES FRÈRES JAUMARD, Urbani Truffles, Tartufi Morra, PLANTIN Truffles, Arotz, SA, SABATINO NA LLC, The Welsh Truffle Co., Gazzarrini Tartufi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Truffle Market Strategic Shifts
Biotechnology and climate adaptation are fragmenting traditional supply hierarchies while digital traceability tools compress transaction friction between origin and end-use.
CRISPR-assisted mycorrhizal strain selection is bifurcating the propagation landscape. French and Australian nursery operators are deploying marker-assisted breeding to accelerate Tuber melanosporum colonization rates. Laboratory-cultured inoculum is displacing traditional spore-slurry methods, enabling plantation developers to bypass the generational knowledge barriers that historically protected European foraging cooperatives.
REACH chemical registration and EFSA novel food pathways are tightening input scrutiny for truffle-derived flavor extracts. Synthetic biology firms seeking to replicate Tuber magnatum aroma compounds face extended toxicology review timelines. The regulatory burden falls heaviest on European processors attempting to commercialize lab-grown alternatives, driving capital toward verified natural provenance rather than bioidentical substitutes.
Chef procurement patterns are rotating toward contracted seasonal allocations. Direct sourcing agreements between Melbourne cultivators and Sydney fine-dining groups are replacing spot-market purchasing through wholesale intermediaries. This channel compression is most advanced in Australia, where plantation-scale supply predictability supports volume commitments impossible under European wild-harvest volatility.
Global Truffle Market Segmentation
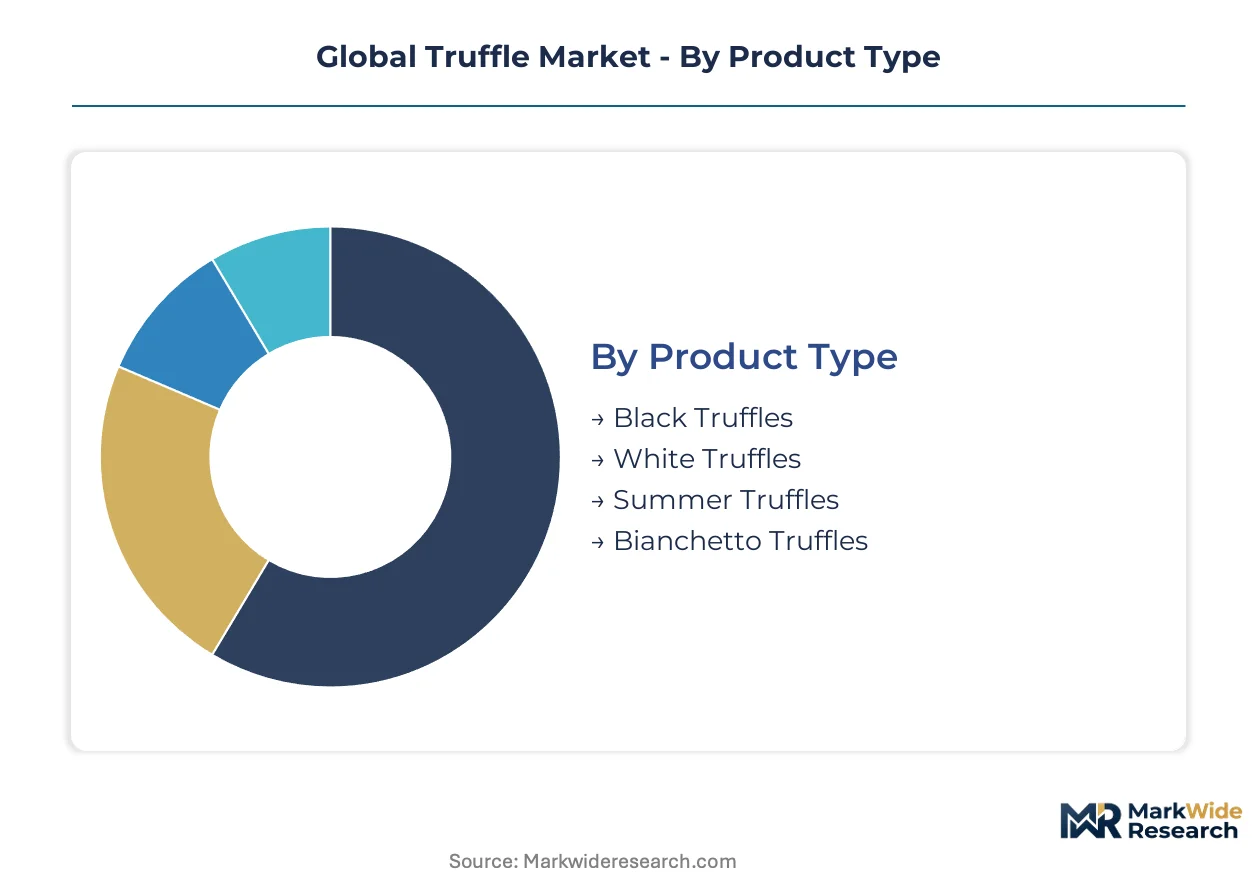
Truffle market segmentation reveals how value migrates through divergent supply chains. Product type determines cultivation feasibility and price architecture, while distribution channel selection governs margin capture and authentication requirements.
Product Type:
Channel-mix patterns diverge sharply across truffle varieties, with premium grades flowing through direct chef relationships while cultivated blacks penetrate broader wholesale networks.
- Black Truffles:Tuber melanosporum and Tuber aestivum dominate plantation-scale output in France, Spain, and Australia. Direct sales to Michelin-starred kitchens in Paris and Lyon capture premium tiers, though wholesale volumes supply processed food manufacturers seeking flavor extracts.
- White Truffles:Tuber magnatum from Piedmont's Alba district commands auction-based pricing through authenticated digital platforms. Supply constraints limit cultivation success; wild harvest dependence preserves cooperative intermediary dominance in Italian sourcing.
- Summer Truffles:Tuber aestivum offers entry-level aromatic intensity for casual dining applications. Italian and Croatian foraging cooperatives supply this grade through consolidated wholesale channels to European foodservice distributors.
- Bianchetto Truffles:Tuber borchii provides milder flavor profiles at accessible price points. Tuscan and Marche harvesters move this variety through specialty retailers and online authenticated marketplaces targeting home gourmets.
By volume, Black Truffles leads. By growth pace, White Truffles is ahead.
End User:
Cost-tier stratification separates institutional buyers committing to contracted allocations from transactional purchasers in volatile spot markets.
- Restaurants:Fine-dining establishments in France, Italy, and the United States anchor demand through seasonal menu embedding. Three-Michelin-star venues in Paris and New York maintain direct sourcing relationships with Périgord foraging cooperatives and Australian plantation operators.
- Food Retailers:Harrods, Eataly, and Dean & DeLuca curate authenticated provenance for affluent consumers. Shelf-life constraints favor preserved formats over fresh specimens in this channel.
- Online Marketplaces:Blockchain-verified platforms collapse intermediary layers between Piedmont harvesters and global buyers. This vector expands most quickly where plantation supply predictability enables volume commitments.
- Culinary Schools:Le Cordon Bleu and ALMA drive educational demand for training specimens. Procurement concentrates through specialty distributors offering mixed-grade assortments at institutional pricing.
Restaurants command the highest per-kilogram prices. Online Marketplaces are expanding most quickly.
Distribution Channel:
Margin capture potential inversely correlates with channel fragmentation, rewarding upstream control over downstream dispersal.
- Direct Sales:Plantation operators in Australia's Manjimup region and Tasmanian cultivation zones bypass intermediaries through chef-contracted allocations. This channel preserves quality authentication and captures full value-chain margin.
- Wholesalers:PLANTIN Truffles and similar Provençal intermediaries aggregate wild harvest from dispersed foraging cooperatives. Concentration in this tier blocks new entrants from securing reliable supply volumes.
- Online Sales:Digital platforms with provenance verification reduce transaction friction for remote buyers. Southern Hemisphere counter-seasonal supply from Chilean Andean foothills development projects targets this channel.
- Specialty Stores:Urban delicatessens in London, Tokyo, and Dubai serve expatriate and tourist demand. Inventory turnover challenges favor preserved formats with extended shelf stability.
Direct Sales yields the highest margins. Online Sales are climbing the fastest.
Packaging Type:
Application requirements and shelf-life specifications determine format selection across fresh and processed value chains.
- Vacuum Sealed:Modified-atmosphere packaging extends fresh truffle viability from days to weeks. Premium restaurants in Milan and Sydney specify this format for just-in-time delivery from Australian plantation maturation zones.
- Jars:Brined and oil-preserved specimens serve retail and foodservice processing applications. Italian conservators in Umbria and Abruzzo dominate this preservation tier.
- Cans:Heat-sterilized formats support industrial food manufacturing and extended distribution. Lower aromatic intensity limits this format to flavor base applications rather than finishing garnishes.
- Bulk Packaging:Ungraded mixed lots move through wholesale channels to processors and secondary sorters. French and Spanish intermediaries utilize this format for commodity-tier truffle derivatives.
Vacuum Sealed commands premium positioning. Jars are gaining share fastest in retail expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across consuming regions. French and Italian buyers absorb substantial premiums for designated-origin specimens, while Australian and Chilean procurement emphasizes volume predictability over provenance certification.
France
Michelin-starred kitchens in Paris and Lyon sustain demand for Périgord black truffles through contracted seasonal allocations. The Institut National de la Propriété Industrielle enforces Geographical Indication protections that constrain non-designated supply entry. The Périgord basin anchors wild harvest volumes, though Provençal cooperatives maintain intermediary control over dispersed forager networks.
Italy
Alba white truffle auctions command the highest per-kilogram margins globally, driven by Piedmont's concentration of traditional harvester cooperatives. The Ministry of Health imposes phytosanitary inspection protocols on cross-border fresh fungi shipments. Turin-based intermediaries leverage generational relationships with rural harvesters to secure premium-grade specimens ahead of competitive bidders.
Australia
Manjimup and Tasmanian plantation operators target Southern Hemisphere counter-seasonal supply windows with predictable cultivated output. The TGA's food safety standards govern domestic distribution and export certification requirements. Melbourne cultivators are contracting directly with Sydney fine-dining groups, bypassing wholesale intermediaries previously dominant in European sourcing.
Spain
Aragon and Catalonia cultivation zones are expanding black truffle orchard acreage with French inoculation technology licensing. The national agricultural ministry coordinates with EFSA on mycotoxin threshold compliance for intra-EU shipments. Saragossa-based nursery operators are scaling laboratory-cultured mycorrhizal inoculum production for domestic and export plantation developers.
United States
New York and San Francisco fine-dining establishments import fresh specimens under FDA food safety protocols for imported fungi. The agency's hazard analysis requirements shape supplier qualification timelines for European and Australian exporters. Manhattan-based specialty distributors curate authenticated provenance for three-Michelin-star venues with embedded truffle tasting menus.
Global Truffle Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with quality authentication and captive supply relationships determining tier membership. The upper tier commands full value-chain margin through backward integration into cultivation or forager networks. Three archetypes dominate: vertically integrated plantation operators, provenance-anchored intermediaries with cooperative relationships, and heritage-brand auction houses. Competitive moves center on geographic expansion into Southern Hemisphere counter-seasonal zones and technology licensing for accelerated mycorrhizal colonization.
Among European heritage specialists, Urbani Truffles, Tartufi Morra, and PLANTIN Truffles occupy positions reflecting distinct sourcing strategies. Urbani exemplifies the vertically integrated archetype with Italian-origin sourcing extending to international distribution control. Tartufi Morra represents the auction-house heritage model concentrated in Piedmont's premium white truffle segment. PLANTIN Truffles anchors the cooperative-relationship intermediary tier through deep Provençal forager network integration.
| Leading Market Players |
|---|
| TruffleHunter, Inc. |
| LES FRÈRES JAUMARD |
| Urbani Truffles |
| Tartufi Morra |
| PLANTIN Truffles |
| Arotz, SA |
| SABATINO NA LLC |
| The Welsh Truffle Co. |
| Gazzarrini Tartufi |
| Others |
Value Chain & Pricing Dynamics
Plantation-cultivated Tuber melanosporum is displacing wild-foraged Périgord supply in premium restaurant procurement, compressing seasonal price volatility while redrawing competitive geography toward Australia's Manjimup and Tasmania zones. This substitution simultaneously erodes traditional cooperative pricing power in France and anchors new contract-based allocation models that trade provenance premiums for volume predictability.
Pricing Analysis
Direct-to-chef service contracts and extended seasonal allocations drive lifetime value for plantation operators, displacing spot-market intermediation. Three-tier pricing structure across auction-grade Piedmont whites, designated-origin Périgord blacks, and cultivated Australian supply reflects certification intensity and harvest method. Cost compression in wholesale tiers intensifies as Chilean and Spanish plantation maturation expands black truffle availability. Michelin-starred kitchens in Paris and New York exhibit lowest price sensitivity, while casual dining processors face acute margin pressure from aromatic extract substitutes.
Supply Chain Analysis
Just-in-time procurement dominates fresh truffle logistics, with vacuum-sealed modified-atmosphere formats enabling 48-72 hour delivery windows from Australian plantations to Sydney and Singapore kitchens. Supply concentrates in France, Italy, and Australia, with emerging volume from Spain and Chile. Mycorrhizal inoculum, trained Lagotto Romagnolo detection dogs, and calcium-amended orchard soil constitute critical input dependencies. Single-source vulnerability runs through Provençal cooperative networks that gatekeep wild Périgord harvest. Distribution runs through authenticated digital marketplaces collapsing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic biology firms engineering Tuber magnatum aroma compounds pose imminent substitution threat to natural provenance premiums, demanding defensive positioning from heritage intermediaries and plantation operators alike.
For Market Incumbents: Consolidate captive supply relationships with Piedmont foraging cooperatives and Provençal harvester networks before Australian plantation scale erodes seasonal scarcity pricing. Invest in blockchain-verified provenance infrastructure to differentiate against bioidentical flavor substitutes entering European novel food review pathways. Priority levers include backward integration into nursery inoculum production and direct chef contracting in counter-seasonal Southern Hemisphere windows. For New Entrants and Emerging Players: White-space in authenticated home-gourmet digital channels offers penetration opportunity where heritage brands maintain weak direct-to-consumer presence. Target Chilean Andean foothills cultivation for Q2-Q3 Northern Hemisphere supply gaps, leveraging Mediterranean climate analogs with lower land costs than European alternatives. Go-to-market angle emphasizes plantation predictability enabling subscription-based seasonal allocations absent in volatile wild-harvest sourcing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed Australian plantation operators approaching commercial maturation without downstream brand infrastructure. Long-term viability hinges on whether designated-origin European protections sustain price premiums against scalable cultivated supply. Acquisition target archetype: vertically integrated Southern Hemisphere cultivators with direct chef relationships. Signal to watch is EFSA novel food pathway acceleration for lab-grown aroma alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Counter-Seasonal Supply Contracting | Australian plantation operators capture Q2-Q3 demand windows when European wild harvest lies dormant. |
| Blockchain Provenance Verification | Piedmont harvesters bypass wholesale intermediaries through authenticated digital marketplace direct sales. |
| Mycorrhizal Inoculum Scale-Up | French and Australian nursery operators accelerate Tuber melanosporum colonization via marker-assisted breeding. |
| Chef Procurement Platform Integration | Melbourne cultivators embed contracted allocations into Sydney fine-dining group seasonal menu planning. |
| Novel Food Regulatory Defense | European heritage specialists lobby EFSA to extend toxicology timelines for synthetic biology aroma competitors. |
Study Parameters
Desk research of EU Geographical Indication filings, EFSA mycotoxin threshold documentation, and Australian TGA food safety standards preceded structured interviews with plantation operations managers, Provençal foraging cooperative leaders, Michelin-starred executive chefs, specialty distributor procurement heads, and Lagotto Romagnolo breeding program directors. Secondary validation drew from customs trade databases, national agricultural ministry harvest statistics, and SEC filings of publicly listed foodservice distributors. Bottom-up volume modeling triangulated against top-down expenditure analysis across identified end-use segments.
Variance decomposition across product type, distribution channel, and regional regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include truffle variety, cultivation method, buyer tier, and authentication intensity. CAGRs derived from S-curve adoption patterns for plantation supply and price elasticity functions for designated-origin specimens. Industry-specific forecast inputs encompass climate volatility indices for Mediterranean limestone basins and Lagotto Romagnolo breeding program expansion rates.
Forecasts assume regulatory continuity in EU Geographical Indication enforcement and FDA fresh fungi import protocols; material policy shifts would require re-modeling. Specific risks include EFSA novel food pathway acceleration for synthetic aroma compounds and Australian drought impacts on Manjimup irrigation-dependent orchards. Revision becomes warranted when plantation supply from Southern Hemisphere sources crosses thresholds that erode European price premiums.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Cat Food Toppings Market
Specialty Foods
Halal Products Market
Specialty Foods
Vegetarian Taquitos Market
Specialty Foods
Gluten-Free Desserts and Ice Creams Market
Specialty Foods
Global Guilt-Free Desserts Market
Specialty Foods
Global Bee Products Market
Specialty Foods
Dill Juice Market
Specialty Foods
Marine Thermal Water Ferments Market
Specialty Foods
Edible Cutlery Market
Specialty Foods
Thai Cuisine Market
Specialty Foods
Acacia Honey Market
Specialty Foods
Honey Spread Market
Specialty Foods
CBD-Infused Ice Cream Market
Specialty Foods
Kosher Food Market
Specialty Foods
Brahmi Market
Specialty Foods
Low-Fat Low-Calorie Desserts Market