
 Asia Pacific Cat Food Market | 2026-2036
Asia Pacific Cat Food Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Cat Food Market Insights
Human-grade ingredient processing is fragmenting traditional supply chains into parallel cold-chain and dry-mix networks across the Asia Pacific. Mars Incorporated leverages captive sourcing of animal proteins to secure batch consistency in wet food lines. Nestle S.A. (Purina) anchors its regional position through veterinary prescription channels. Unicharm Corporation dominates Japan's treat segment via convenience-store distribution density.
Asia Pacific cat food comprises nutritionally formulated products meeting feline obligate carnivore requirements, typically containing minimum crude protein thresholds, taurine supplementation, and moisture levels ranging from dry kibble below 10% to wet formats exceeding 75%. Dry food remains the volume base due to shelf stability and lower logistics costs, while raw and fresh formats represent the fastest-expanding margin pool as cold-chain infrastructure penetrates urban Southeast Asia. Ingredient quality tiers—natural, organic, and grain-free—now command price multiples that reshape manufacturer portfolio priorities.
Japan's Ministry of Agriculture, Forestry and Fisheries enforces strict labeling and contaminant standards, while China's National Feed Industry Standardization Technical Committee governs pet food formulation under broader feed safety frameworks. Australia's Department of Agriculture, Fisheries and Forestry administers import biosecurity protocols that constrain raw ingredient sourcing flexibility. Stakeholders must monitor regulatory divergence across these jurisdictions to avoid reformulation costs and market exclusion.
Market Dynamics
Human-grade ingredient certification is virtualizing traditional manufacturing boundaries across the Asia Pacific cat food sector, forcing parallel cold-chain investments alongside legacy dry-mix infrastructure as urban pet owners reject commodity-grade sourcing.
Growth Catalysts
- Japan's MAFF Labeling Revisions:Mandatory contaminant disclosure and origin traceability requirements are compressing informal supplier networks and accelerating formal channel consolidation.
- Single-Person Household Multiplication:China's tier-one cities generate concentrated demand for portion-controlled wet formats as companion animal roles displace traditional family structures.
- Raw Format Cold-Chain Penetration:Southeast Asian urban logistics infrastructure now supports fresh and frozen distribution, unlocking margin pools previously constrained by spoilage risk.
Market Restraints
- Animal Protein Input Volatility:Captive sourcing requirements for batch-consistent wet food lines expose manufacturers to livestock commodity price swings and avian influenza quarantine disruptions.
- Australian Biosecurity Protocol Rigidity:The Department of Agriculture, Fisheries and Forestry's import restrictions on unprocessed animal tissues constrain raw ingredient flexibility and extend lead times.
- Feed-Grade versus Food-Grade Facility Duality:China's National Feed Industry Standardization Technical Committee governs pet food under broader feed safety frameworks, creating certification friction for human-grade positioning.
Strategic Opportunities
- Veterinary Prescription Channel Expansion:Therapeutic and renal-specific formulations distributed through clinic networks capture price multiples unavailable in mass retail.
- Convenience-Store Distribution Density:Japan's treat segment demonstrates how high-frequency impulse purchasing in 24-hour retail formats builds brand recognition without advertising scale.
- South Korean Premiumization Trajectory:Urban pet owner willingness to pay for organic and grain-free certifications supports three-tier pricing stratification across economy, standard, and super-premium levels.
Industry Challenges
- Dual Supply Network Capital Intensity:Parallel cold-chain and ambient-dry infrastructure requirements demand simultaneous investment in incompatible logistics systems without guaranteed volume migration.
- Cross-Jurisdictional Reformulation Risk:Divergent contaminant thresholds between Japan's MAFF, China's feed standards, and Australia's biosecurity protocols force SKU proliferation and inventory fragmentation.
- Taurine Stability Expertise Scarcity:Wet format processing requires precise thermal control to preserve amino acid bioavailability, constraining contract manufacturing options.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Cat Food Market |
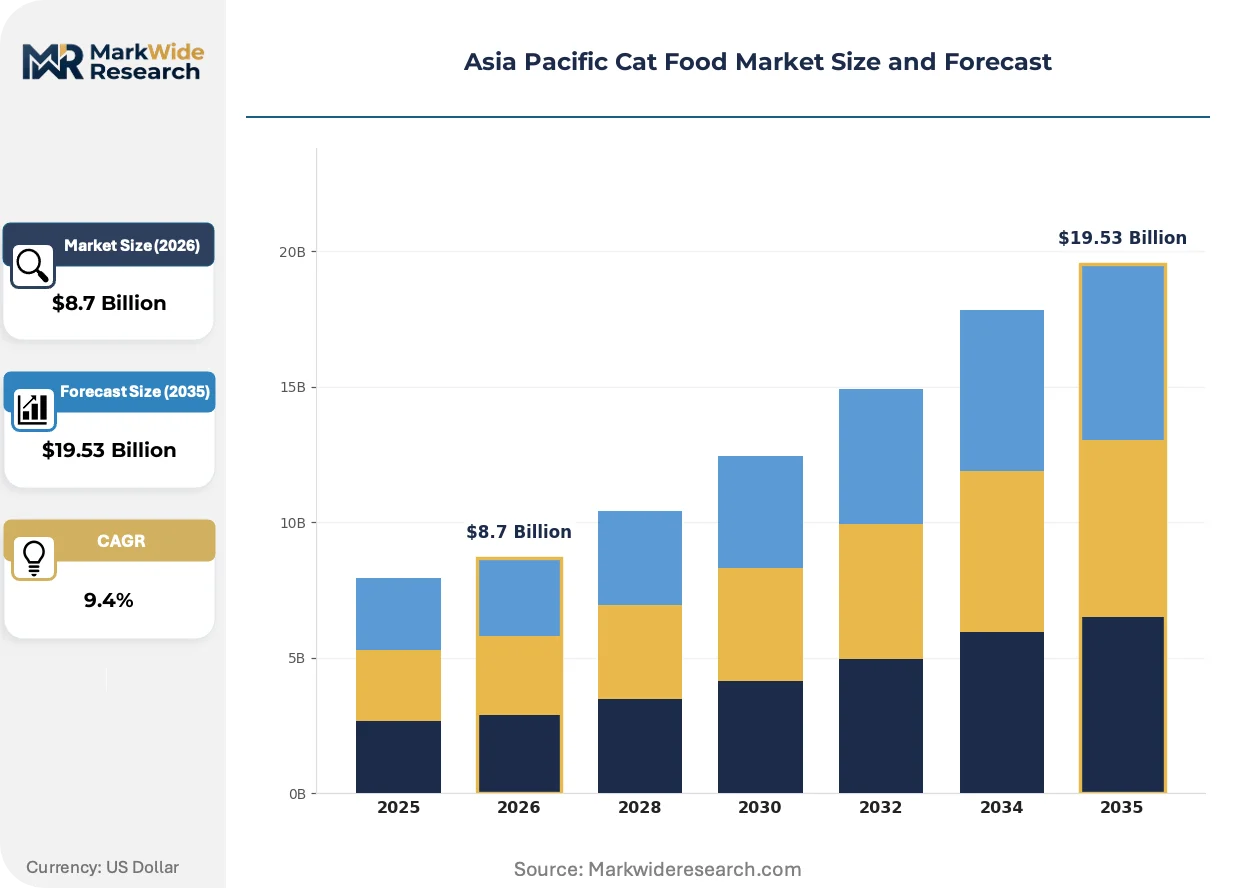
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Distribution Channel: Supermarkets, Online Retailers, Pet Specialty Stores, Convenience Stores Customer Type: Pet Owners, Breeders, Veterinarians, Shelters Ingredient Quality: Natural, Organic, Grain-Free, Others |
| Companies Covered | Colgate-Palmolive Company (Hill's Pet Nutrition Inc.), Mars Incorporated, Nestle S.A. (Purina), General Mills Inc., Archer Daniels Midland (ADM), Unicharm Corporation, Affinity Petcare SA, IB Group (Drools Pet Food Pvt. Ltd.), JM Smucker Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Cat Food Market Trends and Innovations
Ingredient transparency technologies and channel fragmentation are compressing traditional brand loyalty mechanisms, while regulatory divergence forces anticipatory compliance investments ahead of enforcement timelines.
Blockchain-enabled provenance tracking is virtualizing supply chain verification across the Asia Pacific cat food market. Premium-positioned manufacturers deploy distributed ledger systems to document farm-to-bowl traceability for human-grade protein claims. South Korean and Japanese urban consumers demand scan-accessible batch records, compressing trust-building timelines and displacing legacy quality assurance marketing.
China's National Feed Industry Standardization Technical Committee is tightening heavy metal and mycotoxin thresholds under revised GB standards. The industrial consequence is forced facility upgrades and third-party testing cost absorption for both domestic producers and import license holders. Wet food manufacturers sourcing fishmeal from regional aquaculture operations face the most acute compliance pressure and are consolidating supplier bases to reduce audit burden.
Subscription-based replenishment models are displacing supermarket bulk purchasing among China's tier-one city households. Digital-native brands bypass traditional distribution markups through direct-to-consumer apps with AI-driven portion forecasting. This behavioral shift is most visible in Shanghai and Beijing, where single-person households prioritize convenience over price comparison and generate predictable recurring revenue streams for formatted nutrition providers.
Asia Pacific Cat Food Market Segmentation
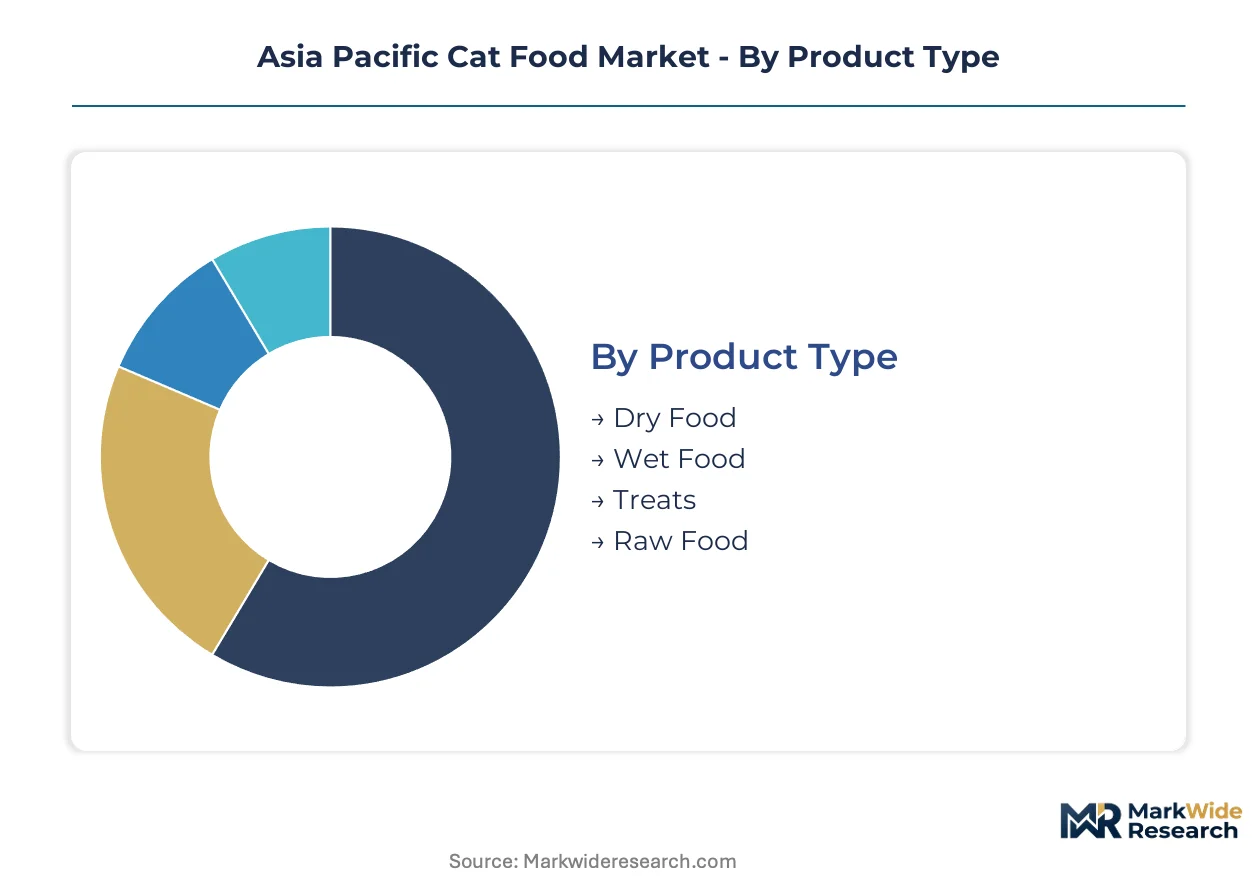
Asia Pacific cat food segmentation reveals how urbanization patterns and cold-chain maturity reshape product mix priorities. Manufacturers must align portfolio depth across moisture formats, channel access tiers, and ingredient certification levels to capture divergent willingness-to-pay across Tokyo apartments and Jakarta households.
Product Type:
Moisture content and shelf stability define the cost tier structure across feline nutrition formats.
- Dry Food:Kibble formats maintain moisture below 10% through extrusion, delivering shelf stability that minimizes last-mile logistics costs. Volume concentrates in China's tier-one cities where single-person households prioritize storage convenience and multi-week purchasing cycles.
- Wet Food:Cans and pouches exceed 75% moisture with taurine-supplemented protein slurries requiring precise thermal processing. Demand clusters in Japan's urban corridors where MAFF labeling compliance and portion-controlled single-serve formats align with aging pet owner demographics.
- Treats:High-frequency impulse formats leverage convenience-store distribution density in South Korean and Japanese 24-hour retail networks.
- Raw Food:Frozen and fresh formats depend on cold-chain penetration into Southeast Asian urban logistics infrastructure.
Dry food holds installed capacity. Wet food is rotating up the share rankings.
Distribution Channel:
Channel selection determines margin capture and customer relationship depth across the region's fragmented retail landscape.
- Supermarkets:Mass retail anchors volume throughput for economy-tier dry formats with standardized packaging and promotional pricing cycles. Shelf space allocation favors established brands with trade marketing budgets in Australia's Coles and Woolworths networks.
- Online Retailers:Direct-to-consumer platforms enable subscription replenishment with AI-driven portion forecasting among China's digital-native single-person households in Shanghai and Beijing.
- Pet Specialty Stores:Staff-assisted consultation drives therapeutic and prescription format attachment rates.
- Convenience Stores:High-frequency treat purchasing builds brand recognition without advertising scale in Japan's Lawson and 7-Eleven networks.
Supermarkets hold installed capacity. Online retailers are rotating up the share rankings.
Customer Type:
Purchasing authority and volume scale separate institutional buyers from discretionary household decision-makers.
- Pet Owners:Individual households drive premiumization through organic and grain-free certification willingness-to-pay in South Korean urban centers.
- Breeders:Volume purchasers prioritize batch consistency and growth-stage formulation precision for kitten development protocols.
- Veterinarians:Prescription channel gatekeepers capture price multiples for renal-specific and therapeutic formulations unavailable in mass retail.
- Shelters:Cost-optimized procurement concentrates in economy-tier dry formats with bulk pricing negotiations.
Pet owners hold installed capacity. Veterinarians are rotating up the share rankings.
Ingredient Quality:
Certification tiers command price multiples that reshape manufacturer sourcing priorities and facility investments.
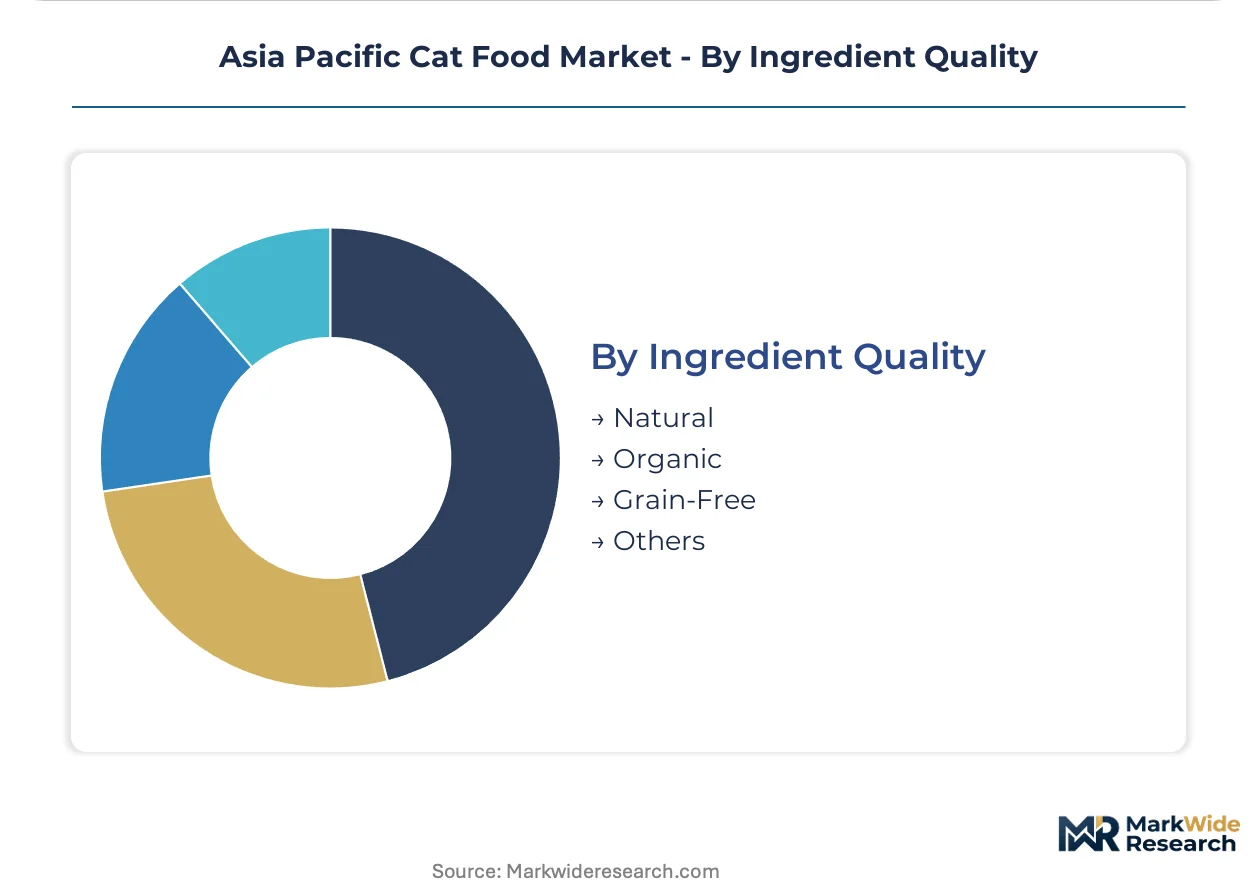
- Natural:Minimally processed ingredient claims require supply chain documentation without synthetic additive verification, occupying the mid-tier positioning between commodity and certified organic.
- Organic:Third-party certification mandates compliant livestock and crop sourcing with audit trails that extend lead times and compress supplier bases for wet food manufacturers.
- Grain-Free:Formulation excludes corn, wheat, and soy to address perceived carbohydrate sensitivity, driving tapioca and pea starch alternative sourcing in Thailand and Indonesia.
- Others:Human-grade and functional ingredient claims leverage blockchain-enabled provenance tracking for South Korean and Japanese urban consumers demanding scan-accessible batch records.
Natural holds installed capacity. Organic is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Single-person households in China's tier-one cities, aging pet owner demographics in Japan's urban corridors, and premiumization among South Korean urban consumers concentrate purchasing authority across distinct buyer archetypes with divergent format preferences.
China
Shanghai and Beijing generate concentrated demand for portion-controlled wet formats and subscription-based replenishment models as companion animal roles displace traditional family structures. The National Feed Industry Standardization Technical Committee governs pet food formulation under broader feed safety frameworks with tightening heavy metal and mycotoxin thresholds under revised GB standards. Yangtze River Delta manufacturing clusters absorb forced facility upgrades and third-party testing cost absorption for both domestic producers and import license holders.
Japan
Aging pet owner demographics in Tokyo and Osaka drive portion-controlled single-serve wet food attachment rates alongside treat purchasing in 24-hour retail networks. The Ministry of Agriculture, Forestry and Fisheries enforces strict labeling and contaminant standards with mandatory origin traceability requirements compressing informal supplier networks. Kanto region distribution infrastructure accelerates formal channel consolidation as MAFF compliance costs filter smaller competitors from veterinary prescription and mass retail channels.
South Korea
Urban pet owners in Seoul demonstrate willingness to pay for organic and grain-free certifications supporting three-tier pricing stratification across economy, standard, and super-premium levels. The Ministry of Food and Drug Safety regulates pet food safety with evolving standards for functional ingredient claims. Seoul Capital Area cold-chain penetration now supports fresh and frozen raw format distribution, unlocking margin pools previously constrained by spoilage risk in premium positioning strategies.
Australia
Coles and Woolworths networks anchor volume throughput for economy-tier dry formats with standardized packaging and promotional pricing cycles in mass retail. The Department of Agriculture, Fisheries and Forestry administers import biosecurity protocols that constrain raw ingredient sourcing flexibility and extend lead times. New South Wales and Victoria distribution centers manage the operational friction of livestock commodity price swings and avian influenza quarantine disruptions affecting captive sourcing requirements.
Thailand
Jakarta-connected Southeast Asian urban logistics infrastructure supports raw and fresh format expansion as cold-chain maturity penetrates beyond tier-one metropolitan boundaries. The country's national feed regulator maintains formulation standards under broader agricultural safety frameworks creating certification friction for human-grade positioning. Bangkok manufacturing clusters consolidate supplier bases to reduce audit burden for wet food manufacturers sourcing fishmeal from regional aquaculture operations facing acute compliance pressure.
Asia Pacific Cat Food Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures where mass retail shelf allocation, veterinary prescription gatekeeping, and convenience-store distribution density determine margin capture. The vendor base spans multinational consumer goods conglomerates with captive protein sourcing, regional specialists with veterinary channel anchoring, and digital-native brands with direct-to-consumer subscription infrastructure. Three archetypes dominate: scale-driven mass retail suppliers, premium-positioned cold-chain operators, and prescription-channel therapeutic formulators. Competitive moves concentrate on M&A for regional brand portfolios and parallel cold-chain infrastructure investments alongside legacy dry-mix capacity.
Within the multinational conglomerate tier, Mars Incorporated, Nestle S.A. (Purina), and Colgate-Palmolive Company (Hill's Pet Nutrition Inc.) occupy positions exemplifying divergent strategic anchors—captive protein sourcing for batch consistency, veterinary prescription channel anchoring, and therapeutic formulation specialization respectively. These entities represent scale-driven infrastructure deployment across incompatible logistics systems without guaranteed volume migration between ambient-dry and cold-chain networks.
| Leading Market Players |
|---|
| Colgate-Palmolive Company (Hill's Pet Nutrition Inc.) |
| Mars Incorporated |
| Nestle S.A. (Purina) |
| General Mills Inc. |
| Archer Daniels Midland (ADM) |
| Unicharm Corporation |
| Affinity Petcare SA |
| IB Group (Drools Pet Food Pvt. Ltd.) |
| JM Smucker Company |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta freight corridors impose cold-chain premiums that compress margins for human-grade wet food manufacturers while enabling three-tier price stratification between ambient-dry economy formats and frozen raw super-premium positioning across Shanghai and Beijing distribution nodes.
Pricing Analysis
Cost-plus contracts indexed to livestock commodity benchmarks dominate wet food procurement between Mars Incorporated and Australian protein suppliers, with taurine-supplemented formulations commanding certification premiums over feed-grade alternatives. Price differentiation rests on organic third-party verification and veterinary prescription channel access, with subscription-based direct-to-consumer models in China's tier-one cities showing lowest price sensitivity while Indonesian mass retail buyers drive cost compression in economy-tier dry kibble.
Supply Chain Analysis
Contract manufacturing capacity concentrates among Thailand's Bangkok processing clusters and Australia's New South Wales rendering facilities, with Mars and Nestle maintaining captive wet food lines alongside third-party thermal processing partnerships. Raw material dependencies center on Vietnamese fishmeal aquaculture operations, Australian mutton and poultry rendering streams, and South Korean organic livestock certification pools. Single-source vulnerability runs through Australian Department of Agriculture biosecurity clearances for unprocessed animal tissue imports. Distribution runs through Japan's Lawson convenience-store networks for treat formats and China's Tmall-JD direct-to-consumer platforms for subscription replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive positioning as blockchain-enabled provenance tracking and AI-driven portion forecasting create interoperability standards between ingredient verification systems and recurring revenue infrastructure across the Asia Pacific cat food ecosystem.
For Market Incumbents: Pre-empt digital-native subscription challengers by consolidating cold-chain infrastructure investments with veterinary prescription channel control, capturing the margin compression threat from direct-to-consumer AI forecasting platforms while anchoring therapeutic formulation gatekeeping through clinic network exclusivity. For New Entrants and Emerging Players: Jakarta-connected Southeast Asian urban corridors outside tier-one metropolitan boundaries offer raw format white-space expansion as cold-chain maturity penetrates secondary cities, with convenience-store treat distribution in Thailand's 24-hour retail networks presenting the most penetrable channel entry point alongside blockchain-verified human-grade protein positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors prescription-channel therapeutic formulators with captive taurine-stability processing expertise, as wet food thermal control capabilities scarcity constrains contract manufacturing options. Long-term viability across the analysis window hinges on cold-chain infrastructure ownership rather than brand equity alone. Watch for MFDS functional ingredient claim standardization in South Korea as the inflection signal for regulatory-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Seoul Capital Area penetration unlocks raw format margins previously constrained by spoilage risk. |
| Veterinary Prescription Channel Anchoring | Renal-specific formulation exclusivity through Japan's MAFF-compliant clinic networks captures price multiples. |
| Blockchain Provenance Integration | Farm-to-bowl traceability meets South Korean urban consumer demands for scan-accessible batch records. |
| Subscription Platform Development | AI-driven portion forecasting in Shanghai and Beijing generates predictable recurring revenue streams. |
| Organic Certification Investment |
Research Methodology
Operator-level perspectives from wet food plant managers, veterinary clinic procurement officers, convenience-store category buyers, and cold-chain logistics directors anchored the qualitative base, cross-referenced with MAFF filing databases, China's GB standard revision records, Australian biosecurity clearance logs, and Nielsen retail audit data across tier-one metropolitan markets. Bottom-up volume modeling triangulated against top-down macroeconomic consumption projections.
Scenario-bracketing around regulatory enforcement timelines and cold-chain infrastructure buildout rates structured the analytical framework across the projection horizon, with segmentation dimensions spanning moisture format tiers, ingredient certification levels, distribution channel types, and customer purchasing authority. CAGRs derived from elasticity-adjusted volume trajectory modeling incorporating livestock commodity price volatility and single-person household formation rates in China's urban centers.
Practitioners should monitor avian influenza quarantine disruptions, MAFF labeling revision enforcement intensity, and MFDS functional claim standardization for early signals of forecast deviation. Quarterly review of cold-chain infrastructure commissioning announcements and veterinary clinic network expansion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Gluten-Free Desserts and Ice Creams Market
Specialty Foods
Kosher Food Market
Specialty Foods
Global Cocoa Nibs Market
Specialty Foods
Edible Mushroom Market
Specialty Foods
Cannabis-Infused Burger Market
Specialty Foods
Moringa Products Market
Specialty Foods
Malaysia Manuka Honey Market
Specialty Foods
Morocco Couscous Market
Specialty Foods
Low Calorie Chocolate Desserts Market
Specialty Foods
Acacia Honey Market
Specialty Foods
CBD Snacks Market
Specialty Foods
Halal Market
Specialty Foods
Vegetarian Tacos Market
Specialty Foods
Soft Tofu Market
Specialty Foods
Middle East and Africa Yerba Mate Market
Specialty Foods
Goldenseal Market