
 Vegan Dressing Market | 2026-2036
Vegan Dressing Market Size, Share, and Industry Trends Forecast 2026-2036
Vegan Dressing Market Analytics
Foodservice procurement is realigning toward plant-forward menus as institutional buyers reduce conventional dairy exposure. B&G Foods Inc. leverages its retail distribution infrastructure to secure shelf placement in conventional grocers. Follow Your Heart differentiates through dedicated vegan manufacturing facilities that eliminate cross-contamination risks. Primal Kitchen specializes in avocado-oil-based formulations that command premium positioning in health-focused channels.
Vegan dressing denotes emulsified condiments formulated without animal-derived ingredients, typically stabilizing oil-in-water suspensions using plant-based lecithins, gums, or modified starches to achieve pourable viscosity between 500 and 5,000 centipoise. These products serve commercial kitchens and retail consumers seeking flavor delivery compatible with allergen-restricted, plant-based, or kosher dietary protocols. Balsamic vinaigrette and ranch variants anchor volume sales through familiar flavor profiles that reduce consumer trial barriers. Nut butters as a base ingredient represent the fastest-growing formulation category, as almond and cashew emulsions enable clean-label positioning without synthetic stabilizers. Bottle packaging dominates value capture due to higher unit economics and established filling line infrastructure, though pouches gain traction in foodservice bulk purchasing.
The FDA's Food Safety Modernization Act mandates preventive controls for acidified foods, directly affecting vegan dressing production protocols and facility validation requirements. USDA organic certification and Non-GMO Project verification operate as parallel gatekeeping systems that determine retail access in premium channels. Stakeholders must monitor evolving allergen labeling thresholds for sesame and tree nuts, as these ingredients feature prominently in next-generation formulations and carry emerging disclosure obligations.
Market Dynamics
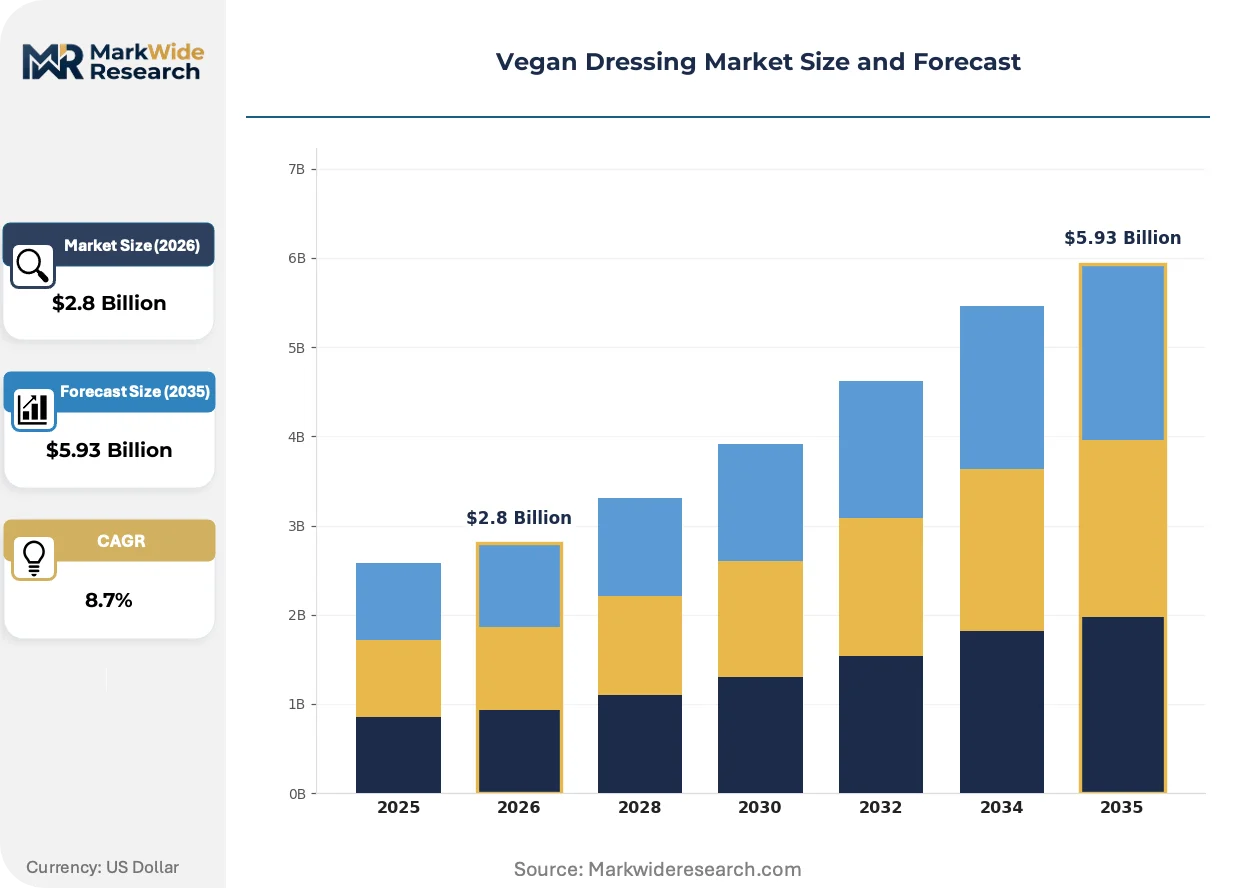
Clean-label formulation mandates are compressing synthetic stabilizer demand while accelerating nut-butter emulsion adoption across commercial kitchens and retail channels. EU Green Deal targets on sustainable food systems are forcing ingredient provenance documentation that reshapes sourcing relationships throughout the supply chain.
Growth Catalysts
- EU Green Deal sustainable food targets:Mandatory carbon footprint disclosure for foodservice procurement is redirecting institutional buyers toward plant-based condiments with verified supply chains. Member states are rewriting public tender specifications to favor allergen-compatible, animal-free formulations.
- Nut-butter emulsion technology:Almond and cashew base ingredients eliminate synthetic stabilizer dependencies while enabling clean-label positioning. Commercial kitchens are reformulating house-made dressings around these emulsions to meet disclosure requirements.
- Germany:Retail shelf space allocation for plant-based condiments has expanded significantly, creating visible category presence that reduces consumer trial barriers for unfamiliar vegan variants.
Market Restraints
- Tree nut input cost volatility:Almond and cashew commodity prices fluctuate with California and Vietnam harvest cycles, compressing margin stability for clean-label formulations dependent on these emulsion bases.
- Acidified food facility validation:FDA Food Safety Modernization Act preventive controls require dedicated production lines or complex changeover protocols, elevating capital barriers for multi-product manufacturers.
- Conventional dairy dressing substitution:Established ranch and Caesar variants in foodservice retain cost advantages and familiar flavor profiles that slow vegan conversion in price-sensitive institutional accounts.
Strategic Opportunities
- Foodservice bulk pouch distribution:Pouch packaging formats are gaining traction in institutional purchasing, enabling portion control and waste reduction that aligns with sustainability reporting requirements.
- Non-GMO Project verification channel access:Premium retail placement depends on third-party certification that operates as a parallel gatekeeping system alongside USDA organic standards.
- Sesame allergen labeling threshold evolution:Emerging disclosure obligations for sesame and tree nuts create first-mover positioning for manufacturers already featuring these ingredients prominently in next-generation formulations.
Industry Challenges
- Cross-contamination elimination protocols:Dedicated vegan manufacturing facilities require substantial capital investment to eliminate allergen risks, separating committed producers from conventional condiment manufacturers.
- Avocado oil supply security:Premium positioning in health-focused channels depends on stable access to avocado oil, which concentrates geographically and faces climate-driven harvest variability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegan Dressing Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balsamic Vinaigrette, Caesar, Ranch, Italian Base Ingredient: Olive Oil, Soy Milk, Avocado, Nut Butters Packaging Type: Bottle, Pouch, Jar, Spray Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Health Food Shops |
| Companies Covered | B&G Foods Inc., Litehouse Inc., Follow Your Heart, Sir Kensington's, Red Duck Foods Inc., Daiya Foods Inc., Meridian Foods Limited, Primal Kitchen, Amy's Kitchen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegan Dressing Market Evolving Landscape
Automation in emulsion processing is compressing batch-to-batch variability while enabling smaller production runs that serve niche dietary protocols. Regulatory disclosure requirements are forcing ingredient transparency that favors simple, recognizable formulations over complex stabilizer systems.
High-pressure processing technology is automating pathogen reduction in acidified vegan dressings without thermal degradation of flavor compounds. Mid-sized co-manufacturers are adopting these systems to serve emerging brands lacking captive pasteurization capacity. This automation is compressing the minimum viable scale for clean-label production, fragmenting what previously required centralized facilities.
EU Green Deal sustainable food system targets are mandating farm-to-fork traceability documentation that elevates supplier auditing burdens. Ingredient producers must now verify deforestation-free sourcing and carbon intensity metrics to retain foodservice contracts. German retail chains are responding by delisting suppliers unable to provide blockchain-verified provenance data for nut and oil inputs.
Restaurant procurement committees are consolidating vendor relationships around full-spectrum plant-based condiment suppliers capable of dressing, sauce, and marinade coverage. Multi-unit operators are displacing single-category distributors with broadline partners offering consolidated plant-forward portfolios. This concentration is most visible in US fast-casual chains where menu simplification priorities favor fewer, deeper supplier partnerships.
Vegan Dressing Market Segmentation
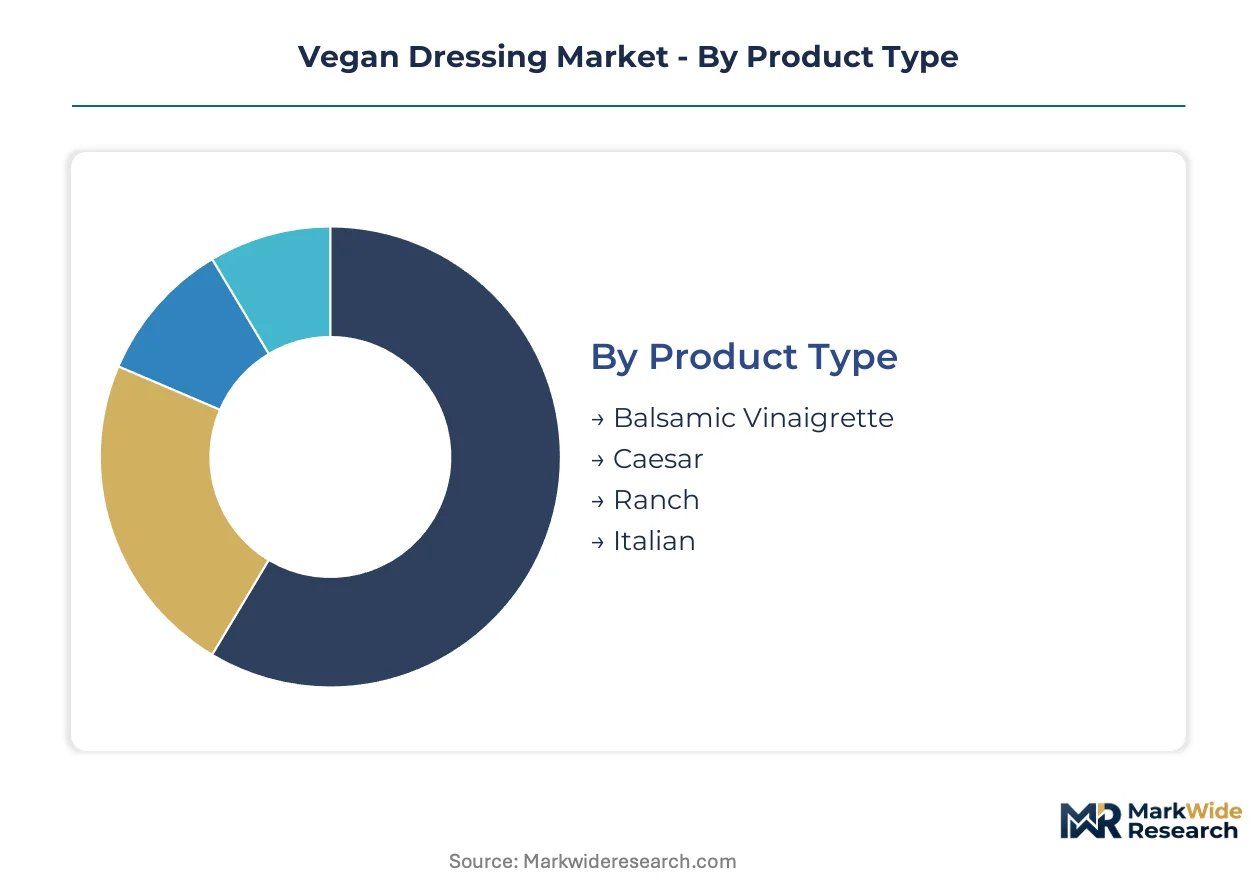
Vegan dressing segmentation reveals how formulation choices, packaging economics, and channel access determine competitive position. Manufacturers must align technical capabilities with buyer procurement priorities across retail and foodservice verticals.
Product Type:
Flavor familiarity drives trial conversion among conventional dressing users migrating to plant-based alternatives.
- Balsamic Vinaigrette:Acid-forward emulsions stabilized with plant-based lecithins achieve shelf-stable viscosity without egg yolk. German retail chains have expanded facings for this variant as entry-level vegan purchases concentrate in Mediterranean flavor profiles.
- Ranch:Buttermilk replacement through fermented oat or soy bases requires precise culture selection to replicate tang without dairy. Foodservice operators in the United States specify this variant for plant-based menu expansion due to its versatility across salad and wing applications.
- Caesar:Anchovy-free formulations depend on seaweed-derived umami compounds and nutritional yeast for depth. Clean-label positioning limits synthetic flavor enhancers in premium retail channels.
- Italian:Herb-forward oil-and-vinegar suspensions with minimal stabilizer requirements suit cost-sensitive foodservice procurement. Volume sits with Ranch; growth tilts toward Balsamic Vinaigrette.
Volume concentrates in Ranch for institutional buyers; premium retail expansion favors Balsamic Vinaigrette.
Base Ingredient:
Raw material sourcing geography and input cost stability separate formulation strategies.
- Nut Butters:Almond and cashew emulsions enable clean-label positioning without modified starches or synthetic gums. California harvest variability compresses margin predictability for manufacturers dependent on domestic almond supply.
- Avocado:Oil and puree bases command premium shelf placement in health-focused channels. Mexican and Peruvian sourcing concentration creates climate exposure for processors lacking diversified origin contracts.
- Olive Oil:Mediterranean-origin extra virgin grades anchor traditional vinaigrette formulations. EU Green Deal traceability mandates require blockchain-verified provenance documentation for retail access.
- Soy Milk:Cost-efficient emulsion bases suit economy-tier positioning and foodservice bulk formats. Genetic modification concerns limit placement in Non-GMO Project verified channels.
Cost structure favors Soy Milk; clean-label premiumization drives Nut Butter adoption fastest.
Packaging Type:
Unit economics and consumption occasion shape format selection across buyer segments.
- Bottle:Established filling infrastructure and higher price points dominate value capture in conventional retail. PET and glass formats serve distinct sustainability positioning requirements.
- Pouch:Flexible formats reduce shipping cube and enable precise portion control for foodservice operators. Waste reduction metrics align with institutional sustainability reporting obligations.
- Jar:Wide-mouth glass containers suit spoonable dressing textures and premium artisan positioning. Higher unit costs limit penetration beyond specialty retail.
- Spray:Aerosol and pump mechanisms enable precise application for oil-based variants. Manufacturing complexity restricts supplier base to specialized co-packers.
Bottle infrastructure dominates current capacity; pouch formats expand most quickly in foodservice procurement.
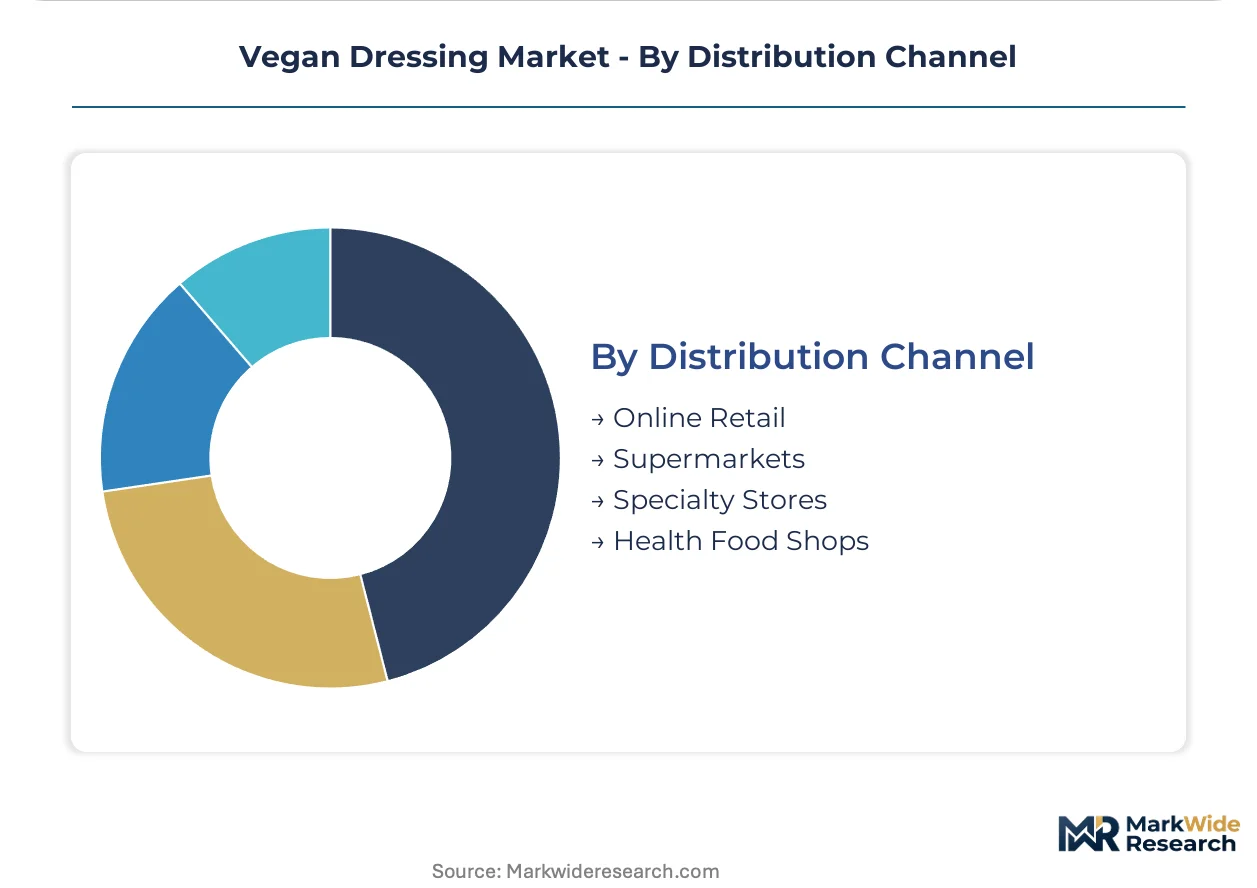
Distribution Channel:
Channel selection determines certification requirements, margin structure, and consumer education burden.
- Supermarkets:Conventional grocers demand slotting fees and promotional support that favor scaled manufacturers with broad SKU portfolios. Clean-label and organic certifications operate as table stakes for placement.
- Online Retail:Direct-to-consumer and marketplace platforms enable subscription models and flavor variety packs. Fulfillment economics favor lightweight pouch formats over glass bottles.
- Specialty Stores:Curated assortments in gourmet retailers prioritize provenance storytelling and small-batch credentials. Local and regional brands compete effectively against national players.
- Health Food Shops:Supplement and natural product retailers demand Non-GMO Project verification and allergen-free facility documentation. Staff recommendation drives trial among motivated health-conscious consumers.
Supermarket volume anchors manufacturer revenue; online retail climbs fastest as fulfillment infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Bioeconomy Strategy tax incentives have concentrated vegan dressing R&D in Baden-Württemberg and Bavaria, drawing formulation labs and pilot plants to specialized zones near Stuttgart and Munich.
United States
Foodservice procurement committees at fast-casual chains are consolidating vendor relationships around plant-forward portfolios. FDA Food Safety Modernization Act preventive controls for acidified foods elevate capital barriers for multi-product manufacturers. California's Central Valley anchors almond supply chains for nut-butter emulsion formulations, though harvest variability compresses margin predictability.
Germany
Retail chains have expanded shelf space allocation for plant-based condiments significantly, creating visible category presence that reduces consumer trial barriers. EU Green Deal sustainable food system targets mandate farm-to-fork traceability documentation, elevating supplier auditing burdens. Berlin-Brandenburg clusters house blockchain-verified provenance startups serving nut and oil input documentation needs.
United Kingdom
Supermarket slotting fee structures favor scaled manufacturers with broad SKU portfolios able to absorb promotional support costs. EFSA novel food regulations govern seaweed-derived umami compounds entering Caesar formulations without anchovy. London/Southeast concentrates specialty retail and gourmet channel headquarters demanding small-batch credentials.
France
Mediterranean-origin extra virgin olive oil grades anchor traditional vinaigrette formulations with established consumer recognition. EU Green Deal carbon footprint disclosure requirements redirect institutional procurement toward verified supply chains. Île-de-France hosts major foodservice distributor headquarters consolidating plant-based condiment purchasing.
Canada
Health Canada allergen labeling thresholds for sesame and tree nuts create first-mover positioning for manufacturers featuring these ingredients prominently. USDA organic certification and Non-GMO Project verification operate as parallel gatekeeping systems for premium retail access. Ontario's food processing corridor attracts co-manufacturers adopting high-pressure processing technology for pathogen reduction.
Vegan Dressing Market Competitive Landscape
Top-tier vendors anchor conventional retail distribution, while mid-tier specialists occupy clean-label and allergen-free niches. The vendor base stratifies across three tiers: multinational condiment conglomerates with slotting fee capacity, dedicated vegan manufacturers with captive facilities, and emerging brands leveraging co-manufacturing partnerships. Strategic archetypes include retail infrastructure maximizers, clean-label formulators, and foodservice bulk specialists. Dominant competitive moves span M&A for distribution access and capacity expansion into dedicated allergen-free production lines.
Among North American-based operators, B&G Foods Inc. and Follow Your Heart occupy distinct archetype positions. B&G Foods represents the retail infrastructure maximizer, leveraging established conventional grocer relationships for shelf placement. Follow Your Heart exemplifies the dedicated vegan manufacturer archetype through facility investments eliminating cross-contamination risks. Primal Kitchen anchors the premium health-channel specialist position with avocado-oil-based formulations. Meridian Foods Limited represents European clean-label formulation capabilities, while Sir Kensington's occupies the emerging brand tier utilizing co-manufacturing partnerships for scale.
| Leading Market Players |
|---|
| B&G Foods Inc. |
| Litehouse Inc. |
| Follow Your Heart |
| Sir Kensington's |
| Red Duck Foods Inc. |
| Daiya Foods Inc. |
| Meridian Foods Limited |
| Primal Kitchen |
| Amy's Kitchen Inc. |
| Others |
Value Network & Pricing Analysis
High-pressure processing automation is compressing minimum viable production scale while redistributing cost economics toward mid-sized co-manufacturers and fragmenting supply concentration away from centralized pasteurization facilities. This technology shift simultaneously enables smaller batch clean-label production and intensifies price competition as barrier-to-entry thresholds fall.
Pricing Analysis
Short lead-time premiums apply to nut-butter emulsion formulations dependent on California almond harvest cycles, while spot inventory discounts emerge for soy-based economy tiers with stable commodity inputs. Three-tier pricing structure across premium, standard, and economy levels separates avocado-oil-based health-channel positioning from olive oil Mediterranean grades and soy milk foodservice bulk. Pricing pressure stems from tree nut input cost volatility compressing margin stability for clean-label manufacturers. Foodservice institutional buyers exhibit highest price sensitivity; health food shop consumers demonstrate lowest sensitivity due to certification-driven loyalty.
Supply Chain Analysis
EU Green Deal farm-to-fork traceability mandates and FDA Food Safety Modernization Act preventive controls operate as parallel qualification gates determining supplier eligibility for retail and foodservice contracts. Ingredient sourcing concentrates in California for almond supply, Vietnam for cashew inputs, and Mexico-Peru for avocado oil. Raw material dependencies rest on tree nut harvest cycles, plant-based lecithin availability, and acidified food-grade packaging. Single-source vulnerability runs through California Central Valley almond concentration exposed to climate-driven harvest variability. Distribution feeds from co-manufacturer networks through broadline foodservice distributors and conventional retail slotting-fee channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nut-butter emulsion technology is displacing synthetic stabilizer systems as the dominant formulation platform, creating transition-phase winners among clean-label adopters and stranded cost risk for legacy modified-starch-dependent producers.
For Market Incumbents: Deepen backward integration into dedicated allergen-free manufacturing facilities to eliminate cross-contamination risks that separate committed vegan producers from conventional condiment manufacturers facing FDA validation barriers. Expand captive high-pressure processing capacity to defend margin position against co-manufacturer cost compression. Prioritize EU Green Deal traceability documentation investments to retain German retail chain listings as blockchain-verified provenance becomes mandatory. For New Entrants and Emerging Players: Capture foodservice bulk pouch distribution white space where institutional sustainability reporting requirements align with waste reduction metrics and portion control demand. Target Germany's expanded retail shelf space allocation for plant-based condiments where visible category presence reduces consumer trial barriers for unfamiliar variants. Deploy Non-GMO Project verification as primary go-to-market credential to unlock health food shop channel access. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational condiment conglomerates seeking slotting fee capacity and plant-forward portfolio expansion. Long-term viability across the analysis window favors dedicated vegan manufacturers with captive facilities over co-manufacturing-dependent emerging brands facing capacity constraints. Watch for FDA sesame allergen labeling threshold finalization as inflection signal creating first-mover positioning for tree nut-forward formulation specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Dedicated Allergen-Free Facility Investment | Eliminates cross-contamination risks and satisfies FDA preventive control mandates for acidified foods. |
| Blockchain-Verified Provenance Documentation | Secures German retail listings under EU Green Deal farm-to-fork traceability requirements. |
| High-Pressure Processing Technology Adoption | Enables pathogen reduction without thermal degradation for clean-label flavor preservation. |
| Foodservice Bulk Pouch Format Expansion | Aligns with institutional sustainability reporting and waste reduction procurement criteria. |
| Non-GMO Project Verification Channel Push | Unlocks premium placement in health-focused retail channels with staff recommendation influence. |
Research Methodology
Trade publications, regulatory filings, and customs records formed the secondary backbone, supplemented by Nielsen retail audit data and EU agricultural statistics. Primary interviews with foodservice procurement directors, plant-based R&D formulators, co-manufacturer operations managers, and retail category buyers validated secondary findings. Bottom-up and top-down triangulation cross-referenced production capacity estimates against channel shipment data.
Bottom-up modeling built from individual SKU velocity and production run economics, while top-down analysis anchored macro trends against EU Green Deal implementation timelines and FDA rulemaking schedules. Segmentation dimensions spanned flavor profile, base ingredient technology, packaging format, and distribution channel. CAGRs derived from weighted average of historical trajectory and technology adoption curve inflection points. Forecast inputs incorporated almond harvest cycle variability and high-pressure processing capacity expansion rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to tree nut commodity price volatility and EU traceability mandate enforcement intensity. Model outputs reflect assumptions on clean-label adoption velocity and foodservice procurement committee consolidation pace. A model refresh is warranted upon material change in FDA acidified food facility validation requirements or California Central Valley water allocation policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Jams, Jellies & Preserves Market
Specialty Foods
Low Calorie Chocolate Desserts Market
Specialty Foods
Triphala Powder Market
Specialty Foods
CBD Snacks Market
Specialty Foods
Asia-Pacific Tofu Market
Specialty Foods
Low Calorie Hummus Market
Specialty Foods
North America Alcohol-Infused Ice Cream Market
Specialty Foods
Sofrito Market
Specialty Foods
Brahmi Market
Specialty Foods
Organic Skin Care Market
Specialty Foods
Medicinal Herbs Market
Specialty Foods
Superfood Bars Market
Specialty Foods
Non-GMO Food Products Market
Specialty Foods
Global Cocoa Nibs Market
Specialty Foods
Low Calorie Veggie Dip Market
Specialty Foods
Space Food Market