
 Cat Food Flavors Market | 2026-2036
Cat Food Flavors Market Size, Share, and Industry Trends Forecast 2026-2036
Cat Food Flavors Market Outlook
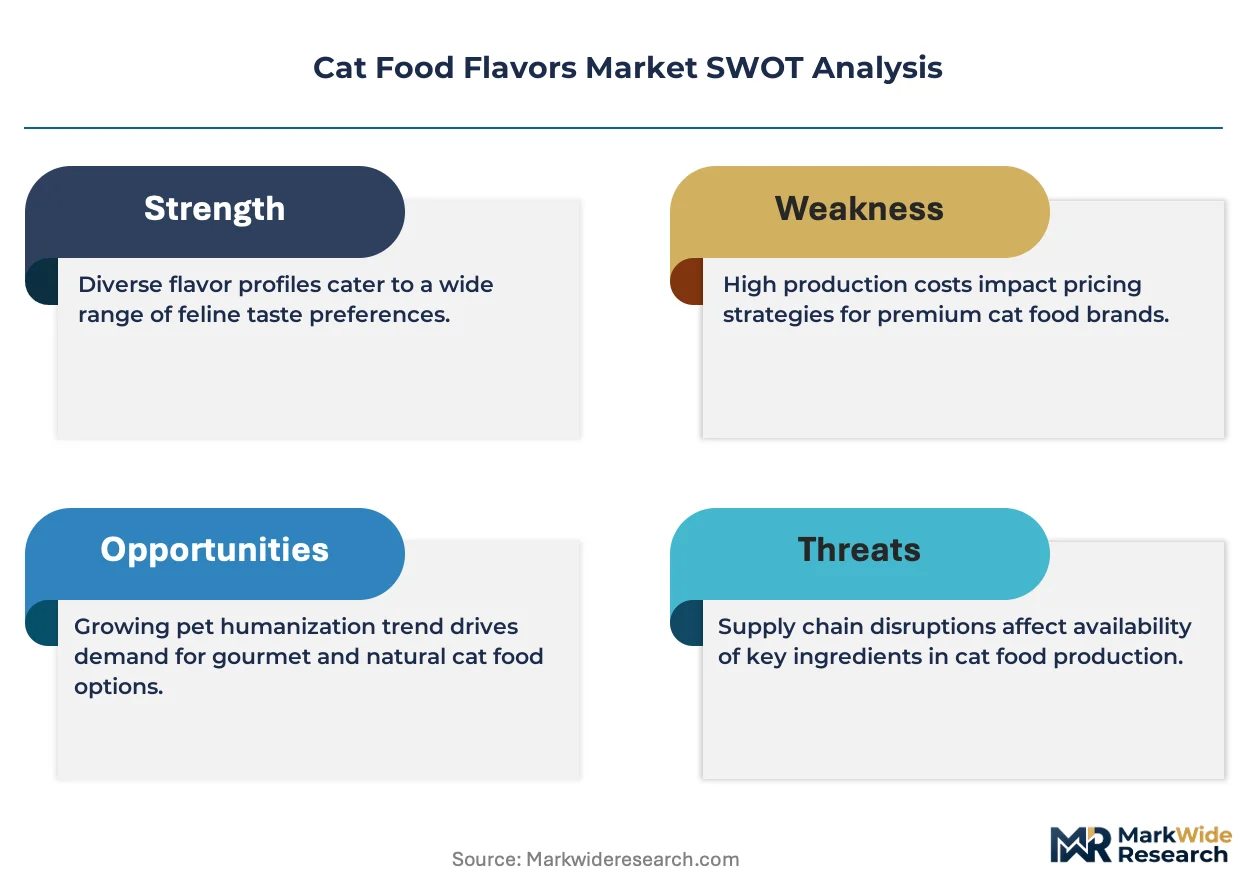
Aftermarket subscription services for personalized flavor rotations is reshaping how brands capture lifetime value from feline households. Mars Petcare leverages its global manufacturing footprint to sustain cost advantages across multiple texture formats. Nestlé Purina PetCare anchors North American distribution through veterinary and mass retail channels. Blue Buffalo differentiates via grain-free positioning and premium ingredient storytelling that commands shelf price premiums.
Cat food flavors encompass palatant systems, broth coatings, and dried protein meals engineered to enhance feline olfactory acceptance and meal completion rates, typically formulated at moisture levels between 6% and 78% depending on texture class. The primary commercial purpose is to reduce feeding refusal and support nutritional compliance in companion animals with selective taste preferences. Fish-based flavor variants occupy mature volume positions in wet and pate textures, while chicken formulations lead dry kibble segments due to cost-efficient protein sourcing and broader digestive tolerance. Premium ingredient quality tiers, particularly grain-free and organic certifications, concentrate margin pools as consumers trade up from economy positioning.
The FDA's Center for Veterinary Medicine enforces ingredient safety and facility registration requirements that elevate compliance costs for flavor suppliers entering the U.S. market. AAFCO model regulations on complete and balanced claims directly constrain how manufacturers label flavor benefits versus nutritional adequacy. The USDA's oversight of meat and poultry ingredients used in pet food further shapes sourcing geography and supply chain documentation burdens. Stakeholders must monitor evolving state-level raw feeding restrictions and clean-label litigation trends that could redirect formulation investment toward synthetic-free palatant alternatives.
Market Dynamics
Pet humanization among urban millennials is compressing traditional texture hierarchies as households trade volume for premiumization, forcing reformulation investments across moisture classes and palatant systems.
Growth Catalysts
- AAFCO nutrient profile updates:Tightened complete-and-balanced labeling standards are elevating formulation expertise barriers, advantaging suppliers with in-house veterinary nutrition teams.
- Subscription flavor rotation services:Direct-to-consumer platforms are capturing recurring revenue streams by automating variety-seeking behavior in multi-cat households.
- Freeze-dried protein inclusions:Raw-adjacent formats are expanding addressable demand among owners seeking minimal processing without home-prepared safety risks.
Market Restraints
- Animal protein input volatility:Wild-caught fishmeal and rendered poultry meal prices fluctuate with commodity cycles, compressing margin predictability for mid-tier producers.
- Midwest rendering concentration:Over half of U.S. poultry meal supply originates from a three-state corridor, creating geographic vulnerability to weather and logistics disruptions.
- Palatant patent thickets:Proprietary nucleotide and hydrolysate formulations lock incumbents into licensing structures that deter new flavor house entry.
Strategic Opportunities
- Insect protein regulatory tailwind:EFSA novel food approvals for black soldier fly larvae are opening formulation pathways with lower environmental footprints than conventional livestock.
- Veterinary therapeutic channel expansion:Prescription flavor profiles for renal and diabetic management diets command price multiples through clinic-exclusive distribution.
- AI-driven preference mapping:Machine learning analysis of individual cat consumption patterns enables hyper-personalized flavor recommendations at household level.
Industry Challenges
- Palatant chemist talent scarcity:Formulation science expertise sits concentrated among retiring cohorts at legacy flavor houses, constraining R&D velocity for emerging suppliers.
- Clean-label certification timelines:USDA organic and Non-GMO Project verification processes extend 14-18 months, delaying premium product launches behind competitor windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cat Food Flavors Market |
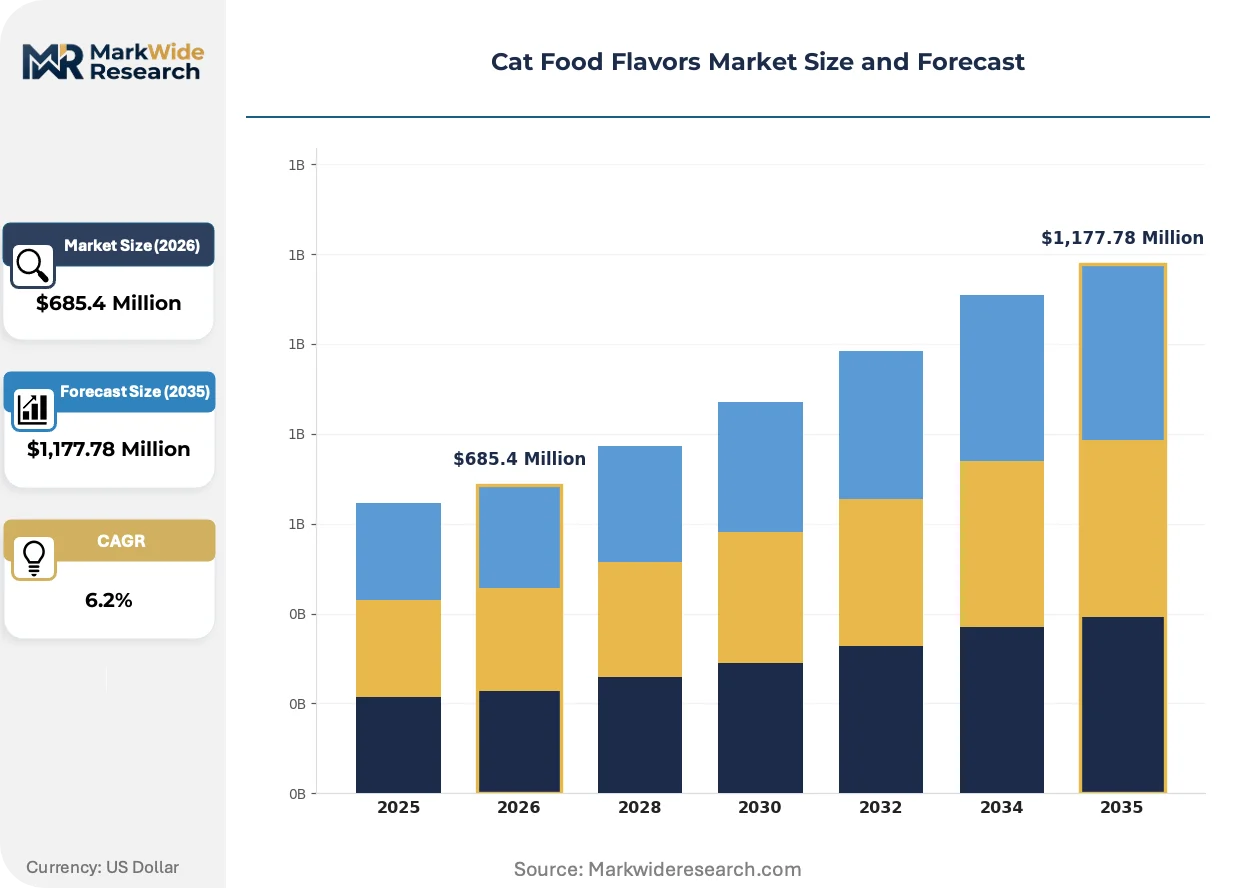
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Flavor Type: Chicken, Fish, Beef, Lamb Texture: Dry, Wet, Pate, Crumble Ingredient Quality: Grain-Free, Organic, Natural, Premium Specialty Diet: Allergy, Weight Management, Senior, Indoor |
| Companies Covered | Hill's Pet Nutrition, Diamond Pet Foods, Mars Petcare, Stella & Chewy's, Royal Canin, Nestlé Purina PetCare, Blue Buffalo, The Honest Kitchen, J.M. Smucker Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cat Food Flavors Market Strategic Shifts
Flavor technology is fragmenting along functional lines as manufacturers separate palatant performance from nutritional payload, enabling modular formulation architectures that respond faster to shifting feline preference data.
High-pressure processing of raw-coated kibble is collapsing the safety-versus-palatability tradeoff that previously segmented wet and dry formats. Mars Petcare and mid-tier private-label manufacturers are adopting HPP systems at scale for premium dry lines. The technology is collapsing capital barriers between texture classes, permitting flavor migration across moisture boundaries that AAFCO categories once enforced rigidly.
EU F-Gas Regulation phase-down schedules are pressuring synthetic refrigerant use in frozen raw flavor preservation, accelerating investment in CO2 cascade systems and lyophilization alternatives. The industrial consequence is elevated facility capex for European production assets. Wet food manufacturers in Germany and the Netherlands are responding with localized thermal processing investments that reduce cold-chain dependency for high-moisture palatant delivery.
Subscription-based flavor discovery boxes are displacing single-SKU loyalty in coastal U.S. metropolitan markets. Chewy and direct-brand platforms capture household data that informs rapid formulation pivots. Urban millennial buyers in Seattle, San Francisco, and New York demonstrate highest adoption, trading bulk purchasing for variety guarantees that reduce feeding refusal incidents in selective cats.
Cat Food Flavors Market Segmentation
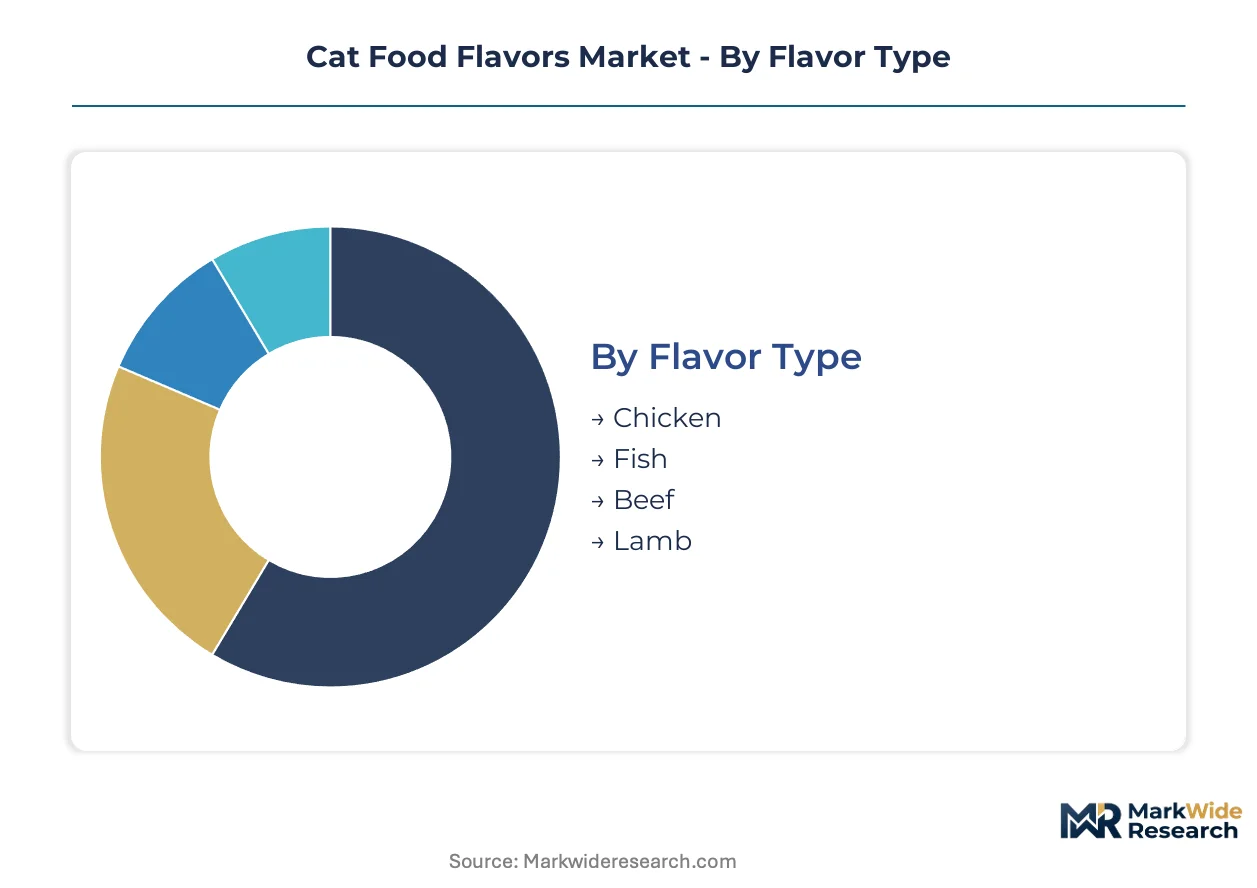
Segmentation in cat food flavors reveals how formulation priorities diverge across household types, from cost-conscious multi-cat owners to premium single-pet adopters seeking veterinary-grade nutrition. Manufacturers calibrate palatant intensity, moisture content, and certification tiers to match distinct feeding contexts and compliance requirements.
Flavor Type:
Species preference maps onto protein sourcing economics and olfactory receptor sensitivity in domestic cats.
- Chicken:Rendered poultry meal and hydrolyzed chicken liver deliver cost-efficient umami stimulation through nucleotide-rich palatant systems. Concentrated demand in dry kibble segments across the United States, particularly in Midwest metropolitan markets where price elasticity constrains premium migration.
- Fish:Wild-caught tuna and salmon extracts provide high biological value protein with potent volatile sulfur compounds that trigger feline feeding response. Coastal U.S. households in Seattle and San Francisco sustain wet format preference, though mercury accumulation concerns are elevating sourcing documentation burdens under FDA Center for Veterinary Medicine guidance.
- Beef:Bovine meal and bone broth inclusions target rotational feeding strategies in multi-pet households seeking variety beyond poultry saturation.
- Lamb:Novel protein positioning serves elimination diet protocols for suspected food sensitivity cases, typically commanding veterinary channel distribution premiums.
Established volume favors chicken; emerging adoption favors fish in raw-adjacent freeze-dried applications.
Texture:
Moisture class determines manufacturing capital intensity, cold-chain dependency, and shelf stability economics.
- Wet:Retort-processed cans and pouches at 75-78% moisture maximize palatant bioavailability through lipid-soluble aroma compound preservation. Urban millennial adopters in New York and Los Angeles drive subscription rotation services, though EU F-Gas Regulation compliance elevates European production facility capex for frozen raw preservation alternatives.
- Dry:Extruded kibble at 6-10% moisture minimizes logistics cost and enables bulk purchasing patterns in price-sensitive segments. High-pressure processing adoption by Mars Petcare and private-label manufacturers is collapsing traditional safety-versus-palatability tradeoffs for premium coated lines.
- Pate:Homogenized emulsion textures support senior cats and dental-compromised animals requiring minimal chewing effort.
- Crumble:Intermediate moisture formats bridge palatant performance with portion control convenience for automated feeder compatibility.
Margin concentration sits with wet; volume scale dominates dry.
Ingredient Quality:
Certification tier separates pricing architecture and distribution channel access.
- Grain-Free:Tapioca and pea starch substitutions address perceived carbohydrate sensitivity, though FDA dilated cardiomyopathy investigations have introduced formulation liability exposure. Blue Buffalo and similar positioned brands command shelf price premiums through ancestral diet storytelling.
- Organic:USDA certification requires 14-18 month verification timelines, delaying product launches and concentrating advantage among incumbent suppliers with established supplier relationships.
- Natural:Absence of artificial colors and synthetic preservatives meets clean-label threshold without full organic compliance cost.
- Premium:Human-grade ingredient claims and single-source protein traceability target veterinary endorsement and clinic-exclusive distribution.
Grain-free captures mainstream premiumization; organic faces certification bottleneck constraints.
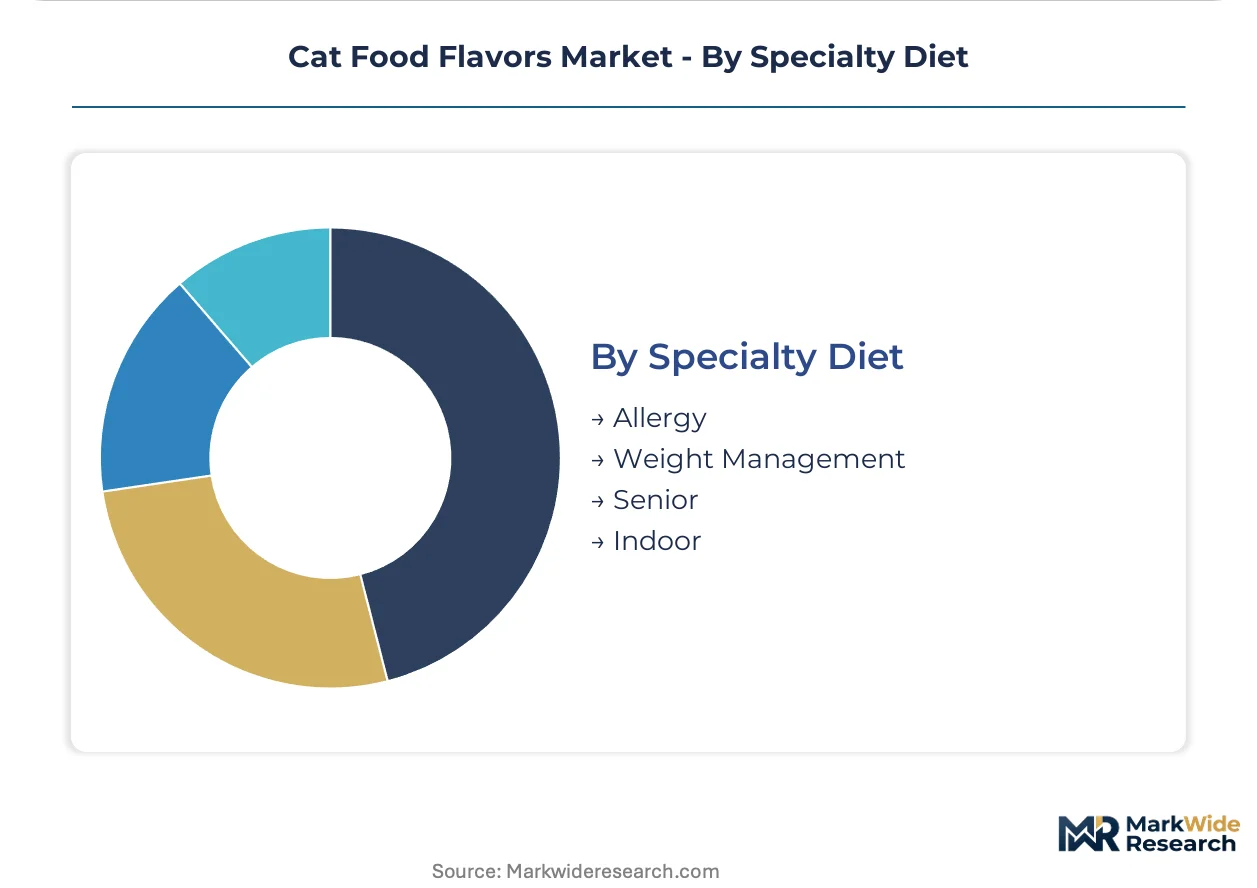
Specialty Diet:
Clinical nutrition applications command price multiples through prescription channel exclusivity.
- Allergy:Hydrolyzed protein and limited ingredient formulations reduce immunogenic epitope exposure for atopic dermatitis management.
- Weight Management:L-carnitine supplementation and fiber-enhanced satiety profiles address feline obesity prevalence in indoor-confined populations.
- Senior:Reduced phosphorus and enhanced omega-3 ratios support renal function preservation in aging cats.
- Indoor:Hairball control fibers and reduced calorie density match sedentary lifestyle metabolic requirements.
Veterinary therapeutic positioning favors renal and diabetic variants; mass retail accessibility constrains indoor formula margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban millennial pet owners in coastal U.S. metros exhibit the lowest price elasticity, while Midwest households and emerging Asian markets retain higher volume sensitivity to unit cost fluctuations.
United States
Pet humanization drives premium wet food adoption in Seattle, San Francisco, and New York, where subscription rotation services capture recurring revenue. FDA Center for Veterinary Medicine labeling requirements elevate compliance costs for flavor suppliers entering coastal distribution channels. Mars Petcare and Nestlé Purina PetCare anchor manufacturing capacity in the Midwest rendering corridor, sourcing poultry meal from Illinois, Indiana, and Ohio processing clusters.
Germany
Freeze-dried protein inclusions expand among owners seeking raw-adjacent formats without home-prepared safety risks. EU F-Gas Regulation phase-down schedules pressure synthetic refrigerant use in frozen raw preservation, accelerating CO2 cascade system investments at Dutch and German production assets. Wet food manufacturers in the Netherlands respond with localized thermal processing investments that reduce cold-chain dependency for high-moisture palatant delivery.
United Kingdom
Veterinary therapeutic channel expansion commands price multiples for prescription flavor profiles targeting renal and diabetic management diets. FSA and Defra oversight of meat and poultry ingredients shapes sourcing geography and supply chain documentation burdens for importers. Greater London pet specialty retail concentrates demand for grain-free and organic certification tiers, though USDA organic verification timelines extend 14-18 months for U.S.-sourced ingredients.
Japan
AI-driven preference mapping enables hyper-personalized flavor recommendations at household level in Tokyo and Osaka metropolitan markets. METI standards on pet food manufacturing facilities intersect with JIS quality management requirements for imported flavor systems. Premium single-pet adopters in Kanto drive demand for human-grade ingredient claims and single-source protein traceability targeting veterinary endorsement.
Australia
Insect protein regulatory tailwind from EFSA novel food approvals opens formulation pathways with lower environmental footprints than conventional livestock, influencing Australian ingredient import strategies. TGA and Department of Agriculture oversight of imported animal products constrains black soldier fly larvae sourcing until domestic regulatory alignment completes. Sydney and Melbourne coastal metros sustain fish-based wet format preference despite mercury accumulation documentation burdens under imported seafood standards.
Cat Food Flavors Market Competitive Environment
Capability concentration sits with legacy flavor houses possessing in-house veterinary nutrition teams; scale advantage sits with diversified CPG conglomerates leveraging global manufacturing footprints. The market structures around three tiers: multinational pet care divisions with veterinary channel dominance, premium independent brands with grain-free positioning, and private-label manufacturers serving mass retail price points. Strategic moves center on M&A for therapeutic diet capabilities and high-pressure processing capacity expansion for raw-coated dry lines.
Within the multinational tier, Mars Petcare and Nestlé Purina PetCare exemplify scale-driven positioning through mass retail and veterinary distribution anchoring. Blue Buffalo occupies the premium independent archetype with grain-free ingredient storytelling commanding shelf price premiums. Among specialty manufacturers, The Honest Kitchen and Stella & Chewy's represent human-grade and freeze-dried format specialists respectively, each sitting within distinct certification-tier positioning rather than competing directly on volume scale.
| Leading Market Players |
|---|
| Hill's Pet Nutrition |
| Diamond Pet Foods |
| Mars Petcare |
| Stella & Chewy's |
| Royal Canin |
| Nestlé Purina PetCare |
| Blue Buffalo |
| The Honest Kitchen |
| J.M. Smucker Company |
| Others |
Value Chain & Pricing Dynamics
The Illinois-Indiana-Ohio poultry rendering corridor concentrates over half of U.S. poultry meal supply, anchoring cost structures for mid-tier dry kibble producers while coastal metropolitan buyers absorb premium wet food markups through subscription rotation services. This geographic asymmetry between feedstock concentration and end-market willingness-to-pay shapes margin distribution across moisture classes and certification tiers.
Pricing Analysis
Aftermarket subscription revenue for personalized flavor rotations drives lifetime value capture as Chewy and direct-brand platforms automate variety-seeking behavior in multi-cat households. Three-tier pricing structure across premium, standard, and economy levels separates USDA organic verification timelines from natural-positioned mid-tier offerings and price-sensitive bulk dry formats. Cost compression in economy segments intensifies because animal protein input volatility compresses margin predictability for mid-tier producers. Midwest metropolitan households exhibit highest price sensitivity, while Seattle, San Francisco, and New York adopters demonstrate lowest elasticity to unit cost fluctuations.
Supply Chain Analysis
Upstream poultry meal and rendered protein feedstock draws from the U.S. Midwest rendering corridor, Thailand seafood processing clusters, and Brazilian beef byproduct streams. Black soldier fly larvae, wild-caught fishmeal, and hydrolyzed protein palatants constitute critical formulation inputs with divergent sourcing geographies. Single-source vulnerability concentrates in the three-state poultry rendering corridor, exposing formulation costs to weather and logistics disruptions. Distribution runs through veterinary clinic-exclusive channels for therapeutic diets, mass retail for standard tiers, and direct-to-consumer platforms for subscription rotation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among subscription platform aggregators and veterinary channel gatekeepers, fragmenting traditional brand loyalty and elevating data-rich direct-to-consumer operators as price-setters in premium tiers.
For Market Incumbents: Harden formulation expertise barriers by expanding in-house veterinary nutrition teams to meet AAFCO tightened labeling standards, while securing captive supply of black soldier fly larvae ahead of EFSA regulatory alignment. Lock in high-pressure processing capacity for raw-coated dry lines before capital barriers between texture classes fully collapse. Elevate clean-label certification pipelines to compress USDA organic verification timelines behind competitor windows. For New Entrants and Emerging Players: Pursue AI-driven preference mapping white-space in Tokyo and Osaka metropolitan markets where METI standards intersect with hyper-personalization demand. Target veterinary therapeutic channel expansion for renal and diabetic prescription flavor profiles commanding clinic-exclusive price multiples. Enter through freeze-dried protein inclusion formats that expand addressable demand among raw-adjacent seekers without home-prepared safety risks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors high-pressure processing capacity owners and AI-enabled flavor recommendation platforms over commodity texture manufacturers. Long-term viability hinges on regulatory tailwinds for insect protein and collapsing cold-chain dependency through lyophilization alternatives. Watch EFSA novel food approval velocity for black soldier fly larvae as inflection indicator for environmental footprint positioning. Cross-checking against veterinary clinic dispensing data is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Capacity Expansion | Mars Petcare adoption collapses safety-versus-palatability tradeoffs for premium dry lines. |
| Insect Protein Regulatory Alignment | EFSA approvals for black soldier fly larvae open lower environmental footprint formulation pathways. |
| Subscription Platform Data Capture | Chewy and direct-brand operators leverage household consumption patterns for rapid formulation pivots. |
| Veterinary Therapeutic Channel Penetration | Prescription renal and diabetic diets command price multiples through clinic-exclusive distribution. |
| Clean-Label Certification Pipeline Investment | USDA organic and Non-GMO Project verification compresses 14-18 month timelines behind competitors. |
Study Parameters
Cross-validation between primary interviews with flavor house formulation chemists, veterinary nutritionists, and retail category buyers anchors the qualitative findings against secondary validation from FDA Center for Veterinary Medicine guidance documents, AAFCO model regulations, EU F-Gas Regulation phase-down schedules, and customs records of poultry meal trade flows. Bottom-up segmentation modeling triangulates with top-down macroeconomic calibration across the analysis window.
Calibration against historical price elasticity data and subscription platform adoption curves refines the analytical framework across flavor type, texture class, ingredient quality tier, and specialty diet positioning. CAGRs derive from segmented growth rate reconciliation with input cost trajectory modeling. Palatant patent expiration schedules and EFSA novel food approval timelines constitute industry-specific forecast inputs.
Sensitivities concentrate around AAFCO nutrient profile updates, Midwest rendering corridor disruption events, and clean-label litigation trends redirecting formulation investment. Forecasts reflect documented assumptions on pet humanization velocity and urban millennial household formation. Cross-checking against Nielsen retail audit data and veterinary clinic dispensing benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Curculin Market
Specialty Foods
Low Fat and Low Carb Foods Market
Specialty Foods
Jams, Jellies & Preserves Market
Specialty Foods
Organic Skin Care Market
Specialty Foods
Sweet Spreads Market
Specialty Foods
Global Bee Products Market
Specialty Foods
Foie Gras Market
Specialty Foods
Low Salt Low Fat Meals Market
Specialty Foods
Low Calorie Chocolate Desserts Market
Specialty Foods
North American Jam, Jelly, and Preserve Market
Specialty Foods
Global Guilt-Free Desserts Market
Specialty Foods
Global Ethnic Foods Market
Specialty Foods
Space Food Market
Specialty Foods
Heat-Stable Fruit Fillings Market
Specialty Foods
US Jam Jelly and Preserves Market
Specialty Foods
Triphala Powder Market