
 Asia-Pacific Nuclear Bombs and Missiles Market | 2026-2036
Asia-Pacific Nuclear Bombs and Missiles Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Nuclear Bombs and Missiles Market Analytics
China's uranium enrichment complex near Lanzhou is reconfiguring regional supply security calculations. BrahMos Aerospace leverages Indo-Russian joint venture structures to sustain hypersonic cruise missile output. Bharat Dynamics Limited anchors India's tactical missile inventory with integrated production of Prithvi and Agni variants. Mitsubishi Heavy Industries dominates Japan's solid-fuel rocket motor segment through precision manufacturing for space-lift and defense applications.
Asia-Pacific nuclear bombs and missiles encompass fission and thermonuclear warheads paired with ballistic or cruise delivery systems, typically employing plutonium or highly enriched uranium cores with yields from sub-kiloton tactical devices to multi-megaton strategic weapons designed for deterrence or theater strike missions. Thermonuclear warheads lead value pools given their complexity and strategic platform pairing, while submarine-launched ballistic missile segments represent the fastest-growing delivery category as second-strike capability investments accelerate across regional navies. Ground-based ballistic systems remain the most mature segment with established maintenance cycles and predictable replacement demand.
China's MIIT coordinates civilian-military fusion standards for dual-use aerospace components, while India's BIS and DRDO enforce indigenous content thresholds that restrict foreign subsystem access. Australia's TGA-equivalent defense export frameworks and South Korea's MFDS-aligned nonproliferation compliance protocols further complicate cross-border technology flows. Stakeholders must monitor how domestic content mandates and technology transfer restrictions reshape supplier qualification pathways across national programs.
Market Dynamics
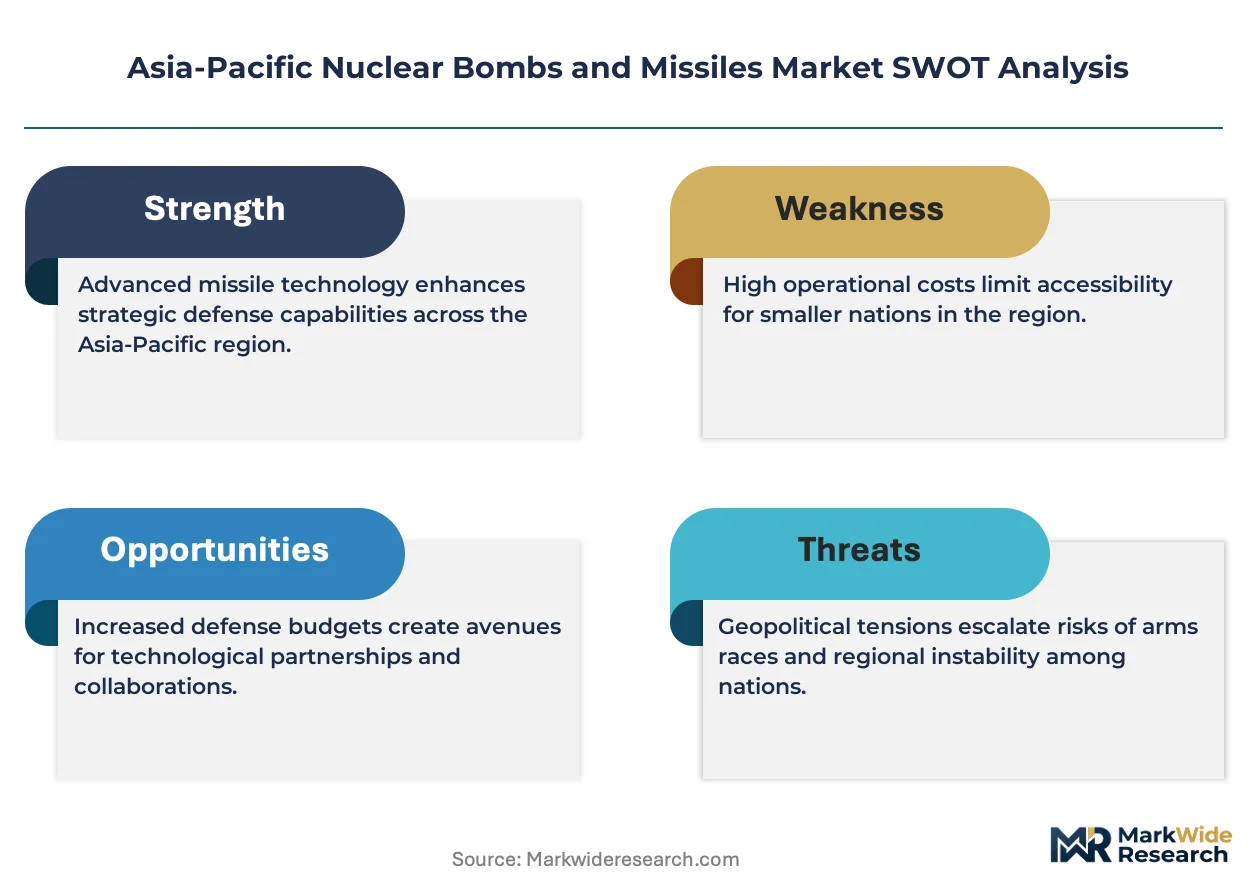
Naval second-strike investments across the Asia-Pacific are compressing procurement cycles for submarine-launched ballistic missile systems, with indigenous enrichment capabilities and dual-use aerospace component standards now determining supplier qualification pathways.
Growth Catalysts
- India's Agni-V MIRV deployment:Multiple independently targetable reentry vehicle integration expands strategic deterrence coverage across the Indian Ocean rim, triggering follow-on orders for solid-fuel booster stages.
- China's dual carbon goals:Civilian nuclear power expansion under MIIT coordination channels domestic uranium enrichment capacity toward weapons-grade material production without foreign supply dependence.
- Australia's AUKUS submarine program:Nuclear-powered attack boat procurement establishes regional precedent for fissile material handling infrastructure that supports future deterrent architecture.
Market Restraints
- Highly enriched uranium feedstock concentration:China's Lanzhou complex and Russia's Angarsk facility control over 60% of Asia-Pacific separative work unit capacity, creating single-source vulnerability for non-indigenous programs.
- Japan's constitutional Article 9 constraints:METI interpretation of peaceful-use clauses restricts plutonium stockpile utilization for warhead cores, capping domestic deterrent optionality regardless of technical readiness.
- Solid-fuel propellant precursor scarcity:Ammonium perchlorate and hydroxyl-terminated polybutadiene supply chains concentrate in Chinese state-owned chemical conglomerates, exposing missile motor production to export licensing friction.
Strategic Opportunities
- South Korea's SLBM Blue Whale program:Indigenous 3,000-ton submarine development creates demand for compact reactor designs and vertical launch system integration expertise currently underpenetrated in domestic industry.
- Pakistan's Babur-III cruise missile maturation:Air-independent propulsion submarine pairing with nuclear-tipped turbofan delivery vehicles opens precision-strike deterrence segments previously dominated by ballistic trajectories.
- ASEAN neutral-state reactor builds:Indonesia's and Vietnam's civilian nuclear programs under IAEA safeguards establish fissile material accounting frameworks that could accelerate breakout timelines if regional security architectures shift.
Industry Challenges
- Warhead physics package miniaturization:Thermonuclear secondary staging and boosted primaries require specialized beryllium reflector machining and tritium breeding blanket engineering talent pools concentrated in legacy defense establishments.
- Submarine reactor compartment certification:Naval reactor pressure vessel welding and shielding qualification timelines extend 8-14 years, compressing fleet delivery schedules against political procurement windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Nuclear Bombs and Missiles Market |
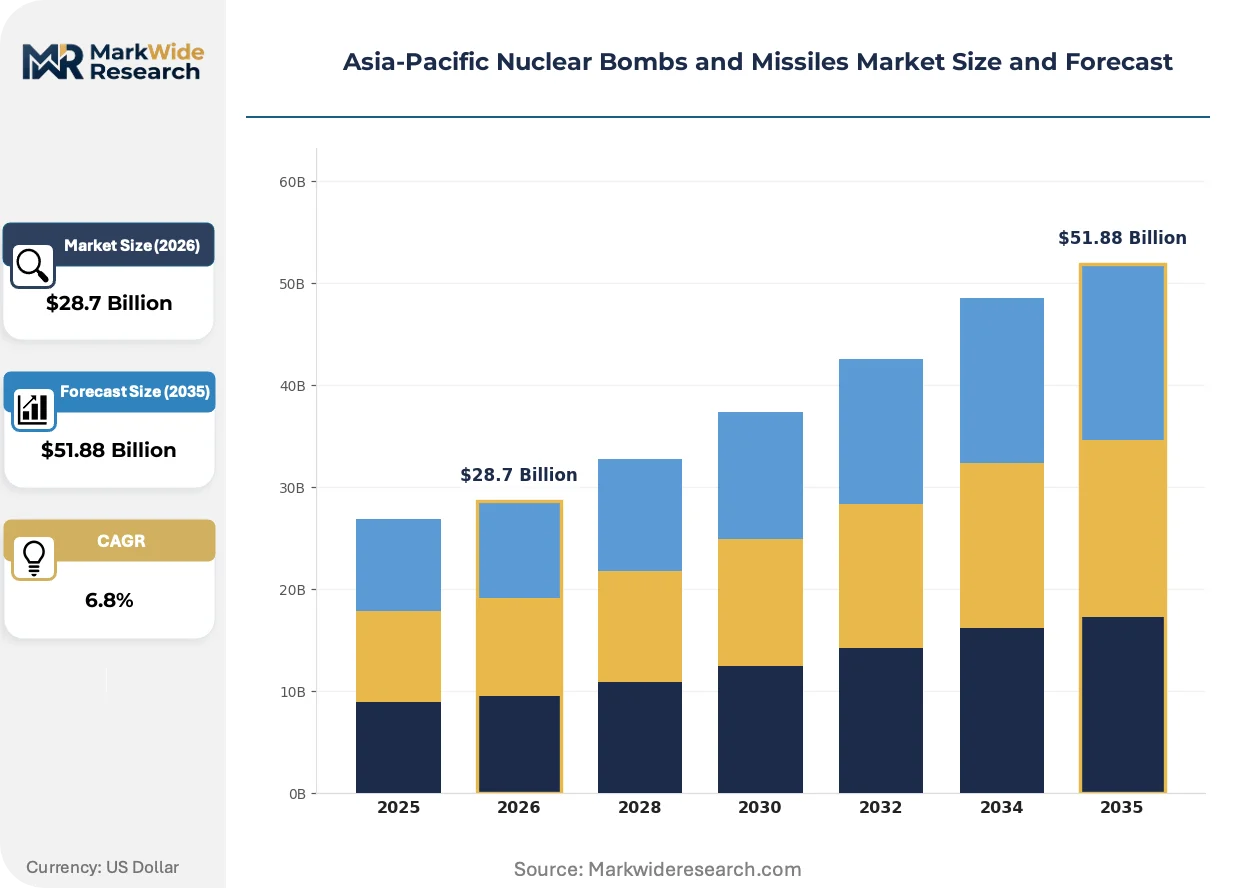
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Warhead Type: Thermonuclear, Fission, Enhanced Radiation, Tactical Delivery Platform: Submarine Launched, Air Launched, Ground Based, Ballistic Operational Status: Active, Decommissioned, Under Development, Experimental Payload Capacity: Low Yield, Medium Yield, High Yield, Strategic |
| Companies Covered | BrahMos Aerospace, Bharat Dynamics Limited, Mitsubishi Heavy Industries Ltd., LIG Nex1, China Aerospace Science and Industry Corporation, Defence Research and Development Organisation, JSC Tactical Missiles Corporation, Kawasaki Heavy Industries, Ltd., RTX Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Nuclear Bombs and Missiles Market Evolving Landscape
Hypersonic glide vehicle integration and solid-fuel motor advances are compressing traditional ballistic missile defense architectures, while civilian-military fusion policies reshape component sourcing boundaries across national programs.
Hypersonic boost-glide systems utilizing waverider aerodynamics and scramjet sustainer motors are virtualizing the distinction between ballistic and cruise delivery categories. China's DF-ZF and Russia's Avangard derivatives drive regional investment in terminal-phase interceptors and space-based sensor constellations. Defense ministries in India and Japan now require dual-capability testing infrastructure that accommodates both traditional reentry vehicles and maneuvering warhead profiles within single launch campaigns.
MIIT's civilian-military fusion standards for aerospace-grade titanium alloys and carbon-fiber motor casings now mandate traceable supply chains from raw sponge to finished component. China's GB/T certification regime requires defense contractors to source from MIIT-approved dual-use vendor lists, effectively walling off foreign subsystem access for critical guidance and propulsion elements. Indian DRDO countermeasures emphasize BIS indigenous content thresholds that restrict foreign content below 30% for strategic platform subcontracts.
Naval procurement officers across the Asia-Pacific now bundle submarine construction with 30-year fuel-cycle and reactor servicing contracts, unbundling traditional shipyard-only arrangements. Australia's AUKUS implementation and India's Arihant-class follow-ons embed fleet sustainment within sovereign industrial base development rather than foreign original equipment manufacturer dependency. This pattern concentrates contract value with domestic nuclear engineering consortia capable of cradle-to-grave platform stewardship.
Asia-Pacific Nuclear Bombs and Missiles Market Segmentation
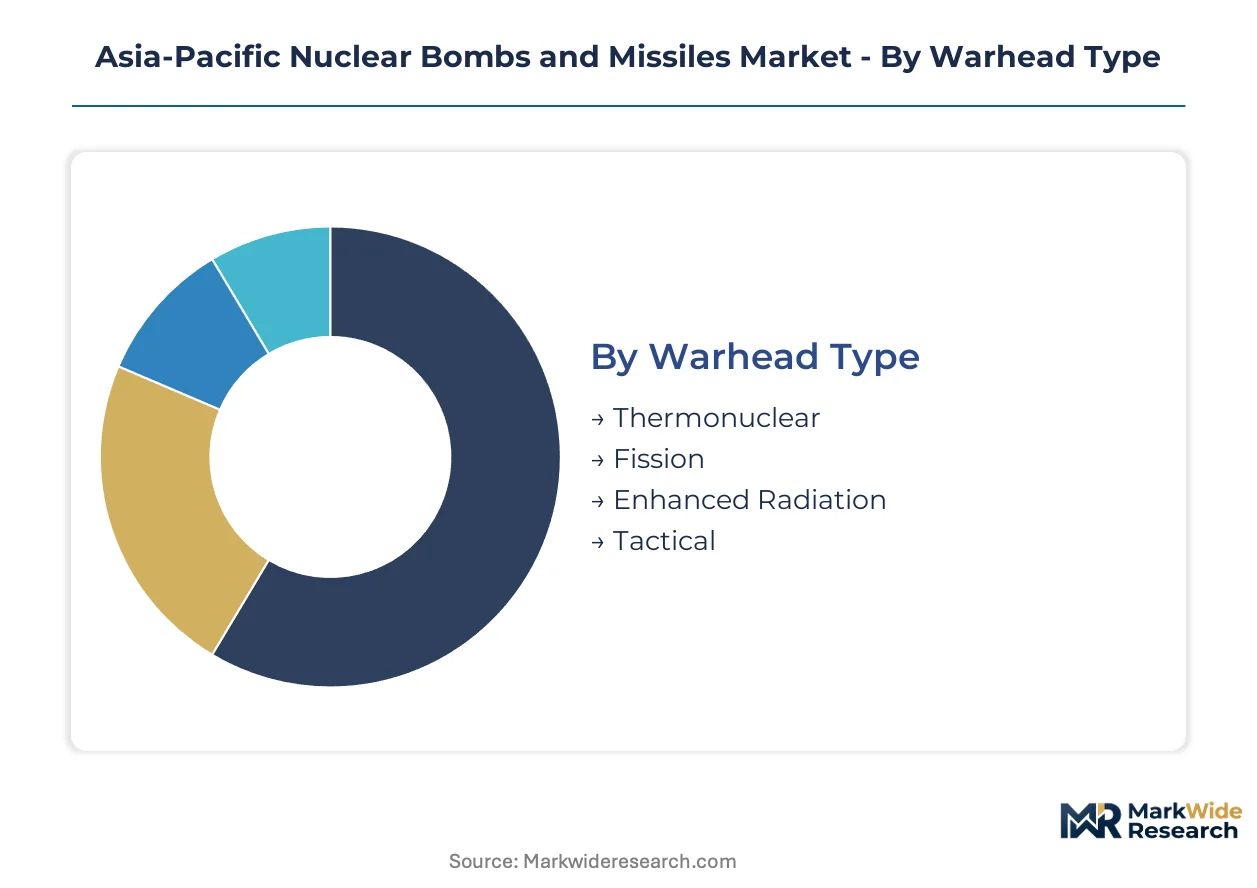
Segmentation reveals how procurement priorities diverge across Asia-Pacific arsenals. Warhead physics complexity, platform survivability requirements, and yield classifications determine supplier qualification pathways and contract structures differently in each category.
Warhead Type:
After-sales service intensity peaks with thermonuclear warheads due to tritium reservoir replenishment cycles and periodic physics package certification requirements.
- Thermonuclear:Two-stage fission-fusion designs employing lithium-6 deuteride secondaries and boosted primaries. India's DRDO and China's CAEP concentrate demand here as MIRV modernization drives replacement schedules for aging single-stage stockpiles.
- Fission:Pure plutonium or highly enriched uranium cores with yields below 500 kilotons. Pakistan's National Defence Complex and North Korean facilities sustain regional demand for tactical and theater systems where miniaturization constraints limit thermonuclear adoption.
- Enhanced Radiation:Neutron-optimized designs with reduced blast effects and intensified prompt radiation output. Specialized beryllium reflector machining requirements restrict viable supplier pools to legacy defense establishments.
- Tactical:Sub-kiloton to low-kiloton yields intended for battlefield use against military formations. India's Cold Start doctrine and Pakistan's Nasr program anchor regional demand for short-range delivery integration.
Thermonuclear warheads hold the largest share; momentum sits with tactical systems as limited warfighting doctrines gain traction in South Asian force postures.
Delivery Platform:
Platform selection determines supply chain concentration, with submarine-based systems demanding the most specialized vendor ecosystems.
- Submarine Launched:Solid-fuel ballistic missiles in vertical launch tubes or torpedo tube cruise variants. China's JL-3 and India's K-15 programs concentrate demand in Bohai Shipyard and Larsen & Toubro facilities as second-strike investments accelerate.
- Air Launched:Cruise missiles and gravity bombs delivered by strategic bombers or tactical aircraft. Pakistan's Ra'ad and India's Nirbhay programs sustain regional turbofan propulsion demand.
- Ground Based:Silo-based or mobile transporter-erector-launcher systems. China's DF-41 and India's Agni-V anchor demand for large-diameter solid motors and cold-launch technologies.
- Ballistic:Boost-glide and traditional ballistic trajectories spanning tactical to intercontinental ranges. Terminal maneuvering requirements reshape guidance subsystem specifications across regional programs.
Ground-based systems retain the largest installed base; submarine-launched platforms are expanding most quickly as naval deterrence investments compress procurement cycles.
Operational Status:
Status distribution reflects divergent modernization timelines across regional arsenals, with lifecycle management requirements varying sharply by category.
- Active:Deployed warheads and delivery systems under continuous alert or patrol. China's Rocket Force and India's Strategic Forces Command concentrate operational inventory in mobile and silo-based configurations.
- Decommissioned:Retired systems awaiting dismantlement or component reclamation. Safeguards verification and fissile material accounting requirements shape service provider selection for legacy stockpile management.
- Under Development:Platforms and warheads in engineering or flight-test phases. India's Agni-V MIRV integration and China's DF-ZF hypersonic program anchor regional R&D demand.
- Experimental:Early-stage concepts including pure-fusion devices and directed-energy delivery. Limited to national laboratory programs with restricted industrial participation.
Active systems dominate inventory value; under-development platforms are gaining share fastest as modernization cycles accelerate across regional deterrent forces.
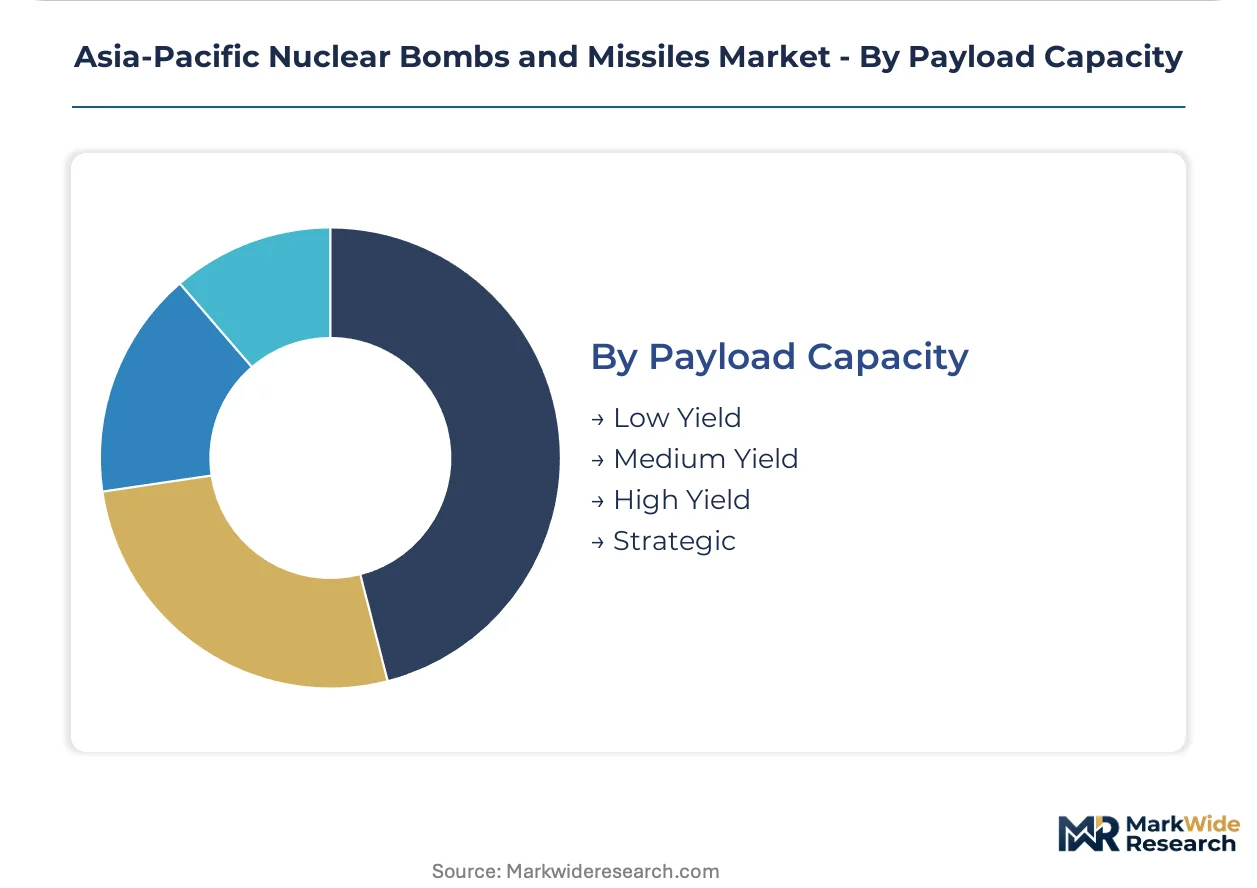
Payload Capacity:
Yield classification determines targeting doctrine compatibility and platform integration constraints, with strategic systems commanding premium pricing tiers.
- Low Yield:Sub-kiloton to 10-kiloton designs for tactical employment. Pakistan's Nasr and India's Prahaar programs concentrate demand for precision delivery against hardened point targets.
- Medium Yield:10-kiloton to 100-kiloton range for theater-level deterrence. Conventional counterforce targeting requirements shape fuzing and accuracy specifications in regional procurement.
- High Yield:100-kiloton to 1-megaton designs for countervalue missions. Thermonuclear staging complexity restricts viable suppliers to sovereign nuclear establishments.
- Strategic:Multi-megaton yields or MIRV configurations for assured destruction postures. China's DF-5C and India's forthcoming Agni-VI programs anchor demand for compact, high-reliability reentry vehicles.
Strategic payloads command the largest contract values; low-yield systems are climbing the fastest as limited nuclear warfighting doctrines reshape regional force structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Lanzhou enrichment complex and Russia's Angarsk facility concentrate over 60% of Asia-Pacific separative work unit capacity, creating geographic chokepoints that shape procurement security calculations for non-indigenous programs across the region.
China
Dual carbon goals under MIIT coordination channel civilian nuclear expansion toward weapons-grade material production without foreign uranium dependence. GB/T certification regimes for aerospace-grade titanium alloys mandate traceable supply chains from raw sponge to finished component, walling off foreign subsystem access for critical guidance elements. Bohai Shipyard in Liaoning province concentrates JL-3 submarine-launched ballistic missile integration as second-strike investments accelerate.
India
Agni-V MIRV deployment and Arihant-class submarine follow-ons drive solid-fuel booster stage procurement and compact reactor design demand. BIS indigenous content thresholds restrict foreign content below 30% for strategic platform subcontracts, reinforcing sovereign industrial base development. Bharat Dynamics Limited in Hyderabad anchors tactical missile inventory production alongside DRDO's integrated Agni and Prithvi variant programs.
Japan
METI interpretation of constitutional Article 9 peaceful-use clauses restricts plutonium stockpile utilization for warhead cores regardless of technical readiness. Solid-fuel rocket motor demand concentrates in Mitsubishi Heavy Industries' precision manufacturing operations for space-lift and defense applications. Nagoya-based aerospace clusters supply carbon-fiber motor casings under JIS standards that accommodate dual-use component flows.
South Korea
Blue Whale indigenous submarine development creates demand for compact reactor designs and vertical launch system integration expertise currently underpenetrated in domestic industry. MFDS-aligned nonproliferation compliance protocols complicate cross-border technology flows for fissile material handling infrastructure. Seoul Capital Area defense consortia coordinate with Daegu-Gyeongbuk manufacturing bases on SLBM propulsion subsystem localization.
Australia
AUKUS nuclear-powered attack boat procurement establishes regional precedent for fissile material handling infrastructure that supports future deterrent architecture. TGA-equivalent defense export frameworks govern technology transfer restrictions that reshape supplier qualification pathways. South Australia submarine construction hubs embed 30-year fuel-cycle and reactor servicing contracts within sovereign industrial base development rather than foreign OEM dependency.
Asia-Pacific Nuclear Bombs and Missiles Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in propulsion, guidance, and materials segments. The vendor ecosystem organizes around sovereign nuclear establishments with restricted foreign participation, creating tiered qualification pathways where domestic content mandates determine subcontract access. Strategic archetypes include state-owned aerospace conglomerates with captive enrichment-to-delivery verticals, defense ministry laboratories with production mandates, and joint venture structures leveraging bilateral technology transfer agreements. Competitive positioning depends on reactor compartment certification timelines and 30-year fleet sustainment bundling rather than unit production economics.
Within the joint venture tier, BrahMos Aerospace exemplifies Indo-Russian bilateral structures that sustain hypersonic cruise missile output through shared production responsibilities. Bharat Dynamics Limited occupies a position among laboratory-to-production bridge entities that translate DRDO designs into serial manufacturing. Mitsubishi Heavy Industries anchors Japan's solid-fuel motor segment through precision manufacturing capabilities spanning space-lift and defense applications.
| Leading Market Players |
|---|
| BrahMos Aerospace |
| Bharat Dynamics Limited |
| Mitsubishi Heavy Industries Ltd. |
| LIG Nex1 |
| China Aerospace Science and Industry Corporation |
| Defence Research and Development Organisation |
| JSC Tactical Missiles Corporation |
| Kawasaki Heavy Industries, Ltd. |
| RTX Corporation |
| Others |
Value Network & Pricing Analysis
China's Lanzhou enrichment complex and Angarsk separative work unit capacity anchor 60% of regional fissile material supply, concentrating margin capture with sovereign nuclear establishments while compressing procurement leverage for non-indigenous programs across India, South Korea, and Australia.
Pricing Analysis
MIIT's GB/T certification regime and BIS indigenous content thresholds dictate the pricing tier structure across strategic platform subcontracts. Three-tier pricing structure across premium, standard, and economy levels separates MIRV-configured thermonuclear systems from tactical fission devices and experimental physics packages. Cost compression in solid-fuel propellant precursors intensifies because ammonium perchlorate supply chains concentrate in Chinese state-owned chemical conglomerates. Defense ministry laboratories exhibit least price sensitivity given sovereign mission mandates; emerging ASEAN neutral-state reactor programs demonstrate highest sensitivity to upfront fissile material accounting infrastructure costs.
Supply Chain Analysis
Tariff exposure between Russia and Western-aligned procurement networks dominates supply chain risk calculations for highly enriched uranium feedstock and beryllium reflector machining equipment. Geographic supply concentration centers on China, Russia, and India for separative work units, solid-fuel motor casings, and reactor pressure vessel forgings. Raw material dependencies rest on lithium-6 deuteride for thermonuclear secondaries, tritium breeding blankets, and aerospace-grade titanium sponge. Single-source vulnerability permeates naval reactor compartment certification timelines. Distribution runs through sovereign nuclear engineering consortia with 30-year fuel-cycle bundling rather than spot-market component transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hypersonic boost-glide systems utilizing scramjet sustainer motors pose a direct substitution threat to traditional ballistic missile defense architectures, forcing incumbents to defend platform integration value against maneuvering warhead virtualization.
For Market Incumbents: Entrench reactor compartment certification capabilities and 30-year fleet sustainment bundling to lock out foreign OEM dependency. Deepen backward integration into tritium breeding blanket engineering and beryllium reflector machining to close physics package miniaturization gaps against emerging hypersonic delivery threats. For New Entrants and Emerging Players: Pursue compact reactor design and vertical launch system integration expertise currently underpenetrated in South Korea's Blue Whale program and Australia's AUKUS implementation. Target submarine-launched ballistic missile propulsion subsystems as the most penetrable segment, leveraging Seoul Capital Area defense consortia coordination with Daegu-Gyeongbuk manufacturing bases for localization partnerships. For Investors and Strategic Acquirers: Capital is best deployed toward laboratory-to-production bridge entities that translate sovereign nuclear establishment designs into serial manufacturing. Long-term viability hinges on 8-14 year reactor pressure vessel welding qualification timelines compressing against political procurement windows. Watch for IAEA safeguards verification shifts in Indonesia's and Vietnam's civilian nuclear programs as inflection indicators for regional breakout timeline acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enrichment Infrastructure | MIIT coordination of civilian-military fusion standards channels domestic uranium capacity toward weapons-grade production without foreign supply dependence. |
| Naval Reactor Compartment Certification Investment | Bohai Shipyard and Larsen & Toubro facilities concentrate JL-3 and K-15 integration as second-strike investments accelerate procurement cycles. |
| Hypersonic Testing Infrastructure Dual-Use Development | DRDO and Japan's defense ministry requirements now accommodate both traditional reentry vehicles and DF-ZF-derived maneuvering warhead profiles. |
| 30-Year Fuel-Cycle Fleet Sustainment Bundling | Australia's AUKUS implementation embeds sovereign industrial base development rather than foreign original equipment manufacturer dependency. |
| Indigenous Content Threshold Compliance Engineering | BIS mandates restricting foreign content below 30% for strategic platform subcontracts reshape supplier qualification pathways across national programs. |
Research Methodology
Desk research of customs/trade data, national nuclear regulatory filings, and sovereign defense procurement disclosures preceded structured interviews with submarine program procurement officers, reactor compartment certification engineers, solid-fuel motor production directors, and physics package miniaturization specialists. Bottom-up platform delivery forecasts triangulated against top-down regional deterrent modernization budget allocations across the analysis window.
Assumptions held fixed include current IAEA safeguards verification protocols, existing constitutional constraints on plutonium stockpile utilization, and prevailing dual-use aerospace component certification regimes. The projection framework modeled warhead type, delivery platform, operational status, and payload capacity segmentation dimensions alongside national indigenous content mandate stringency. CAGRs derived from procurement cycle compression rates for second-strike naval investments and replacement schedules for aging single-stage thermonuclear stockpiles. Tritium reservoir replenishment cycles and periodic physics package certification requirements informed after-sales service intensity assumptions.
Macroeconomic conditions sit as an overlay; deviation in sovereign defense budget prioritization, uranium spot market volatility, or bilateral technology transfer agreement renegotiation would shift the trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Weapons and Ammunition
Missile Launching Systems Market
Weapons and Ammunition
Turret System Market
Weapons and Ammunition
Small Arms Market
Weapons and Ammunition
Ammunition Handling Systems Market
Weapons and Ammunition
Military Fire Control Systems Market
Weapons and Ammunition
Mortar Ammunition Market
Weapons and Ammunition
Explosives for Civil Uses Market
Weapons and Ammunition
Smart Bombs Market
Weapons and Ammunition
Europe Ammunition Market
Weapons and Ammunition
North Korea Nuclear Bombs and Missiles Market
Weapons and Ammunition
Southeast Asia, Middle-East and Africa Small Arms and Ammunition Market
Weapons and Ammunition
Supersonic and Hypersonic Weapons Market
Weapons and Ammunition
Shotgun and Rifles Market
Weapons and Ammunition
US Perforating Gun Market
Weapons and Ammunition
Europe Cruise Missile Market
Weapons and Ammunition
Ammunition Storage Market