
 Europe Air Defense Systems Market | 2026-2036
Europe Air Defense Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Air Defense Systems Market Foresight
Multi-source procurement for critical subsystems is hardening across European defense ministries. MBDA leverages its missile integration expertise to anchor long-range interceptor programs in multiple NATO states. Rheinmetall AG competes through ground-based air defense platforms with emphasis on modular launcher architectures. Thales Group specializes in radar and command infrastructure, sustaining its position across French, British, and allied European programs.
Europe air defense systems encompass integrated weapon platforms, sensor networks, and battle management architectures designed to detect, track, and neutralize hostile aircraft, missiles, and unmanned aerial vehicles at ranges from point-defense to theater-wide coverage, typically incorporating phased-array radars with detection thresholds below 0.01 square meter radar cross-section and interceptor missiles reaching speeds exceeding Mach 3. These systems serve primarily to protect military installations, population centers, and critical infrastructure against saturation attacks and hypersonic threats. Missile systems and radar systems together dominate procurement budgets, with electronic warfare systems representing the fastest-expanding segment as operators prioritize non-kinetic defeat mechanisms against drone swarms. Command and control systems concentrate margin pools where software-defined architectures enable interoperability across national boundaries.
EU Green Deal implementation through the European Defence Agency shapes environmental compliance requirements for system energy consumption and materials sourcing, while CE marking and NATO standardization agreements govern technical interoperability and market access for cross-border procurement. EMA and national regulators in France, Germany, and Italy coordinate on dual-use technology export controls that constrain component flows outside allied frameworks. Stakeholders must weigh the tension between sovereign production mandates and the cost advantages of trans-European supply integration as threat timelines compress procurement cycles.
Market Dynamics
Layered air defense architectures are hardening procurement patterns across European defense ministries as threat saturation from drone swarms and hypersonic missiles compresses deployment timelines. Sovereign production mandates clash with trans-European supply integration pressures, forcing operators to reconcile national security imperatives with cost efficiency.
Growth Catalysts
- EU Green Deal mandates:Energy efficiency requirements for radar and directed-energy platforms are accelerating R&D investment in solid-state transmitters and gallium nitride components.
- Polish modernization urgency:Warsaw's accelerated procurement programs for medium-range interceptors and integrated battle management systems are reshaping regional demand concentration.
- NATO standardization agreements:Technical interoperability protocols are enabling cross-border maintenance networks and pooled ammunition stocks across allied frameworks.
Market Restraints
- Gallium nitride substrate shortage:Limited European foundry capacity for wide-bandgap semiconductors creates input bottlenecks for next-generation radar systems.
- Dual-use export controls:EMA coordination with French, German, and Italian national regulators constrains component flows outside allied frameworks, fragmenting supplier access.
- Directed-energy technical thresholds:Power density and atmospheric propagation limitations delay operational deployment of laser-based interceptors against maneuvering targets.
Strategic Opportunities
- Electronic warfare integration:Non-kinetic defeat mechanisms against drone swarms represent underexploited white space as operators seek alternatives to missile expenditure.
- Baltic corridor expansion:Estonia, Latvia, and Lithuania lack layered coverage, creating first-mover advantage for mobile short-range systems with rapid redeployment capability.
- Software-defined architectures:Modular command and control systems enable interoperability premiums where national operators prioritize plug-and-fight integration.
Industry Challenges
- Systems engineering talent scarcity:Specialized expertise in phased-array calibration and battle management algorithm development concentrates in a handful of defense clusters.
- Legacy platform integration friction:Cold War-era radar networks require extensive middleware adaptation to achieve data fusion with modern interceptor batteries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Air Defense Systems Market |
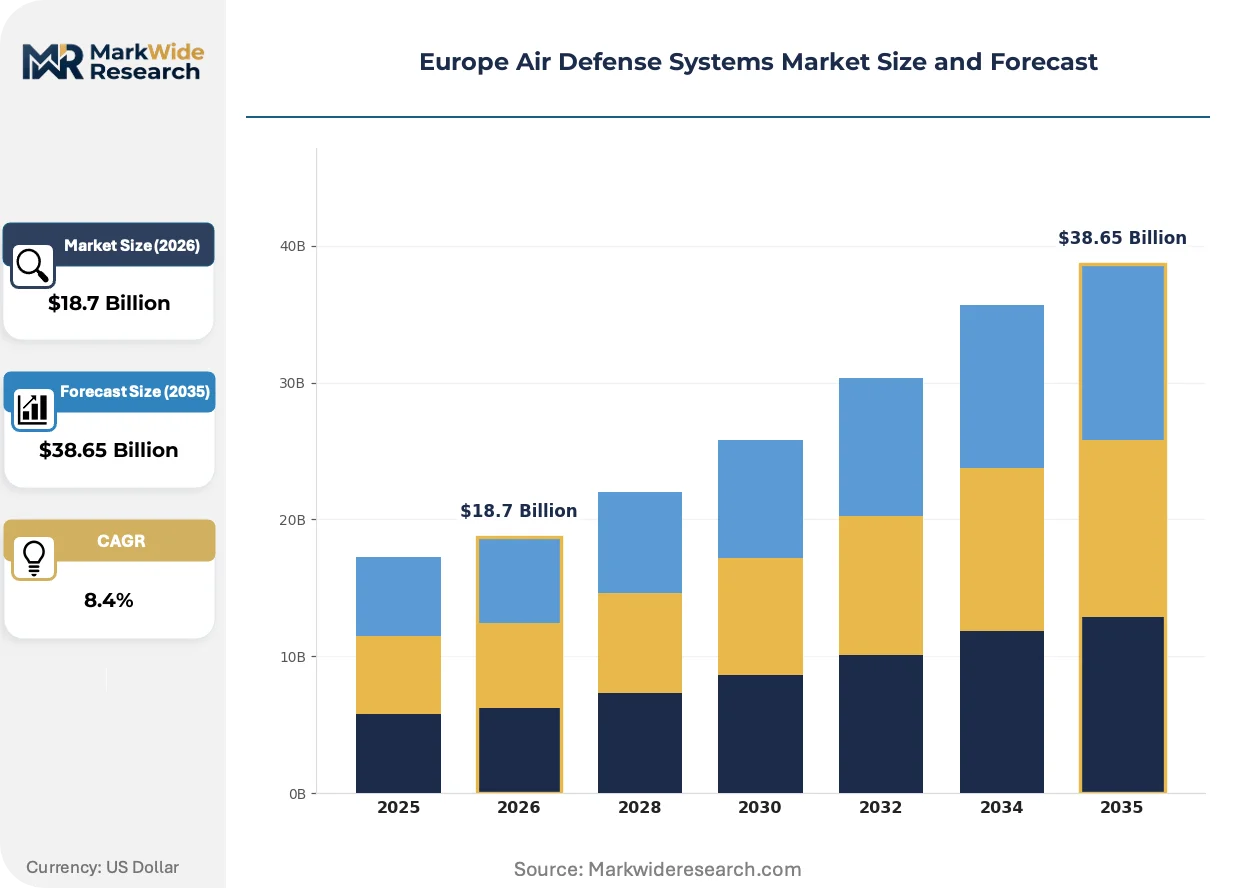
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Missile Systems, Radar Systems, Command and Control Systems, Electronic Warfare Systems End User: Defense Forces, Government Agencies, Security Agencies, Private Contractors Technology: Active Radar, Passive Radar, Infrared Systems, Laser Systems Deployment: Onshore, Offshore, Mobile Systems, Fixed Installations |
| Companies Covered | MBDA, Thales Group, BAE Systems, Rheinmetall AG, Leonardo, Saab AB, Lockheed Martin, Raytheon Technologies, Kongsberg Gruppen ASA, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Air Defense Systems Market Shifts & Advancements
Artificial intelligence is compressing sensor-to-shooter timelines across European air defense networks. Three developments are restructuring competitive positioning and procurement patterns.
Machine learning-based target classification is automating threat prioritization in dense electromagnetic environments. French and British operators are deploying neural network filters to distinguish decoys from warheads in real-time tracking loops. This capability is automating operator workload reduction while enabling engagement decisions against saturation raids that exceed human cognitive bandwidth.
REACH and RoHS compliance deadlines are forcing material substitutions in radar transmitters and missile propulsion systems. European manufacturers face reformulation requirements for thermal management compounds and energetic materials by 2027. German and Italian prime contractors are accelerating qualification programs for lead-free solder alternatives and reduced-toxicity propellants to maintain CE marking access.
Defense ministries are consolidating maintenance contracts under performance-based availability agreements. Polish and Romanian procurement offices now specify operational readiness thresholds rather than spare parts lists, transferring lifecycle risk to integrators. This restructuring concentrates margin pools with contractors capable of predictive diagnostics and regional logistics hubs.
Europe Air Defense Systems Market Segmentation
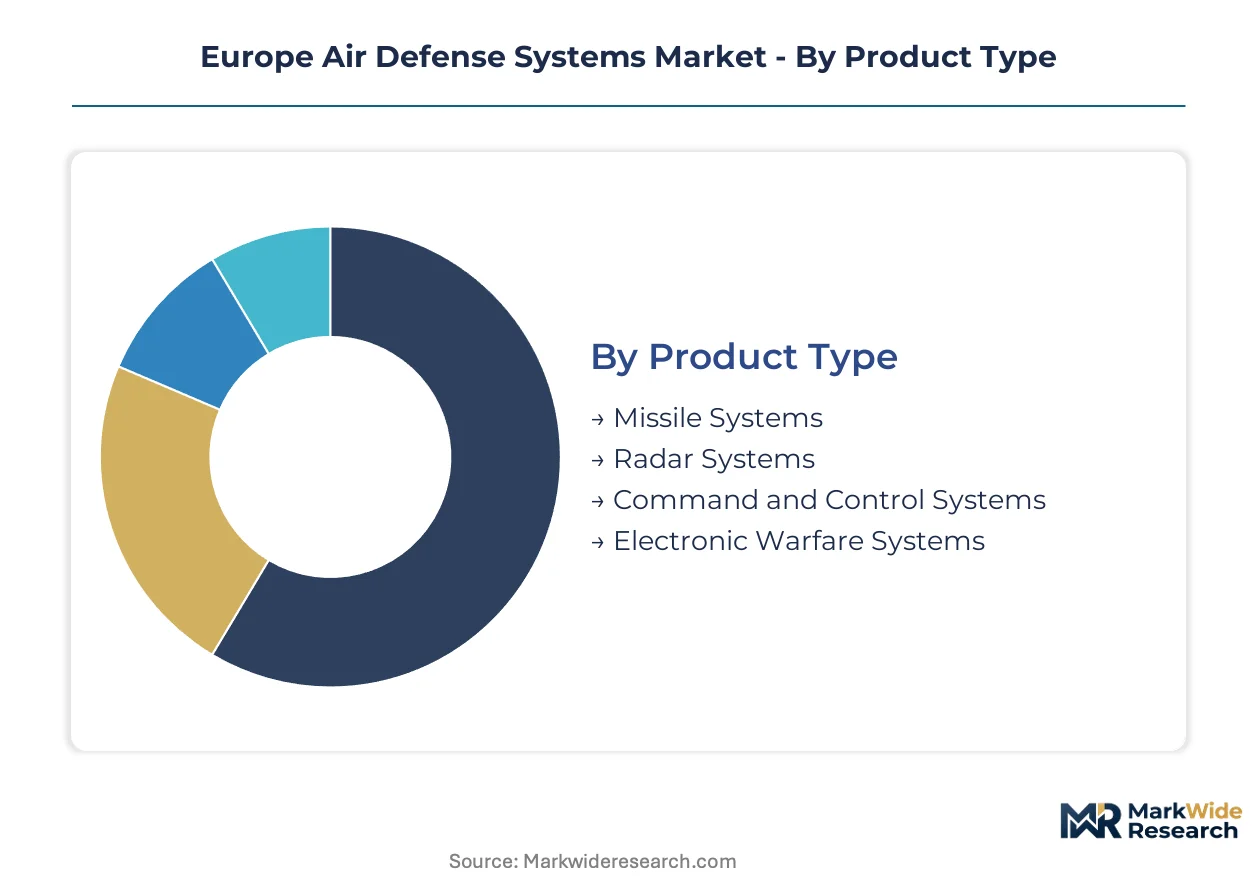
Segmentation in European air defense procurement reveals where defense ministries concentrate budgets and where technology transitions create displacement risk. Procurement officers balance legacy platform sustainment against leap-ahead investments in software-defined architectures and non-kinetic defeat mechanisms.
Product Type:
Supply concentration for critical subsystems—seekers, solid-state transmitters, gallium nitride components—shapes which product categories capture margin and which face input bottlenecks.
- Missile Systems:Long-range and medium-range interceptors incorporating dual-mode seekers and thrust-vectoring propulsion. Polish and Romanian defense ministries are accelerating procurement of medium-range batteries to close coverage gaps along NATO's eastern flank, with performance-based availability contracts transferring lifecycle risk to integrators.
- Radar Systems:Active electronically scanned arrays with gallium nitride transmit/receive modules enabling detection thresholds below 0.01 square meter radar cross-section. Limited European foundry capacity for wide-bandgap semiconductors creates supply constraints for next-generation programs, concentrating procurement with contractors holding captive substrate access.
- Command and Control Systems:Software-defined battle management architectures enabling plug-and-fight interoperability across national boundaries.
- Electronic Warfare Systems:Non-kinetic defeat mechanisms including jamming pods and directed-energy platforms for drone swarm engagement.
Today's leader: Missile Systems. Tomorrow's challenger: Electronic Warfare Systems.
End User:
Cost tier stratification separates sovereign defense ministries with multi-billion procurement authority from security agencies operating constrained budgets for point-defense applications.
- Defense Forces:National military services operating layered air defense architectures from theater-wide to point-defense coverage. French, British, and Polish armed forces are consolidating maintenance contracts under performance-based availability agreements, specifying operational readiness thresholds rather than spare parts lists.
- Government Agencies:Civil protection and critical infrastructure guard units requiring mobile short-range systems for rapid redeployment to population centers and energy facilities.
- Security Agencies:Specialized units protecting high-value assets and diplomatic installations with portable counter-UAS capabilities.
- Private Contractors:Facility protection providers and critical infrastructure operators procuring commercial-off-the-shelf counter-drone systems under simplified acquisition frameworks.
Defense Forces command procurement volume. Security agencies are climbing the fastest.
Technology:
Volume concentration in active radar reflects proven track records, while emerging modalities face technical thresholds delaying operational deployment.
- Active Radar:Phased-array systems with electronic beam steering and pulse-Doppler processing for clutter rejection. German and Italian prime contractors are accelerating qualification programs for lead-free solder alternatives to maintain CE marking access under REACH compliance deadlines.
- Passive Radar:Bistatic architectures exploiting third-party illuminators to reduce electromagnetic signature and deployment footprint.
- Infrared Systems:Thermal imaging trackers for short-range engagement and electro-optical cueing in dense electromagnetic environments.
- Laser Systems:Directed-energy interceptors facing power density and atmospheric propagation limitations against maneuvering targets.
Active Radar dominates procurement pipelines. Passive Radar offers the steepest expansion trajectory as operators prioritize signature reduction.
Deployment:
Application requirements drive divergence between fixed installations protecting static high-value assets and mobile systems enabling maneuver warfare and rapid crisis response.
- Onshore:Ground-based air defense networks protecting military installations, population centers, and critical infrastructure across continental European territory.
- Offshore:Navalized air defense systems for fleet area defense and littoral protection, integrating with shipboard combat management systems.
- Mobile Systems:Self-propelled launcher vehicles and towed configurations with rapid emplacement timelines. Estonian, Latvian, and Lithuanian defense planners are prioritizing mobile short-range systems with rapid redeployment capability to address layered coverage gaps in the Baltic corridor.
- Fixed Installations:Permanent radar sites and hardened missile batteries with integrated power and communications infrastructure.
Fixed Installations anchor current posture. Mobile Systems are gaining share fastest as threat timelines compress deployment requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's accelerated procurement programs are concentrating regional demand for medium-range interceptors and integrated battle management systems. Defense ministries across the continent are reconciling sovereign production mandates with trans-European supply integration pressures.
Poland
Warsaw's urgent modernization timeline drives procurement of layered air defense architectures to close coverage gaps along NATO's eastern flank. The Polish Ministry of National Defense specifies performance-based availability contracts that transfer lifecycle risk to system integrators. Industrial activity clusters around Warsaw and the Tri-City corridor where maintenance networks and logistics hubs are consolidating under consolidated service agreements.
Germany
Berlin's focus on modular ground-based air defense platforms anchors demand for gallium nitride radar components and solid-state transmitters. REACH compliance deadlines and RoHS mandates from ECHA are accelerating qualification programs for lead-free solder alternatives in thermal management systems. Manufacturing concentrates in Bavaria and Baden-Württemberg where prime contractors maintain captive foundry relationships for wide-bandgap semiconductors.
France
Paris prioritizes software-defined command architectures enabling plug-and-fight interoperability across allied frameworks. The French national regulator ANSM coordinates with EMA on dual-use export controls that constrain component flows outside NATO-aligned supply chains. Development clusters in the Île-de-France region and Provence-Alpes-Côte d'Azur where neural network filters for target classification are undergoing operational deployment.
United Kingdom
London's procurement offices emphasize electronic warfare integration for non-kinetic defeat mechanisms against drone swarms. CE marking requirements under EU Green Deal implementation shape environmental compliance for system energy consumption despite post-Brexit regulatory divergence. Engineering activity concentrates in Greater London and the Midlands where battle management algorithm development draws on specialized systems engineering talent pools.
Italy
Rome's defense ministry accelerates directed-energy platform development while navigating power density limitations for laser-based interceptors. Italian regulators coordinate with EMA and French authorities on export control frameworks affecting gallium nitride substrate flows. Industrial capacity clusters in Lombardy and Lazio where qualification programs for reduced-toxicity propellants are advancing toward 2027 deadlines.
Europe Air Defense Systems Market Competitive Landscape
Global majors compete with regional champions across technology licensing and sovereign production partnerships. The European vendor base organizes around missile integration specialists, radar and sensor houses, and ground platform fabricators. Three archetypes dominate: prime contractors with captive semiconductor access, systems integrators leveraging NATO standardization protocols, and niche players in electronic warfare subsystems. Competitive dynamics center on performance-based availability contracting and cross-border maintenance network consolidation.
Among established European defense houses, MBDA represents the missile integration archetype across multiple NATO states, while Thales Group exemplifies radar and command infrastructure specialization sustaining position in French, British, and allied programs. Rheinmetall AG occupies a distinct tier in ground-based air defense platforms with modular launcher architectures. These three anchors illustrate how procurement concentration with defense ministries translates into differentiated competitive positioning based on subsystem depth and sovereign production relationships.
| Leading Market Players |
|---|
| MBDA |
| Thales Group |
| BAE Systems |
| Rheinmetall AG |
| Leonardo |
| Saab AB |
| Lockheed Martin |
| Raytheon Technologies |
| Kongsberg Gruppen ASA |
| Others |
Supply & Pricing Matrix
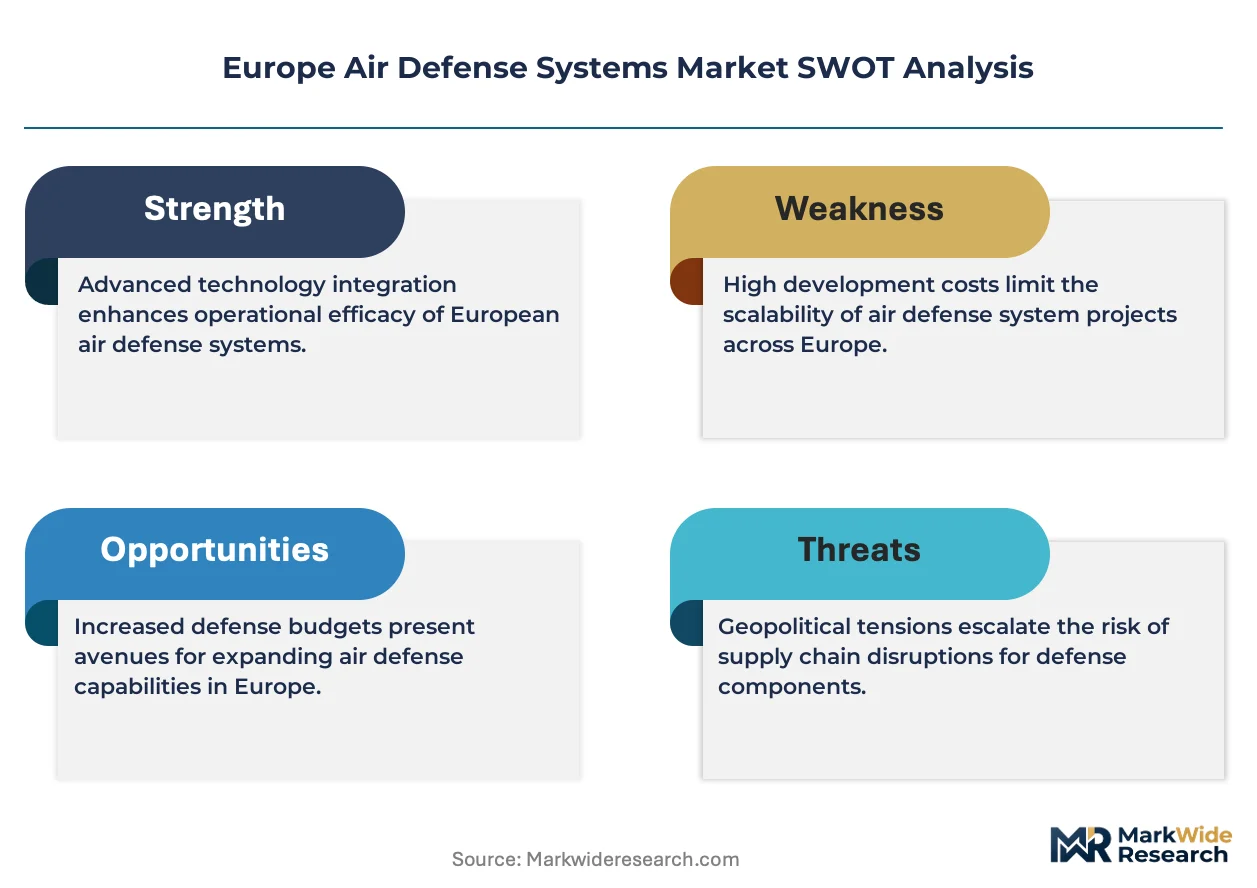
Sovereign-backed defense primes with captive semiconductor foundries anchor supply-side pricing power across European air defense procurement, transferring gallium nitride substrate scarcity into premium positioning for radar and directed-energy platforms while compressing margins for integrators without upstream substrate access.
Pricing Analysis
Gallium nitride substrate costs pass through to radar system pricing with minimal absorption by prime contractors holding captive foundry relationships. Three-tier pricing structure across premium, standard, and economy levels separates NATO-interoperable battle management suites from national-only configurations and export-restricted legacy platforms. Cost compression in standard-tier electronic warfare systems is intensifying because Polish and Romanian procurement offices now specify operational readiness thresholds rather than equipment lists. Security agencies exhibit highest price sensitivity due to constrained budgets for portable counter-UAS capabilities, while defense ministries demonstrate lowest sensitivity where sovereign production mandates override cost efficiency.
Supply Chain Analysis
Direct-to-defense-ministry channels handle national-scale procurement for layered air defense architectures, bypassing distributor intermediaries. Supply concentrates in Germany, France, and Poland for ground-based platforms, with gallium nitride substrates, solid-state transmitters, and reduced-toxicity propellants representing critical input dependencies. Single-source vulnerability in European wide-bandgap semiconductor foundry capacity creates structural risk for next-generation radar programs. Distribution runs through consolidated maintenance networks under performance-based availability agreements, transferring lifecycle logistics risk to prime contractors with regional hub presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal implementation compounds procurement velocity as energy efficiency mandates for radar and directed-energy platforms accelerate R&D investment timelines and reshape supplier qualification criteria.
For Market Incumbents: To counter gallium nitride substrate scarcity eroding margin pools, deepen backward integration into wide-bandgap semiconductor foundry capacity in Germany and France while anchoring long-term offtake agreements with Polish defense procurement offices for medium-range interceptor batteries.
For New Entrants and Emerging Players: REACH compliance deadlines in Germany and Italy open a window for specialty chemical suppliers offering lead-free solder alternatives and reduced-toxicity propellant formulations. Target electronic warfare subsystem integration for drone swarm defeat as the most penetrable white space, entering through software-defined architecture partnerships with established battle management integrators.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap electronic warfare specialists with neural network target classification IP and NATO interoperability certifications. Long-term viability in this sector hinges on sustained defense budget growth across NATO's eastern flank. Monitor Baltic corridor procurement announcements from Estonia, Latvia, and Lithuania as the inflection signal for mobile short-range system demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Gallium Nitride Foundry Investment | MBDA and Thales Group secure substrate supply for next-generation AESA radar programs against European capacity constraints. |
| Performance-Based Availability Contracting | Polish Ministry of National Defense transfers lifecycle risk to Rheinmetall AG and integrators with predictive maintenance capabilities. |
| Software-Defined Battle Management Integration | French and British operators achieve plug-and-fight interoperability premiums across NATO standardization protocols. |
| REACH-Compliant Material Qualification | German and Italian primes accelerate lead-free solder and reduced-toxicity propellant programs to maintain CE marking access. |
| Baltic Corridor Mobile System Deployment | Estonian, Latvian, and Lithuanian defense planners address layered coverage gaps with rapid-redeployment short-range batteries. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with defense procurement officers, systems engineering directors at prime contractors, gallium nitride foundry operations managers, and EMA regulatory affairs specialists with secondary validation against NATO standardization agreement databases, EU Defence Agency procurement records, national defense ministry budget filings, and REACH compliance deadline schedules. Bottom-up project pipeline analysis triangulated against top-down defense expenditure forecasts.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation modeling across product type, end user, technology, and deployment dimensions. CAGRs derived from polynomial trend fitting against procurement cycle data and threat timeline compression indicators. Forecast inputs incorporated gallium nitride substrate supply constraints, Polish modernization urgency indices, and software-defined architecture adoption curves.
Revisions become necessary when gallium nitride foundry capacity expansions materialize, when NATO interoperability protocols shift, or when EU Green Deal implementation timelines accelerate. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Air Defense
Anti-Aircraft Defense Systems Market
Air Defense
Airborne Fire Control Radar Market
Air Defense
Asia-Pacific Airborne Fire Control Radar Market
Air Defense
Short Range Air Defense Systems Market
Air Defense
Ground-Based Aircraft and Missile Defense Systems Market
Air Defense
Air Defense System Market
Air Defense
North America Missiles and Missile Defense Systems Market
Air Defense
Asia-Pacific Air Defense Systems Market
Air Defense
Global Missile Interceptor Market
Air Defense
Air and Missile Defense Radar System Market
Air Defense
Americas Air Defense Systems Market