
 Europe Missiles and Missile Defense Systems Market | 2026-2036
Europe Missiles and Missile Defense Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Missiles and Missile Defense Systems Market Foresight
German industrial capacity is realigning toward scalable missile production to meet NATO's replenishment targets. MBDA leverages its Anglo-French-German industrial base to sustain cross-border supply chains for complex weapons. Rheinmetall AG anchors Central European manufacturing with its expanding metalworks and propulsion capabilities. Saab AB competes in the Nordic-Baltic corridor through specialized sensor and command-and-control integration.
Missiles and missile defense systems encompass self-propelled guided weapons and their countermeasures, typically employing solid-fuel rocket motors, inertial navigation with terminal seekers, and blast-fragmentation or kinetic kill vehicles to neutralize airborne or surface threats. Surface-to-air missiles dominate procurement volumes as European nations rebuild area air-defense networks depleted by donations to Ukraine. Land-based systems absorb the largest share of deployment-mode spending, though naval systems are gaining traction as frigate fleets expand under national shipbuilding programs. Guidance systems represent the highest-margin technology segment, with infrared and active radar seekers commanding premium pricing over command-guided alternatives.
The EU Green Deal and REACH regulations constrain propellant formulations and manufacturing emissions, while CE marking and ECHA chemical restrictions shape component sourcing across member states. National regulators in France, Germany, and Italy impose additional defense-specific certification requirements that fragment procurement standards. Stakeholders must monitor how NATO's new defense industrial plans harmonize these divergent national approval pathways to avoid supply bottlenecks.
Market Dynamics
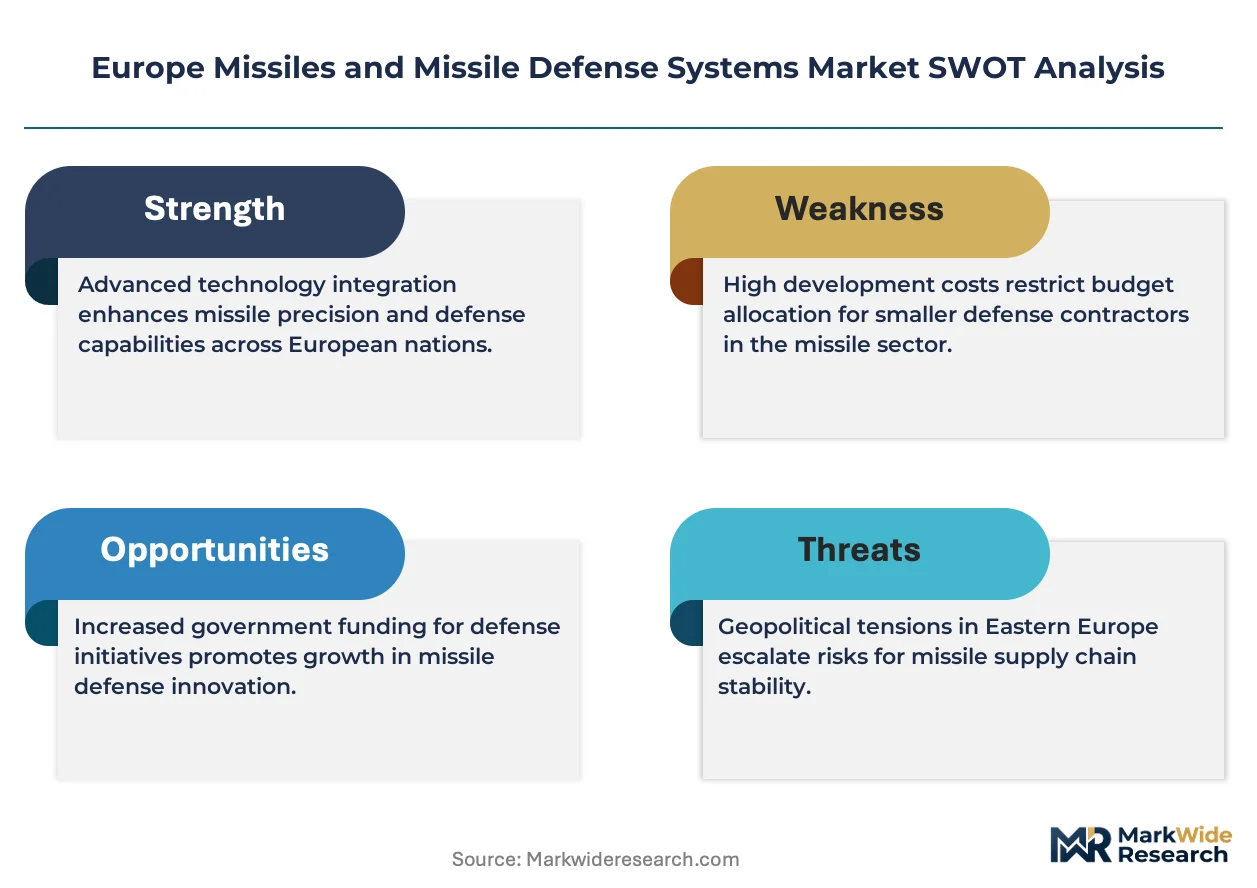
Russia's invasion of Ukraine has forced European defense ministries to rebuild depleted air-defense inventories while REACH and EU Green Deal mandates simultaneously constrain propellant chemistry and manufacturing emissions. This dual pressure—security urgency against environmental compliance—is compressing procurement timelines and forcing industrial retooling across the continent.
Growth Catalysts
- EU Green Deal industrial mandates:Defense manufacturers are accelerating cleaner propellant development to meet decarbonization targets, opening procurement pathways for compliant suppliers.
- Poland and Nordic corridor front-loading:These nations are advancing military modernization budgets ahead of NATO's replenishment schedules, concentrating near-term demand.
- Layered air-defense architectures:European ministries are procuring integrated short-, medium-, and long-range systems to replace donated stockpiles.
Market Restraints
- Nitrocellulose and ammonium perchlorate supply concentration:Solid-rocket propellant precursors face sourcing bottlenecks from limited European chemical producers.
- REACH chemical restrictions:ECHA classification processes delay new propellant formulations by 18-36 months, freezing R&D pipelines.
- Cross-border certification fragmentation:France's DGA, Germany's BAAINBw, and Italy's Segredifesa impose non-harmonized defense-specific approval requirements.
Strategic Opportunities
- Naval frigate fleet expansion:National shipbuilding programs in Germany, France, and Italy are driving vertical-launch system integration for area air defense.
- Guidance system convergence:Infrared and active radar seeker fusion is creating premium-margin kill vehicles for complex threat environments.
- CE marking pathway harmonization:NATO's new defense industrial plans may streamline component sourcing across member state borders.
Industry Challenges
- Skilled propulsion engineer scarcity:Solid-rocket motor design expertise has atrophied in Western Europe over three decades of procurement drought.
- Legacy system integration complexity:New command-and-control architectures must interface with 1980s-era NATO air-defense networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Missiles and Missile Defense Systems Market |
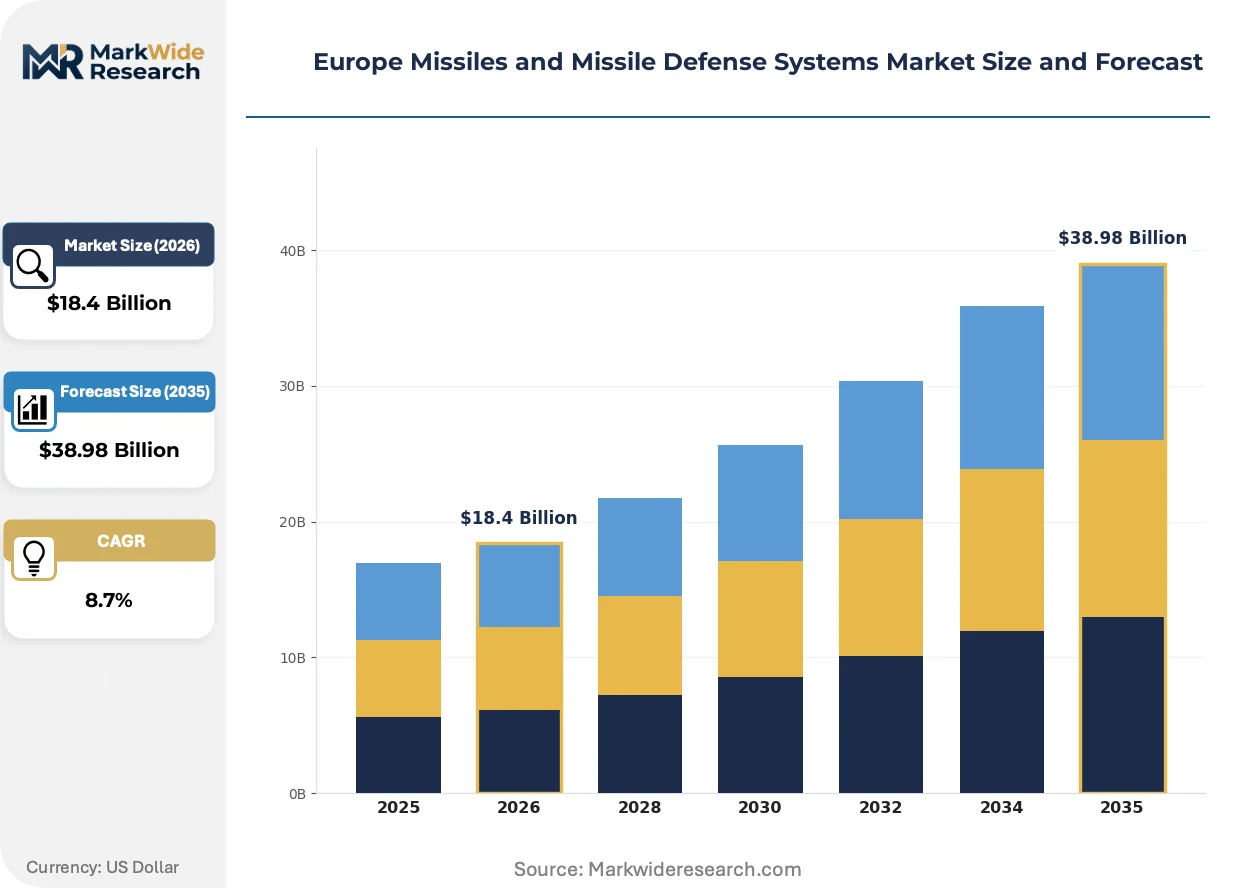
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $38.98 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ballistic Missiles, Cruise Missiles, Anti-Ship Missiles, Surface-to-Air Missiles Deployment Mode: Land-Based Systems, Naval Systems, Airborne Systems, Remote-Controlled Systems End User: Defense Forces, Government Agencies, National Security Organizations, Private Contractors Technology: Guidance Systems, Launch Systems, Interception Technology, Sensors |
| Companies Covered | MBDA, Saab AB, Lockheed Martin Corporation, Thales Group, RTX Corporation, BAE Systems, Rheinmetall AG, Leonardo, Kongsberg Defence & Aerospace, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Missiles and Missile Defense Systems Market Shifts & Advancements
Active seeker fusion and dual-mode guidance are compressing engagement timelines against hypersonic threats. Manufacturing is simultaneously adapting to REACH-compliant chemistry and NATO's demand surge.
Dual-mode infrared/radar seekers are integrating terminal discrimination capabilities against low-observable cruise missiles. Polish and German procurement offices are prioritizing these seekers for layered defense networks. The technology is integrating fire-control loops that previously required separate tracking radars, reducing system footprint and reaction latency.
REACH Annex XVII restrictions on perchlorate compounds are forcing reformulation of solid-rocket boosters across MBDA and Rheinmetall supply chains. ECHA's 2023 candidate list expansion has designated additional propellant stabilizers as substances of very high concern. French and German manufacturers are responding with nitramine-based alternatives, though these require redesigned thermal protection systems.
European ministries are consolidating multi-year framework agreements to secure production slots at strained metalworks and propulsion facilities. The traditional spot-procurement model for missile replenishment is yielding to capacity-reservation contracts with penalty clauses. This shift is most visible in Germany's Bundeswehr and Poland's Ministry of National Defence, where 10-year munitions plans now anchor industrial planning.
Europe Missiles and Missile Defense Systems Market Segmentation
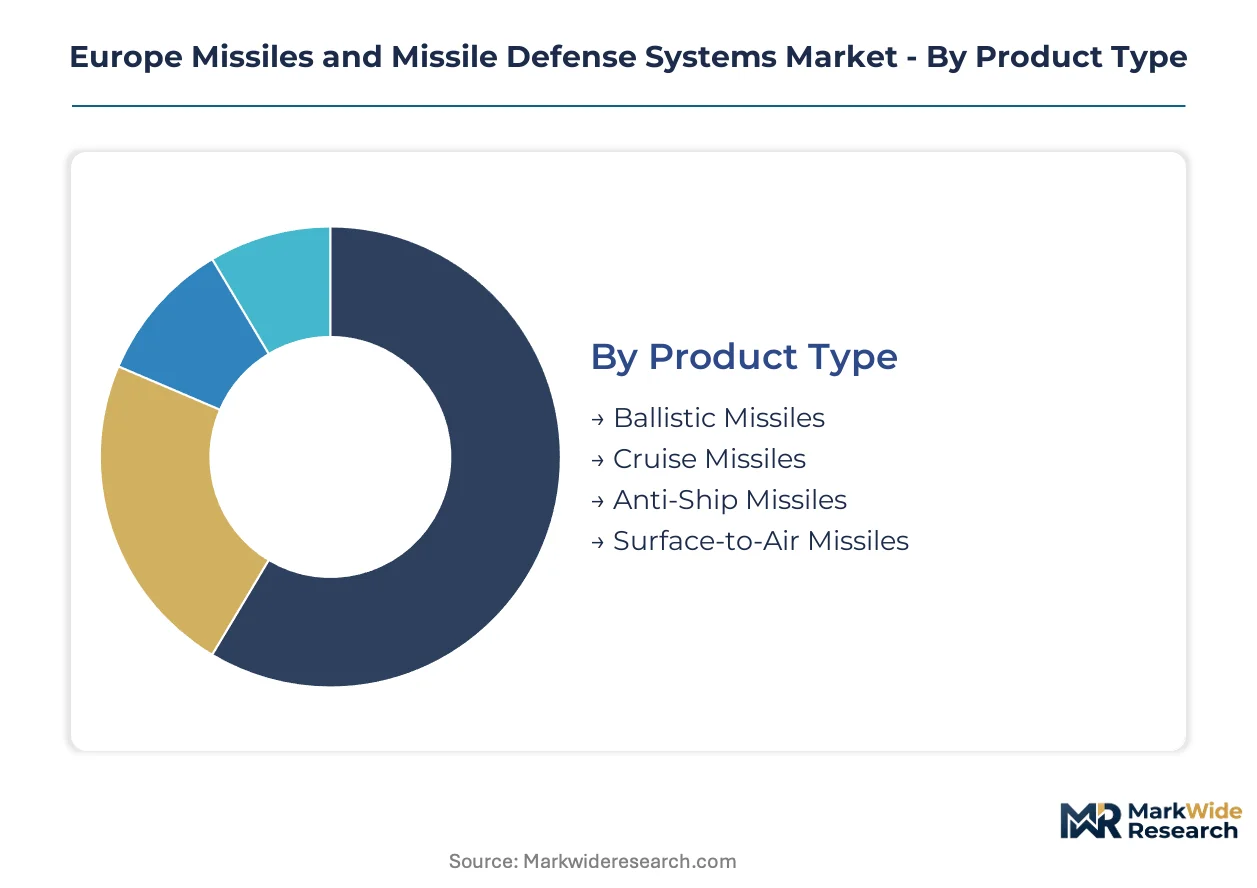
Segmentation in European missile systems reveals how procurement priorities diverge across threat profiles and operational domains. Defense ministries allocate budgets differently depending on whether they prioritize area air defense, maritime protection, or strategic deterrence.
Product Type:
Procurement volumes split between systems designed for fixed-target destruction and those intercepting maneuverable threats.
- Ballistic Missiles:Long-range solid-fuel systems with inertial and terminal guidance for strategic deterrence. German and French nuclear delivery modernization programs sustain demand despite non-proliferation constraints.
- Cruise Missiles:Turbojet-powered precision weapons with terrain-following navigation. Polish acquisition of submarine-launched variants for Baltic Sea deterrence exemplifies regional prioritization.
- Anti-Ship Missiles:Sea-skimming weapons with active radar seekers. Naval procurement concentrates in Mediterranean littoral states.
- Surface-to-Air Missiles:Layered interceptors from man-portable to long-range area defense. Nordic corridor nations front-load replenishment of donated stockpiles.
Surface-to-Air Missiles lead volumes today; Cruise Missiles are gaining share fastest.
Deployment Mode:
Platform selection determines integration complexity with existing command networks and mobility requirements.
- Land-Based Systems:Mobile launchers and fixed-site batteries with integrated radar and fire control. German IRIS-T SLM deployments along NATO's eastern flank absorb the largest procurement share.
- Naval Systems:Vertical-launch cells and point-defense turrets on frigate decks. French and Italian FREMM programs drive integration demand.
- Airborne Systems:Fighter-launched interceptors and standoff munitions. Polish F-35 integration contracts concentrate regional spending.
- Remote-Controlled Systems:Ground-based unmanned launch platforms with beyond-line-of-sight targeting. Baltic states test loitering munition concepts.
Land-Based Systems dominate current procurement; Naval Systems show steepest expansion trajectory.
End User:
Budget authority and operational control determine specification requirements and approval timelines.
- Defense Forces:National military branches with NATO interoperability mandates. Bundeswehr and Polish Armed Forces concentrate multi-year framework agreements.
- Government Agencies:Civil defense and border security directorates with dual-use procurement authority. German Federal Police coastal protection units exemplify this segment.
- National Security Organizations:Intelligence services with specialized intercept requirements. Limited procurement volumes but premium specifications.
- Private Contractors:Security firms and training providers with restricted system access. Growth constrained by export control classifications.
Defense Forces command the majority of spending; Government Agencies are expanding procurement most quickly.
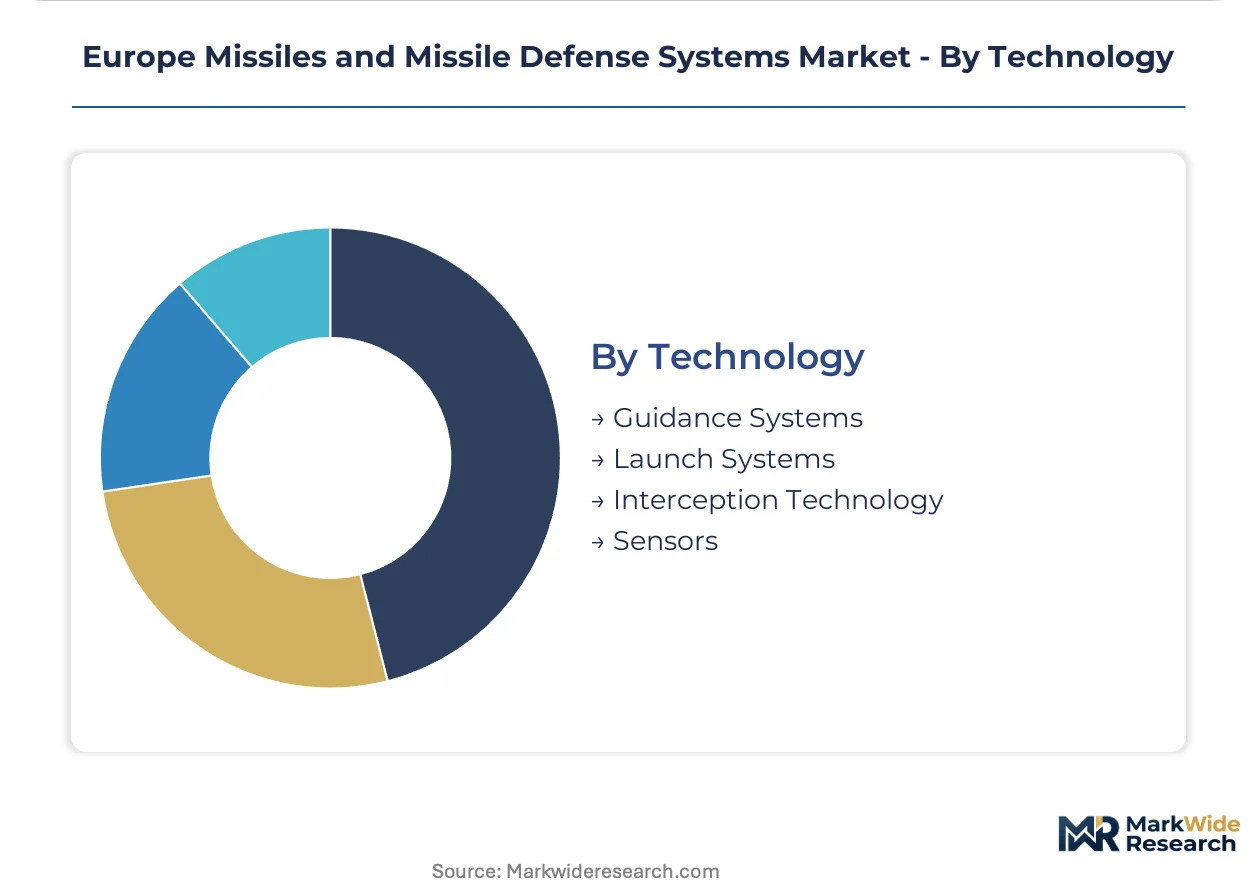
Technology:
Component selection determines system performance margins and supply chain vulnerability.
- Guidance Systems:Inertial measurement units fused with terminal seekers. Infrared and active radar variants command premium pricing over command-guided alternatives.
- Launch Systems:Cold-launch ejectors and hot-launch rails for varied platform integration. MBDA and Rheinmetall compete on modular cell architecture.
- Interception Technology:Blast-fragmentation warheads and kinetic kill vehicles. Dual-mode seekers integrating terminal discrimination against low-observable threats.
- Sensors:Fire-control radars and electro-optical trackers. Saab AB specializes in distributed aperture integration for Nordic networks.
Guidance Systems generate the highest margins today; Interception Technology is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH-compliant chemistry requirements and divergent national certification timelines are pushing propulsion manufacturing toward jurisdictions with harmonized defense procurement frameworks. Production capacity is migrating to corridors where BAAINBw, DGA, and Segredifesa approval pathways overlap.
Germany
Bundeswehr multi-year munitions frameworks and NATO eastern flank deployments drive sustained procurement volumes. BAAINBw certification requirements for solid-rocket propellants shape supplier qualification timelines. North Rhine-Westphalia metalworks and propulsion facilities anchor Central European manufacturing expansion.
Poland
Front-loaded military modernization budgets and layered air-defense network rebuilds concentrate near-term demand. Ministry of National Defence 10-year framework agreements secure production slots at strained facilities. Warsaw and Baltic corridor procurement offices prioritize dual-mode seeker integration for donated stockpile replacement.
France
Nuclear delivery modernization and FREMM frigate vertical-launch programs sustain strategic system demand. DGA defense-specific certification requirements fragment approval pathways relative to neighboring jurisdictions. Île-de-France and Provence-Alpes-Côte d'Azur clusters host guidance system and seeker fusion development.
Sweden
Nordic-Baltic corridor air-defense integration and distributed aperture sensor networks define procurement priorities. Swedish Defence Materiel Administration specifications influence cross-border standardization efforts. Linköping and Stockholm regions concentrate command-and-control system engineering for regional networks.
Italy
Naval system integration for Mediterranean littoral protection and FREMM program participation drive vertical-launch demand. Segredifesa certification requirements add regulatory layers beyond CE marking baseline. Lazio and Lombardy facilities specialize in launch system modular cell architecture development.
Europe Missiles and Missile Defense Systems Market Competitive Landscape
German and French producers anchor one tier; Nordic and Anglo-Italian specialists hold differentiated positions in sensor and naval integration. The vendor structure concentrates around cross-border industrial bases with established propulsion and guidance capabilities. Three archetypes dominate: vertically integrated prime contractors managing multi-national supply chains, specialized sensor and seeker houses, and metalworks-propellant integrated manufacturers. Capacity-reservation contracting and REACH-compliant chemistry retooling represent the dominant competitive moves.
Among the prime contractor tier, MBDA leverages its Anglo-French-German industrial base to sustain complex weapons production across member state borders. Rheinmetall AG anchors Central European manufacturing with expanding metalworks capabilities. Saab AB occupies a specialized position in Nordic-Baltic corridor sensor and command-and-control integration. These three exemplify how geographic distribution of technical competencies shapes competitive positioning under EU Green Deal compliance pressure.
| Leading Market Players |
|---|
| MBDA |
| Saab AB |
| Lockheed Martin Corporation |
| Thales Group |
| RTX Corporation |
| BAE Systems |
| Rheinmetall AG |
| Leonardo |
| Kongsberg Defence & Aerospace |
| Others |
Supply & Pricing Matrix
Guidance system tier divergence between infrared-active radar fusion seekers and command-guided alternatives manifests in both pricing premiums and supply chain concentration around specialized sensor foundries in France and Sweden. REACH-compliant propellant chemistry adds a certification ladder that reshapes supplier qualification timelines and cost structures across MBDA and Rheinmetall networks.
Pricing Analysis
Direct-to-defense-procurement discounts dominate the channel structure, with framework agreements replacing spot purchasing to secure strained production slots. Pricing stratifies across premium dual-mode seekers, standard active radar variants, and economy command-guided alternatives, with certification grade and volume scale as primary differentiation drivers. Cost compression in solid-rocket propellants intensifies due to nitrocellulose precursor bottlenecks. Government agencies exhibit highest price sensitivity, while national security organizations accept premium specifications.
Supply Chain Analysis
Domestic-content mandates in Poland and Germany are reshaping sourcing patterns, forcing propulsion component localization near North Rhine-Westphalia metalworks. Supply concentration centers on Germany, France, and Italy for guidance systems, with nitrocellulose and ammonium perchlorate dependencies drawing from limited European chemical producers. Single-source vulnerability in solid-rocket propellant precursors poses structural risk. Distribution runs through national procurement offices with multi-year capacity-reservation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal compounds procurement urgency by mandating cleaner propellant chemistry while NATO replenishment targets accelerate demand, creating a regulatory-demand squeeze that favors prepared suppliers.
For Market Incumbents: Deploy capacity-reservation contracting to lock in production slots before competitor expansion. MBDA and Rheinmetall should deepen backward integration into REACH-compliant propellant chemistry to defend margins against ECHA regulatory delays. Threat substitution from non-European suppliers intensifies as domestic capacity strains. For New Entrants and Emerging Players: Tier 2 sensor suppliers offer the most penetrable channel partner type for Nordic-Baltic corridor integration. White-space targets include distributed aperture command-and-control systems for Baltic states and loitering munition platforms for remote-controlled deployment segments. Go-to-market positioning should emphasize CE marking pathway expertise to accelerate national certification timelines. For Investors and Strategic Acquirers: Consolidation pressure builds where solid-rocket propulsion expertise has atrophied and skilled engineer scarcity constrains expansion. Long-term viability favors vertically integrated prime contractors with cross-border supply chain management capabilities. Acquisition target archetypes include specialized seeker fusion developers and REACH-compliant propellant formulators. Watch for NATO defense industrial plan harmonization announcements as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Propellant Transition | ECHA chemical restrictions force reformulation investments that reshape competitive qualification barriers. |
| Dual-Mode Seeker Fusion Development | Polish and German procurement offices prioritize terminal discrimination capabilities against low-observable threats. |
| Capacity-Reservation Contracting | Bundeswehr and Polish Ministry of National Defence anchor industrial planning with penalty-clause frameworks. |
| Cross-Border Supply Chain Harmonization | MBDA leverages Anglo-French-German industrial base to sustain complex weapons production across member states. |
| Nordic-Baltic Sensor Network Integration | Saab AB specializes in distributed aperture systems that define regional air-defense procurement priorities. |
Research Methodology
Bottom-up defense procurement modeling reconciled against top-down propulsion capacity tracking forms the analytical core of this study. Primary interviews with BAAINBw procurement officers, DGA certification engineers, Segredifesa program managers, and MBDA supply chain directors combined with secondary validation from NATO defense industrial plans, ECHA regulatory filings, and national munitions framework disclosures. Triangulation across stakeholder inputs and documented procurement schedules anchors volume estimates.
Input-output matrices map guidance system, propulsion, and launch platform segments across product type, deployment mode, and end-user dimensions throughout the projection horizon. CAGRs derive from capacity-constrained production slot allocation and front-loaded modernization budget trajectories. Forecast inputs include REACH compliance timelines and NATO eastern flank deployment schedules.
Revisions become necessary when ECHA expands candidate substance lists, NATO harmonization plans accelerate, or propellant precursor supply disruptions materialize. Forecasts reflect documented assumptions about certification pathway convergence and capacity expansion commitments. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Military Aerospace and Defense Lifecycle Management Market
Defense and Military Systems and Equipment
Network Centric Warfare (NCW) Market
Defense and Military Systems and Equipment
Mergers and Acquisitions (Manda) in Aerospace and Defense Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Displays Market
Defense and Military Systems and Equipment
Soldier System Market
Defense and Military Systems and Equipment
Middle East and Africa Defense Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Display Systems Market
Defense and Military Systems and Equipment
Military Embedded System Software Market
Defense and Military Systems and Equipment
Military Rifle Market
Defense and Military Systems and Equipment
Bio-Defense Market
Defense and Military Systems and Equipment
Military Phased Array Antenna Market
Defense and Military Systems and Equipment
Military Vetronics Market
Defense and Military Systems and Equipment
Military Exoskeleton Market
Defense and Military Systems and Equipment
Global Military Defense Vehicle Intercom System Market
Defense and Military Systems and Equipment
Military Actuators Market
Defense and Military Systems and Equipment
India Defense Market