
 Asia-Pacific Last Mile Delivery Market | 2026-2036
Asia-Pacific Last Mile Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Last Mile Delivery Market Insights
The capital-intensity divergence between asset-heavy and asset-light operators is bifurcating competitive dynamics across the region. JD Logistics sustains one of the most extensive proprietary fulfillment networks, operating integrated warehouses and delivery fleets across hundreds of Chinese cities. SF Express anchors premium express services through direct-controlled last-mile infrastructure. Ninja Van competes via a partner-driver model that minimizes fixed-asset exposure across Southeast Asian markets.
Asia-Pacific last mile delivery encompasses the final transportation leg from distribution hub to end recipient, typically spanning distances under 50 kilometers and requiring real-time tracking, dynamic route calculation, and proof-of-delivery verification. Motorcycle-based delivery dominates dense urban corridors across Bangkok, Jakarta, and Ho Chi Minh City due to maneuverability and fuel efficiency. Same-day delivery commands premium positioning among time-sensitive customer segments, while scheduled delivery captures recurring subscription commerce volumes with higher predictability.
China's SAMR enforces GB standards for electric two-wheelers used in urban delivery fleets, while India's FSSAI mandates temperature-controlled transport for perishable goods. METI in Japan promotes standardized parcel locker interoperability to reduce failed delivery attempts. Stakeholders must monitor evolving emissions regulations and cross-border customs digitization initiatives that will reshape fleet composition and border-clearance economics.
Market Dynamics
China's SAMR mandates on electric two-wheeler specifications and India's FSSAI cold-chain rules are forcing fleet operators across Asia-Pacific to reconfigure vehicle procurement and temperature-control infrastructure simultaneously.
Growth Catalysts
- Urban Congestion Patterns:Motorcycle-based delivery networks in Bangkok, Jakarta, and Ho Chi Minh City exploit maneuverability advantages to compress delivery windows in dense corridors where four-wheeled access faces restrictions.
- FSSAI Cold-Chain Mandates:India's food safety regulator mandates temperature-controlled transport for perishables, compelling platform operators to deploy refrigerated last-mile capacity across tier-two cities where grocery eCommerce penetration deepens.
- Parcel Locker Standardization:Japan's METI promotes interoperable locker networks that reduce failed delivery attempts and recapture driver productivity in high-cost labor markets.
Market Restraints
- Lithium-Ion Cost Volatility:Battery cell prices fluctuate with raw material markets, compressing margins for electric fleet operators who must absorb procurement risk or pass costs to shippers.
- Driver Supply Concentration:Southeast Asian markets depend on gig-economy driver pools concentrated in platform-specific networks, creating switching friction and wage pressure during peak demand windows.
- Cross-Border Customs Digitization Gaps:Inconsistent electronic documentation standards between ASEAN member states generate clearance delays that degrade express service commitments.
Strategic Opportunities
- Indonesian Archipelago Expansion:Refrigerated last-mile networks remain underdeveloped across Indonesia's outer islands, creating first-mover advantage for operators who solve inter-island cold-chain handoffs.
- Vietnamese Grocery Platforms:Online fresh food commerce in Hanoi and Ho Chi Minh City demands dedicated chilled fulfillment infrastructure that incumbent parcel networks have not prioritized.
- China's Dual Carbon Goals:National emissions targets accelerate subsidies for electric delivery vehicle replacement, reducing total cost of ownership for fleet operators who front-load capital conversion.
Industry Challenges
- Refrigeration Technician Scarcity:Cold-chain fleet maintenance requires specialized HVAC skills that vocational training pipelines across Southeast Asia have not scaled to match vehicle deployment rates.
- Route Optimization Algorithm Integration:Legacy dispatch systems in tier-two Indian cities resist API-based dynamic routing, forcing manual overlay that degrades same-day service reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Last Mile Delivery Market |
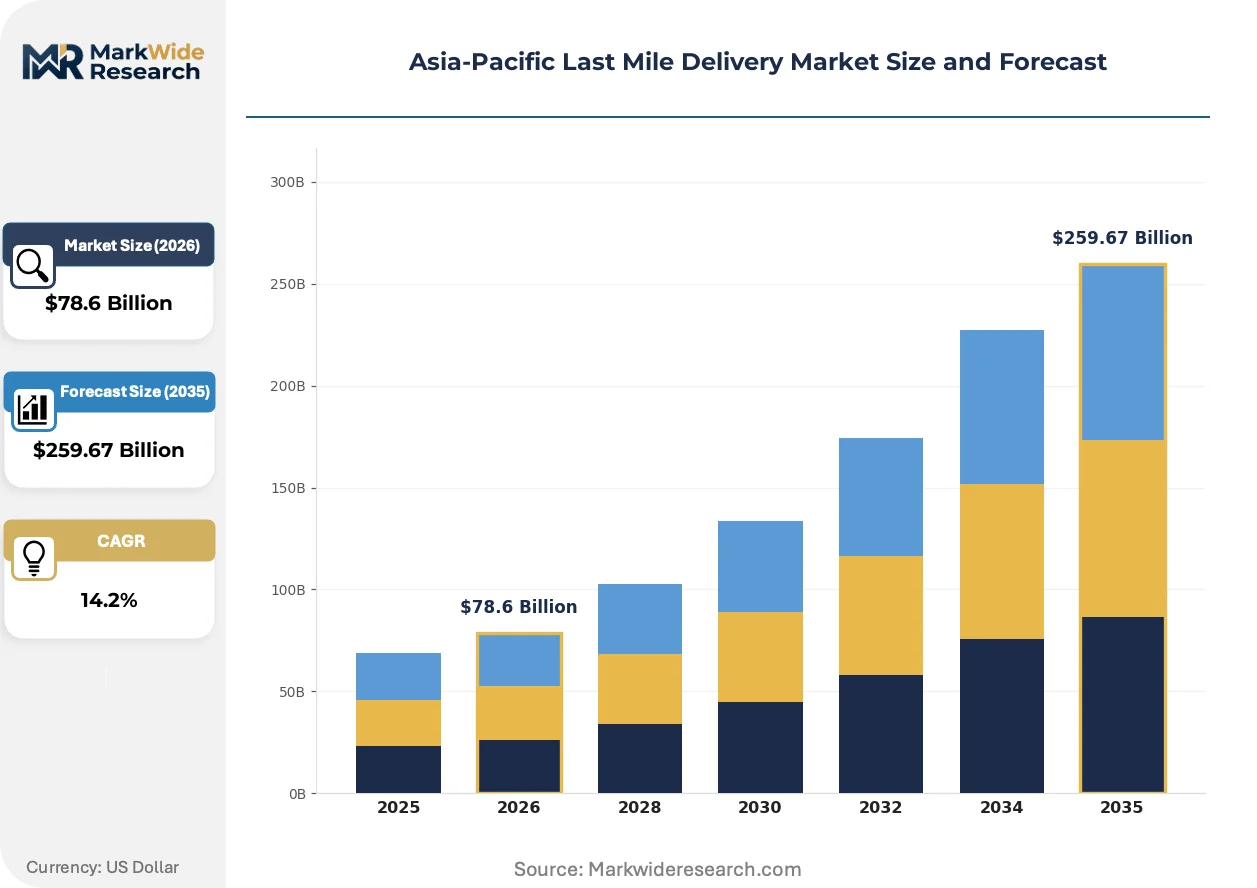
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $259.67 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Scheduled Delivery, On-Demand Delivery Delivery Mode: Motorcycle, Van, Bicycle, Drone Customer Type: Business-to-Consumer, Business-to-Business, eCommerce, Retail Technology: Mobile Apps, GPS Tracking, Route Optimization, Automated Systems |
| Companies Covered | SF Express, JD Logistics, ZTO Express, J&T Express, Ninja Van, Delhivery, GrabExpress, Lalamove, Qxpress, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Last Mile Delivery Market Trends and Innovations
Autonomous delivery pilots and AI-powered dispatch systems are fragmenting traditional hub-and-spoke models across Asia-Pacific urban corridors, while regulatory pressure on emissions and food safety accelerates capital redeployment toward electrified and refrigerated assets.
Electric cargo bikes and compact three-wheelers are fragmenting last-mile fleet composition in Chinese and Vietnamese cities. Metro operators in Shenzhen and Hanoi deploy these vehicles for sub-10-kilogram parcel volumes previously assigned to motorcycles. The technology is fragmenting vehicle-class economics, enabling dedicated lanes and parking privileges that compress per-stop costs in central business districts.
China's GB standards for electric two-wheelers, enforced by SAMR, mandate battery safety testing and fire-suppression specifications that disqualify uncertified vehicles from urban delivery registration. Fleet operators in Shanghai and Beijing face accelerated replacement cycles as local authorities deny license renewals for non-compliant assets. Premium express services absorb compliance costs fastest, while economy platforms delay conversion and risk operational suspension.
Scheduled delivery windows are displacing on-demand urgency among subscription commerce users in India's tier-two cities. Grocery and meal-kit platforms in Pune and Jaipur report higher retention when customers self-select two-hour arrival slots rather than paying premiums for immediate fulfillment. This behavioral shift concentrates volume predictability, allowing route density optimization that reduces per-delivery cost structures.
Asia-Pacific Last Mile Delivery Market Segmentation
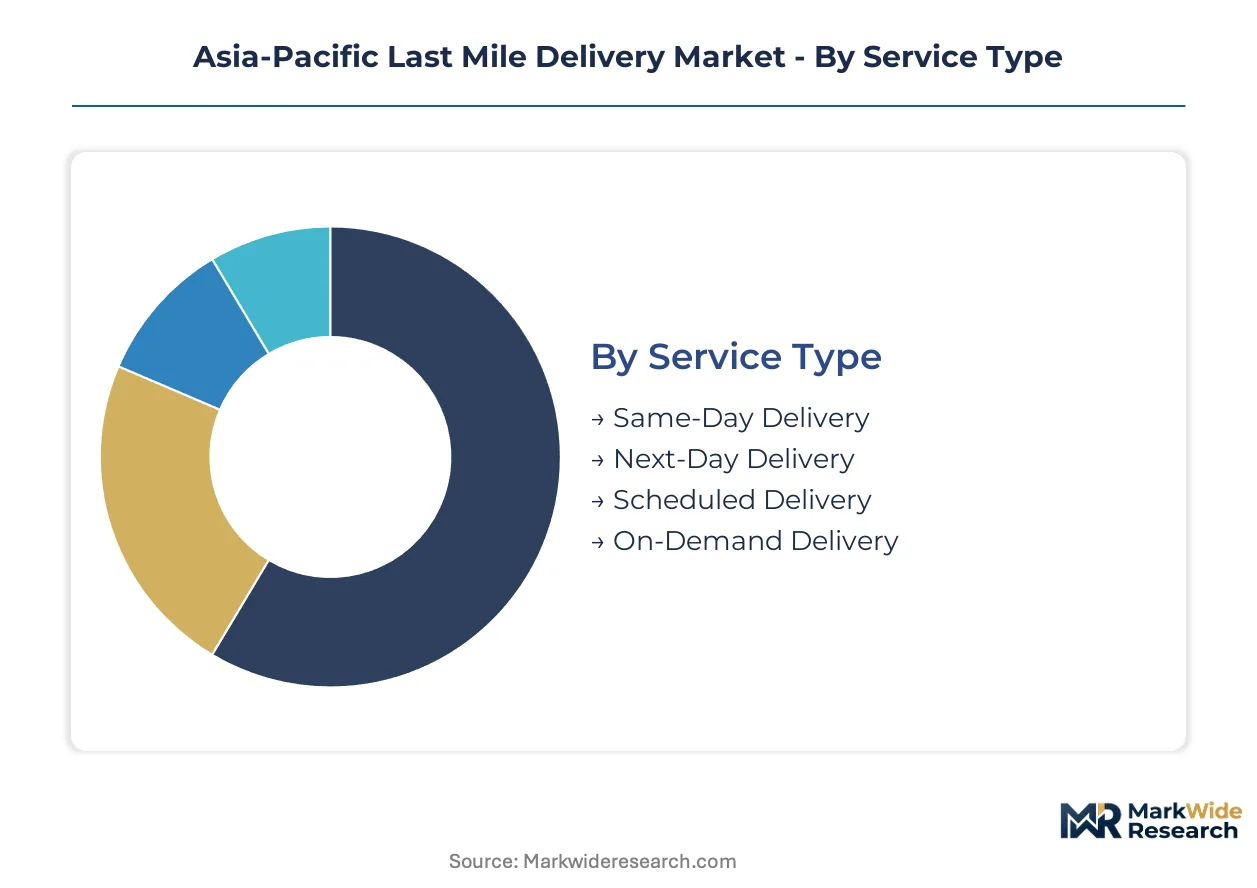
Last mile delivery segmentation in Asia-Pacific reflects divergent capital requirements across temperature-controlled and ambient networks. Service type and delivery mode choices determine compliance exposure to China's SAMR electric vehicle mandates and India's FSSAI cold-chain rules.
Service Type:
Regulatory differentiation separates time-definite services from flexible scheduling across temperature-sensitive and ambient cargo lanes.
- Same-Day Delivery:Compressed fulfillment windows demand real-time inventory positioning and dynamic dispatch algorithms. Premium positioning in Shanghai and Singapore absorbs higher per-stop costs through customer willingness to pay for speed.
- Next-Day Delivery:Standard express service balances cost efficiency with predictable arrival windows. Volume concentrates in cross-border eCommerce corridors where customs pre-clearance enables reliable next-morning delivery.
- Scheduled Delivery:Customer-selected arrival slots optimize route density for subscription commerce operators. Retention advantages in India's tier-two cities reduce churn for grocery and meal-kit platforms.
- On-Demand Delivery:Immediate fulfillment triggers surge pricing mechanisms during peak demand windows. Labor cost volatility in Jakarta and Bangkok compresses margins when driver supply concentrates on competing platforms.
Established volume favors next-day delivery; emerging adoption favors scheduled delivery.
Delivery Mode:
Vehicle classification determines lane access privileges and emissions compliance pathways across dense urban corridors.
- Motorcycle:Two-wheeled fleets dominate Bangkok, Jakarta, and Ho Chi Minh City through maneuverability in restricted traffic zones. SAMR GB standards for electric two-wheelers force battery safety certification and accelerated replacement cycles in Chinese cities.
- Van:Four-wheeled capacity serves refrigerated cargo and bulk parcel consolidation. FSSAI mandates for temperature-controlled transport compel van deployment across Indian tier-two cities where grocery eCommerce penetration deepens.
- Bicycle:Human-powered and electric-assisted cargo bikes access pedestrian zones and dedicated lanes. Deployment concentrates in Shenzhen and Hanoi central business districts for sub-10-kilogram parcel volumes.
- Drone:Autonomous aerial delivery remains experimental across archipelago geographies with limited road infrastructure. Regulatory frameworks in Indonesia and Philippines lag technical capability for commercial scaling.
Established volume favors motorcycle; emerging adoption favors van.
Customer Type:
End-user category shapes fulfillment network design through order frequency, parcel profile, and service level expectations.
- Business-to-Consumer:Individual recipient delivery dominates parcel volume with fragmented drop points. Residential access restrictions in Japanese and South Korean markets drive parcel locker adoption to reduce failed attempts.
- Business-to-Business:Commercial consignee concentration enables route optimization and scheduled arrival windows. Manufacturing supply chains in Vietnam and Thailand demand time-definite delivery for just-in-line production.
- eCommerce:Platform-aggregated demand generates scale economies for hub-and-spoke network design. Marketplace operators in Indonesia and Vietnam invest in proprietary last-mile capacity to control customer experience.
- Retail:Store-based fulfillment and ship-from-store models repurpose physical inventory for online orders. Click-and-collect growth in Australian and New Zealand markets reduces last-mile delivery cost exposure.
Established volume favors eCommerce; emerging adoption favors retail.
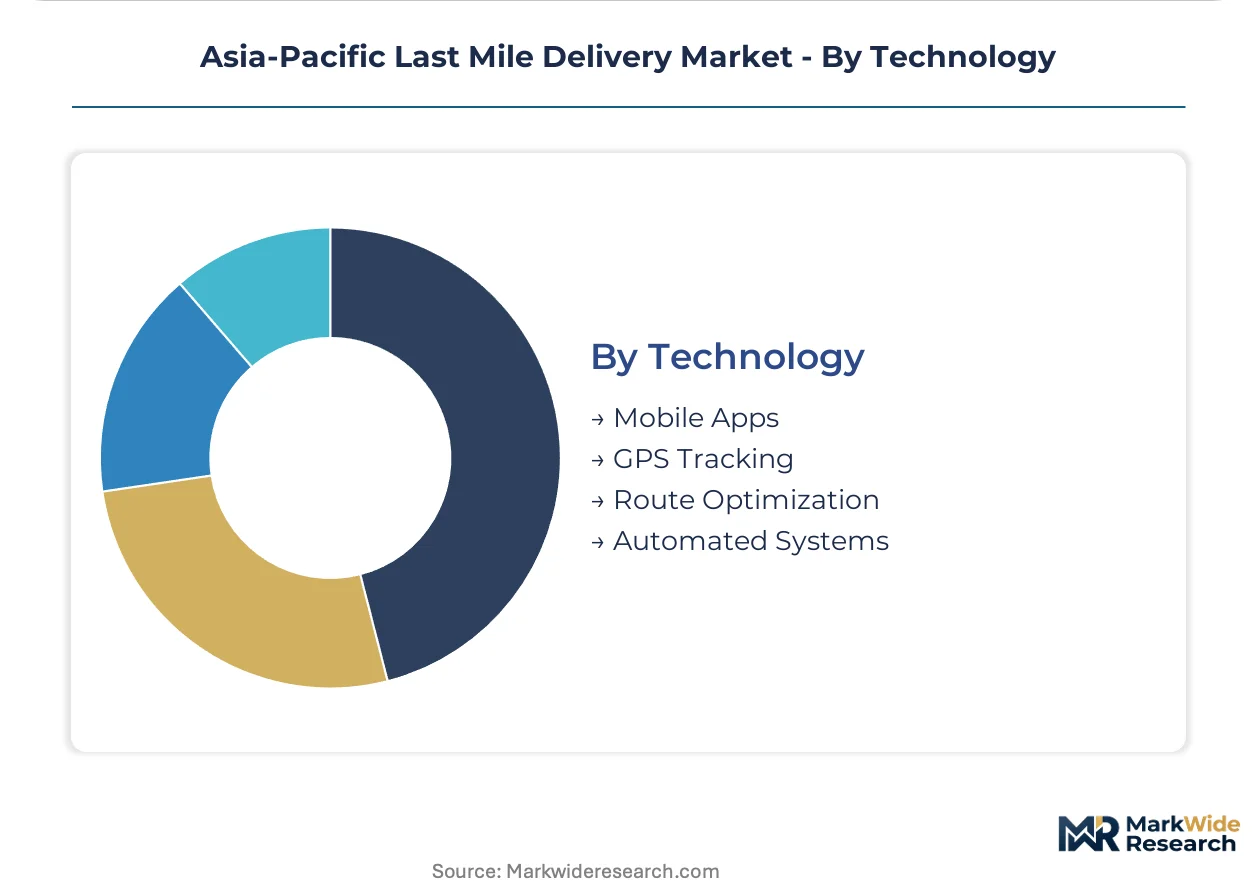
Technology:
Digital infrastructure investment separates integrated operators from legacy dispatch systems across tier-two city expansion.
- Mobile Apps:Driver-facing applications enable real-time order acceptance and navigation. Gig-economy platforms in Southeast Asia depend on smartphone penetration for driver pool recruitment and retention.
- GPS Tracking:Location visibility supports customer communication and exception management. Parcel networks across China and Japan deploy tracking as table stakes for premium service positioning.
- Route Optimization:Algorithmic dispatch reduces per-stop costs through density maximization. Legacy systems in Indian tier-two cities resist API integration, forcing manual overlay that degrades reliability.
- Automated Systems:Robotic sortation and autonomous vehicle pilots fragment traditional hub operations. METI-promoted locker interoperability in Japan reduces driver productivity loss from failed delivery attempts.
Established volume favors mobile apps; emerging adoption favors automated systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the region. Vietnamese and Indonesian buyers resist delivery premiums, while Singaporean and Australian customers absorb surcharges for speed and reliability.
China
E-commerce platform operators demand same-day fulfillment in Shanghai and Beijing. SAMR enforces GB standards for electric two-wheeler battery safety and fire suppression. Shenzhen operators accelerate fleet replacement to maintain urban delivery licenses.
India
Grocery platforms penetrate Pune and Jaipur with scheduled delivery slots. FSSAI mandates temperature-controlled transport for perishables, forcing refrigerated van deployment. Bangalore and Hyderabad hubs scale cold-chain capacity for tier-two city expansion.
Japan
Parcel locker adoption reduces failed delivery attempts in Tokyo and Osaka. METI promotes standardized locker interoperability across carrier networks. Kansai manufacturers integrate just-in-line delivery for automotive supply chains.
Indonesia
Online grocery platforms scale refrigerated networks across Java. Archipelago geography fragments inter-island cold-chain handoffs. Jakarta operators experiment with motorcycle-based chilled containers for fresh food commerce.
Vietnam
Hanoi and Ho Chi Minh City demand dedicated chilled fulfillment infrastructure. Ho Chi Minh City platforms deploy electric cargo bikes in central business districts. Da Nang emerges as a testbed for compact three-wheeler consolidation.
Asia-Pacific Last Mile Delivery Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with asset-heavy operators controlling fulfillment infrastructure while asset-light platforms minimize fixed-capital exposure. JD Logistics and SF Express anchor the integrated tier through proprietary warehouse and fleet networks. Ninja Van and Delhivery occupy the specialist tier with partner-driver models. Competitive moves concentrate on fleet electrification compliance and refrigerated capacity expansion.
Within the integrated logistics tier, JD Logistics and SF Express exemplify asset-heavy positioning through captive infrastructure. Ninja Van represents the asset-light archetype across Southeast Asian markets. Delhivery occupies a hybrid position in India, balancing proprietary hubs with gig-economy last-mile fulfillment.
| Leading Market Players |
|---|
| SF Express |
| JD Logistics |
| ZTO Express |
| J&T Express |
| Ninja Van |
| Delhivery |
| GrabExpress |
| Lalamove |
| Qxpress |
| Others |
Pricing and Supply Chain Analysis
Three-day inventory turns in refrigerated last-mile networks concentrate pricing power with asset-heavy operators who control cold-chain infrastructure across Chinese and Indian metropolitan corridors. This compression between perishable goods velocity and fixed-asset ownership shapes margin structures that asset-light platforms cannot replicate without capital-intensive fleet conversion.
Pricing Analysis
After-sales service contracts and extended maintenance agreements drive lifetime value for refrigerated fleet operators facing FSSAI and SAMR compliance cycles. Three-tier pricing structure across premium same-day, standard next-day, and economy scheduled delivery levels stratifies customer segments by urgency tolerance. Cost compression in economy tiers is intensifying because gig-economy driver wage floors are rising in Jakarta and Bangkok. Subscription commerce users in India's tier-two cities show least price sensitivity, while Indonesian archipelago buyers resist any delivery premium.
Supply Chain Analysis
Inventory velocity constraints in temperature-controlled networks tether procurement decisions to lithium-ion cell suppliers in China, South Korea, and Japan. Electric two-wheeler and compact three-wheeler production draws from battery pack assembly, HVAC refrigeration units, and telematics hardware. Single-source vulnerability concentrates in battery cell supply where raw material price volatility transmits directly to fleet operators. Distribution runs through hub-and-spoke networks with refrigerated micro-fulfillment nodes positioned within 50 kilometers of dense demand clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refrigeration technician scarcity and specialized cold-chain maintenance capability gaps are constraining expansion velocity for operators targeting Indonesian and Vietnamese grocery platforms. This skill bottleneck favors incumbents with established training pipelines over new entrants seeking rapid fleet deployment.
For Market Incumbents: Shield refrigerated network density in tier-two Indian cities by accelerating proprietary technician academy investments before FSSAI enforcement tightens. Consolidate position through backward integration into electric vehicle refurbishment facilities that reduce battery replacement costs under SAMR compliance cycles. Lock in exclusive partnerships with Indonesian inter-island ferry operators to secure cold-chain handoff infrastructure that emerging platforms cannot replicate. For New Entrants and Emerging Players: Differentiate on scheduled delivery slot reliability rather than speed by targeting Pune and Jaipur grocery subscribers who prioritize predictability over immediacy. Penetrate Vietnamese compact three-wheeler corridors in Da Nang where incumbent parcel networks have not deployed chilled infrastructure. Anchor go-to-market strategy around direct employer-driver models that reduce gig-economy wage volatility during peak demand windows. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across refrigerated last-mile networks as electric fleet conversion and cold-chain compliance compound fixed-asset requirements. Long-term viability favors operators with captive fulfillment infrastructure rather than asset-light platforms dependent on partner-driver elasticity. Target acquisition profiles should emphasize proprietary micro-fulfillment node networks in Indian and Southeast Asian tier-two cities. Monitor lithium-ion cell price trajectories as the critical inflection signal for fleet operator margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerated Fleet Electrification | SAMR GB standards compliance secures urban delivery licenses in Shanghai and Beijing. |
| Cold-Chain Micro-Fulfillment Expansion | FSSAI mandates force refrigerated van deployment across Indian tier-two city corridors. |
| Inter-Island Logistics Partnership | Indonesian archipelago geography fragments cold-chain handoffs without dedicated ferry alliances. |
| Technician Training Pipeline Investment | HVAC skill scarcity constrains refrigerated fleet maintenance capacity across Southeast Asia. |
| Parcel Locker Interoperability | METI-promoted standardization reduces failed delivery attempts in Japanese high-cost labor markets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet operations directors, cold-chain logistics managers, platform engineering leads, and regulatory compliance officers across China, India, Indonesia, and Vietnam. Secondary validation drew from SAMR GB standard filings, FSSAI cold-chain circulars, METI locker interoperability guidelines, customs trade data for electric two-wheeler imports, and SEC disclosures from listed logistics operators. Bottom-up service type segmentation triangulated against top-down regional demand aggregation.
Across the analysis window, projections integrated service type, delivery mode, customer category, and technology adoption dimensions with fleet electrification compliance timelines and refrigerated capacity buildout trajectories. CAGRs derived from segment-level volume buildups weighted by regional eCommerce penetration curves and grocery platform expansion schedules. Forecast inputs incorporated battery cost elasticity models and driver supply concentration indices for Southeast Asian gig-economy markets.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement of SAMR and FSSAI mandates, or abrupt lithium supply disruptions, would require recalibration. Forecasts reflect documented assumptions regarding platform consolidation rates and cold-chain infrastructure investment continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Australia Cold Chain Logistics Market
Logistics and Shipping
ASEAN Cross Border Road Freight Transport Market
Logistics and Shipping
New York Freight and Logistics Market
Logistics and Shipping
Saudi Arabia Secure Logistics Market
Logistics and Shipping
Asean Freight Forwarding Market
Logistics and Shipping
GCC Air Freight Transport Market
Logistics and Shipping
Logistics Data Quality and Normalization Services Market
Logistics and Shipping
Japan Third-Party Logistics (3PL) Market
Logistics and Shipping
North America FMCG Logistics Market
Logistics and Shipping
New Zealand Freight and Logistics Market
Logistics and Shipping
Global Logistics Market
Logistics and Shipping
Tanker Shipping Market
Logistics and Shipping
Asia-Pacific less-Than Container Load (LCL) Market
Logistics and Shipping
North America Sea Freight Forwarding Market
Logistics and Shipping
Chemical Tanker Shipping Market
Logistics and Shipping
United Kingdom Domestic Courier, Express, and Parcel (CEP) Market