
 Asean Freight Forwarding Market | 2026-2036
Asean Freight Forwarding Market Size, Share, and Industry Trends Forecast 2026-2036
Asean Freight Forwarding Market Outlook
EU Green Deal-aligned emissions reporting is hardening buyer mandates across European-destined export lanes from ASEAN. DSV A/S leverages its integrated air-sea platform to capture pharmaceutical and automotive flows out of Singapore and Bangkok. Kerry Logistics Network Limited anchors last-mile distribution through its Thailand-Cambodia-Vietnam road network. Nippon Express Holdings, Inc. differentiates via temperature-controlled capabilities serving Japanese automotive parts suppliers in Indonesia.
Asean freight forwarding encompasses the coordination, documentation, and multimodal management of cargo shipments across the ten-member regional bloc, typically involving customs brokerage, cargo consolidation, and carrier allocation across air, ocean, road, and rail legs with transit times ranging from same-day regional trucking to two-week ocean loops. The primary commercial purpose is to reduce landed costs for manufacturers and traders by optimizing modal choice, consolidating volumes, and navigating divergent national customs regimes. Ocean freight dominates value contribution given ASEAN's position as a global electronics and apparel export hub, while air freight captures premium margin pools from semiconductor and pharmaceutical shippers requiring speed and temperature integrity. Road freight sustains the fastest volume expansion as Vietnam, Thailand, and Cambodia deepen cross-border highway connectivity under the ASEAN Transport Facilitation framework.
Indonesia's Ministry of Transportation and Vietnam's Directorate for Roads of Vietnam enforce divergent truck weight and emissions standards that fragment fleet interoperability across borders. Thailand's Department of Land Transport mandates GPS tracking and digital manifest submission for all cross-border cargo, reshaping technology investment requirements for forwarders operating the Bangkok-Laos-Vietnam corridor. Singapore's Maritime and Port Authority maintains strict bunker fuel and vessel emissions protocols that filter ocean carrier eligibility for hub-and-spoke services. Stakeholders must monitor which national digital trade platforms achieve interoperability first, as this will determine where customs clearance speed becomes a competitive moat rather than a operational bottleneck.
Market Dynamics
Cross-border highway connectivity under the ASEAN Transport Facilitation framework is compressing transit times between Vietnam, Thailand, and Cambodia, forcing forwarders to reconfigure hub-and-spoke networks around road corridors rather than traditional port-centric models.
Growth Catalysts
- Electronics export corridors:Factory clusters near Hai Phong and Bac Ninh in Vietnam's northern industrial corridor are pulling dedicated freight capacity from regional hubs, creating sustained demand for multimodal solutions.
- EU Green Deal alignment:Emissions reporting mandates are hardening buyer requirements across European-destined export lanes, rewarding forwarders with verified carbon tracking capabilities.
- Indonesia's logistics masterplan:Port modernization programs and carrier certification reforms are unlocking container throughput capacity and streamlining customs interfaces.
Market Restraints
- Divergent national standards:Indonesia's Ministry of Transportation and Vietnam's Directorate for Roads enforce incompatible truck weight and emissions standards that fragment fleet interoperability across borders.
- Digital compliance fragmentation:Thailand's Department of Land Transport mandates GPS tracking and digital manifest submission for cross-border cargo, imposing technology investment burdens on smaller forwarders.
- Bunker fuel protocols:Singapore's Maritime and Port Authority maintains strict vessel emissions standards that filter ocean carrier eligibility for hub-and-spoke services, constraining carrier choice.
Strategic Opportunities
- Laos-Cambodia connectivity gaps:Underdeveloped cross-border road infrastructure between these markets offers first-mover advantage for forwarders investing in dedicated trucking assets and local customs partnerships.
- Temperature-controlled pharmaceutical flows:Cold chain capabilities remain undersupplied for ASEAN's growing vaccine and biologics distribution requirements.
- Digital trade platform interoperability:National single-window systems achieving cross-border integration will create competitive moats for forwarders with API-ready customs clearance architectures.
Industry Challenges
- Customs brokerage talent scarcity:Specialized expertise in navigating divergent national documentation regimes—particularly Indonesia's complex import licensing—commands premium wages and constrains scaling.
- Legacy system integration:Forwarders must bridge proprietary transport management systems with government digital platforms while maintaining operational continuity during migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asean Freight Forwarding Market |
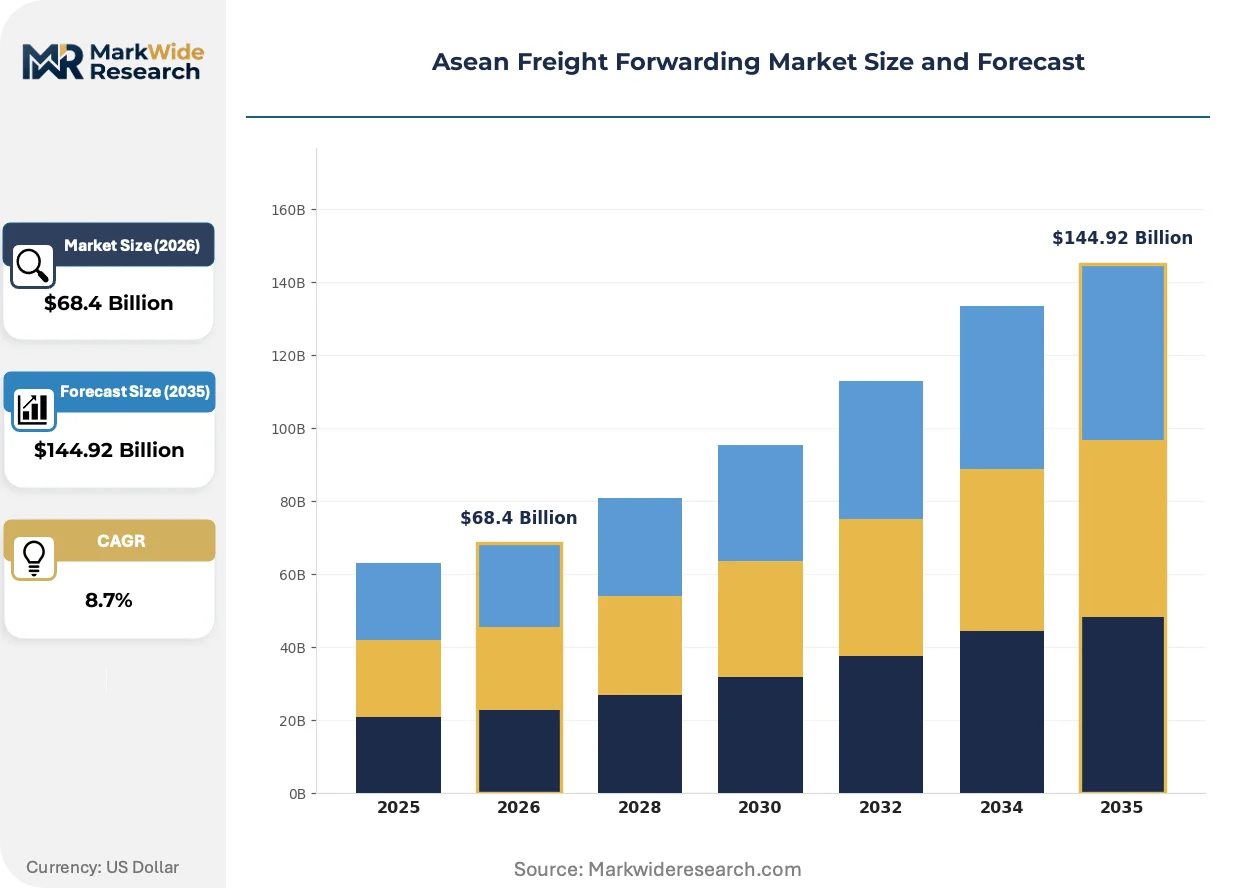
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $144.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Air Freight, Ocean Freight, Road Freight, Rail Freight Customer Type: Manufacturers, Retailers, Importers, Exporters Transportation Mode: Full Truck Load, Less Than Truck Load, Intermodal, Bulk Shipping Delivery Model: Door-to-Door, Port-to-Port, Airport-to-Airport, Terminal-to-Terminal |
| Companies Covered | Deutsche Post DHL Group (DHL Global Forwarding), Kuehne + Nagel International AG, DSV A/S, Sinotrans Limited, Kerry Logistics Network Limited, DB Schenker, Nippon Express Holdings, Inc., CEVA Logistics, Yusen Logistics Co., Ltd., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asean Freight Forwarding Market Strategic Shifts
Digital freight platforms and sensor-enabled cargo monitoring are compressing information asymmetries between shippers and carriers, while sustainability verification tools are becoming bid requirements rather than differentiators.
Blockchain-enabled bill-of-lading documentation is rewriting trust architectures in multimodal handoffs. Electronics manufacturers with just-in-time supply chains are adopting these systems fastest. The technology is rewriting liability allocation between ocean and road carriers by creating immutable custody records.
Thailand's Department of Land Transport now mandates real-time GPS tracking and electronic manifest submission for all cross-border cargo. This regulatory pressure is accelerating cloud-based fleet management adoption among Bangkok-Laos-Vietnam corridor operators. Mid-size forwarders without integrated telematics face exclusion from approved carrier lists.
Shippers are unbundling freight procurement from integrated logistics contracts, creating spot-market liquidity platforms for containerized ASEAN-Europe lanes. Traditional annual rate negotiations are fragmenting into quarterly or monthly bidding cycles. Vietnam-based electronics exporters are driving this behavioral shift most aggressively.
Asean Freight Forwarding Market Segmentation
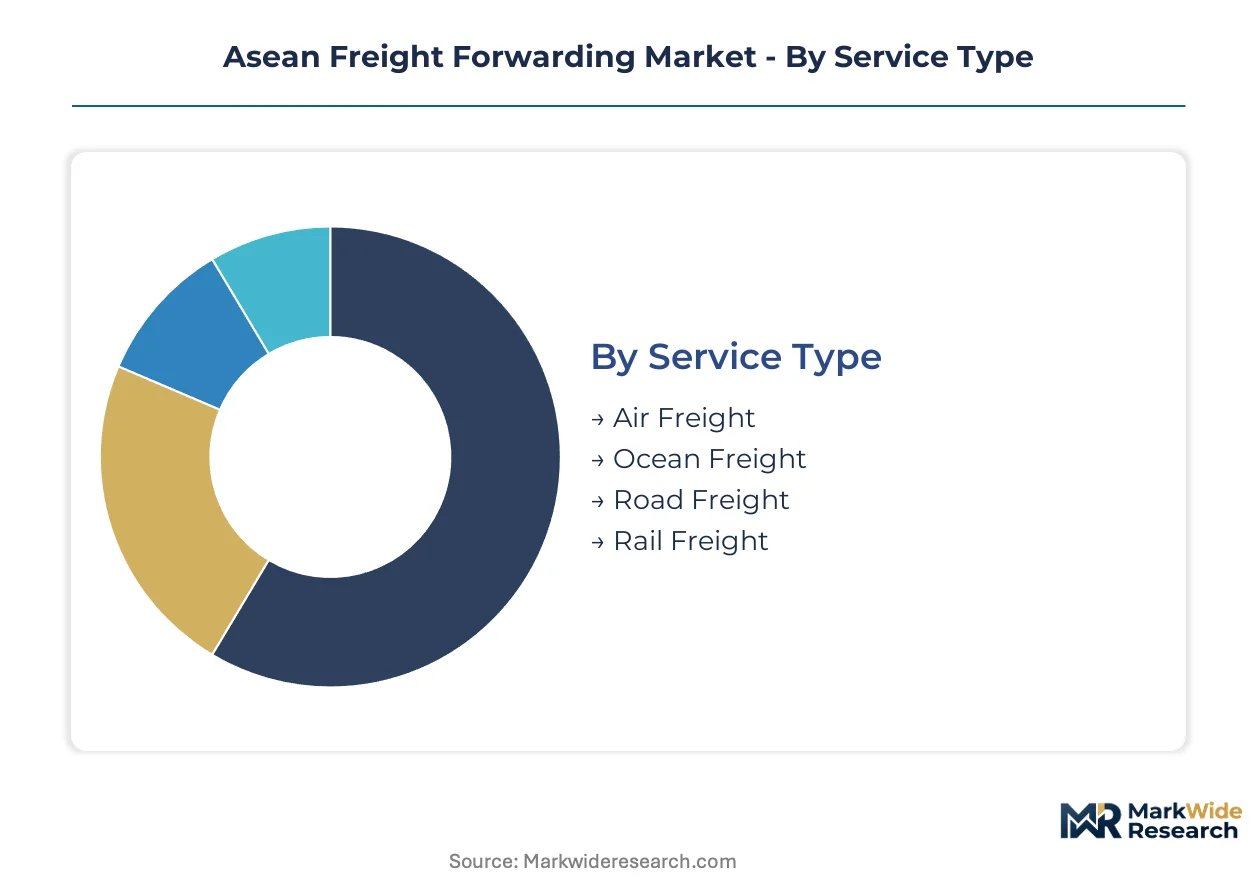
Freight forwarding segmentation in ASEAN reflects divergent buyer priorities across electronics exporters, automotive manufacturers, and pharmaceutical distributors. Modal choice and service configuration directly determine landed cost competitiveness in Vietnam's northern industrial corridor and Indonesia's port modernization zones.
Service Type:
Ocean freight buyers prioritize container throughput reliability; air freight buyers demand temperature integrity and customs velocity.
- Ocean Freight:Full-container-load coordination dominates value contribution, driven by ASEAN's electronics and apparel export concentration. Factory clusters near Hai Phong and Bac Ninh pull dedicated feeder capacity from Singapore and Port Klang, while Indonesia's port modernization programs expand carrier certification slots for mainline vessels.
- Road Freight:Cross-border trucking sustains the steepest expansion trajectory as Vietnam, Thailand, and Cambodia deepen highway connectivity under ASEAN Transport Facilitation frameworks. GPS tracking mandates from Thailand's Department of Land Transport reshape technology investment requirements for corridor operators.
- Air Freight:Semiconductor and pharmaceutical shippers command premium margins through speed-sensitive routing from Singapore Changi and Bangkok Suvarnabhumi. Temperature-controlled capabilities differentiate specialist forwarders serving Japanese automotive parts suppliers in Indonesia.
- Rail Freight:Emerging multimodal option connecting China's manufacturing interior to ASEAN markets via Laos-China Railway corridors, with cargo consolidation points developing at Vientiane and Boten border terminals.
Volume sits with Ocean Freight; growth tilts toward Road Freight.
Customer Type:
Procurement scale and supply chain complexity separate enterprise manufacturers from trading-house intermediaries.
- Manufacturers:Electronics producers across Vietnam and Thailand drive just-in-time multimodal demand, unbundling freight procurement from integrated logistics contracts into shorter bidding cycles. EU Green Deal alignment hardens emissions reporting requirements for European-destined export lanes.
- Exporters:Apparel and agricultural commodity shippers concentrate in Indonesia's logistics masterplan zones and Cambodia's garment processing districts, navigating divergent national customs documentation regimes.
- Retailers:Omnichannel distribution networks spanning Thailand-Cambodia-Vietnam road corridors require last-mile integration and inventory visibility through cloud-based fleet management systems.
- Importers:Raw material and component sourcing operations face customs brokerage talent scarcity, particularly for Indonesia's complex import licensing procedures.
Revenue concentrates with Manufacturers; margin expansion favors Retailers.
Transportation Mode:
Cargo density and consolidation economics determine modal selection across ASEAN's fragmented highway and port infrastructure.
- Full Truck Load:Direct dedicated capacity serves factory clusters with predictable volume patterns, leveraging cross-border highway compression between Vietnam, Thailand, and Cambodia.
- Intermodal:Container handoffs between ocean, road, and rail legs demand blockchain-enabled custody documentation for electronics manufacturers with just-in-time supply chains.
- Less Than Truck Load:Consolidation economics attract mid-size shippers without dedicated fleet requirements, though divergent truck weight standards between Indonesia and Vietnam fragment interoperability.
- Bulk Shipping:Agricultural commodities and raw materials move through specialized vessel classes serving Indonesia's archipelago distribution and Mekong Delta rice export corridors.
Operational scale clusters with Full Truck Load; flexibility advantages accrue to Intermodal.
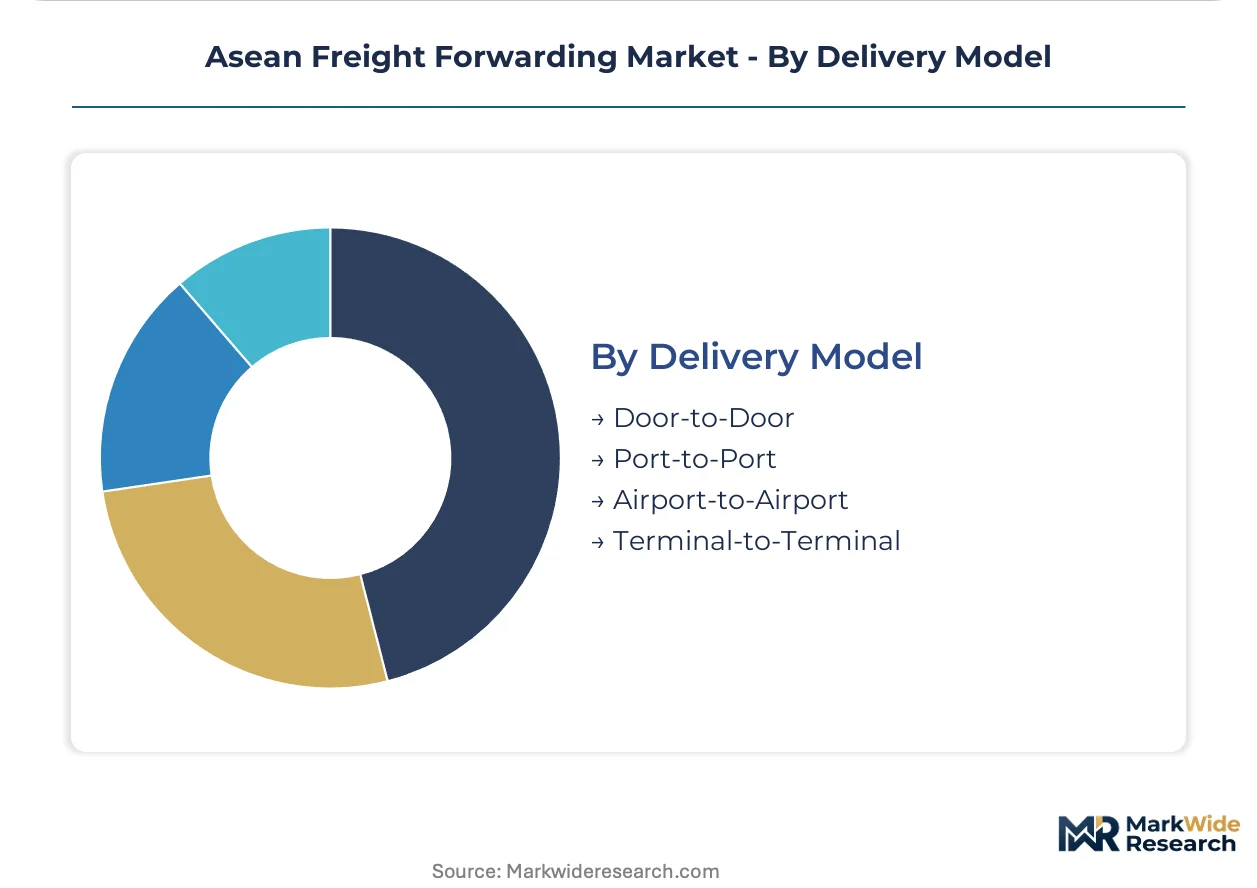
Delivery Model:
Control handoff points separate integrated logistics buyers from port-centric procurement.
- Door-to-Door:End-to-end liability coverage appeals to pharmaceutical and automotive shippers requiring temperature integrity across multimodal handoffs, with Kerry Logistics Network anchoring Thailand-Cambodia-Vietnam road distribution.
- Port-to-Port:Traditional ocean contracting persists for commodity exporters with established customs broker relationships at origin and destination terminals.
- Airport-to-Airport:Speed-critical semiconductor and biologics flows leverage DSV A/S integrated air-sea platforms from Singapore and Bangkok hubs.
- Terminal-to-Terminal:Cost-focused procurement for standardized containerized cargo, with Singapore's Maritime and Port Authority bunker fuel protocols filtering carrier eligibility.
Contract value aggregates at Door-to-Door; spot-market liquidity concentrates at Port-to-Port.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hai Phong and Bac Ninh anchor freight demand across Vietnam's northern industrial corridor, where electronics factory clusters pull dedicated capacity from regional hubs. Indonesia's port modernization programs and Thailand's GPS tracking mandates reshape carrier certification requirements. Divergent national standards fragment fleet interoperability despite ASEAN Transport Facilitation framework commitments.
Vietnam
Electronics manufacturers near Hai Phong and Bac Ninh drive multimodal demand, expanding cross-border sourcing from Thai component suppliers. The Directorate for Roads of Vietnam enforces truck weight standards incompatible with Indonesian regulations. Factory clusters along the northern industrial corridor pull dedicated feeder capacity from Singapore and Port Klang.
Thailand
Automotive parts suppliers and pharmaceutical distributors command premium cold chain services from Bangkok Suvarnabhumi. The Department of Land Transport mandates real-time GPS tracking and electronic manifest submission for cross-border cargo. Road corridors through the Bangkok-Laos-Vietnam axis compress transit times and reconfigure hub-and-spoke networks.
Indonesia
Port modernization programs under the national logistics masterplan unlock container throughput capacity at Tanjung Priok and Surabaya. The Ministry of Transportation enforces emissions standards that fragment fleet interoperability with Vietnamese truck specifications. Japanese automotive parts suppliers in Bekasi and Karawag demand temperature-controlled capabilities from specialist forwarders.
Singapore
Semiconductor and pharmaceutical shippers leverage integrated air-sea platforms through Changi Airport and PSA terminals. The Maritime and Port Authority maintains strict bunker fuel protocols that filter ocean carrier eligibility for hub-and-spoke services. Pharmaceutical flows to European destinations face hardening EU Green Deal emissions reporting mandates.
Cambodia
Garment processing districts in Phnom Penh and Bavet generate consolidation demand for cross-border trucking to Vietnam's Cai Mep port. Underdeveloped Laos-Cambodia connectivity gaps offer first-mover advantage for forwarders investing in dedicated trucking assets. Customs partnerships at Poipet and Bavet border terminals determine clearance velocity.
Asean Freight Forwarding Market Competitive Environment
Premium-margin players sit above commodity-margin players across temperature-controlled and digital integration capabilities. The vendor base concentrates around integrated logistics networks with multimodal assets, while specialized cold chain operators capture pharmaceutical and automotive segments. Three archetypes dominate: global integrators with owned air-sea platforms, regional road network specialists, and temperature-controlled niche operators. Competitive moves center on API-ready customs architectures and cross-border highway asset acquisitions.
Among global integrators, Deutsche Post DHL Group and Kuehne + Nagel International AG exemplify scale-driven archetypes with multimodal asset footprints. DSV A/S occupies a position within the premium-tier vector through its integrated air-sea platform serving pharmaceutical and automotive flows. Kerry Logistics Network Limited represents the regional road specialist archetype, anchoring last-mile distribution across Thailand-Cambodia-Vietnam corridors. These three companies illustrate how geographic coverage depth and modal integration intensity separate margin tiers in ASEAN forwarding.
| Leading Market Players |
|---|
| Deutsche Post DHL Group (DHL Global Forwarding) |
| Kuehne + Nagel International AG |
| DSV A/S |
| Sinotrans Limited |
| Kerry Logistics Network Limited |
| DB Schenker |
| Nippon Express Holdings, Inc. |
| CEVA Logistics |
| Yusen Logistics Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Horizontal integration across Thailand-Cambodia-Vietnam road corridors anchors supply positioning for regional specialists while compressing pricing power for port-centric operators. Captive fleet ownership along the Bangkok-Laos-Vietnam axis lets forwarders command premium door-to-door rates, whereas asset-light competitors face margin erosion from spot-market liquidity platforms.
Pricing Analysis
Outcome-based pricing tied to customs clearance velocity and temperature integrity anchors premium tiers in pharmaceutical and semiconductor lanes. Three-tier pricing structure separates certified cold chain operators from standard multimodal providers and economy-grade port-to-port brokers. Cost compression in economy ocean freight intensifies as Vietnam-based electronics exporters fragment annual contracts into quarterly bidding cycles. Small and mid-size forwarders without integrated telematics exhibit highest price sensitivity, while enterprise manufacturers prioritize uptime guarantees over rate minimization.
Supply Chain Analysis
Regional distribution centers cluster around Singapore's PSA terminals, Thailand's Laem Chabang port, and Vietnam's Cai Mep deep-water facility, forming a hub-and-spoke pattern for ASEAN-Europe lanes. Container chassis, refrigerated units, and cross-border trucking permits constitute critical input dependencies. Single-source vulnerability concentrates in Singapore's Maritime and Port Authority bunker fuel certification, which filters carrier eligibility for hub-and-spoke services. Distribution runs through multimodal handoffs at Vientiane and Boten border terminals, with blockchain-enabled custody documentation reducing liability gaps between ocean and road carriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is unfolding as forwarders pursue captive control over cross-border trucking assets to defend margin pools against digital freight platforms. Upstream fleet ownership in Laos-Cambodia connectivity gaps represents the critical lever separating premium-tier operators from commodity-margin competitors.
For Market Incumbents: Cement control over Thailand-Cambodia-Vietnam road corridors through dedicated asset acquisitions and customs partnership lock-ins at Poipet and Bavet terminals. Digital freight platforms threaten spot-market revenue streams; API-ready customs clearance architectures offer defensive differentiation against unbundled procurement trends.
For New Entrants and Emerging Players: Begin with underdeveloped Laos-Cambodia cross-border lanes where infrastructure gaps deter integrated logistics networks from rapid deployment. Temperature-controlled pharmaceutical distribution offers the most penetrable white space, with biologics shippers undersupplied by incumbent cold chain capabilities. A go-to-market angle anchored to EU Green Deal emissions verification tools attracts European-destined electronics exporters.
For Investors and Strategic Acquirers: Exit pathways concentrate in regional road network specialists with captive fleet assets and established customs broker relationships. Long-term viability hinges on forwarders bridging proprietary transport management systems with interoperable national digital trade platforms. Watch for the first ASEAN member achieving cross-border single-window integration as the inflection signal determining competitive moat formation.
| Strategic Initiative | Industry Significance |
|---|---|
| Cross-Border Fleet Acquisition | Captive trucking assets along Bangkok-Laos-Vietnam corridors compress transit times and lock in pharmaceutical shippers. |
| API-Ready Customs Architecture | Thailand's GPS tracking mandates exclude mid-size forwarders lacking integrated telematics from approved carrier lists. |
| Temperature-Controlled Capability Expansion | Japanese automotive parts suppliers in Indonesia's Bekasi cluster demand verified cold chain credentials from specialist operators. |
| Digital Trade Platform Integration | National single-window interoperability determines where customs clearance speed becomes competitive moat versus operational bottleneck. |
| EU Green Deal Verification Tools | Emissions reporting mandates harden bid requirements for European-destined export lanes from Vietnam's northern industrial corridor. |
Study Parameters
Independent corroboration across freight forwarding executives, customs brokerage specialists, and electronics supply chain managers underwrites the qualitative findings in this study. Primary fieldwork with Thailand's Department of Land Transport officials and Vietnam's Directorate for Roads of Vietnam supplemented secondary validation from ASEAN Transport Facilitation framework documents, national logistics masterplan filings, and carrier certification registries. Bottom-up volume modeling across service type, customer segment, and transportation mode triangulates against top-down macroeconomic indicators for the regional bloc.
Comparable-period anchoring to historical trade flow patterns across the projection horizon ensures forecast consistency with observed modal shift trajectories. The analytical framework segments by service type, customer archetype, transportation mode, and delivery model, with cross-border highway connectivity intensity serving as an additional industry-specific dimension. CAGRs derive from elasticity-adjusted trade volume projections incorporating electronics export corridor expansion and port modernization program timelines.
Underlying measurement precision varies by segment; ocean freight and established air corridors carry tighter precision than emerging rail intermodal options. Forecasts reflect documented assumptions regarding ASEAN single-window interoperability progress and EU Green Deal implementation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Australia Last Mile Delivery Market
Logistics and Shipping
China Local Courier Market
Logistics and Shipping
Middle East and Africa Courier Market
Logistics and Shipping
North America Cargo Inspection Market
Logistics and Shipping
Romania Freight and Logistics Market
Logistics and Shipping
Turkey Cold Chain Logistics Market
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
Global Container Terminal Operations Market
Logistics and Shipping
Spain Third-Party Logistics (3PL) Market
Logistics and Shipping
United Kingdom Contract Logistics Market
Logistics and Shipping
Chemical Tanker Shipping Market
Logistics and Shipping
China Freight Forwarding Market
Logistics and Shipping
Latin America Container Terminal Operations Market
Logistics and Shipping
Pharmaceutical Logistics Market
Logistics and Shipping
Europe Domestic Courier Market
Logistics and Shipping
Straddle Carrier Market