
 Global Logistics Market | 2026-2036
Global Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Logistics Market Outlook
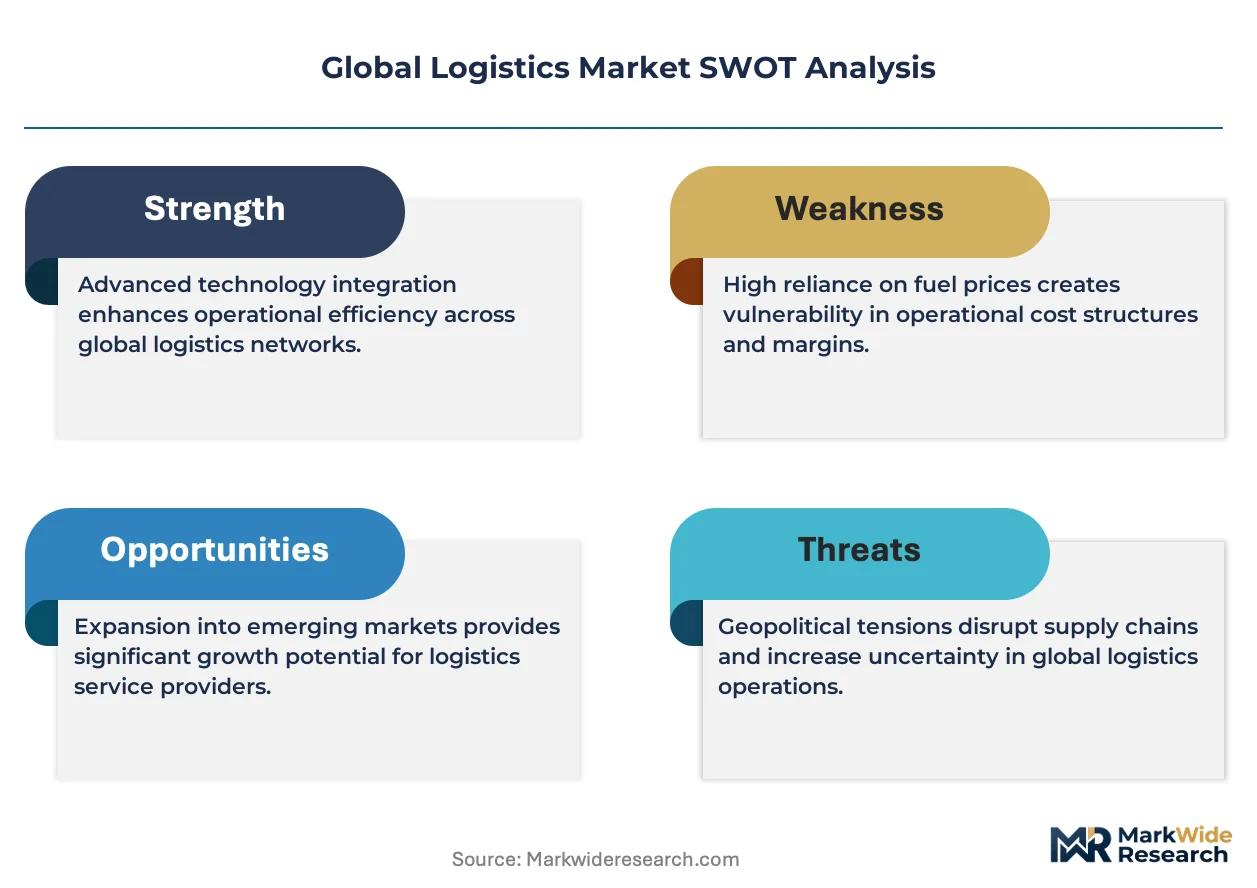
Premium cold-chain and specialized pharmaceutical logistics is consolidating around temperature-controlled infrastructure and compliance certification, while commodity freight remains fragmented on price. DHL Supply Chain & Global Forwarding leverages its pharmaceutical certification network across European hubs. Maersk Logistics anchors ocean-air intermodal capacity on Asia-Europe lanes. C.H. Robinson competes through digital freight matching platforms that compress spot-market transaction cycles.
Logistics encompasses the planning, execution, and control of goods movement across supply chains, requiring coordination of transportation modes, inventory positioning, and information systems operating within temperature tolerances of minus 80 to plus 25 degrees Celsius for pharmaceutical-grade networks. Its commercial purpose centers on minimizing total landed cost while meeting delivery-time commitments for industrial and consumer supply chains. Freight forwarding and customs brokerage command disproportionate margin pools as regulatory complexity intensifies trade documentation requirements. Multimodal delivery networks are expanding fastest where shippers seek carbon-accounted routing alternatives to pure air freight. Warehousing faces structural pressure from automated fulfillment centers that compress labor cost structures in e-commerce end-user segments.
The EU Green Deal and its Fit for 55 package enforce emissions reporting on intra-European trucking fleets, while the IMO's carbon intensity indicators reshape ocean carrier fuel strategies on trans-Pacific routes. India's BIS certification requirements for cold-chain equipment and the US EPA heavy-duty truck emissions standards collectively elevate capital barriers for fleet operators. Stakeholders must monitor how carbon-border adjustment mechanisms redirect manufacturing sourcing and the freight corridors that serve them.
Market Dynamics
E-commerce fulfillment networks are compressing traditional retail distribution timelines while EU Green Deal emissions mandates force fleet operators toward alternative powertrains across European corridors.
Growth Catalysts
- EU Green Deal Fit for 55:Mandatory emissions reporting on intra-European trucking fleets accelerates electric and hydrogen vehicle procurement among contract logistics providers serving German manufacturing clusters.
- India's industrial belt:Manufacturing relocation from coastal China concentrates demand for multimodal freight corridors connecting Mumbai port to Delhi-NCR warehousing zones.
- Cold-chain infrastructure:BIS certification requirements for pharmaceutical-grade temperature control equipment expand addressable market for certified fleet operators serving CDSCO-regulated biologics distribution.
Market Restraints
- IMO carbon intensity indicators:Ocean carrier fuel strategies face structural cost pressure on trans-Pacific routes as low-sulfur fuel premiums compress margin pools for non-integrated forwarders.
- European trucking fleet concentration:Emissions trading scheme permit costs disproportionately burden small and mid-sized carriers operating sub-50 vehicle fleets across Benelux corridors.
- Alternative powertrain technical limitation:Battery energy density constraints restrict electric heavy-duty truck range below 500 kilometers, excluding long-haul lanes from immediate electrification.
Strategic Opportunities
- Carbon-accounted routing:Multimodal delivery networks combining rail and short-sea shipping capture shipper preference as Scope 3 reporting requirements tighten under CSRD disclosure mandates.
- Automated fulfillment centers:Robotics integration in e-commerce end-user segments compresses labor cost structures for operators serving same-day delivery promises in dense urban zones.
- India PLI scheme:Production-linked incentives for domestic manufacturing expand contract logistics demand for inbound component warehousing and finished goods distribution within the subcontinent.
Industry Challenges
- Refrigeration technician scarcity:Specialized certification for minus 80 degrees Celsius pharmaceutical handling exceeds available trained workforce supply in emerging market hubs.
- Legacy WMS integration:Automated storage and retrieval systems require costly middleware development to synchronize with incumbent warehouse management platforms deployed across brownfield distribution centers.
- Cross-border documentation friction:Post-Brexit customs complexity and divergent digital trade documentation standards between UK and EU customs authorities extend clearance timelines on Channel routes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Logistics Market |
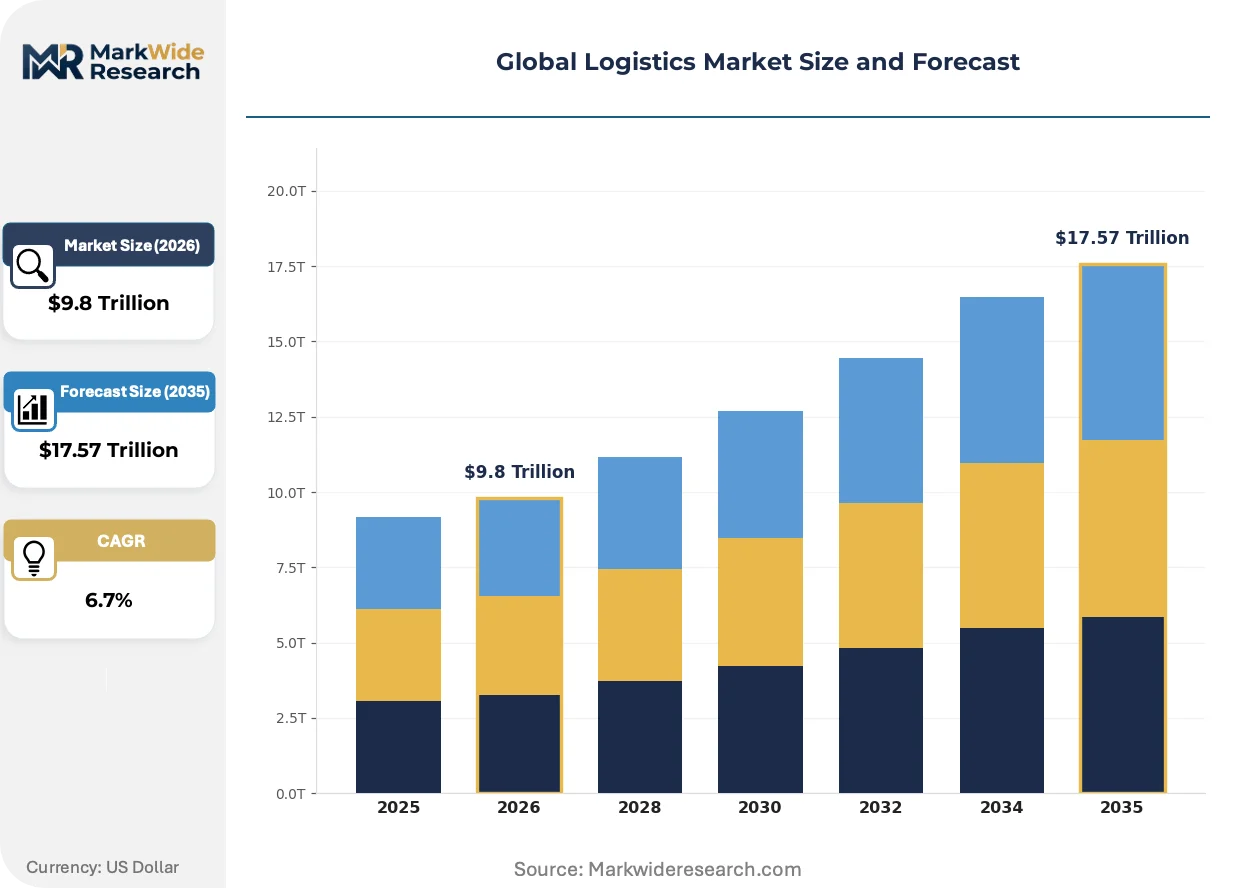
| Market Size in 2026 | $9.8 Trillion |
| Market Size in 2035 | $17.57 Trillion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Customs Brokerage Delivery Mode: By Land, By Sea, By Air, Multimodal End User: Retail, E-commerce, Manufacturing, Pharmaceuticals Technology: IoT, AI, Blockchain, Automation |
| Companies Covered | DSV, CEVA Logistics, Amazon, C.H. Robinson, Nippon Express, DHL Supply Chain & Global Forwarding, DB Schenker, Maersk Logistics, Kuehne + Nagel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Logistics Market Strategic Shifts
Digital freight matching platforms compress spot-market transaction cycles while autonomous yard management and predictive cargo routing reshape operational economics across asset-light and asset-heavy business models.
Battery-electric terminal tractors and yard hostlers are electrifying port and intermodal facility operations where fixed duty cycles and predictable charging windows eliminate range anxiety concerns. Maersk and DP World deploy these units at Rotterdam and Singapore terminals. The technology is electrifying equipment procurement strategies among terminal operators seeking to preempt EU port emissions regulations.
EPA heavy-duty truck emissions standards phase in stringent NOx limits for model year 2027 vehicles, forcing engine manufacturers toward advanced aftertreatment systems and compressed natural gas alternatives. Fleet operators face premature asset retirement risk on US interstate corridors. California Air Resources Board zero-emission mandates accelerate pilot deployments of hydrogen fuel cell tractors at Long Beach port drayage lanes.
Shippers now specify carbon-accounted routing alternatives in procurement tenders, displacing pure cost-based carrier selection with emissions-verified lane assignments. Consumer brands with Science Based Targets initiative commitments drive this specification shift. European automotive and fashion verticals demonstrate highest adoption intensity, with German OEMs requiring primary logistics partners to disclose well-to-wheel emissions per ton-kilometer.
Global Logistics Market Segmentation
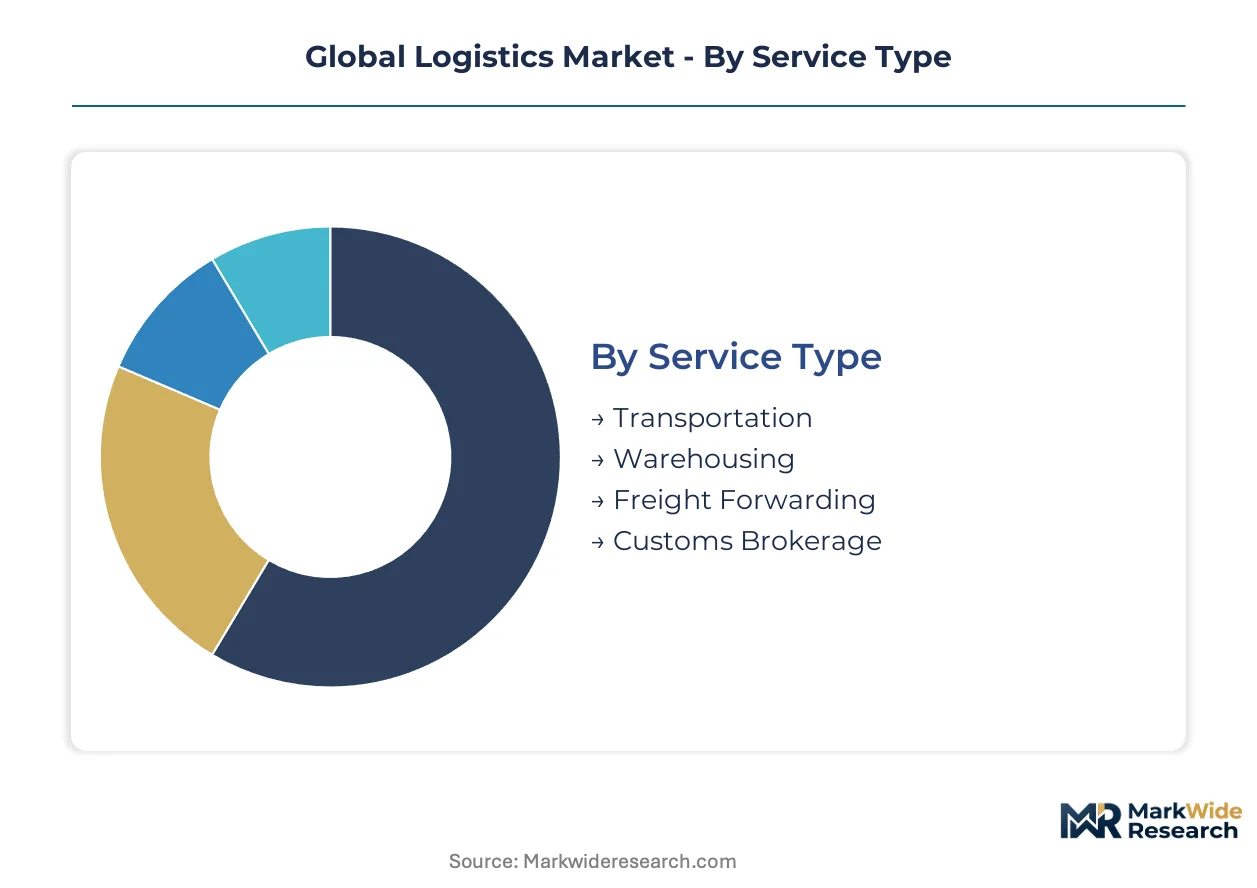
Logistics segmentation reveals how capital allocation diverges across service tiers, with asset-heavy infrastructure competing against digital intermediaries for margin capture. Understanding these divides exposes where procurement budgets concentrate and which technology layers command pricing power.
Service Type:
Replacement cycles for logistics infrastructure accelerate where regulatory mandates force fleet turnover and warehouse automation obsolescence.
- Transportation:Fleet assets span diesel, electric, and hydrogen powertrains with payload ratings from light commercial vans to heavy-duty tractor-trailers. EU Green Deal emissions trading extensions compress replacement timelines for German and Benelux carriers operating intra-European lanes.
- Warehousing:Facilities integrate automated storage and retrieval systems, temperature-controlled zones, and cross-dock configurations for e-commerce fulfillment. India's industrial belt concentrates demand for Mumbai-Delhi-NCR corridor distribution centers as manufacturing relocates from coastal China.
- Freight Forwarding:Non-asset intermediaries orchestrate multimodal cargo movements through carrier contracts and customs documentation expertise.
- Customs Brokerage:Regulatory compliance services navigate divergent digital trade documentation standards between UK and EU authorities post-Brexit.
Volume placements concentrate in Transportation; the faster expansion belongs to Warehousing.
Delivery Mode:
Cost tier separation across delivery modes intensifies as carbon-accounted routing displaces pure cost-based carrier selection in European procurement tenders.
- By Land:Road and rail networks handle continental freight distribution with varying emissions profiles per ton-kilometer. Battery energy density constraints restrict electric heavy-duty truck range below 500 kilometers, excluding long-haul lanes from immediate electrification.
- By Sea:Containerized ocean freight moves bulk commodities and manufactured goods across trans-Pacific and Asia-Europe lanes. IMO carbon intensity indicators reshape fuel strategies as low-sulfur fuel premiums compress margin pools for non-integrated forwarders.
- By Air:Time-definite express services command premium pricing for pharmaceutical and high-value electronics shipments.
- Multimodal:Intermodal combinations of rail and short-sea shipping capture shipper preference as Scope 3 reporting requirements tighten under CSRD disclosure mandates.
Volume placements concentrate in By Sea; the steepest expansion trajectory belongs to Multimodal.
End User:
Application-specific requirements fragment service specifications, with temperature tolerances and delivery velocity driving divergent infrastructure investments.
- Retail:Traditional distribution networks face capacity pressure as e-commerce fulfillment compresses delivery timelines and inventory positioning strategies.
- E-commerce:Same-day and next-day delivery promises require dense urban fulfillment center placement with robotics integration. Automated storage and retrieval systems compress labor cost structures for operators serving dense urban zones.
- Manufacturing:Just-in-sequence and just-in-time supply chains demand precise inbound component coordination.
- Pharmaceuticals:Biologics distribution requires minus 80 to plus 25 degrees Celsius temperature control with CDSCO, EMA, and FDA compliance certification. Specialized certification for pharmaceutical-grade handling exceeds available trained workforce supply in emerging market hubs.
Volume placements concentrate in Manufacturing; the fastest climb belongs to Pharmaceuticals.
Technology:
Technology maturity curves separate proven deployments from pilot-stage investments, with integration costs determining adoption velocity across asset bases.
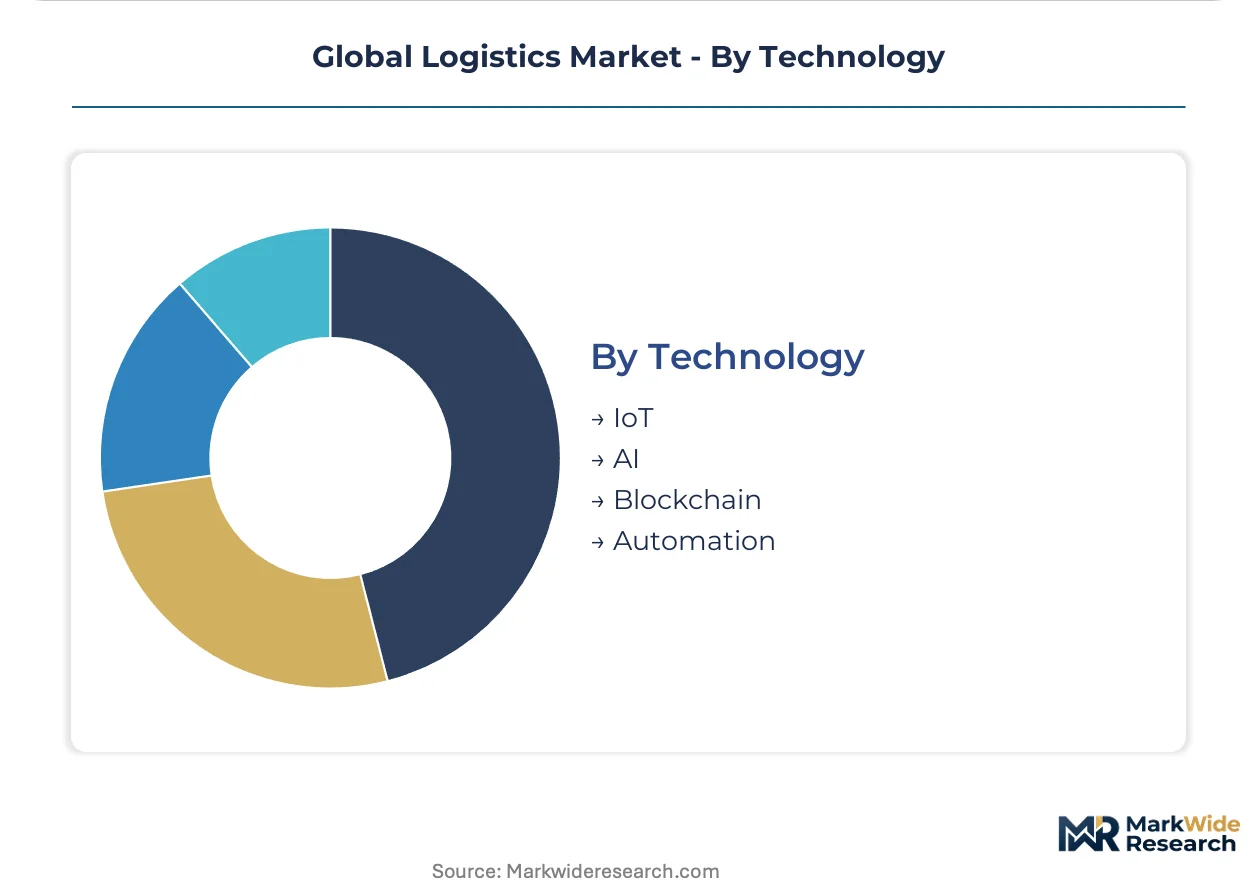
- IoT:Sensor networks provide real-time cargo location, temperature, and condition monitoring across multimodal journeys.
- AI:Predictive cargo routing and demand forecasting algorithms optimize inventory positioning and carrier selection. Digital freight matching platforms compress spot-market transaction cycles for C.H. Robinson and competing intermediaries.
- Blockchain:Distributed ledger applications target trade documentation authenticity and supply chain provenance verification.
- Automation:Robotics integration spans warehouse picking, yard management, and autonomous terminal tractors at Rotterdam and Singapore port facilities.
Volume placements concentrate in IoT; the fastest gain belongs to Automation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam anchors European multimodal freight activity through its automated terminal operations and short-sea shipping connections to German industrial clusters. The port's electrification investments preempt EU emissions mandates while serving as a transshipment hub for Asia-Europe cargo.
United States
E-commerce fulfillment demand concentrates in California's Inland Empire and Texas's Dallas-Fort Worth corridor. EPA heavy-duty truck emissions standards for model year 2027 force fleet operators toward compressed natural gas alternatives and advanced aftertreatment systems. Long Beach port drayage lanes host hydrogen fuel cell tractor pilots under California Air Resources Board zero-emission mandates.
Germany
Automotive just-in-sequence supply chains drive contract logistics demand across Bavaria and Baden-Württemberg manufacturing zones. EU Green Deal Fit for 55 package enforces emissions reporting on intra-European trucking fleets, accelerating electric vehicle procurement. The Rhine-Main corridor connects Frankfurt air freight capacity to Stuttgart industrial clusters through multimodal rail-truck networks.
India
Manufacturing relocation from coastal China concentrates freight demand along Mumbai-Delhi-NCR warehousing corridors. BIS certification requirements for cold-chain equipment elevate capital barriers for pharmaceutical-grade fleet operators. Gujarat's Mundra port expansion and Maharashtra's Pune-Nashik industrial belt anchor production-linked incentive scheme logistics demand.
China
Yangtze River Delta container throughput and Pearl River Delta manufacturing exports sustain ocean freight volume on trans-Pacific lanes. Dual carbon goals reshape domestic fleet procurement toward electric heavy-duty trucks on fixed-duty port drayage routes. Ningbo-Zhoushan port automation investments compress vessel turnaround times for Asia-Europe cargo.
Singapore
Transshipment hub status attracts carbon-accounted routing demand from European shippers seeking Scope 3 emissions reductions. Battery-electric terminal tractors at PSA facilities preempt port emissions regulations through fixed-duty cycle electrification. The city-state's digital trade documentation standards reduce cross-border friction for ASEAN-sourced manufacturing components.
Global Logistics Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification intensity, with pharmaceutical-grade cold-chain networks commanding structural pricing power over generic freight brokerage. The vendor base separates into three tiers: integrated ocean-air-forwarding conglomerates, digital freight-matching intermediaries, and specialized temperature-controlled operators. Dominant competitive moves include multimodal capacity integration and warehouse automation deployment.
Within the integrated forwarding tier, DSV and Kuehne + Nagel occupy positions spanning asset-heavy ocean capacity and asset-light customs brokerage. Maersk Logistics anchors ocean-air intermodal offerings on Asia-Europe lanes. C.H. Robinson represents digital freight-matching archetypes that compress spot-market transaction cycles through algorithmic carrier selection.
| Leading Market Players |
|---|
| DSV |
| CEVA Logistics |
| Amazon |
| C.H. Robinson |
| Nippon Express |
| DHL Supply Chain & Global Forwarding |
| DB Schenker |
| Maersk Logistics |
| Kuehne + Nagel |
| Others |
Value Chain & Pricing Dynamics
Automated fulfillment center deployment across the United States and Germany simultaneously compresses labor cost structures and concentrates warehousing capacity among operators with capital access for robotics integration, reshaping how logistics services are priced and procured.
Pricing Analysis
Outcome-based contracts anchored to on-time-in-full delivery performance command premium positioning over transactional spot-rate arrangements. Three-tier pricing structure across certified pharmaceutical-grade, standard commercial, and economy freight tiers separates margin pools by compliance intensity and temperature-control requirements. Cost compression in commodity ocean freight runs through low-sulfur fuel premiums and carbon intensity surcharges mandated by IMO regulations. E-commerce shippers demonstrate highest price sensitivity due to thin retail margins, while pharmaceutical manufacturers accept elevated rates for validated cold-chain assurance.
Supply Chain Analysis
Workforce scarcity for minus 80 degrees Celsius refrigeration technicians in India and Southeast Asia constrains cold-chain capacity expansion despite BIS and CDSCO certification requirements. Fleet asset manufacturing concentrates in China, Germany, and the United States, with battery-electric powertrain production anchored in Chinese industrial clusters. Lithium-ion cells, hydrogen fuel systems, and advanced aftertreatment components represent critical input dependencies. Single-source vulnerability in semiconductor-based telematics modules threatens fleet management system availability. Distribution runs through hub-and-spoke networks with regional consolidation centers feeding last-mile density in metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as EU Green Deal emissions mandates and capital-intensive automation requirements force sub-scale operators toward exit or acquisition.
For Market Incumbents: Hedge against margin erosion by securing pharmaceutical-grade certification networks across European hubs and deploying automated storage systems in high-velocity e-commerce corridors. DHL Supply Chain's cold-chain infrastructure investments demonstrate how certification depth defends pricing power against digital freight-matching intermediaries. For New Entrants and Emerging Players: Capture white-space in India's Mumbai-Delhi-NCR multimodal corridor where manufacturing relocation from coastal China concentrates demand for contract logistics services. Target pharmaceutical-grade warehousing where BIS certification barriers limit competition. Position through carbon-accounted routing capabilities that satisfy German automotive OEM Scope 3 disclosure requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated ocean-air-forwarding conglomerates seeking last-mile density. Long-term viability favors asset-light digital platforms with algorithmic carrier selection and specialized temperature-controlled operators with regulatory certification moats. Watch for carbon-border adjustment mechanism implementation as demand inflection signal redirecting freight corridor economics.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical Certification Investment | EMA and FDA validation opens biologics distribution contracts with structurally higher margins. |
| Automated Fulfillment Center Deployment | Robotics integration compresses labor costs for same-day delivery promises in dense German urban zones. |
| Carbon-Accounted Routing Capability | CSRD-compliant multimodal options capture preference from European automotive shippers. |
| Hydrogen Fuel Cell Fleet Pilot | California Air Resources Board zero-emission mandates create first-mover positioning at Long Beach port drayage lanes. |
| Digital Freight Matching Platform Scale | Algorithmic carrier selection compresses spot-market transaction cycles for C.H. Robinson competitors. |
Study Parameters
Independent corroboration across fleet operations executives, pharmaceutical supply chain directors, customs brokerage specialists, and e-commerce fulfillment managers underwrites the qualitative findings. Primary interviews with contract logistics providers and freight forwarders combined with secondary validation from IMO carbon intensity disclosures, EU emissions trading registry data, EPA heavy-duty truck certification records, and BIS equipment standards documentation. Bottom-up carrier capacity assessments and top-down trade flow analysis triangulate volume estimates.
Comparable-period anchoring to historical freight rate indices and fleet procurement cycles established the forecast window baseline. The analysis models transportation mode, service tier, delivery velocity, temperature-control requirement, and end-use vertical across the projection horizon. CAGRs derive from segmented growth rate blending weighted by addressable market size. Forecast inputs include EU Green Deal implementation pace, India PLI scheme manufacturing relocation velocity, and battery energy density improvement curves for electric heavy-duty applications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon-border adjustment mechanism scope, hydrogen infrastructure buildout pace, and autonomous vehicle regulatory authorization timelines. Assumptions reflect current policy trajectories and technology cost curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Remanufacturing and Core Returns Logistics Management Market
Logistics and Shipping
Qatar Freight and Logistics Market
Logistics and Shipping
Spain Freight and Logistics Market
Logistics and Shipping
Courier, Express and Parcel Services Market
Logistics and Shipping
Moving Services (Mover and Packers) Market
Logistics and Shipping
China Project Logistics Market
Logistics and Shipping
Cambodia Freight and Logistics Market
Logistics and Shipping
Nordics Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
US Express Delivery Market
Logistics and Shipping
Spain Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Japan Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Japan Dangerous Goods Logistics Market
Logistics and Shipping
Germany Freight and Logistics Market
Logistics and Shipping
APAC Contract Logistics Market
Logistics and Shipping
Empty Container Repositioning Optimization Platforms Market
Logistics and Shipping
Poland Third Party Logistics (3PL) Market