
 Sustainable Last-Mile Delivery Network Design Services Market | 2026-2036
Sustainable Last-Mile Delivery Network Design Services Market Size, Share, and Industry Trends Forecast 2026-2036
Sustainable Last-Mile Delivery Network Design Services Market Insights
Aftermarket service revenue from legacy fleet consulting is tilting toward zero-emission network architecture. DHL Group leverages its European logistics density to build proprietary carbon accounting tools for last-mile redesign. Amazon anchors North American demand through in-house route optimization platforms that integrate electric vehicle charging infrastructure. FedEx competes with a hybrid consulting model that blends SaaS deployment with on-site network engineering.
Sustainable last-mile delivery network design services encompass the analytical and engineering activities required to configure distribution endpoints, vehicle fleets, and routing algorithms to minimize emissions while maintaining service-level agreements. These services typically incorporate GIS-based territory mapping, load-factor simulation, and charging-station siting algorithms to achieve sub-kilogram CO2 per parcel targets. Route optimization and carbon footprint assessment command the widest client bases, while fleet management services carry higher margins due to recurring telemetry integration. E-commerce fulfillment and grocery distribution applications are outpacing parcel delivery in growth velocity, driven by time-window compression and temperature-control requirements.
The EPA tailpipe standards and the EU Green Deal emissions framework jointly elevate compliance thresholds for urban delivery fleets, forcing logistics providers to procure external network design expertise rather than rely on internal planning teams. California's Advanced Clean Trucks regulation and the UK's ZEV mandate create parallel compliance deadlines that sustain cross-border service demand. Stakeholders must weigh cloud-based deployment scalability against on-premise data sovereignty requirements as municipal congestion pricing schemes proliferate and real-time routing data becomes a contested asset.
Market Dynamics
Fleet electrification mandates and municipal congestion pricing schemes are compressing planning cycles for urban distribution networks, forcing logistics providers to externalize network architecture decisions that previously stayed in-house.
Growth Catalysts
- EU Green Deal emissions framework:Binding carbon reduction targets for commercial transport fleets are compelling operators to procure carbon footprint assessment and route optimization services from specialized consultants.
- Grocery distribution:Temperature-controlled last-mile requirements and compressed delivery windows are expanding demand for load-factor simulation and charging-station siting algorithms.
- California's Advanced Clean Trucks regulation:Parallel compliance deadlines with the UK's ZEV mandate are sustaining cross-border service demand for fleet electrification planning expertise.
Market Restraints
- Telemetry integration costs:Fleet management services require recurring hardware and data infrastructure investments that strain mid-market logistics operators.
- Data sovereignty requirements:Municipal congestion pricing schemes are fragmenting real-time routing data ownership across jurisdictional boundaries.
- Skills concentration:GIS-based territory mapping and charging-station siting expertise remains concentrated among a limited pool of specialized engineering consultancies.
Strategic Opportunities
- Cloud-based deployment scalability:SaaS delivery models for route optimization platforms are lowering entry barriers for smaller e-commerce fulfillment operators.
- India's PLI scheme for electric mobility:Production-linked incentives for domestic EV manufacturing are creating demand for localized network design services as fleet procurement accelerates.
- Integration of AI-driven demand forecasting with charging infrastructure planning:Converging technologies are enabling dynamic depot siting that responds to parcel volume volatility in real time.
Industry Challenges
- Electrical engineering talent scarcity:Grid interconnection and high-power charging infrastructure design capabilities are outpacing supply in key logistics clusters.
- Legacy fleet transition timelines:Depreciation schedules and residual value uncertainty are complicating zero-emission network architecture decisions for mixed-fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sustainable Last-Mile Delivery Network Design Services Market |
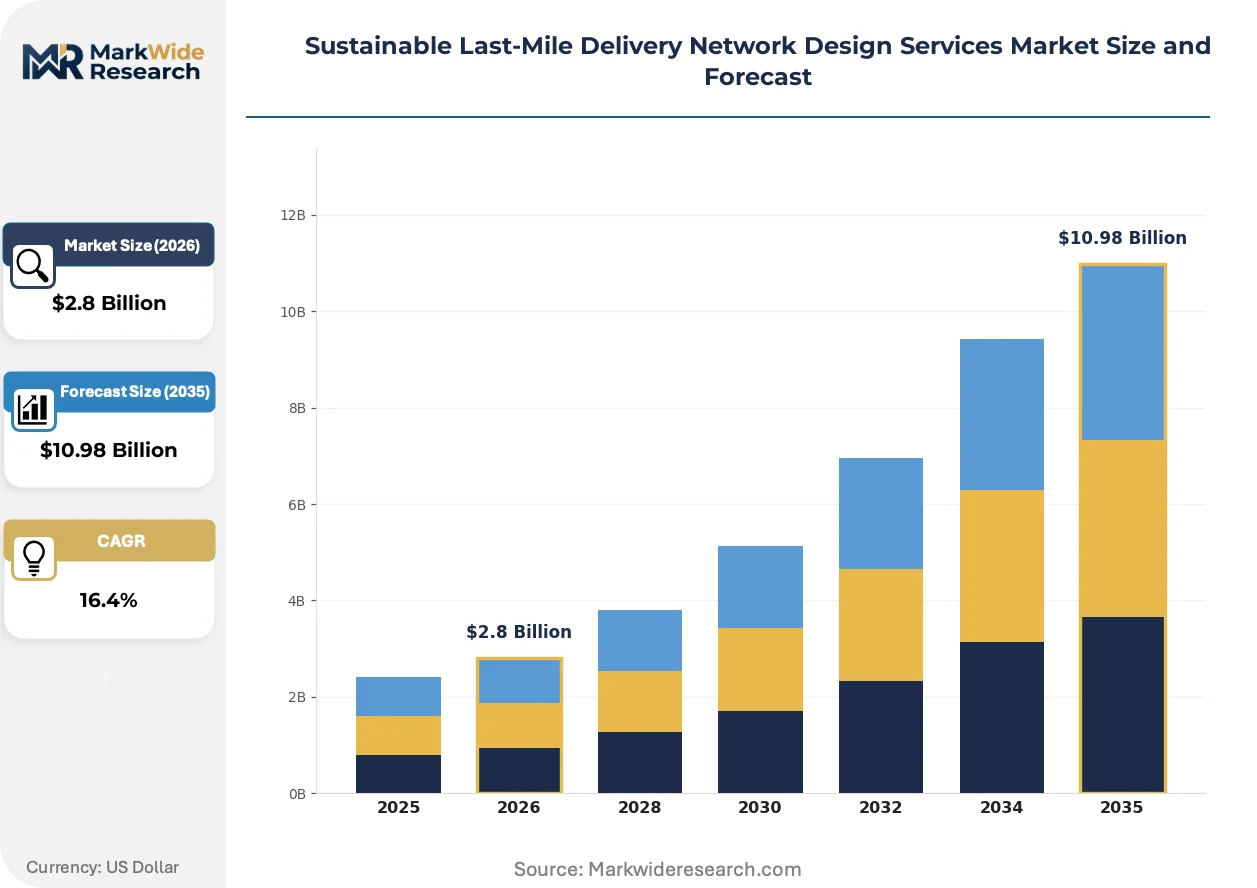
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $10.98 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Route Optimization, Fleet Management, Demand Forecasting, Network Planning, Carbon Footprint Assessment, Vehicle Scheduling Application: Parcel Delivery, Grocery Distribution, Food & Beverage Logistics, Healthcare Supplies, E-commerce Fulfillment, Courier Services Client Industry: Retail Chains, Food & Beverage Companies, Pharmaceutical Distributors, Logistics Providers, E-commerce Platforms Deployment: Cloud-based Solutions, On-Premise Installation, Hybrid Models, SaaS Platforms, Mobile Integration |
| Companies Covered | DHL Group, United Parcel Service, FedEx, Amazon, Maersk, Ryder System, Kuehne + Nagel, DB Schenker, Aramex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sustainable Last-Mile Delivery Network Design Services Market Trends and Innovations
Digital twin technology is compressing the validation cycle for sustainable network configurations, allowing operators to simulate multi-scenario fleet deployments before capital commitment.
GIS-based territory mapping is digitizing the spatial analysis of delivery density, charging accessibility, and emissions exposure. E-commerce fulfillment operators are adopting these platforms at accelerating pace to meet sub-kilogram CO2 per parcel targets. The technology is digitizing how logistics providers balance service-level agreements against carbon accounting requirements.
The EPA tailpipe standards and their state-level equivalents are elevating compliance thresholds for urban delivery fleets. California's Advanced Clean Trucks regulation creates binding electrification timelines that force operators to procure external network design expertise. Parcel delivery segments in the US Northeast are responding by accelerating charging-station siting studies ahead of 2030 model-year phase-ins.
Buyer procurement patterns are gravitating toward performance-based engagements that tie consultant fees to achieved emissions reductions. Traditional time-and-materials contracts are losing share to outcome-based structures in grocery distribution and pharmaceutical cold chain applications. Germany and the Netherlands are exhibiting the fastest adoption of these risk-sharing arrangements as EU Green Deal reporting requirements mature.
Sustainable Last-Mile Delivery Network Design Services Market Segmentation
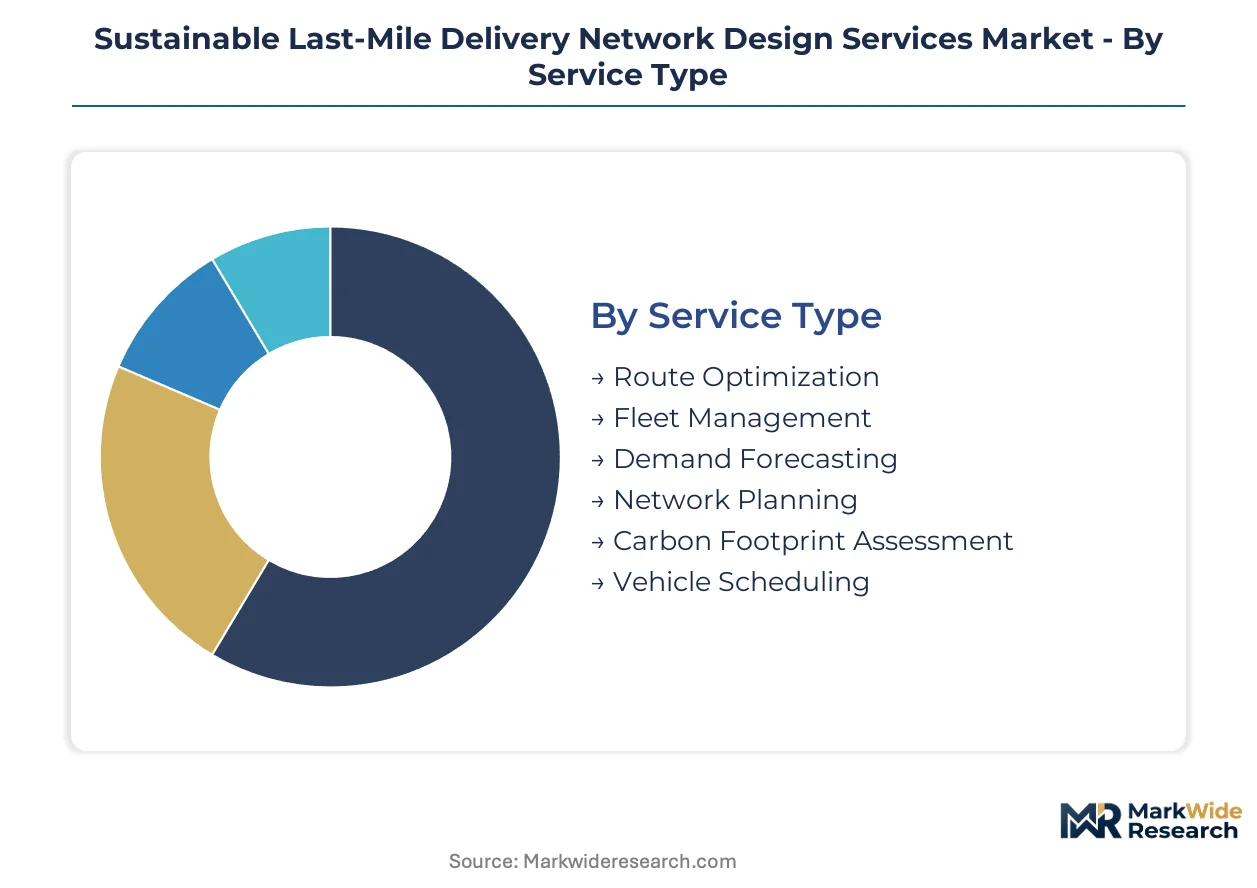
Last-mile network design services fragment across service intensity, application complexity, and infrastructure requirements. Each segment carries distinct margin profiles and technical barriers that shape procurement patterns among logistics operators.
Service Type:
Use-case spectrum spans real-time operational tools to multi-year capital planning exercises.
- Route Optimization:GIS-based territory mapping and dynamic routing algorithms reduce kilometers per parcel. E-commerce fulfillment operators in Germany deploy these platforms to meet EU Green Deal emissions targets.
- Fleet Management:Telemetry integration and predictive maintenance scheduling command recurring revenue streams. California's Advanced Clean Trucks regulation forces logistics providers to externalize electrification planning expertise.
- Demand Forecasting:AI-driven volume prediction models inform depot siting decisions.
- Network Planning:Multi-node distribution architecture design for hub-and-spoke configurations.
- Carbon Footprint Assessment:Emissions accounting and compliance reporting services.
- Vehicle Scheduling:Time-window optimization for temperature-controlled deliveries.
The dominant share belongs to Route Optimization, while Fleet Management is closing the gap fastest.
Application:
Margin structure varies with temperature control requirements and delivery window compression.
- Grocery Distribution:Cold chain compliance and sub-hour delivery windows demand load-factor simulation and charging-station siting algorithms. Netherlands-based operators lead adoption of outcome-based consulting contracts.
- E-commerce Fulfillment:High parcel volumes and returns processing complexity drive cloud-based deployment. India's PLI scheme for electric mobility is accelerating localized network design demand.
- Parcel Delivery:Standardized package profiles suit algorithmic route density optimization.
- Food & Beverage Logistics:Perishability constraints and hygiene protocols shape fleet specifications.
- Healthcare Supplies:Regulatory traceability requirements and temperature excursions mandate specialized planning.
- Courier Services:Same-day and instant delivery models prioritize micro-fulfillment node placement.
Grocery Distribution commands premium pricing, though E-commerce Fulfillment is expanding most quickly.
Client Industry:
Procurement sophistication divides between asset-heavy operators and platform intermediaries.
- E-commerce Platforms:In-house route optimization development competes with external consulting engagements. Amazon anchors North American demand through proprietary charging infrastructure integration.
- Logistics Providers:Third-party operators require white-label network design for multiple shipper contracts. DHL Group leverages European density for proprietary carbon accounting tools.
- Retail Chains:Omnichannel fulfillment convergence drives store-as-depot configurations.
- Food & Beverage Companies:Direct-to-consumer pivots necessitate last-mile capability builds.
- Pharmaceutical Distributors:GDP compliance and serialization requirements constrain routing flexibility.
Logistics Providers generate the largest contract values, while E-commerce Platforms are gaining share fastest.
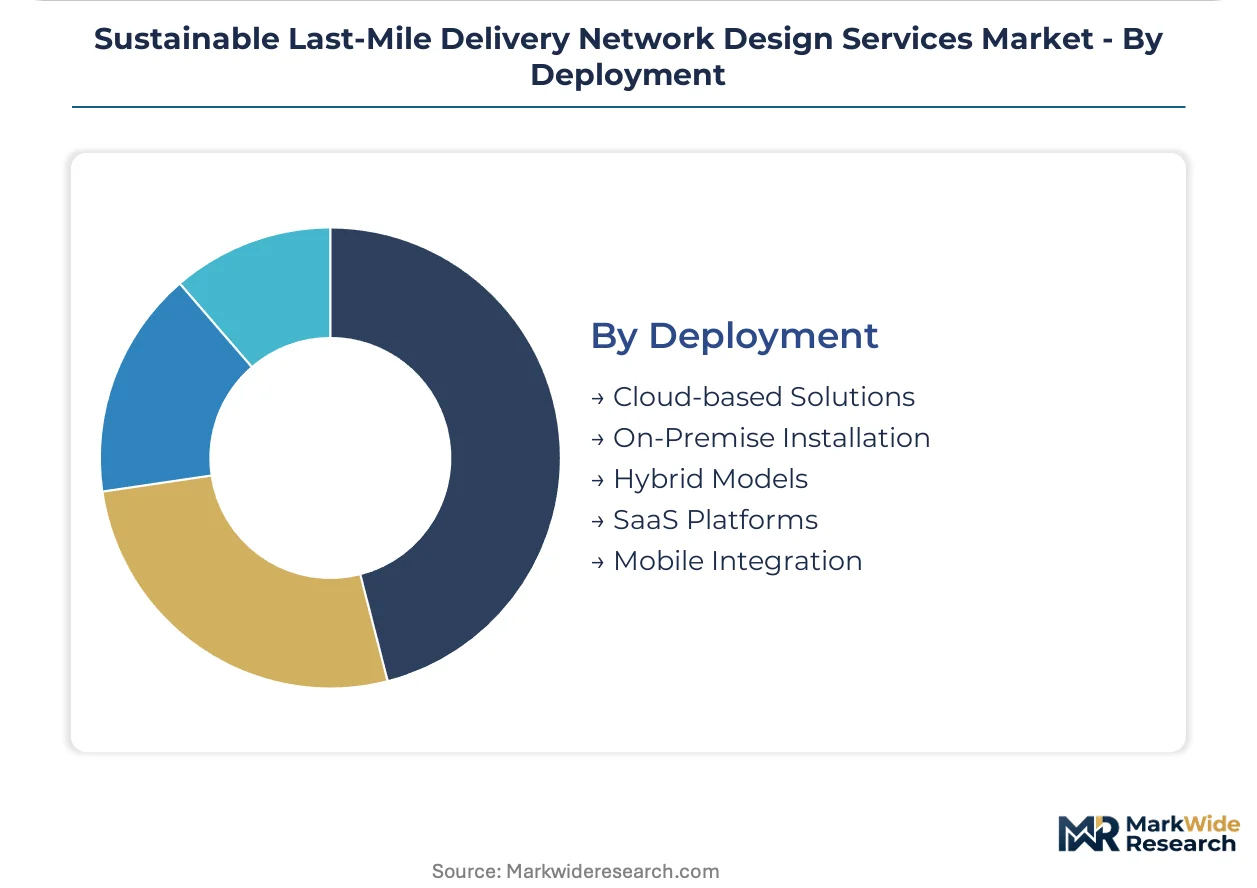
Deployment:
Infrastructure ownership models determine data sovereignty exposure and integration cost profiles.
- Cloud-based Solutions:Scalable SaaS delivery lowers entry barriers for mid-market operators. Municipal congestion pricing schemes fragment real-time routing data ownership across jurisdictional boundaries.
- Hybrid Models:Sensitive planning data remains on-premise while optimization engines run cloud-native. UK ZEV mandate compliance deadlines sustain cross-border service demand for these configurations.
- SaaS Platforms:Subscription-based route optimization with standardized API integrations.
- On-Premise Installation:Air-gapped systems for defense and classified supply chains.
- Mobile Integration:Driver-facing applications for dynamic rerouting and proof-of-delivery.
Cloud-based Solutions hold the installed base lead, yet Hybrid Models are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the Netherlands accept premium pricing for carbon-accounting-integrated services, while mid-market operators in India and Brazil remain price-sensitive and favor modular SaaS entry points.
United States
Amazon and FedEx anchor demand through proprietary route optimization platforms that embed electric vehicle charging infrastructure. California's Advanced Clean Trucks regulation forces logistics providers to externalize electrification planning ahead of 2030 compliance deadlines. The Los Angeles Basin and New York Metro concentrate charging-station siting studies for parcel density optimization.
Germany
DHL Group and DB Schenker drive large-scale sustainable network redesign programs leveraging European logistics density. The EU Green Deal emissions framework binds commercial transport fleets to carbon reduction targets that require specialized consulting procurement. The Rhine-Ruhr corridor hosts the continent's densest cluster of GIS-based territory mapping expertise.
Netherlands
Temperature-controlled grocery distribution demands load-factor simulation and sub-hour delivery window optimization. Outcome-based consulting contracts tied to achieved emissions reductions mature fastest here under EU Green Deal reporting requirements. Rotterdam and Amsterdam anchor cross-border service demand for hybrid cloud-on-premise deployment models.
India
The PLI scheme for electric mobility accelerates localized network design demand as domestic EV manufacturing scales. Mid-market e-commerce fulfillment operators favor cloud-based SaaS route optimization to avoid telemetry integration capital burdens. Maharashtra and Karnataka concentrate emerging fleet electrification planning expertise around Mumbai and Bangalore logistics clusters.
United Kingdom
The ZEV mandate creates binding electrification timelines that sustain cross-border service demand alongside California's parallel regulations. Hybrid deployment models dominate as operators balance cloud scalability against data sovereignty requirements for municipal congestion pricing compliance. The Midlands and Southeast England concentrate carbon footprint assessment service providers serving grocery and pharmaceutical cold chain applications.
Sustainable Last-Mile Delivery Network Design Services Market Competitive Landscape
Capability concentration sits with specialized engineering consultancies mastering GIS-based territory mapping and charging-station siting algorithms; scale advantage sits with integrated logistics operators leveraging proprietary network density. The market structures around three tiers: asset-heavy carriers with in-house platforms, independent SaaS vendors, and hybrid consulting-engineering firms. Dominant competitive moves include vertical integration into carbon accounting tools and strategic partnerships bridging telemetry hardware with optimization software.
Within the integrated logistics carrier tier, DHL Group, FedEx, and United Parcel Service exemplify divergent strategic postures. DHL Group occupies a position emphasizing European density and proprietary carbon accounting capabilities. FedEx represents the hybrid consulting-SaaS model blending on-site network engineering with platform deployment. United Parcel Service anchors North American demand through scale-driven route optimization and fleet management integration.
| Leading Market Players |
|---|
| DHL Group |
| United Parcel Service |
| FedEx |
| Amazon |
| Maersk |
| Ryder System |
| Kuehne + Nagel |
| DB Schenker |
| Aramex |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in GIS-based territory mapping expertise across the Rhine-Ruhr corridor is elevating day rates for charging-station siting consultants while compressing margins for mid-market operators unable to secure specialized engineering talent. This utilization imbalance feeds directly into procurement behavior, with buyers accepting premium pricing for outcome-based engagements that transfer electrification risk to external advisors.
Pricing Analysis
After-sales revenue from recurring telemetry integration and predictive maintenance scheduling drives lifetime value for fleet management service tiers. Subscription-based SaaS models dominate route optimization deployment, with price differentiation anchored in data sovereignty guarantees and API integration depth. Cost compression in standardized carbon footprint assessment services is intensifying as cloud-native entrants automate emissions reporting workflows. Mid-market e-commerce fulfillment operators in India exhibit highest price sensitivity, while Netherlands-based grocery distributors accept premium outcome-based contracts tied to achieved emissions reductions.
Supply Chain Analysis
Export-control restrictions on high-resolution geospatial data and AI-driven routing algorithms are fragmenting cross-border service delivery capabilities. Engineering talent concentrates in Germany, the Netherlands, and the United Kingdom, while cloud infrastructure provisioning draws from Ireland, Singapore, and US hyperscaler regions. Supply chain risk centers on single-source vulnerability for specialized electrical grid interconnection expertise. Distribution runs through direct enterprise sales for complex network planning engagements and standardized API marketplaces for SaaS route optimization modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sustainable last-mile delivery network design services occupy an early-cycle expansion phase, with EU Green Deal compliance deadlines and California's Advanced Clean Trucks regulation together accelerating externalized procurement of electrification planning expertise.
For Market Incumbents: Insulate proprietary carbon accounting capabilities through captive development of charging infrastructure digital twins, while securing exclusive telemetry partnerships with emerging EV OEMs to lock out SaaS competitors. DHL Group's European density advantage demonstrates how network data assetization creates defensive moats against cloud-native entrants.
For New Entrants and Emerging Players: Pursue white-space opportunities in India's PLI-accelerated EV fleet procurement, where localized network design demand outpaces domestic consulting capacity. Target mid-market e-commerce fulfillment operators seeking modular SaaS entry points without telemetry integration capital burdens, leveraging outcome-based pilot structures to establish credibility before scaling.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet management service providers with embedded telemetry hardware relationships, suggesting superior cash flow quality versus project-based network planning consultancies. Acquisition targets should exhibit proprietary GIS datasets or exclusive charging infrastructure siting algorithms. The signal to watch is municipal congestion pricing scheme proliferation, which accelerates demand for real-time routing data assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Accounting Tool Development | Proprietary emissions measurement capabilities differentiate DHL Group and FedEx in EU Green Deal compliance markets. |
| Telemetry Hardware Partnership | Exclusive sensor integration agreements lock in recurring fleet management revenue streams for logistics providers. |
| Cloud-Native SaaS Platform Launch | Scalable route optimization deployment lowers entry barriers for India's mid-market e-commerce fulfillment segment. |
| Digital Twin Technology Integration | Multi-scenario fleet simulation compresses validation cycles for zero-emission network architecture decisions. |
| Outcome-Based Contract Structuring | Risk-sharing arrangements tied to achieved emissions reductions mature fastest in Netherlands grocery distribution applications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet electrification planners at DHL Group and DB Schenker, route optimization engineers at Amazon and FedEx, carbon accounting specialists, and municipal congestion pricing administrators. Secondary validation drew from EU Green Deal implementation documents, EPA tailpipe standard rulemakings, California Air Resources Board regulatory filings, and customs data on EV fleet procurement. Bottom-up service revenue estimates triangulated against top-down market sizing derived from logistics operator disclosed consulting expenditures.
Calibration anchored projections to observed adoption curves for charging infrastructure deployment across Germany, California, and the Netherlands. Segmentation modeling spanned service type intensity, application temperature-control requirements, client industry asset ownership patterns, and deployment infrastructure ownership models. CAGRs were derived from logistic diffusion curves fitted to electrification mandate compliance deadlines, incorporating fleet turnover timelines and residual value uncertainty effects on network redesign investment cycles.
Sensitivities concentrate around municipal congestion pricing scheme proliferation rates and electrical engineering talent supply constraints in key logistics clusters. Forecasts reflect documented assumptions regarding EU Green Deal enforcement consistency and California ZEV mandate phase-in adherence. Material shifts in grid interconnection approval timelines or battery residual value recovery rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Nordic Bike Sharing Market
Smart Transportation Solutions
Transportation by Drone Market
Smart Transportation Solutions
Global IoT Fleet Management Market
Smart Transportation Solutions
Global V2X Market
Smart Transportation Solutions
Road Profile Laser Sensor Market
Smart Transportation Solutions
North America Smart Transportation Market
Smart Transportation Solutions
Car Sharing Market
Smart Transportation Solutions
5G in Automotive and Smart Transportation Market
Smart Transportation Solutions
Long Haul Solutions Market
Smart Transportation Solutions
North America IoT Transportation Market
Smart Transportation Solutions
Advanced Traffic Management System (ATMS) Market
Smart Transportation Solutions
New Energy Vehicle Sweeper Market
Smart Transportation Solutions
Europe Connected Cars Market
Smart Transportation Solutions
Automotive Platooning Systems Market
Smart Transportation Solutions
Europe Hyperloop Technology Market
Smart Transportation Solutions
Smart Parking Systems Market