
 GCC Air Freight Transport Market | 2026-2036
GCC Air Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Air Freight Transport Market Foresight
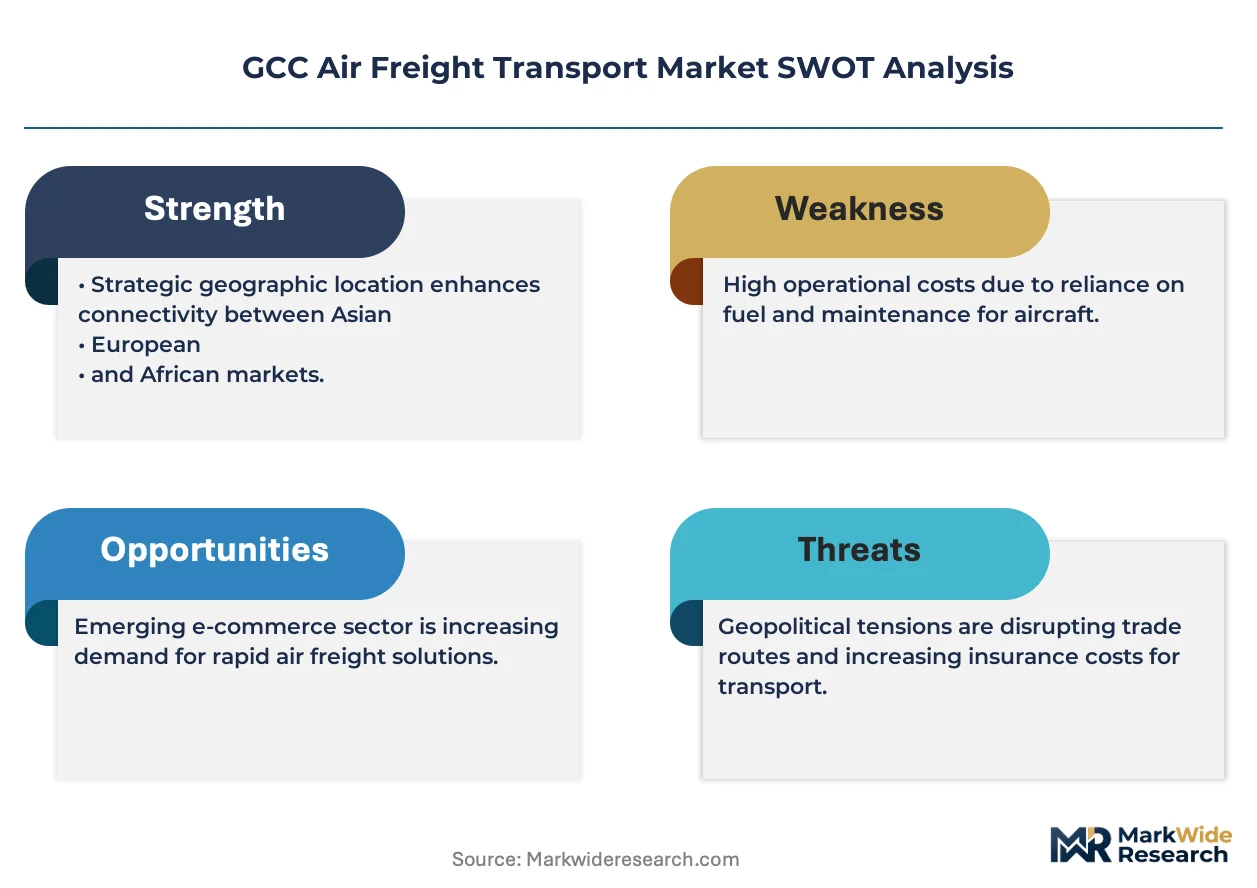
Aftermarket service revenue is narrowing as a distinct margin pool as Gulf carriers integrate ground handling, warehousing, and last-mile delivery under unified operations. Emirates SkyCargo leverages its dedicated freighter fleet and pharmaceutical-certified cool chain infrastructure to dominate temperature-controlled shipments across the Gulf. Qatar Airways Cargo anchors its competitive position through hub-and-spoke connectivity via Hamad International Airport, while Etihad Cargo differentiates through specialized automotive and aerospace logistics serving Abu Dhabi's industrial zones.
GCC Air Freight Transport encompasses the scheduled, charter, and express movement of goods via fixed-wing aircraft operating within and from the six Gulf Cooperation Council states, utilizing both belly-hold capacity on passenger flights and dedicated cargo freighters with payload capabilities typically exceeding 100 tonnes for wide-body applications. The sector serves cross-border trade facilitation, time-sensitive supply chains, and hydrocarbon-related project logistics across a region lacking integrated rail freight alternatives. Express cargo and scheduled freight command the largest volume shares, driven by e-commerce fulfillment requirements and predictable manufacturing supply schedules, while pharmaceutical shipments represent the fastest-growing segment as Gulf states expand healthcare infrastructure and cold-chain certification standards. Charter services retain premium pricing power during peak Hajj and Umrah periods when passenger aircraft belly-hold capacity diverts to religious tourism flows.
The UAE's General Civil Aviation Authority enforces stringent operational safety and emissions monitoring protocols that elevate compliance costs for smaller operators while creating barriers to informal market entry. Saudi Arabia's General Authority of Civil Aviation aligns with ICAO standards but imposes additional domestic route licensing requirements that shape carrier network strategies. Stakeholders must monitor evolving carbon-offset mandates and bilateral air service agreements as Gulf governments renegotiate traffic rights to protect national carrier market positions against expanding third-country logistics platforms.
Market Dynamics
Consolidation of ground handling, warehousing, and last-mile delivery under unified carrier operations is compressing aftermarket service margins and reshaping competitive positioning across Gulf air freight corridors.
Growth Catalysts
- E-commerce logistics adoption:Saudi Arabia and the UAE are witnessing accelerated fulfillment infrastructure buildout as domestic online retail volumes expand, driving dedicated freighter deployments and pharmaceutical-certified cool chain investments.
- SFDA cold-chain mandates:Saudi Arabia's national pharmaceutical regulator is tightening temperature-control certification requirements, forcing infrastructure upgrades that simultaneously expand serviceable addressable market for certified operators.
- Hydrocarbon project logistics:Energy sector capital expenditure cycles across Kuwait, Qatar, and the UAE generate outsized demand for charter and heavy-lift cargo capacity during construction phases.
Market Restraints
- Jet fuel price volatility:Kerosene cost swings constitute the largest variable in unit economics, with smaller operators lacking hedging programs exposed to margin erosion during supply shocks.
- Hub concentration risk:Dubai-Abu Dhabi corridor dominance creates single-point-of-failure exposure for transshipment-dependent Gulf cargo flows.
- Bilateral traffic right constraints:Renegotiated air service agreements between Gulf states and third countries restrict fifth-freedom operations, protecting national carrier positions but limiting network expansion for independent logistics platforms.
Strategic Opportunities
- Oman and Bahrain underpenetration:These smaller GCC markets lack dedicated freighter infrastructure, creating first-mover advantage for operators establishing pharmaceutical and e-commerce handling capabilities ahead of demand maturation.
- Carbon-offset mandates:Emerging compliance frameworks across the UAE and Saudi Arabia will create premium pricing tiers for verified low-emission cargo services.
- Blockchain-IoT convergence:Real-time shipment visibility and smart contract automation are enabling new service models around pharmaceutical provenance and high-value cargo insurance.
Industry Challenges
- Pilot and maintenance technician scarcity:Gulf aviation labor markets face structural shortages in certificated flight crew and airframe-engine specialists, inflating wage costs and limiting fleet expansion velocity.
- Cool chain certification timelines:IATA CEIV Pharma and GDP compliance processes require 12-18 month facility overhauls, delaying revenue recognition for infrastructure investments.
- Legacy warehouse management system integration:Unified carrier operations struggle to harmonize disparate IT architectures across acquired ground handling subsidiaries, fragmenting customer experience.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Air Freight Transport Market |
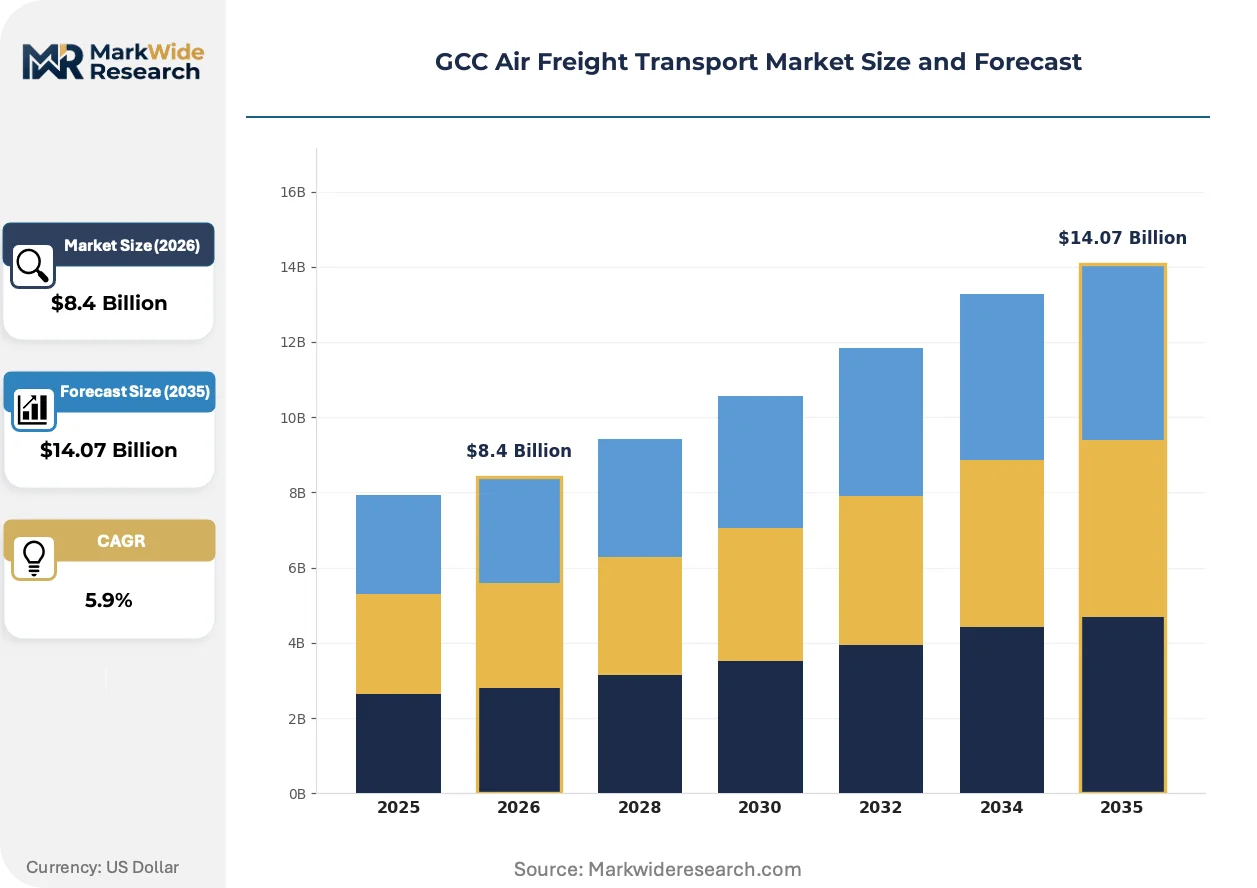
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.07 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express Cargo, Charter Services, Scheduled Freight, Courier Services, General Cargo Shipment Type: Perishable Goods, Pharmaceuticals, Electronics, Automotive Parts, Industrial Equipment End User Industry: Manufacturing, E-commerce, Oil & Gas Operations, Aerospace, Construction Distribution Channel: Direct Booking, Freight Forwarders, Online Platforms, Third-Party Logistics, Airport Agents |
| Companies Covered | Etihad Cargo, Gulf Air Cargo, Emirates SkyCargo, FedEx, DHL, Qatar Airways Cargo, Jazeera Airways Cargo, Maximus Air, Saudia Cargo, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Air Freight Transport Market Shifts & Advancements
Digital infrastructure investments are compressing information asymmetries between shippers and carriers, enabling dynamic capacity pricing and predictive disruption management across Gulf cargo networks.
Blockchain-enabled cargo documentation is digitizing paper-based airway bills and customs declarations across Dubai's logistics free zones. Emirates SkyCargo and ground handlers at Al Maktoum International are piloting distributed ledger systems for pharmaceutical shipments. This technology is digitizing compliance verification workflows, reducing documentation processing from days to hours while creating immutable audit trails for SFDA and MOHAP inspections.
MOHAP's emissions monitoring protocols are tightening operational reporting requirements for UAE-registered cargo operators, mandating granular fuel burn and carbon intensity disclosures. The regulation is elevating compliance software spending across the carrier base. Pharmaceutical and perishables segments face the steepest adaptation costs due to temperature-controlled payload weight penalties affecting emissions calculations.
Shippers are consolidating procurement around integrated logistics providers capable of offering door-to-door service level agreements rather than discrete air freight contracts. This behavioral shift is compressing spot market volumes and extending contract durations. Saudi Arabia's domestic manufacturing zones and UAE's Jebel Ali industrial corridor exhibit the most pronounced concentration of procurement authority among large pharmaceutical and automotive OEMs.
GCC Air Freight Transport Market Segmentation
GCC air freight segmentation reveals divergent operational rhythms across service tiers, with express networks turning inventory daily while charter contracts extend across multi-month project cycles. Understanding these velocity differentials shapes capacity planning and working capital deployment across Gulf logistics corridors.
Service Type:
Express cargo contracts renew weekly against charter agreements spanning quarterly or annual horizons, creating fundamentally different cash flow profiles and fleet utilization strategies.
- Express Cargo:Time-definite delivery networks operate on 24-48 hour cycle times with dedicated freighter rotations between Dubai, Riyadh, and Jeddah. E-commerce fulfillment mandates from Saudi Arabia's domestic retail platforms are compressing delivery windows and forcing overnight capacity investments.
- Scheduled Freight:Predictable belly-hold and freighter deployments on fixed routings serve manufacturing supply chains with weekly or bi-weekly replenishment cadences. The Dubai-Abu Dhabi corridor concentrates the densest scheduled frequencies, though Dammam and Kuwait City gain connections as industrial zones mature.
- Charter Services:Project-specific heavy-lift and outsized cargo contracts align with hydrocarbon construction timelines across Qatar and Kuwait.
- Courier Services:Document and small parcel movements integrate with last-mile ground networks for B2C final delivery.
- General Cargo:Non-specialized commodity movements fill residual capacity on mixed freight operations.
Scheduled freight anchors the volume base while express cargo gains share at the steepest rate.
Shipment Type:
Margin structures stratify sharply across temperature requirements, with ambient electronics shipments commanding baseline yields against pharmaceutical cold-chain premiums.
- Pharmaceuticals:Temperature-controlled shipments between 2-8°C and 15-25°C ranges require IATA CEIV Pharma-certified handling infrastructure. SFDA and MOHAP inspections are tightening GDP compliance standards across Saudi Arabia and the UAE, elevating facility investment barriers.
- Electronics:High-value consumer devices and semiconductor components move through secure custody protocols with minimal environmental controls. Dubai's Jebel Ali Free Zone and Riyadh's industrial districts concentrate procurement authority among regional distributors.
- Perishable Goods:Fresh produce and floral shipments demand active cooling through narrow delivery windows.
- Automotive Parts:Just-in-time manufacturing supply chains synchronize air freight with assembly line schedules.
- Industrial Equipment:Project cargo and maintenance components serve energy and infrastructure sectors.
Electronics shipments anchor the volume base while pharmaceuticals expand most quickly.
End User Industry:
Procurement concentration varies dramatically, with oil and gas majors negotiating annual framework agreements against e-commerce platforms' spot-market volatility.
- E-commerce:Domestic online retail fulfillment generates fragmented, high-frequency shipments requiring sortation hub density. Saudi Arabia's domestic manufacturing zones and the UAE's logistics free zones exhibit pronounced procurement consolidation among platform operators.
- Oil & Gas Operations:Exploration and production cycles in Kuwait, Qatar, and the UAE generate lumpy, high-value charter demand for drilling equipment and spare parts.
- Manufacturing:Automotive and aerospace OEMs maintain predictable supply schedules with contract freight commitments.
- Aerospace:MRO parts and assembly components serve Abu Dhabi's industrial zones and Dubai's aviation clusters.
- Construction:Building material movements align with infrastructure project timelines across the six GCC states.
Oil and gas operations anchor the volume base while e-commerce climbs the fastest.
Distribution Channel:
Customer acquisition costs diverge across channel structures, with direct carrier relationships requiring dedicated sales teams against forwarder networks' aggregated volume access.
- Freight Forwarders:Consolidators aggregate shipments from multiple shippers, achieving scale economies on lane-specific contracts. Large forwarders dominate pharmaceutical and automotive verticals through integrated warehousing and customs brokerage capabilities.
- Third-Party Logistics:End-to-end supply chain managers bundle air freight with ground distribution and inventory management. Saudi Arabia's domestic route licensing requirements shape 3PL network strategies as they expand controlled-temperature capabilities.
- Direct Booking:Large shippers contract directly with carriers for volume commitments.
- Online Platforms:Digital freight marketplaces enable spot capacity matching for SME shippers.
- Airport Agents:Local ground handling intermediaries facilitate customs clearance and last-mile coordination.
Freight forwarders anchor the volume base while third-party logistics gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Charter buyers in Kuwait and Qatar show the lowest price elasticity during hydrocarbon construction cycles, while e-commerce shippers in Saudi Arabia and the UAE negotiate aggressively on express rates. Pharmaceutical cold-chain contracts command premium stability across all six GCC states.
United Arab Emirates
Dubai's Jebel Ali Free Zone and Abu Dhabi's Khalifa Port industrial corridor generate the densest scheduled freighter frequencies in the Gulf. MOHAP enforces emissions monitoring protocols that mandate granular fuel burn disclosures from UAE-registered operators. Al Maktoum International anchors pharmaceutical certification investments as Emirates SkyCargo expands dedicated cool-chain infrastructure.
Saudi Arabia
Domestic e-commerce platforms are compressing delivery windows to 24-hour cycles across Riyadh and Jeddah, forcing overnight freighter deployments. SFDA cold-chain mandates require GDP-compliant temperature controls for pharmaceutical shipments, elevating facility investment barriers. King Abdulaziz International Airport in Jeddah and King Khalid International in Riyadh concentrate sortation hub buildouts.
Qatar
Hydrocarbon project logistics generate lumpy charter demand for heavy-lift capacity during North Field expansion phases. The national civil aviation regulator aligns with ICAO standards while imposing bilateral traffic right protections for Qatar Airways Cargo. Hamad International Airport serves as the primary transshipment node for Gulf-Africa and Gulf-Asia flows.
Kuwait
Oil field maintenance cycles and refinery upgrade projects sustain periodic outsized cargo movements. The Directorate General of Civil Aviation maintains conservative fifth-freedom licensing that limits independent logistics platform expansion. Kuwait International Airport handles residual transshipment volumes subordinate to Dubai-Abu Dhabi corridor dominance.
Oman
Pharmaceutical and e-commerce handling capabilities remain underdeveloped relative to demand maturation curves. The national aviation authority is streamlining route licensing to attract dedicated freighter operators. Muscat International Airport and Salalah Free Zone offer first-mover positioning for cold-chain infrastructure investors.
GCC Air Freight Transport Market Competitive Landscape
Capability concentration sits with full-service Gulf carriers operating dedicated freighter fleets and pharmaceutical-certified infrastructure; scale advantage sits with global integrators leveraging consolidated ground networks. The market structures around three tiers: national flag carriers with hub dominance, regional specialists with charter flexibility, and international express platforms with last-mile density. Consolidation of ground handling under unified carrier operations and bilateral traffic right renegotiations constitute the dominant competitive moves reshaping positioning.
Among Gulf-based flag carriers, Emirates SkyCargo, Qatar Airways Cargo, and Etihad Cargo exemplify the capability-heavy archetype combining dedicated freighter assets with integrated cool-chain infrastructure. These three operators anchor pharmaceutical and temperature-controlled segments through hub investments at Dubai, Doha, and Abu Dhabi respectively. Global integrators FedEx and DHL occupy the scale-driven tier, leveraging consolidated procurement relationships with e-commerce platforms and automotive OEMs across Saudi Arabia and the UAE.
| Leading Market Players |
|---|
| Etihad Cargo |
| Gulf Air Cargo |
| Emirates SkyCargo |
| FedEx |
| DHL |
| Qatar Airways Cargo |
| Jazeera Airways Cargo |
| Maximus Air |
| Saudia Cargo |
| Others |
Supply & Pricing Matrix
The Dubai-Abu Dhabi corridor anchors Gulf air freight cost dynamics, where concentrated belly-hold capacity and dedicated freighter deployments generate tiered rate structures that differentiate pharmaceutical-certified shipments from general cargo while bilateral traffic rights constrain alternative routing options.
Pricing Analysis
Aftermarket service revenue from ground handling and warehousing contracts drives lifetime value for integrated carriers. Three-tier pricing structure across pharmaceutical-certified, temperature-controlled standard, and general cargo levels reflects IATA CEIV Pharma certification premiums and SFDA GDP compliance tiers. Cost compression in express networks is intensifying because e-commerce platforms negotiate annual rate reductions against volume commitments. E-commerce fulfillment shippers exhibit the highest price sensitivity, while oil and gas charter buyers accept premium rates during project construction phases.
Supply Chain Analysis
Single-point vulnerability at Dubai-Abu Dhabi transshipment hubs dominates Gulf air freight risk profiles. Manufacturing inputs for aerospace and automotive components draw from Germany, Japan, and China, while pharmaceutical active ingredients rely on Indian and Swiss production. Jet fuel price volatility constitutes the primary structural risk, with kerosene cost swings transmitting directly to spot market rates. Distribution runs through freight forwarder networks that aggregate SME volumes before tendering to scheduled freighter operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GCC air freight operates as a regulatory-moat market where bilateral traffic rights and national carrier protections create entrenched competitive positions with substantial switching costs for contracted shippers.
For Market Incumbents: Pre-empt margin erosion in express cargo by integrating last-mile ground networks under unified operations, while accelerating pharmaceutical certification investments at secondary hubs ahead of SFDA enforcement waves. Defensive consolidation of ground handling subsidiaries reduces fragmentation risk from legacy warehouse management system incompatibilities. For New Entrants and Emerging Players: Establish a beachhead in Oman's underdeveloped pharmaceutical cold-chain infrastructure before demand maturation eliminates first-mover positioning. Target Bahrain's e-commerce sortation gap through partnerships with Saudi domestic retail platforms seeking alternative routing options beyond Dubai-Abu Dhabi concentration. For Investors and Strategic Acquirers: Regional specialists with charter flexibility and pharmaceutical GDP compliance represent the most attractive acquisition archetype for portfolio diversification. Watch carbon-offset mandate implementation timelines across the UAE and Saudi Arabia as the inflection signal for premium pricing tier emergence.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical Certification Investment | IATA CEIV Pharma and GDP compliance unlock premium-rate cargo segments across Saudi Arabia and the UAE. |
| Ground Handling Integration | Unified control over warehousing and last-mile operations compresses cost structures for Gulf carriers. |
| Secondary Hub Development | Muscat and Salalah positioning captures pharmaceutical and e-commerce flows outside Dubai-Abu Dhabi dominance. |
| Carbon-Offset Service Launch | Verified low-emission cargo tiers command premium pricing under emerging MOHAP and SFDA protocols. |
| Blockchain-IoT Platform Deployment | Real-time pharmaceutical provenance tracking reduces documentation processing from days to hours for customs clearance. |
Research Methodology
Operator-level perspectives from cargo fleet managers, pharmaceutical logistics directors, ground handling executives, and bilateral aviation negotiators anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against IATA cargo statistics, ICAO emissions disclosures, national civil aviation authority licensing records, and customs trade flow databases. Bottom-up capacity deployment modeling and top-down trade corridor analysis provided triangulation across the analysis window.
Scenario-bracketing around jet fuel price volatility and e-commerce penetration rates shaped the analytical framework. Segmentation dimensions modeled include service type, shipment temperature requirements, end-user industry procurement patterns, and distribution channel concentration. CAGRs derived from capacity deployment schedules, trade flow projections, and regulatory enforcement timelines. Forecast inputs incorporated pharmaceutical cold-chain infrastructure investment pipelines and bilateral air service agreement renegotiation postures.
Sensitivities concentrate around hydrocarbon construction cycle timing, SFDA enforcement intensity, and fifth-freedom traffic right expansions. Forecasts reflect documented assumptions about fleet renewal schedules and certification completion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
North America Logistics Automation Market
Logistics and Shipping
Nordics Freight and Logistics Market
Logistics and Shipping
United Kingdom Contract Logistics Market
Logistics and Shipping
Europe Refrigerated Container Shipping Market
Logistics and Shipping
Car Carrier Market
Logistics and Shipping
Sweden Cold Chain Logistics Market
Logistics and Shipping
Baggage Handling System Market
Logistics and Shipping
Japan Contract Logistics Market
Logistics and Shipping
Freight and Logistics Market
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
Europe Full Container Load (FCL) Market
Logistics and Shipping
Morocco Freight and Logistics Market
Logistics and Shipping
Italy Freight and Logistics Market
Logistics and Shipping
Thailand Freight and Logistics Market
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
Inbound Logistics Market