
 Japan Third-Party Logistics (3PL) Market | 2026-2036
Japan Third-Party Logistics (3PL) Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Third-Party Logistics (3PL) Market Foresight
Pharmaceutical-grade logistics certification is reorganizing competitive tiers across Japan's 3PL sector. Nippon Express Co., Ltd. leverages its nationwide cold chain infrastructure to dominate temperature-sensitive pharmaceutical distribution. Yamato Holdings Co., Ltd. sustains last-mile density through an unmatched parcel locker and home delivery network. LOGISTEED, Ltd. specializes in automated warehousing systems for precision manufacturing clients in the Nagoya industrial corridor.
Third-party logistics encompasses outsourced supply chain management where providers coordinate transportation, warehousing, and inventory control through integrated information systems, typically operating facilities exceeding ten thousand square meters with warehouse management systems achieving inventory accuracy above 99.5%. Warehousing services command premium margins in Japan due to land scarcity and automated vertical storage investments, while transportation remains volume-driven with thin spreads. E-commerce end users now drive fastest growth in same-day fulfillment networks, whereas cold chain management applications attract specialized operators seeking defensible technical barriers.
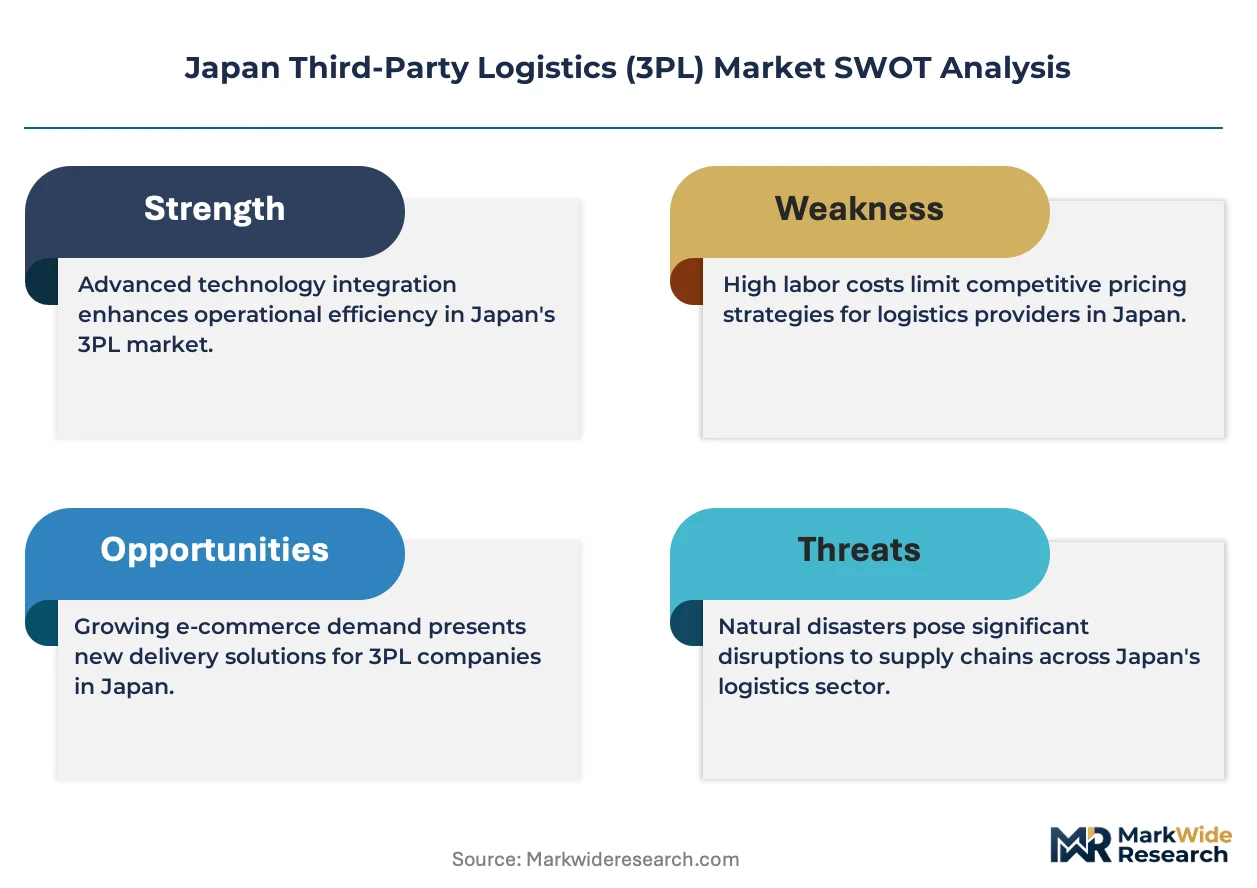
METI's logistics efficiency directives and Japan's Pharmaceutical and Medical Device Act jointly elevate compliance costs for temperature validation and traceability, filtering smaller operators from pharmaceutical and food-grade contracts. JIS standards for warehouse automation interoperability further shape technology procurement decisions among mid-tier providers. Stakeholders must monitor regulatory alignment between METI's decarbonization roadmap and customer Scope 3 emission reporting requirements, as carbon-accounting capabilities become a contract qualification threshold rather than a marketing differentiator.
Market Dynamics
Japan's 3PL sector faces a structural squeeze between METI's logistics efficiency mandates and the PMDA's escalating cold chain compliance requirements. Pharmaceutical outsourcing now demands temperature-validated infrastructure that smaller operators cannot finance.
Growth Catalysts
- E-commerce same-day fulfillment:Online retailers in the Kanto corridor require micro-fulfillment networks with sub-two-hour delivery windows. Automated sortation hubs in Saitama and Chiba prefectures absorb capital inflows.
- Pharmaceutical outsourcing:PMDA's revised Pharmaceutical and Medical Device Act compels manufacturers to abandon in-house distribution. Specialized cold chain operators capture contract migrations from Tokyo-based drug makers.
- Automated vertical storage:Land scarcity in Osaka and Nagoya drives investment in high-bay warehouse systems. JIS interoperability standards accelerate equipment procurement cycles among mid-tier providers.
Market Restraints
- Labor cost compression:Driver shortages in the Kansai region force wage premiums exceeding 15% above inflation. Transportation margins absorb this input cost volatility.
- Land scarcity premiums:Industrial zoned land in the Greater Tokyo Area commands valuations that exclude regional entrants. Incumbents with legacy site holdings capture disproportionate warehousing margins.
- Carbon accounting compliance:METI's decarbonization roadmap demands Scope 3 emission tracking that legacy IT infrastructure cannot support. Smaller operators face exclusion from pharmaceutical and food-grade contracts.
Strategic Opportunities
- Hokkaido cold chain expansion:Underpenetrated temperature-controlled infrastructure in northern Japan serves seafood export corridors. Specialized operators can anchor pharmaceutical distribution north of the Kanto cluster.
- Battery logistics for EV manufacturing:Toyota and Nissan's domestic battery production requires hazardous materials handling certification. 3PL operators with UN 38.3 compliance capture automotive supply chain contracts.
- Reverse logistics for electronics:Extended producer responsibility frameworks mandate collection networks for consumer electronics. Automated inspection and refurbishment systems create defensible service tiers.
Industry Challenges
- Certification timeline compression:PMDA's temperature validation protocols require 18-24 month qualification periods for new cold chain facilities. Pharmaceutical contracts migrate to pre-qualified incumbents.
- Legacy WMS integration:Warehouse management system upgrades to support real-time inventory tracking demand capital outlays that strain mid-tier balance sheets. Interoperability gaps persist between automated equipment and existing software stacks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Third-Party Logistics (3PL) Market |
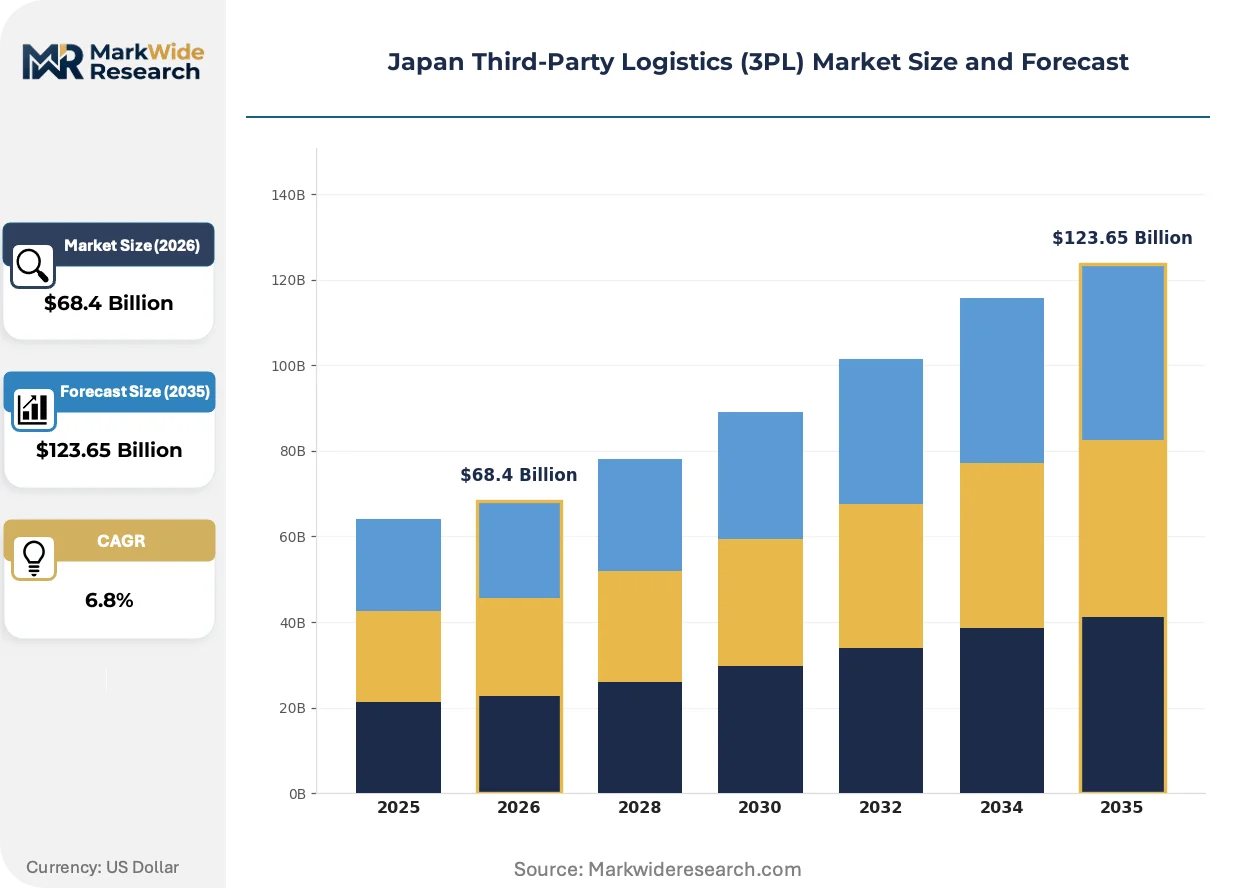
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Distribution, Inventory Management End User: E-commerce, Retail, Manufacturing, Healthcare Technology: Automation, Cloud Logistics, IoT Solutions, Data Analytics Application: Order Fulfillment, Cold Chain Management, Freight Forwarding, Cross-Docking |
| Companies Covered | SG Holdings Co., Ltd., NYK Line, Nippon Express Co., Ltd., Sankyu Inc., Mitsui-Soko Holdings Co., Ltd., Yamato Holdings Co., Ltd., LOGISTEED, Ltd., Sagawa Express Co., Ltd., Kintetsu World Express, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Third-Party Logistics (3PL) Market Shifts & Advancements
Automation and regulatory compliance are converging to reshape competitive positioning across Japan's logistics infrastructure. Technology deployment now separates contract-eligible operators from excluded regional players.
Autonomous mobile robots (AMRs) with LiDAR navigation and collaborative picking capabilities are supplanting fixed conveyor systems in high-SKU e-commerce fulfillment. Rakuten and Amazon Japan deploy these systems in Yokohama and Kawasaki facilities. The technology compresses order cycle times from hours to minutes while reducing labor dependency in the Kanto warehouse cluster.
PMDA's 2023 enforcement guidance on temperature excursion documentation mandates continuous digital logging for all pharmaceutical shipments. Cold chain operators must retrofit vehicle telematics and warehouse sensors to capture minute-level thermal data. The regulation most affects last-mile distributors serving Tokyo's hospital networks, forcing consolidation toward technology-capable providers.
Pharmaceutical procurement departments now require carbon footprint reporting as a contract qualification threshold rather than a marketing differentiator. METI's emissions disclosure framework pressures 3PL operators to invest in electric vehicle fleets and renewable-powered warehouses. The shift is most visible among Tokyo-based drug manufacturers selecting logistics partners for 2025-2028 contract cycles.
Japan Third-Party Logistics (3PL) Market Segmentation
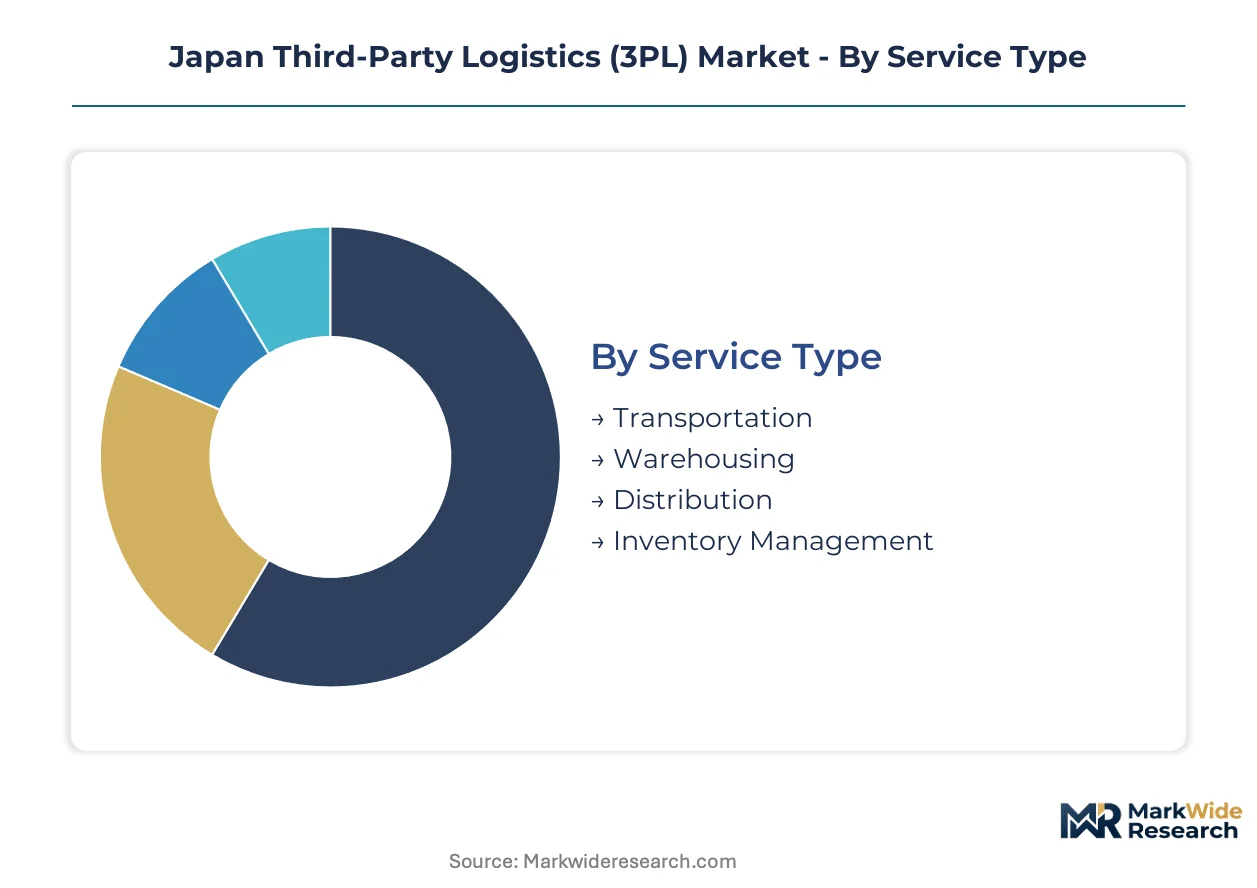
Segmentation reveals how Japan's 3PL operators allocate capital across service tiers and customer types. Channel configuration differs sharply between pharmaceutical cold chain networks and e-commerce fulfillment corridors.
Service Type:
Transportation and warehousing segments flow through distinct channel architectures. Pharmaceutical manufacturers require integrated service bundles, while retail clients unbundle transportation from storage.
- Transportation:Full-truckload and less-than-truckload services coordinate temperature-validated vehicle fleets across the Kanto corridor. Driver shortages in Kansai compress margins despite volume concentration from automotive and electronics manufacturers.
- Warehousing:Automated vertical storage systems in Yokohama and Nagoya achieve inventory accuracy above 99.5% through JIS-standardized equipment. Land scarcity premiums exclude new entrants from the Greater Tokyo Area.
- Distribution:Last-mile networks integrate parcel lockers and home delivery infrastructure. Yamato Holdings sustains density advantages through unmatched locker deployment in urban prefectures.
- Inventory Management:Real-time tracking systems synchronize stock levels across multi-node networks. Pharmaceutical clients demand WMS integration with PMDA temperature excursion documentation protocols.
By volume, Transportation leads. By growth pace, Warehousing is ahead.
End User:
Cost tier differentiation separates premium pharmaceutical contracts from volume-driven retail engagements. Certification requirements create pricing stratification across customer categories.
- E-commerce:Same-day fulfillment networks in Saitama and Chiba absorb capital inflows from Rakuten and Amazon Japan. Micro-fulfillment hubs compress order cycle times to sub-two-hour windows.
- Healthcare:Pharmaceutical manufacturers outsource temperature-controlled distribution under PMDA's revised Pharmaceutical and Medical Device Act. Cold chain compliance filters smaller operators from contract eligibility.
- Retail:Department store and supermarket chains demand seasonal surge capacity. Automated sortation systems handle peak volume spikes during holiday periods.
- Manufacturing:Precision electronics and automotive clients in the Nagoya industrial corridor require just-in-time delivery windows. LOGISTEED specializes in automated warehousing for these exacting schedules.
E-commerce captures the steepest expansion trajectory. Healthcare commands the highest margin premiums.
Technology:
Application maturity varies across the technology stack. Cloud logistics and IoT solutions now function as baseline infrastructure rather than competitive differentiators.
- Automation:Autonomous mobile robots with LiDAR navigation supplant fixed conveyor systems in high-SKU fulfillment. AMR deployments in Yokohama and Kawasaki facilities reduce labor dependency.
- IoT Solutions:Vehicle telematics and warehouse sensors capture minute-level thermal data for pharmaceutical shipments. PMDA enforcement guidance mandates continuous digital logging.
- Cloud Logistics:Distributed computing architectures enable real-time inventory visibility across multi-node networks. Mid-tier providers struggle with legacy WMS integration costs.
- Data Analytics:Predictive routing algorithms optimize last-mile delivery density. Carbon accounting modules track Scope 3 emissions for pharmaceutical contract qualification.
Automation attracts the largest capital commitments. Data analytics is climbing the fastest as procurement departments mandate emission reporting.
Application:
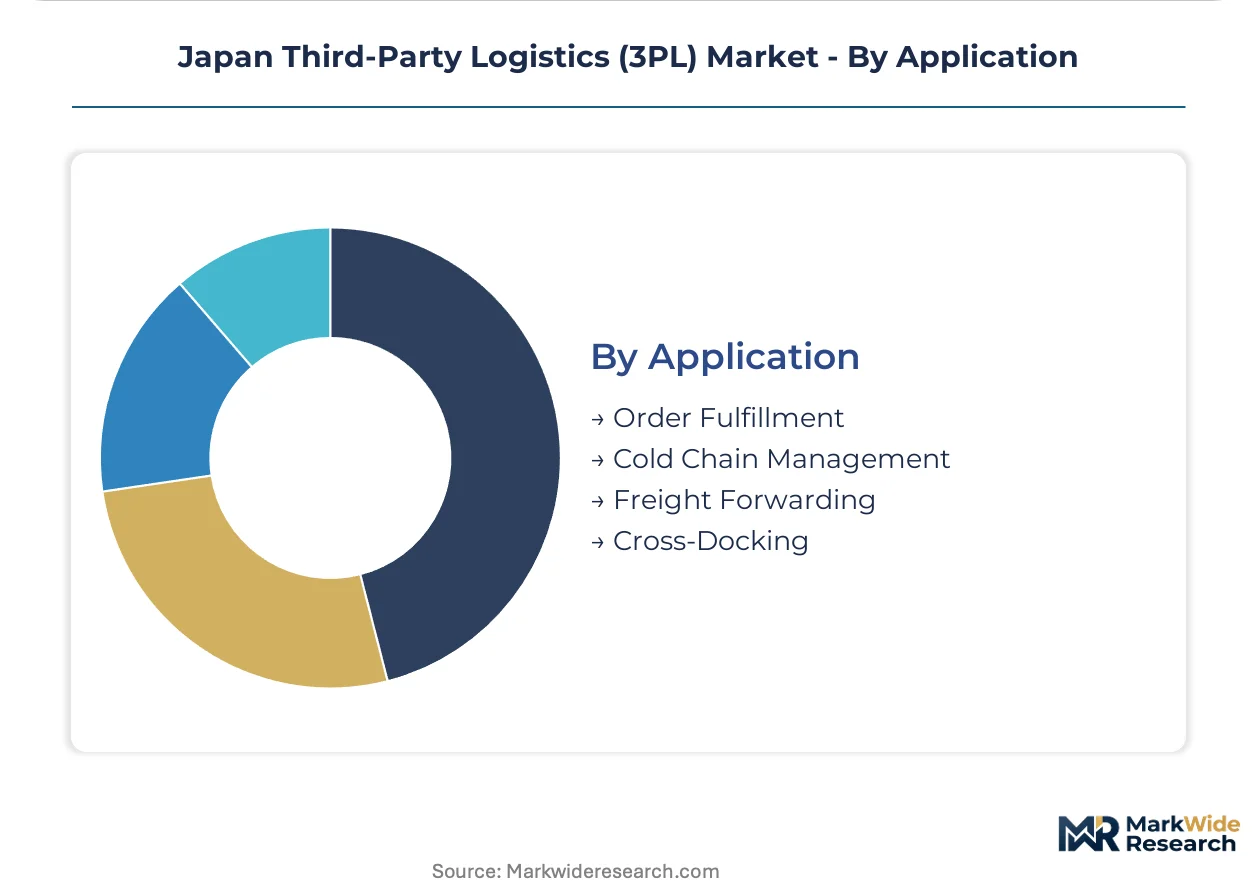
Geographic concentration shapes application-level demand. Cold chain management concentrates in Kanto, while cross-docking hubs anchor intermodal corridors.
- Cold Chain Management:Temperature-validated infrastructure serves pharmaceutical and seafood export corridors. Nippon Express leverages nationwide cold chain assets to dominate this segment.
- Order Fulfillment:E-commerce same-day networks require automated sortation and micro-fulfillment proximity. Kanto-based operators capture disproportionate contract value.
- Freight Forwarding:International consolidation and customs brokerage support manufacturing export flows. Port-centric operations in Yokohama and Kobe handle containerized volume.
- Cross-Docking:Transloading facilities minimize inventory holding time for retail and automotive supply chains. Just-in-time manufacturing schedules demand sub-four-hour dock-to-departure cycles.
Order Fulfillment leads by transaction volume. Cold Chain Management is gaining share fastest on pharmaceutical outsourcing momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Japan's logistics corridors. E-commerce retailers in Greater Tokyo absorb premium rates for same-day fulfillment, while regional manufacturers in Tohoku and Kyushu prioritize cost-minimization over speed.
Kanto/Tokyo
Pharmaceutical outsourcing and e-commerce same-day fulfillment drive demand concentration. METI's logistics efficiency directives and PMDA cold chain compliance requirements elevate operating costs. Automated fulfillment centers in Saitama and Chiba prefectures process sub-two-hour delivery windows for Rakuten and Amazon Japan.
Kansai/Osaka
Precision manufacturing supply chains and automotive just-in-time delivery dominate regional demand. Driver shortages force wage premiums exceeding 15% above inflation, compressing transportation margins. The Osaka industrial corridor hosts dense clusters of electronics and machinery manufacturers requiring exacting delivery schedules.
Chubu/Nagoya
Automotive and aerospace manufacturing anchor logistics demand in this central industrial belt. JIS standards for warehouse automation interoperability shape technology procurement among mid-tier providers. LOGISTEED specializes in automated warehousing systems serving Toyota and Nissan production networks.
Hokkaido
Seafood export corridors and underpenetrated pharmaceutical distribution create expansion opportunities. Temperature-controlled infrastructure remains sparse relative to Kanto density. Specialized cold chain operators can anchor pharmaceutical networks serving northern hospital systems.
Kyushu
Semiconductor and automotive component manufacturing drives freight forwarding demand. Port-centric operations in Fukuoka handle containerized volume for export manufacturing. Regional operators compete primarily on transportation cost rather than value-added warehousing services.
Japan Third-Party Logistics (3PL) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Japan's 3PL sector. The market structure consolidates around diversified logistics conglomerates with legacy infrastructure holdings, while mid-tier regional operators compete on price-sensitive transportation contracts. Three archetypes dominate: nationwide cold chain specialists, last-mile density leaders, and automated warehousing integrators. Competitive moves center on pharmaceutical certification acquisition and carbon-accounting capability investment to meet METI's Scope 3 disclosure requirements.
Within the diversified conglomerate tier, Nippon Express Co., Ltd. and Yamato Holdings Co., Ltd. occupy positions reflecting distinct strategic emphases. Nippon Express exemplifies the cold chain infrastructure archetype through nationwide temperature-validated assets. Yamato Holdings represents last-mile density leadership through urban parcel locker networks. LOGISTEED, Ltd. anchors the automated warehousing specialization serving precision manufacturing clients in central Japan.
| Leading Market Players |
|---|
| SG Holdings Co., Ltd. |
| NYK Line |
| Nippon Express Co., Ltd. |
| Sankyu Inc. |
| Mitsui-Soko Holdings Co., Ltd. |
| Yamato Holdings Co., Ltd. |
| LOGISTEED, Ltd. |
| Sagawa Express Co., Ltd. |
| Kintetsu World Express, Inc. |
| Others |
Supply & Pricing Matrix
PMDA's pharmaceutical-grade logistics certification gates both supply qualification and price differentiation simultaneously. Operators without temperature-validated infrastructure face automatic exclusion from healthcare contracts regardless of rate competitiveness.
Pricing Analysis
Long-term service contracts with embedded maintenance and compliance monitoring drive lifetime value for cold chain operators. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-certified pharmaceutical distribution from food-grade temperature control and generic ambient warehousing. Cost compression in transportation stems from Kansai driver shortages forcing wage premiums above inflation. E-commerce retailers absorb premium rates for same-day fulfillment, while regional manufacturers prioritize cost-minimization over speed.
Supply Chain Analysis
Port congestion at Yokohama and Kobe elevates inbound logistics costs for automated warehouse equipment imported from Germany, South Korea, and China. Critical components include LiDAR navigation systems, high-bay racking assemblies, and refrigerated vehicle compressors. Single-source vulnerability concentrates in German-engineered warehouse automation controllers. Distribution runs through Kanto fulfillment hubs serving Tokyo's dense hospital and e-commerce networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. PMDA certification timelines create switching costs that lock pharmaceutical manufacturers into incumbent relationships.
For Market Incumbents: Secure PMDA pre-qualification status for expanded cold chain facilities before competitors complete 18-24 month validation cycles. Deepen backward integration into automated equipment maintenance to reduce dependency on German controller suppliers. Acquire underutilized land holdings in Greater Tokyo Area to preempt regional entrant expansion.
For New Entrants and Emerging Players: Certification fast-track through partnership with established PMDA-compliant operators enables contract eligibility without full infrastructure investment. Hokkaido's underpenetrated pharmaceutical distribution network offers the most penetrable geography. Target seafood export corridors with dual-use temperature-controlled assets to amortize cold chain investments across seasonal demand cycles.
For Investors and Strategic Acquirers: METI's Scope 3 disclosure mandate reshapes the acquisition landscape toward carbon-accounting-capable operators. Five-to-ten year viability favors diversified conglomerates with legacy site holdings and integrated service bundles. Target operators with pre-qualified pharmaceutical infrastructure and established hospital network relationships. Monitor PMDA enforcement guidance amendments as the critical inflection signal for compliance investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Certification Investment | PMDA pre-qualification locks in pharmaceutical contract eligibility before competitors complete validation. |
| Automated Warehouse Expansion | JIS-standardized equipment procurement in Saitama and Chiba compresses order cycle times for e-commerce clients. |
| Carbon Accounting Capability Buildout | METI's Scope 3 disclosure framework elevates emission tracking to contract qualification threshold for Tokyo drug manufacturers. |
| Last-Mile Network Densification | Parcel locker deployment in urban prefectures sustains delivery density advantages against regional price competitors. |
| Hokkaido Infrastructure Anchoring | Temperature-controlled facilities in northern Japan capture seafood export volume and pharmaceutical distribution white space. |
Research Methodology
Desk research of METI logistics efficiency reports, PMDA enforcement guidance documents, and JIS warehouse automation standards preceded structured interviews with pharmaceutical supply chain directors, cold chain operations managers, 3PL procurement leads, and automated equipment integrators. Primary fieldwork with Tokyo-based drug manufacturers and Kanto fulfillment operators combined with secondary validation from customs trade data and industrial land transaction records. Bottom-up facility capacity estimates and top-down market size triangulation cross-checked segment allocations.
Variance decomposition across service type, end user category, technology tier, and geographic cluster shaped the analytical framework over the projection horizon. Modeled dimensions included transportation-warehousing-distribution service bundles, e-commerce-healthcare-retail-manufacturing end use segments, automation-IoT-cloud-data analytics technology stacks, and Kanto-Kansai-Chubu-Hokkaido-Kyushu regional corridors. CAGRs derived from facility investment pipelines, contract migration patterns, and regulatory compliance cost trajectories.
Decision-makers should treat outputs as directional under assumptions of sustained PMDA enforcement intensity and METI decarbonization timeline adherence; material deviation would warrant model refresh. Pharmaceutical outsourcing velocity, electric vehicle fleet conversion rates, and automated equipment procurement cycles represent primary forecast sensitivities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
North America Pharmaceutical Logistics Market
Logistics and Shipping
Philippines Freight and Logistics Market
Logistics and Shipping
Air Freight Software Market
Logistics and Shipping
Japan Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Egypt Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
South Korea Parcel Delivery Market
Logistics and Shipping
Peru Road Freight Transport Market
Logistics and Shipping
Chile Cold Chain Logistics Market
Logistics and Shipping
Cloud Logistics Market
Logistics and Shipping
United States Air Freight Market
Logistics and Shipping
Asean Freight and Logistics Market
Logistics and Shipping
Russia Freight and Logistics Market
Logistics and Shipping
Middle Mile Delivery Market
Logistics and Shipping
Military Logistics Market
Logistics and Shipping
Egypt Freight and Logistics Market
Logistics and Shipping
US Fourth-Party Logistics (4PL) Market