
 ASEAN Cross Border Road Freight Transport Market | 2026-2036
ASEAN Cross Border Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Cross Border Road Freight Transport Market Outlook
Electronics manufacturing is shifting toward just-in-time cross-border replenishment between Vietnam and Thailand. Deutsche Post DHL Group leverages its ASEAN customs brokerage network to anchor bonded warehouse flows across multiple land borders. Kerry Logistics Network Limited dominates temperature-controlled trailer movements for perishables on the Bangkok-Phnom Penh route. SF Express competes through dedicated freight lanes connecting southern China with northern Vietnam.
ASEAN cross border road freight transport encompasses overland cargo movement between member states using commercial vehicles subject to bilateral transit permits, axle load limits, and customs seal protocols. Truck fleets operate under the ASEAN Framework Agreement on the Facilitation of Goods in Transit, with maximum gross vehicle weights typically capped at forty-four tonnes on designated corridors. Full Truck Load services capture the largest revenue share due to electronics and automotive component volumes, while Less Than Truck Load segments attract margin from SME retailers seeking consolidated Bangkok, Kuala Lumpur, and Jakarta distribution. Intermodal services linking Thai deepwater ports with Lao PDR and Myanmar land borders represent the fastest-growing structural category as manufacturers diversify from sole China dependency.
ASEAN Secretariat transit agreements, Thailand's Department of Land Transport cross-border permit schemes, and Vietnam's customs electronic data interchange requirements collectively shape fleet specifications, driver certification, and route licensing. The ASEAN Single Window and national digital customs platforms determine market access speed and compliance costs for operators. Stakeholders must monitor which member states ratify the ASEAN Customs Transit System and where bilateral quota expansions unlock new corridor capacity.
Market Dynamics
The ASEAN Cross Border Road Freight Transport Market is being fundamentally restructured by the ASEAN Single Window protocols, which compress customs clearance times and eliminate redundant documentation across Thailand, Vietnam, and Malaysia land borders. Electronics manufacturers now demand synchronized replenishment cycles that require real-time transit visibility.
Growth Catalysts
- ASEAN Customs Transit System ratification:Member states adopting the unified transit framework eliminate physical customs seals and bonded warehouse stops. Thailand and Vietnam lead implementation, cutting border dwell times for automotive component flows.
- Electronics just-in-time sourcing:Semiconductor and consumer electronics manufacturers now source precision components across Thailand-Vietnam corridors rather than sole China dependency. This creates dedicated Full Truck Load demand with strict delivery windows.
- Digital customs platform integration:National electronic data interchange systems in Vietnam and Malaysia enable pre-arrival clearance. Truck operators submit manifests before border arrival, reducing inspection rates for certified fleet operators.
Market Restraints
- Bilateral permit quota scarcity:Thailand's Department of Land Transport caps cross-border permits at levels below actual freight demand. This artificial supply constraint inflates spot market rates during peak electronics shipping seasons.
- Axle load limit fragmentation:Maximum gross vehicle weights vary from forty tonnes in Myanmar to forty-four tonnes in Thailand. Fleet operators must maintain mixed trailer specifications or accept payload inefficiencies on certain corridors.
- Driver certification reciprocity gaps:ASEAN member states lack mutual recognition of commercial driver qualifications. Vietnamese-licensed operators face re-certification requirements to enter Thai territory, limiting labor pool flexibility.
Strategic Opportunities
- Cambodia-Myanmar corridor development:These underpenetrated markets offer first-mover positioning as manufacturing relocates from coastal China. Thai deepwater port connections through Laem Chabang to Phnom Penh and Yangon represent structural white space.
- Temperature-controlled trailer specialization:Perishable agricultural exports from Thailand's eastern provinces to Vietnam and Cambodia lack sufficient refrigerated capacity. Dedicated cold chain fleets command rate premiums on the Bangkok-Phnom Penh axis.
- Intermodal port-rail-road integration:Thai government infrastructure incentives support bonded container movements from Laem Chabang and Map Ta Phut to Lao PDR and Myanmar land borders. This multimodal positioning captures manufacturing diversification flows.
Industry Challenges
- Fleet telematics integration complexity:Legacy truck assets lack standardized GPS and electronic logging device compatibility. Operators must retrofit mixed-age fleets to meet customer visibility requirements and insurance compliance.
- Cross-border fuel taxation reconciliation:Diesel purchased in one jurisdiction cannot be easily accounted for in another's tax regime. This creates administrative burden and audit risk for multi-country route operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Cross Border Road Freight Transport Market |
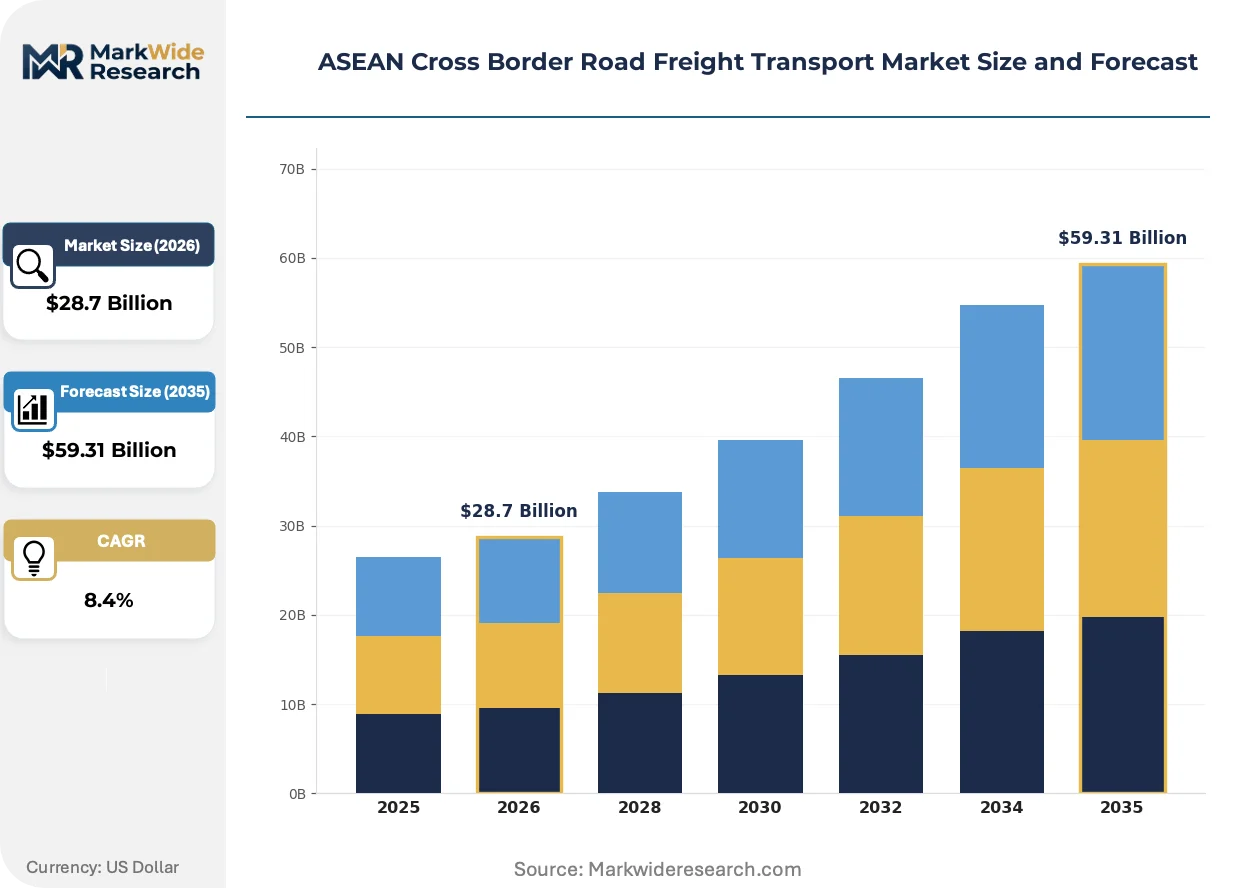
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $59.31 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transport Mode: Truck, Trailer, Container, Van Service Type: Full Truck Load, Less Than Truck Load, Intermodal, Dedicated Freight Client Type: Retailers, Manufacturers, Distributors, Importers Cargo Type: Perishables, Electronics, Textiles, Heavy Machinery |
| Companies Covered | DB Schenker, Deutsche Post DHL Group, Kerry Logistics Network Limited, Tiong Nam Logistics, Konoike Group, Yamato Transport, SF Express, “K” Line Logistics, Gemadept, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Cross Border Road Freight Transport Market Strategic Shifts
Digital freight matching platforms and blockchain-based customs documentation are compressing transaction costs and eliminating paper-based inefficiencies that historically dominated ASEAN land border crossings. Fleet operators now compete on data transparency rather than asset scale alone.
Blockchain-enabled customs documentation is consolidating fragmented paper trails into immutable shipment records shared between Thai, Vietnamese, and Malaysian customs authorities. Electronics manufacturers and automotive Tier-1 suppliers now mandate blockchain-verified chain-of-custody as a procurement condition. This technology is consolidating compliance advantage among early-adopter fleet operators who invested in integrated document management systems.
ASEAN Framework Agreement on the Facilitation of Goods in Transit amendments now mandate electronic advance cargo information submission across all ratifying member states. Thai and Vietnamese customs authorities coordinate inspection risk profiling through shared algorithms, reducing physical examination rates for low-risk shippers. Temperature-controlled perishable exporters face accelerated inspection protocols under the updated framework.
Shippers now consolidate previously fragmented Less Than Truck Load movements into scheduled lane contracts with guaranteed capacity. Small and medium electronics component suppliers in Bangkok and Ho Chi Minh City abandon spot market procurement in favor of annual rate agreements with visibility dashboards. This behavioral shift concentrates volume with integrated logistics providers who control both cross-border permits and bonded warehouse networks.
ASEAN Cross Border Road Freight Transport Market Segmentation
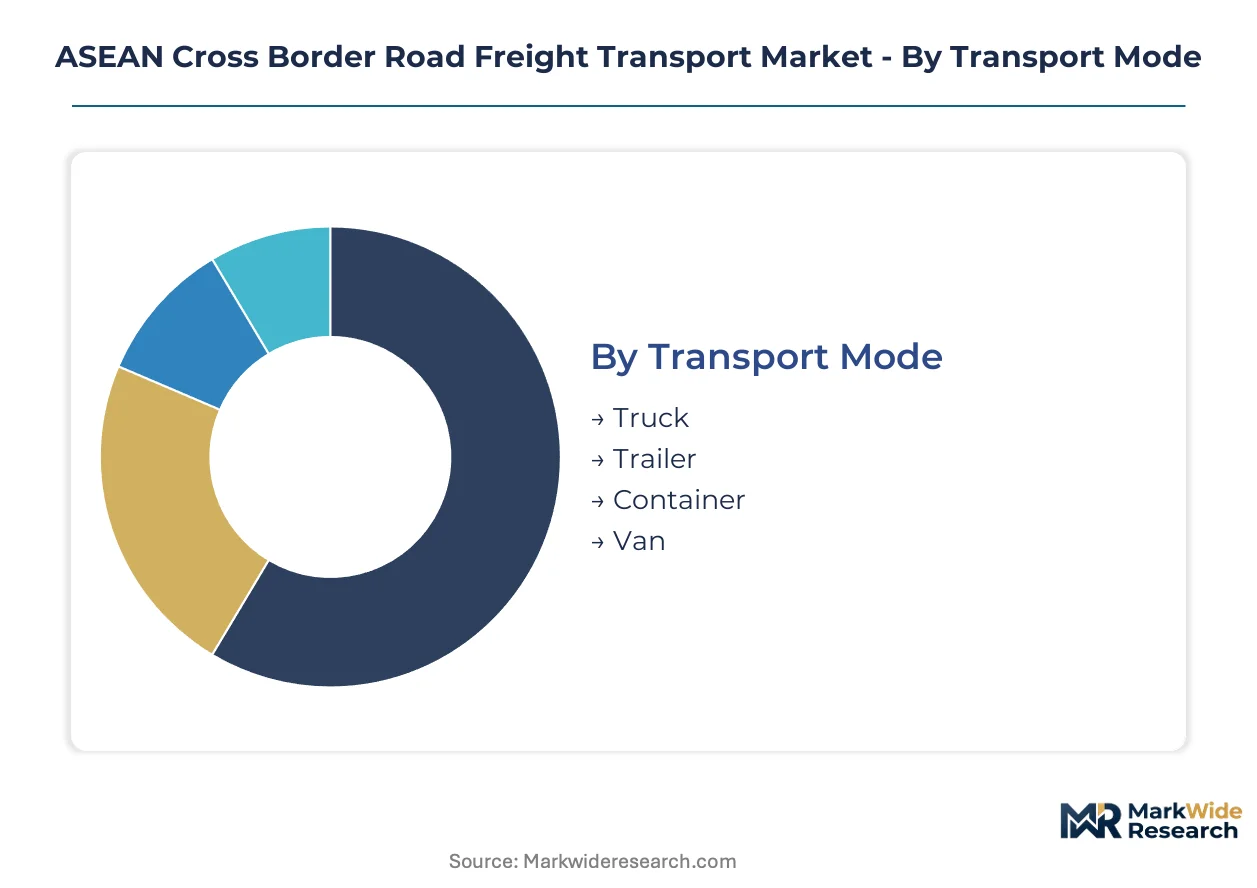
Cross-border road freight in ASEAN fragments across equipment specifications, service intensity, and cargo handling requirements. Electronics manufacturers and perishable exporters impose radically different constraints on fleet configuration and routing protocols. Understanding these divides reveals where margin concentrates and which operational capabilities separate market leaders from commodity haulers.
Transport Mode:
Equipment selection reflects corridor infrastructure limits, cargo security requirements, and backhaul efficiency calculations across Thailand, Vietnam, and Malaysia land borders.
- Truck:Rigid-body trucks dominate short-haul movements under 300 kilometers, particularly for Bangkok-Phnom Penh and Ho Chi Minh City-Phnom Penh corridors. Thai Department of Land Transport permit quotas favor truck-based operators for bilateral flows, though payload limits vary by axle configuration.
- Trailer:Articulated combinations with detachable semi-trailers enable efficient cab rotation at border points, reducing driver downtime during customs processing. Electronics manufacturers specify curtain-sided trailers with GPS tracking and customs seal compatibility for Thailand-Vietnam precision component flows.
- Container:ISO container movements integrate with Laem Chabang and Cai Mep deepwater port networks, supporting bonded transit to Lao PDR and Myanmar land borders. Intermodal container positioning captures manufacturing diversification away from sole China dependency.
- Van:Light commercial vehicles handle last-mile distribution and high-value electronics samples requiring rapid customs clearance. Van fleets operate under less restrictive permit regimes but face volume ceilings that limit scalability on major corridors.
Truck and trailer configurations lead volumes today; container-based intermodal positioning is gaining share fastest as manufacturers integrate port-rail-road networks.
Service Type:
Service intensity tiers separate integrated logistics providers from spot-market operators based on contract duration, visibility requirements, and network control depth.
- Full Truck Load:Dedicated vehicle allocation for single-shipper volumes dominates electronics and automotive component corridors. FTL contracts specify delivery windows within four-hour tolerances, with penalties for deviation that favor operators controlling bonded warehouse networks and cross-border permit reserves.
- Less Than Truck Load:Consolidated shipments from multiple SME retailers require hub-and-spoke terminal networks in Bangkok, Ho Chi Minh City, and Kuala Lumpur. LTL margins depend on load factor optimization and customs clearance speed at consolidation points.
- Intermodal:Sea-land and rail-land combinations reduce transit cost for non-urgent manufacturing inputs. Thai government infrastructure incentives support bonded container movements from eastern seaboard ports to Mekong subregion land borders.
- Dedicated Freight:Exclusive lane contracts with guaranteed capacity and real-time visibility dashboards now displace spot procurement for electronics component suppliers. Annual rate agreements with integrated providers concentrate volume among operators controlling ASEAN customs brokerage networks.
Full Truck Load commands revenue concentration today; dedicated freight contracts are climbing the fastest as shippers abandon spot volatility.
Client Type:
Buyer sophistication and procurement scale determine service bundling requirements and pricing leverage across the freight procurement spectrum.
- Retailers:Bangkok and Ho Chi Minh City-based retail chains demand scheduled lane contracts with inventory visibility and returns handling. Retail procurement teams negotiate annual rate agreements that bundle cross-border transport with last-mile distribution.
- Manufacturers:Electronics and automotive Tier-1 suppliers mandate synchronized replenishment cycles with strict delivery windows. Manufacturing procurement specifies blockchain-verified chain-of-custody and real-time GPS tracking as mandatory conditions.
- Distributors:Regional trading companies aggregate fragmented SME demand and resell consolidated capacity. Distributor relationships concentrate volume with operators maintaining flexible permit access across multiple bilateral corridors.
- Importers:First-time entrants to ASEAN sourcing networks rely on freight forwarders for customs compliance and route optimization. Importer demand concentrates on Thailand-Vietnam corridors with established customs facilitation protocols.
Manufacturers lead volume concentration today; retailer procurement consolidation is expanding most quickly as scheduled lane contracts displace spot arrangements.
Cargo Type:
Physical handling requirements and regulatory treatment differentiate fleet specifications, insurance coverage, and corridor routing priorities.
- Perishables:Temperature-controlled trailers with continuous cold chain monitoring command rate premiums on Bangkok-Phnom Penh and eastern Thailand-Vietnam axes. Thai agricultural exporters face accelerated inspection protocols under ASEAN Framework Agreement amendments.
- Electronics:Precision semiconductor and consumer electronics components require vibration-controlled transport with customs seal integrity. Electronics flows concentrate on Thailand-Vietnam corridors where ASEAN Single Window protocols compress clearance times.
- Textiles:Garment and fabric movements from Bangkok and Ho Chi Minh City manufacturing zones tolerate longer transit windows. Textile freight competes on cost efficiency rather than speed, favoring consolidated LTL arrangements.
- Heavy Machinery:Oversized equipment and construction materials require specialized low-loader trailers and route permits for bridge weight limits. Heavy cargo flows concentrate on infrastructure development corridors linking Thai deepwater ports with Lao PDR and Myanmar.
Electronics and perishables dominate value-weighted volumes today; heavy machinery positioning shows the steepest expansion trajectory as infrastructure investment accelerates across Mekong subregion markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing relocation from coastal China to lower-cost ASEAN jurisdictions accelerates cross-border freight flows as regulatory arbitrage widens between Vietnam's streamlined customs protocols and Myanmar's underdeveloped transit frameworks.
Thailand
Electronics component manufacturers cluster along the Eastern Economic Corridor, generating dense Full Truck Load demand toward Vietnam. Thailand's Department of Land Transport administers bilateral permit quotas that cap fleet expansion below actual freight requirements. Laem Chabang port anchors intermodal container movements to Lao PDR and Myanmar land borders.
Vietnam
Semiconductor packaging facilities in Bac Ninh and Ho Chi Minh City drive synchronized replenishment cycles with Thai suppliers. Vietnam's customs electronic data interchange mandates pre-arrival manifest submission, compressing border dwell times. The Bangkok-Hanoi-Ho Chi Minh City corridor captures the highest freight volumes in the subregion.
Malaysia
Penang-based electronics assemblers source precision components across the Thai border, favoring dedicated freight contracts with real-time visibility. Malaysia's digital customs platform integrates with ASEAN Single Window protocols, enabling risk-based inspection profiling. Johor Bahru functions as the primary consolidation hub for Singapore-originating cargo.
Cambodia
Garment manufacturers in Phnom Penh and Sihanoukville generate temperature-controlled demand for Thai agricultural inputs. Cambodia's ratification of ASEAN Customs Transit System amendments remains incomplete, preserving physical customs seal requirements. The Bangkok-Phnom Penh axis lacks sufficient refrigerated trailer capacity for perishable export growth.
Myanmar
Infrastructure development corridors linking Yangon with Thai deepwater ports attract heavy machinery movements. Myanmar's axle load limits cap gross vehicle weights at forty tonnes, forcing payload inefficiencies on mixed-fleet operators. Cross-border permit scarcity and political instability constrain formal freight market development.
ASEAN Cross Border Road Freight Transport Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated logistics providers commanding premium positioning in electronics corridors while regional haulers compete on cost in perishable and textile lanes. Market structure concentrates around operators controlling bonded warehouse networks and bilateral permit reserves, creating tiered competition between asset-heavy multinationals and permit-dependent local fleets. Three archetypes dominate: customs brokerage-integrated providers, temperature-controlled specialists, and intermodal port operators. Competitive dynamics center on permit quota acquisitions and cold chain fleet expansion rather than pure price competition.
Within the customs brokerage-integrated tier, Deutsche Post DHL Group and Kerry Logistics Network Limited exemplify operators leveraging ASEAN-wide clearance networks to anchor bonded warehouse flows. Deutsche Post DHL Group's permit reserves across multiple land borders position it for electronics manufacturer contracts with strict delivery windows. Kerry Logistics Network Limited occupies the temperature-controlled specialization vector, commanding rate premiums on perishable corridors where refrigerated capacity scarcity persists. SF Express represents the China-ASEAN connectivity archetype, with dedicated freight lanes linking southern China manufacturing zones with northern Vietnam electronics clusters. These three operators illustrate how network control depth separates market leaders from commodity haulers in quota-constrained corridors.
| Leading Market Players |
|---|
| DB Schenker |
| Deutsche Post DHL Group |
| Kerry Logistics Network Limited |
| Tiong Nam Logistics |
| Konoike Group |
| Yamato Transport |
| SF Express |
| "K" Line Logistics |
| Gemadept |
| Others |
Value Chain & Pricing Dynamics
Electronics manufacturers concentrated along Thailand's Eastern Economic Corridor and Vietnam's Bac Ninh province anchor contract-based pricing with strict delivery penalties. Their procurement power compresses margins for operators lacking bonded warehouse networks or bilateral permit reserves.
Pricing Analysis
Distributor margins on Less Than Truck Load consolidation absorb the steepest compression as shippers migrate to direct contracts with integrated providers. Contract-based long-term offtake dominates Full Truck Load corridors, with price differentiation hinging on real-time GPS visibility and customs clearance speed versus basic transport-only rates. Cost compression in spot-market LTL is intensifying because digital freight platforms erode traditional broker markups. Small and medium electronics component suppliers show highest price sensitivity, while automotive Tier-1 suppliers prioritize reliability premiums over rate negotiation.
Supply Chain Analysis
Diesel supply rests on Thai and Vietnamese refinery networks, with cross-border fuel taxation creating administrative friction for multi-country operators. Fleet assets draw from Japanese and Chinese truck manufacturers, while refrigerated trailer components source from South Korean thermal unit specialists. Single-source vulnerability concentrates in bilateral permit quotas controlled by Thailand's Department of Land Transport. Distribution runs through bonded warehouse networks at Laem Chabang, Cai Mep, and Ho Chi Minh City before final-mile van deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN Customs Transit System ratification compounds regulatory-driven demand as member states eliminate physical customs seals and bonded warehouse stops. This milestone rewards early-adopter fleet operators with compliance advantages across Thailand-Vietnam corridors.
For Market Incumbents: Lock in cross-border permit reserves through multi-year bilateral agreements with Thailand's Department of Land Transport and Vietnam's customs authorities. Expand temperature-controlled trailer fleets along Bangkok-Phnom Penh axes before regional competitors capture perishable export growth. Counter margin pressure from digital freight platforms by integrating blockchain-verified chain-of-custody into standard service offerings. For New Entrants and Emerging Players: Enter via Cambodia-Myanmar corridor development where manufacturing relocation from coastal China outpaces established logistics capacity. Target temperature-controlled agricultural exports from Thailand's eastern provinces as the most penetrable segment, where refrigerated trailer scarcity persists. Build initial presence through dedicated freight contracts with annual rate agreements rather than spot-market competition. For Investors and Strategic Acquirers: Integrated logistics providers with ASEAN customs brokerage networks are the most active acquirer in this space, consolidating permit-dependent local fleets. Long-term viability favors operators controlling both cross-border infrastructure and digital visibility platforms. Watch ASEAN Customs Transit System ratification timelines across remaining member states as the critical inflection indicator for corridor capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Bilateral Permit Quota Acquisition | Thailand's Department of Land Transport caps constrain formal market entry for unlicensed operators. |
| Temperature-Controlled Fleet Expansion | Perishable agricultural exports from Thailand's eastern provinces lack sufficient refrigerated capacity. |
| Bonded Warehouse Network Integration | Laem Chabang and Cai Mep port connections enable intermodal positioning for manufacturing diversification flows. |
| Blockchain Customs Documentation Deployment | Electronics manufacturers mandate immutable shipment records as mandatory procurement conditions. |
| Digital Freight Platform Partnership | Real-time matching platforms compress transaction costs and eliminate paper-based border inefficiencies. |
Study Parameters
Coverage spans Thailand, Vietnam, Malaysia, Cambodia, and Myanmar, with primary inputs from each jurisdiction's logistics operators and regulatory bodies. The research combines interviews with fleet operations directors, customs brokerage managers, electronics manufacturer procurement leads, and Thai Department of Land Transport officials with secondary validation from ASEAN Secretariat transit agreement documents, national customs electronic data interchange specifications, and bilateral permit quota records. Bottom-up fleet capacity estimates triangulate against top-down trade flow data.
Rate-of-change decomposition separates volume growth from pricing trajectory across transport mode, service type, and cargo type segments. The analytical framework models equipment specifications, contract duration tiers, and client procurement sophistication throughout the projection horizon. CAGRs derive from corridor-specific freight flow projections, permit quota expansion schedules, and manufacturing relocation patterns from coastal China. Industry-specific inputs include ASEAN Single Window implementation timelines and temperature-controlled trailer fleet deployment rates.
Inputs from customs authorities and logistics operators were available through the study window; gaps in informal cross-border traffic data introduce uncertainty bands around Myanmar and Cambodia volume estimates. Forecasts reflect assumptions regarding ASEAN Customs Transit System ratification progress and manufacturing diversification continuity. A small set of triggers—including bilateral permit quota expansions, political stability shifts in Myanmar, and electronics sourcing pattern changes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Airfreight Forwarding Market
Logistics and Shipping
ASEAN Domestic Courier Market
Logistics and Shipping
Manufacturing Logistics Market
Logistics and Shipping
GCC Air Freight Transport Market
Logistics and Shipping
Thailand Courier Express Parcel (CEP) Market
Logistics and Shipping
United States Air Freight Market
Logistics and Shipping
Egypt Third Party Logistics (3PL) Market
Logistics and Shipping
Mexico Road Freight Transport Market
Logistics and Shipping
Texas Freight and Logistics Market
Logistics and Shipping
Europe Automotive Logistics Market
Logistics and Shipping
Germany Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
LAOS Freight and Logistics Market
Logistics and Shipping
United States Freight and Logistics Market
Logistics and Shipping
Hungary Third Party Logistics (3PL) Market
Logistics and Shipping
Japan Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Indonesia Courier, Express, and Parcel (CEP) Market