
 United Kingdom Domestic Courier, Express, and Parcel (CEP) Market | 2026-2036
United Kingdom Domestic Courier, Express, and Parcel (CEP) Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Domestic Courier, Express, and Parcel (CEP) Market Insights
Clean Air Zone legislation is decoupling diesel fleet access from central business district coverage across Birmingham, Bristol, and London. International Distribution Services PLC leverages its universal service obligation infrastructure to sustain six-day weekly delivery to every UK postcode. Evri Ltd. competes through dense parcel shop networks that anchor suburban and rural last-mile reach. DHL Group differentiates via integrated supply chain control spanning domestic express, freight, and contract logistics operations.
United Kingdom Domestic Courier, Express, and Parcel services constitute time-definite and non-time-definite logistics operations involving collection, sortation, line-haul transport, and final delivery of items typically weighing under 30 kilograms, with express variants guaranteeing delivery within 24 hours through dedicated air and road networks. The primary commercial purpose centers on enabling business-to-consumer, business-to-business, and consumer-to-consumer exchange of goods with verifiable chain-of-custody documentation. Next-day delivery occupies the largest revenue pool among service types, reflecting consumer expectation calibration following pandemic-era habit formation. E-commerce platforms represent the fastest-expanding customer type, though margin compression intensifies as platform-negotiated rates commoditize standard delivery tiers. Locker service and drop-off point methods gain structural share as failed delivery costs and recipient absence rates erode pure home delivery economics.
Ofcom regulates postal market competition and safeguards universal service standards while the Department for Transport governs commercial vehicle operator licensing and emissions compliance timelines. The Health and Safety Executive shapes warehouse and driver welfare protocols that directly affect sortation automation investment and route scheduling algorithms. Stakeholders must monitor how the UK's evolving extended producer responsibility frameworks for packaging waste redistribute cost burdens across e-commerce platforms and their logistics partners, as this will determine whether captive delivery networks or third-party carriers capture incremental margin in high-volume parcel corridors.
Market Dynamics
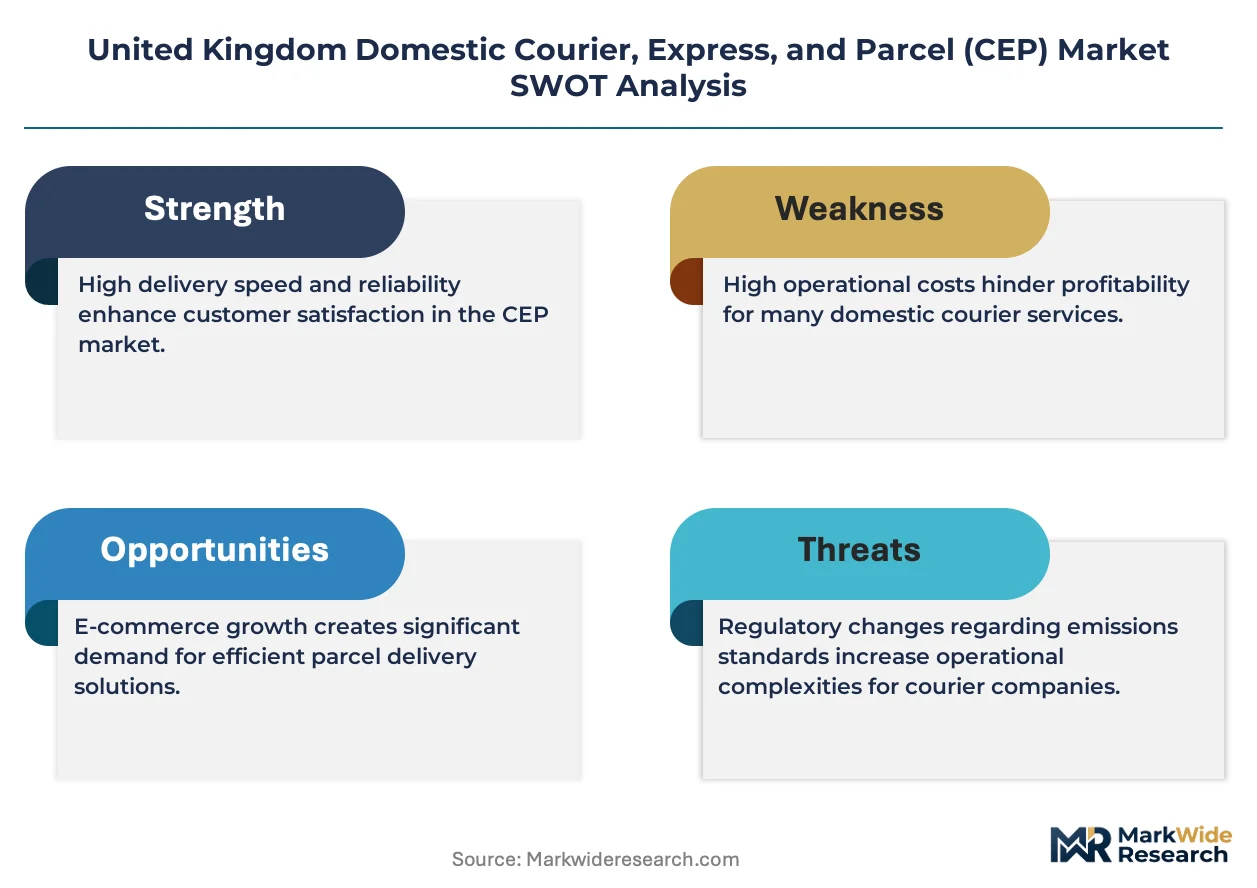
Clean Air Zone expansions across Birmingham, Bristol, and London are decoupling diesel fleet economics from central business district access, forcing carriers to reconstitute last-mile operations around electric vehicle infrastructure or forfeit premium delivery corridors.
Growth Catalysts
- E-commerce platform density:Online retail penetration deepens parcel volume throughput across Greater London and the South East corridor, creating economies of scale in last-mile sortation infrastructure.
- Extended Producer Responsibility frameworks:Packaging waste redistribution mandates under UK environmental law are pressuring e-commerce platforms to consolidate logistics partnerships around carriers with verified circular economy capabilities.
- Locker service proliferation:Failed delivery cost compression is accelerating parcel shop and automated locker deployment across suburban and rural postcodes, expanding addressable market reach without proportional fleet expansion.
Market Restraints
- Electric vehicle capex intensity:Fleet electrification requirements under Transport for London's Ultra Low Emission Zone demand capital deployment that compresses operating margins for mid-tier carriers without captive financing.
- Sortation hub concentration:Automated parcel processing capacity concentrates in the Midlands and South East, creating single-point-of-failure risk for national network resilience during peak volume periods.
- Driver availability compression:Warehouse and logistics operator licensing requirements governed by the Department for Transport restrict labor pool elasticity during seasonal demand surges.
Strategic Opportunities
- Net-zero fleet transition incentives:UK government grants for commercial electric vehicle adoption create first-mover advantage windows for carriers retrofitting diesel-dependent line-haul routes.
- Reverse logistics integration:E-commerce return volume growth enables margin capture through dedicated collection network density, particularly in fashion and electronics verticals.
- Scottish and Northern English corridor expansion:Underpenetrated next-day delivery coverage outside the South East presents white space for carriers with sufficient sortation automation to offset distance-based cost premiums.
Industry Challenges
- Automated sortation integration:Legacy warehouse management systems require substantial reconfiguration to interface with robotic parcel handling equipment, delaying throughput gains.
- Health and Safety Executive compliance:Warehouse welfare protocols and driver scheduling algorithms must balance automation investment against manual handling risk mitigation requirements.
- Cross-carrier interoperability:Parcel shop network fragmentation across competing drop-off point operators complicates unified tracking and customer experience standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Domestic Courier, Express, and Parcel (CEP) Market |
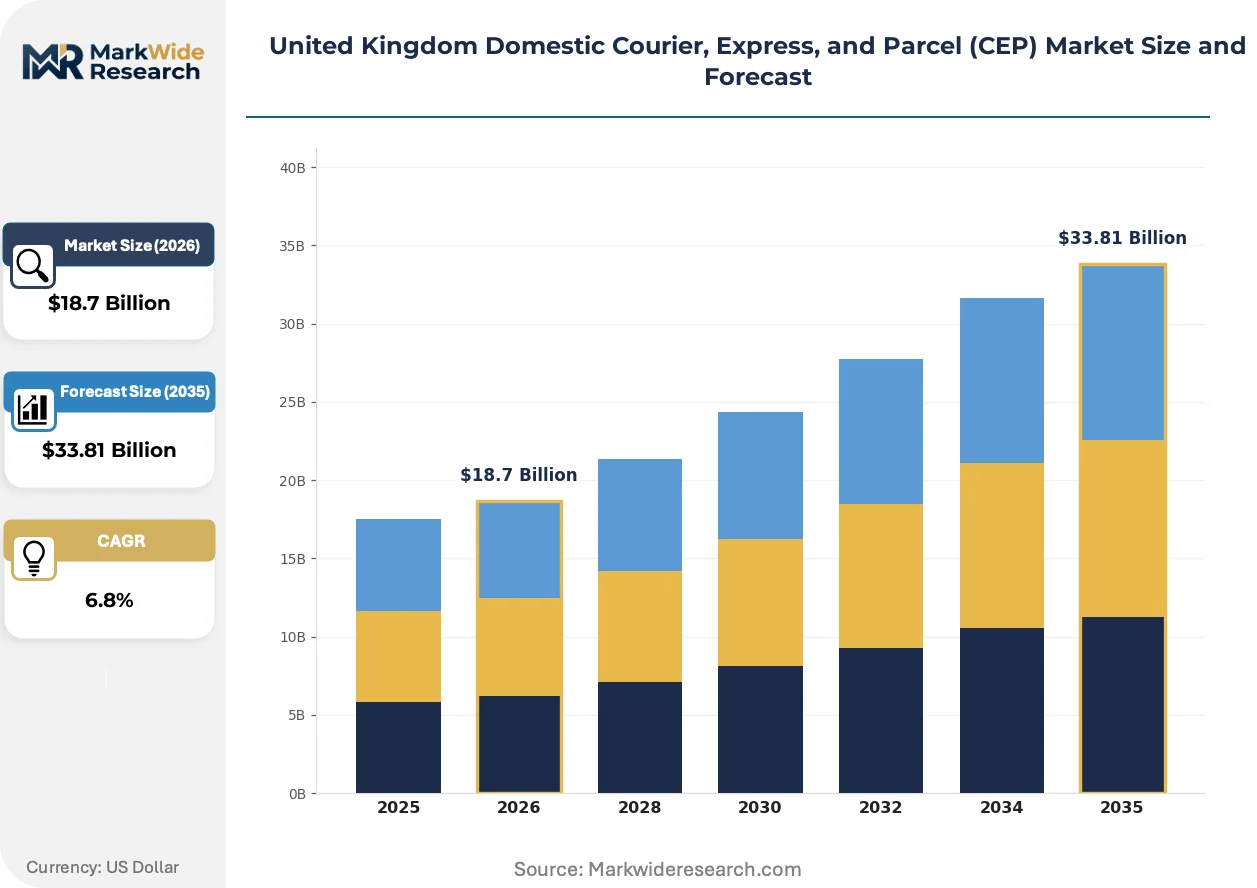
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Same-Day Delivery, Next-Day Delivery, Standard Delivery, Scheduled Delivery Package Size: Small Parcel, Medium Parcel, Large Parcel, Oversized Item Delivery Method: Contactless Delivery, Locker Service, Home Delivery, Drop-Off Point Customer Type: Individual Consumers, Small Businesses, Large Enterprises, E-commerce Platforms |
| Companies Covered | International Distribution Services PLC (Royal Mail), Evri Ltd., DHL Group, La Poste Group (DPD Group), United Parcel Service of America, Inc. (UPS), FedEx Corporation, Yodel, Otto Group (Hermes Group), InPost, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Domestic Courier, Express, and Parcel (CEP) Market Trends and Innovations
Operational technology deployment is absorbing capital and attention across UK domestic CEP operations as carriers compete on delivery certainty rather than speed alone. Three developments are restructuring competitive positioning.
Dynamic route optimization software is absorbing planning functions previously executed by dispatch supervisors, compressing delivery cost per stop through real-time traffic and recipient availability integration. Mid-market carriers lacking proprietary algorithm development are licensing third-party platforms to avoid capability gaps. This technology diffusion is absorbing margin pressure from commoditized standard delivery tiers by preserving service reliability at lower operating cost.
The Department for Transport's commercial vehicle emissions compliance timelines are accelerating zero-emission van deployment mandates across urban delivery zones. Fleet operators face permit access restrictions in Clean Air Zones without demonstrated electrification progress. Birmingham and Bristol implementations are following London's Ultra Low Emission Zone precedent, forcing nationwide network reconfiguration around electric vehicle range constraints and charging infrastructure placement.
Buyer concentration among e-commerce platforms is compressing carrier negotiating leverage and unbundling delivery service components into separately contracted elements. Platform-negotiated rates commoditize standard tiers while premium service levels retain pricing power. This procurement evolution is most visible in fashion and electronics verticals where return logistics complexity creates carrier differentiation opportunities beyond pure cost competition.
United Kingdom Domestic Courier, Express, and Parcel (CEP) Market Segmentation
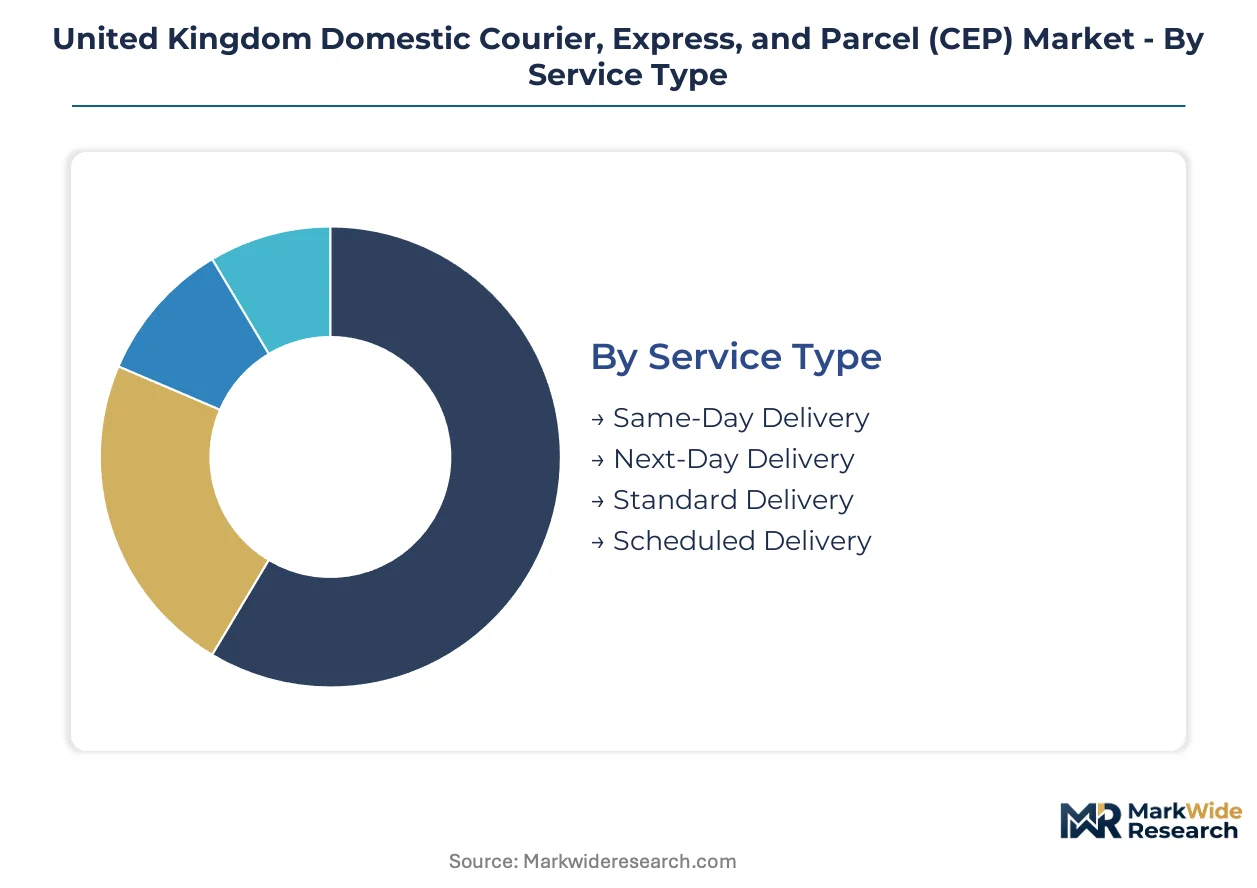
Carrier profitability across the United Kingdom Domestic Courier, Express, and Parcel (CEP) Market hinges on precise segment targeting. Service tier selection, parcel size economics, delivery method infrastructure, and customer concentration each dictate capital deployment and margin capture differently.
Service Type:
Customization intensity spans from rigid time-definite guarantees to flexible cost-optimized windows across this category.
- Next-Day Delivery:Time-definite guarantees within 24 hours rely on dedicated air and road networks with late cut-off times. E-commerce platforms in Greater London and the South East corridor drive volume concentration, though platform-negotiated rates compress margins on standard tiers.
- Same-Day Delivery:Ultra-rapid fulfillment within hours demands hyperlocal micro-fulfillment nodes and dynamic route optimization. Premium pricing power persists in central business districts where congestion pricing and Clean Air Zone access restrict competitor entry.
- Standard Delivery:Non-time-definite service windows of two to five days optimize line-haul density over speed. Cost-sensitive individual consumers and small businesses anchor demand, with failed delivery costs driving locker service adoption as an alternative.
- Scheduled Delivery:Appointment-based windows with recipient-specified time slots reduce redelivery attempts. Large enterprises with predictable inbound logistics requirements sustain this tier despite higher operational coordination costs.
Most installed capacity flows through Next-Day Delivery. Expansion is steepest in Same-Day Delivery.
Package Size:
Handling equipment and vehicle configuration requirements create distinct cost tier boundaries across parcel dimensions.
- Small Parcel:Items under 2 kilograms dominate automated sortation throughput and maximize van cube utilization. E-commerce Platforms generate the densest volume flows, particularly in fashion and electronics verticals where return logistics integration creates margin opportunities.
- Medium Parcel:Standard carton dimensions between 2 and 10 kilograms balance manual and automated handling. Suburban and rural last-mile density constraints elevate per-stop costs compared to small parcel economics.
- Large Parcel:Bulky items requiring two-person handling or tail-lift vehicles. Home Delivery methods face higher failure rates due to recipient availability mismatches.
- Oversized Item:Freight-adjacent dimensions exceeding standard parcel network specifications. Specialized fleet assets and appointment scheduling separate this tier from mainstream CEP operations.
Volume concentrates in Small Parcel. Value capture is climbing fastest in Large Parcel due to service differentiation premiums.
Delivery Method:
Recipient presence requirements and infrastructure capital intensity define the margin structure across fulfillment modalities.
- Home Delivery:Doorstep fulfillment remains the default expectation for Individual Consumers despite failed delivery cost erosion. First-attempt success rates in dense urban corridors exceed suburban and rural performance significantly.
- Locker Service:Automated parcel terminals enable 24/7 collection without recipient presence. Transport for London's Ultra Low Emission Zone compliance pressures accelerate deployment as electric van range constraints favor consolidated drop points.
- Drop-Off Point:Retail-hosted parcel shops extend network reach without dedicated fleet expansion. Evri Ltd.'s dense suburban and rural networks demonstrate this method's scalability outside premium corridors.
- Contactless Delivery:Pandemic-era protocols now standardize as default safe-drop procedures. Residential property security and liability concerns limit commercial adoption.
Network investment prioritizes Home Delivery. Structural share is gaining fastest in Locker Service.
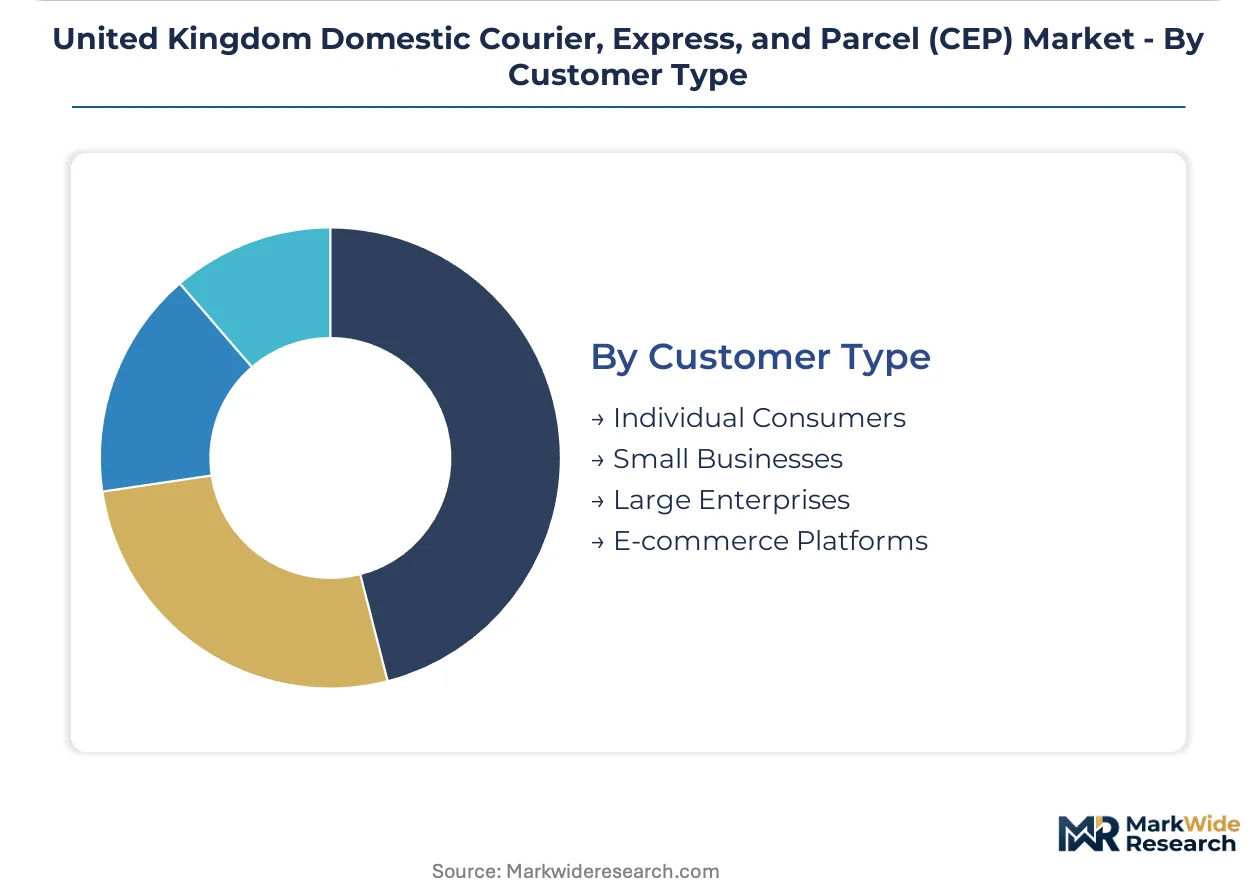
Customer Type:
Procurement sophistication and volume concentration separate enterprise-grade contract negotiation from transactional shipment economics.
- E-commerce Platforms:Aggregated demand from online retail marketplaces commands rate leverage and unbundles service components. Extended Producer Responsibility frameworks for packaging waste pressure consolidation around carriers with verified circular economy capabilities.
- Large Enterprises:Dedicated contract logistics relationships spanning domestic express, freight, and warehousing. DHL Group's integrated supply chain control exemplifies the service bundling these customers require.
- Small Businesses:Fragmented demand with limited negotiating power and higher per-shipment costs. Drop-Off Point methods reduce access barriers for this segment.
- Individual Consumers:Occasional sender behavior with price sensitivity and convenience expectations. International Distribution Services PLC's universal service obligation infrastructure reaches this segment through six-day weekly coverage.
Revenue concentration sits with E-commerce Platforms. Account growth is strongest among Small Businesses adopting platform-integrated shipping tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Driver availability concentrates in Greater London and the South East corridor, where last-mile density and congestion pricing create premium service tiers. The Midlands anchors automated sortation infrastructure. Northern England and Scotland present underpenetrated next-day delivery coverage.
London and the South East
E-commerce platform density drives parcel volume throughput across Greater London and the South East corridor. Transport for London's Ultra Low Emission Zone compliance pressures accelerate electric van deployment mandates. Heathrow and Gatwick logistics clusters concentrate express air freight operations alongside dedicated road networks.
Midlands
Automated parcel processing capacity concentrates in the Midlands, creating economies of scale in national sortation infrastructure. The Department for Transport governs commercial vehicle operator licensing affecting warehouse and driver welfare protocols. Birmingham's Clean Air Zone implementation forces carriers to reconstitute last-mile operations around electric vehicle infrastructure.
North England
Underpenetrated next-day delivery coverage outside the South East presents expansion opportunities for carriers with sufficient automation. Extended Producer Responsibility frameworks for packaging waste pressure logistics partnership consolidation. Manchester and Leeds logistics corridors develop as alternative hubs to Midlands concentration.
Scotland
Distance-based cost premiums challenge parcel economics in Scottish corridors without automated sortation scale. The Health and Safety Executive shapes warehouse welfare protocols affecting route scheduling algorithms. Edinburgh and Glasgow metropolitan zones concentrate demand while Highland and Island postcodes rely on universal service obligation coverage.
Wales
Suburban and rural last-mile density constraints elevate per-stop costs compared to English corridors. Clean Air Zone expansions in Bristol affect cross-border logistics operations from South Wales. Cardiff and Swansea logistics nodes serve as distribution gateways for Welsh market coverage.
United Kingdom Domestic Courier, Express, and Parcel (CEP) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered service segments. The market structure consolidates around integrated supply chain operators, dense parcel shop networks, and universal service obligation infrastructure. Three strategic archetypes dominate: integrated logistics conglomerates, low-cost last-mile specialists, and incumbent postal operators with regulatory obligations. Competitive moves center on fleet electrification investments and locker service network expansion.
Within the incumbent postal tier, International Distribution Services PLC exemplifies universal service obligation infrastructure sustaining six-day weekly delivery coverage. Among low-cost last-mile specialists, Evri Ltd. occupies a position anchored by dense suburban and rural parcel shop networks. On the integrated logistics vector, DHL Group represents supply chain control spanning domestic express, freight, and contract logistics operations.
| Leading Market Players |
|---|
| International Distribution Services PLC (Royal Mail) |
| Evri Ltd. |
| DHL Group |
| La Poste Group (DPD Group) |
| United Parcel Service of America, Inc. (UPS) |
| FedEx Corporation |
| Yodel |
| Otto Group (Hermes Group) |
| InPost |
| Others |
Pricing and Supply Chain Analysis
Diesel futures volatility cascading through fleet operating costs is bifurcating carrier economics between electrified premium corridors and diesel-dependent standard tiers across the United Kingdom Domestic Courier, Express, and Parcel market. Transport for London's Ultra Low Emission Zone compliance penalties now embed directly into service pricing, compressing margins on unbundled standard delivery while preserving premium tier profitability.
Pricing Analysis
Bundled-versus-unbundled service splits now dominate procurement negotiations between e-commerce platforms and carriers. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery certainty and emissions compliance status rather than speed alone. Price differentiation stems from Clean Air Zone permit access and verified circular economy certification under Extended Producer Responsibility frameworks. Cost compression in standard tiers is intensifying because platform-negotiated rates commoditize basic delivery, while premium service levels retain pricing power through guaranteed time-definite windows. Small Businesses exhibit highest price sensitivity due to fragmented volume, whereas Large Enterprises accept premium pricing for integrated supply chain control.
Supply Chain Analysis
Logistics cost pressures from line-haul electrification and last-mile congestion pricing are reshaping network configuration priorities. Supply concentration centers on the Midlands for automated sortation infrastructure, Greater London for express air freight clusters at Heathrow and Gatwick, and the South East corridor for e-commerce fulfillment density. Raw material dependencies include electric vehicle battery supply, automated sortation equipment, and charging infrastructure components. Single-source vulnerability concentrates in Midlands-based automated processing capacity during peak volume periods. Distribution runs through hub-and-spoke configurations anchored by regional sortation facilities with micro-fulfillment nodes penetrating urban last-mile corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential in United Kingdom Domestic Courier, Express, and Parcel operations rests on electric vehicle transition cost curves flattening and premium service tier demand deepening. Fleet electrification grants and locker service infrastructure deployment represent the primary levers for sustainable profitability improvement.
For Market Incumbents: Deepen electric vehicle fleet penetration ahead of Clean Air Zone expansions in Birmingham and Bristol to preserve central business district access. Secure charging infrastructure partnerships along line-haul corridors to offset range constraints. Vertical integration into reverse logistics networks captures margin from e-commerce return volume growth in fashion and electronics verticals. Lock in platform-negotiated rate structures before mid-tier carriers achieve comparable electrification scale. For New Entrants and Emerging Players: Parcel shop network operators represent the most accessible channel partnership for rapid suburban and rural coverage expansion. White space exists in Scottish next-day delivery corridors where distance-based cost premiums deter incumbent automation investment. Northern English metropolitan zones outside Manchester and Leeds logistics clusters offer underpenetrated scheduled delivery opportunities for appointment-based service tiers. Target Small Businesses through platform-integrated shipping tools that reduce access barriers against established carrier relationships. For Investors and Strategic Acquirers: Asymmetric upside sits with carriers possessing verified circular economy capabilities under Extended Producer Responsibility frameworks. Long-term viability favors operators with captive electric vehicle financing and proprietary dynamic route optimization algorithms. Acquisition targets should demonstrate locker service network density or micro-fulfillment node penetration in Clean Air Zone corridors. Watch for inflection signals in government grant program exhaustion dates that would accelerate competitive consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Fleet Electrification Acceleration | Transport for London's Ultra Low Emission Zone mandates preserve premium corridor access for compliant carriers. |
| Locker Service Network Expansion | Automated parcel terminals reduce failed delivery costs and extend reach without proportional fleet growth. |
| Reverse Logistics Integration | Dedicated collection density captures margin from e-commerce return volume in fashion and electronics verticals. |
| Dynamic Route Optimization Deployment | Real-time traffic and recipient availability integration compresses delivery cost per stop for mid-market carriers. |
| Scottish Corridor Automation Investment | Sortation scale offsets distance-based cost premiums in underpenetrated next-day delivery coverage zones. |
Research Methodology
Direct dialogue with fleet operations directors, e-commerce logistics procurement managers, warehouse automation engineers, and Clean Air Zone compliance officers grounded qualitative insights for this analysis. Secondary validation drew from Department for Transport commercial vehicle licensing records, Transport for London emissions compliance disclosures, Ofcom postal market reports, Health and Safety Executive warehouse welfare protocols, and Extended Producer Responsibility framework documentation. Bottom-up volume modeling triangulated against top-down market sizing from carrier revenue disclosures and e-commerce platform fulfillment data.
Bottom-up segmentation analysis tracked service type, parcel size tier, delivery method, and customer concentration across the projection horizon. Modeled dimensions included time-definite guarantee levels, automated sortation throughput capacity, electric vehicle range constraints, and recipient presence requirements. CAGRs derived from volume trajectory analysis against infrastructure capacity expansion timelines and regulatory compliance phase-in schedules. Forecast inputs incorporated Clean Air Zone expansion calendars, government grant program allocations, and e-commerce penetration rate assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electric vehicle battery supply constraints, government subsidy program continuity, and platform buyer concentration dynamics. Forecasts reflect documented assumptions about regulatory compliance timelines and technology cost curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Cargo Shipping Market
Logistics and Shipping
Latin America Freight Forwarding Market
Logistics and Shipping
IoT Spend by Logistics Industry Market
Logistics and Shipping
North America Pharmaceutical Logistics Market
Logistics and Shipping
Germany Freight and Logistics Market
Logistics and Shipping
WAN Connected Returnable Transport Asset Tracking Market
Logistics and Shipping
Asia Pacific Sea Freight Forwarding Market
Logistics and Shipping
GCC Air Freight and Logistics Market
Logistics and Shipping
Japan Contract Logistics Market
Logistics and Shipping
Asean Freight and Logistics Market
Logistics and Shipping
Kazakhstan Freight and Logistics Market
Logistics and Shipping
GCC Freight and Logistics Market
Logistics and Shipping
Thailand E-Commerce Logistics Market
Logistics and Shipping
Straddle Carrier Market
Logistics and Shipping
LAMEA Last Mile Delivery Market
Logistics and Shipping
Armenia Freight and Logistics Market