
 Asia-Pacific Ride on Bikes Market | 2026-2036
Asia-Pacific Ride on Bikes Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Ride on Bikes Market Insights
Capital-intensity divergence between integrated battery producers and frame-assemblers is redrawing competitive boundaries across the Asia-Pacific ride on bikes landscape. Giant Manufacturing Co., Ltd. leverages in-house carbon fiber fabrication and proprietary frame geometries to command premium positioning in performance segments. Yadea Group Holdings Ltd. anchors its cost structure through captive lithium-ion cell production at scale in Jiangsu province. AIMA Technology Group Co., Ltd. competes through dense distributor networks penetrating county-level markets throughout central and western China.
Ride on bikes encompass human-powered and electric-assisted two-wheeled vehicles designed for recreational, commuter, and light commercial transport, with electric variants typically integrating hub motors rated between 250W and 750W and lithium-ion battery packs ranging from 36V to 48V configurations. Electric bikes now lead volume shipments as municipal congestion charges and fuel taxation across Asia-Pacific cities elevate total cost of ownership for internal combustion alternatives. The children and teenagers consumer age group represents the fastest-expanding demographic as parents prioritize outdoor activity equipment and schools expand cycling safety curricula. Specialty stores retain margin concentration through test-ride experiences and aftermarket service attachment, while online retail captures volume growth in replacement parts and accessories.
China's SAMR enforces compulsory GB 17761 certification for e-bike speed and braking performance, while India's BIS mandates IS 17017 standards for lithium-ion traction batteries used in electric two-wheelers. Japan's METI administers subsidy programs under its Green Growth Strategy that reduce consumer acquisition costs for domestically certified electric bicycles. Stakeholders must monitor evolving subsidy phase-out schedules and battery recycling mandates across multiple Asia-Pacific jurisdictions to calibrate production planning and pricing architecture.
Market Dynamics
China's SAMR enforcement of GB 17761 certification is compressing supplier margins while accelerating consolidation among frame-assemblers unable to fund in-house battery testing labs. This regulatory pressure is redrawing competitive boundaries between integrated producers and component-dependent assemblers across Southeast Asian supply chains.
Growth Catalysts
- India's PLI scheme for e-mobility:Production-linked incentives for domestic lithium-ion cell manufacturing are reducing import dependency and lowering landed costs for electric two-wheeler assemblers in Gujarat and Tamil Nadu.
- Japan's METI Green Growth subsidies:Consumer rebate programs for domestically certified electric bicycles are accelerating replacement cycles in Tokyo and Osaka metropolitan areas.
- Last-mile logistics electrification:Food delivery platforms across Bangkok, Jakarta, and Ho Chi Minh City are mandating fleet transitions to electric mopeds under corporate net-zero commitments.
Market Restraints
- Lithium carbonate price volatility:Raw material cost swings between Australian and Chilean supply sources are destabilizing cell procurement budgets for mid-tier assemblers.
- Jiangsu cell production concentration:Overreliance on a single Chinese province for lithium-ion output creates geographic vulnerability to regional power rationing or logistics disruptions.
- IS 17017 certification timelines:India's BIS battery testing protocols impose extended approval windows that delay product launches by six to nine months.
Strategic Opportunities
- Vietnam's tier-2 urban corridors:Da Nang and Can Tho exhibit underpenetrated e-bike adoption relative to Hanoi and Ho Chi Minh City, with rising disposable incomes and incomplete public transit coverage.
- Battery-swapping infrastructure:Interoperable swap station networks are emerging as an alternative ownership model for commercial fleet operators seeking to eliminate charging downtime.
- Indonesia's nickel processing integration:Downstream cathode material production from domestic laterite reserves offers cost advantages for regional cell suppliers serving ASEAN markets.
Industry Challenges
- Power electronics engineering scarcity:Shortages of motor controller firmware developers are extending R&D cycles for torque-mapping and regenerative braking optimization.
- Multi-jurisdiction recycling compliance:Divergent end-of-life battery handling rules across China, India, and Japan are forcing parallel logistics systems and raising operational complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Ride on Bikes Market |
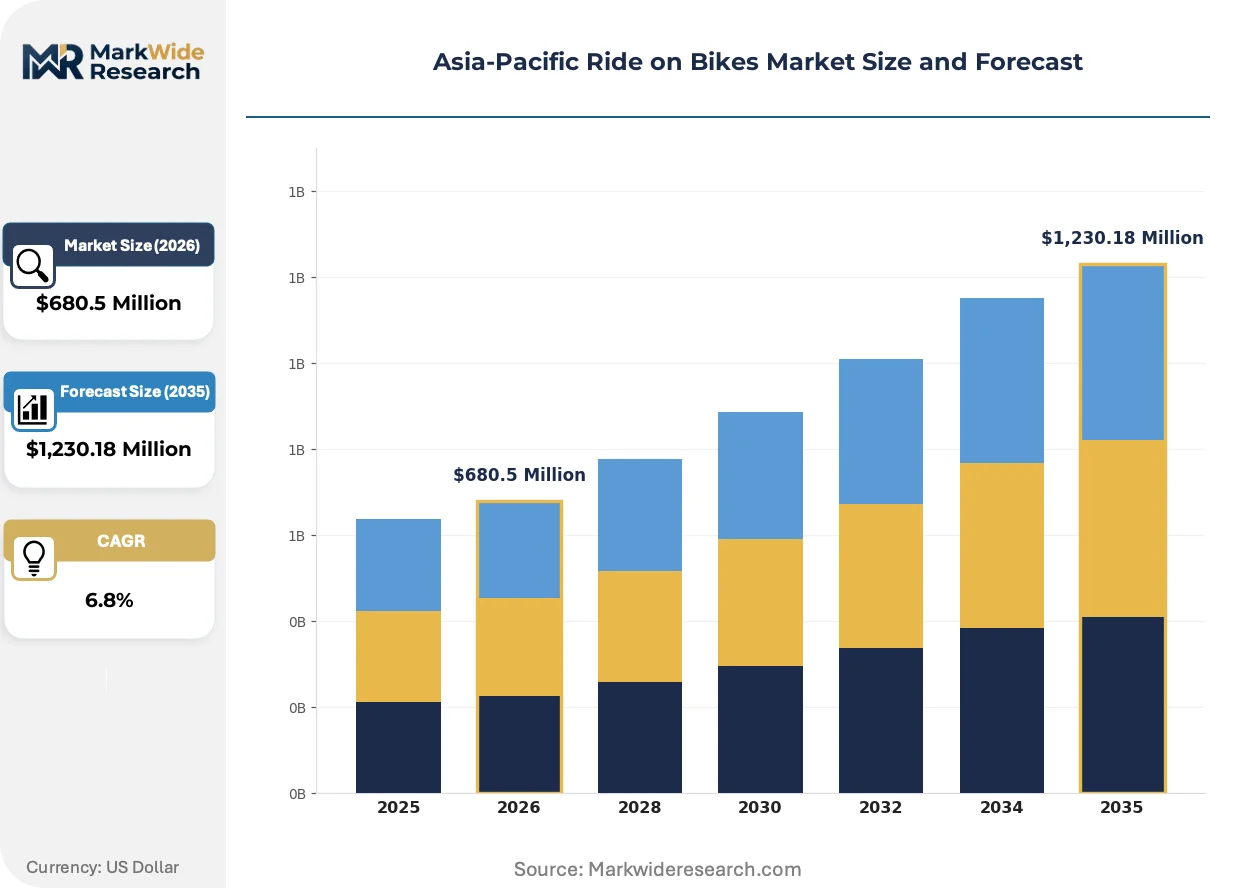
| Market Size in 2026 | $680.5 Million |
| Market Size in 2035 | $1,230.18 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Bikes, Traditional Bikes, Hybrid Bikes, Mountain Bikes Consumer Age Group: Children, Teenagers, Adults, Seniors Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales Price Range: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Giant Manufacturing Co., Ltd., Yadea Group Holdings Ltd., AIMA Technology Group Co., Ltd., Yamaha Motor Co., Ltd., Merida Industry Co., Ltd., NIU Technologies, Shenzhen TAILG Technology Group Co., Ltd., Panasonic Corporation, Jiangsu Xinri E-Vehicle Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Ride on Bikes Market Trends and Innovations
Solid-state battery chemistry and AI-enabled motor control systems are converging to redefine performance benchmarks across the Asia-Pacific electric two-wheeler segment. These advances are compressing product lifecycles and forcing incumbent suppliers into accelerated R&D commitments.
Silicon-anode lithium-ion cells are fragmenting the mid-range powertrain segment. These energy-dense configurations extend single-charge range by thirty to forty percent versus conventional graphite anodes. Premium commuter brands in South Korea and Japan are integrating silicon-anode packs for urban professionals with intercity travel requirements. The technology is fragmenting supplier tiers by creating a performance gap between early adopters with cell partnerships and legacy assemblers dependent on commodity cylindrical formats.
China's GB 42295 standard for lithium-ion battery safety in electric bicycles mandates thermal runaway propagation testing and automated fire suppression systems. The regulation is eliminating uncertified cell suppliers from the procurement base of major frame manufacturers. Exporters to the Chinese market must now maintain dual certification tracks for domestic and international product variants, raising compliance overhead.
Fleet operators across Singapore and Sydney are unbundling after-sales service from hardware procurement, contracting third-party maintenance networks for predictive diagnostics and battery health monitoring. This decoupling is displacing traditional dealer service revenue models. Specialty retailers in Melbourne and Auckland are responding with subscription-based maintenance packages to retain customer relationships.
Asia-Pacific Ride on Bikes Market Segmentation
Regulatory fragmentation across Asia-Pacific jurisdictions forces suppliers to maintain parallel product lines with distinct certification tracks. Segmentation strategies must align with divergent safety mandates from China's SAMR, India's BIS, and Japan's METI to avoid compliance-driven margin erosion.
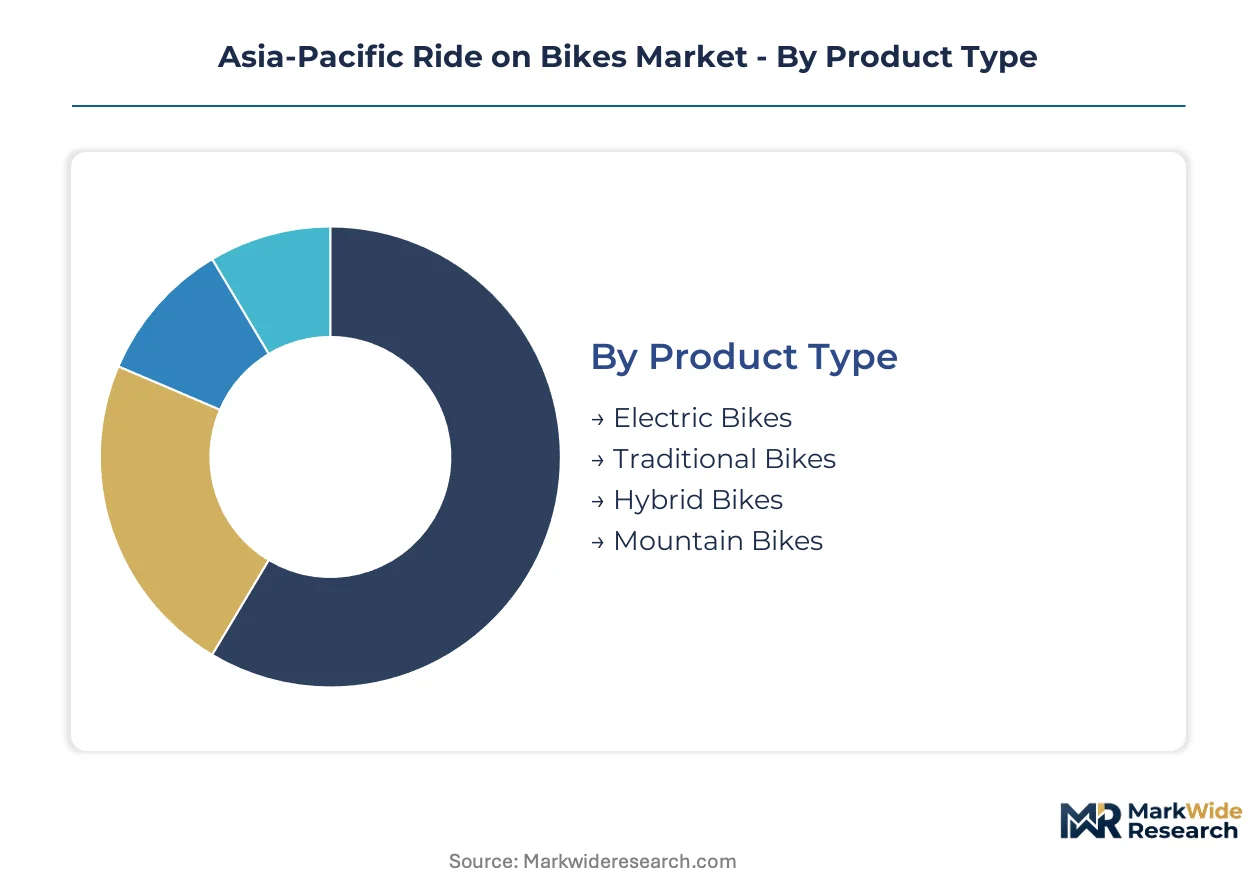
Product Type:
China's GB 17761 and GB 42295 standards impose divergent technical requirements on electric versus human-powered variants, reshaping supplier specialization.
- Electric Bikes:Hub motors rated 250W–750W paired with 36V–48V lithium-ion configurations dominate urban fleet procurement. Food delivery platforms in Bangkok, Jakarta, and Ho Chi Minh City mandate electrified mopeds under corporate net-zero commitments, compressing replacement cycles.
- Traditional Bikes:Human-powered frames with steel or aluminum construction retain volume leadership in India's tier-2 cities where municipal e-mobility incentives have not yet penetrated. Rising fuel costs push consumer switching toward non-motorized commuter options in Gujarat and Tamil Nadu.
- Hybrid Bikes:Dual-mode systems blending pedal power with light electric assist target suburban commuters in Tokyo and Osaka metropolitan areas receiving METI Green Growth subsidies.
- Mountain Bikes:Performance-oriented geometries with suspension systems concentrate in specialty retail channels across Melbourne and Auckland.
Electric bikes handle the majority of throughput; hybrid bikes are expanding most quickly on share.
Consumer Age Group:
Application intensity varies sharply across life stages, with safety curricula and outdoor activity priorities driving differential equipment specifications.
- Children:Smaller wheel diameters and training-wheel-compatible frames align with school cycling safety programs expanding across Southeast Asian education systems. Parents prioritize outdoor activity equipment as post-pandemic health awareness elevates.
- Teenagers:Style-conscious designs with connectivity features gain traction in South Korean and Japanese urban centers. This demographic shows the steepest expansion trajectory as disposable income thresholds for independent mobility decline.
- Adults:Commuter-optimized geometries with cargo capacity dominate last-mile logistics electrification and daily transport substitution.
- Seniors:Step-through frames with stability enhancements address aging populations in Japan and South Korea seeking low-impact mobility solutions.
Adults generate the highest absolute unit volumes; teenagers are climbing the fastest on segment share.
Distribution Channel:
Margin capture diverges between experience-driven physical retail and efficiency-focused digital fulfillment.
- Specialty Stores:Test-ride experiences and aftermarket service attachment retain margin concentration. Predictive diagnostics and battery health monitoring subscriptions in Singapore and Sydney displace traditional dealer revenue models.
- Online Retail:Volume growth concentrates in replacement parts and accessories where specification clarity reduces purchase risk. Platform logistics networks penetrate county-level markets throughout central and western China.
- Supermarkets:Mass-market positioning for entry-level traditional bikes targets impulse purchases in India's tier-2 urban corridors.
- Direct Sales:Manufacturer-owned channels bypass distributor markups for fleet operators in Indonesia and Vietnam seeking volume procurement efficiency.
Specialty stores command the highest margin per unit; online retail is gaining share fastest on transaction velocity.
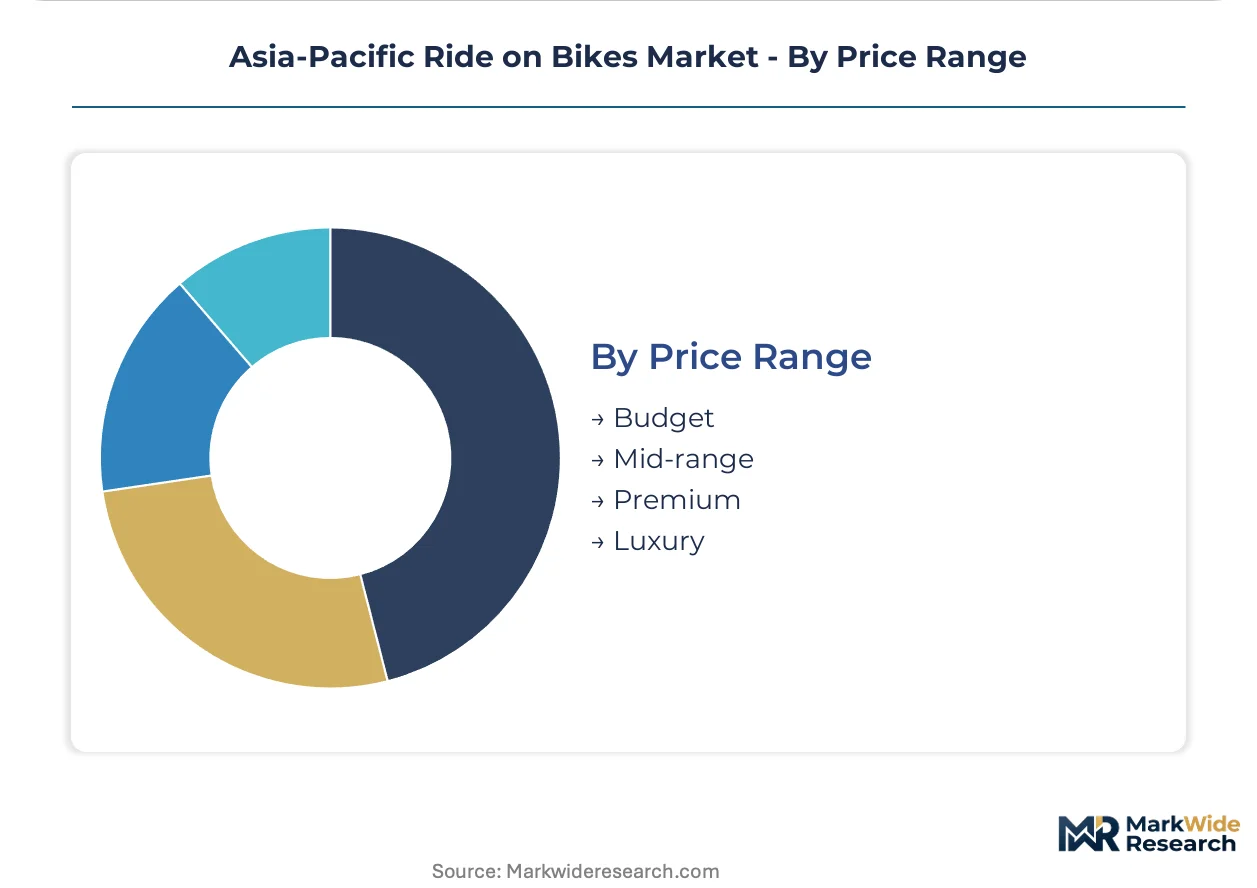
Price Range:
Cost tier stratification maps directly to battery chemistry grade and frame material selection.
- Premium:Silicon-anode lithium-ion cells extending single-charge range by thirty to forty percent versus conventional graphite anodes. South Korean and Japanese commuter brands target urban professionals with intercity travel requirements.
- Mid-range:Commodity cylindrical cell formats and aluminum frame construction balance performance with accessibility. This tier captures the broadest geographic penetration across Da Nang and Can Tho in Vietnam.
- Budget:Lead-acid battery variants and steel frames retain position in price-sensitive Indian municipal markets.
- Luxury:Carbon fiber fabrication with proprietary geometries commands positioning in performance segments with in-house production capabilities.
Mid-range products move the highest unit volumes; premium tiers are expanding most quickly on value contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japanese and South Korean metropolitan markets where METI subsidies and premium commuter positioning sustain margin structures unavailable to mass-market producers in Vietnam and Indonesia. This asymmetry redistributes investment flows toward certification-heavy jurisdictions with subsidy durability.
China
GB 17761 and GB 42295 standards enforce thermal runaway testing and fire suppression mandates that eliminate uncertified cell suppliers from procurement bases. SAMR compliance costs compress margins for frame-assemblers lacking in-house battery labs. Production clusters in Jiangsu province concentrate lithium-ion output for regional supply chains.
Japan
METI Green Growth subsidies accelerate replacement cycles in Tokyo and Osaka metropolitan areas for domestically certified electric bicycles. Aging demographics drive step-through frame demand among seniors seeking low-impact mobility. Kanto region specialty retailers deploy subscription-based maintenance packages to retain customer relationships.
India
BIS IS 17017 certification timelines extend product launch windows by six to nine months for lithium-ion traction batteries. PLI scheme incentives for domestic cell manufacturing reduce import dependency in Gujarat and Tamil Nadu assembly operations. Tier-2 cities in these states exhibit rising fuel-cost-driven switching toward commuter-optimized geometries.
Vietnam
Da Nang and Can Tho corridors show underpenetrated e-bike adoption relative to Hanoi and Ho Chi Minh City with rising disposable incomes and incomplete public transit coverage. Food delivery platforms mandate fleet electrification under corporate net-zero commitments. Battery-swapping infrastructure emerges as an alternative ownership model for commercial operators.
South Korea
Silicon-anode lithium-ion cells extend single-charge range for urban professionals with intercity travel requirements in Seoul metropolitan area. MFDS-equivalent safety protocols and premium positioning sustain pricing power unavailable in ASEAN mass markets. Connectivity-featured designs gain traction among style-conscious teenagers in urban centers.
Asia-Pacific Ride on Bikes Market Competitive Landscape
Concentration sits with integrated battery producers and carbon fiber fabricators who control upstream cost structures and premium positioning vectors. The supplier base stratifies across three tiers: captive cell manufacturers with Jiangsu production bases, specialty retailers with predictive diagnostics capabilities, and mass-market assemblers dependent on commodity cylindrical formats. Dominant competitive moves include backward integration into cathode material processing and geographic expansion through county-level distributor networks penetrating central and western China.
Within the integrated producer tier, Giant Manufacturing Co., Ltd. and Yadea Group Holdings Ltd. exemplify divergent specialization paths—frame fabrication with proprietary geometries versus captive lithium-ion cell production at scale. AIMA Technology Group Co., Ltd. occupies a position emphasizing dense distribution penetration. These three entities represent the primary competitive archetypes: premium performance positioning, cost-anchored scale operations, and network-driven market access.
| Leading Market Players |
|---|
| Giant Manufacturing Co., Ltd. |
| Yadea Group Holdings Ltd. |
| AIMA Technology Group Co., Ltd. |
| Yamaha Motor Co., Ltd. |
| Merida Industry Co., Ltd. |
| NIU Technologies |
| Shenzhen TAILG Technology Group Co., Ltd. |
| Panasonic Corporation |
| Jiangsu Xinri E-Vehicle Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Jiangsu province's lithium-ion cell production at scale anchors cost structures across the Asia-Pacific ride on bikes landscape, compressing price floors for frame-assemblers while elevating margin capture for integrated producers with captive supply. This concentration simultaneously enables volume-tier pricing for fleet procurement and forces component-dependent assemblers into thinner margin bands.
Pricing Analysis
Configured-to-order pricing for silicon-anode battery packs commands a thirty-to-forty percent premium over standard graphite-anode configurations in South Korean and Japanese commuter segments. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling, with METI-subsidized domestic certification in Japan sustaining the widest premium spreads. Cost compression in mid-range tiers is intensifying because lithium carbonate volatility destabilizes cell procurement budgets. Fleet operators exhibit the lowest price sensitivity due to total-cost-of-ownership calculations, while India's tier-2 municipal markets show acute sensitivity to upfront acquisition costs.
Supply Chain Analysis
Strategic stockpile preferences dominate lithium-ion procurement as assemblers buffer against Jiangsu power-rationing risks and Australian-Chilean raw material volatility. Supply concentrates in China for cell production, Indonesia for nickel laterite processing, and South Korea for cathode material refinement. Raw material dependencies center on lithium carbonate from Australian hard-rock and Chilean brine operations, nickel laterite from Indonesian reserves, and rare earth elements for motor magnets. Single-source vulnerability to Jiangsu province concentration creates geographic risk exposure. Distribution runs through specialty retail channels for test-ride conversion in Tokyo and Osaka, while online platform logistics penetrate county-level markets throughout central and western China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific ride on bikes market expansion represents high-growth disruption as solid-state battery chemistry and AI-enabled motor control systems compress product lifecycles and force accelerated R&D commitments across incumbent supplier bases.
For Market Incumbents: Shield margin structures by deepening backward integration into cathode material processing and securing dual GB 17761 and IS 17017 certification tracks ahead of subsidy phase-out schedules. Battery testing lab investments defend against SAMR enforcement eliminating uncertified cell suppliers from procurement bases. Geographic capacity expansion in Gujarat and Tamil Nadu leverages India's PLI scheme to reduce import dependency exposure.
For New Entrants and Emerging Players: Differentiate on battery-swapping infrastructure ownership models targeting commercial fleet operators in Da Nang and Can Tho corridors where public transit gaps and rising disposable incomes converge. Vietnam's tier-2 urban markets offer the most penetrable white-space for electrified moped adoption under food delivery platform mandates. Direct sales channels bypassing distributor markups provide the optimal go-to-market angle for volume procurement efficiency.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty retailers with predictive diagnostics subscriptions and battery health monitoring capabilities in Singapore and Sydney metropolitan areas. Long-term viability over the projection horizon favors integrated producers with Jiangsu cell production bases and proprietary frame geometries. Acquisition targets should demonstrate county-level distribution penetration throughout central and western China. The signal to watch is METI subsidy phase-out velocity as an inflection indicator for Japanese market pricing power erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Processing | Indonesian nickel laterite refining captures cost advantages for ASEAN regional cell supply. |
| Dual Certification Track Investment | Parallel GB 17761 and IS 17017 compliance opens simultaneous access to China and India procurement pools. |
| Battery-Swapping Infrastructure Deployment | Interoperable station networks eliminate charging downtime for Bangkok and Ho Chi Minh City fleet operators. |
| County-Level Distribution Expansion | AIMA Technology Group's dense network model demonstrates penetration depth throughout central and western China. |
| Predictive Diagnostics Subscription Launch | Melbourne and Auckland specialty retailers retain customer relationships against third-party maintenance unbundling. |
Research Methodology
The analysis maps electric bike, traditional bike, hybrid bike, and mountain bike sub-sectors, each validated through frame-assembler procurement directors, specialty retailer operations managers, fleet operator logistics heads, and lithium-ion cell supplier commercial leads. Primary interview intelligence triangulates against secondary validation from SAMR GB standard filings, BIS IS 17017 certification records, METI Green Growth subsidy disbursement data, and ASEAN customs trade flows. Bottom-up unit shipment modeling and top-down value aggregation ensure cross-verification across the analysis window.
Consistency-check validation against external benchmarks confirms output reliability across the projection horizon. The analytical framework segments by product type, consumer age group, distribution channel, and price range, with regional regulatory cluster as an additional dimension. CAGRs derive from regression analysis of historical shipment trajectories and elasticity-adjusted demand drivers. Forecast inputs incorporate lithium carbonate price index movements and municipal e-mobility incentive phase-out schedules.
Forecasts assume regulatory continuity in China's SAMR enforcement regimes, India's BIS certification protocols, and Japan's METI subsidy programs; material policy shifts would require re-modeling of supplier margin structures and replacement cycle timing. Revision becomes warranted when lithium carbonate volatility crosses threshold levels destabilizing cell procurement budgets or when battery-swapping infrastructure penetration accelerates beyond modeled adoption curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bikes and Motorcycles
Bike Taxi Market
Bikes and Motorcycles
Two-Wheeler Motorcycle Market
Bikes and Motorcycles
Motorcycle Advanced Rider Assistance System Market
Bikes and Motorcycles
Motorcycle Seat Market
Bikes and Motorcycles
Asia-Pacific Motorcycle Market
Bikes and Motorcycles
Motorcycle Drive Chain Market
Bikes and Motorcycles
Global Motorcycle Supercharger Market
Bikes and Motorcycles
Motorcycle Lighting Market
Bikes and Motorcycles
Switzerland E-Bike Market
Bikes and Motorcycles
Two Wheeler Handlebars Market
Bikes and Motorcycles
Motorcycle Exhaust Mounting Brackets Market
Bikes and Motorcycles
Global Motorcycle Airbag System Market
Bikes and Motorcycles
Global Motorcycle Market
Bikes and Motorcycles
Two Wheeler Kick Lever Market
Bikes and Motorcycles
Motorcycle Rider Assistance System Market
Bikes and Motorcycles
Asia-Pacific Two-Wheeler Taxi Market