
 Logistics Data Quality and Normalization Services Market | 2026-2036
Logistics Data Quality and Normalization Services Market Size, Share, and Industry Trends Forecast 2026-2036
Logistics Data Quality and Normalization Services Market Insights
The gap between premium AI-native data quality platforms and commodity cleansing tools is realigning procurement budgets across logistics enterprises. Informatica leverages deep integration with enterprise ERP stacks to dominate complex multi-source normalization projects. SAP anchors its position through embedded data services within its logistics execution suite. AWS competes on elastic compute pricing for high-velocity streaming data pipelines.
Logistics data quality and normalization services encompass automated cleansing, schema harmonization, and master data governance applied to heterogeneous supply chain datasets including EDI transactions, IoT sensor feeds, and carrier manifests. These services resolve format fragmentation across TMS, WMS, and OMS platforms to enable interoperable analytics and automated decision workflows. Cloud-based deployment models are capturing the fastest expansion as freight operators retire on-premises ETL infrastructure, while data standardization services command the deepest margin pools due to recurring schema maintenance contracts. The end-user base tilts toward third-party logistics providers managing multi-tenant data architectures for dispersed shipper portfolios.
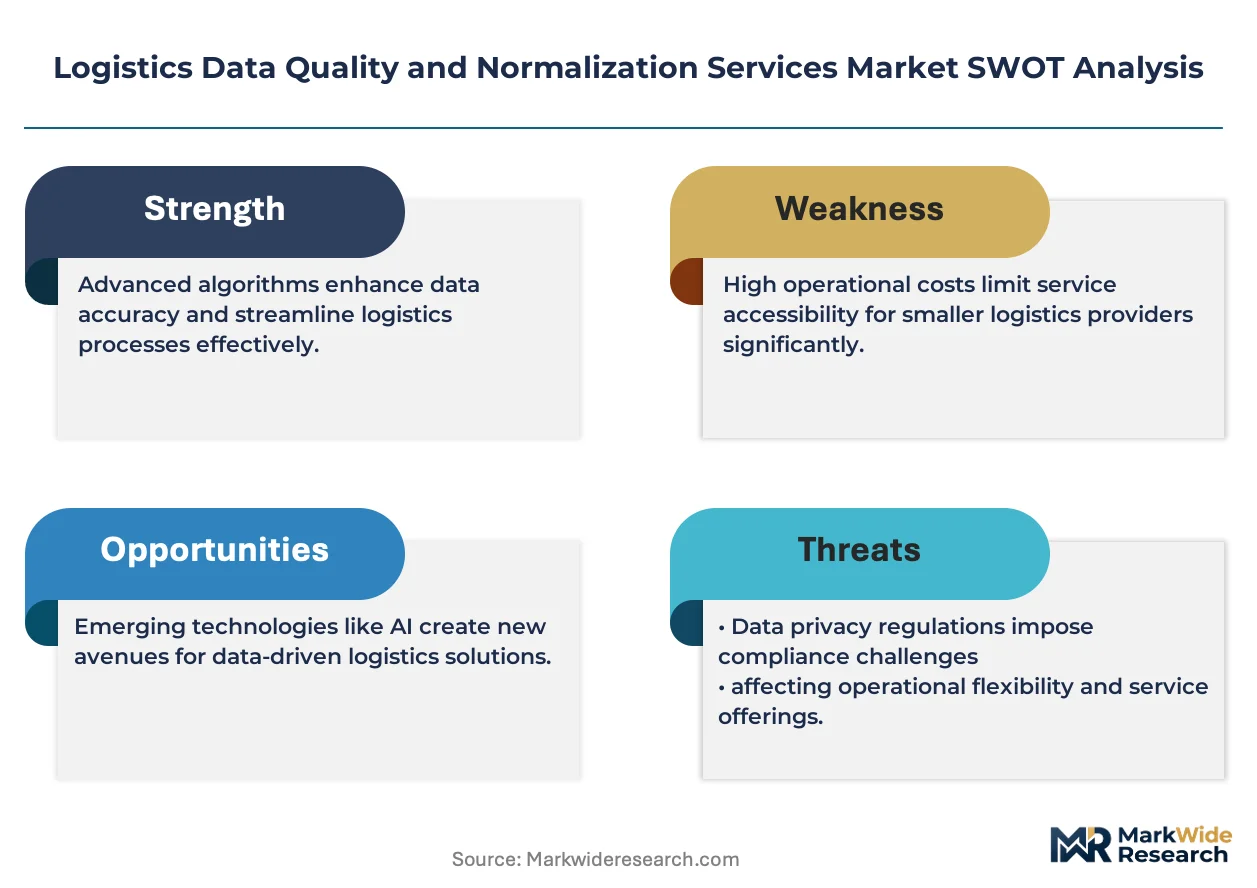
GDPR and the EU AI Act impose strict lineage and bias-audit requirements on automated logistics decision systems, compelling investment in auditable data preparation pipelines. The US FDA and FAA maintain distinct data integrity standards for pharmaceutical cold-chain and air-cargo documentation respectively, fragmenting compliance architectures for cross-border operators. Stakeholders must evaluate whether to build captive normalization capabilities or absorb SaaS pricing premia as carrier interoperability mandates proliferate across jurisdictions.
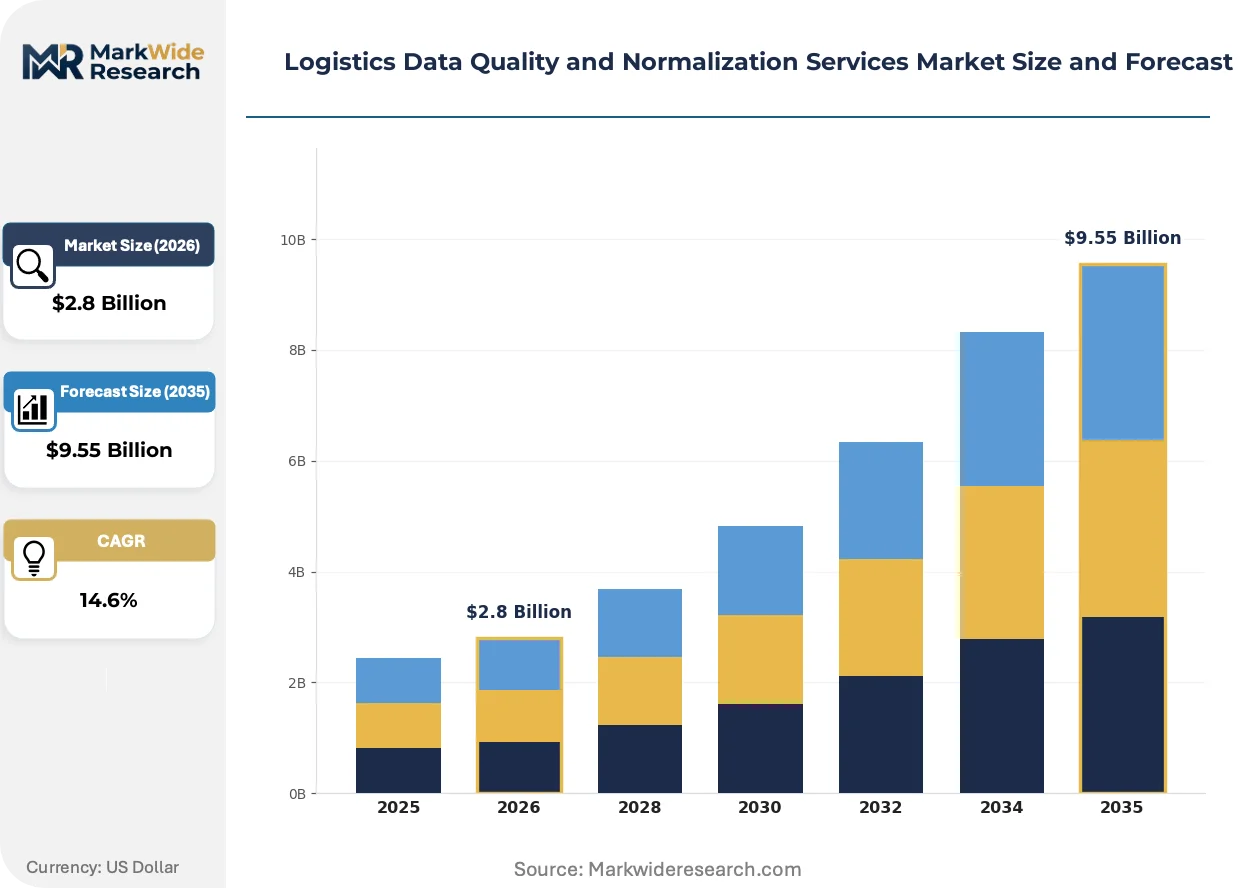
Market Dynamics
The EU's Digital Operations Resilience Act is compressing compliance timelines for multimodal freight operators, forcing simultaneous upgrades to data lineage architecture across TMS, WMS, and carrier EDI networks.
Growth Catalysts
- E-commerce fulfillment velocity:Real-time inventory synchronization demands are pulling cloud-native normalization services into automated warehouse networks. Third-party logistics providers now require sub-second schema harmonization across shipper portfolios.
- GDPR Article 30 mandates:Record-keeping requirements for processing activities are compelling investment in auditable data preparation pipelines for cross-border freight documentation.
- Rhine-Ruhr multimodal density:Germany's inland waterway-rail-road hub concentration is creating concentrated demand for unified data standards across heterogeneous carrier systems.
Market Restraints
- Cloud egress cost volatility:High-velocity IoT sensor streaming across distributed logistics networks generates unpredictable data transfer expenses that erode SaaS margin structures.
- Schema maintenance concentration:Specialized data standardization expertise pools in Germany and the Netherlands, creating geographic talent bottlenecks for complex harmonization projects.
- FAA documentation fragmentation:Distinct air-cargo data integrity standards impose parallel compliance architectures that resist unified normalization workflows.
Strategic Opportunities
- Pharmaceutical cold-chain expansion:FDA temperature excursion documentation requirements are opening specialized data quality service lanes for biologics distribution networks.
- EU AI Act bias auditing:Automated logistics decision systems now require auditable training data pipelines, creating recurring revenue attachments for governance platforms.
- API-first carrier connectivity:Direct system-to-system integration is displacing traditional EDI clearinghouses, enabling new entrants to capture schema translation value.
Industry Challenges
- Legacy ETL retirement friction:On-premises data infrastructure carries embedded business logic that resists cloud migration without expensive manual recoding.
- Master data stewardship gaps:Shortage of supply chain domain specialists who bridge technical normalization skills with freight operational knowledge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Logistics Data Quality and Normalization Services Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Data Cleansing, Data Enrichment, Data Standardization, Address Validation, Duplicate Removal Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS, Managed Services End User: Third-Party Logistics, Freight Forwarders, Warehousing Providers, Courier Services, Supply Chain Consultants Application: Shipment Tracking, Inventory Management, Route Optimization, Freight Billing, Performance Analytics |
| Companies Covered | Informatica, SAP, IBM, Oracle, Microsoft, AWS, Talend, Blue Yonder, Teradata, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Logistics Data Quality and Normalization Services Market Trends and Innovations
Real-time data pipeline architectures are compressing decision latencies from hours to seconds across freight networks, rewriting competitive benchmarks for operational responsiveness.
Streaming data fabrics are rewriting how logistics operators integrate heterogeneous IoT sensor feeds, carrier manifest formats, and warehouse execution systems. Large 3PLs in Germany and the Netherlands are deploying these architectures to unify rail, road, and barge data streams. The technology is compressing schema reconciliation cycles from batch overnight processing to continuous in-flight normalization.
REACH chemical substance tracking extensions are forcing hazardous materials shippers to embed granular composition data into standard freight documentation. This regulatory pressure is fragmenting previously standardized EDI message formats across European chemical logistics corridors. Specialized normalization services that automate regulatory field mapping are capturing premium pricing in Rotterdam-Antwerp chemical hub traffic.
Shippers are unbundling data quality service contracts from bundled TMS subscriptions, creating direct procurement relationships with specialized normalization vendors. This pattern is most visible among mid-market e-commerce operators in the US and Germany who rejected one-size-fits-all ERP data modules. Direct sourcing is compressing vendor switching costs and accelerating platform replacement cycles.
Logistics Data Quality and Normalization Services Market Segmentation
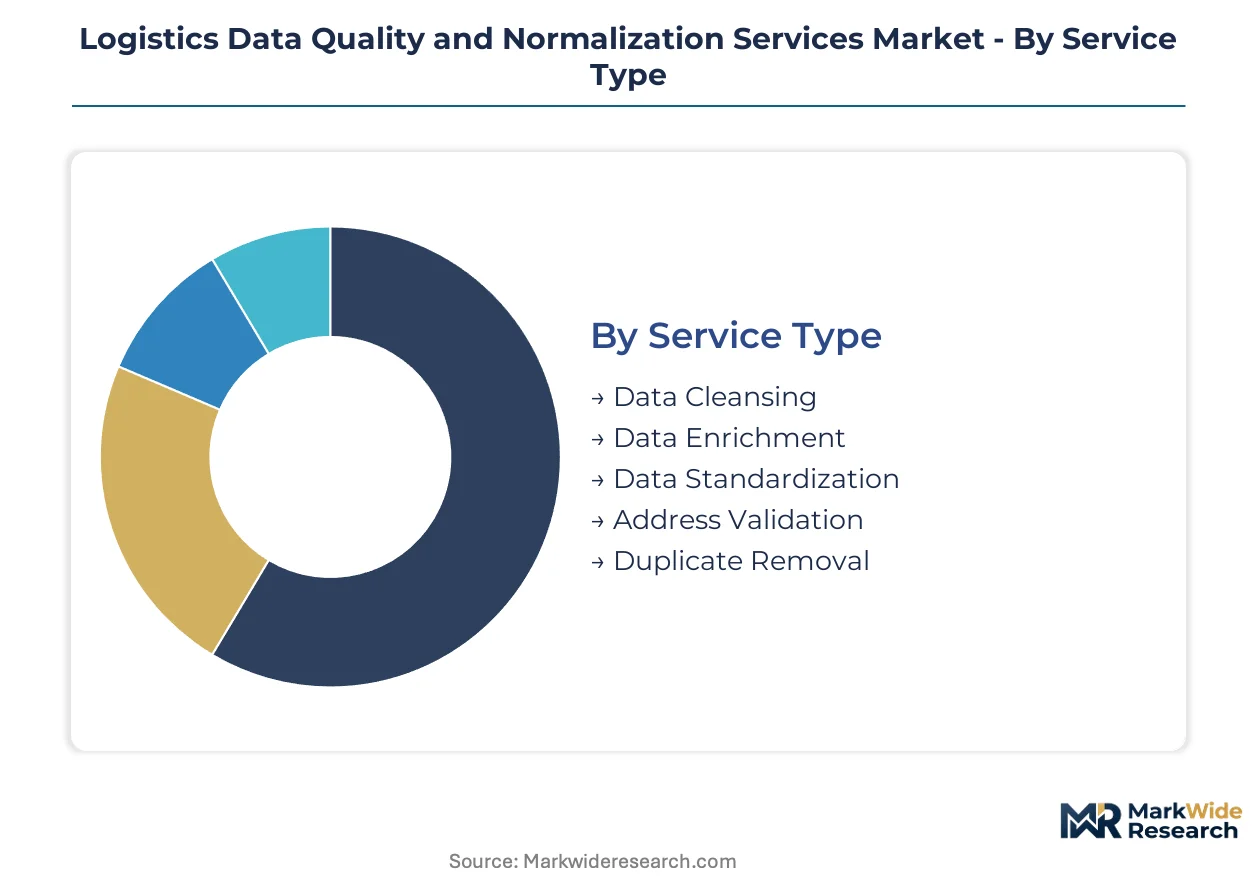
Logistics data quality services fragment across technical capabilities, infrastructure preferences, and operational use cases. Procurement patterns diverge sharply between asset-heavy carriers seeking embedded normalization and digital-native 3PLs demanding API-first flexibility.
Service Type:
Buyers differentiate primarily by data maturity—enterprises with legacy ERP stacks prioritize remediation services while cloud-native operators invest in preventive governance layers.
- Data Cleansing:Automated detection and correction of format errors, null values, and semantic inconsistencies in carrier manifests and EDI transactions. Demand concentrates among mid-market freight forwarders in Germany's Rhine-Ruhr corridor confronting heterogeneous rail-road-waterway data feeds. GDPR Article 30 record-keeping mandates are accelerating procurement of auditable cleansing pipelines.
- Data Standardization:Schema harmonization across TMS, WMS, and OMS platforms to enable interoperable analytics. Third-party logistics providers managing multi-tenant architectures for dispersed shipper portfolios represent the deepest demand concentration. Recurring maintenance contracts for evolving carrier EDI specifications generate the stickiest revenue attachments.
- Data Enrichment:Augmentation of core logistics records with external reference data including geocoding, weather, and regulatory classifications.
- Address Validation:Verification and normalization of location data against postal authority databases and proprietary geospatial reference sets.
- Duplicate Removal:Entity resolution algorithms identifying redundant records across merged datasets from acquisition-driven carrier consolidations.
Data cleansing leads volumes today; data standardization is gaining share fastest.
Deployment Model:
Cost tier segmentation separates capital-constrained operators from enterprises absorbing premium pricing for operational agility.
- Cloud-Based:Elastic compute resources for high-velocity streaming normalization without infrastructure ownership. E-commerce fulfillment networks in the Netherlands and Germany are retiring on-premises ETL infrastructure in favor of consumption-priced pipelines. Unpredictable egress costs from distributed IoT sensor streaming remain the primary procurement friction.
- SaaS:Pre-configured normalization workflows with subscription pricing and automatic schema updates. Mid-market warehousing providers across Europe favor this model for rapid deployment without specialized data engineering hires. Vendor switching costs are compressing as shippers unbundle data quality from bundled TMS subscriptions.
- On-Premises:Localized data processing for operators with strict data residency requirements or legacy system dependencies.
- Hybrid:Split architectures processing sensitive master data on-site while leveraging cloud elasticity for high-volume transaction streams.
- Managed Services:Outsourced normalization operations including dedicated stewardship teams and SLA-governed output quality.
Cloud-based deployments anchor current infrastructure decisions; SaaS models are climbing the fastest as procurement unbundling accelerates.
End User:
Volume scale distinguishes multi-tenant platform operators from single-enterprise data consumers with simpler harmonization requirements.
- Third-Party Logistics:Multi-shipper data architectures requiring sub-second schema harmonization across dispersed portfolios. Germany's largest 3PLs are deploying streaming data fabrics to unify rail, road, and barge feeds in the Rhine-Ruhr corridor. EU AI Act bias-audit requirements for automated decision systems are compelling investment in auditable training data pipelines.
- Freight Forwarders:Intermediary operators consolidating carrier manifests, customs documentation, and shipper instructions into unified execution records.
- Warehousing Providers:Inventory synchronization demands pulling real-time normalization into automated warehouse networks.
- Courier Services:Last-mile operators with high-velocity address validation and delivery confirmation data quality requirements.
- Supply Chain Consultants:Advisory firms delivering data-driven optimization recommendations requiring standardized inputs across client systems.
Third-party logistics dominates current procurement; freight forwarders are expanding most quickly as API-first carrier connectivity displaces traditional EDI clearinghouses.
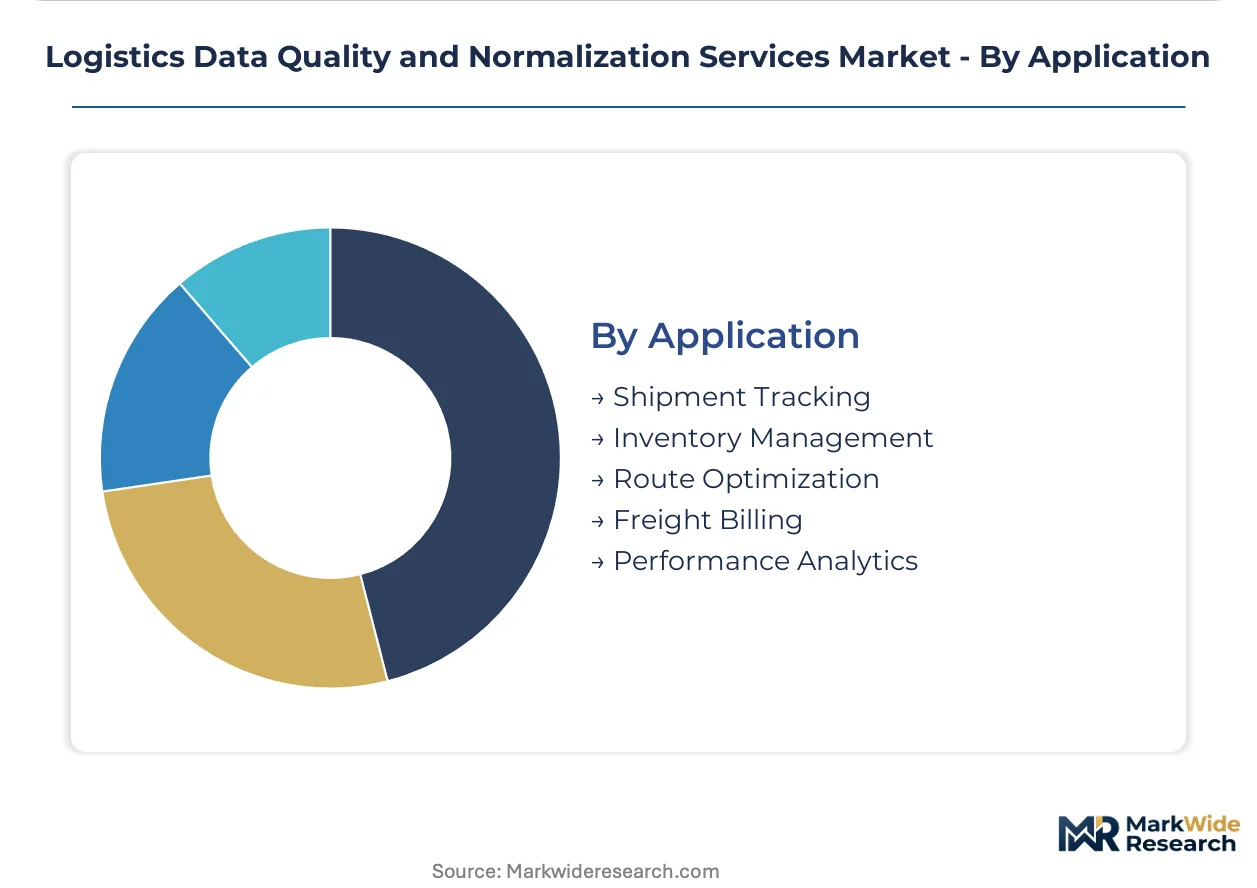
Application:
Maturity curves separate transactional use cases with immediate ROI from strategic analytics requiring longer data lineage investments.
- Shipment Tracking:Real-time location data normalization across GPS, cellular, and satellite positioning feeds with carrier-specific format variations. Pharmaceutical cold-chain operators are prioritizing this application to meet FDA temperature excursion documentation requirements for biologics distribution.
- Freight Billing:Invoice validation and chargeback detection through automated reconciliation of rate cards, accessorials, and executed service records.
- Inventory Management:Multi-echelon stock visibility requiring harmonization of SKU hierarchies, unit-of-measure conversions, and location master data.
- Route Optimization:Cleanse and enrichment of traffic, weather, and vehicle constraint data for algorithmic dispatch decisions.
- Performance Analytics:Cross-functional KPI standardization enabling benchmarking across carrier networks and facility networks.
Shipment tracking commands the largest current investment; freight billing shows the steepest expansion trajectory as automated audit capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data engineering talent pools in Germany's Rhine-Ruhr corridor and the Netherlands' Randstad region anchor European service delivery. North American demand concentrates around cloud infrastructure hubs in Seattle and Northern Virginia. Asia-Pacific expansion tracks e-commerce fulfillment network buildouts in Shanghai and Singapore.
Germany
Rhine-Ruhr multimodal density drives concentrated demand for rail-road-waterway data harmonization. The EU Digital Operations Resilience Act compresses compliance timelines for freight operators managing TMS-WMS integration. Duisburg's inland port cluster deploys streaming data fabrics to unify barge manifest formats with Deutsche Bahn cargo systems.
United States
Pharmaceutical cold-chain operators prioritize FDA-compliant temperature excursion documentation for biologics distribution. The FAA maintains distinct air-cargo data integrity standards that fragment normalization workflows for cross-border operators. Seattle's cloud infrastructure corridor hosts elastic compute deployments for high-velocity IoT sensor streaming across warehouse networks.
Netherlands
Rotterdam-Antwerp chemical hub traffic requires specialized services automating REACH regulatory field mapping. GDPR Article 30 record-keeping mandates compel investment in auditable data preparation pipelines for cross-border freight documentation. Amsterdam's logistics technology cluster attracts schema standardization expertise from across the European Economic Area.
China
E-commerce fulfillment velocity pulls cloud-native normalization services into automated warehouse networks serving domestic consumption. MIIT data localization requirements shape infrastructure deployment decisions for multinational logistics platforms. Shanghai's Yangshan port complex experiments with real-time container data pipelines linking customs systems to carrier manifest feeds.
United Kingdom
Post-Brexit customs documentation complexity increases demand for automated harmonization across divergent EU-UK data standards. The Information Commissioner's Office enforces GDPR-equivalent data processing record-keeping for cross-channel freight operators. London's financial services logistics sector invests in master data governance for high-value cargo insurance workflows.
Logistics Data Quality and Normalization Services Market Competitive Landscape
Top-tier vendors anchor enterprise ERP integration, while mid-market specialists compete on API-first flexibility and consumption pricing. The vendor base stratifies across three tiers: legacy platform incumbents with deep enterprise footprints, cloud-native challengers offering elastic infrastructure, and vertical specialists targeting pharmaceutical cold-chain or hazardous materials compliance. Strategic moves concentrate on unbundling data quality services from bundled TMS subscriptions and deploying streaming data fabrics for real-time schema harmonization.
Within the enterprise platform tier, Informatica, SAP, and AWS occupy distinct positioning vectors. Informatica exemplifies deep ERP stack integration for complex multi-source normalization projects. SAP anchors embedded data services within logistics execution suites. AWS represents elastic compute pricing for high-velocity streaming pipelines, competing on infrastructure cost efficiency rather than domain-specific functionality.
| Leading Market Players |
|---|
| Informatica |
| SAP |
| IBM |
| Oracle |
| Microsoft |
| AWS |
| Talend |
| Blue Yonder |
| Teradata |
| Others |
Pricing and Supply Chain Analysis
Premium AI-native data quality platforms and commodity cleansing tools diverge sharply in both procurement economics and supplier geography. This bifurcation concentrates margin capture among vendors with embedded ERP integration in Germany and the Netherlands, while price-sensitive mid-market buyers in the US and UK gravitate toward consumption-priced cloud pipelines.
Pricing Analysis
Bundled TMS subscription pricing is unbundling as shippers establish direct procurement relationships with specialized normalization vendors. SaaS subscription tiers dominate, with differentiation driven by schema complexity handling and GDPR audit trail certification. Cost compression in the mid-market tier intensifies as AWS and Azure commoditize elastic compute for streaming pipelines. Freight forwarders show highest price sensitivity; pharmaceutical cold-chain operators absorb premium pricing for FDA-compliant documentation modules.
Supply Chain Analysis
Specialized data engineering talent rests on Germany's Rhine-Ruhr corridor and the Netherlands' Randstad region, with secondary pools in Seattle and Shanghai. Cloud infrastructure inputs draw from hyperscaler data centers in Northern Virginia, Frankfurt, and Singapore. Single-source vulnerability concentrates in schema maintenance expertise for REACH chemical compliance and EU AI Act bias auditing. Distribution runs through direct enterprise sales for complex multi-source projects and self-serve API portals for mid-market warehousing providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU regulatory density justifies premium pricing for compliance-embedded services, while US cloud infrastructure cost advantages enable margin capture in high-velocity streaming segments.
For Market Incumbents: To counter API-first carrier connectivity displacing traditional EDI clearinghouses, deepen embedded integration with SAP and Oracle logistics execution suites while acquiring specialized REACH compliance mapping capabilities in Rotterdam-Antwerp chemical corridors.
For New Entrants and Emerging Players: Enter via pharmaceutical cold-chain documentation services for FDA temperature excursion requirements, targeting mid-market biologics distributors with hybrid cloud-on-premise deployment flexibility and outcome-based SLA pricing.
For Investors and Strategic Acquirers: Consolidation pressure builds where schema maintenance expertise pools geographically while carrier interoperability mandates proliferate across jurisdictions. Viable acquisition targets combine supply chain domain stewardship with streaming data fabric engineering; watch EU Digital Operations Resilience Act enforcement timelines as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Streaming Data Fabric Deployment | Compresses schema reconciliation cycles from batch overnight to continuous in-flight normalization for Rhine-Ruhr multimodal operators. |
| REACH Regulatory Field Mapping Automation | Captures premium pricing in Rotterdam-Antwerp chemical hub traffic through automated hazardous composition data embedding. |
| API-First Carrier Connectivity Platform | Displaces traditional EDI clearinghouses by enabling direct system-to-system integration for freight forwarders. |
| EU AI Act Bias Audit Pipeline | Creates recurring revenue attachments through auditable training data governance for automated logistics decision systems. |
| Pharmaceutical Cold-Chain Documentation Module | Addresses FDA temperature excursion requirements for biologics distribution networks with specialized compliance architecture. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged logistics technology officers at 3PLs, data engineering directors at freight forwarders, TMS procurement leads at e-commerce operators, compliance officers at pharmaceutical distributors, and cloud infrastructure architects at hyperscalers. Secondary validation drew from EU regulatory filings, FDA guidance documents, SEC 10-K infrastructure disclosures, and customs trade data. Bottom-up service revenue estimates triangulated against top-down market sizing across deployment models and end-user segments.
Comparable historical periods anchored volume and value projections across the analysis window. The analytical framework modeled segmentation dimensions including service type, deployment architecture, end-user category, and application use case, with additional granularity for regulatory compliance tier. CAGRs derived from logistic curve fitting to adoption saturation patterns, with inputs from cloud infrastructure capex cycles and carrier EDI migration timelines.
Inputs from logistics platform earnings calls and regulatory agency guidance releases were available throughout the study window; gaps in private 3PL contract pricing introduce uncertainty bands around SaaS penetration estimates. Forecasts reflect documented assumptions regarding EU AI Act implementation pacing and cloud egress cost trajectories. A small set of triggers—specifically DORA enforcement severity and REACH extension scope—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Middle East and Africa Courier Market
Logistics and Shipping
GCC Automotive Logistics Market
Logistics and Shipping
Canada Road Freight Transport Market
Logistics and Shipping
Asia-Pacific Cold Chain Logistics Market
Logistics and Shipping
South America Freight and Logistics Market
Logistics and Shipping
Italy Apparel Logistics Market
Logistics and Shipping
Manufacturing Logistics Market
Logistics and Shipping
Latin America Stevedoring and Marine Cargo Handling Market
Logistics and Shipping
Hazardous Goods Logistics Market
Logistics and Shipping
Colombia Cold Chain Logistics Market
Logistics and Shipping
Qatar Freight and Logistics Market
Logistics and Shipping
Inbound Logistics Market
Logistics and Shipping
North America Shipping Agency Market
Logistics and Shipping
UK Freight Forwarding Market
Logistics and Shipping
India 3PL Market
Logistics and Shipping
United States Digital Freight Forwarding Market